
 Dicumyl Peroxide Market | 2026-2036
Dicumyl Peroxide Market Size, Share, and Industry Trends Forecast 2026-2036
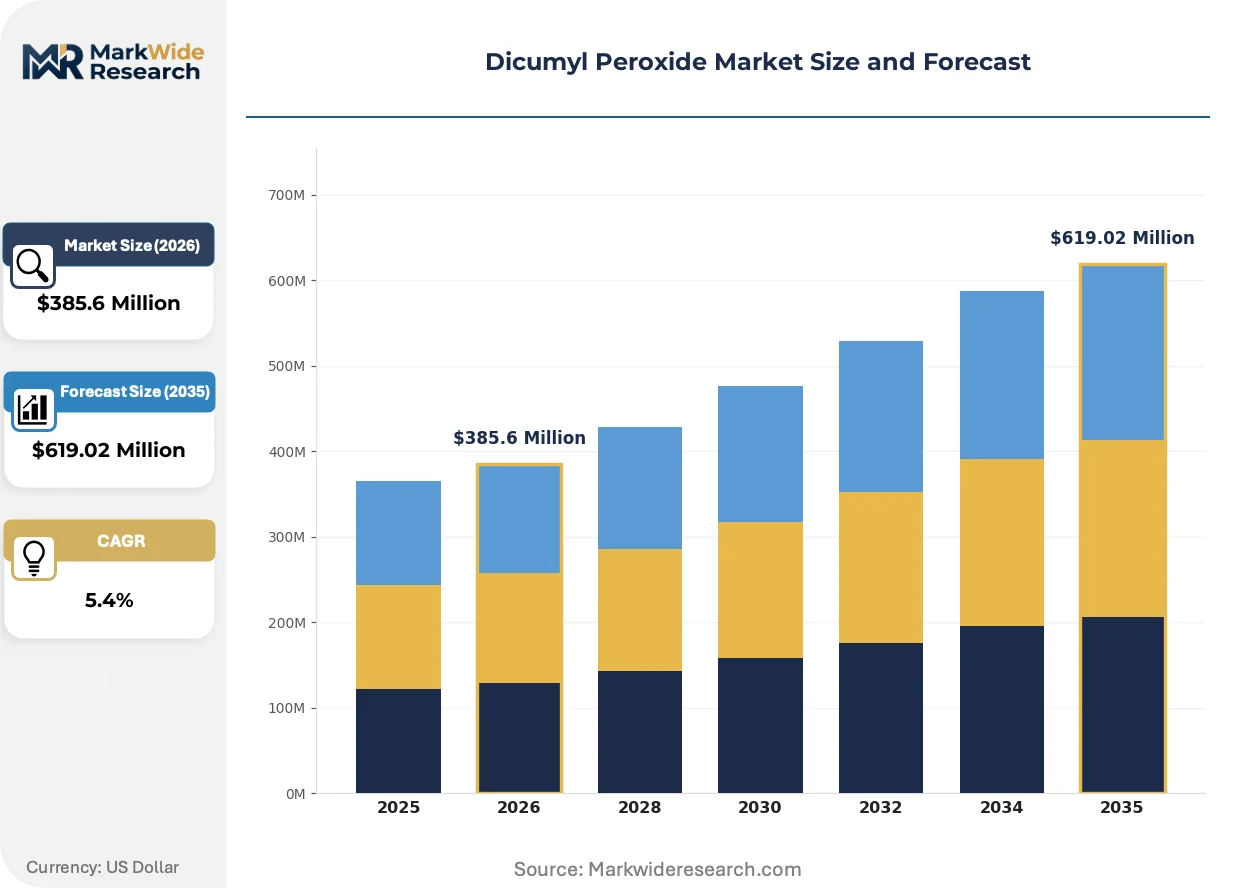
Dicumyl Peroxide Market Outlook
Capital-intensity divergence between integrated peroxide manufacturers and commodity traders is rotating competitive advantage toward producers with captive cumene supply chains. PERGAN GmbH leverages backward integration into hydrogen peroxide feedstock to sustain margin stability across European delivery contracts. Shandong Rui Huang Chemical Co Ltd anchors its position through dedicated dicumyl peroxide capacity serving domestic silicone rubber compounders. Arkema Group differentiates via controlled decomposition technology that extends product shelf life in tropical logistics corridors.
Dicumyl peroxide is an organic peroxide with the formula C18H22O2, typically supplied as a white crystalline solid with an active oxygen content near 5.9%, functioning primarily as a free-radical initiator for crosslinking polymers at temperatures between 120°C and 175°C. High purity grades command premium positioning in medical-grade silicone applications where residual acetophenone levels must stay below stringent thresholds, while technical grade material dominates volume flows into general rubber processing. The automotive end-user segment concentrates demand for crosslinked EPDM and silicone components, whereas construction applications in sealants and adhesives represent a faster-growing but smaller margin pool.
REACH registration requirements in Europe and GB standard compliance under China's SAMR framework shape product certification costs and market access timelines for non-domestic suppliers. OSHA process safety management rules in the United States govern storage and handling protocols for organic peroxide shipments, directly influencing distributor liability structures. Stakeholders must monitor evolving transportation classification debates between ICAO and national regulators, as reclassification of dicumyl peroxide hazard ratings would ripple through packaging specifications and air freight availability.
Market Dynamics
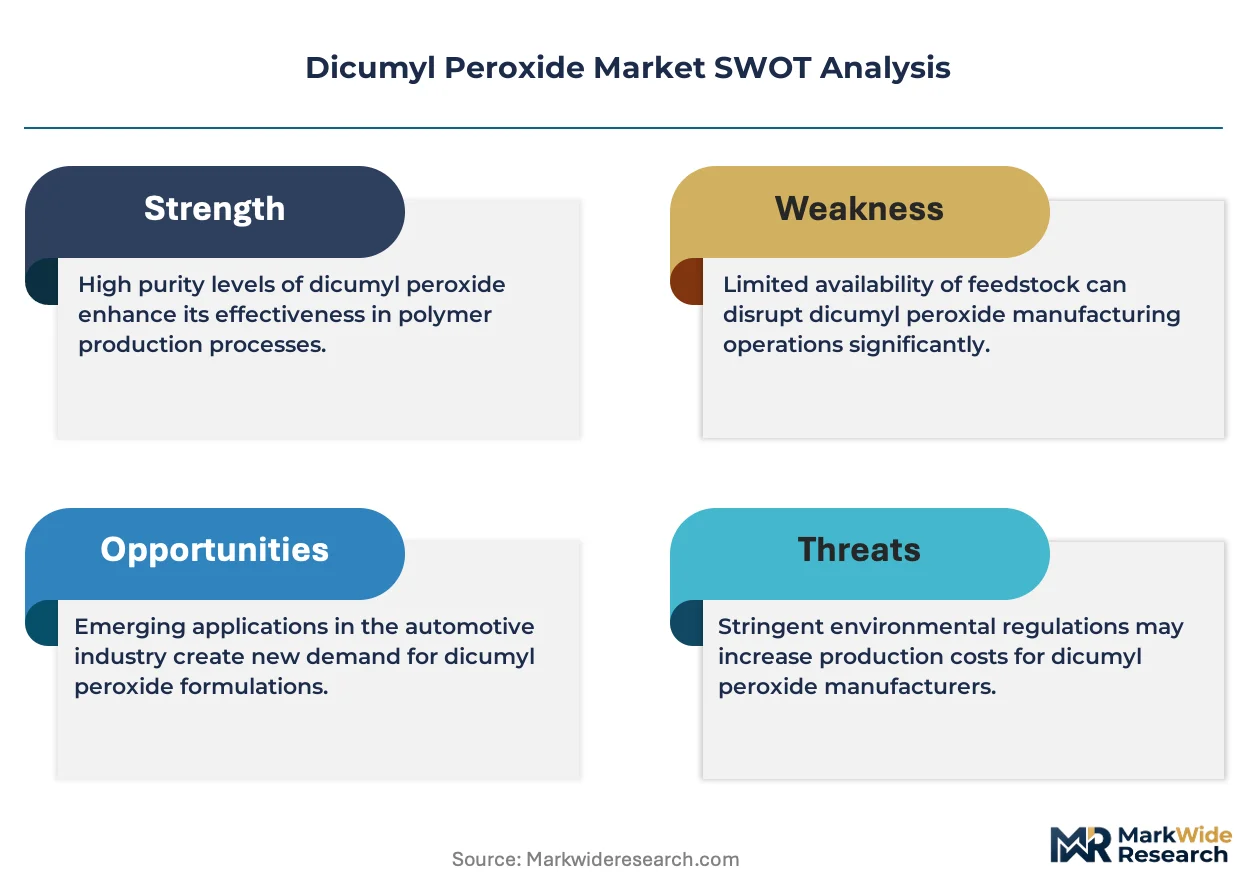
Automotive rubber compounders are consolidating procurement around suppliers with REACH-registered, high-purity dicumyl peroxide grades, compressing margins for undifferentiated technical-grade producers and rewarding backward-integrated manufacturers with captive cumene supply.
Growth Catalysts
- EPDM roofing membrane specifications:Commercial construction codes in Germany and France now mandate crosslinked synthetic rubber for flat-roof durability, pulling dicumyl peroxide into building-material supply chains.
- REACH Article 33 disclosure requirements:EU downstream users must document Substances of Very High Concern in finished goods, creating preference for registered peroxide grades with full safety data sheet lineage.
- Silicone rubber medical device molding:FDA 21 CFR Part 177 compliance for implantable-grade silicones requires ultra-low acetophenone residual peroxides, opening premium positioning for purified grades.
Market Restraints
- Cumene feedstock volatility:Benzene-propylene spread fluctuations directly transmit to dicumyl peroxide production economics, squeezing non-integrated compounders without captive aromatics supply.
- Shandong production cluster concentration:Over 60% of Chinese dicumyl peroxide capacity sits within 200 kilometers of Zibo, creating single-point vulnerability to regional environmental enforcement actions or logistics disruptions.
- Organic peroxide thermal stability limits:Mandatory 35°C maximum storage temperature for transport classification restricts distribution network reach and necessitates cold-chain infrastructure investment.
Strategic Opportunities
- India specialty silicone expansion:PLI scheme incentives for medical electronics and electric vehicle component manufacturing are attracting silicone compounders seeking localized peroxide supply.
- UV-LED hybrid curing systems:Convergence of traditional thermal peroxide initiation with photoinitiated polymerization enables energy-efficient processing for heat-sensitive substrates.
- Saudi downstream petrochemical integration:SABIC and downstream partners are evaluating peroxide production for captive use in EPDM and polyolefin crosslinking within the Kingdom's industrial cities.
Industry Challenges
- Process safety engineer scarcity:Organic peroxide handling expertise is concentrated among aging specialists in Europe and North America, complicating plant commissioning in emerging production locations.
- Multi-jurisdiction registration synchronization:Simultaneous REACH, TSCA, and NMPA new chemical notifications require 18-36 month timelines and dedicated regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dicumyl Peroxide Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $619.02 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Purity, Technical Grade, Industrial Grade, Laboratory Grade Application: Rubber Processing, Plastics, Adhesives, Coatings End User: Automotive, Construction, Electronics, Consumer Goods Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | PERGAN GmbH, Shandong Rui Huang Chemical Co Ltd, Sinopec Shanghai Gaoqiao, AkzoNobel, Dongsung Corporation, Arkema Group, Taicang Plastics Additives Factory Co Ltd, Green Chemicals Spa, Nouryon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dicumyl Peroxide Market Strategic Shifts
Controlled decomposition formulations and digital supply chain traceability are reconfiguring how dicumyl peroxide manufacturers defend margin position and access premium end-use segments.
Masterbatch concentrates with 40-50% dicumyl peroxide loading in polymer carriers are supplanting traditional crystalline solid packaging for automated dosing systems. Automotive hose manufacturers in Stuttgart and Detroit are adopting these concentrates to eliminate dust exposure and improve batch consistency. The shift is compressing demand for standard flake grades while rewarding compounders with extrusion compounding capabilities.
China's GB 30000.16-2013 chemical classification standard revision is tightening purity thresholds for organic peroxide export certification. Domestic producers serving SAMR-registered downstream users must upgrade crystallization and drying equipment to meet the new acetophenone limits. Medical-grade silicone processors in Wuxi and Shenzhen are already qualifying suppliers against the draft standard, accelerating qualification timelines for compliant producers.
Compounders are consolidating annual contracts around integrated peroxide suppliers with captive hydrogen peroxide and cumene production. Tier-1 automotive suppliers in Nagoya and Munich now require lot-level digital certificates of analysis with blockchain traceability. This behavioral shift is disintermediating traditional distributors in favor of direct manufacturer relationships, most visible in the German automotive supply base where EPDM sealant specifications now mandate supplier audit rights.
Dicumyl Peroxide Market Segmentation
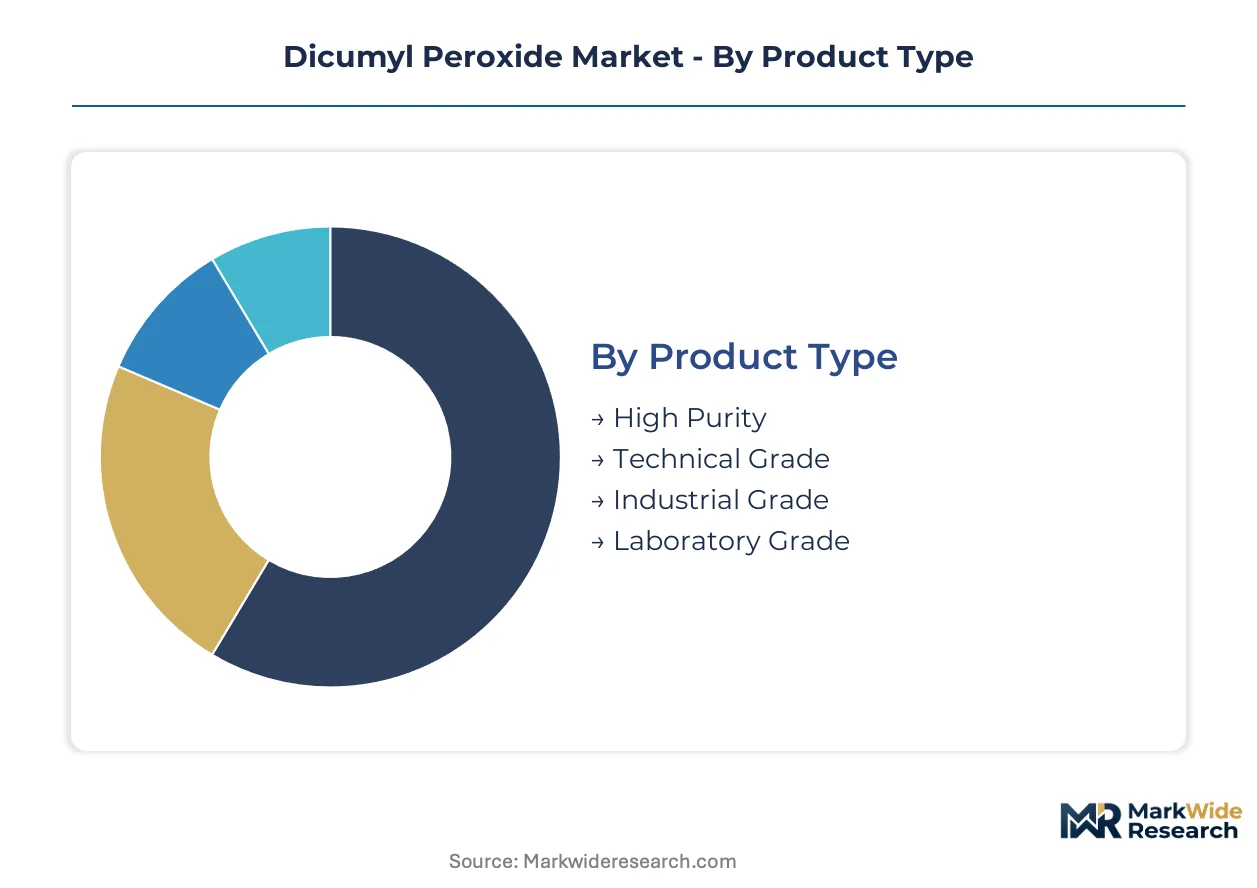
Dicumyl peroxide demand fragments across purity grades and end-use specifications that dictate supplier qualification timelines. Procurement patterns diverge sharply between automotive compounders requiring REACH-registered supply and construction buyers prioritizing cost efficiency over certification lineage.
Product Type:
Domestic Chinese consumption concentrates in technical and industrial grades serving silicone rubber clusters in Shandong and Jiangsu. Export flows toward European automotive suppliers favor high-purity grades with full REACH dossier documentation.
- High Purity:Specifications limit residual acetophenone below 0.1% for FDA 21 CFR Part 177 compliance in implantable silicone devices. German automotive sealant manufacturers in Stuttgart mandate this grade for EPDM crosslinking in underhood applications where thermal degradation resistance is critical.
- Technical Grade:Active oxygen content near 5.9% serves general rubber processing with less stringent purity thresholds. Chinese domestic silicone compounders in Zibo absorb the majority of global technical grade volume for commodity sealant production.
- Industrial Grade:Bulk material for construction adhesive applications where cost sensitivity outweighs performance optimization.
- Laboratory Grade:Small-batch quantities for R&D validation and new formulation development in polymer science institutes.
Technical grade commands the established base. The steepest expansion runs through high purity.
Application:
Application mix correlates directly with crosslinking temperature requirements and substrate heat tolerance. Automotive rubber processors dominate volume offtake while adhesive formulators represent the most price-sensitive demand pool.
- Rubber Processing:EPDM and silicone vulcanization at 140-175°C consumes the majority of dicumyl peroxide tonnage. German roofing membrane specifications now mandate crosslinked synthetic rubber for flat-roof durability, pulling material into building-material supply chains.
- Plastics:Polyolefin crosslinking for wire and cable insulation requires precise peroxide dosing control. Construction codes in France and Germany are expanding specifications for crosslinked polyethylene in electrical conduit applications.
- Adhesives:Structural bonding formulations for automotive assembly use dicumyl peroxide as a co-curing agent with silane-modified polymers.
- Coatings:Limited penetration in powder coating cure systems where UV alternatives are displacing thermal initiation.
Rubber processing anchors volume demand. Plastics applications are climbing the fastest.
End User:
End-user concentration reflects the geographic clustering of rubber and silicone manufacturing capacity. Automotive procurement consolidates around qualified suppliers while construction demand fragments across regional formulators.
- Automotive:Tier-1 suppliers in Nagoya and Munich require lot-level digital certificates of analysis with blockchain traceability for EPDM sealant specifications. Underhood component thermal resistance requirements drive specification toward high-purity grades.
- Construction:EPDM roofing membrane demand in Germany and France is expanding fastest among building material applications. Commercial code mandates for crosslinked synthetic rubber durability are pulling dicumyl peroxide into flat-roof supply chains.
- Electronics:Silicone encapsulation for high-temperature circuit protection uses purified grades with low ionic contamination.
- Consumer Goods:Kitchenware and baby product silicone molding requires FDA-compliant peroxide residuals.
Automotive commands the established base. Construction is gaining share fastest.
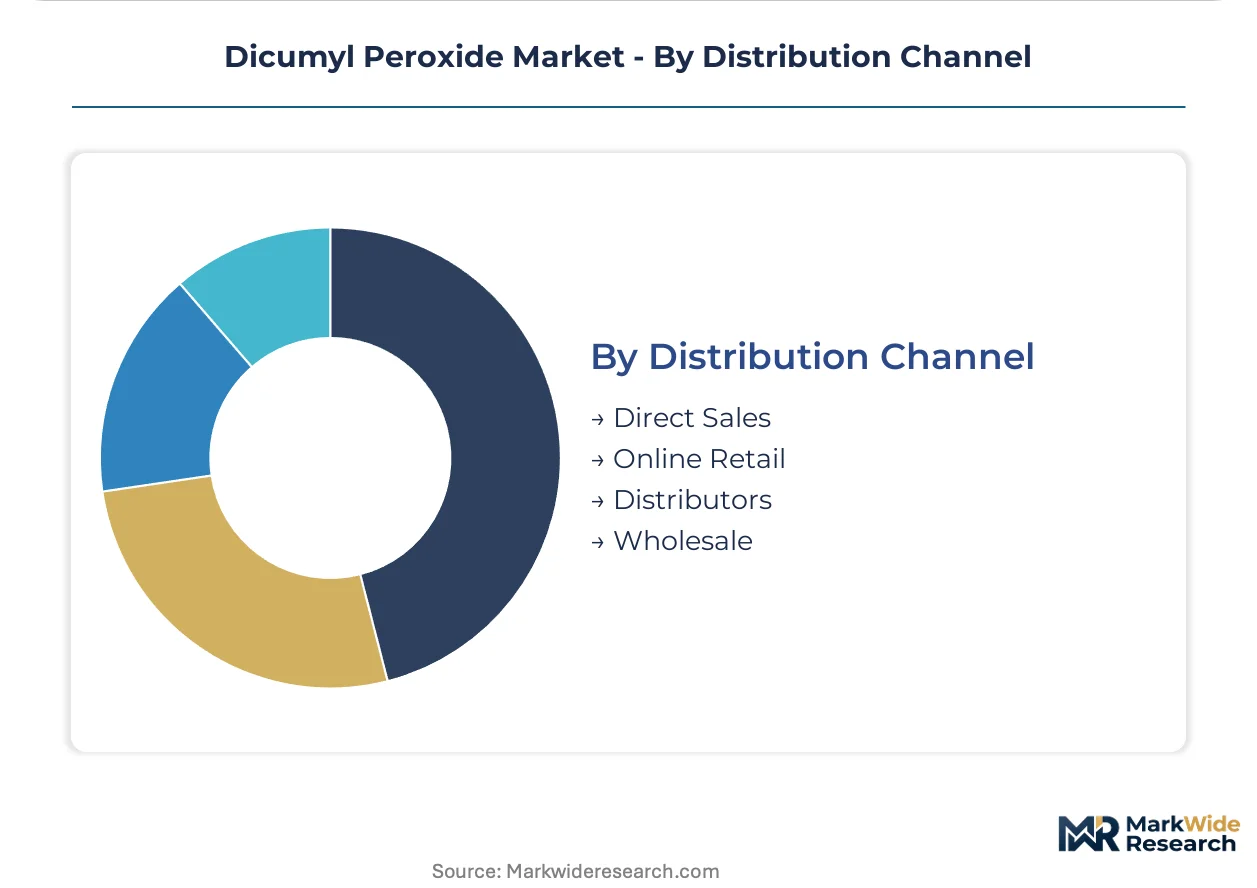
Distribution Channel:
Channel structure is bifurcating between direct manufacturer relationships for qualified automotive supply and distributor intermediation for smaller construction compounders. Cold-chain requirements for organic peroxide storage constrain channel economics.
- Direct Sales:Annual contracts with integrated peroxide manufacturers now dominate German automotive supply bases. Tier-1 suppliers exercise audit rights over production facilities and demand captive cumene supply chain documentation.
- Distributors:Regional chemical distributors serve construction adhesive formulators with technical grade material. Liability structures are tightening under OSHA process safety management rules for organic peroxide handling.
- Online Retail:Laboratory grade quantities for R&D procurement through specialized chemical supply platforms.
- Wholesale:Bulk material aggregation for commodity rubber processors in Chinese provincial industrial zones.
Direct sales commands the established base. Distributor channel consolidation represents the steepest structural shift.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power asymmetry between German automotive compounders and Chinese technical-grade buyers is widening as REACH compliance costs concentrate margin capture in Western Europe. Chinese domestic absorption favors undifferentiated industrial grades, while European procurement consolidates around registered high-purity supply. This divergence is reshaping regional production economics and trade flow patterns.
Germany
Automotive EPDM sealant manufacturers in Stuttgart and Munich anchor European demand for REACH-registered high-purity grades. ECHA Article 33 disclosure requirements for Substances of Very High Concern now mandate full safety data sheet lineage for downstream automotive supply chains. The Baden-Württemberg rubber processing cluster is consolidating annual contracts around backward-integrated peroxide suppliers with captive cumene documentation.
China
Silicone rubber compounders in Zibo and Wuxi absorb the majority of global technical-grade volume for commodity sealant and medical device molding applications. SAMR's evolving GB 30000.16-2013 standard revision is tightening acetophenone residual limits for export certification. The Shandong Peninsula production cluster hosts over sixty percent of national capacity within two hundred kilometers of Zibo, creating single-point environmental enforcement vulnerability.
United States
Wire and cable insulation manufacturers in Texas and the Southeast drive polyolefin crosslinking demand for electrical conduit applications. OSHA process safety management rules govern organic peroxide storage and handling protocols, directly influencing distributor liability structures and cold-chain infrastructure investment requirements. The Gulf Coast petrochemical corridor is evaluating captive peroxide production for integrated EPDM and synthetic rubber operations.
India
Specialty silicone compounders in Maharashtra and Gujarat are expanding capacity to serve medical electronics and electric vehicle component manufacturing. PLI scheme incentives for domestic manufacturing are attracting peroxide suppliers seeking localized supply relationships. The Mumbai-Pune industrial belt is emerging as a qualification hub for FDA 21 CFR Part 177 compliant medical-grade silicone processors.
Saudi Arabia
Downstream petrochemical integration within SABIC's industrial cities is evaluating captive dicumyl peroxide production for EPDM and polyolefin crosslinking. SFDA regulatory frameworks for chemical import certification are shaping market access timelines for non-domestic suppliers. The Eastern Province industrial cluster is positioning for regional supply to Middle East and African rubber processing markets.
Dicumyl Peroxide Market Competitive Environment
Concentration sits with backward-integrated peroxide manufacturers possessing captive cumene and hydrogen peroxide supply chains. The vendor base stratifies across three tiers: integrated chemical conglomerates with aromatics production, dedicated peroxide specialists with regional distribution networks, and commodity traders dependent on spot feedstock procurement. Two dominant competitive moves are capacity consolidation around automotive qualification requirements and digital traceability investments for lot-level certificate of analysis documentation.
Within the integrated manufacturer tier, PERGAN GmbH and Arkema Group exemplify European producers leveraging captive feedstock control for margin stability across delivery contracts. Shandong Rui Huang Chemical Co Ltd occupies a position among Chinese domestic specialists serving silicone rubber clusters through dedicated dicumyl peroxide capacity. These three companies represent divergent archetypes: German backward integration into hydrogen peroxide, French controlled decomposition technology positioning, and Chinese regional cluster concentration.
| Leading Market Players |
|---|
| PERGAN GmbH |
| Shandong Rui Huang Chemical Co Ltd |
| Sinopec Shanghai Gaoqiao |
| AkzoNobel |
| Dongsung Corporation |
| Arkema Group |
| Taicang Plastics Additives Factory Co Ltd |
| Green Chemicals Spa |
| Nouryon |
| Others |
Value Chain & Pricing Dynamics
Masterbatch concentrate substitution for crystalline flake formats is redrawing supply geography toward extrusion-compounding hubs in Stuttgart and Detroit while compressing margins for undifferentiated solid-grade producers. This format shift simultaneously concentrates procurement power with automotive compounders capable of automated dosing and eliminates dust-handling distributors from qualified supply chains.
Pricing Analysis
The customization-premium spread between REACH-registered high-purity grades and technical-grade commodity material now exceeds the underlying cost differential. Three-tier pricing structure across premium, standard, and economy levels reflects certification lineage, captive cumene supply, and cold-chain delivery capability. Cost compression in technical-grade material is intensifying because Shandong cluster oversupply meets slowing construction demand. Construction adhesive formulators exhibit the highest price sensitivity, while German automotive sealant manufacturers absorb premiums for lot-level blockchain traceability.
Supply Chain Analysis
Strategic stockpile preferences dominate among German automotive compounders facing ECHA Article 33 disclosure deadlines, whereas Chinese silicone processors run lean inventory against Zibo cluster proximity. Supply concentrates in China, Germany, and the United States, with over sixty percent of global capacity anchored in Shandong Peninsula production. The chain draws from cumene, hydrogen peroxide, and acetophenone recovery streams. Single-source vulnerability runs through Shandong environmental enforcement actions. Distribution runs through direct manufacturer contracts for automotive and regional chemical distributors for construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical-grade silicone qualification requirements under FDA 21 CFR Part 177 are accelerating as a technological-regulatory inflection, compressing timelines for peroxide producers lacking ultra-low acetophenone purification capability.
For Market Incumbents: Shield margin position by deepening captive cumene supply documentation for German automotive audit requirements and accelerating controlled-decomposition formulation R&D against tropical logistics degradation. UV-LED hybrid curing systems threaten thermal-initiation volume in heat-sensitive substrate applications. For New Entrants and Emerging Players: Cold-chain logistics service gaps in Indian specialty silicone corridors present immediate white-space opportunity. Target Maharashtra and Gujarat medical electronics compounders seeking localized peroxide supply with PLI scheme alignment. Qualification support services for FDA 21 CFR Part 177 compliance represent the most penetrable entry vector. For Investors and Strategic Acquirers: Secondary-cycle assets sit with hydrogen peroxide-backed peroxide specialists in European industrial clusters lacking Asian production footprint. Five-to-ten year viability hinges on REACH registration maintenance and SAMR GB standard compliance capability. The signal to watch is acetophenone limit tightening in China's draft GB 30000.16-2013 revision accelerating qualification failures among technical-grade producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cumene | Captive aromatics supply secures margin stability against benzene-propylene spread volatility. |
| Controlled Decomposition Technology Investment | Arkema's shelf-life extension capability commands premium positioning in tropical logistics corridors. |
| Masterbatch Concentrate Capacity Addition | Automated dosing adoption in Stuttgart and Detroit eliminates dust exposure liability for compounders. |
| REACH Registration Maintenance | ECHA Article 33 disclosure requirements now mandate full safety data sheet lineage for automotive supply. |
| Digital Certificate of Analysis Implementation | Blockchain traceability meets Tier-1 supplier audit rights in Munich and Nagoya procurement specifications. |
Study Parameters
Desk research of customs trade data, SEC chemical company filings, and ECHA registration databases preceded structured interviews with dicumyl peroxide plant managers, automotive rubber procurement leads, silicone compounder technical directors, and cold-chain distribution partners. Primary fieldwork across Shandong, Stuttgart, and Mumbai-Pune industrial belts validated secondary projections. Bottom-up capacity modeling and top-down end-use consumption estimates were triangulated against import-export flow analysis.
Variance decomposition across the projection horizon isolates feedstock cost, regulatory compliance, and substitution threat contributions to price trajectory. Segmentation dimensions modeled include purity grade tier, end-use industry application, packaging format, and regional production hub concentration. CAGRs were derived from elasticity-adjusted demand projections incorporating automotive EPDM specification changes and construction code mandates. Industry-specific inputs include benzene-propylene spread forecasting and SAMR GB standard revision timing.
Forecasts assume regulatory continuity in REACH, FDA 21 CFR Part 177, and SAMR frameworks; material policy shifts would require re-modeling. Forecasts reflect assumptions of stable transportation classification under ICAO and OSHA process safety management enforcement patterns. Revision becomes warranted when Shandong environmental enforcement intensity crosses thresholds triggering capacity withdrawal.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Heat Shrink Tubes Market
Industrial Chemicals
Trimethylolpropane (TMP) Market
Industrial Chemicals
Foam Market
Industrial Chemicals
Organophosphate Insecticides Market
Industrial Chemicals
1-Octanol Market
Industrial Chemicals
Global Ethiprole Market
Industrial Chemicals
Isononanol (INA) Market
Industrial Chemicals
Lime Manufacturing Market
Industrial Chemicals
Global Phosphate Esters Market
Industrial Chemicals
Middle East and Africa Non-Phthalate Plasticizers Market
Industrial Chemicals
Cryolite Market
Industrial Chemicals
Automotive Chemicals Market
Industrial Chemicals
Global Cyanuric Chloride Market
Industrial Chemicals
Diesel Exhaust Fluid Market
Industrial Chemicals
Thermally Stable Antiscalant Market
Industrial Chemicals
Drag Reducing Agents Market