
 Deoiler Chemicals Market | 2026-2036
Deoiler Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Deoiler Chemicals Market Outlook
A shortage of experienced petroleum process chemists is unwinding capacity expansion timelines at several suppliers. Nouryon leverages its integrated alkoxylation footprint in the US Gulf to sustain cost-competitive surfactant supply for demulsifier blends. Kemira anchors Nordic and North Sea oilfield service relationships through specialized polymer chemistry expertise. Clariant competes on application-specific formulation libraries that reduce separator residence times for heavy crude processors.
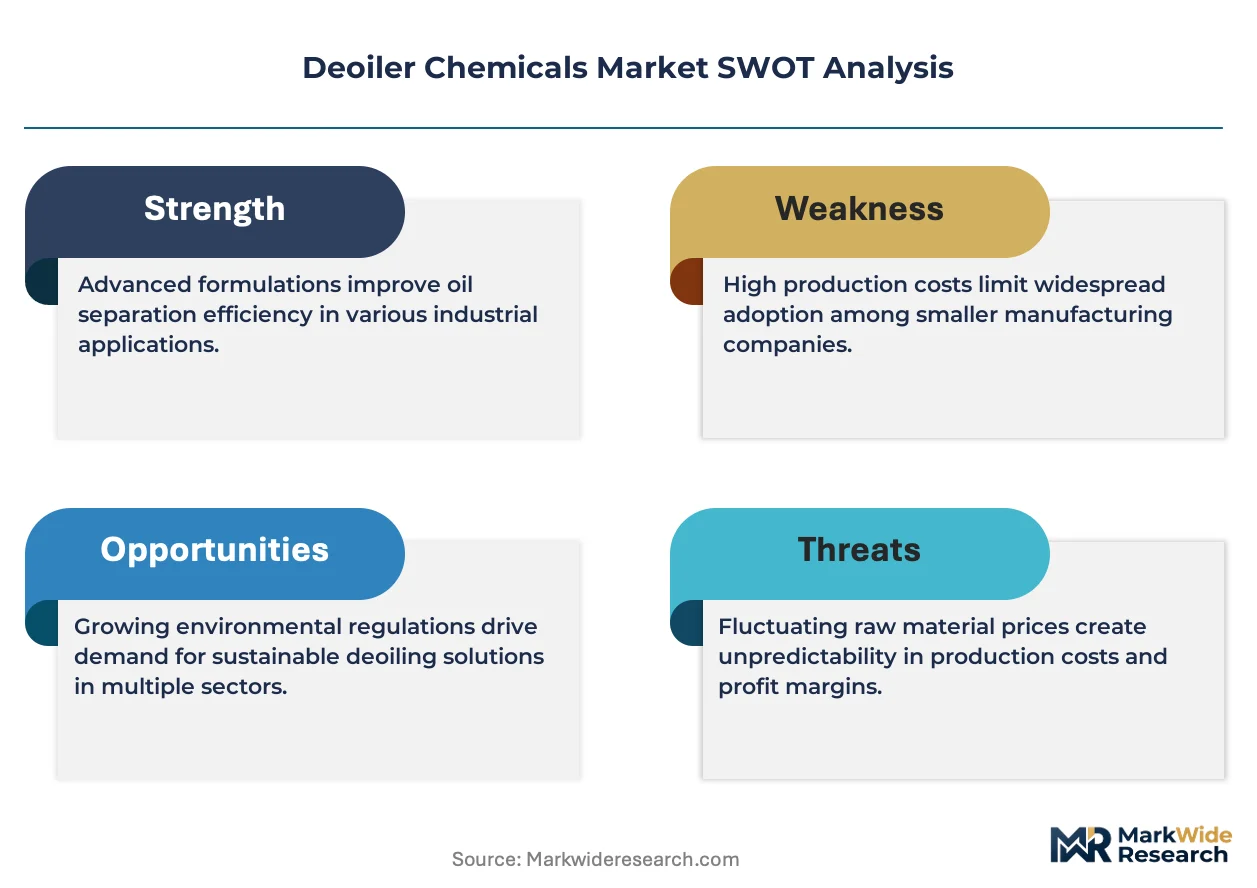
Deoiler chemicals are specialty formulations designed to break oil-water emulsions through surface-active agents that reduce interfacial tension, typically operating at dosages between 5-500 ppm depending on crude gravity and emulsion stability. Their primary purpose is to accelerate phase separation in production separators, desalters, and wastewater treatment systems across upstream and midstream hydrocarbon operations. Surfactant-based demulsifiers command the largest share of product-type value due to their versatility across paraffinic and naphthenic crude profiles, while microbial treatment technologies represent the fastest-expanding technology segment as operators seek to reduce chemical inventory toxicity in offshore discharge zones. Solvent-assisted formulations retain entrenched positions in heavy oil thermal production where viscosity reduction demands hydrocarbon carrier phases.
EPA effluent limitation guidelines under the Clean Water Act enforce oil-in-water discharge thresholds that directly determine demulsifier performance specifications and dosing economics for US operators. REACH registration requirements in Europe and China's MEE discharge standards for produced water create divergent compliance cost structures that fragment formulation strategies across jurisdictions. Stakeholders must monitor regulatory trajectory on per- and polyfluoroalkyl substance restrictions, as fluorinated surfactant alternatives face emerging scrutiny that could force reformulation cycles across legacy offshore chemical portfolios.
Market Dynamics
EPA discharge standards under the Clean Water Act are compressing permissible oil-in-water limits, forcing reformulation cycles across demulsifier portfolios and redrawing competitive advantage around rapid regulatory compliance capabilities.
Growth Catalysts
- Offshore Production Expansion:Deepwater operators in the US Gulf Coast corridor are scaling procurement of advanced demulsifier formulations to handle higher water-cut reservoirs and tighter discharge windows.
- REACH Registration Compliance:European chemical registration requirements are accelerating substitution of legacy surfactant chemistries with biodegradable alternatives, opening formulation service contracts.
- Thermal Heavy Oil Recovery:Solvent-assisted demulsifier demand is climbing in steam-assisted gravity drainage operations where viscosity reduction requires hydrocarbon carrier phases.
Market Restraints
- Ethylene Oxide Feedstock Volatility:Alkoxylation precursor costs swing with petrochemical refining margins, compressing surfactant blend economics for Gulf Coast formulators.
- Specialized Chemist Scarcity:A shortage of experienced petroleum process chemists is unwinding capacity expansion timelines at several suppliers, constraining technical service bandwidth.
- Microbial Treatment Substitution:Biological demulsification technologies are displacing chemical dosing in Norwegian and UK North Sea discharge zones with strict toxicity limits.
Strategic Opportunities
- Brazilian Pre-Salt Development:Petrobras-led offshore projects present untapped demand for high-pressure demulsifier systems handling ultra-deepwater emulsion stability challenges.
- PFAS Regulatory Tailwind:Emerging EPA and state-level restrictions on fluorinated surfactants are forcing portfolio replacements, creating first-mover advantage for PFAS-free formulation libraries.
- Digital Dosing Integration:Convergence of real-time separator monitoring with automated chemical injection systems is enabling performance-based supply contracts.
Industry Challenges
- Petroleum Process Chemist Pipeline Collapse:Universities have shuttered specialized hydrocarbon chemistry programs, extending recruitment cycles for formulation laboratories.
- Cross-Jurisdictional Registration Burden:Divergent EPA, REACH, and MEE compliance timelines force parallel development tracks, duplicating toxicology and efficacy testing expenditures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deoiler Chemicals Market |
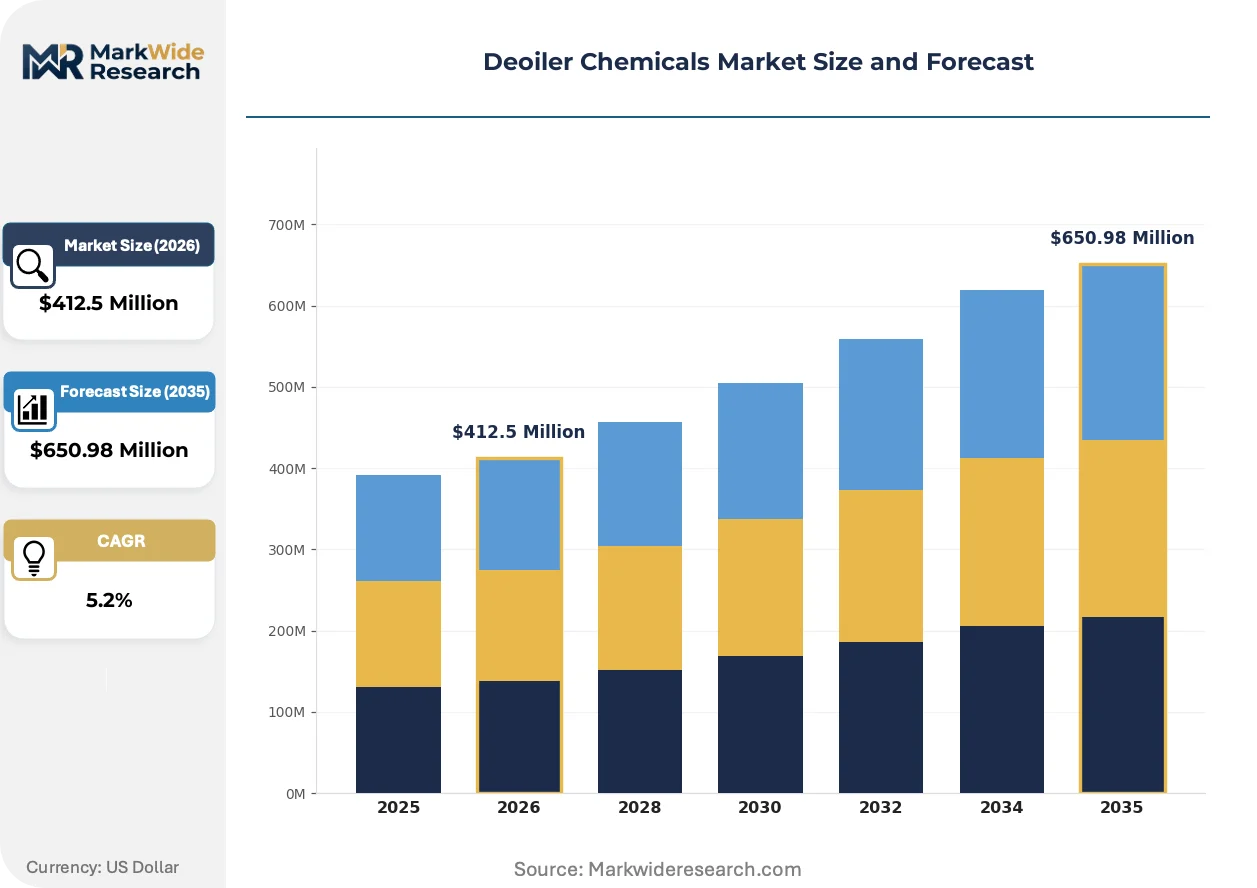
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $650.98 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surfactants, Solvents, Emulsifiers, Biocides Application: Oil Recovery, Wastewater Treatment, Oilfield Operations, Chemical Processing End User: Energy Sector, Manufacturing Sector, Environmental Services, Oil & Gas Industry Technology: Microbial Treatment, Chemical Precipitation, Membrane Filtration, Activated Carbon Adsorption |
| Companies Covered | Eastman Chemical, Nouryon, Ashland, Clariant, Croda International, LANXESS, Kemira, Solvay, Stepan Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deoiler Chemicals Market Strategic Shifts
Formulation chemistry is pivoting toward bio-based and low-toxicity architectures as discharge regulations tighten across major production basins, while automation and data integration reshape how chemicals are specified and dosed.
Microbial demulsification technology is miniaturizing through encapsulated bacterial consortia delivered via slow-release substrates. Norwegian offshore operators are piloting these systems in unmanned platform configurations. The technology is miniaturizing chemical inventory footprints and reducing supply vessel frequency in remote North Sea installations.
EPA effluent limitation guidelines under the Clean Water Act are enforcing oil-in-water discharge thresholds below 29 mg/L for produced water. This compression directly determines demulsifier performance specifications and dosing economics for US operators. Heavy crude processors in the Gulf Coast corridor are responding with application-specific formulation libraries that reduce separator residence times.
Buyer concentration among integrated supermajors is consolidating procurement decisions into centralized chemical management frameworks. Independent service companies are losing direct specification authority as operators bundle demulsifier supply into integrated production chemical contracts. This pattern is most visible in the US Permian and Gulf of Mexico where ExxonMobil and Chevron have streamlined supplier panels.
Deoiler Chemicals Market Segmentation
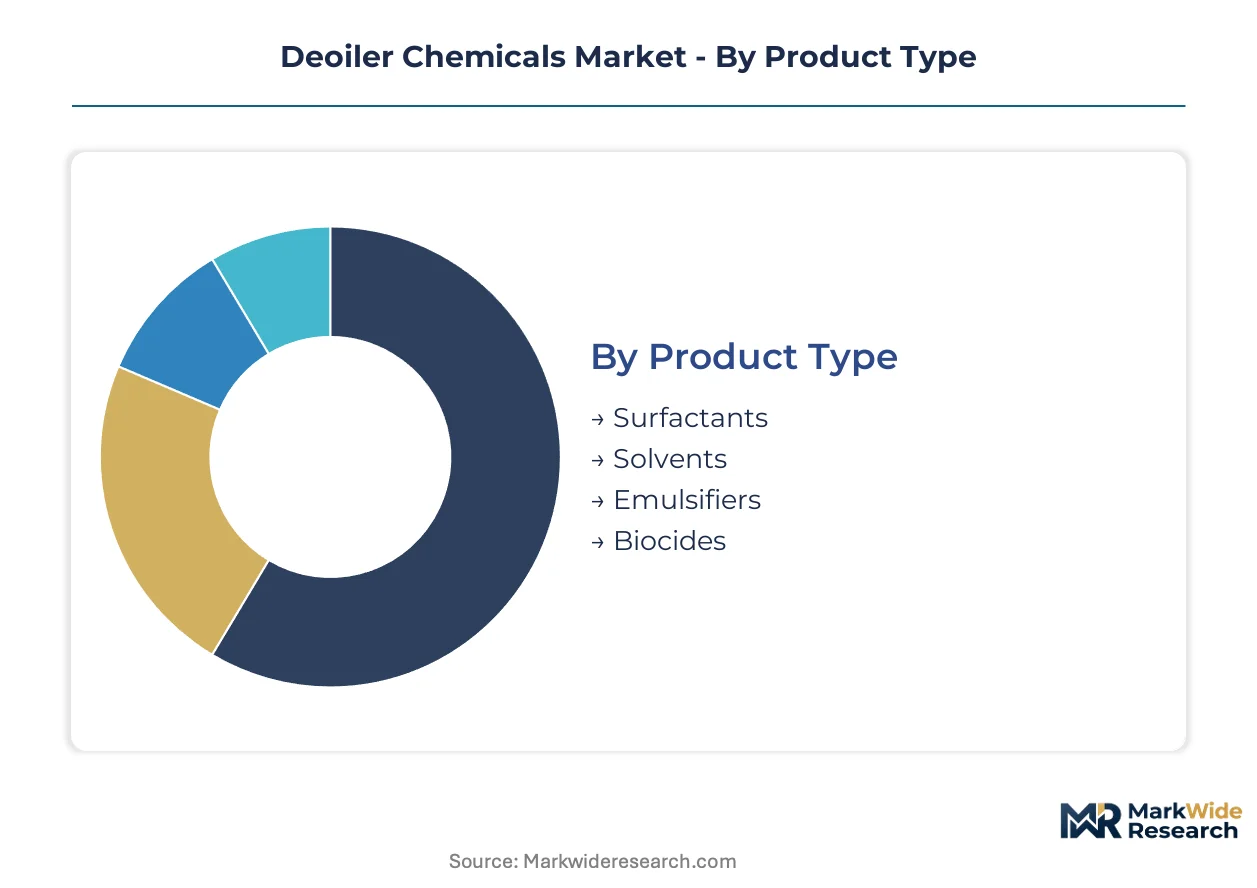
Deoiler chemical procurement decisions fragment across four distinct axes: molecular architecture determines unit economics, application setting dictates performance specifications, end-user consolidation shapes contract structures, and technology selection locks in operational footprints for decades. Understanding margin distribution across these dimensions exposes where formulation suppliers can defend pricing power versus where commoditization pressures dominate.
Product Type:
Margin pools concentrate in surfactant blends where alkoxylation chemistry expertise creates formulation differentiation, while solvent carriers face feedstock volatility that compresses value capture.
- Surfactants:Surface-active agents reduce interfacial tension between oil and water phases through hydrophilic-lipophilic balance engineering. Demand concentrates in US Gulf Coast heavy crude processing where EPA discharge limits below 29 mg/L oil-in-water force high-performance demulsifier specifications. Clariant and Nouryon compete on application-specific libraries that shorten separator residence times.
- Solvents:Hydrocarbon carrier phases enable viscosity reduction in thermal heavy oil recovery, particularly steam-assisted gravity drainage operations in Alberta and Venezuela. Pricing tracks ethylene oxide and aromatic refining margins, eroding margin stability for Gulf Coast formulators when petrochemical spreads tighten.
- Emulsifiers:Stabilize or destabilize oil-water interfaces depending on charge density and molecular weight. Used in chemical processing and refinery desalting units.
- Biocides:Control microbial-induced corrosion and souring in production systems. Required in offshore platforms with seawater injection.
Surfactants hold installed capacity. Solvents are rotating up the share rankings as thermal recovery expands.
Application:
Volume gravity sits with oilfield operations where produced water volumes scale with reservoir maturity, while wastewater treatment commands premium pricing tied to discharge permit compliance.
- Oilfield Operations:Production separators, desalters, and gathering systems consume demulsifiers at 5-500 ppm dosage depending on crude gravity and emulsion stability. Offshore installations in the US Gulf of Mexico and Norwegian North Sea drive specification intensity as unmanned platforms reduce chemical inventory tolerance.
- Wastewater Treatment:Produced water effluent processing faces tightening EPA, REACH, and China's MEE discharge standards that force reformulation cycles. Performance-based supply contracts emerge where real-time monitoring enables automated dosing optimization.
- Oil Recovery:Enhanced oil recovery operations use deoiler chemicals to manage emulsions in polymer and surfactant floods.
- Chemical Processing:Refinery and petrochemical plant effluent treatment requires demulsifiers for API separator and dissolved air flotation units.
Oilfield Operations anchor current procurement volumes. Wastewater Treatment is gaining share fastest as regulatory thresholds compress.
End User:
Customer concentration patterns split between integrated supermajors with centralized chemical management frameworks and fragmented environmental services contractors competing on local logistics.
- Oil & Gas Industry:Upstream and midstream operators bundle demulsifier supply into integrated production chemical contracts, consolidating supplier panels. ExxonMobil and Chevron have streamlined procurement decisions in the US Permian and Gulf of Mexico, squeezing independent service companies.
- Energy Sector:Power generation and renewable fuel processors require deoiler chemicals for fuel washing and effluent treatment. Demand scales with refinery complexity upgrades.
- Environmental Services:Third-party wastewater treatment contractors serve independent producers and industrial facilities without captive chemical expertise.
- Manufacturing Sector:Metalworking, textiles, and food processing plants use demulsifiers for tramp oil removal and process water recycling.
Oil & Gas Industry holds installed capacity. Environmental Services is rotating up the share rankings as outsourcing expands.
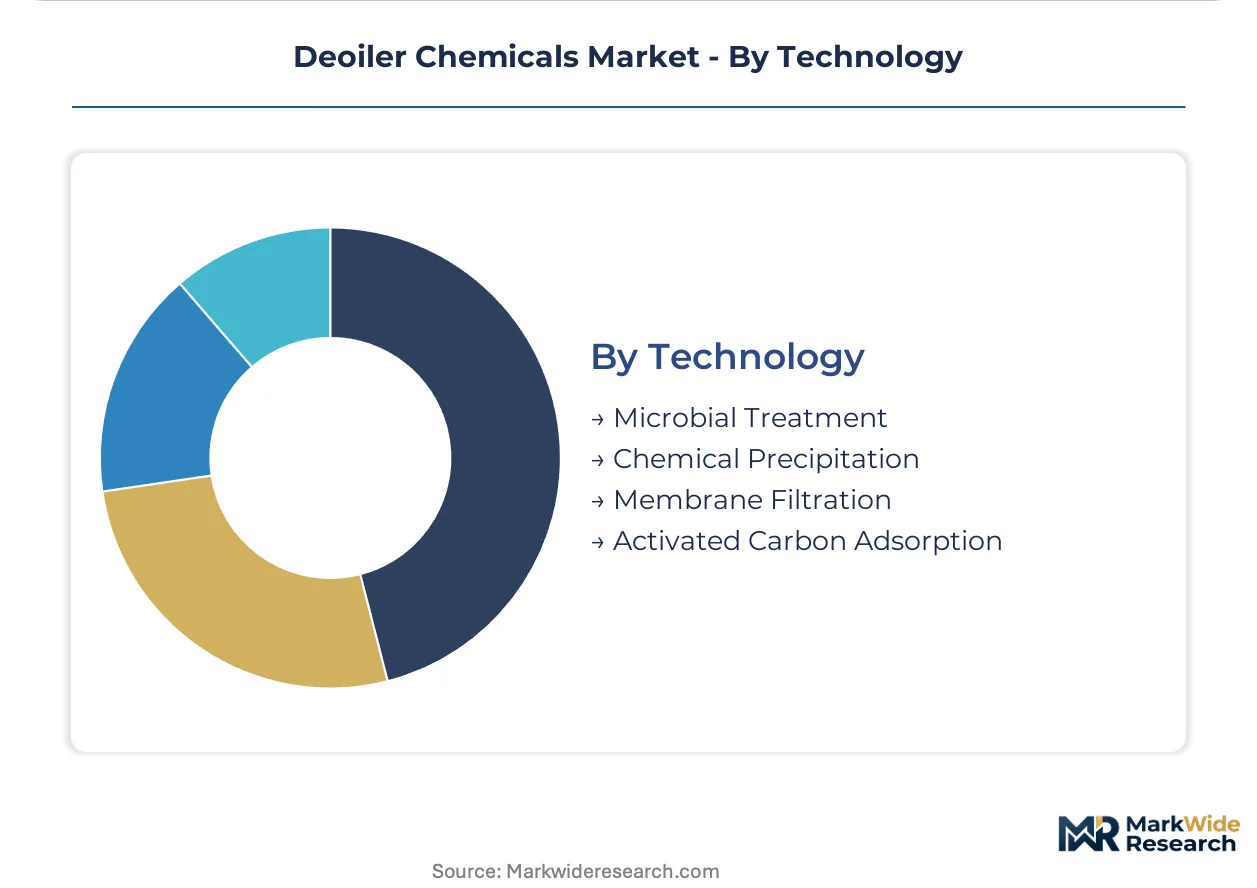
Technology:
Technology selection locks in operational architectures where microbial systems reduce chemical inventory toxicity but require longer commissioning cycles, while chemical precipitation retains immediacy for batch processing needs.
- Microbial Treatment:Encapsulated bacterial consortia delivered via slow-release substrates miniaturize chemical footprints on unmanned platforms. Norwegian offshore operators pilot these systems in North Sea installations with strict toxicity limits, reducing supply vessel frequency.
- Chemical Precipitation:Conventional demulsifier dosing through continuous injection skids dominates heavy oil thermal production where rapid phase separation demands immediate chemical availability.
- Membrane Filtration:Ceramic and polymeric membranes remove emulsified oil without chemical addition, competing for produced water reuse applications.
- Activated Carbon Adsorption:Polishing step for residual oil and dissolved organics in discharge-compliant effluent streams.
Chemical Precipitation holds installed capacity. Microbial Treatment is rotating up the share rankings as offshore automation advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States Gulf Coast corridor where EPA discharge mandates force premium formulation specifications, while cost-competitive supply from Asian manufacturing centers erodes margins in standardized surfactant blends.
United States
Deepwater operators in the Gulf of Mexico scale procurement of advanced demulsifier systems for higher water-cut reservoirs. EPA effluent limitation guidelines enforce oil-in-water thresholds below 29 mg/L for produced water discharge. Houston anchors formulation development clusters where Clariant and Nouryon maintain technical service laboratories.
Norway
Offshore unmanned platforms in the North Sea drive demand for miniaturized chemical inventory solutions. REACH registration requirements accelerate substitution of legacy surfactants with biodegradable alternatives. Stavanger hosts service company headquarters coordinating microbial treatment pilots for strict toxicity-limited discharge zones.
Brazil
Petrobras-led pre-salt development creates demand for high-pressure demulsifier systems handling ultra-deepwater emulsion stability. ANVISA chemical registration protocols shape import compliance timelines for foreign suppliers. Rio de Janeiro concentrates procurement decision-making for integrated production chemical contracts.
China
State-owned operators expand thermal heavy oil recovery in Xinjiang and Bohai Bay fields. MEE discharge standards for produced water tighten effluent treatment specifications. Shanghai and Tianjin house domestic surfactant manufacturing clusters serving regional oilfield service demand.
United Arab Emirates
ADNOC offshore expansion drives specification intensity for high-temperature demulsifier formulations. MOHAP chemical product registration requirements govern import authorization for specialty formulations. Abu Dhabi anchors technical service operations covering Lower Zakum and Upper Zakum field developments.
Deoiler Chemicals Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where formulation expertise commands premium pricing while commodity surfactant supply faces margin compression. The vendor base splits between integrated petrochemical majors with captive alkoxylation capacity and specialized oilfield chemical houses competing on application-specific libraries. Three archetypes dominate: integrated petrochemical suppliers with backward control over ethylene oxide feedstocks, specialized demulsifier formulators with deep petroleum process chemistry expertise, and regional distributors with logistics advantages in remote basin operations. Capacity expansion and portfolio diversification toward bio-based alternatives constitute the dominant competitive moves.
Among integrated chemical majors, Nouryon and Clariant occupy positions exemplifying distinct strategic archetypes. Nouryon leverages integrated alkoxylation footprint in the US Gulf to sustain cost-competitive surfactant supply. Clariant competes on application-specific formulation libraries that reduce separator residence times. Kemira anchors Nordic and North Sea relationships through specialized polymer chemistry expertise. These three companies represent the technology-driven tier where petroleum process chemistry capabilities determine specification authority.
| Leading Market Players |
|---|
| Eastman Chemical |
| Nouryon |
| Ashland |
| Clariant |
| Croda International |
| LANXESS |
| Kemira |
| Solvay |
| Stepan Company |
| Others |
Value Chain & Pricing Dynamics
EPA effluent limitation guidelines under the Clean Water Act gate both supplier qualification and price differentiation simultaneously, compressing permissible oil-in-water discharge thresholds below 29 mg/L and forcing only formulation-capable suppliers to capture premium positioning while standard surfactant blenders face margin compression in commoditized tiers.
Pricing Analysis
The customization-premium spread separates configured-to-order demulsifier formulations from standard surfactant blends. Contract-based long-term offtake dominates procurement between integrated supermajors and qualified suppliers, with price differentiation resting on certification grade (EPA discharge compliance tier) and customization level (application-specific library depth). Cost compression in standard surfactant tiers is intensifying because ethylene oxide feedstock volatility erodes blender economics. Independent environmental services contractors exhibit highest price sensitivity, while Gulf Coast heavy crude processors prioritize performance over unit cost.
Supply Chain Analysis
Inventory-strategy preferences favor just-in-time chemical delivery for offshore platforms with limited storage, while strategic stockpiling persists for thermal heavy oil operations requiring continuous solvent-assisted demulsifier availability. Supply concentrates in the United States, China, and Germany where alkoxylation capacity and petroleum process chemistry expertise cluster. Raw material dependencies draw from ethylene oxide, propylene oxide, and specialty polymer intermediates. Single-source vulnerability runs through integrated petrochemical majors controlling captive ethylene oxide supply. Distribution runs through integrated production chemical contracts bundling demulsifiers with corrosion inhibitors and scale control agents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as microbial demulsification technologies displace chemical dosing in Norwegian and UK North Sea discharge zones with strict toxicity limits.
For Market Incumbents: Fortify formulation libraries against microbial substitution threats by deepening backward integration into bio-based alkoxylation feedstocks and securing EPA pre-approval for next-generation biodegradable surfactant architectures. Capacity addition in the US Gulf Coast corridor reinforces technical service bandwidth where petroleum process chemist scarcity constrains competitor expansion timelines. For New Entrants and Emerging Players: Lead with PFAS-free formulation development targeting first-mover advantage as emerging EPA and state-level restrictions on fluorinated surfactants force portfolio replacements across legacy offshore chemical portfolios. Brazilian pre-salt development presents the most penetrable geography, with ANVISA registration compliance capabilities as the critical go-to-market angle for Petrobras-led procurement decisions. For Investors and Strategic Acquirers: PFAS regulatory tailwinds reshape the acquisition landscape toward specialists with PFAS-free formulation libraries and established EPA registration pathways. Long-term viability centers on suppliers capable of navigating divergent EPA, REACH, and MEE compliance timelines without duplicating toxicology expenditures. The signal to watch is EPA advancement of formal fluorinated surfactant restriction timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Feedstocks | Secures alkoxylation precursor supply against ethylene oxide volatility for Gulf Coast formulators. |
| PFAS-Free Formulation Library Development | Captures first-mover positioning as EPA restrictions force replacement cycles across offshore portfolios. |
| Microbial Treatment Technology Licensing | Enables Norwegian North Sea unmanned platform pilots with encapsulated bacterial consortia systems. |
| Digital Dosing Integration Partnership | Converges real-time separator monitoring with automated injection for performance-based supply contracts. |
| Brazilian Pre-Salt Technical Service Expansion | Positions for Petrobras-led ultra-deepwater demulsifier procurement with ANVISA registration capabilities. |
Study Parameters
The analysis maps surfactant blends, solvent carriers, microbial treatments, and membrane filtration technologies, each validated through petroleum process chemists, offshore platform operations managers, refinery desalter engineers, and oilfield service procurement leads. Primary interviews combined with secondary validation from EPA effluent guideline databases, ACC chemical trade data, SEC 10-K filings, and customs import records support bottom-up and top-down triangulation across segmentation dimensions.
Consistency checks validated volume and value outputs against external benchmarks including alkoxylation capacity utilization rates, offshore platform chemical inventory disclosures, and regional produced water treatment expenditure patterns. The analytical framework models product type, application setting, end-user consolidation patterns, and technology selection across the projection horizon, with CAGRs derived from segment-level demand elasticity and regulatory compliance cost trajectories. Forecast inputs incorporate water-cut reservoir maturity curves and unmanned platform automation adoption rates.
Underlying assumptions cover ethylene oxide feedstock price stability, EPA discharge threshold enforcement intensity, and petroleum process chemist pipeline recovery, with deviation risk concentrated in microbial treatment substitution velocity and PFAS regulatory acceleration. Forecasts reflect these documented conditions. Revision becomes warranted when microbial demulsification efficacy crosses operational reliability thresholds for continuous offshore deployment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Alkyl Acrylate Market
Industrial Chemicals
India Thermic Fluid Market
Industrial Chemicals
Global Microencapsulated Pesticides Market
Industrial Chemicals
Global Dodecanedioic Acid Market
Industrial Chemicals
Butadiene Extraction Market
Industrial Chemicals
Global Biochemical Market
Industrial Chemicals
Lime Manufacturing Market
Industrial Chemicals
1,4-Dioxane Market
Industrial Chemicals
Global Ethylene Carbonate Market
Industrial Chemicals
Bio Derived Enzymes for Detergents Market
Industrial Chemicals
Electronic Grade Trimethylindium Market
Industrial Chemicals
Northern Europe Calcium Sulphate Market
Industrial Chemicals
Global Flow Chemistry Market
Industrial Chemicals
Europe Molecular Sieve Market
Industrial Chemicals
Molecular Sieves Market
Industrial Chemicals
Kraft Lignin Products Market