
 Polymeric Optical Fiber Market | 2026-2036
Polymeric Optical Fiber Market Size, Share, and Industry Trends Forecast 2026-2036
Polymeric Optical Fiber Market Analytics
Software-defined fiber diagnostics is consolidating what buyers purchase alongside raw cable. Mitsubishi Rayon Co., Ltd. anchors Japanese supply through captive PMMA precursor production. Furukawa Electric Co., Ltd. leverages integrated compound-to-cable manufacturing to control cost curves. TE Connectivity Ltd. competes on connector interoperability across industrial fieldbus protocols.
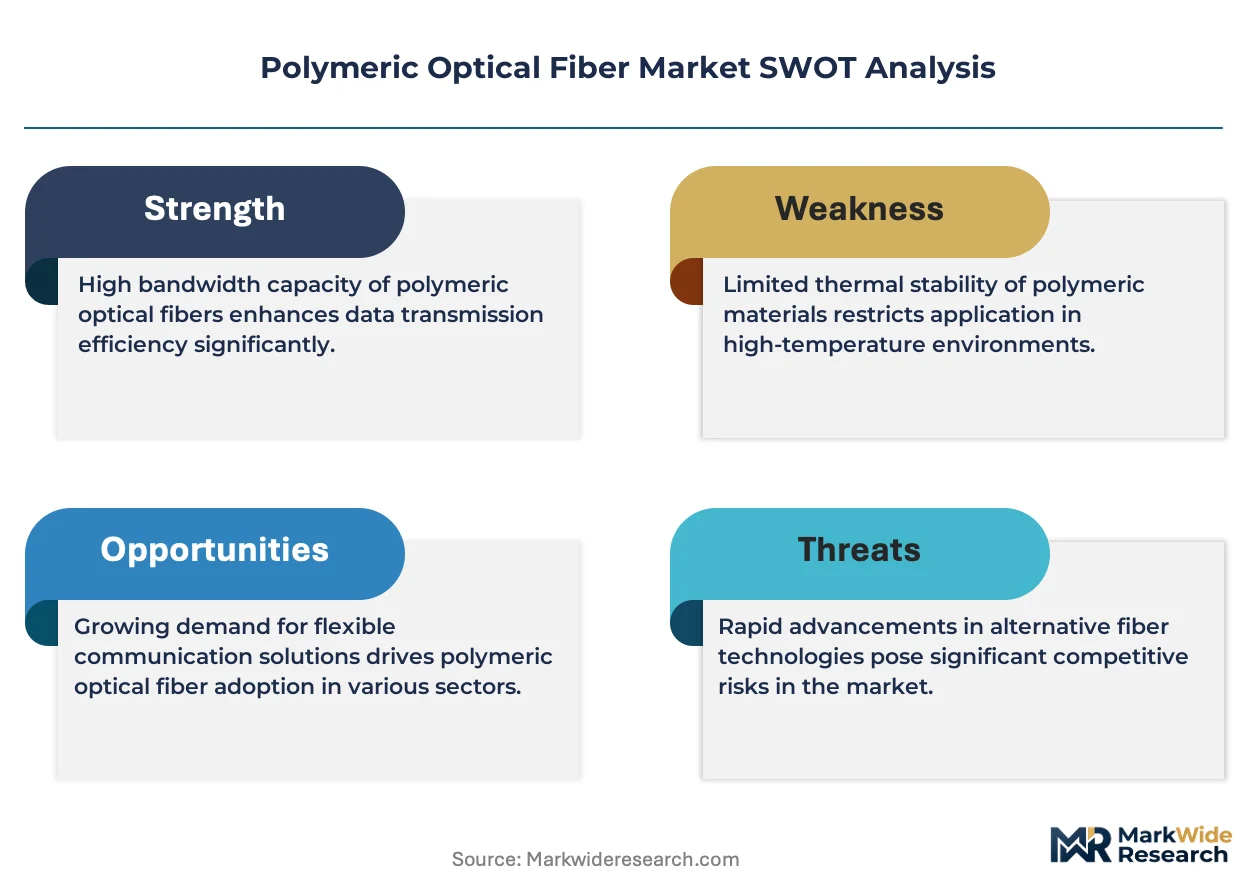
Polymeric optical fiber comprises a polymethyl methacrylate or perfluorinated polymer core sheathed in fluorinated cladding, transmitting light at 650 nm with attenuation typically between 100 and 200 dB per kilometer, serving short-reach data links where copper fails on electromagnetic immunity. Multi-mode fiber dominates volume owing to mature extrusion economics and compatibility with low-cost LED sources, while specialty fiber captures margin pools in medical imaging bundles where biocompatibility certifications command premium positioning. Sensor applications within the technology dimension are expanding fastest as distributed temperature and strain monitoring displace conventional electrical gauges in hazardous environments.
FDA 21 CFR biocompatibility requirements constrain medical-grade POF formulations, while REACH and RoHS in Europe restrict halogenated additives in consumer-facing cable jackets. IEC 60793 fiber optic test methods provide the interoperability baseline that enables cross-vendor procurement in industrial automation. Stakeholders must monitor how evolving EU F-Gas Regulation amendments affect perfluorinated polymer feedstock availability and cost structures.
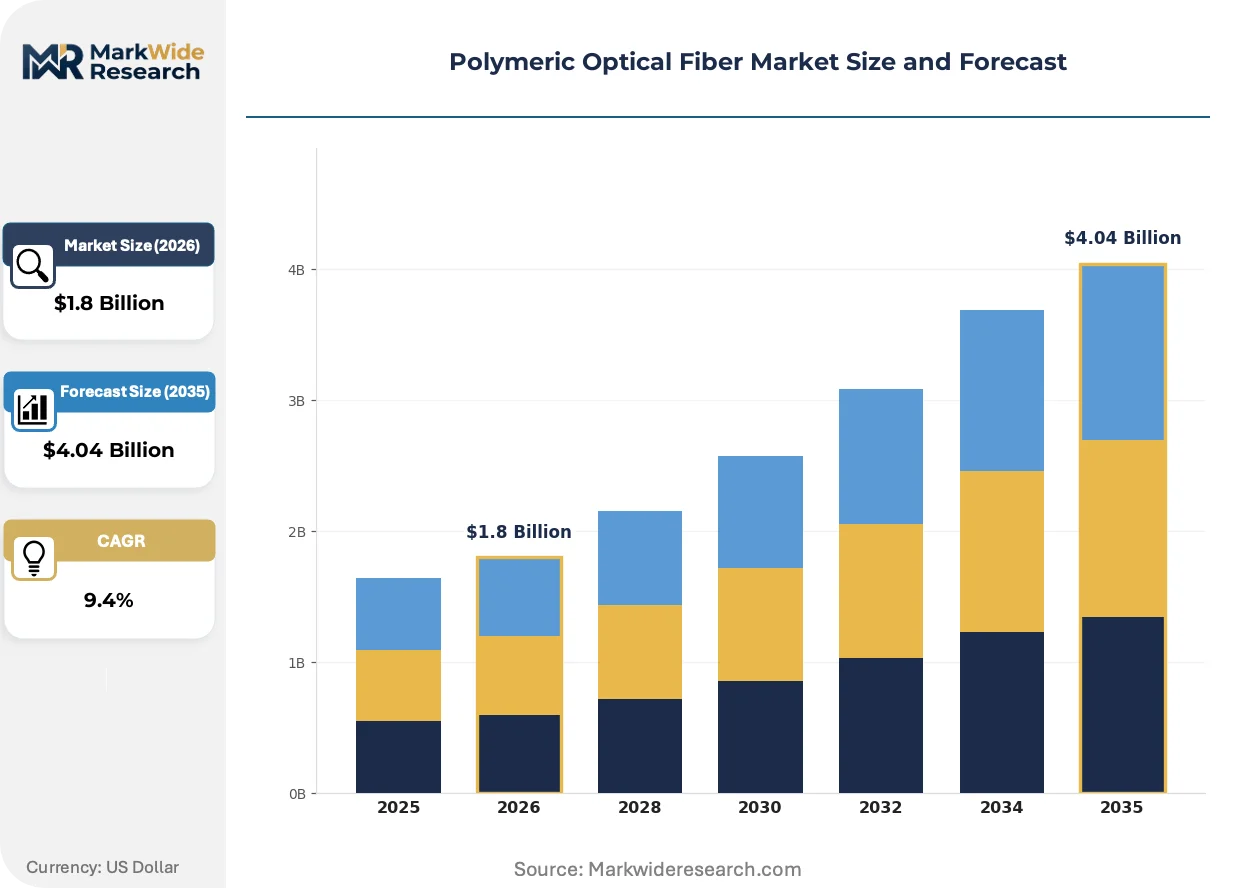
Market Dynamics
Automotive electrification is forcing a wholesale re-architecture of in-vehicle data backbones, with polymer optical fiber displacing copper harnesses in high-voltage zones where electromagnetic immunity is non-negotiable. Tier-1 suppliers now specify POF for battery management systems and infotainment loops, rewriting procurement criteria across Stuttgart, Detroit, and Nagoya simultaneously.
Growth Catalysts
- EU F-Gas Regulation tightening:Restrictions on perfluorinated greenhouse gases are accelerating R&D into low-attenuation halogen-free cladding formulations, opening compliant product lines for European industrial automation buyers.
- Automotive in-vehicle networking:Electric vehicle platforms in Germany and Japan are mandating optical isolation between powertrain and cabin domains, creating specification pull-through for multi-mode POF cable assemblies.
- Industrial sensor densification:Factory floors in Stuttgart and Munich are retrofitting with distributed temperature and strain monitoring, replacing electrical gauges in hazardous process environments with intrinsically safe POF sensor loops.
Market Restraints
- PMMA precursor supply concentration:Captive production of optical-grade polymethyl methacrylate monomer sits with a handful of Japanese chemical conglomerates, exposing cable converters to feedstock allocation risk during capacity tightness.
- Attenuation-distance tradeoff:Polymeric fiber's 100-200 dB/km loss envelope caps usable reach below 100 meters, disqualifying POF from campus backbone and metro access applications where silica fiber dominates.
- Perfluorinated polymer cost volatility:Cytop and perfluorinated cladding resins track fluorochemical feedstock indices, compressing margins for medical imaging bundle manufacturers when petrochemical spreads widen.
Strategic Opportunities
- Medical imaging bundle certification:FDA 21 CFR biocompatibility pathways for implantable POF remain underdeveloped; first-movers capturing Class II device approvals will command premium positioning in endoscopic and surgical illumination.
- RoHS-driven halogen-free conversion:European consumer electronics cable mandates are pushing jacket compound innovation, rewarding compounders with validated phosphorus-nitrogen flame retardant systems.
- Software-defined fiber diagnostics convergence:Integration of OTDR analytics with POF installations enables predictive maintenance contracts, shifting revenue models from commodity cable to recurring service streams in industrial automation accounts.
Industry Challenges
- Optical connector interoperability:Fieldbus protocol fragmentation across PROFINET, EtherCAT, and SERCOS III forces cable assemblers to maintain excessive SKU diversity, inflating inventory carrying costs.
- IEC 60793 test method adaptation:Standardized attenuation and bandwidth measurement protocols for plastic fiber lag silica fiber equivalents, creating certification timeline uncertainty for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymeric Optical Fiber Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multi-mode Fiber, Single-mode Fiber, Specialty Fiber, Hybrid Fiber End User: Telecommunications, Consumer Electronics, Medical Applications, Industrial Automation Installation Type: Indoor, Outdoor, Specialty Installations, Temporary Setups Technology: Active Devices, Passive Devices, Sensors, Network Solutions |
| Companies Covered | Furukawa Electric Co., Ltd., Amphenol Corporation, Corning Incorporated, Mitsubishi Rayon Co., Ltd., TE Connectivity Ltd., 3M Company, Sumitomo Electric Industries, Ltd., Toray Industries Inc., Asahi Kasei Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymeric Optical Fiber Market Evolving Landscape
Perfluorinated graded-index fiber is overtaking step-index PMMA in performance-critical niches, while regulatory chemistry constraints and diagnostic software integration are rewiring how value is captured across the value chain.
Graded-index perfluorinated polymer fiber is overtaking conventional step-index PMMA in automotive and medical applications where bandwidth-distance product determines system architecture. Tier-1 automotive suppliers in Germany and Japan are specifying GI-POF for 500 Mbps+ infotainment links, compressing the addressable market for legacy step-index constructions. This technology is overtaking copper-based shielded twisted pair in battery electric vehicle zones where galvanic isolation and weight reduction carry equal design priority.
REACH and RoHS amendments in Europe are tightening permissible halogen content in cable jackets and cladding compounds, forcing compounders to reformulate with phosphorus-nitrogen intumescent systems. The industrial consequence is a bifurcation between REACH-compliant premium grades and legacy halogenated constructions locked out of European consumer-facing applications. Medical device manufacturers targeting European notified body approvals are responding by front-loading biocompatibility testing for halogen-free POF bundles to preempt regulatory rejection.
Buyers in German industrial automation clusters are unbundling cable procurement from installation and diagnostics, treating fiber infrastructure as a managed service rather than capital equipment. System integrators in Stuttgart and Munich are capturing this shift by offering subscription-based health monitoring of POF sensor networks, displacing traditional distributor markups with recurring revenue streams. This behavioral pivot is most visible in automotive OEM captive plants, where total cost of ownership models now dominate pure cable price evaluation.
Polymeric Optical Fiber Market Segmentation
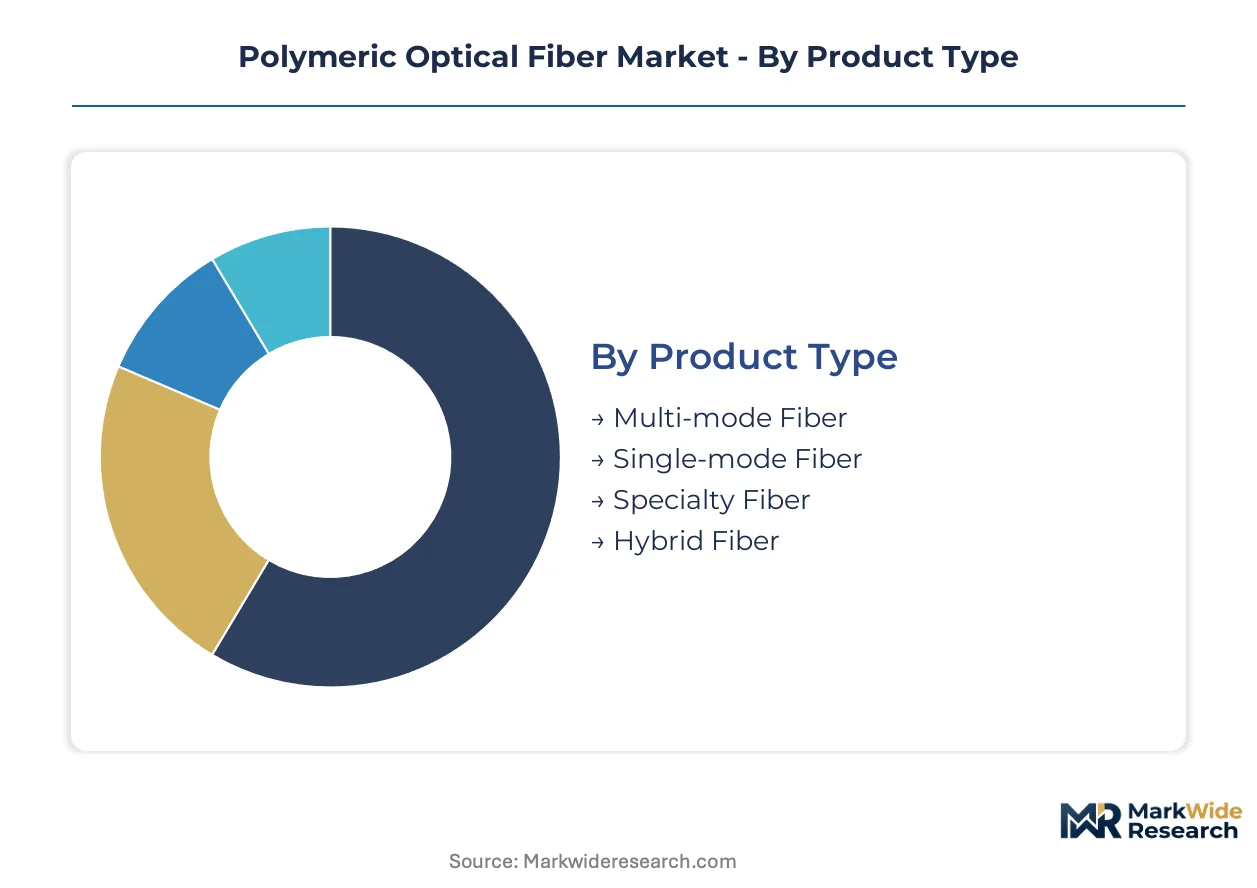
POF procurement patterns diverge sharply by application environment and performance requirements. Buyers in automotive and medical verticals prioritize biocompatibility and electromagnetic immunity over raw bandwidth, while industrial accounts weight diagnostic integration and fieldbus compatibility more heavily than cable cost alone.
Product Type:
Cost tier separates commodity extrusion buyers from performance-driven specification engineers.
- Multi-mode Fiber:Step-index PMMA construction dominates volume economics with 100-200 dB/km attenuation at 650 nm wavelength. German automotive OEMs in Stuttgart specify multi-mode POF for battery management system isolation loops, driven by mandatory galvanic separation between high-voltage powertrain and cabin domains.
- Specialty Fiber:Graded-index perfluorinated polymer cores deliver 500 Mbps+ bandwidth-distance products for endoscopic illumination bundles. FDA 21 CFR biocompatibility certification requirements constrain formulation options, limiting qualified suppliers and supporting premium positioning in surgical device supply chains.
- Single-mode Fiber:Niche construction for precision sensing applications requiring modal noise suppression.
- Hybrid Fiber:Composite constructions blending polymer and silica segments for transitional reach requirements.
Multi-mode fiber leads volumes today; graded-index specialty constructions are gaining share fastest in automotive infotainment specification.
End User:
Application maturity determines whether buyers treat POF as capital equipment or consumable infrastructure.
- Industrial Automation:Factory floors in Munich deploy distributed temperature and strain monitoring loops to replace electrical gauges in hazardous process zones. REACH-compliant halogen-free jacket compounds are becoming mandatory for European consumer-facing cable deployments, forcing compounders to validate phosphorus-nitrogen flame retardant systems.
- Medical Applications:Endoscopic and surgical illumination bundles require Class II device approvals under FDA 21 CFR biocompatibility pathways. European notified body pre-submissions are front-loading halogen-free POF testing to preempt regulatory rejection under tightening RoHS amendments.
- Telecommunications:Campus and access network applications where silica fiber attenuation advantages disqualify POF on reach grounds.
- Consumer Electronics:Short-reach interconnects facing RoHS-driven material conversion pressures in European markets.
Industrial automation leads volumes today; medical imaging bundles are climbing the fastest on certification scarcity premiums.
Installation Type:
Environmental exposure severity dictates jacket compound specifications and connector sealing requirements.
- Indoor:Controlled environment deployments in automotive assembly plants and medical device manufacturing.
- Outdoor:UV-stabilized jacket formulations for temporary event infrastructure and mobile sensor networks.
- Specialty Installations:Confined-space and hazardous-area deployments requiring intrinsically safe POF sensor loops in chemical processing facilities.
- Temporary Setups:Rapid-deployment configurations for automotive test tracks and trade show demonstration networks.
Indoor installations lead volumes today; specialty hazardous-environment deployments are expanding most quickly on safety regulation tightening.
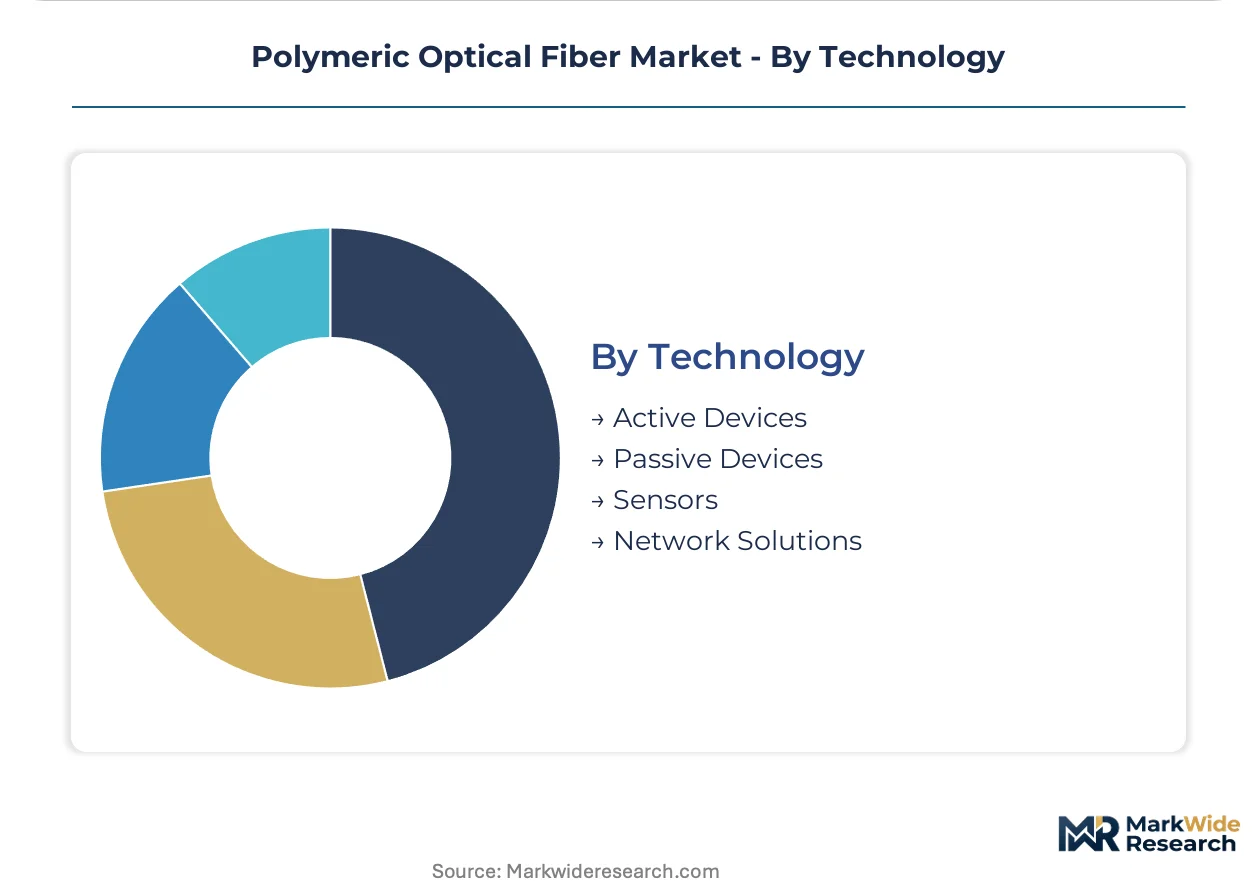
Technology:
System architecture choices determine whether procurement centers on passive cable or active subsystem integration.
- Sensors:Distributed fiber optic sensing displaces conventional electrical gauges for temperature and strain monitoring in German automotive OEM captive plants. OTDR analytics integration enables predictive maintenance contracts, shifting revenue models from commodity cable to recurring service streams.
- Network Solutions:Fieldbus protocol fragmentation across PROFINET, EtherCAT, and SERCOS III forces cable assemblers to maintain excessive SKU diversity for connector interoperability, inflating inventory carrying costs for system integrators.
- Passive Devices:Connectors, couplers, and splitters for signal distribution in multi-drop industrial networks.
- Active Devices:Transceivers and media converters bridging POF to copper or silica fiber infrastructure.
Sensor technology leads volumes today; network solutions integration is gaining share fastest on software-defined diagnostics convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands specification authority for automotive-grade POF assemblies, while Japan anchors captive precursor supply chains that constrain converter flexibility elsewhere.
United States
Automotive OEMs in Detroit specify POF for battery management system isolation on electric vehicle platforms. NHTSA electromagnetic compatibility guidelines are tightening shielding requirements for high-voltage harnesses. Tier-1 suppliers in Michigan are retrofitting assembly lines with POF-based sensor networks for predictive maintenance contracts.
Germany
Industrial automation clusters in Stuttgart and Munich deploy distributed fiber optic sensing to replace electrical gauges in hazardous process zones. EU F-Gas Regulation amendments are accelerating R&D into halogen-free cladding formulations for REACH compliance. Automotive OEM captive plants in Baden-Württemberg now mandate optical isolation between powertrain and cabin domains.
Japan
METI industrial technology roadmaps prioritize polymer optical fiber integration in factory automation networks. Captive production of optical-grade PMMA monomer concentrates with chemical conglomerates in the Kanto and Kansai regions. Nagoya-based Tier-1 suppliers specify graded-index POF for 500 Mbps+ infotainment links in battery electric vehicles.
China
MIIT standards for industrial fieldbus protocols are driving connector interoperability requirements for POF cable assemblers. Dual carbon goals are pressuring manufacturers to reformulate jacket compounds away from halogenated additives. Yangtze River Delta factory automation projects are adopting POF sensor loops for intrinsically safe temperature monitoring.
South Korea
MFDS biocompatibility pathways for implantable POF remain underdeveloped, creating first-mover opportunities in endoscopic device supply chains. Seoul Capital Area industrial parks are retrofitting with OTDR-integrated POF networks for predictive maintenance. Busan-Ulsan chemical processing facilities specify specialty POF installations for confined-space hazardous-area deployment.
Polymeric Optical Fiber Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated compound-to-cable producers capturing margin pools that converters cannot access. The vendor base organizes around three archetypes: captive precursor producers controlling feedstock economics, integrated cable manufacturers with in-house compounding capabilities, and connector specialists competing on fieldbus protocol interoperability. Consolidation pressure is mounting as automotive OEMs reduce qualified supplier lists, while backward integration into PMMA precursor production represents the dominant defensive maneuver for cable converters facing allocation risk.
Within the integrated manufacturing tier, Furukawa Electric Co., Ltd. and Mitsubishi Rayon Co., Ltd. exemplify the captive supply model that defines competitive positioning in this industry. TE Connectivity Ltd. occupies a position on the connector interoperability vector where fieldbus protocol fragmentation forces excessive SKU diversity. These three anchors demonstrate how geography and vertical scope determine which margin pools remain accessible to different competitive positions.
| Leading Market Players |
|---|
| Furukawa Electric Co., Ltd. |
| Amphenol Corporation |
| Corning Incorporated |
| Mitsubishi Rayon Co., Ltd. |
| TE Connectivity Ltd. |
| 3M Company |
| Sumitomo Electric Industries, Ltd. |
| Toray Industries Inc. |
| Asahi Kasei Corporation |
| Others |
Value Network & Pricing Analysis
Fluorochemical feedstock indices cascade through perfluorinated cladding resin costs, compressing margins for medical bundle manufacturers while REACH-compliant halogen-free formulations command 15-20% premia in European industrial automation procurement.
Pricing Analysis
Capacity additions in Japan are reshaping price floors for optical-grade PMMA monomer, forcing cable converters toward long-term offtake contracts to lock in feedstock economics. Three-tier pricing structure across premium, standard, and economy levels separates FDA 21 CFR-certified medical bundles from industrial-grade multi-mode constructions. Cost compression in standard-grade multi-mode cable is intensifying because automotive OEMs in Germany are consolidating qualified supplier lists. Tier-1 automotive buyers exhibit lowest price sensitivity due to total cost of ownership models dominating pure cable evaluation.
Supply Chain Analysis
Dual-sourcing mandates from German automotive OEMs are forcing cable assemblers to qualify secondary PMMA precursor suppliers beyond Japanese chemical conglomerates. Manufacturing gravity centers on Japan, Germany, and China, with optical-grade monomer production anchored in Kanto and Kansai regions. The value chain draws from fluorinated polymer feedstocks, PMMA monomer, and specialized jacket compounds. Single-source vulnerability concentrates in optical-grade PMMA precursor allocation. Distribution runs through Tier-1 automotive suppliers and system integrators in Stuttgart and Munich industrial clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through halogen-free formulation premiums and software-defined diagnostics bundling, with cost-down drivers emerging from extrusion automation and compound-to-cable integration.
For Market Incumbents: Anticipate REACH amendment acceleration by front-loading biocompatibility certification for halogen-free medical bundles before European notified body submission windows tighten. Defensive consolidation should prioritize backward integration into PMMA precursor production to neutralize Japanese chemical conglomerate allocation leverage, while expanding OTDR-integrated service contracts to capture recurring revenue streams displacing traditional distributor markups. For New Entrants and Emerging Players: The 30-40% price-point gap between graded-index perfluorinated specialty fiber and step-index PMMA commodity constructions offers entry space for mid-tier compounders with validated phosphorus-nitrogen flame retardant systems. South Korean medical device supply chains present the most penetrable white space given underdeveloped MFDS biocompatibility pathways for implantable POF. Go-to-market should target Busan-Ulsan chemical processing facilities with intrinsically safe sensor loop packages bundled with predictive maintenance analytics. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated compound-to-cable manufacturers possessing captive fluoropolymer formulation capabilities. Long-term viability over the projection horizon favors producers with dual REACH-RoHS compliance and automotive OEM qualification status. Acquisition targets should screen for OTDR software integration competencies. The signal to watch is EU F-Gas Regulation amendment timing affecting perfluorinated polymer feedstock availability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PMMA Precursor | Captive monomer supply neutralizes Japanese chemical conglomerate allocation risk for cable converters. |
| Halogen-Free Compound Certification | REACH-RoHS compliance unlocks European automotive and medical procurement specifications. |
| OTDR Diagnostics Platform Integration | Software-defined fiber health monitoring shifts revenue from commodity cable to recurring service contracts. |
| Graded-Index POF Capacity Expansion | 500 Mbps+ bandwidth-distance products displace step-index constructions in German automotive infotainment. |
| Medical Device Bundle Partnership | FDA 21 CFR Class II pathway access commands premium positioning in surgical illumination supply chains. |
Research Methodology
Multiple input streams — executive interviews with Tier-1 automotive procurement officers, technical discussions with compound R&D directors, and validation sessions with industrial system integrators in Stuttgart and Munich — were reconciled against customs trade data, IEC 60793 certification records, and SEC filings from integrated cable manufacturers. Bottom-up volume modeling across end-use segments was cross-checked against top-down industry association aggregates.
Data-stream reconciliation applied a structured analytical framework across the analysis window, modeling product type, end-user vertical, installation environment, and technology integration dimensions. CAGRs were derived from segment-level trajectory blending. Forecast inputs incorporated EU F-Gas Regulation amendment scenarios and automotive electrification platform deployment curves.
Caveats apply where PMMA precursor capacity tightness or fluorochemical feedstock volatility could materially shift the outlook. Deviation in REACH enforcement intensity or automotive OEM supplier consolidation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Advanced Optics Market
Optics
Fiber Optics Market
Optics
Photonics Sensor Market
Optics
Camera Module Lens Market
Optics
Glass Scintillator Market
Optics
Optical Profilometer Market
Optics
Global Semiconductor Lasers Market
Optics
Optical Imaging Market
Optics
Middle East and Africa Optical Imaging Market
Optics
Photonic Crystals Market
Optics
Asia-Pacific Anti-Blue Ray Myopia Lenses Market
Optics
Optical Fiber Market
Optics
North America Optical Imaging Market
Optics
Optical Telephoto Lens Market
Optics
Optical Wavelength Service Market
Optics
Fiber-Optic Filters Market