
 Hydrocracking Market | 2026-2036
Hydrocracking Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrocracking Market Foresight
Middle Eastern refinery expansion is hardening the global supply outlook for hydrocracking technology and catalyst systems. ExxonMobil leverages its integrated refining-chemicals footprint to sustain long-term catalyst supply agreements across multiple licensing jurisdictions. Chevron anchors its competitive position through proprietary hydrocracking process technology developed at its Richmond research complex. Sinopec dominates domestic hydrocracker deployments through captive engineering subsidiaries and state-backed project finance.
Hydrocracking is a catalytic refining process that operates at elevated hydrogen partial pressures and temperatures to crack heavy hydrocarbon feedstocks into lighter, higher-value products such as diesel, jet fuel, and naphtha. The process typically employs bifunctional catalysts containing acidic supports and metal hydrogenation components to achieve simultaneous cracking and saturation reactions. Fixed-bed hydrocracking technology occupies the largest installed base due to operational reliability and established catalyst regeneration protocols, while slurry-phase systems are gaining traction for processing ultra-heavy residuum and unconventional feedstocks. Diesel fuel applications command the most substantial margin pool among product categories, though light distillates output is expanding fastest in petrochemical-integrated refineries targeting aromatics and olefins precursors.
EPA fuel sulfur regulations and the EU F-Gas Framework shape hydrocracker investment cycles by mandating progressively lower product sulfur content and restricting fluorinated greenhouse gas emissions from associated refrigeration systems. India's BIS auto fuel norms and China's GB VI emission standards enforce comparable sulfur limits, creating synchronized upgrade demand across major refining centers. Stakeholders must monitor catalyst lifecycle economics and hydrogen supply cost trajectories as feedstock quality deteriorates and carbon intensity disclosure requirements expand.
Market Dynamics
Refiners face mounting pressure to process heavier, higher-sulfur crude slates while simultaneously cutting carbon intensity in finished products. This tension between feedstock quality degradation and product specification tightening is forcing wholesale reassessment of conversion unit economics.
Growth Catalysts
- IMO 2020 Sulfur Caps:Marine fuel sulfur limits have redirected residual fuel oil volumes into hydrocracker feedstocks at Asian and Middle Eastern refineries.
- India:State-owned refiners are commissioning integrated hydrocracking trains at greenfield sites to meet BIS auto fuel norms and domestic diesel demand.
- Slurry-Phase Systems:Emerging hydrocracking configurations for ultra-heavy residuum are unlocking previously uneconomical unconventional feedstocks.
Market Restraints
- Hydrogen Supply Cost Volatility:Steam methane reforming economics and electrolyzer capacity constraints are elevating hydrogen procurement costs for hydrocracker operators.
- Catalyst Manufacturing Concentration:Specialized hydrocracking catalyst production clusters in Germany and Japan create supply vulnerability during trade disruptions.
- EU F-Gas Framework:Refrigeration system restrictions on fluorinated greenhouse gases complicate hydrocracker unit design and retrofit planning.
Strategic Opportunities
- China's Dual Carbon Goals:National oil companies are prioritizing hydrocracker efficiency upgrades to align refinery emissions trajectories with MEE guidelines.
- Petrochemical Integration:Hydrocracker light distillates output is redirecting toward aromatics and olefins precursors production at integrated refining-chemicals complexes.
- Biomass Co-Processing:Hydrocracker units configured for renewable feedstock blends are accessing biofuel credit mechanisms in multiple jurisdictions.
Industry Challenges
- Catalyst Lifecycle Management:Deteriorating feedstock quality is compressing catalyst run lengths and complicating regeneration scheduling.
- Process Control Talent Gap:Specialized expertise in hydrocracker reaction kinetics and hydrogen management is concentrating among retiring operator cohorts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrocracking Market |
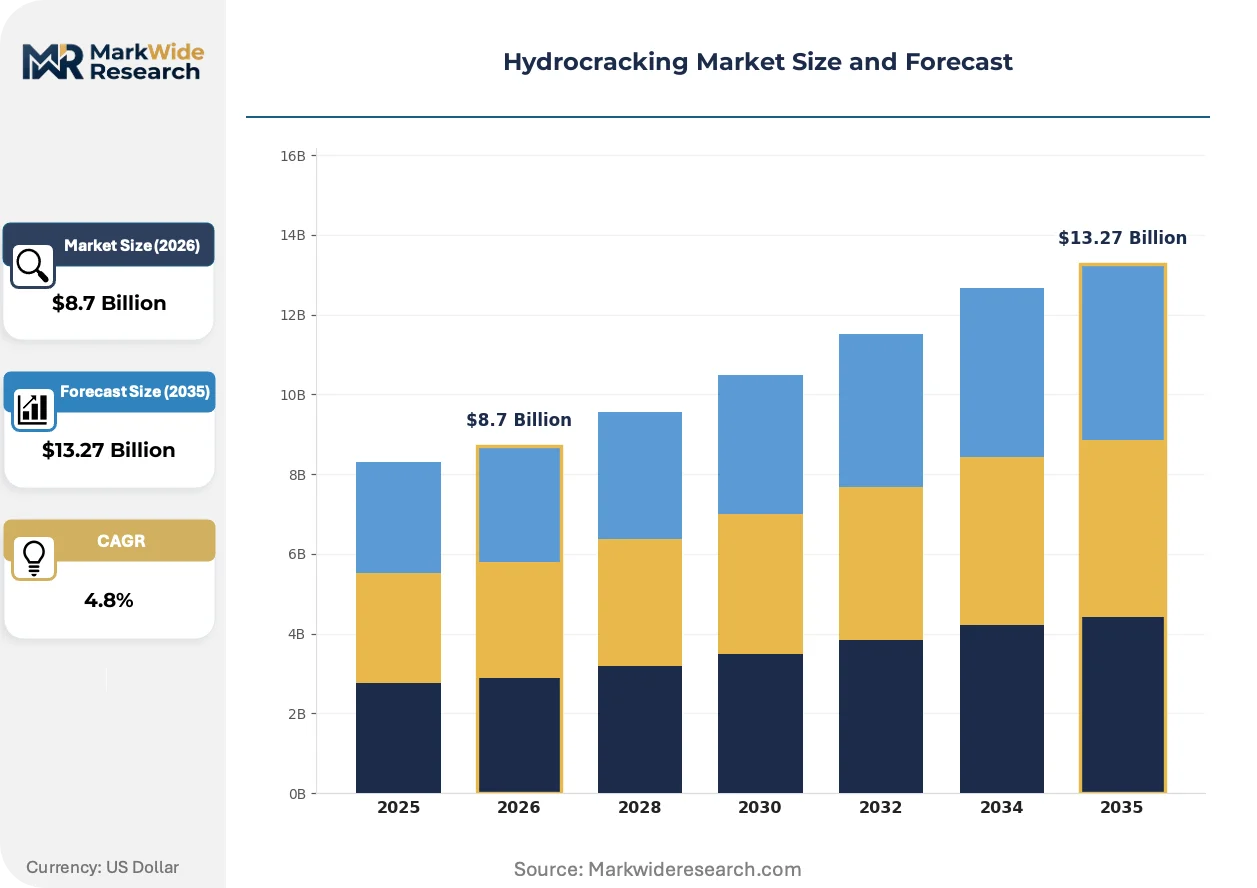
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Fixed-bed Hydrocracking, Fluidized-bed Hydrocracking, Slurry-phase Hydrocracking, Catalytic Hydrocracking End User: Refineries, Petrochemical Plants, Chemical Manufacturers, Fuel Producers Application: Light Distillates, Heavy Distillates, Liquefied Petroleum Gas, Diesel Fuel Feedstock: Vacuum Gas Oil, Atmospheric Gas Oil, Residuum, Shale Oil |
| Companies Covered | ExxonMobil, Chevron, Royal Dutch Shell, TotalEnergies, Sinopec, CNPC, Saudi Aramco, Valero Energy, Marathon Petroleum, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrocracking Market Shifts & Advancements
Process intensification and digital instrumentation are converging to reshape hydrocracker unit economics. These developments are compressing the gap between fixed-bed reliability and slurry-phase flexibility.
Advanced bifunctional catalyst formulations with tailored acidic supports and optimized metal hydrogenation components are absorbing heavier metals and nitrogen contaminants without catastrophic deactivation. Refiners processing high-TAN crudes in the US Gulf Coast and Middle East are adopting these materials to extend cycle lengths. The technology is absorbing incremental feedstock quality risk that would otherwise force premature unit shutdowns.
EPA fuel sulfur regulations are tightening diesel and jet fuel specifications through progressive sulfur content mandates. Refiners must now achieve sub-10 ppm sulfur levels while managing associated hydrogen consumption increases. US operators are responding with stacked reactor configurations and intermediate hydrogen quench systems.
Buyers are consolidating procurement of hydrocracking technology and catalyst systems under long-term performance contracts rather than discrete equipment purchases. Engineering-procurement-construction firms are absorbing lifecycle accountability that previously sat with refinery operators. This shift is most pronounced in India and China, where national oil companies favor integrated service agreements over fragmented vendor management.
Hydrocracking Market Segmentation
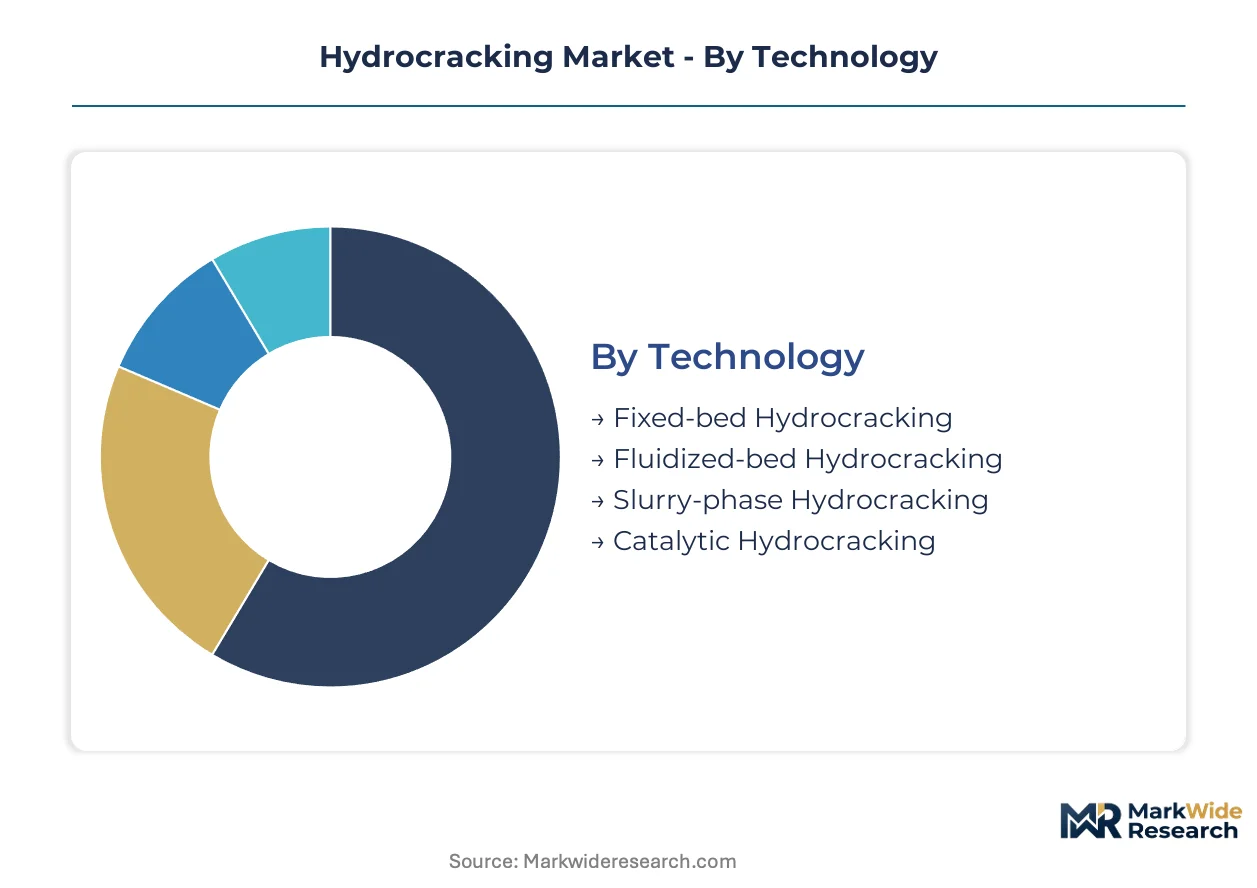
Segmentation in hydrocracking reveals how technology choices, feedstock quality, and end-product specifications interconnect to determine unit economics. Refiners select configurations based on hydrogen availability, catalyst regeneration capabilities, and target product slates rather than optimizing single variables.
Technology:
Upgrade cycles favor established platforms with proven catalyst regeneration protocols over unproven configurations.
- Fixed-bed Hydrocracking:Bifunctional catalysts in stacked reactor configurations dominate installed capacity. Indian and Chinese refiners favor this technology for BIS and GB VI compliance due to operational predictability and established maintenance schedules.
- Slurry-phase Hydrocracking:Dispersed catalyst systems process residuum with metals content exceeding fixed-bed tolerance. Middle Eastern operators deploy these units for ultra-heavy crude upgrading where conventional catalysts would deactivate prematurely.
- Fluidized-bed Hydrocracking:Continuous catalyst circulation enables heavier feedstock processing with online catalyst replacement. Limited commercial deployment outside Chevron's proprietary licensing network.
- Catalytic Hydrocracking:Term encompasses heterogeneous catalyst systems across process configurations. Sinopec's captive engineering subsidiaries optimize these systems for domestic crude characteristics.
Fixed-bed Hydrocracking sits at the top of the volume ranking, with Slurry-phase Hydrocracking climbing the fastest.
End User:
Customer type determines procurement structure, with national oil companies favoring integrated service agreements over fragmented vendor management.
- Refineries:Integrated conversion units processing atmospheric and vacuum gas oil into transportation fuels. Indian Oil Corporation and Saudi Aramco deploy hydrocracking trains at greenfield complexes to meet domestic diesel demand and export specifications.
- Petrochemical Plants:Hydrocracker light distillates feed aromatics and olefins production. Chinese refining-chemicals complexes redirect naphtha output toward para-xylene and ethylene precursors under dual carbon goals.
- Chemical Manufacturers:Specialty producers requiring high-purity feedstocks for downstream synthesis. Limited scale relative to refining integration.
- Fuel Producers:Blending operations sourcing hydrocracked components for finished product pools. Marine fuel suppliers access hydrocracker bottoms for IMO 2020-compliant very low sulfur fuel oil.
Refineries capture the dominant share of installed capacity, while Petrochemical Plants expand most quickly through refining-chemicals integration.
Application:
Product slate determines hydrogen consumption intensity and margin capture potential across downstream markets.
- Diesel Fuel:Maximum margin pool among hydrocracker products. EPA and EU sulfur regulations enforce sub-10 ppm specifications, requiring intermediate hydrogen quench systems at US Gulf Coast facilities.
- Light Distillates:Naphtha-range output redirects toward petrochemical feedstocks. Chinese operators prioritize this stream for aromatics integration under MEE emissions guidelines.
- Heavy Distillates:Higher-boiling fractions including jet fuel and heating oil components. Jet fuel specifications tighten under ICAO carbon offset requirements.
- Liquefied Petroleum Gas:Lightest hydrocracker yield stream. Limited value capture relative to liquid products; often recycled as refinery fuel.
Diesel Fuel maintains the largest revenue contribution, though Light Distillates gains share fastest from petrochemical integration trends.
Feedstock:
Quality degradation in available crudes is compressing catalyst run lengths and forcing regeneration schedule adjustments.
- Vacuum Gas Oil:Primary hydrocracker feedstock from vacuum distillation units. Standard feed for fixed-bed units processing medium-gravity crudes.
- Atmospheric Gas Oil:Lighter fraction requiring less hydrogen consumption. Favored where hydrogen supply costs constrain operations.
- Residuum:Heaviest refinery stream with elevated metals and asphaltene content. Slurry-phase systems unlock this feedstock where fixed-bed catalysts would suffer rapid deactivation.
- Shale Oil:Light tight oil with varying paraffin content. US Permian Basin production supplies domestic hydrocrackers with lower hydrogen demand than imported heavy crudes.
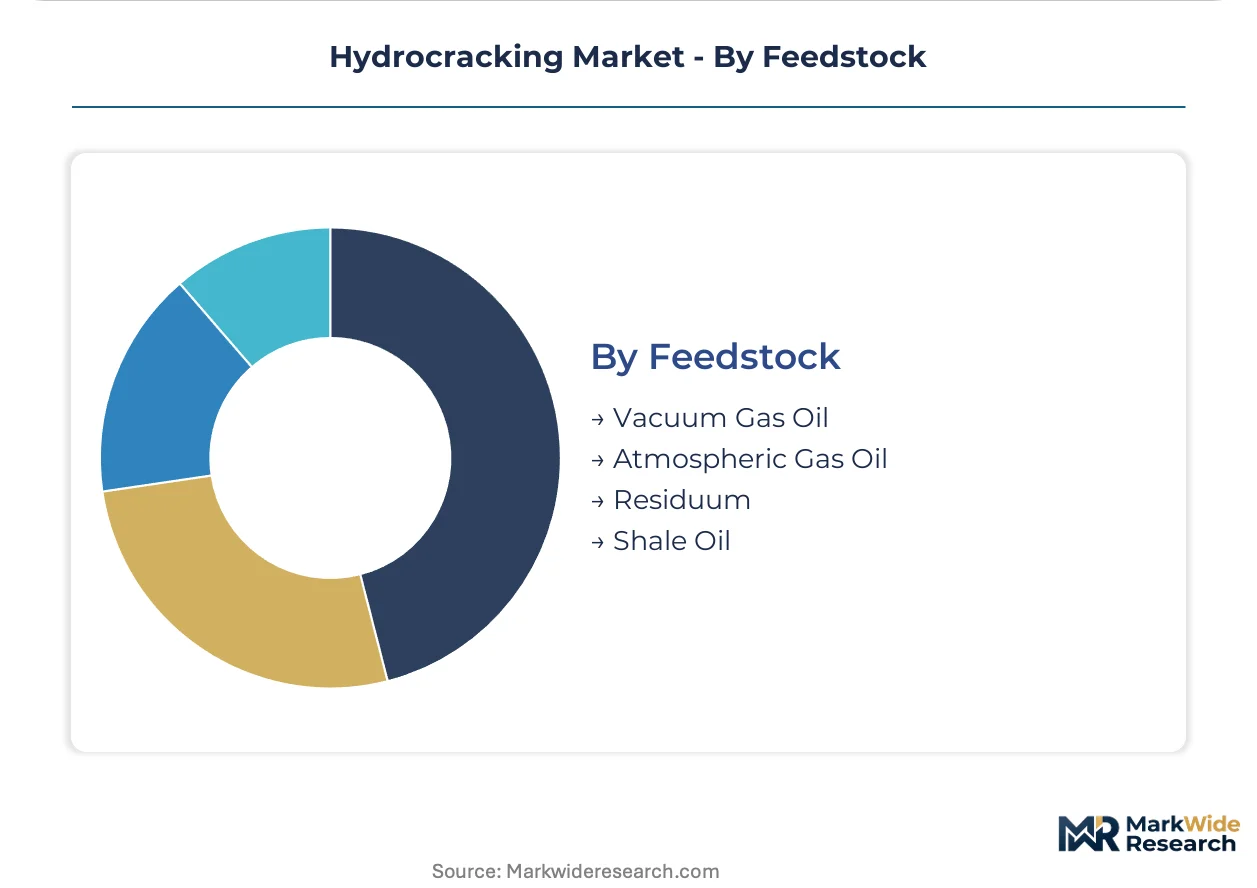
Vacuum Gas Oil dominates feedstock intake volumes, with Residuum expanding most quickly as refiners process heavier available slates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China processes heavier crude slates than the United States, yet both markets face tightening sulfur specifications that reshape hydrocracker investment cycles. India and the Middle East are commissioning greenfield units at faster rates than European refiners focused on retrofit economics.
United States
Gulf Coast refiners process Permian Basin light tight oil through hydrocracking trains configured for lower hydrogen intensity than heavy crude units. EPA Tier 3 gasoline standards enforce sub-10 ppm sulfur limits across finished diesel pools. Houston and Beaumont host the densest concentration of hydrocracker capacity, where operators stack reactor configurations to manage intermediate hydrogen quench demands.
China
National oil companies expand hydrocracking capacity at integrated refining-chemicals complexes along the eastern seaboard. MEE guidelines under dual carbon goals mandate efficiency upgrades that redirect naphtha output toward para-xylene precursors. The Yangtze River Delta cluster anchors domestic deployment, with Sinopec's captive engineering subsidiaries optimizing catalyst systems for regional crude characteristics.
India
State-owned refiners commission integrated hydrocracking trains at greenfield sites to meet BIS auto fuel norms and domestic diesel demand. The BIS VI emission timeline accelerates conversion unit procurement across public sector undertakings. Gujarat and Maharashtra host the most active project development, with Indian Oil Corporation deploying trains at new coastal refineries targeting export specifications.
Saudi Arabia
Saudi Aramco anchors Middle Eastern hydrocracker expansion through integrated megaprojects processing ultra-heavy regional crudes. The kingdom's national industrial strategy prioritizes downstream conversion capacity over simple crude export. The Eastern Province concentrates deployment activity, where slurry-phase systems unlock residuum with metals content exceeding fixed-bed tolerance thresholds.
Germany
European refiners face retrofit economics under EU F-Gas Framework restrictions on fluorinated greenhouse gases in hydrocracker refrigeration systems. REACH compliance obligations compound catalyst procurement complexity for units processing Russian-origin feedstock alternatives. The Rhine-Ruhr industrial corridor maintains the most substantial installed base, where operators balance regeneration scheduling against deteriorating available crude quality.
Hydrocracking Market Competitive Landscape
United States and European producers anchor one tier of process technology licensing; Chinese and Middle Eastern specialists hold captive engineering capacity tied to national oil company procurement. The market structures around three archetypes: integrated supermajors with proprietary research complexes, state-backed national champions with captive project execution capabilities, and independent refiners relying on third-party technology packages. Competitive moves concentrate on long-term catalyst supply agreements and integrated service contracts that absorb lifecycle accountability from operators.
Within the integrated supermajor tier, ExxonMobil and Chevron occupy positions defined by proprietary technology development and sustained licensing relationships across multiple jurisdictions. ExxonMobil leverages its integrated refining-chemicals footprint to anchor catalyst supply agreements, while Chevron represents the proprietary process technology archetype developed at its Richmond research complex. Sinopec exemplifies the state-backed national champion model, dominating domestic deployments through captive engineering subsidiaries and state-backed project finance structures that consolidate procurement under integrated service agreements.
| Leading Market Players |
|---|
| ExxonMobil |
| Chevron |
| Royal Dutch Shell |
| TotalEnergies |
| Sinopec |
| CNPC |
| Saudi Aramco |
| Valero Energy |
| Marathon Petroleum |
| Others |
Supply & Pricing Matrix
Catalyst performance tier divergence between premium bifunctional formulations and commodity hydroprocessing materials manifests in both pricing spreads and supply chain configurations. Premium grades command sustained premiums through proprietary metal hydrogenation component ratios and tailored acidic support engineering, while commodity catalysts flow through distributor networks serving independent refiners in India and China.
Pricing Analysis
Distributor margin layers in hydrocracking catalyst procurement typically absorb 12-18 percent of final delivered cost, with direct-to-NOC agreements eliminating this markup entirely. Three-tier pricing structure across premium, standard, and economy levels tracks catalyst metals loading, with nickel-molybdenum formulations pricing above base metal alternatives. Pricing pressure stems from hydrogen supply cost volatility compressing refinery conversion margins and forcing catalyst budget cuts. National oil companies exhibit lowest price sensitivity due to state-backed project finance structures, while independent refiners in Europe demonstrate highest sensitivity to per-ton catalyst procurement costs.
Supply Chain Analysis
Hydrocracking catalyst supply rests on German and Japanese specialty chemical producers for proprietary bifunctional formulations, with Chinese state-backed manufacturers capturing domestic volume through Sinopec captive engineering subsidiaries. Critical inputs include alumina supports, rare earth promoters, and Group VIII metal hydrogenation components. Single-source vulnerability concentrates in advanced acidic support technologies held by BASF and Clariant manufacturing clusters. Distribution runs through long-term performance contracts that absorb lifecycle accountability, with EPC firms consolidating procurement for Indian and Middle Eastern greenfield deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hydrocracking market represents a late-cycle quality story as IMO 2020 sulfur caps and evolving EU Fuel Quality Directive standards force wholesale replacement of marginal conversion capacity with premium hydrocracker trains.
For Market Incumbents: Anticipate catalyst regeneration service demand compression as deteriorating feedstock quality shortens cycle lengths and forces premature unit shutdowns. Defensive consolidation moves center on backward integration into hydrogen supply infrastructure and captive engineering subsidiary expansion in India. Priority lever: secure long-term catalyst supply agreements with Saudi Aramco and Indian Oil Corporation before competitor licensing arrangements harden. For New Entrants and Emerging Players: Engineering-procurement-construction partnerships offer the most penetrable entry vector for slurry-phase hydrocracking technology licensing in Middle Eastern megaprojects. White-space targets include biomass co-processing catalyst configurations for EU biofuel credit mechanisms and ultra-heavy residuum units for Eastern Province expansion. Go-to-market angle: position as integrated service providers absorbing lifecycle accountability that incumbent licensors resist. For Investors and Strategic Acquirers: Consolidation pressure builds where catalyst manufacturing concentration intersects with deteriorating feedstock quality compressing run lengths. Long-term viability favors integrated supermajors with proprietary research complexes and state-backed national champions with captive project execution. Acquisition target archetype: independent catalyst regeneration technology specialists serving US Gulf Coast refineries. Signal to watch: hydrogen electrolyzer capacity buildout rates as inflection indicator for hydrocracker operating cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Catalyst Supply Agreement | ExxonMobil anchors multi-jurisdiction licensing relationships through sustained catalyst supply commitments. |
| Backward Integration into Hydrogen Supply | Refinery operators secure electrolyzer capacity to insulate hydrocracker economics from SMR volatility. |
| Slurry-Phase Technology Licensing | Chevron's proprietary Richmond research complex unlocks ultra-heavy residuum processing for Middle Eastern operators. |
| Biomass Co-Processing Configuration | Hydrocracker units access EU biofuel credit mechanisms through renewable feedstock blend capabilities. |
| Integrated Service Contract Consolidation | EPC firms absorb lifecycle accountability previously fragmented across multiple vendor relationships in India. |
Research Methodology
Bottom-up refinery capacity modeling reconciled against top-down catalyst production tracking forms the analytical core of this study. Primary interviews with hydrocracker unit managers, catalyst procurement leads at national oil companies, EPC project directors, and hydrogen supply specialists combined with secondary validation from EPA fuel sulfur regulation filings, EU F-Gas Framework documentation, BIS auto fuel norm publications, and SEC 10-K disclosures from integrated supermajors. Triangulation across these sources ensures segmentation integrity across technology configurations and regional deployment patterns.
Historical trendline analysis of hydrocracker capacity additions and catalyst consumption intensities established baseline growth parameters across the projection horizon. Segmentation dimensions modeled include technology type, end-user category, application product slate, and feedstock quality tier. CAGRs were derived through regression analysis of capacity deployment timelines against regulatory compliance deadlines, with specific incorporation of hydrogen supply cost trajectories and catalyst lifecycle compression factors from deteriorating crude quality.
Revisions become necessary when hydrogen electrolyzer capacity buildout accelerates beyond SMR economics, or when EU F-Gas Framework restrictions force premature refrigeration system retrofits. Forecasts reflect documented assumptions regarding regulatory timeline adherence and feedstock quality degradation curves. A small set of named triggers warrants ongoing watch: MEE guideline enforcement patterns in China, BIS VI implementation adherence in India, and catalyst metals price volatility affecting formulation economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
South America LNG Bunkering Market
Oil & Gas
Nigeria Wireline Logging Services Market
Oil & Gas
North America Directional Drilling Services Market
Oil & Gas
Oil and Gas Pipeline Coatings Market
Oil & Gas
Swellable Packers Market
Oil & Gas
Mining and Oil & Gas Fasteners Market
Oil & Gas
Oil and Gas Seals Market
Oil & Gas
Europe Well Intervention Market
Oil & Gas
Offshore Drilling Fluid Market
Oil & Gas
Smart Well Market
Oil & Gas
Middle-East and Africa Frac Stack Market
Oil & Gas
Land Drilling Rig Market
Oil & Gas
Vietnam Oil and Gas Market
Oil & Gas
United States Artificial Lift Systems Market
Oil & Gas
Brazil Wireline Logging Services Market
Oil & Gas
Thermal Spray Coating for Oil and Gas Market