
 Asia-Pacific Mortgage/Loan Brokers Market | 2026-2036
Asia-Pacific Mortgage/Loan Brokers Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Mortgage/Loan Brokers Market Analysis
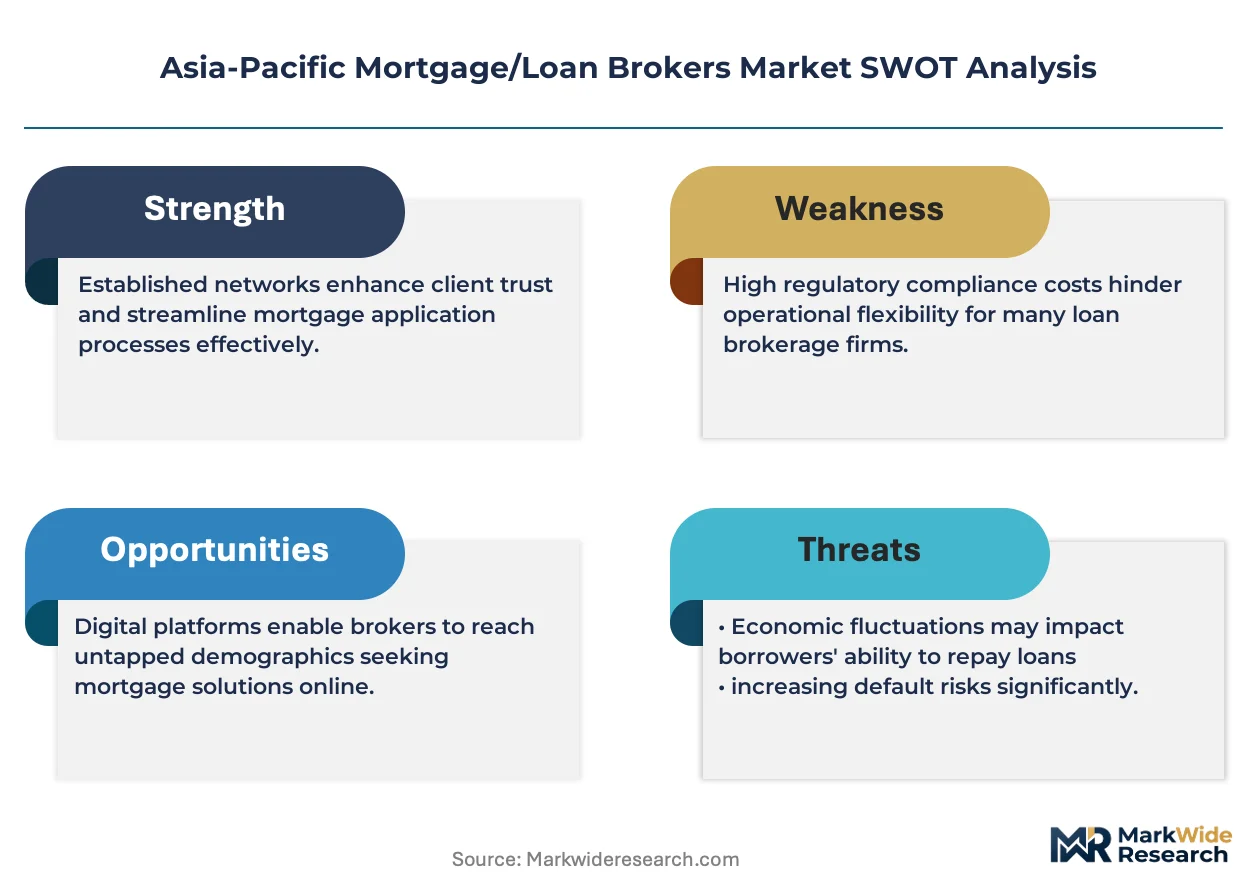
The capital-intensity divergence between full-service deposit banks and nimble non-bank financial companies is bifurcating the Asia-Pacific mortgage intermediary landscape. Prestia SMBC Trust Bank leverages its parent bank's balance sheet to sustain long-term fixed-rate offerings in Japan's low-yield environment. CNFinance Holdings Limited competes through localized credit assessment networks across China's Pearl River Delta manufacturing towns.
Asia-Pacific mortgage and loan brokers are licensed intermediaries that match borrowers with lenders, earning commission income rather than balance-sheet spread; their core function centers on credit file packaging, rate comparison, and settlement coordination across fragmented banking systems. Residential broking anchors commission pools across most markets, while AI-based Services within the Technology segment is attracting venture investment for automated income verification and property valuation. Fixed-rate Mortgages dominate Australia's offering mix as borrowers seek payment certainty against RBA volatility, whereas Variable-rate Mortgages lead in India where banks index to MCLR movements.
Japan's Financial Services Agency, India's RBI, and Australia's APRA each enforce distinct capital adequacy and consumer disclosure regimes that determine which broker categories qualify for lender panel inclusion. China's SAMR and NMPA frameworks extend oversight to fintech-originated loans, tightening data governance for online platform intermediaries. Stakeholders must monitor how regulator-mandated open banking APIs reshape borrower data access and commission structures across the region.
Market Dynamics
Japan's Financial Services Agency disclosure mandates are compressing commission spreads while India's RBI open banking directives are unlocking borrower data portability, forcing intermediaries to rebuild revenue models around advisory depth rather than rate arbitrage.
Growth Catalysts
- APRA lending standard reforms:Australia's tightened responsible lending obligations are steering first-time buyers toward licensed brokers for compliance navigation, expanding panel qualification demand.
- AI-based income verification:Automated document parsing is slashing credit file preparation time across Southeast Asian markets, accelerating broker throughput per loan officer.
- Pearl River Delta manufacturing clusters:CNFinance Holdings' localized credit assessment networks are penetrating informal employment segments previously excluded from formal mortgage channels.
Market Restraints
- Deposit bank balance sheet dominance:Prestia SMBC Trust Bank's parent-funded fixed-rate offerings in Japan's low-yield environment crowd out independent brokers on rate competitiveness.
- SAMR data governance tightening:China's SAMR and NMPA frameworks impose escalating compliance costs on fintech-originated loan platforms, raising operational barriers for digital intermediaries.
- MCLR volatility exposure:India's variable-rate mortgage concentration leaves borrowers and brokers vulnerable to central bank policy swings, compressing refinancing fee predictability.
Strategic Opportunities
- Tier-2 Indian cities:Broker penetration in Indore, Lucknow, and Coimbatore lags metro saturation, creating whitespace for commission-based origination networks.
- Open banking API integration:Australia's Consumer Data Right and India's Account Aggregator framework enable real-time borrower verification, unlocking subscription advisory models.
- Suburban Australian corridors:Post-pandemic housing demand rotation toward Geelong, Sunshine Coast, and Wollongong is redistributing broker geographic deployment.
Industry Challenges
- Credit assessment specialization:Tier-2 city informal employment documentation requires field-level underwriting expertise that conflicts with centralized digital platform scaling.
- Legacy core banking integration:Australia's major lender proprietary systems resist API standardization, forcing brokers to maintain multiple submission portals and fragmenting workflow automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Mortgage/Loan Brokers Market |
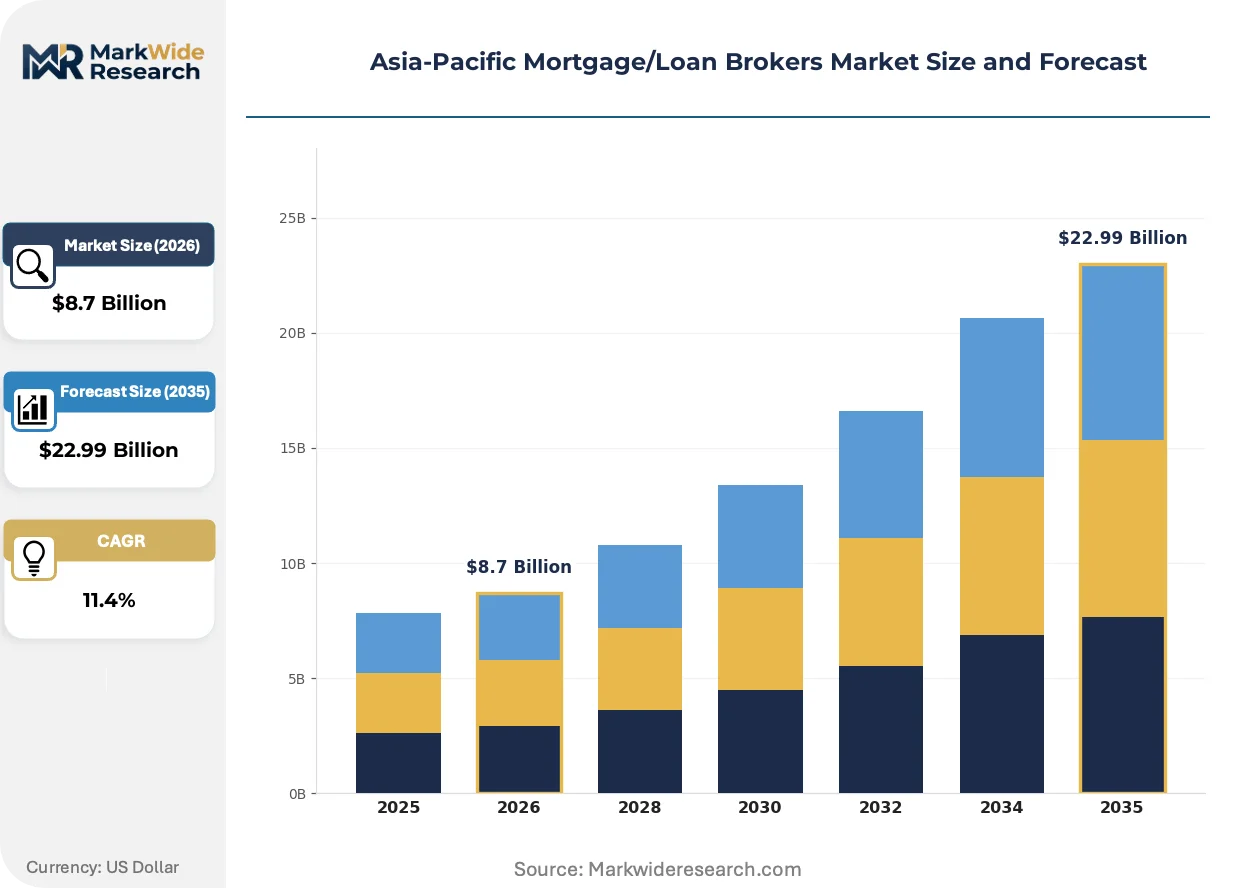
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Residential, Commercial, Personal, Auto Client Type: First-time Buyers, Investors, Refinancers, Builders Offering: Fixed-rate Mortgages, Variable-rate Mortgages, Home Equity Loans, Debt Consolidation Technology: Online Platforms, Mobile Apps, CRM Solutions, AI-based Services |
| Companies Covered | Prestia SMBC Trust Bank, CNFinance Holdings Limited, LIC Housing Finance Ltd, Tokyo Star Bank, Shinsei Bank, ICICI Home Finance Company Ltd, Askari Bank, PNB Housing Finance Ltd, China Huirong Financial Holdings Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Mortgage/Loan Brokers Market Emerging Trajectories
Digital origination infrastructure is compressing the traditional broker value chain while regulatory data portability mandates are redefining competitive moats around borrower relationship depth rather than lender panel breadth.
Automated property valuation models (AVMs) leveraging satellite imagery and transaction databases are supplanting physical appraiser site visits for standard residential mortgages. Australian non-bank lenders have adopted AVMs for 60% of suburban refinances, cutting valuation turnaround from five days to four hours. This compression is enabling same-day conditional approvals that physical appraisal workflows cannot match, reshaping borrower expectations across Australia's broker channel.
India's RBI Account Aggregator framework mandates consent-based financial data sharing between regulated entities, eliminating manual document submission for income verification. Broker platforms integrating AA APIs are reducing loan file preparation from two weeks to 48 hours. Tier-2 city borrowers previously excluded due to documentation gaps are now qualifying through cash-flow-based scoring, expanding addressable mortgage demand beyond salaried employment segments.
First-time buyer segments across Southeast Asia are fragmenting from branch-centric bank relationships toward mobile-native broker comparison platforms. Indonesia and Vietnam's smartphone-first demographics are bypassing traditional lender direct channels, with aggregators capturing origination intent before lender-specific engagement. This rotation is compressing lender customer acquisition costs while elevating broker platform bargaining power for panel placement fees.
Asia-Pacific Mortgage/Loan Brokers Market Segmentation
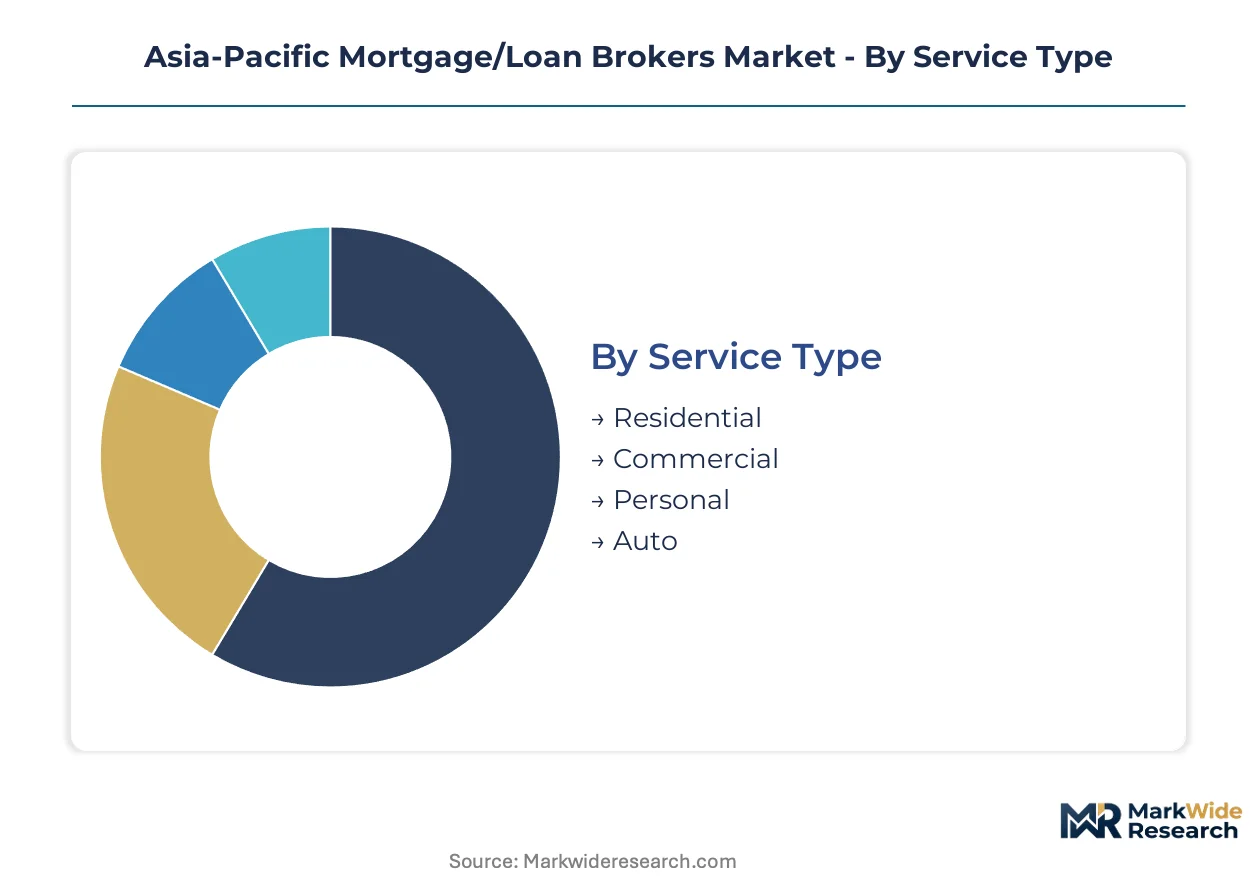
Broker revenue pools across Asia-Pacific fragment sharply by service specialization and borrower sophistication. Regulatory treatment of commission structures and data portability rights varies materially across each segment boundary, reshaping competitive positioning.
Service Type:
Residential broking concentrates domestically across suburban Australian corridors and India's tier-2 cities, while commercial and auto segments increasingly cross borders through regional lender panels.
- Residential:Salaried employment documentation and standardized property valuation workflows dominate credit file preparation. Australian first-time buyers in Geelong and Wollongong drive panel qualification demand under APRA's tightened responsible lending obligations.
- Commercial:Complex entity structuring and lease-based income verification require specialized underwriting expertise. India's manufacturing clusters across Indore and Coimbatore generate cross-border financing demand for industrial property acquisitions.
- Personal:Unsecured lending intermediation faces compressed margins from direct digital lender competition.
- Auto:Dealer-integrated financing dominates origination channels, limiting standalone broker penetration.
Residential commands the established base. The steepest expansion runs through Commercial.
Client Type:
Commission structures bifurcate between high-touch advisory relationships and transaction-only digital facilitation, with cost tiers determining service intensity per borrower category.
- First-time Buyers:Regulatory complexity navigation commands premium advisory fees. Australia's Consumer Data Right and India's Account Aggregator framework enable real-time verification, reducing documentation friction for salaried applicants in tier-2 cities.
- Investors:Portfolio structuring and cross-collateral optimization require sophisticated lender panel navigation. Negative gearing legislation changes in Australia and stamp duty reforms across Indian states reshape property acquisition timing.
- Refinancers:Rate arbitrage-driven switching behavior compresses per-loan commission duration.
- Builders:Construction-to-permanent financing timelines demand specialized drawdown coordination.
First-time Buyers anchor volume throughput. Investors deliver the highest margin per transaction.
Offering:
Product mix reflects central bank policy divergence across the region, with fixed-rate concentration in rate-volatile economies and variable-rate dominance where monetary transmission remains direct.
- Fixed-rate Mortgages:Payment certainty products index to long-term bond yields or swap rates. Australian borrowers facing RBA volatility favor three-to-five-year fixes, crowding out independent brokers competing against parent-bank balance sheet pricing.
- Variable-rate Mortgages:MCLR-linked products dominate Indian originations where banks pass through central bank adjustments. Refinancing fee predictability suffers under policy swing exposure, compressing broker revenue forecasting.
- Home Equity Loans:Second-lien positioning requires sophisticated senior lender consent navigation.
- Debt Consolidation:Unsecured liability restructuring faces regulatory scrutiny under responsible lending frameworks.
Fixed-rate Mortgages hold the volume lead. Home Equity Loans are climbing the fastest as property values appreciate.
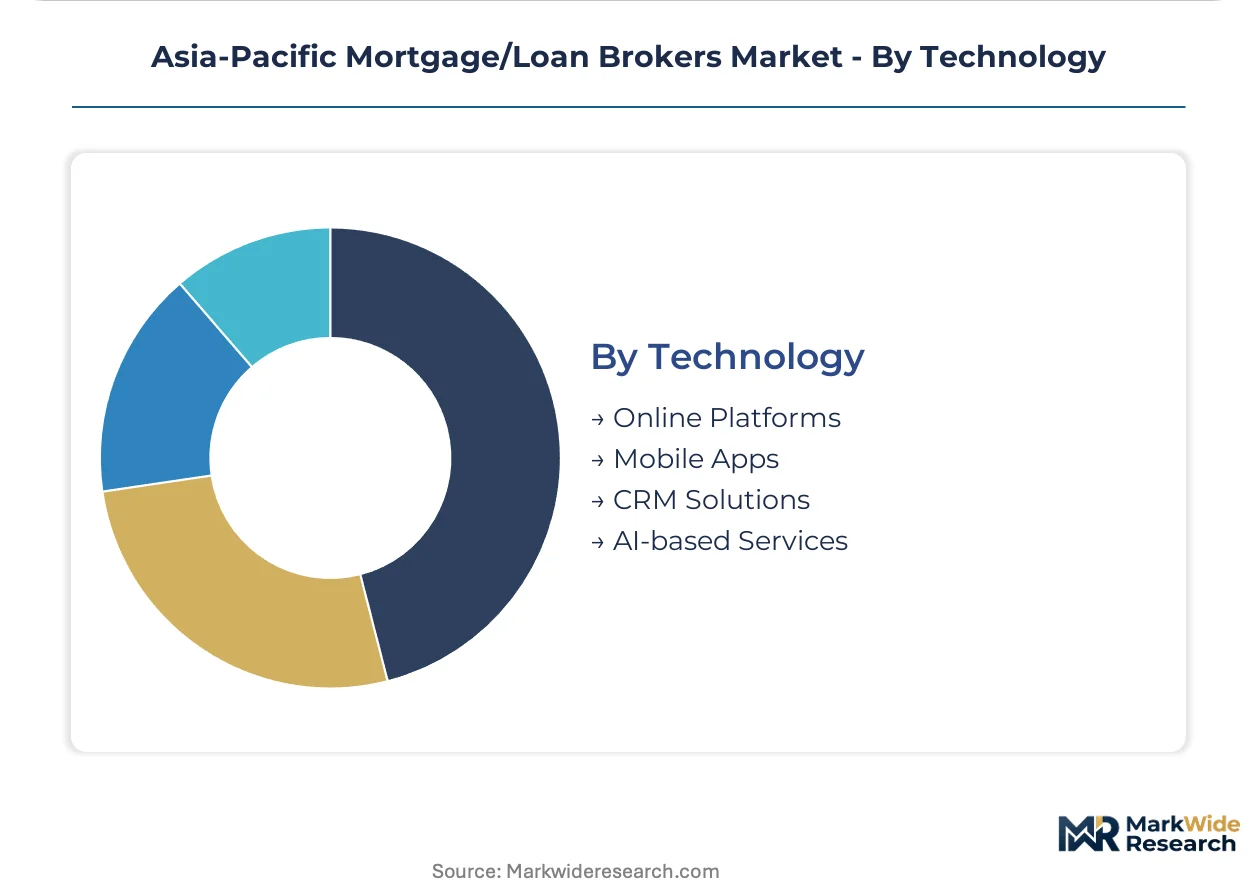
Technology:
Platform maturity stratifies across mobile-native Southeast Asian markets and legacy system-dependent developed economies, with AI deployment racing ahead in document-intensive verification workflows.
- AI-based Services:Automated income verification and property valuation models slash credit file preparation timelines. Australian non-bank lenders deploy satellite-imagery AVMs for suburban refinances, compressing turnaround from days to hours.
- Online Platforms:Aggregator models capture origination intent before lender-specific engagement across Indonesia and Vietnam's smartphone-first demographics. Commission compression follows as platform bargaining power elevates panel placement fees.
- Mobile Apps:Native application development concentrates in Southeast Asian markets with limited desktop infrastructure.
- CRM Solutions:Relationship management tooling remains fragmented across lender-proprietary submission portals.
Online Platforms dominate current deployment. AI-based Services are gaining share fastest through venture capital deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capital flows in mortgage intermediation tilt toward import-dependent financing structures across Southeast Asia, while Australia and Japan export broker-service expertise through regional licensing arrangements. India's outbound remittance-linked housing investment creates cross-border origination demand. China's capital account restrictions limit foreign broker participation despite outward property investment appetite.
Australia
Suburban corridor expansion around Geelong, Wollongong, and Sunshine Coast is redistributing broker deployment density. APRA's responsible lending obligation reforms steer first-time buyers toward licensed intermediaries for compliance navigation. Sydney and Melbourne's mortgage aggregator networks now extend panel qualification services into secondary cities.
India
Tier-2 city penetration in Indore, Lucknow, and Coimbatore lags metro saturation, creating whitespace for commission-based origination. RBI's Account Aggregator framework mandates consent-based financial data sharing, eliminating manual document submission. Manufacturing clusters across Gujarat and Tamil Nadu generate cross-border financing demand for industrial property acquisitions.
Japan
Long-term fixed-rate offerings sustain demand in Tokyo and Osaka's low-yield environment. The Financial Services Agency's disclosure mandates compress commission spreads while elevating advisory service requirements. Nagoya's industrial corridor maintains specialized broker networks for manufacturing facility financing.
China
Pearl River Delta manufacturing towns drive localized credit assessment network expansion. SAMR and NMPA frameworks impose escalating compliance costs on fintech-originated loan platforms. Shenzhen and Guangzhou's digital platform intermediaries face data governance tightening that raises operational barriers.
South Korea
Seoul Capital Area's mortgage refinancing cycles concentrate broker activity around rate-sensitive borrower segments. The Financial Services Commission maintains distinct capital adequacy requirements for non-bank intermediaries. Busan-Ulsan's manufacturing base generates commercial property financing demand through regional lender panels.
Asia-Pacific Mortgage/Loan Brokers Market Vendor Landscape
Concentration sits with parent-bank affiliated brokers leveraging balance sheet scale against nimble non-bank specialists deploying localized credit networks. Deposit-backed institutions sustain rate competitiveness in low-yield environments while independent operators compete through advisory depth and documentation expertise. Two strategic archetypes dominate: balance sheet-anchored intermediaries with captive funding advantages, and technology-enabled specialists with automated verification capabilities. Competitive moves center on open banking API integration and geographic expansion into underpenetrated tier-2 markets.
Among Japan-based financial institutions, Prestia SMBC Trust Bank, Tokyo Star Bank, and Shinsei Bank occupy positions within the balance sheet-anchored archetype, exemplifying parent-funded operational models. These entities represent the deposit bank tier where long-term fixed-rate product sustainability derives from captive funding structures rather than third-party panel negotiations.
| Leading Market Players |
|---|
| Prestia SMBC Trust Bank |
| CNFinance Holdings Limited |
| LIC Housing Finance Ltd |
| Tokyo Star Bank |
| Shinsei Bank |
| ICICI Home Finance Company Ltd |
| Askari Bank |
| PNB Housing Finance Ltd |
| China Huirong Financial Holdings Ltd |
| Others |
Supply Flow & Price Mechanics
APRA's responsible lending disclosure mandates gate both broker panel qualification and advisory fee differentiation simultaneously, compressing commission spreads for transaction-only intermediaries while elevating premium pricing for compliance-navigation services across Australia's suburban corridors.
Pricing Analysis
Configured-to-order pricing for bespoke advisory engagements commands spreads of three-to-five times standard transactional facilitation fees. The dominant pricing structure stratifies across premium advisory tiers, standard panel-access commissions, and economy digital-only facilitation. Price differentiation hinges on regulatory certification depth and geographic delivery cost to tier-2 Indian cities. Cost compression in the economy tier is intensifying because aggregator platforms consolidate origination intent before lender engagement. First-time buyers in Southeast Asia exhibit highest price sensitivity, while Australian investors seeking portfolio structuring tolerate premium fee loads.
Supply Chain Analysis
Data governance chokepoints in China's SAMR compliance layer underwrite operational cost escalation for fintech-originated loan platforms. Broker technology sourcing concentrates in Australia, India, and Singapore for core banking integration modules. Raw material dependencies include cloud compute infrastructure, satellite imagery datasets for automated valuation models, and consent-management API architectures. Single-source vulnerability sits with legacy core banking systems resisting API standardization. Distribution runs through hybrid models combining mobile-native platforms in Southeast Asia with relationship-managed channels in developed markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflection in mortgage intermediation demands ecosystem positioning around open banking interoperability, as India's Account Aggregator framework and Australia's Consumer Data Right reshape borrower data access rights.
For Market Incumbents: Compound advisory service depth through certification investment in RBI and APRA compliance specializations. Build backward integration into proprietary automated valuation model development to offset aggregator platform commission compression. Threat substitution from AI-native income verification specialists demands capability acquisition in document-intensive underwriting workflows.
For New Entrants and Emerging Players: Anchor in tier-2 Indian city whitespace where broker penetration lags metro saturation in Indore, Lucknow, and Coimbatore manufacturing corridors. Target commercial property segments requiring field-level credit assessment expertise that resists pure digital scaling. Go-to-market leverage rests on localized employment documentation networks penetrating informal worker segments.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across AI-enabled verification sub-segments as venture deployment automates document parsing workflows. Long-term viability centers on advisory relationship depth rather than lender panel breadth. Acquisition target archetype: technology-enabled specialists with Account Aggregator API integration and tier-2 city field networks. Signal to watch: open banking consent volumes as inflection indicator for subscription advisory model traction.
| Strategic Initiative | Industry Significance |
|---|---|
| Open Banking API Integration | RBI Account Aggregator and Australia's Consumer Data Right unlock real-time borrower verification, collapsing documentation timelines from weeks to hours. |
| Automated Valuation Model Deployment | Satellite-imagery AVMs adopted by Australian non-bank lenders compress valuation turnaround from five days to four hours for suburban refinances. |
| Tier-2 City Geographic Expansion | Broker deployment into Indore, Lucknow, and Coimbatore captures manufacturing corridor housing demand underserved by metro-centric networks. |
| Regulatory Certification Investment | APRA responsible lending and RBI housing finance specialization commands premium advisory fees as compliance complexity escalates. |
| AI-Based Income Verification Development | Automated document parsing slashes credit file preparation time, enabling broker throughput expansion per loan officer across Southeast Asian markets. |
Methodological Framework
A spread of perspectives from mortgage aggregator executives, regulatory compliance officers, fintech platform engineers, and tier-2 city broker network operators converged on the working assumptions. Primary interviews combined with secondary validation from RBI circulars, APRA prudential standards, and Financial Services Agency disclosure guidelines. Bottom-up origination volume estimates triangulated against top-down commission pool calculations across residential, commercial, and personal lending segments.
Segmentation dimensions modeled span service type, client sophistication tier, product offering structure, and technology deployment maturity across the projection horizon. CAGRs derived from trend extrapolation of first-time buyer channel migration and open banking adoption curves. Industry-specific forecast inputs include Account Aggregator consent volume trajectories and automated valuation model penetration rates in Australian refinancing cycles.
Material uncertainties — central bank policy swings, data governance tightening, and legacy system integration friction — sit outside the modeled envelope. Forecasts reflect assumptions around regulatory implementation timelines and technology adoption elasticity. Practitioners should keep alternative scenarios live as open banking interoperability standards and responsible lending obligation interpretations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
USA Home Loan Market
Loans and Leasing
Corporate Lending Market
Loans and Leasing
Mortgage Lending Market
Loans and Leasing
North America Syndicated Loans Market
Loans and Leasing
Asia-Pacific Syndicated Loans Market
Loans and Leasing
Japan Car Loan Market
Loans and Leasing
Japan Auto Loan Market
Loans and Leasing
Russia Student Loan Market
Loans and Leasing
Canada Mortgage/Loan Brokers Market
Loans and Leasing
North America Mortgage/Loan Brokers Market
Loans and Leasing
Digital Lending Software Market
Loans and Leasing
Brazil Auto Loan Market
Loans and Leasing
Global Automotive Financing Market
Loans and Leasing
Global Automotive Rental and Leasing Market
Loans and Leasing
Brazil Car Loan Market
Loans and Leasing
Latin America Motorcycle Loan Market