
 Mortgage Lending Market | 2026-2036
Mortgage Lending Market Size, Share, and Industry Trends Forecast 2026-2036
Mortgage Lending Market Analysis
Prime conforming loan standards are rotating toward tighter credit overlays as investors demand enhanced collateral quality. Rocket Mortgage leverages its proprietary digital platform to sustain rapid pre-approval velocity. United Wholesale Mortgage anchors broker-channel volume through aggressive correspondent pricing. Mr. Cooper Group dominates servicing rights accumulation, positioning its portfolio for rate-cycle volatility.
Mortgage lending encompasses the origination, underwriting, and securitization of debt instruments collateralized by real property, typically structured as fully amortizing term loans with loan-to-value ratios capped by regulator-mandated thresholds. The primary commercial purpose centers on enabling property acquisition while generating interest income and fee revenue across the lending value chain. Fixed-rate products occupy the largest share of origination volume as borrowers seek payment certainty amid rate uncertainty. FHA lending extends to credit-impaired segments where federal insurance offsets elevated default risk. First-time buyers represent the fastest-expanding borrower category as affordability programs and down-payment assistance broaden access.
The Consumer Financial Protection Bureau enforces qualified mortgage standards that constrain debt-to-income ratios and limit balloon-payment structures. The Federal Housing Finance Agency governs conforming loan limits and capital requirements for government-sponsored enterprises. Basel III frameworks impose risk-weighted capital reserves that directly shape lender portfolio composition and pricing decisions. Stakeholders must monitor how regulatory capital treatment of mortgage servicing rights influences holding strategies across rate environments.
Market Dynamics
Digital origination platforms are compressing loan cycle times from weeks to hours, forcing traditional lenders to restructure front-end operations around API-first architectures and automated underwriting engines.
Growth Catalysts
- Basel III risk-weighting frameworks:European and Asian regulators are recalibrating capital treatment for residential mortgages, nudging banks toward high-quality collateral pools and standardized securitization structures.
- First-time buyer programs:Down-payment assistance initiatives in the United States and targeted affordability schemes in Canada are expanding the addressable borrower base beyond prime credit tiers.
- Cloud-native core banking:Lenders migrating from legacy mainframes to containerized infrastructure are collapsing origination costs and enabling real-time decisioning at scale.
Market Restraints
- Interest rate volatility:Central bank policy uncertainty across the Federal Reserve, European Central Bank, and Bank of England is compressing net interest margins and hedging effectiveness.
- Collateral concentration risk:Urban residential markets in Sydney, London, and Vancouver exhibit synchronized price sensitivity to credit tightening, amplifying portfolio correlation.
- Qualified Mortgage constraints:The Consumer Financial Protection Bureau's debt-to-income caps and points-and-fees limits exclude non-traditional income profiles from conventional channel access.
Strategic Opportunities
- India's housing-for-all mandate:The Credit Linked Subsidy Scheme and priority-sector lending quotas are opening volume in tier-2 and tier-3 cities underserved by formal credit.
- Embedded finance distribution:Property technology platforms and real estate marketplaces in Germany and Australia are integrating point-of-sale mortgage origination into transaction workflows.
- Green mortgage incentives:The EU Energy Performance of Buildings Directive and national retrofit programs in France and the Netherlands are creating differentiated pricing for energy-efficient collateral.
Industry Challenges
- AI/ML model explainability:Fair lending audits and adverse action notice requirements demand interpretable underwriting algorithms, constraining black-box neural network deployment.
- Title and lien data fragmentation:County-level recording systems in the United States create manual reconciliation bottlenecks that automated valuation models cannot fully resolve.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mortgage Lending Market |
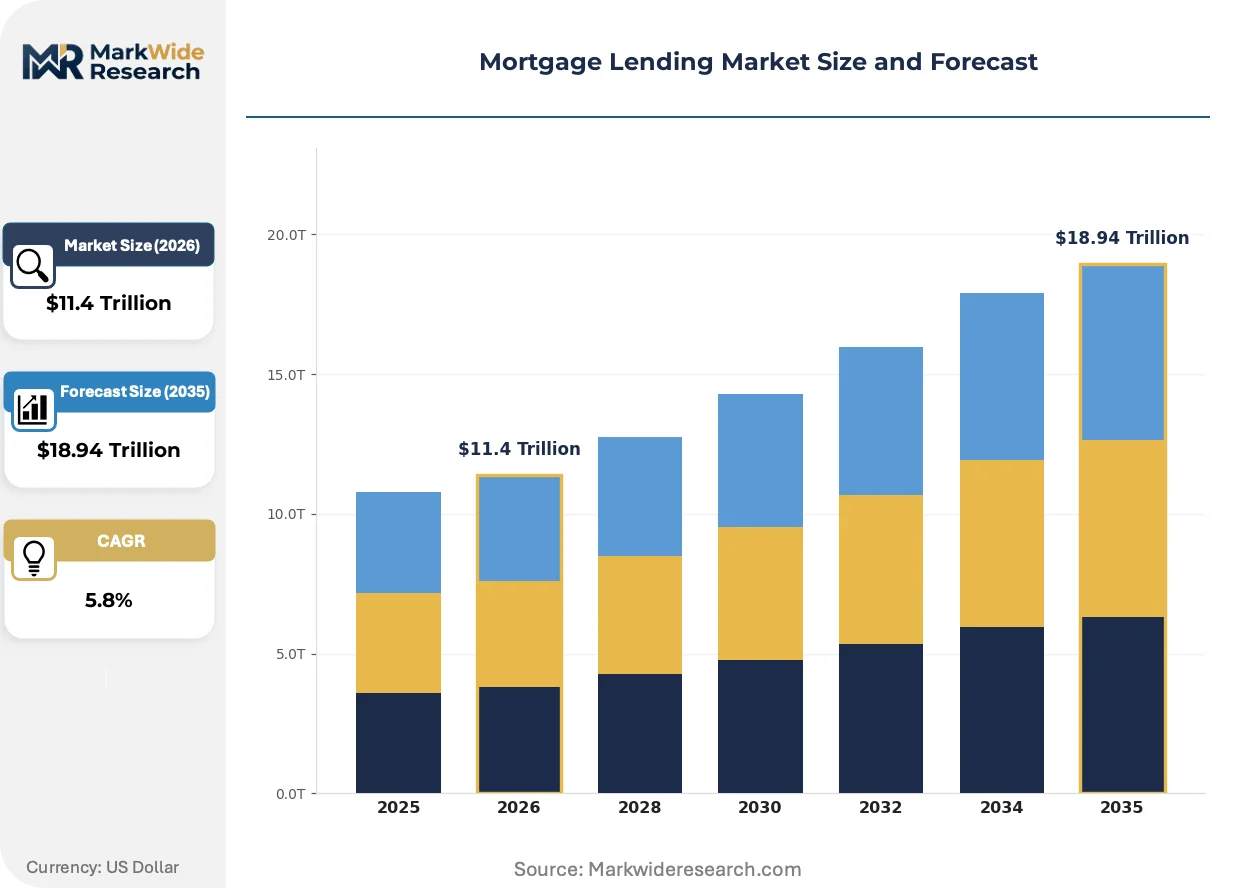
| Market Size in 2026 | $11.4 Trillion |
| Market Size in 2035 | $18.94 Trillion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Loan Type: Fixed-Rate, Adjustable-Rate, Interest-Only, FHA Borrower Type: First-Time Buyers, Investors, Refinancers, Low-Income Property Type: Single-Family Home, Multi-Family Home, Condominiums, Commercial Service Type: Origination, Servicing, Underwriting, Closing |
| Companies Covered | United Wholesale Mortgage, Rocket Mortgage, Mr. Cooper Group, Newrez, Pennymac, loanDepot, Fairway Independent Mortgage, DHI Mortgage, AmeriHome Mortgage, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mortgage Lending Market Emerging Trajectories
Automation is penetrating every stage of the mortgage value chain, from prospecting through servicing, while regulatory pressure on algorithmic fairness and climate risk disclosure is reshaping product design.
Machine learning-powered income verification is miniaturizing the documentation burden for self-employed borrowers. Fintech originators in the United Kingdom and Australia are deploying bank-statement parsing and alternative data scoring to compress verification from days to minutes. This capability is miniaturizing the competitive moat of traditional lenders who rely on manual review processes.
The EU Green Deal and national building performance standards are mandating energy efficiency disclosures at origination. Lenders in France, Germany, and the Netherlands must now capture Energy Performance Certificate ratings and stress-test collateral against stranding risk. Portfolio managers are responding by pricing green mortgages 10-25 basis points below conventional products.
Direct-to-consumer digital channels are displacing branch-dependent origination among younger borrower cohorts. Broker aggregators in Canada and Australia are consolidating market access through platform economics, while retail banks invest in self-service pre-approval tools. This shift is most pronounced in metropolitan markets where property search and financing decisions occur within compressed timelines.
Mortgage Lending Market Segmentation
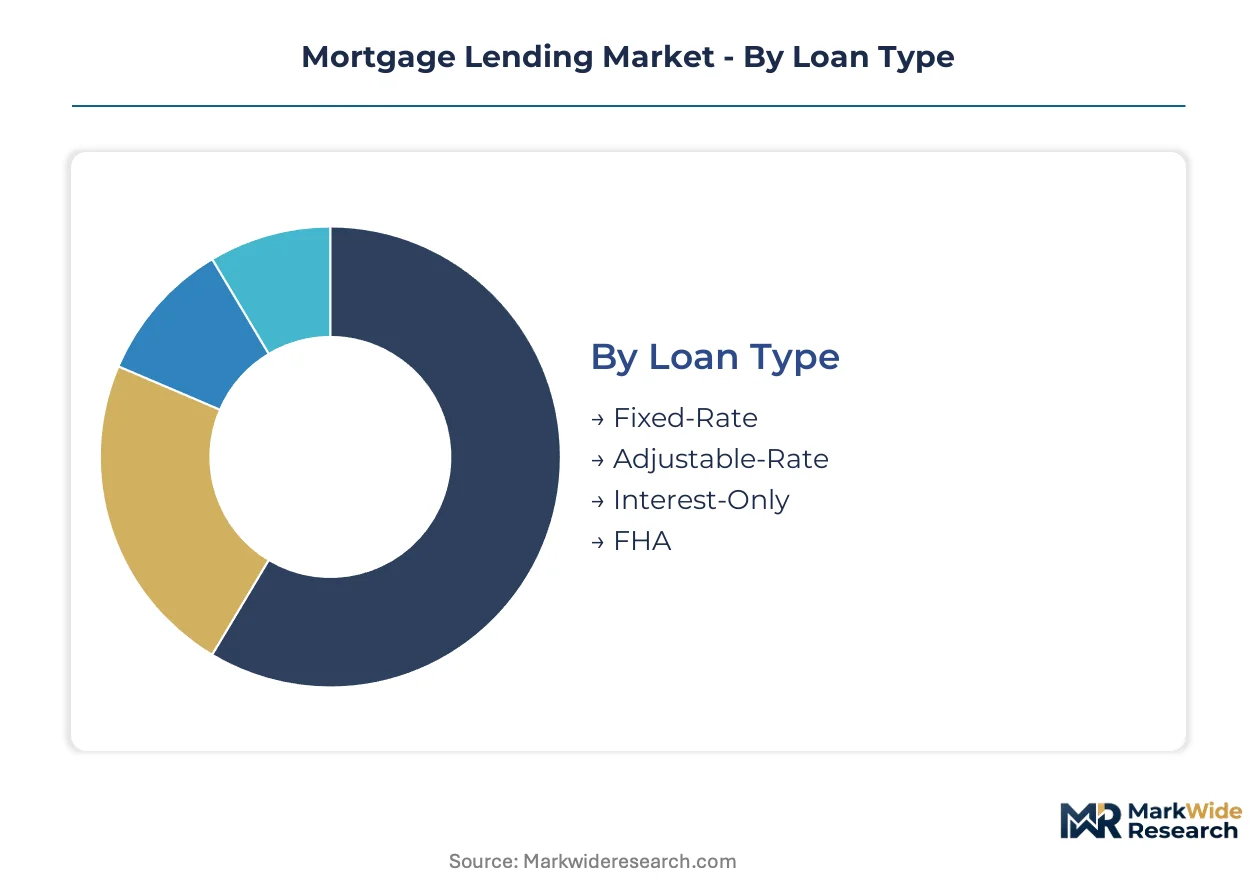
Mortgage market segmentation reveals how capital flows align with borrower risk profiles, collateral characteristics, and operational economics. Lenders calibrate product design, pricing, and distribution strategy around these dimensions to optimize portfolio yield and regulatory capital efficiency.
Loan Type:
Channel mix varies sharply by loan structure, with fixed-rate products dominating retail bank distribution and FHA loans concentrating through correspondent networks and broker channels.
- Fixed-Rate:Fully amortizing instruments with locked interest rates across 15- or 30-year terms. Borrowers in the United States and Canada favor these for payment certainty during central bank tightening cycles. Rate volatility has compressed refinancing activity but sustained purchase origination.
- Adjustable-Rate:Hybrids with initial fixed periods transitioning to floating indices. Demand concentrates among jumbo borrowers in high-cost metropolitan markets where initial rate discounts improve qualification ratios. The Consumer Financial Protection Bureau's qualified mortgage rules constrain teaser-rate structures.
- Interest-Only:Structures deferring principal amortization for initial periods. High-net-worth borrowers deploy these for cash-flow management on investment properties.
- FHA:Federal Insurance Administration-backed products for credit-impaired segments. Down-payment assistance programs in the United States route these through state housing finance agencies.
By volume, Fixed-Rate leads. By growth pace, FHA is climbing fastest as affordability constraints expand the addressable base.
Borrower Type:
Customer acquisition cost tiers separate these segments, with refinancers commanding the lowest per-unit marketing spend and first-time buyers requiring the highest educational investment.
- First-Time Buyers:Entry-level purchasers leveraging down-payment assistance and state bond programs. The Credit Linked Subsidy Scheme in India and similar initiatives in Canada are expanding formal credit access beyond traditional prime tiers.
- Investors:Non-owner-occupied purchasers seeking rental yield or capital appreciation. Portfolio lenders in Australia and the United Kingdom price these 25-75 basis points above owner-occupied products to reflect elevated default correlation.
- Refinancers:Existing borrowers repricing or extracting equity. Rate-sensitive cohorts who drive volume spikes when central banks cut policy rates.
- Low-Income:Borrowers qualifying through specialized programs with subsidized rates or reduced mortgage insurance. Community development financial institutions in the United States anchor this channel.
By origination count, First-Time Buyers dominate. By margin contribution, Investors generate the highest per-loan profitability.
Property Type:
Collateral risk profiles and valuation complexity determine which segments flow through automated underwriting versus manual review.
- Single-Family Home:Detached dwellings with standardized appraisal methodologies. Government-sponsored enterprise guidelines in the United States enable high straight-through processing rates.
- Multi-Family Home:Duplex through quadplex structures combining residential financing with rental income underwriting. Lenders in Germany and the Netherlands apply commercial debt-service-coverage tests.
- Condominiums:Unit-secured loans requiring project-level approval and concentration limits. Homeowners association financial health triggers manual review in most jurisdictions.
- Commercial:Income-producing properties evaluated on net operating income rather than borrower DTI. Basel III risk-weighting treats these as corporate exposures.
By dollar volume, Single-Family Home leads. By origination complexity, Commercial demands the most specialized underwriting infrastructure.
Service Type:
Margin structure and capital intensity diverge across the value chain, with origination capturing front-end fees and servicing generating long-duration interest income.
- Origination:Front-end acquisition encompassing application, processing, and funding. Digital platforms in the United Kingdom and Australia have collapsed cycle times from weeks to hours.
- Servicing:Ongoing administration of performing loans and workout of delinquencies. Basel III capital treatment of mortgage servicing rights influences holding strategies across rate environments.
- Underwriting:Risk assessment and credit decisioning. Machine learning deployment in the United States and Canada faces fair lending audit constraints.
- Closing:Final documentation, title clearance, and disbursement. County-level recording fragmentation in the United States creates persistent bottlenecks.
By revenue stability, Servicing leads. By technology disruption exposure, Origination is transforming most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cross-border capital flows from United States institutional investors into European covered bond markets are reshaping liquidity patterns across the Atlantic corridor. German Pfandbriefe and French obligations foncières now attract significant North American pension fund allocations seeking yield pickup over Treasuries.
United States
Government-sponsored enterprise guarantees sustain the deepest secondary mortgage market worldwide. The Federal Housing Finance Agency governs conforming loan limits and capital requirements for Fannie Mae and Freddie Mac. Rocket Mortgage anchors digital origination velocity from its Detroit headquarters, compressing pre-approval cycles to minutes.
Germany
Pfandbrief banks dominate long-term fixed-rate lending through covered bond funding cost advantages. BaFin enforces strict matching rules between mortgage assets and Pfandbrief liabilities. Frankfurt-based lenders concentrate green mortgage origination as the EU Energy Performance of Buildings Directive mandates efficiency disclosures.
United Kingdom
Building societies compete with retail banks through member-owned structures and regional branch networks. The Prudential Regulation Authority calibrates countercyclical capital buffers against housing market exuberance. London broker aggregators consolidate market access through platform economics, displacing traditional branch-dependent origination.
India
The Credit Linked Subsidy Scheme expands formal credit access in tier-2 and tier-3 cities previously underserved by banks. Reserve Bank of India priority-sector lending quotas compel commercial banks to allocate 18 percent of adjusted net bank credit to housing. Mumbai and Bengaluru housing finance companies deploy co-lending partnerships with regional rural banks to penetrate semi-urban markets.
Australia
Major banks face non-bank lender competition as broker channel share exceeds 60 percent of new originations. Australian Prudential Regulation Authority macroprudential policy caps investor loan growth and interest-only lending proportions. Sydney and Melbourne property markets exhibit synchronized price sensitivity to credit tightening, amplifying portfolio correlation risks.
Mortgage Lending Market Vendor Landscape
Listed leaders compete with private specialists across origination channel strategy and servicing scale. The market structure fragments across three tiers: national direct-to-consumer platforms, wholesale-focused correspondent aggregators, and regional broker-dependent originators. Dominant competitive moves include correspondent network expansion to capture broker channel volume and mortgage servicing rights accumulation to generate rate-cycle hedging income.
Within the wholesale-aggregator tier, United Wholesale Mortgage and Pennymac exemplify volume-driven correspondent pricing strategies that anchor broker channel market share. Rocket Mortgage occupies the direct-to-consumer digital platform position, representing technology-first origination velocity. Mr. Cooper Group sits within the servicing-specialist archetype, accumulating mortgage servicing rights portfolios that generate recurring fee income across interest rate environments.
| Leading Market Players |
|---|
| United Wholesale Mortgage |
| Rocket Mortgage |
| Mr. Cooper Group |
| Newrez |
| Pennymac |
| loanDepot |
| Fairway Independent Mortgage |
| DHI Mortgage |
| AmeriHome Mortgage |
| Others |
Supply Flow & Price Mechanics
Long-term rate-lock commitments dominate mortgage pricing architecture, binding borrowers to payment certainty while exposing lenders to hedging costs that fluctuate with central bank policy. This contract-structure pattern concentrates pricing power among institutions with balance-sheet depth to warehouse interest rate risk.
Pricing Analysis
Digital-platform pricing gaps separate incumbent lenders from fintech originators, with API-first architectures commanding 15-25 basis point cost advantages over branch-dependent competitors. Three-tier pricing structure across correspondent, broker, and direct-to-consumer channels reflects origination cost differentials rather than credit quality variation. Pricing pressure stems from compressed net interest margins as the Federal Reserve holds rates elevated, squeezing gain-on-sale economics. First-time buyers exhibit highest price sensitivity, while jumbo borrowers in coastal metropolitan markets show least elasticity to rate fluctuations.
Supply Chain Analysis
Just-in-time funding preferences dominate mortgage banking, with warehouse lenders extending overnight credit lines that collapse when secondary market liquidity evaporates. Origination capacity concentrates in the United States, United Kingdom, and Australia where deep investor bases absorb securitized product. The supply chain draws from credit bureau data providers, automated valuation model vendors, and title insurance underwriters as critical inputs. Single-source vulnerability sits with the government-sponsored enterprise duopoly controlling conforming loan standards. Distribution runs through correspondent aggregators, broker networks, and direct-to-consumer platforms in tiered access layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mortgage lending operates as a cyclical recovery play, with refinancing volume poised to resurge when central banks pivot toward rate cuts. Rate-cycle positioning determines relative performance across origination-dependent versus servicing-heavy business models.
For Market Incumbents: Fortify servicing rights portfolios to generate recurring fee income that hedges origination cyclicality. Accumulate mortgage servicing rights from distressed sellers to lock in duration-matched cash flows. Deepen correspondent network relationships to defend broker channel share against non-bank competitors. Prioritize API-first origination infrastructure investment to sustain cost competitiveness against digital-native entrants.
For New Entrants and Emerging Players: FHA certification fast-tracks offer the most penetrable entry vector, opening credit-impaired segments underserved by prime-focused incumbents. Target down-payment assistance program administration in state housing finance agencies as a white-space origination channel. Deploy embedded finance partnerships with property technology platforms to capture transaction-timed mortgage demand. Pursue correspondent lending relationships with regional banks seeking balance-sheet capacity relief.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among servicing specialists with rate-sensitive hedge positions and technology-enabled cost structures. Long-term viability favors platforms with scale economics in origination and duration-matched servicing portfolios. Acquisition target archetype: mid-tier originators with underoptimized servicing assets and digital transformation deficits. Watch mortgage servicing rights valuation multiples as the inflection signal for rate-cycle positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Correspondent Network Expansion | United Wholesale Mortgage's broker-channel pricing anchors volume capture against retail bank competition. |
| Servicing Rights Accumulation | Mr. Cooper Group's portfolio positioning generates fee income insulation across Federal Reserve policy cycles. |
| Digital Platform Migration | Rocket Mortgage's API-first architecture collapses pre-approval timelines from days to minutes. |
| Green Mortgage Product Launch | EU Energy Performance of Buildings Directive mandates efficiency-linked pricing differentiation in France and Netherlands. |
| Embedded Finance Integration | German property technology platforms integrate point-of-sale origination into real estate transaction workflows. |
Methodological Framework
Desk research of regulatory filings, securitization prospectuses, and central bank statistical releases preceded structured interviews with chief risk officers, correspondent lending heads, mortgage servicing portfolio managers, and digital transformation executives. Primary fieldwork captured origination cost structures, servicing platform economics, and technology investment priorities across tier-1 banks and non-bank lenders. Secondary validation drew from Federal Housing Finance Agency reports, Consumer Financial Protection Bureau enforcement actions, and Basel Committee regulatory guidance. Bottom-up loan-level data triangulated against top-down market flow estimates to anchor volume projections.
Variance-decomposition framing isolates rate-cycle sensitivity, origination channel mix shifts, and regulatory capital treatment changes as primary forecast drivers. Segmentation modeling spans loan type, borrower category, property collateral, and service function dimensions across the projection horizon. CAGRs derive from historical origination flow patterns, prepayment model outputs, and servicing portfolio runoff schedules. Interest rate path assumptions and housing price trajectory scenarios feed directly into volume and margin forecasts.
Underlying assumptions cover central bank policy continuity, government-sponsored enterprise guarantee permanence, and qualified mortgage rule stability, with deviation risk concentrated in macroprudential tightening and Basel III implementation delays. Forecasts reflect these conditions without contingency buffers for extreme rate volatility or housing market dislocation. Revision becomes warranted when Federal Reserve policy rate trajectories cross 100-basis-point threshold shifts from baseline assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Japan Auto Loan Market
Loans and Leasing
Brazil Home Equity Lending Market
Loans and Leasing
Machinery Rental and Leasing Market
Loans and Leasing
Europe Motorcycle Loan Market
Loans and Leasing
Asia-Pacific Auto Loan Market
Loans and Leasing
United Kingdom Auto Loan Market
Loans and Leasing
Russia Student Loan Market
Loans and Leasing
Truck Financial Leasing Market
Loans and Leasing
Construction Equipment Finance Market
Loans and Leasing
Brazil Home Loan Market
Loans and Leasing
France Mortgage/Loan Brokers Market
Loans and Leasing
Syndicated Loans Market
Loans and Leasing
US Home Equity Lending Market
Loans and Leasing
United States Car Loan Market
Loans and Leasing
US Mortgage/Loan Brokers Market
Loans and Leasing
UK Home Equity Lending Market