
 South Korea Car Loan Market | 2026-2036
South Korea Car Loan Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Car Loan Market Insights
API-based credit scoring is narrowing the gap between traditional bank branches and mobile-first originations. Hyundai Capital leverages its captive finance relationship with the country's largest automaker to sustain dominant origination volumes. KB Kookmin Bank anchors its position through extensive branch networks that handle complex corporate fleet financing. KakaoBank Corp. competes aggressively on user experience, using its super-app ecosystem to reduce customer acquisition costs for used vehicle loans.
A car loan constitutes a secured installment credit instrument collateralized by the vehicle title, typically structured with fixed or variable interest rates over 12-84 month terms and governed by the Installment Transactions Act. New vehicle loans command the largest share of outstanding balances, though used vehicle loans are expanding fastest as certified pre-owned programs improve residual value transparency. Among customer types, private individuals generate the highest transaction frequency, while corporate borrowers deliver superior per-account profitability through fleet-scale arrangements and cross-sell potential.
The Financial Services Commission and the Bank of Korea jointly shape market conditions through macroprudential debt controls and benchmark rate adjustments that directly affect variable loan pricing. Korea Consumer Agency disclosure requirements mandate standardized total cost presentations, compressing opacity-based margin strategies. Stakeholders must monitor how the central bank's digital currency pilots and open banking expansions alter deposit-funded lending economics relative to non-bank capital markets access.
Market Dynamics
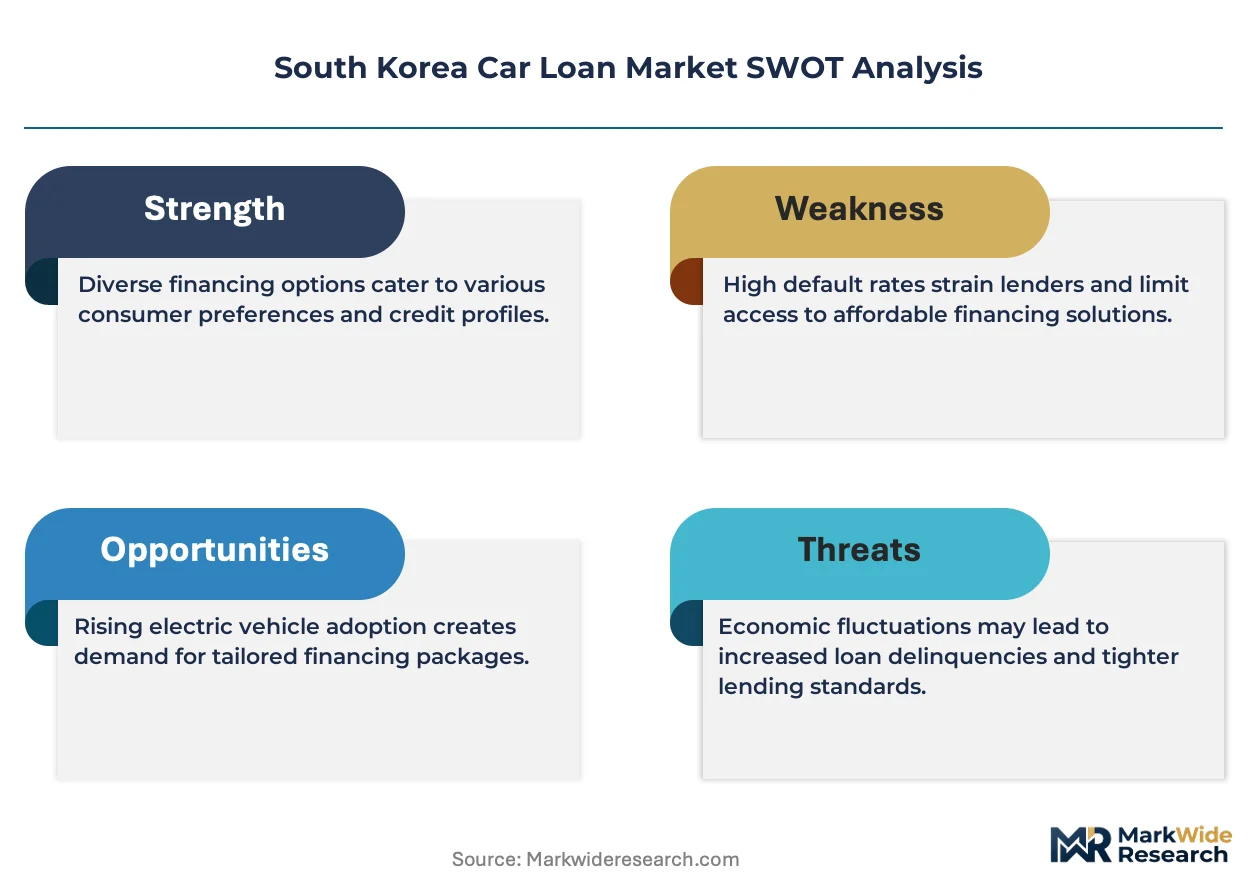
The Financial Services Commission's debt service ratio caps are compressing origination capacity across Seoul-based lenders, forcing a structural pivot toward alternative credit data and non-bank funding channels.
Growth Catalysts
- API-based credit scoring:Real-time bank account aggregation through open banking infrastructure is slashing approval times for private individual borrowers. The technology integrates employment verification and utility payment histories into underwriting models.
- Certified pre-owned programs:Hyundai and Kia's residual value guarantees for used vehicles are expanding addressable collateral pools. These programs reduce lender loss-given-default assumptions and expand loan-to-value ratios.
- Seoul metropolitan concentration:Household vehicle ownership rates in Gyeonggi-do and Seoul exceed national averages by substantial margins. Premium auto purchases in this corridor generate higher per-loan profitability and cross-sell attachment rates.
Market Restraints
- Bank of Korea benchmark volatility:Variable-rate loan repricing tied to central bank policy moves creates margin compression risk for deposit-funded lenders. Rate hedging costs erode net interest margins during tightening cycles.
- Debt service ratio enforcement:The Financial Services Commission's 40% cap on total debt repayment burdens disqualifies substantial borrower segments in high-leverage districts. Regional banks with concentrated exposure to over-leveraged households face origination constraints.
- Used vehicle valuation opacity:Non-certified pre-owned collateral lacks standardized residual forecasting, forcing conservative loan-to-value haircuts. This pricing uncertainty limits secondary market liquidity for used vehicle loan portfolios.
Strategic Opportunities
- Busan-Ulsan corridor underpenetration:Industrial fleet financing in Korea's southeastern manufacturing belt remains underserved by digital-first lenders. Corporate borrowers in this region seek multi-vehicle arrangements with integrated maintenance bundling.
- Green vehicle incentive stacking:Ministry of Environment subsidies for electric and hydrogen fuel cell vehicles create below-market effective borrowing costs. Lenders can structure promotional rate products capturing subsidy pass-through economics.
- Super-app distribution convergence:Messaging platform ecosystems with embedded payment rails are disintermediating traditional branch origination. Kakao and Naver ecosystems offer pre-approved loan offers at point of vehicle search.
Industry Challenges
- Legacy core system integration:Regional banks migrating to cloud-native loan origination platforms face data migration complexity with decades-old collateral registries. Parallel system operation during transition extends project timelines and strains IT resources.
- Alternative data compliance:Korea Consumer Agency disclosure requirements mandate transparent total cost presentation even for algorithmic pricing models. Lenders must reconcile granular risk-based pricing with standardized format obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Car Loan Market |
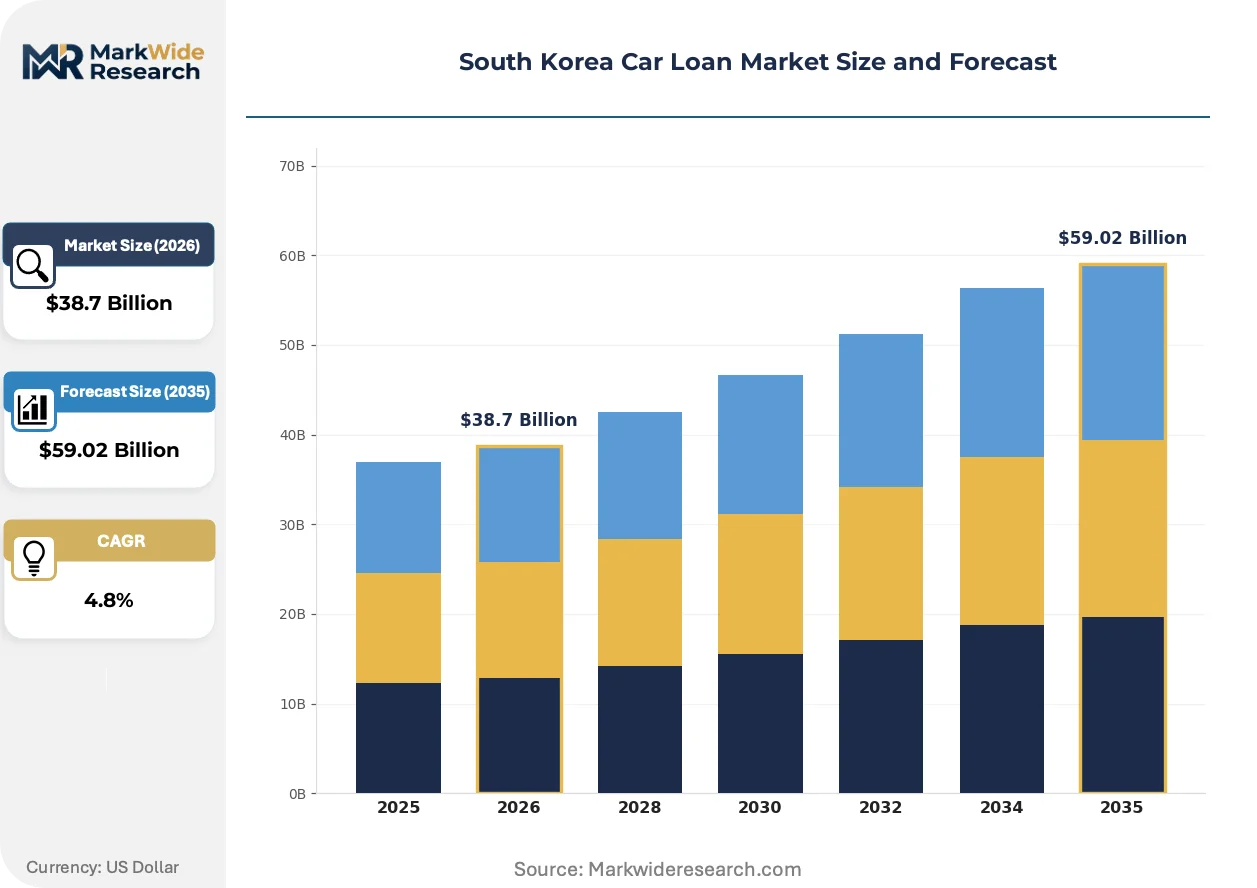
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: New Vehicle Loans, Used Vehicle Loans, Refinance Loans, Leasing Options Customer Type: Private Individuals, Businesses, Corporations, Government Agencies Loan Term: Short-Term Loans, Medium-Term Loans, Long-Term Loans, Balloon Payment Loans Interest Rate Type: Fixed Rate Loans, Variable Rate Loans, Introductory Rate Loans, Baloon Payment Loans |
| Companies Covered | Shinhan Bank, BMW Group Financial Services Korea, Hyundai Capital, IBK (Industrial Bank of Korea), Toyota Financial Services, Hana Capital, KB Kookmin Bank, KakaoBank Corp., Woori Bank, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Car Loan Market Trends and Innovations
Digital origination infrastructure is virtualizing traditional branch-based workflows, while regulatory disclosure mandates and shifting collateral preferences reshape product design across the lending value chain.
Embedded lending APIs are virtualizing the loan application process for automotive marketplaces and dealer management systems. Private individual borrowers now complete full credit decisions within dealership apps without redirecting to bank portals. This architecture compresses abandonment rates and captures intent at peak purchase consideration moments.
The Financial Services Commission's standardized total cost disclosure requirements are eliminating opacity-based pricing strategies across all regulated lenders. Installment Transactions Act amendments now mandate annual percentage rate presentation inclusive of all fees and insurance products. Smaller non-bank lenders with complex fee structures face the steepest compliance reconfiguration costs.
Subscription and mobility-as-a-service models are fragmenting traditional ownership-based loan demand among younger demographic cohorts. Fleet operators and ride-hailing platforms in Seoul and Gwangju are displacing individual purchase financing with corporate vehicle-as-a-service arrangements. Lenders must develop residual risk underwriting capabilities for off-lease vehicle remarketing to serve this pivot.
South Korea Car Loan Market Segmentation
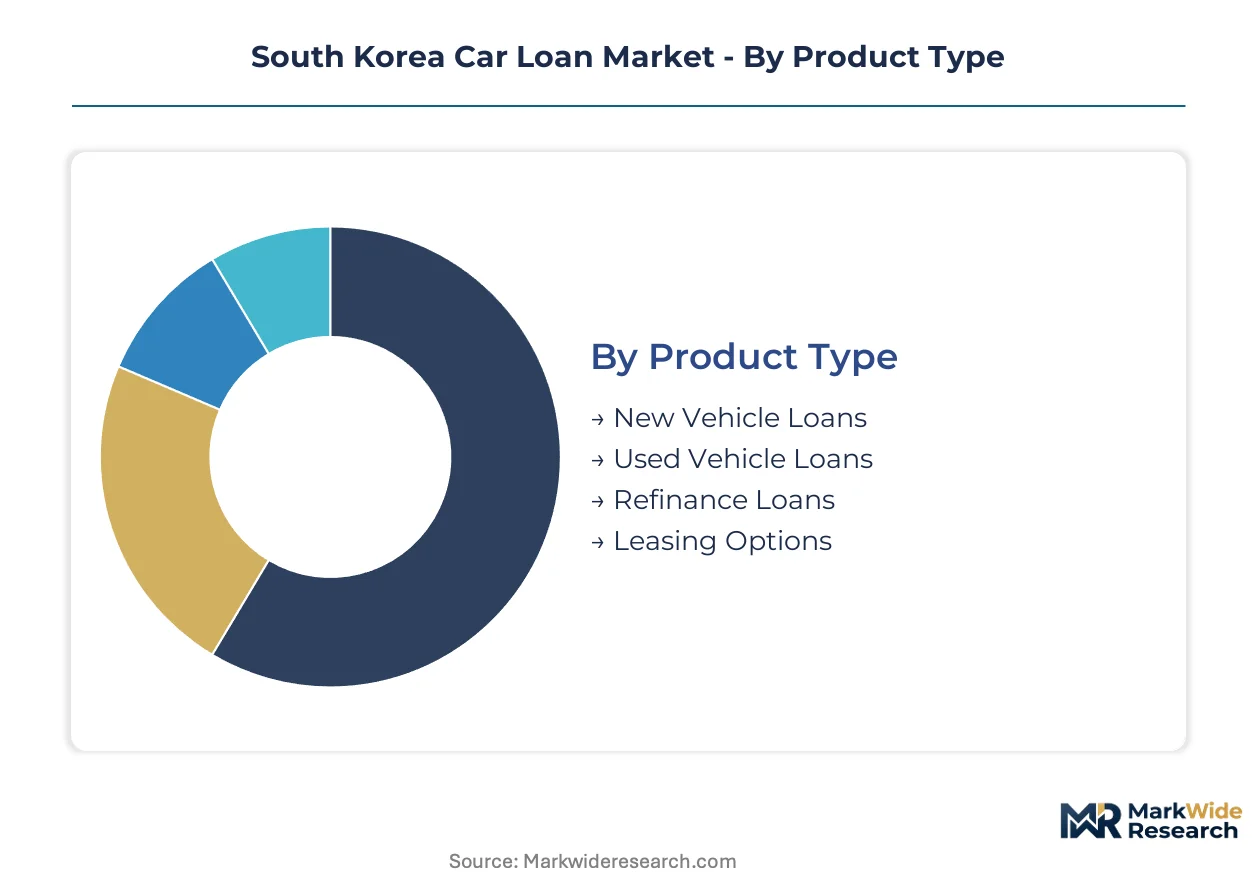
Segmentation reveals how collateral risk profiles and borrower repayment capacity vary across product structures in South Korea's secured auto lending market. Lenders price these differences through loan-to-value ratios and debt service ratio thresholds that align with the Financial Services Commission's macroprudential framework.
Product Type:
After-sales service intensity diverges sharply between new and used vehicle collateral, with manufacturer-certified programs commanding tighter residual value monitoring and warranty bundling.
- New Vehicle Loans:Collateralized by zero-mileage vehicles with manufacturer warranty coverage and predictable depreciation curves. Seoul metropolitan dealers concentrate origination volume through captive finance arrangements with Hyundai Capital and affiliated banking channels.
- Used Vehicle Loans:Financing for pre-owned vehicles spans certified programs with residual guarantees and uncertified collateral requiring conservative valuation haircuts. Certified pre-owned expansion through Hyundai and Kia networks is broadening addressable collateral pools in Gyeonggi-do.
- Refinance Loans:Restructuring of existing auto debt to capture rate arbitrage or extend maturities. Borrowers in high-leverage districts utilize these products to manage debt service ratio compliance.
- Leasing Options:Operating and finance lease structures transferring residual risk to lessors. Corporate fleet operators in Busan-Ulsan manufacturing corridors favor these arrangements for tax and balance sheet optimization.
By volume, New Vehicle Loans leads. By growth pace, Used Vehicle Loans is expanding most quickly.
Customer Type:
Cost tier stratification separates retail borrowers seeking standardized installment products from corporate clients demanding bundled fleet management and maintenance integration.
- Private Individuals:Household borrowers financing personal vehicle acquisition through salary-backed repayment streams. KakaoBank and digital-first lenders target this segment with super-app embedded origination reducing acquisition friction.
- Businesses:Small and medium enterprises acquiring commercial vehicles for operational use. Regional banks with branch presence in secondary cities dominate this borrower category through relationship-based underwriting.
- Corporations:Large enterprises structuring multi-vehicle fleet arrangements with integrated service contracts. These borrowers deliver superior per-account profitability through cross-sell attachment and scale economics.
- Government Agencies:Public sector procurement of official vehicles through mandated competitive bidding processes. KB Kookmin Bank and other major deposit institutions capture this flow via established public finance relationships.
Private Individuals generate the highest transaction frequency. Corporations command the steepest expansion trajectory in average deal size.
Loan Term:
Volume concentration in medium-term structures reflects the standard 60-month depreciation cycle aligning with Korean household income stability assumptions.
- Short-Term Loans:Maturities under 24 months for borrowers with liquidity preference or rapid equity buildup objectives. Premium vehicle purchasers in Seoul frequently select these structures to minimize interest burden.
- Medium-Term Loans:36-60 month tenors matching standard vehicle warranty periods and depreciation schedules. This structure dominates mass-market origination through Hyundai Capital and major bank channels.
- Long-Term Loans:Extended 72-84 month maturities reducing monthly debt service ratio burdens. The Financial Services Commission's 40% cap has accelerated demand for these structures among leveraged households.
- Balloon Payment Loans:Structures with substantial terminal payments enabling lower installments during the loan life. These products require residual value underwriting capabilities and appeal to borrowers with predictable liquidity events.
Medium-Term Loans holds the largest outstanding balance. Long-Term Loans is gaining share fastest as regulatory pressure on debt service ratios intensifies.
Interest Rate Type:
Margin sensitivity to Bank of Korea policy transmission varies across fixed and variable structures, with deposit-funded institutions facing repricing risk on floating-rate portfolios.
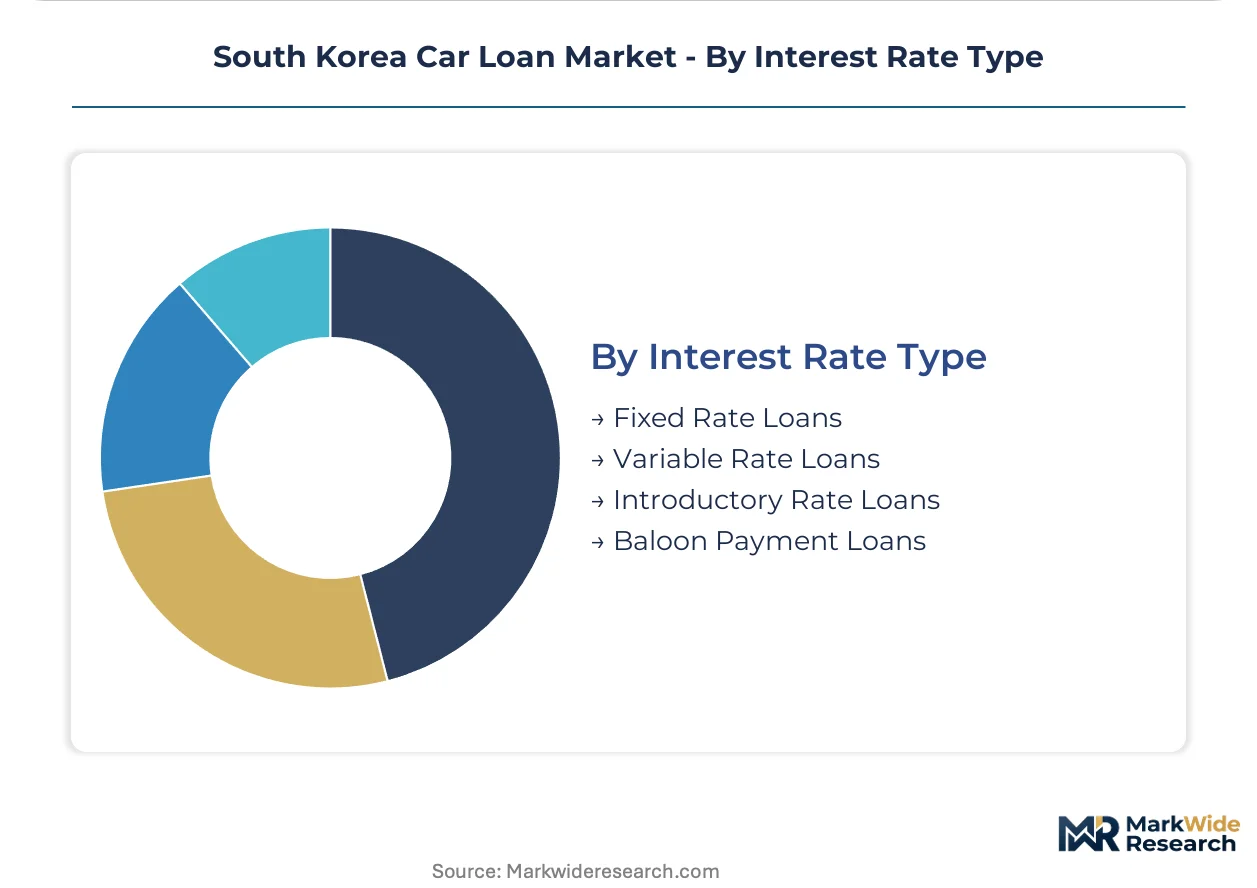
- Fixed Rate Loans:Rate locked at origination protecting borrowers from central bank tightening cycles. These products dominate where borrowers prioritize payment certainty over potential rate decline benefits.
- Variable Rate Loans:Pricing tied to benchmark rate indices with periodic repricing. Non-bank lenders with capital markets funding access favor these structures for asset-liability matching.
- Introductory Rate Loans:Promotional pricing periods transitioning to standard rates. Digital lenders deploy these products for customer acquisition within super-app ecosystems.
- Balloon Payment Loans:Rate structures paired with terminal payment obligations requiring integrated residual risk management. These hybrid products appear in captive finance programs with manufacturer remarketing support.
Variable Rate Loans leads by origination volume. Fixed Rate Loans is climbing the fastest as borrowers seek shelter from benchmark volatility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea's car loan market flows through distinct regional corridors, with Seoul Capital Area absorbing the dominant share of origination volume and secondary industrial belts emerging as fleet financing frontiers.
Seoul Capital Area
Household vehicle ownership rates in Gyeonggi-do and Seoul exceed national averages by substantial margins, driving premium auto purchases and higher per-loan profitability. The Financial Services Commission's debt service ratio caps hit hardest in this high-leverage district, compressing origination capacity for over-leveraged households. Gangnam and Seongnam clusters concentrate the highest density of captive finance arrangements through Hyundai Capital's dealer networks.
Busan-Ulsan Corridor
Industrial fleet financing in Korea's southeastern manufacturing belt remains underserved by digital-first lenders, creating white space for relationship-based underwriting. Corporate borrowers in this region seek multi-vehicle arrangements with integrated maintenance bundling for heavy commercial applications. Ulsan's automotive supplier ecosystem generates parallel demand for commercial vehicle financing tied to production logistics.
Daegu-Gyeongbuk
Regional banks with branch-heavy presence anchor small and medium enterprise vehicle acquisition in this historically manufacturing-oriented zone. The Bank of Korea's benchmark rate transmission affects variable-rate loan demand more acutely here due to thinner household liquidity buffers. Gumi's electronics industrial complex sustains steady commercial vehicle replacement cycles.
Daejeon-Sejong
Government agency vehicle procurement through mandated competitive bidding processes concentrates public sector financing flows in this administrative capital corridor. KB Kookmin Bank and major deposit institutions capture this flow via established public finance relationships. Sejong's planned city development continues generating construction fleet demand with specialized equipment financing requirements.
Gwangju-Honam
Mobility-as-a-service pilot programs in Gwangju are fragmenting traditional ownership-based loan demand among younger demographic cohorts. Fleet operators and ride-hailing platforms displace individual purchase financing with corporate vehicle-as-a-service arrangements. Regional lenders face pressure to develop residual risk underwriting capabilities for off-lease vehicle remarketing.
South Korea Car Loan Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where deposit-funded banks, captive auto finance arms, and digital-native platforms occupy distinct strategic positions. The market consolidates around three archetypes: branch-network incumbents with public sector relationships, manufacturer-captive lenders with residual value control, and super-app-embedded fintechs with user experience advantages. Competitive moves center on open banking API integration for real-time credit decisions and strategic partnerships embedding loan origination within automotive marketplaces.
Within the captive finance tier, Hyundai Capital anchors origination volume through its exclusive pipeline with the country's largest automaker. Among deposit-funded institutions, KB Kookmin Bank occupies a position serving complex corporate fleet arrangements and government procurement flows. On the digital-native vector, KakaoBank Corp. exemplifies super-app ecosystem leverage, reducing customer acquisition costs through embedded distribution within messaging and payment platforms.
| Leading Market Players |
|---|
| Shinhan Bank |
| BMW Group Financial Services Korea |
| Hyundai Capital |
| IBK (Industrial Bank of Korea) |
| Toyota Financial Services |
| Hana Capital |
| KB Kookmin Bank |
| KakaoBank Corp. |
| Woori Bank |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Seoul-based deposit-funded lending channels is compressing net interest margins and forcing lenders toward non-bank funding structures that reprice faster than traditional branch economics. This utilization imbalance feeds directly into pricing posture, with variable-rate products gaining volume share as capital markets access displaces deposit dependency.
Pricing Analysis
Cost-plus contracts indexed to the Bank of Korea base rate dominate variable-rate origination, with fixed-rate products commanding 15-30 basis point premiums for payment certainty. Pricing stratifies across premium captive finance, standard bank branch, and economy digital-native tiers based on after-sales bundling intensity and approval velocity. Cost compression in the standard tier is intensifying because KakaoBank and Naver-embedded lenders are waiving arrangement fees to capture super-app traffic. Corporate fleet borrowers show lowest price sensitivity due to tax optimization and cross-sell attachment, while leveraged private individuals in Gyeonggi-do districts face the highest sensitivity due to debt service ratio constraints.
Supply Chain Analysis
Upstream funding draws from three concentrated pools: household deposits channeled through KB Kookmin and Woori branch networks, institutional capital markets accessed by Hyundai Capital and Hana Capital, and fintech deposit aggregation via KakaoBank. The lending value chain rests on credit bureau data from NICE and KCB, collateral registries maintained by regional courts, and residual value forecasting from Hyundai and Kia certified programs. Single-source vulnerability sits with the Bank of Korea's benchmark rate transmission, which reprices the majority of outstanding variable-rate balances simultaneously. Distribution runs through captive dealer networks, independent used vehicle platforms, and super-app embedded marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Korea's car loan market is approaching a platform-economics inflection where open banking API interoperability and super-app ecosystem convergence will determine origination capture. The shift from branch-based relationship lending to embedded finance distribution rewards lenders who control customer intent at vehicle search moments.
For Market Incumbents: Build data-network moats by integrating alternative credit signals from utility payments and gig-economy income streams into proprietary scoring models. Regional banks must defend against super-app disintermediation by embedding pre-approved offers within automotive marketplace APIs before purchase consideration peaks. Priority lever: cloud-native core system migration to match digital-native approval velocity.
For New Entrants and Emerging Players: Mid-market commercial fleet financing in the Busan-Ulsan manufacturing corridor represents the most penetrable entry point, with relationship-based underwriting gaps left by Seoul-focused digital lenders. Green vehicle incentive stacking for hydrogen fuel cell and electric commercial vehicles offers subsidy-capture economics unavailable to incumbent deposit-funded structures. Go-to-market angle: integrated maintenance bundling with residual value guarantees.
For Investors and Strategic Acquirers: Capital is best deployed toward captive finance arms with manufacturer remarketing control and non-bank funding diversification. Long-term viability over a multi-year horizon hinges on residual risk underwriting capabilities for subscription and mobility-as-a-service transitions. Signal to watch: Hyundai and Kia certified pre-owned program expansion rates as collateral pool depth indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Open Banking API Integration | Real-time account aggregation slashes approval times for KakaoBank and Naver-embedded originations. |
| Certified Pre-Owned Program Expansion | Hyundai and Kia residual guarantees broaden addressable collateral pools in Gyeonggi-do districts. |
| Green Vehicle Incentive Stacking | Ministry of Environment subsidies create below-market effective borrowing costs for hydrogen fuel cell fleets. |
| Cloud-Native Core Migration | Regional banks modernize legacy systems to match digital-native velocity and reduce IT resource strain. |
| Super-App Embedded Distribution | Messaging platform ecosystems disintermediate branch origination with pre-approved point-of-search offers. |
Research Methodology
Operator-level perspectives from captive finance executives, digital lending platform engineers, regional bank branch managers, and corporate fleet procurement officers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against Financial Services Commission regulatory filings, Bank of Korea monetary policy transcripts, Korea Consumer Agency disclosure databases, and vehicle registration data from the Ministry of Land, Infrastructure and Transport. Bottom-up origination volume estimates by lender type and product structure were triangulated against top-down household debt aggregate flows.
Scenario-bracketing around Bank of Korea benchmark rate trajectories and debt service ratio enforcement intensity framed the analytical approach across the projection horizon. Segmentation dimensions modeled include collateral type, customer tier, loan maturity structure, and interest rate fixation period, alongside regional origination concentration by metropolitan statistical area. CAGRs were derived from fitted trend extrapolation adjusted for regulatory intervention probability, with electric vehicle subsidy phase-out schedules and open banking penetration curves as key forecast inputs.
Stress conditions across central bank tightening cycles, household leverage saturation in Seoul Capital Area districts, and used vehicle residual value volatility were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about ecosystem convergence timing and regulatory enforcement consistency. Cross-checking against Bank of Korea household credit aggregate releases and Financial Supervisory Service non-bank lending surveillance data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
United States Car Loan Market
Loans and Leasing
Europe Auto Loan Market
Loans and Leasing
Enterprise Asset Leasing Market
Loans and Leasing
North America Mortgage/Loan Brokers Market
Loans and Leasing
Online Payday Loans Market
Loans and Leasing
Global Automotive Fleet Leasing Market
Loans and Leasing
Europe Home Mortgage Finance Market
Loans and Leasing
Car Finance Market
Loans and Leasing
Vehicle Leasing Market
Loans and Leasing
India Used Car Financing Market
Loans and Leasing
Cash Advance Services Market
Loans and Leasing
Syndicated Loans Market
Loans and Leasing
Asia-Pacific Mortgage/Loan Brokers Market
Loans and Leasing
Qatar Mortgage/Loan Brokers Market
Loans and Leasing
Europe Automotive Finance Market
Loans and Leasing
North America Motorcycle Loan Market