
 Vehicle Leasing Market | 2026-2036
Vehicle Leasing Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Leasing Market Insights
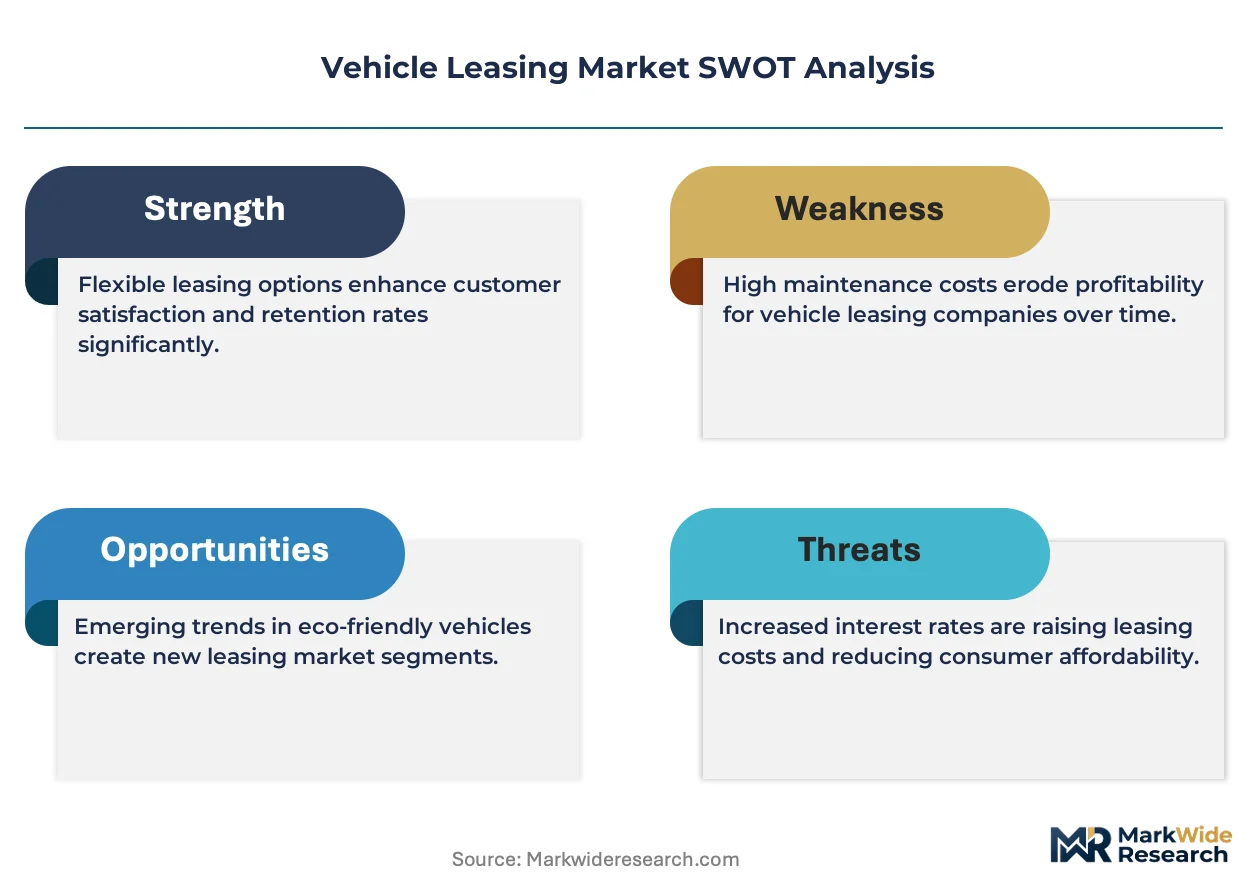
Fleet technician shortages across North America and Western Europe are redrawing how lessors structure maintenance bundles and remarketing timelines. Enterprise Holdings leverages its captive maintenance infrastructure to control lifecycle costs across diversified vehicle classes. ALD Automotive anchors its European position through multi-country fleet management platforms that standardize procurement for cross-border corporate clients. Sixt SE competes in the premium short-term segment where brand positioning and airport concession access create defensible yield premiums.
Vehicle leasing denotes a contractual arrangement where a lessor retains title while granting a lessee exclusive use rights for defined durations and mileage thresholds, with residual value risk allocation varying by lease structure. Closed-end leases transfer residual risk to the lessor and dominate consumer-facing channels, while open-end structures place valuation exposure on corporate fleet operators who cycle assets on customized schedules. Fleet leasing commands the largest revenue pool among lease types due to volume scale and bundled service attachments, yet personal leasing is expanding fastest as subscription-style mobility products blur traditional ownership boundaries. Corporate end users sustain the deepest contract durations and highest renewal rates, while government segments face compressed terms tied to budget cycles and procurement transparency mandates.
The US Environmental Protection Agency tailpipe standards and the EU F-Gas Regulation on mobile air conditioning refrigerants are reshaping lessor vehicle acquisition criteria and remarketing risk assessments. The Securities and Exchange Commission climate disclosure rules and the EU Corporate Sustainability Reporting Directive now require large fleet operators to report scope-three emissions, redirecting lease procurement toward electrified portfolios. Stakeholders must monitor how rapidly evolving battery residual value curves and charging infrastructure density gaps alter total-cost-of-ownership calculations against conventional internal combustion lease benchmarks.
Market Dynamics
The EU Green Deal's emissions benchmarks are compressing lease contract durations as lessors recalibrate residual value assumptions against accelerated electrification timelines. Fleet managers now face compressed decision windows between battery technology generations.
Growth Catalysts
- Corporate Scope-Three Reporting:The EU Corporate Sustainability Reporting Directive and SEC climate disclosure rules mandate emissions transparency from large fleet operators. Lease procurement is redirecting toward electrified portfolios to satisfy audit requirements.
- Asset-Light Logistics Expansion:E-commerce fulfillment networks and ride-hailing platforms are expanding leased vehicle rosters to preserve capital for technology investments. Fleet leasing volumes concentrate among last-mile delivery operators.
- Germany's Fleet Renewal Cycles:Dense dealership networks and standardized corporate procurement platforms sustain lease penetration rates substantially above European averages. Cross-border fleet management contracts anchor regional revenue pools.
Market Restraints
- Battery Residual Value Uncertainty:Rapid chemistry evolution and second-life market immaturity create valuation gaps that exceed conventional depreciation models. Lessors face compressed remarketing windows.
- Charging Infrastructure Density Gaps:Urban-rural disparities in high-speed charging availability limit fleet electrification feasibility outside metropolitan corridors. Range anxiety persists among multi-territory operators.
- F-Gas Regulation Compliance Costs:The EU F-Gas Regulation on mobile air conditioning refrigerants requires fleet-wide retrofits or accelerated vehicle turnover. Compliance expenditures erode margin structures on existing contracts.
Strategic Opportunities
- Subscription-Style Mobility Products:Personal leasing is expanding fastest as bundled insurance, maintenance, and vehicle-swapping privileges displace traditional ownership. Urban professionals represent the primary adoption cohort.
- Multi-Country Fleet Platforms:Cross-border corporate clients demand standardized procurement across Germany, France, and the Netherlands. Lessors with integrated European operations capture premium contract values.
- Captive Maintenance Infrastructure:Technician scarcity across North America and Western Europe rewards lessors with in-house service networks. Lifecycle cost control separates integrated operators from asset-only competitors.
Industry Challenges
- Fleet Technician Scarcity:Maintenance bundle profitability depends on skilled labor pools that are contracting across mature markets. Training pipelines lag electrification skill requirements.
- Legacy System Integration:Open-end lease structures for corporate fleet operators require customized asset cycling schedules that strain standardized IT platforms. Data fragmentation complicates predictive maintenance deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Leasing Market |
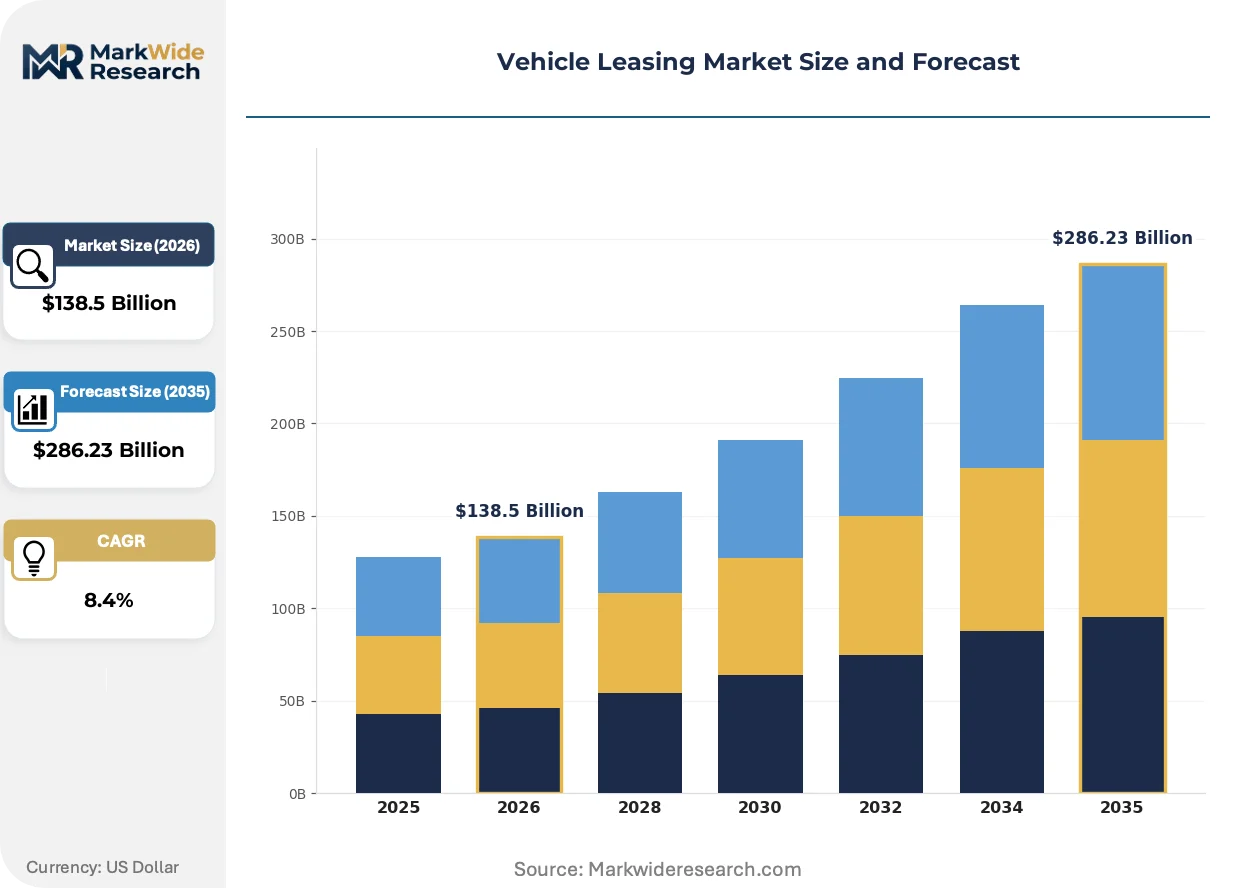
| Market Size in 2026 | $138.5 Billion |
| Market Size in 2035 | $286.23 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Lease Type: Closed-End, Open-End, Fleet Leasing, Personal Leasing End User: Corporate, Individual, Government, Non-Profit Contract Duration: Short-Term, Long-Term, Monthly, Annual Vehicle Type: SUV, Sedan, Truck, Luxury |
| Companies Covered | Enterprise Holdings, Hertz Global Holdings, AVIS Budget Group, ALD Automotive, LeasePlan Corporation, Sixt SE, Europcar Mobility Group, Arval Service Lease, Ayvens SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Leasing Market Trends and Innovations
Telematics-enabled usage-based pricing is restructuring how lessors underwrite mileage risk and how lessees optimize fleet utilization. Data granularity now determines competitive positioning.
Telematics integration is decomposing traditional fixed-mileage lease structures into dynamic pricing models that adjust to actual driving patterns. Logistics firms with dense route data are adopting these instruments fastest. The technology is compressing information asymmetry between lessor residual value models and lessee utilization profiles.
The EU F-Gas Regulation on mobile air conditioning refrigerants is mandating fleet-wide transitions to low-global-warming-potential alternatives. Vehicle acquisition criteria now prioritize compliant cooling systems to avoid mid-contract retrofit penalties. Corporate fleet segments in Germany and France are accelerating replacement cycles to maintain regulatory alignment.
Corporate procurement departments are consolidating vendor relationships around full-service fleet management platforms that bundle financing, maintenance, and remarketing. Traditional equipment finance providers without service capabilities are losing share to integrated operators. This concentration is most visible among German automotive sector suppliers with complex multi-country vehicle requirements.
Vehicle Leasing Market Segmentation
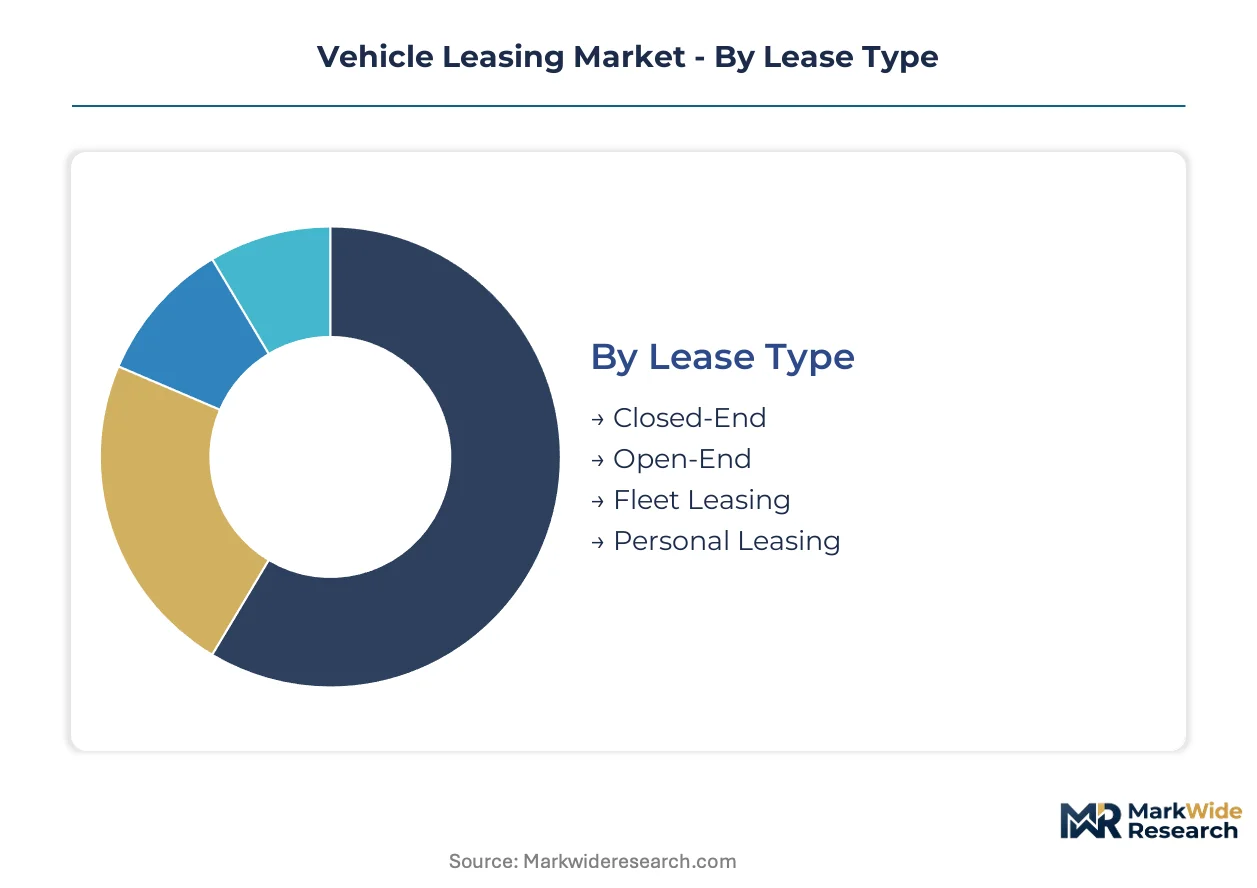
Segmentation in vehicle leasing determines how residual risk, contract flexibility, and service bundling align with lessee operational requirements. Channel economics vary sharply between fleet managers procuring through dedicated account teams and individual consumers accessing digital platforms.
Lease Type:
Fleet leasing and personal leasing flow through fundamentally different channel architectures, with the former relying on direct B2B sales teams and the latter on aggregator platforms and dealership networks.
- Closed-End:The lessor retains full residual value exposure, with fixed mileage thresholds and standardized wear-and-tear schedules. Consumer-facing channels dominate, particularly among individual lessees in Germany seeking predictable monthly obligations without remarketing responsibilities. The EU Green Deal's compressed electrification timelines are forcing recalibration of end-of-term valuations.
- Open-End:Corporate fleet operators assume residual risk through customized asset cycling schedules aligned with operational depreciation. Cross-border logistics firms in the Netherlands and Belgium leverage these structures to match vehicle lifecycles with contract logistics tenure. Flexibility commands premium pricing over closed-end alternatives.
- Fleet Leasing:Bundled maintenance, telematics, and remarketing services attached to volume contracts. Last-mile delivery operators represent the deepest demand concentration.
- Personal Leasing:Subscription-style products integrating insurance and vehicle-swapping privileges. Urban professionals in metropolitan France drive fastest adoption.
Fleet leasing dominates installed base. Personal leasing is where expansion concentrates.
End User:
Margin profiles diverge sharply across end-user categories, with corporate segments rewarding relationship depth and government segments demanding compliance transparency.
- Corporate:Multi-year contracts with integrated fleet management platforms and cross-border standardization requirements. German automotive sector suppliers anchor regional revenue pools through centralized procurement.
- Individual:Digital-first acquisition through comparison platforms with emphasis on monthly payment visibility and brand access. Subscription bundling is displacing traditional ownership in Paris and Munich.
- Government:Compressed terms tied to budget cycles and procurement transparency mandates. SEC climate disclosure rules and EU CSRD requirements redirect specifications toward electrified portfolios.
- Non-Profit:Cost-minimization focus with limited service attachment appetite. Educational and healthcare institutions in France represent primary demand pockets.
Corporate segments sustain the longest contract durations. Individual adoption is climbing the fastest.
Contract Duration:
Duration selection reflects trade-offs between capital commitment flexibility and per-month unit economics, with electrification uncertainty compressing decision windows.
- Short-Term:Premium positioning for project-based logistics and seasonal demand spikes. Airport concession operators in Germany leverage these structures for fleet elasticity.
- Long-Term:Standard corporate fleet procurement with embedded maintenance and predictable remarketing timelines. Battery residual value uncertainty is narrowing preferred commitment horizons.
- Monthly:Maximum flexibility for ride-hailing drivers and gig economy operators. Platform-integrated leasing in Paris reduces driver capital barriers.
- Annual:Balanced commitment for mid-size corporate fleets with stable route profiles. Belgian logistics firms favor this structure for regional distribution networks.
Long-term contracts anchor lessor revenue visibility. Monthly structures are gaining share fastest.
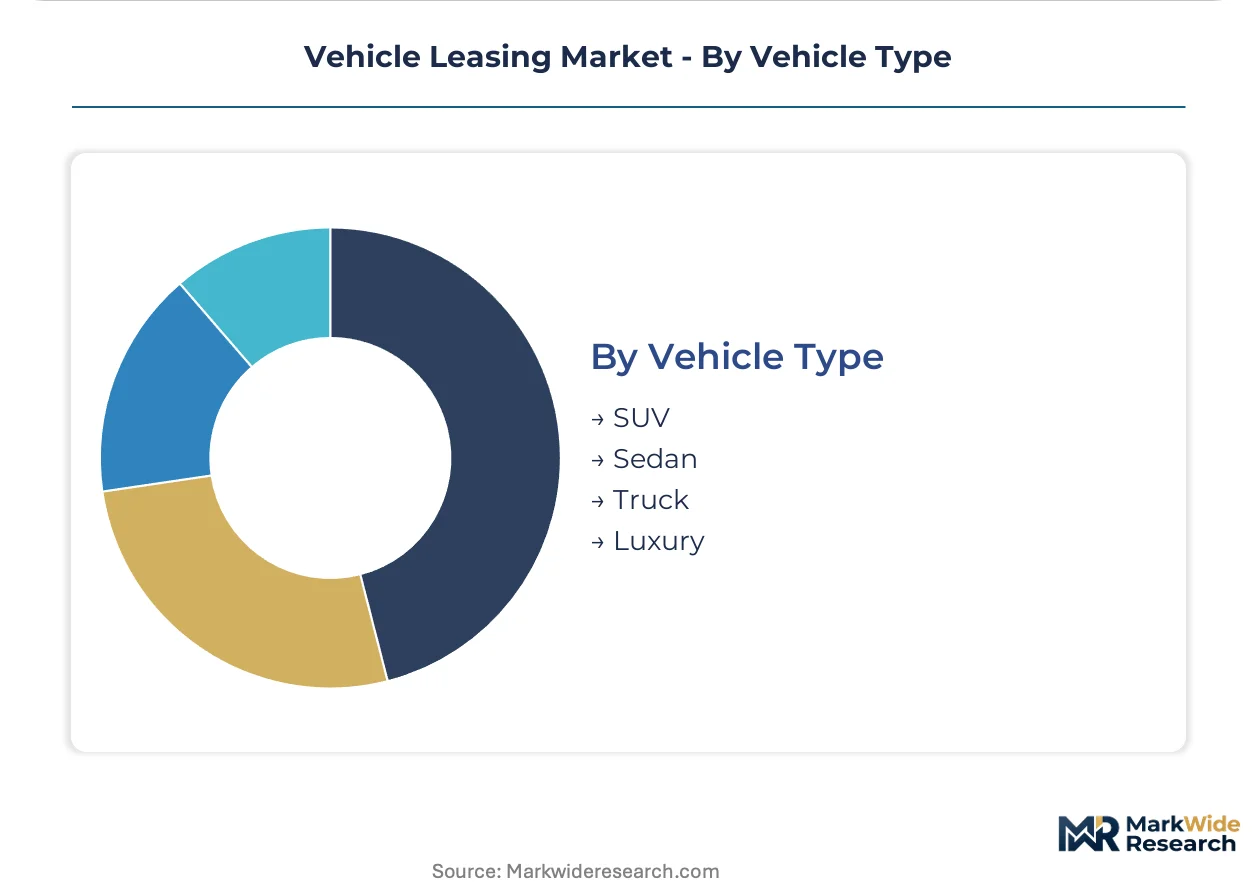
Vehicle Type:
Segment profitability tracks residual value stability, with electrification disrupting traditional depreciation curves across body styles.
- SUV:Corporate fleet preference for field service and executive transport roles. German lessors face compressed remarketing windows as EU emissions benchmarks tighten.
- Sedan:Standardized procurement for sales fleets and mid-management tiers. Range anxiety limits electrified sedan penetration outside urban charging corridors.
- Truck:Heavy-duty logistics applications with specialized maintenance requirements. Last-mile delivery electrification is reshaping light commercial specifications.
- Luxury:Premium short-term positioning through airport concessions and corporate hospitality. Sixt SE's brand positioning yields defensible yield premiums in this tier.
SUV and sedan categories dominate installed base. Luxury and truck electrification represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The KBA anchors European leasing governance through vehicle registration frameworks and emissions compliance protocols that cascade across member states. Fleet procurement patterns in Germany radiate outward through cross-border corporate networks. Lessors calibrate residual value models against national regulatory calendars.
Germany
Corporate fleet renewal cycles and dense dealership networks sustain lease penetration rates substantially above European averages. The EU Green Deal's emissions benchmarks compress contract durations as lessors recalibrate residual assumptions. The Stuttgart-Munich corridor concentrates automotive sector supplier fleets with complex multi-country vehicle requirements.
United States
Asset-light logistics expansion among e-commerce fulfillment networks drives leased vehicle roster growth. The SEC climate disclosure rules mandate scope-three emissions transparency from large fleet operators. Dallas-Fort Worth and Atlanta anchor last-mile delivery electrification programs with charging infrastructure density advantages.
France
Subscription-style mobility products displace traditional ownership among urban professionals in metropolitan Paris. The EU F-Gas Regulation mandates fleet-wide transitions to low-global-warming-potential mobile air conditioning refrigerants. The Lyon-Grenoble corridor hosts corporate procurement consolidation around full-service fleet management platforms.
United Kingdom
Telematics-enabled usage-based pricing adoption restructures mileage risk underwriting for logistics firms with dense route data. The EU Corporate Sustainability Reporting Directive redirects lease specifications toward electrified portfolios for audit compliance. The Midlands logistics triangle concentrates fleet management contract standardization for cross-border operators.
Netherlands
Cross-border logistics firms leverage open-end lease structures to match vehicle lifecycles with contract logistics tenure. The EU Green Deal's compressed electrification timelines narrow preferred commitment horizons for corporate procurement. The Rotterdam-Antwerp port corridor anchors multi-territory fleet operations with range anxiety mitigation through charging density.
Vehicle Leasing Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with market structure consolidating around full-service fleet management capabilities. Captive maintenance infrastructure and multi-country platform scale separate tier-one operators from asset-only competitors. Strategic archetypes include integrated fleet managers, premium short-term specialists, and captive finance arms. Competitive moves concentrate on geographic expansion through cross-border contract consolidation and technology licensing for telematics-enabled pricing models.
Within the integrated fleet management tier, Enterprise Holdings and ALD Automotive exemplify archetypes built on captive service networks and multi-country procurement standardization. Sixt SE occupies a position in the premium short-term segment where brand positioning and airport concession access create defensible yield structures. These three anchors represent divergent strategic vectors: lifecycle cost control through vertical infrastructure, cross-border operational scale, and yield premium capture through experiential positioning.
| Leading Market Players |
|---|
| Enterprise Holdings |
| Hertz Global Holdings |
| AVIS Budget Group |
| ALD Automotive |
| LeasePlan Corporation |
| Sixt SE |
| Europcar Mobility Group |
| Arval Service Lease |
| Ayvens SA |
| Others |
Pricing and Supply Chain Analysis
Three-to-six-month lead times for electric vehicle procurement now concentrate pricing power among lessors with captive OEM relationships, while spot-market fleet operators absorb residual value volatility through compressed contract durations. Days-of-inventory compression across German dealership networks feeds directly into monthly lease rate competitiveness for corporate procurement platforms.
Pricing Analysis
German lease rates for corporate SUVs run fifteen to twenty percent above comparable French contracts due to denser service bundling and faster electrification turnover mandates. Three-tier pricing structure across premium fleet management, standard closed-end leases, and economy monthly rentals dominates channel segmentation. Pricing pressure stems from battery residual value uncertainty forcing accelerated depreciation schedules. Individual subscribers in Paris and Munich exhibit highest price sensitivity, while cross-border logistics firms prioritize lifecycle cost predictability over rate minimization.
Supply Chain Analysis
Just-in-time vehicle allocation from German and Dutch assembly plants dominates fleet procurement, though strategic stockpiling of pre-registered EVs is emerging among lessors anticipating EU Green Deal compliance deadlines. Manufacturing concentration in Germany, the Netherlands, and Belgium anchors supply availability for European corporate clients. Lithium-ion battery cells, semiconductor modules, and climate-control refrigerants constitute critical input dependencies. Single-source vulnerability for battery chemistry from South Korean and Chinese suppliers threatens fleet electrification timelines. Distribution runs through captive dealership networks for closed-end consumer leases and direct fleet management platforms for corporate open-end structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vehicle leasing market is recovering from cyclical compression in residual value confidence, with fleet renewal cycles accelerating as EU emissions benchmarks harden procurement specifications.
For Market Incumbents: Fortify captive maintenance infrastructure against technician scarcity eroding service bundle margins. Enterprise Holdings and ALD Automotive anchor competitive position through in-house service networks that asset-only competitors cannot replicate. Expand backward integration into telematics platforms to capture usage-based pricing data before logistics firms internalize route analytics.
For New Entrants and Emerging Players: Lead with subscription-style mobility products targeting urban professionals in metropolitan France where traditional ownership displacement is most advanced. Personal leasing white space concentrates among gig economy operators seeking monthly flexibility without capital commitment. Deploy platform-integrated leasing through ride-hailing aggregators to reduce customer acquisition costs.
For Investors and Strategic Acquirers: Carve-out targets emerge from automotive OEM captive finance arms seeking to monetize non-core fleet management operations. Long-term viability hinges on electrification portfolio share and charging infrastructure partnerships rather than scale alone. Monitor battery second-life market maturation as the inflection signal for residual value model stability.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Maintenance Infrastructure Expansion | Technician scarcity across Germany and France rewards vertical service control with margin protection. |
| Telematics-Enabled Usage-Based Pricing | Data granularity from logistics route patterns compresses information asymmetry in residual value underwriting. |
| Cross-Border Fleet Platform Integration | Standardized procurement across Germany, Netherlands, and Belgium captures premium contract values. |
| Battery Supply Agreement Structuring | Long-term cell commitments from South Korean suppliers de-risk electrification portfolio expansion. |
| Charging Infrastructure Partnership | High-speed charging density in the Rotterdam-Antwerp corridor mitigates range anxiety for multi-territory operators. |
Research Methodology
Initial hypotheses were tested against primary input from fleet procurement directors, captive finance executives, dealership operations managers, and logistics fleet planners and refined through secondary validation against vehicle registration databases, EU regulatory filings, OEM production disclosures, and fleet management platform metrics. Bottom-up lease volume estimates triangulated against top-down market sizing from automotive sector reports.
Variance decomposition across lease type, end-user category, contract duration, and vehicle propulsion architecture shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate reconciliation against macroeconomic fleet investment indicators. Battery residual value curves and charging infrastructure deployment timelines constituted industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or accelerated battery chemistry evolution would require recalibration. Forecasts reflect documented assumptions regarding electrification penetration and corporate scope-three reporting compliance. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
US Home Equity Lending Market
Loans and Leasing
Commercial Vehicle Rental and Leasing Market
Loans and Leasing
E-Scooter Financing Market
Loans and Leasing
Digital Lending Software Market
Loans and Leasing
Loan Management Software Market
Loans and Leasing
India Home Loan Market
Loans and Leasing
Europe Mortgage Lending Market
Loans and Leasing
Europe Mortgage / Loan Broker Market
Loans and Leasing
Payday Loans Market
Loans and Leasing
Loan Brokers Market
Loans and Leasing
Loan Origination Software Market
Loans and Leasing
Embedded Lending Market
Loans and Leasing
Japan Auto Loan Market
Loans and Leasing
Brazil Auto Loan Market
Loans and Leasing
Global Automotive Financing Market
Loans and Leasing
Microfinance Market