
 Global Dry Construction Market | 2026-2036
Global Dry Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dry Construction Market Analysis
Skilled drywall installer shortages across North America and Western Europe is reorganizing project timelines and pushing general contractors toward prefabricated panel systems. Saint-Gobain leverages its integrated gypsum-to-distribution network to secure material continuity for large-scale commercial developments. Knauf Gips KG anchors Central European supply through captive plasterboard production and specialized metal framing fabrication. Armstrong World Industries, Inc. competes on acoustic ceiling system integration that reduces on-site labor hours.
Dry construction encompasses building methods that assemble prefabricated components without wet trades such as mortar curing or concrete pouring, typically employing gypsum board panels with steel or aluminum framing members in thicknesses ranging from 9.5 mm to 15.9 mm for interior partitions and ceilings. Its primary commercial purpose lies in compressing construction schedules while enabling future reconfiguration of interior layouts. Gypsum board dominates product type value flows due to established manufacturing scale and fire-resistance ratings, while insulation panels capture expanding margin pools as thermal bridging regulations tighten across multiple jurisdictions. Metal studs sustain faster installation growth in high-rise buildings where weight reduction matters, and prefabricated systems within installation methods are displacing conventional on-site drywall labor in markets with constrained craft availability.
F-Gas Regulation in Europe and EPA energy performance standards in the United States are elevating demand for low-embodied-carbon wall assemblies and vapor-control-layer integration in dry construction specifications. REACH compliance and CE marking requirements govern adhesive and sealant chemistries used in modular panel bonding, filtering non-compliant suppliers from project bidding pools. India's BIS certification for gypsum-based building materials and China's GB standards for interior partition fire ratings add further compliance layers for multinational material suppliers. Stakeholders must track evolving national building codes that mandate embodied carbon disclosure, as these will determine which panel compositions and framing systems qualify for public infrastructure and commercial tenders without explicit prohibition of specific technologies.
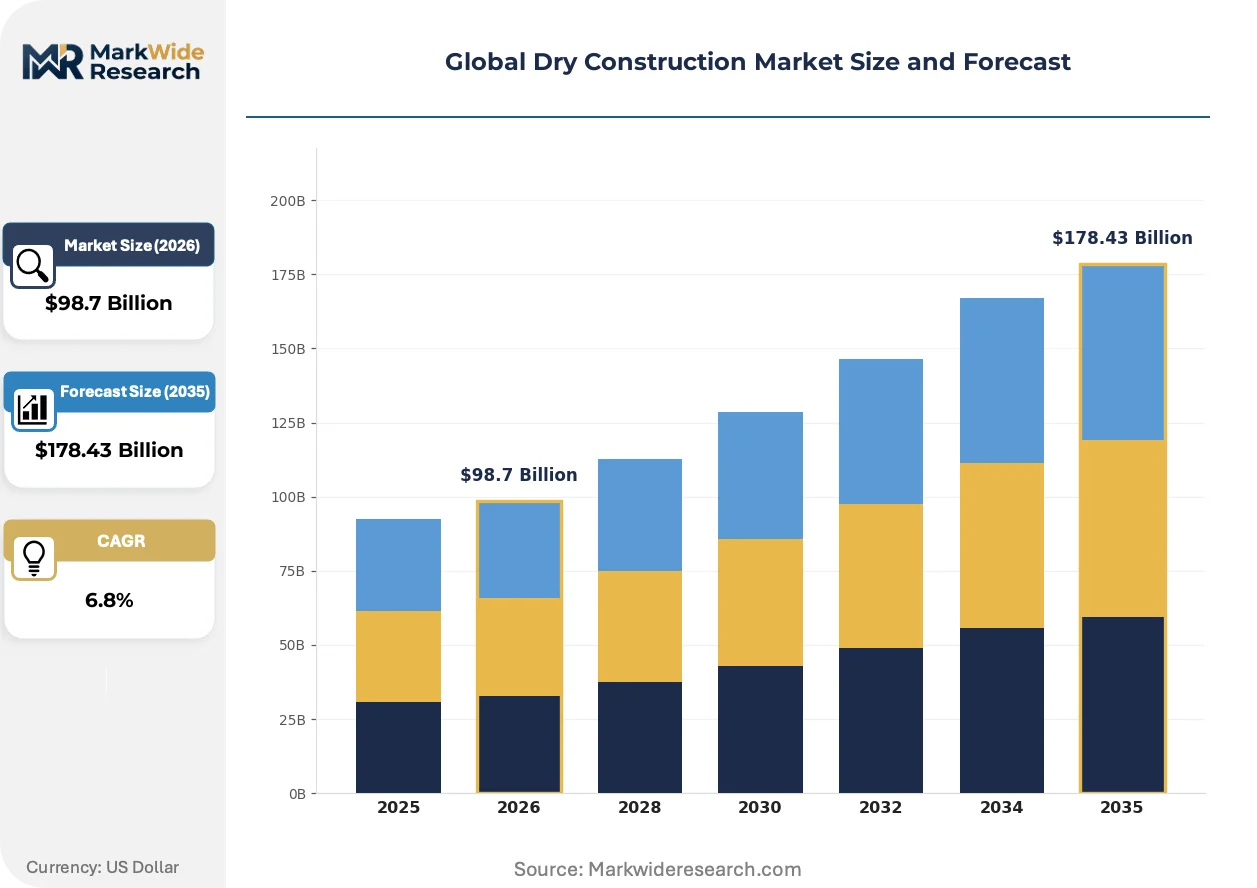
Market Dynamics
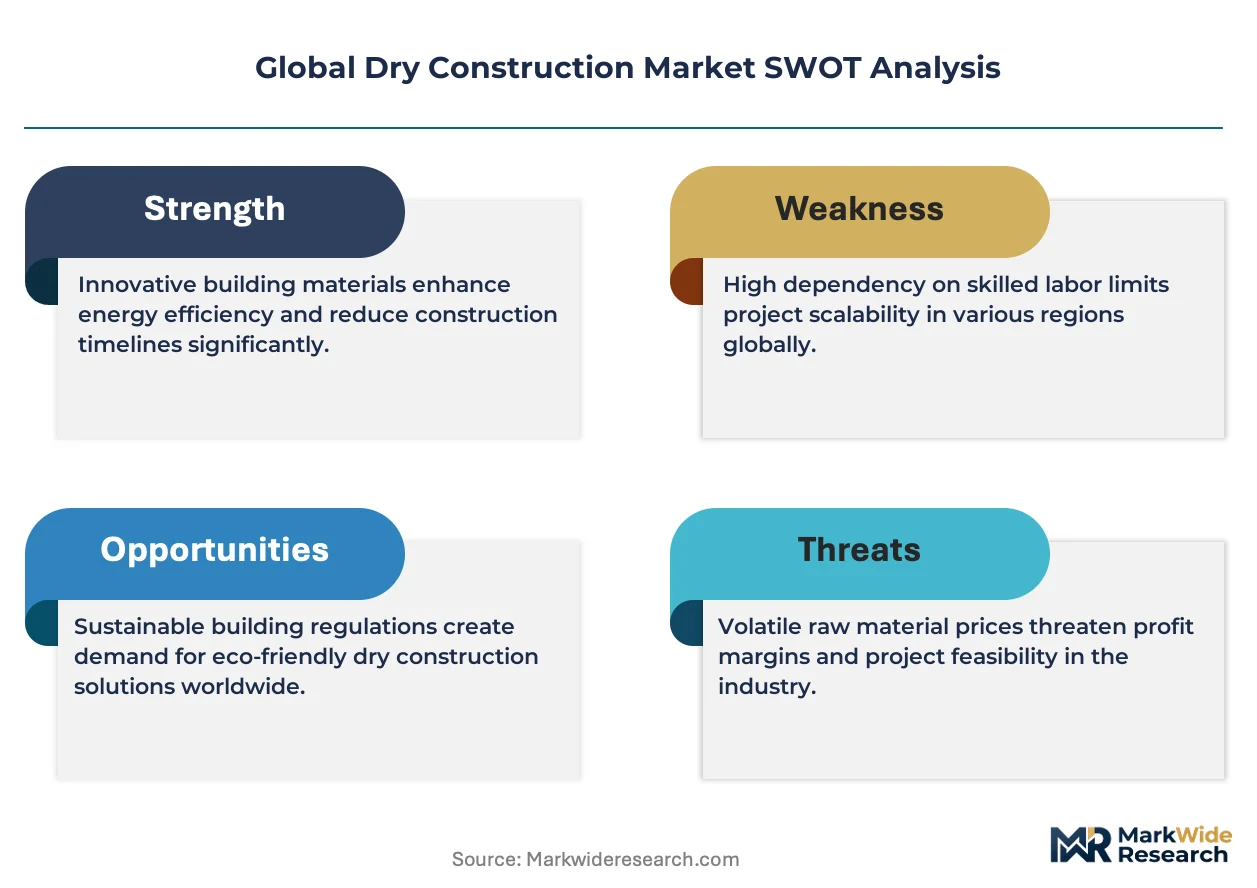
Prefabricated panel systems are compressing construction schedules across commercial and residential verticals as skilled installer shortages force general contractors toward factory-assembled wall and ceiling assemblies that minimize on-site wet trades.
Growth Catalysts
- EU Green Deal energy-efficiency mandates:Tightening building envelope standards in Germany and France are accelerating specification of high-performance drywall systems with integrated thermal breaks.
- Metal stud framing:Urban residential tower construction in China and India is concentrating demand for lightweight steel framing members that reduce structural load and enable faster vertical build rates.
- F-Gas Regulation vapor-control requirements:European commercial developers are retrofitting existing envelopes with low-embodied-carbon wall assemblies to meet tightening thermal bridging standards.
Market Restraints
- Gypsum supply concentration:Captive quarry access in select geographies limits second-tier board producers from securing consistent raw material flows at scale.
- REACH adhesive compliance costs:Modular panel bonding chemistries face escalating certification burdens that filter smaller sealant suppliers from project bidding pools.
- Structural substitution by mass timber:Cross-laminated timber wall systems are capturing mid-rise commercial segments where fire ratings and acoustic performance specifications overlap.
Strategic Opportunities
- India's BIS certification gap:Domestic gypsum-based building material standards are tightening, creating first-mover advantage for compliant multinational suppliers in Tier-2 city residential towers.
- Acoustic ceiling integration:Healthcare and education end-uses in France are specifying factory-integrated ceiling systems that compress MEP coordination timelines.
- China's dual carbon goals:GB standards for interior partition fire ratings are elevating demand for low-carbon panel compositions in government-funded infrastructure tenders.
Industry Challenges
- Drywall installer craft scarcity:North American and Western European labor pools lack sufficient trained technicians to execute conventional on-site board hanging at projected build rates.
- Embodied carbon disclosure timelines:Evolving national building codes mandating lifecycle carbon reporting are compressing product qualification windows for panel manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dry Construction Market |
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $178.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gypsum Board, Cement Board, Metal Studs, Insulation Panels End User: Residential Buildings, Commercial Spaces, Industrial Structures, Infrastructure Projects Installation Method: Prefabricated Systems, Modular Construction, On-Site Assembly, Drywall Installation Building Type: High-Rise Buildings, Single-Family Homes, Office Buildings, Retail Outlets |
| Companies Covered | Saint-Gobain, Etex Group, Armstrong World Industries, Inc., Knauf Gips KG, Xella Group, CSR Limited, Fletcher Building Limited, USG Boral Limited, Pabco Gypsum, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dry Construction Market Emerging Trajectories
Digital fabrication and regulatory carbon accounting are converging to reshape how wall and ceiling assemblies are specified, manufactured, and installed across commercial construction workflows.
Robotic panel cutting and CNC routing of gypsum board is supplanting manual field cutting in large-scale commercial developments. Hospital and airport contractors in Germany are adopting these systems to achieve millimeter tolerances for MEP integration. Factory precision is compressing rework cycles and enabling just-in-time delivery models that reduce site inventory requirements.
REACH compliance protocols are forcing reformulation of adhesive and sealant chemistries used in modular bonding applications. European manufacturers are shifting toward bio-based binding agents to maintain CE marking eligibility. Panel fabricators serving French and German commercial markets are absorbing elevated R&D costs to retain project access.
General contractors are bundling acoustic ceiling and drywall scope into single-source procurement packages to reduce subcontractor coordination overhead. Healthcare developers in the United States are consolidating vendor relationships to compress warranty administration and streamline commissioning. This consolidation favors integrated material suppliers with captive distribution networks over specialized trade contractors.
Global Dry Construction Market Segmentation
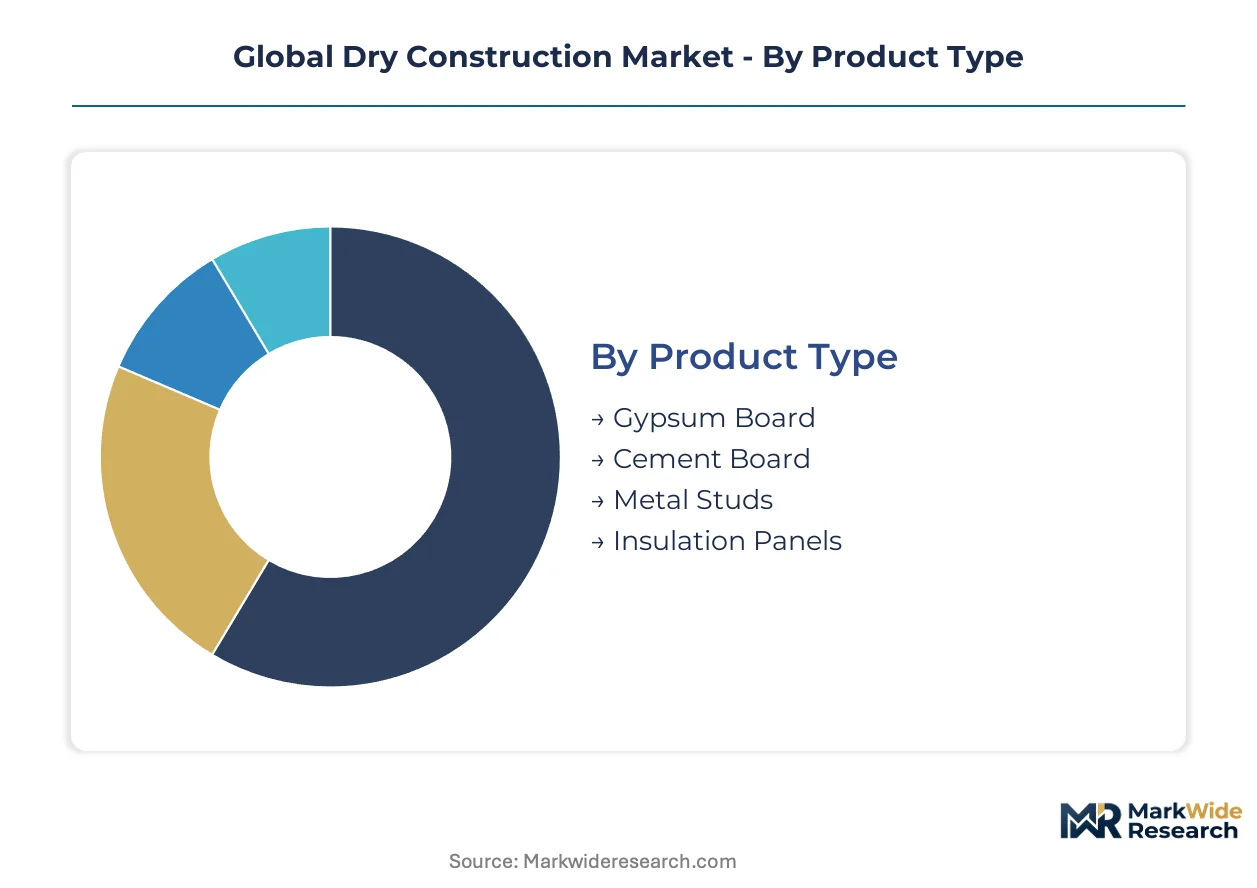
Dry construction markets fragment across material composition, end-use application, and assembly methodology. Each segmentation axis reveals distinct margin structures and competitive dynamics that shape supplier positioning and procurement patterns.
Product Type:
Margin pools concentrate in high-performance panel systems where thermal and acoustic specifications command specification premiums.
- Gypsum Board:Calcium sulfate dihydrate panels with paper facings dominate interior partition and ceiling specifications across commercial and residential verticals. Fire-resistance ratings and established manufacturing scale sustain volume leadership in Germany, France, and the United States. Saint-Gobain and Knauf Gips KG leverage captive quarry networks to defend material continuity.
- Insulation Panels:Rigid foam or mineral wool cores laminated to facing boards capture expanding margin pools as EU Green Deal thermal bridging regulations tighten across multiple jurisdictions. French and German commercial retrofits are specifying these assemblies for envelope compliance.
- Metal Studs:Cold-formed steel framing members reduce structural load in vertical construction.
- Cement Board:Portland cement-based panels serve wet-area applications where moisture resistance exceeds gypsum capabilities.
The dominant share belongs to Gypsum Board, while Insulation Panels is closing the gap fastest.
End User:
Application mix shifts toward commercial and infrastructure segments where compressed schedules and future reconfiguration requirements favor dry assembly methods.
- Commercial Spaces:Office towers, healthcare facilities, and educational institutions specify demountable partition systems that enable rapid interior reconfiguration. German hospital contractors are bundling acoustic ceiling and drywall scope to compress MEP coordination timelines. General contractors face skilled installer shortages that push specification toward prefabricated panel systems.
- Residential Buildings:Urban tower construction in China and India concentrates demand for lightweight steel framing and rapid-assembly board systems. Tier-1 and Tier-2 city developers prioritize vertical build speed over material cost minimization.
- Industrial Structures:Manufacturing and warehouse facilities employ metal stud framing for non-load-bearing partitions.
- Infrastructure Projects:Airports and transit terminals specify high-durability ceiling and wall assemblies.
Commercial Spaces holds the revenue concentration, with Residential Buildings expanding most quickly in emerging Asian markets.
Installation Method:
Supply chain configuration determines competitive access, with factory-integrated systems filtering out conventional trade contractors.
- Prefabricated Systems:Factory-assembled wall and ceiling panels minimize on-site labor hours and wet trades. North American contractors facing craft scarcity are accelerating adoption of these systems for large-scale commercial developments. CNC routing and robotic cutting achieve tolerances that manual field methods cannot replicate.
- Modular Construction:Volumetric units with integrated MEP and finishes compress total project duration.
- On-Site Assembly:Conventional stick-framing and board-hanging persists in markets with available labor pools.
- Drywall Installation:Traditional gypsum board hanging remains cost-competitive in single-family residential segments.
Prefabricated Systems commands specification momentum, while Modular Construction gains share in healthcare and education verticals.
Building Type:
Height and occupancy classification drive fire-rating and acoustic performance requirements that segment material specification.
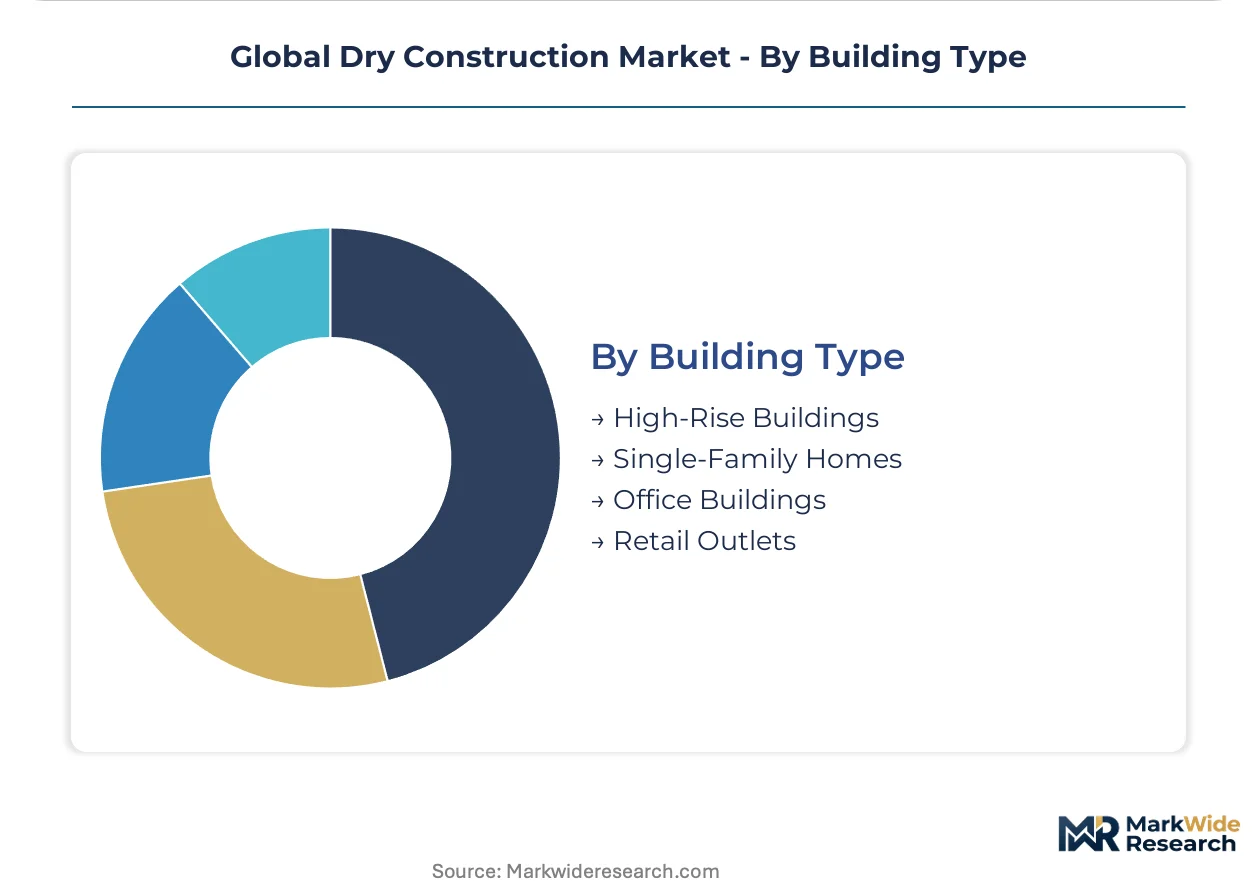
- High-Rise Buildings:Structural load constraints and vertical transportation logistics favor lightweight metal stud framing and thinner board profiles. China's GB standards for interior partition fire ratings shape panel composition requirements in government-funded towers. Weight reduction enables faster floor-cycle times.
- Office Buildings:Tenant improvement cycles demand demountable partition systems.
- Single-Family Homes:Cost-sensitive residential construction maintains conventional on-site drywall methods.
- Retail Outlets:Fast-fitout requirements for franchise rollouts specify rapid-assembly systems.
High-Rise Buildings anchors volume concentration, while Office Buildings shows the steepest specification upgrade trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal mandates anchor European specification patterns, while China's GB standards and India's BIS certification reshape procurement across emerging Asian verticals. National building codes in Germany, the United States, China, India, and France now govern which panel compositions qualify for public infrastructure tenders.
Germany
Commercial real estate developers in Frankfurt and Munich are accelerating specification of prefabricated drywall systems with integrated thermal breaks. The F-Gas Regulation elevates demand for low-embodied-carbon wall assemblies in envelope retrofits. Hospital contractors in Berlin bundle acoustic ceiling and drywall scope to compress MEP coordination timelines.
United States
EPA energy performance standards push general contractors toward factory-assembled wall and ceiling assemblies that minimize on-site wet trades. Skilled installer shortages across the Northeast and West Coast reorganize project timelines toward prefabricated panel systems. Healthcare developers in Texas and California consolidate vendor relationships to streamline commissioning.
China
Urban residential towers across Tier-1 and Tier-2 cities concentrate demand for metal stud framing and rapid-assembly board systems. GB standards for interior partition fire ratings shape panel composition requirements in government-funded infrastructure. The dual carbon goals elevate demand for low-carbon panel compositions in state-backed tenders.
India
Tier-2 city residential towers drive specification of lightweight steel framing that reduces structural load and enables faster vertical build rates. BIS certification for gypsum-based building materials tightens, filtering non-compliant suppliers from project bidding pools. Developers in Maharashtra and Gujarat prioritize vertical build speed over material cost minimization.
France
Healthcare and education end-users in Paris and Lyon specify factory-integrated ceiling systems that compress MEP coordination timelines. REACH compliance protocols force reformulation of adhesive chemistries used in modular panel bonding. Commercial developers absorb elevated R&D costs to retain CE marking eligibility and project access.
Global Dry Construction Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with material continuity and captive distribution networks determining competitive access. Consolidated quarry-to-fabrication operations defend supply security for large-scale commercial developments. Three archetypes dominate: integrated material suppliers with captive distribution, specialized acoustic system integrators, and regional board producers with quarry access. Competitive moves concentrate on backward integration into raw material sourcing and single-source procurement bundling that reduces subcontractor coordination overhead.
Within the integrated tier, Saint-Gobain and Knauf Gips KG exemplify archetypes built around captive gypsum networks and specialized metal framing fabrication. Armstrong World Industries, Inc. occupies a distinct position among acoustic ceiling specialists, representing the integration-focused vector that compresses on-site labor hours through factory-precision systems.
| Leading Market Players |
|---|
| Saint-Gobain |
| Etex Group |
| Armstrong World Industries, Inc. |
| Knauf Gips KG |
| Xella Group |
| CSR Limited |
| Fletcher Building Limited |
| USG Boral Limited |
| Pabco Gypsum |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between German hospital contractors and Saint-Gobain lock in gypsum board supply at fixed indices while insulating buyers from spot volatility in quarry access. These structures bind price visibility to captive raw material networks, compressing margin exposure for developers facing EU Green Deal thermal compliance deadlines.
Pricing Analysis
Project-based contracting dominates commercial drywall procurement, with price differentiation hinging on fire-rating certification tiers and volume scale commitments. Cost compression in standard-grade gypsum board intensifies as Chinese producers expand export capacity into Southeast Asian markets. Residential developers in India's Tier-2 cities exhibit highest price sensitivity, while German healthcare contractors prioritize thermal performance over unit cost.
Supply Chain Analysis
Just-in-time delivery models are displacing strategic stockpiles among French commercial developers seeking to reduce site inventory carrying costs. Raw material sourcing draws from German and Spanish captive quarries for gypsum, Chinese steel mills for metal studs, and Belgian chemical plants for adhesive binders. Single-source vulnerability concentrates in high-purity gypsum deposits, while distribution runs through integrated material suppliers with captive logistics networks rather than fragmented trade contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Dry Construction Market is accelerating through a regulatory inflection as embodied carbon disclosure mandates in Germany, France, and China filter non-compliant panel suppliers from public tender pools. This technological-regulatory convergence compresses qualification windows and rewards integrated producers with captive certification capabilities.
For Market Incumbents: Fortify quarry-to-fabrication integration in Central Europe to defend material continuity against REACH compliance cost escalation. Prioritize captive metal framing production in Poland and the Czech Republic to offset installer craft scarcity pushing specification toward prefabricated systems. For New Entrants and Emerging Players: Acoustic ceiling integration services represent a service-layer gap where Armstrong World Industries and Saint-Gobain under-serve mid-tier healthcare developers in India's Maharashtra state. Penetrate this white space through factory-integrated MEP coordination offerings that compress commissioning timelines for hospital contractors. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated mid-cap specialists with captive BIS certification for gypsum-based materials and established Tier-2 city distribution in India. Watch for inflection when China's GB standards for interior partition fire ratings elevate low-carbon panel specifications in state-backed infrastructure tenders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Quarry Networks | Saint-Gobain and Knauf Gips KG defend supply security against German F-Gas Regulation compliance timelines. |
| Prefabricated Panel System Certification | CE marking for factory-assembled wall systems filters non-compliant sealant suppliers from French commercial bidding pools. |
| Acoustic Ceiling-Drywall Bundle Expansion | Healthcare developers in Texas consolidate vendor relationships to compress MEP coordination overhead. |
| BIS Certification Investment in India | Compliant multinational suppliers capture first-mover advantage in Maharashtra and Gujarat residential towers. |
| Low-Carbon Panel Composition R&D | Chinese producers align with dual carbon goals to qualify for government-funded infrastructure tenders. |
Methodological Framework
A standing panel of commercial general contractors, drywall installation foremen, hospital facility managers, and gypsum board procurement leads provided ongoing calibration against secondary validation from customs trade data, SEC 10-K filings, BIS certification registries, and EU ETS carbon disclosure databases. Bottom-up project pipeline tracking triangulated with top-down construction spend forecasts to anchor volume estimates.
Consistency checks validated volume and value outputs against external benchmarks across product type, end user, installation method, and building type segmentation dimensions. CAGRs derived from modeled floor-area completion rates and panel intensity coefficients, incorporating metal stud substitution elasticities and prefabrication adoption curves as industry-specific forecast inputs.
Forecasts assume regulatory continuity in EU Green Deal implementation, REACH adhesive protocols, and India's BIS certification expansion; material policy shifts would require re-modeling. Revision becomes warranted when embodied carbon disclosure mandates cross enforcement thresholds in additional national building codes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Turkey Commercial Construction Market
Building Construction
Australia Construction Market
Building Construction
Europe Prefab Wood Buildings Market
Building Construction
Early Production Facility Market
Building Construction
Europe Prefabricated Buildings Market
Building Construction
Modular and Portable Building Market
Building Construction
Ireland Data Center Construction Market
Building Construction
UK Construction Market
Building Construction
Saudi Arabia Construction Market
Building Construction
Pre-Engineered Building Market
Building Construction
India Pre-Engineered Buildings Market
Building Construction
Indonesia Commercial Construction Market
Building Construction
Germany Prefab Wood Buildings Market
Building Construction
Sweden New Construction Market
Building Construction
North America Construction Market
Building Construction
India Prefabricated Buildings Market