
 Pyrolysis Oil Market | 2026-2036
Pyrolysis Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Pyrolysis Oil Market Outlook
The gap between premium bio-oil and commodity heavy fuel oil is expanding as certification standards and refinery integration requirements harden. Enerkem leverages gasification-to-liquid expertise to anchor premium pricing for ISCC-certified outputs. Nexus Fuels sustains geographic dominance in the US Gulf Coast through offtake partnerships with regional petrochemical complexes. OMV Aktiengesellschaft differentiates by controlling integrated refining capacity that co-processes pyrolysis oil into drop-in transport fuels.
Pyrolysis oil is a dark, viscous liquid produced through thermal decomposition of biomass or waste plastics in oxygen-starved conditions at temperatures typically ranging from 400°C to 600°C, yielding a complex mixture of oxygenated hydrocarbons used primarily as a renewable industrial fuel or chemical feedstock. Bio-oil from lignocellulosic sources dominates current production volumes due to established agricultural residue supply chains, though synthetic crude from mixed plastic waste is gaining traction as chemical recycling mandates tighten across jurisdictions. Chemical feedstock applications command the strongest margin pools because refiners pay premiums for ISCC Plus-certified material that displaces virgin naphtha, while power production remains a commoditized outlet vulnerable to natural gas price swings.
The EU Green Deal and RED III framework mandate escalating renewable energy shares in transport, compelling fuel suppliers to source certified pyrolysis oil or face compliance penalties. EPA Renewable Fuel Standard pathways for cellulosic diesel create parallel demand pull in the United States, though RIN qualification timelines introduce regulatory uncertainty for project developers. Stakeholders must monitor evolving lifecycle assessment methodologies, as border carbon adjustments and fuel certification schemes increasingly differentiate tradable volumes from stranded production lacking verified greenhouse gas reductions.
Market Dynamics
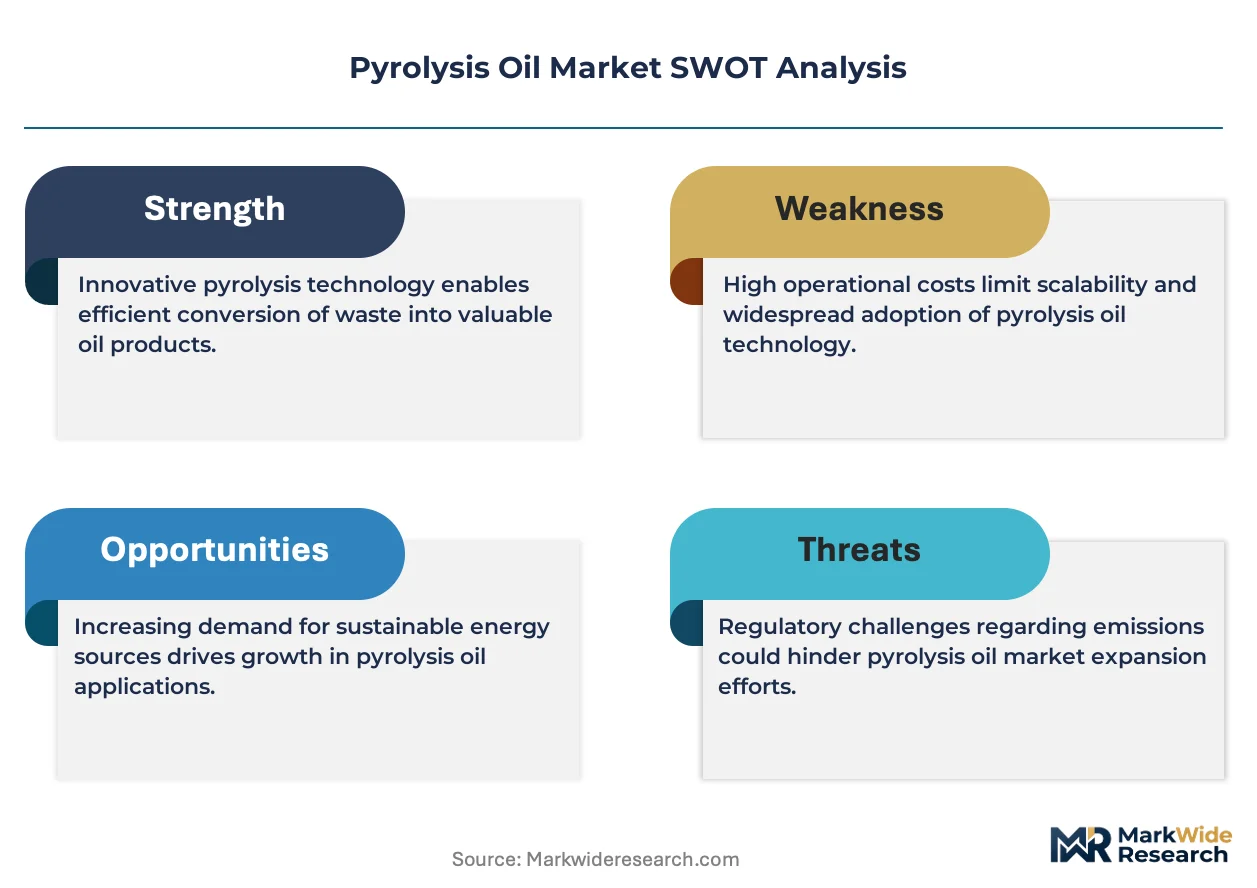
Refinery co-processing certification requirements are bifurcating the pyrolysis oil supply base into ISCC Plus-qualified premium volumes and stranded commodity production, concentrating offtake power among integrated chemical park operators with captive upgrading infrastructure.
Growth Catalysts
- EU Green Deal transport fuel mandates:RED III escalating renewable energy obligations compel fuel suppliers to secure certified pyrolysis oil volumes or absorb compliance penalties, redirecting procurement toward verified low-carbon pathways.
- Chemical recycling infrastructure buildout:Clustered waste-to-fuel hubs in Germany and the Netherlands enable economies of scale in feedstock aggregation and quality upgrading for refinery integration.
- Lignocellulosic residue valorization:Agricultural waste supply chains in Finland and the Baltic states provide cost-advantaged biomass feedstock for continuous pyrolysis reactor operations.
Market Restraints
- Natural gas price volatility:Commodity pyrolysis oil for power generation competes directly with gas-fired alternatives, compressing margins when Henry Hub or TTF benchmarks spike.
- Feedstock quality inconsistency:Mixed plastic waste streams require extensive pre-treatment to meet refinery co-processing specifications, elevating operational complexity and yield losses.
- REACH registration burden:EU chemical regulation compliance timelines for novel bio-oil fractions delay market entry for emerging producers lacking regulatory affairs capacity.
Strategic Opportunities
- Border carbon adjustment preparation:EU CBAM implementation creates first-mover advantage for producers with verified lifecycle greenhouse gas inventories ahead of full phase-in.
- Marine fuel blending:IMO 2020 sulfur caps and pending well-to-wake carbon intensity rules position pyrolysis oil as a compliant bunker fuel component for coastal shipping routes.
- Biomass-to-chemicals pivot:Hydrotreated bio-oil fractions displace virgin naphtha in aromatics production, capturing margin premiums from brand-owner recycled content commitments.
Industry Challenges
- ISCC Plus auditor scarcity:Certification body capacity constraints extend verification timelines from months to over a year, delaying offtake contract execution and revenue recognition.
- Reactor scaling engineering:Translating pilot-scale pyrolysis yields to commercial continuous operation requires specialized thermal process expertise concentrated among a limited contractor pool.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pyrolysis Oil Market |
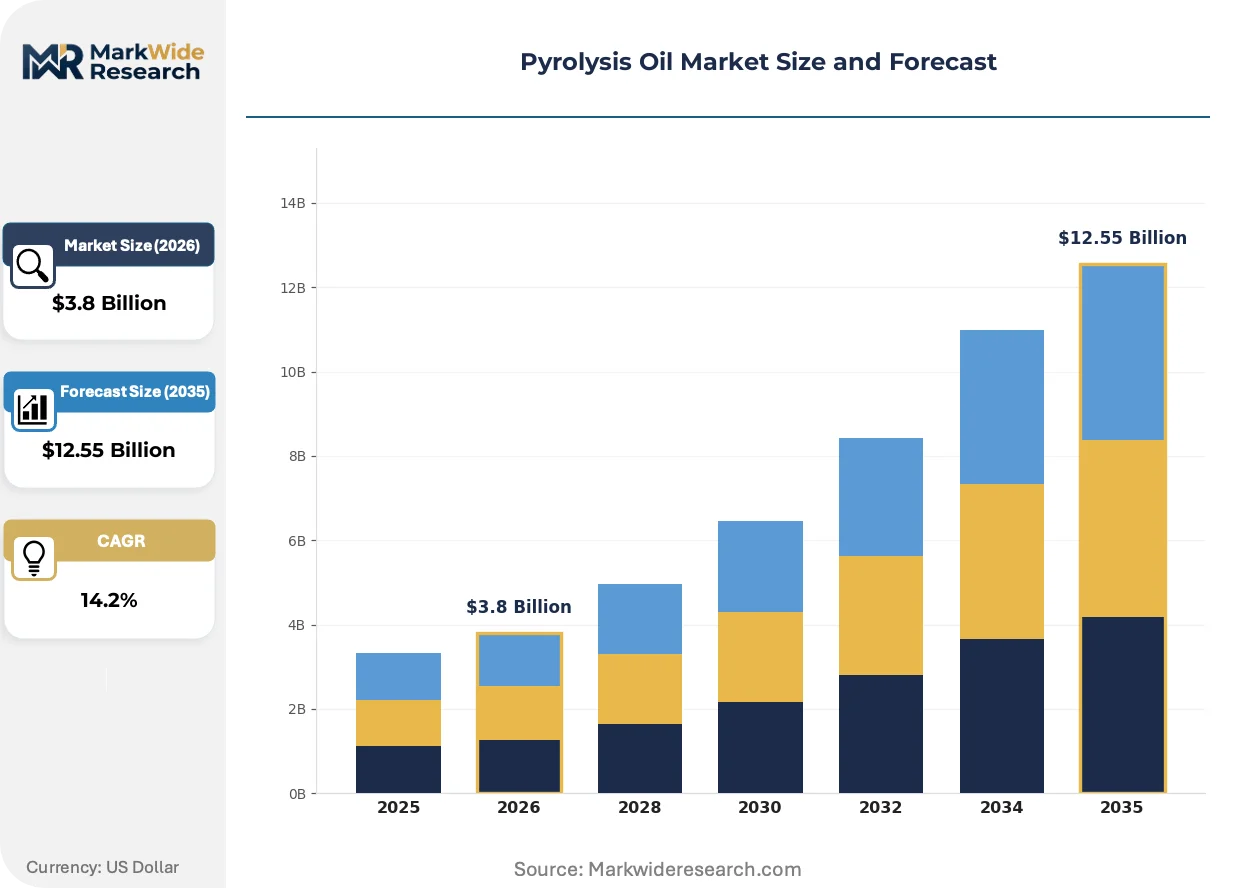
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bio-Oil, Char Oil, Synthetic Crude, Heavy Fuel Oil End User: Power Generation, Chemical Manufacturing, Transportation, Heating Application: Heating Applications, Industrial Fuel, Chemical Feedstock, Power Production Deployment: Onshore, Modular Units, Small Scale, Large Scale |
| Companies Covered | Enerkem, Nexus Fuels, Agilyx Corporation, Plastic Energy, BTG Biomass Technology Group, OMV Aktiengesellschaft, Alterra Energy, Neste, Fortum Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pyrolysis Oil Market Strategic Shifts
Technology convergence between fast pyrolysis reactor design and hydrotreating catalyst development is compressing the capital intensity gap between bio-oil upgrading and conventional refinery investments, reshaping project finance assumptions.
Fast pyrolysis reactor technology converts lignocellulosic biomass into liquid bio-oil through rapid heating and quenching cycles. Refinery operators with existing hydrotreater capacity are piloting direct co-processing at 5-10% blend ratios to validate catalyst stability. This technology is modularizing, enabling distributed production nodes that aggregate feedstock regionally before pipeline injection to central upgrading facilities.
The EU Green Deal's delegated acts on renewable fuels of non-biological origin establish stringent carbon intensity thresholds for transport fuel crediting. Fuel suppliers must demonstrate 65% lifecycle greenhouse gas savings against fossil baselines to qualify for multiplier incentives. Chemical park operators in Rotterdam and Antwerp are restructuring supply agreements to lock in certified volumes ahead of 2030 compliance deadlines.
Long-term offtake contracting is displacing spot market transactions as the dominant procurement modality for premium-grade material. Brand-owner recycled content mandates in packaging and automotive sectors are concentrating demand among chemical manufacturers with ISCC Plus chain-of-custody systems. This shift is most visible in Germany, where integrated refinery-petrochemical complexes now require five-year supply commitments to justify co-processing infrastructure investments.
Pyrolysis Oil Market Segmentation
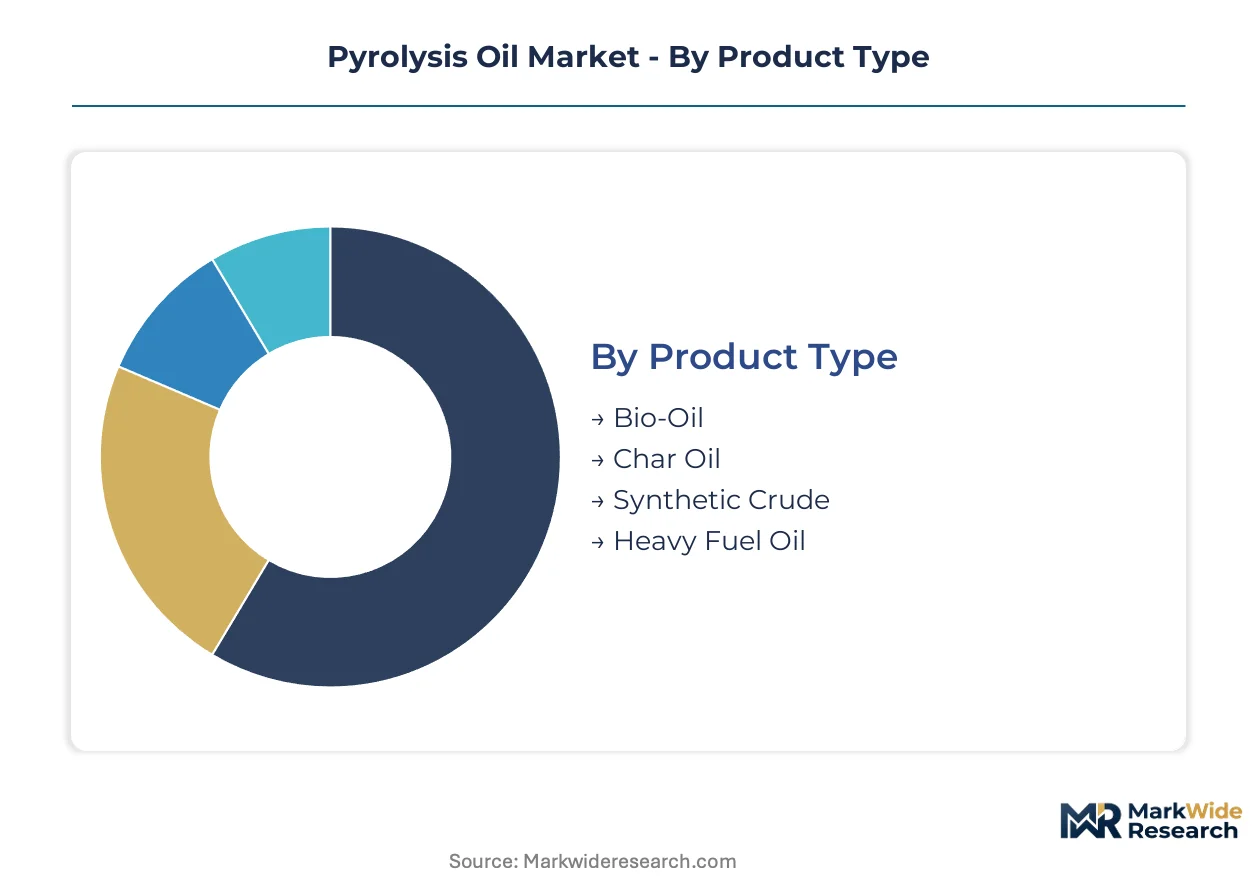
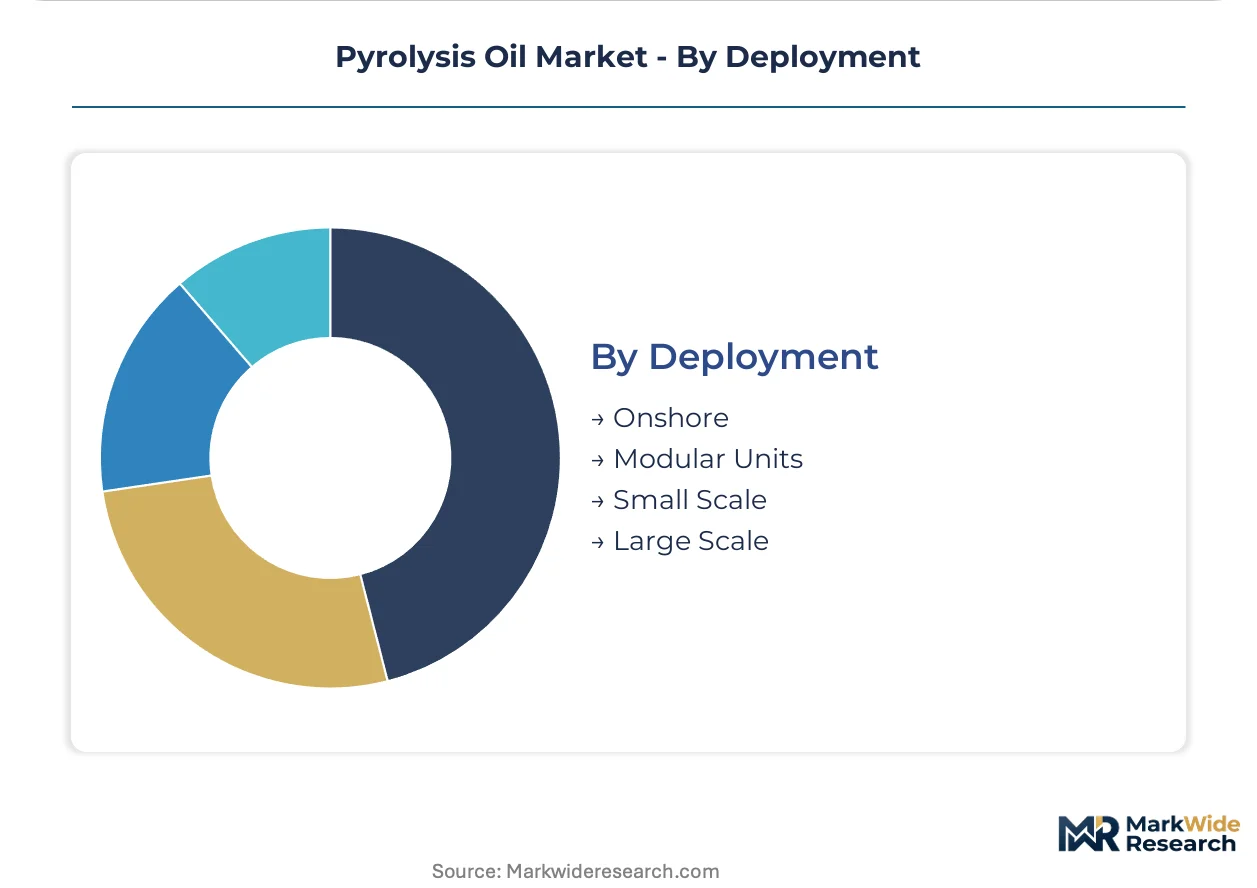
Pyrolysis oil segmentation reveals stark capital intensity gradients across product grades and deployment scales. Refinery co-processing specifications and certification tiers fragment the supply base into premium-certified volumes versus stranded commodity production.
Product Type:
Fast pyrolysis reactors and hydrotreater integration requirements create divergent capital thresholds across product categories.
- Bio-Oil:Oxygenated liquid from lignocellulosic biomass thermal decomposition at 400-600°C. Demand concentrates in Germany and the Netherlands where clustered chemical parks enable ISCC Plus-certified refinery co-processing under EU Green Deal transport mandates.
- Synthetic Crude:Deoxygenated hydrocarbon stream from mixed plastic waste catalytic upgrading. Chemical manufacturers in Rotterdam and Antwerp pay premiums for this ISCC-certified naphtha substitute to meet brand-owner recycled content commitments.
- Char Oil:High-carbon fraction from slow pyrolysis of woody biomass. Steel producers in Finland blend this into pulverized coal injection systems.
- Heavy Fuel Oil:Unupgraded raw pyrolysis liquid with high water and particulate content. Power generators in the Baltic states deploy this for baseload heat when natural gas prices spike.
Most installed capacity flows through Bio-Oil. Expansion is steepest in Synthetic Crude.
End User:
Margin capture varies dramatically by customer sophistication and chain-of-custody requirements.
- Chemical Manufacturing:Aromatics and olefins producers leverage hydrotreated fractions to displace virgin naphtha. OMV Aktiengesellschaft's integrated refineries in Austria co-process certified volumes into drop-in transport fuels.
- Power Generation:District heating operators and industrial boilers burn raw bio-oil for thermal output. This segment faces margin compression when TTF natural gas benchmarks collapse.
- Transportation:Marine fuel blenders position pyrolysis oil as IMO 2020-compliant bunker component for coastal shipping routes in the North Sea and Baltic.
- Heating:Residential and commercial boilers in rural Finland and Estonia utilize local agricultural residue supply chains for distributed thermal supply.
Chemical Manufacturing commands the strongest pricing power. Transportation is climbing the fastest as marine decarbonization rules tighten.
Application:
Downstream value creation depends on oxygen content reduction and catalyst compatibility with existing refinery infrastructure.
- Chemical Feedstock:Hydrotreated bio-oil fractions meet refinery naphtha specifications for aromatics production. REACH registration burdens delay market entry for novel fractions lacking regulatory affairs capacity.
- Industrial Fuel:Cement kilns and steel furnaces burn medium-grade pyrolysis oil for process heat. Pre-treatment requirements elevate operational complexity for mixed plastic waste streams.
- Heating Applications:District energy systems in the Netherlands inject upgraded bio-oil into existing fuel oil distribution networks.
- Power Production:Combined heat and power plants face stranded asset risk when natural gas price volatility undercuts bio-oil economics.
Chemical Feedstock captures the highest margin pools. Heating Applications is expanding most quickly as district energy systems decarbonize.
Deployment:
Scale economics and feedstock aggregation radius determine project finance viability and offtake contract structures.
- Large Scale:Centralized facilities with 100+ ton per day capacity co-locate with refinery-petrochemical complexes. Five-year supply commitments justify co-processing infrastructure investments in Germany.
- Modular Units:Containerized fast pyrolysis systems enable distributed production nodes that aggregate agricultural residue regionally. These units feed pipeline injection to central upgrading facilities.
- Small Scale:Farm-level pyrolyzers process 5-20 tons daily of local lignocellulosic waste. Finland's Baltic state supply chains favor this configuration.
- Onshore:Fixed installations at industrial parks leverage existing utility infrastructure and skilled labor pools.
Most installed capacity flows through Large Scale. Modular Units are gaining share fastest as feedstock logistics optimization reshapes project economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized chemical engineers and pyrolysis process technicians cluster around Rotterdam, Antwerp, and the German Rhine-Ruhr corridor. These talent pools enable refinery co-processing integration at scale. Their concentration shapes where certified pyrolysis oil volumes achieve commercial traction.
Germany
Chemical manufacturers in Ludwigshafen and Leverkusen purchase ISCC Plus-certified bio-oil for naphtha displacement. The EU Green Deal's RED III mandates compel fuel suppliers to source renewable feedstocks or face penalties. The Rhine-Ruhr chemical park network aggregates pyrolysis oil from Baltic biomass supply chains for continuous refinery co-processing.
Netherlands
Rotterdam's port infrastructure enables waste-to-fuel feedstock aggregation from across Northwest Europe. REACH registration requirements for novel bio-oil fractions filter out smaller producers lacking regulatory capacity. The Port of Rotterdam Authority coordinates pipeline injection of upgraded pyrolysis oil to Shell and BP refining complexes.
Finland
Forest industry engineers and lignocellulosic supply chain managers concentrate around Helsinki and Tampere. The country's national energy regulator enforces strict sustainability criteria for transport fuel crediting. UPM-Kymmene's biorefinery cluster in Lappeenranta processes agricultural residues into hydrotreated bio-oil fractions.
United States
EPA Renewable Fuel Standard pathways for cellulosic diesel create compliance-driven demand in Texas and Louisiana. RIN qualification timelines introduce regulatory uncertainty that delays project financing. The US Gulf Coast petrochemical corridor hosts Nexus Fuels' offtake partnerships with regional refining complexes.
Belgium
Antwerp's integrated refinery-petrochemical sites require five-year supply commitments to justify co-processing infrastructure investments. The EU Green Deal's delegated acts on renewable fuels establish carbon intensity thresholds that filter uncertified volumes. The Antwerp@C carbon capture cluster explores bio-oil integration with circular carbon technologies.
Pyrolysis Oil Market Competitive Environment
Top-tier vendors anchor integrated refining and chemical manufacturing positions, while mid-tier specialists concentrate on modular reactor deployment and feedstock aggregation. The supply base stratifies between ISCC Plus-certified premium producers and commodity-grade operators lacking verification. Three archetypes dominate: integrated energy majors with captive upgrading infrastructure, pure-play pyrolysis technology licensors, and waste management conglomerates backward-integrating into fuel production. Competitive moves center on long-term offtake contracting and certification body partnerships to secure auditor access.
Within the integrated energy tier, OMV Aktiengesellschaft and Neste occupy positions exemplifying refinery co-processing dominance. Among technology-focused developers, Enerkem and Nexus Fuels represent archetypes of gasification-to-liquid and plastic waste pyrolysis specialization respectively. Fortum Oyj anchors the Nordic biomass-to-fuel vector. These named entities illustrate how geographic clustering around Rotterdam, Vienna, and Helsinki shapes competitive positioning without requiring specific operational claims.
| Leading Market Players |
|---|
| Enerkem |
| Nexus Fuels |
| Agilyx Corporation |
| Plastic Energy |
| BTG Biomass Technology Group |
| OMV Aktiengesellschaft |
| Alterra Energy |
| Neste |
| Fortum Oyj |
| Others |
Value Chain & Pricing Dynamics
ISCC Plus certification bifurcation splits the pyrolysis oil market into premium contract tiers and stranded commodity volumes, with this divergence manifesting in long-term offtake premiums for verified low-carbon pathways and concentrated supply chain investment around Rotterdam and Antwerp refining clusters.
Pricing Analysis
Bundled certification-plus-upgrading services command substantial premiums over unbundled raw bio-oil spot transactions. Three-tier pricing structure across premium-certified, standard-grade, and economy spot tiers reflects oxygen content and carbon intensity verification levels. Cost compression in commodity power-generation grades is intensifying because natural gas price volatility erodes bio-oil competitiveness during supply gluts. Chemical manufacturers with ISCC Plus chain-of-custody systems exhibit the least price sensitivity, while district heating operators demonstrate acute responsiveness to fuel switching economics.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Antwerp, and Hamburg anchor hub-and-spoke feedstock aggregation patterns across Northwest Europe. Feedstock supply concentrates in Germany, the Netherlands, and Finland where clustered chemical parks enable pipeline injection to central upgrading facilities. Production draws from lignocellulosic agricultural residues, mixed plastic waste streams, and forestry byproducts. Single-source vulnerability around ISCC Plus auditor capacity extends certification timelines and delays revenue recognition. Distribution runs through integrated refinery-petrochemical complexes with captive hydrotreater infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pyrolysis oil market represents a late-cycle quality story as EU Green Deal transport mandates harden carbon intensity thresholds and redirect procurement toward verified premium grades with documented lifecycle greenhouse gas savings.
For Market Incumbents: Acquire ISCC Plus certification body partnerships to secure auditor access and accelerate verification timelines. Consolidate backward integration into Baltic agricultural residue supply chains to lock in cost-advantaged biomass feedstock. Emerging pure-play pyrolysis technology licensors threaten margin compression through modular reactor deployment. Capacity addition in Finland and the Baltic states anchors feedstock security against regional competitors. For New Entrants and Emerging Players: Capture modular unit deployment opportunities in agricultural residue-rich regions lacking pipeline connectivity to central upgrading hubs. Marine fuel blending for IMO 2020-compliant coastal shipping routes represents the most penetrable application segment. Target district heating operators in Estonia and rural Finland with distributed small-scale pyrolyzer configurations. Technology licensing partnerships with established hydrotreater operators provide the critical go-to-market angle for quality validation. For Investors and Strategic Acquirers: Asymmetric upside sits with integrated refinery-petrochemical operators with captive upgrading infrastructure and existing ISCC Plus chain-of-custody systems. Long-term viability over the mid-decade horizon rests on demonstrated ability to meet tightening EU delegated acts on renewable fuel carbon intensity thresholds. Acquisition targets should exhibit five-year offtake contract coverage with brand-owner backed recycled content commitments. The signal to watch is ISCC Plus auditor capacity expansion announcements as inflection indicator for certification bottleneck resolution.| Strategic Initiative | Industry Significance |
|---|---|
| ISCC Plus Certification Investment | Secures premium pricing access under EU Green Deal RED III transport mandates. |
| Backward Integration into Feedstock Supply | Captures cost advantages from Baltic lignocellulosic residue aggregation networks. |
| Long-term Offtake Contracting | Locks in five-year supply commitments from Rotterdam and Antwerp chemical parks. |
| Modular Reactor Deployment | Enables distributed production nodes feeding pipeline injection to central upgrading facilities. |
| Hydrotreater Co-processing Partnership | Validates catalyst stability for 5-10% blend ratios in existing refinery infrastructure. |
Study Parameters
Direct dialogue with pyrolysis plant managers, refinery co-processing engineers, ISCC certification auditors, and chemical procurement leads grounds qualitative assessment in operational reality. Secondary validation draws from EU ETS registry data, REACH registration filings, customs trade statistics for bio-oil movements, and SEC disclosures from integrated energy majors. Bottom-up capacity installation tracking and top-down demand modeling from transport fuel mandates enable triangulation across independent analytical paths.
Bottom-up segmentation modeling across product type, end user, application, and deployment scale dimensions structures volume and value outputs across the projection horizon. CAGRs derive from feedstock availability curves, refinery co-processing capacity expansion announcements, and regulatory compliance deadline clustering. Modeled inputs include ISCC Plus certification penetration rates, natural gas price benchmark correlations, and hydrotreater catalyst replacement cycles.
Feedstock quality inconsistency, ISCC auditor capacity constraints, and natural gas price volatility are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented parameter sets without claiming predictive certainty. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Petroleum Products
Pygas (Pyrolysis Gasoline) Market
Petroleum Products
Helical Submerged Arc Welded Pipe Market
Petroleum Products
Natural Gas Liquid Market
Petroleum Products
France Refined Petroleum Product Market
Petroleum Products
Nigeria Petrol Station Market
Petroleum Products
Gasoline-Naphtha-Crude-MTBE Market
Petroleum Products
Very Low Sulphur Fuel Oil (VLSFO) Market
Petroleum Products
Crude Tall Oil Market
Petroleum Products
East Africa Refined Petroleum Products Market
Petroleum Products
Crude Oil Flow Improvers Market
Petroleum Products
Petroleum Liquid Feedstock Market
Petroleum Products
Performance Oil Sales Market
Petroleum Products
United States Refined Petroleum Products Market
Petroleum Products
Africa Refined Petroleum Products Market
Petroleum Products
North America Natural Gas Liquids Market
Petroleum Products
Pale Oil Market