
 Europe Bunker Fuel Market | 2026-2036
Europe Bunker Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Bunker Fuel Market Foresight
ISO 8217 marine fuel quality certification is unwinding the competitive landscape for smaller blenders unable to meet tightened sulphur and catfine specifications. Shell PLC leverages its integrated refining network to secure VLSFO supply across ARA hub terminals. TotalEnergies SE anchors its position through biofuel blending investments at French Atlantic ports. Minerva Bunkering competes by specializing in LNG-bunker dual-fuel deliveries at Mediterranean transshipment nodes.
Bunker fuel denotes residual and distillate marine fuels burned in two-stroke and four-stroke diesel engines aboard commercial vessels, with VLSFO containing maximum 0.50% sulphur by mass and MGO offering sub-0.10% sulphur content for emission control areas. Its primary purpose is propulsion and auxiliary power generation for cargo ships, tankers, and offshore support craft. VLSFO dominates volume flows as the default compliant grade post-IMO 2020, while MGO captures premium pricing in Baltic and North Sea ECAs where sulphur limits tighten further. LNG bunkering posts the fastest growth trajectory among fuel types, though from a small base concentrated at northwest European ports with cryogenic infrastructure.
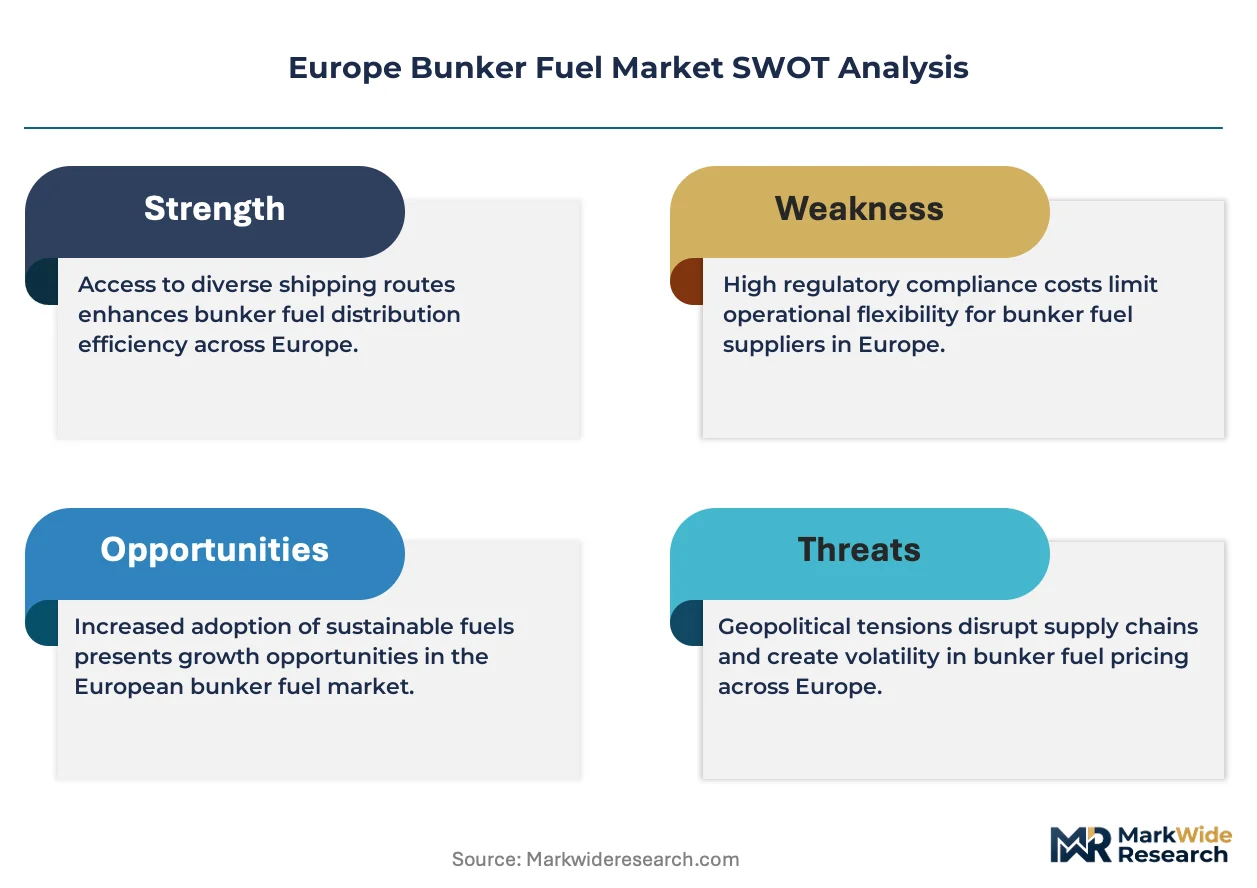
The EU Green Deal, FuelEU Maritime regulation, and IMO 2020 sulphur cap collectively reshape product specifications and carbon accounting requirements for suppliers serving European waters. ECHA's REACH framework additionally governs chemical safety documentation for fuel additives and bio-component blends. Stakeholders must monitor whether the EU Emissions Trading System extends to cover marine fuels fully, as this would restructure bunker procurement economics for operators on intra-European routes.
Market Dynamics
FuelEU Maritime's progressive carbon intensity mandates are forcing vessel operators to recalibrate bunker procurement strategies across European port networks. Suppliers must now certify fuel carbon footprints while maintaining ISO 8217 quality compliance, compressing margins for blenders lacking integrated refining or biofuel capabilities.
Growth Catalysts
- Container shipping expansion:Mediterranean and North Sea port calls by major lines sustain VLSFO demand at Rotterdam, Antwerp, and Barcelona terminals.
- EU Green Deal implementation:The FuelEU Maritime regulation mandates 2% renewable fuel use by 2025, accelerating biofuel blend adoption.
- LNG infrastructure buildout:Cryogenic bunkering facilities at northwest European ports enable dual-fuel vessel conversions.
Market Restraints
- Crude price volatility:Residual fuel oil feedstock costs fluctuate with Russian crude substitution patterns, destabilizing blender margins.
- ARA hub concentration:Rotterdam-Amsterdam-Antwerp supply dominance creates single-point vulnerability for northwest European coverage.
- Catfine contamination risk:Tightened ISO 8217 particulate specifications disqualify smaller storage terminals lacking centrifuge upgrades.
Strategic Opportunities
- Biofuel blending at French Atlantic ports:Underutilized storage capacity at La Rochelle and Le Havre supports hydrotreated vegetable oil distribution.
- Methanol bunkering pilot programs:Maersk's vessel orders create demand for green methanol supply chains at first-mover terminals.
- Carbon accounting services:FuelEU Maritime's well-to-wake reporting requirements open adjacent revenue streams for verification providers.
Industry Challenges
- Cryogenic engineering talent scarcity:LNG bunkering operations require certified cryogenic handlers, with training pipelines lagging deployment timelines.
- Dual-certification complexity:Operators must simultaneously satisfy ISO 8217 quality standards and FuelEU carbon intensity verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Bunker Fuel Market |
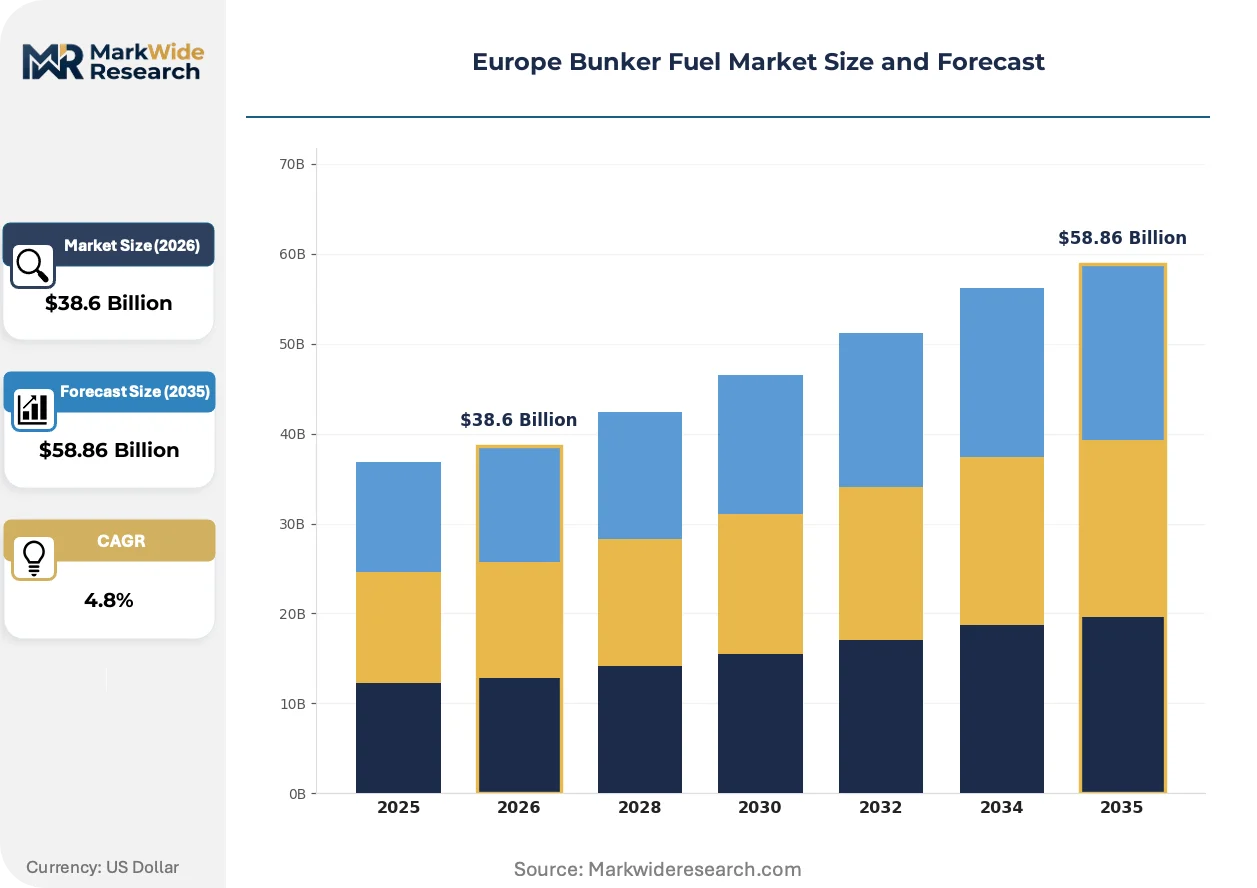
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $58.86 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: IOPS, MGO, HFO, VLSFO Application: Shipping, Fishing, Offshore, Tugboat Distribution Channel: Direct Sales, Wholesale, Retail, Online End User: Commercial Shipping, Yachts, Navy, Freight |
| Companies Covered | Gazprom Neft PJSC, Peninsula Petroleum, Shell PLC, Vitol Group, Minerva Bunkering, BP PLC, Bunker Holding, Monjasa A/S, TotalEnergies SE, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Bunker Fuel Market Shifts & Advancements
Digital fuel quality tracking and alternative fuel infrastructure are compressing traditional bunker trading margins while opening new service revenue pools. Suppliers are repositioning from commodity merchants to integrated marine energy providers.
Biofuel bunkering is decomposing the conventional fossil-residual supply structure. Container lines operating Baltic and North Sea routes are mandating B30-B100 biofuel blends for chartered tonnage. This shift is fragmenting procurement contracts into separate fossil and renewable fuel streams with distinct pricing and certification requirements.
ECHA's REACH framework now governs chemical safety documentation for fuel additives and bio-component blends entering European ports. Fuel suppliers must register novel biofuel molecules and maintain updated safety data sheets. Mediterranean transshipment hubs face particular compliance pressure due to mixed-origin cargo handling.
Long-term offtake agreements are displacing spot market purchases among container shipping lines seeking supply security for alternative fuels. Charter parties now incorporate fuel clause renegotiation triggers tied to carbon intensity thresholds. Greek and German liner operators have pioneered this contracting evolution in their European network procurement.
Europe Bunker Fuel Market Segmentation
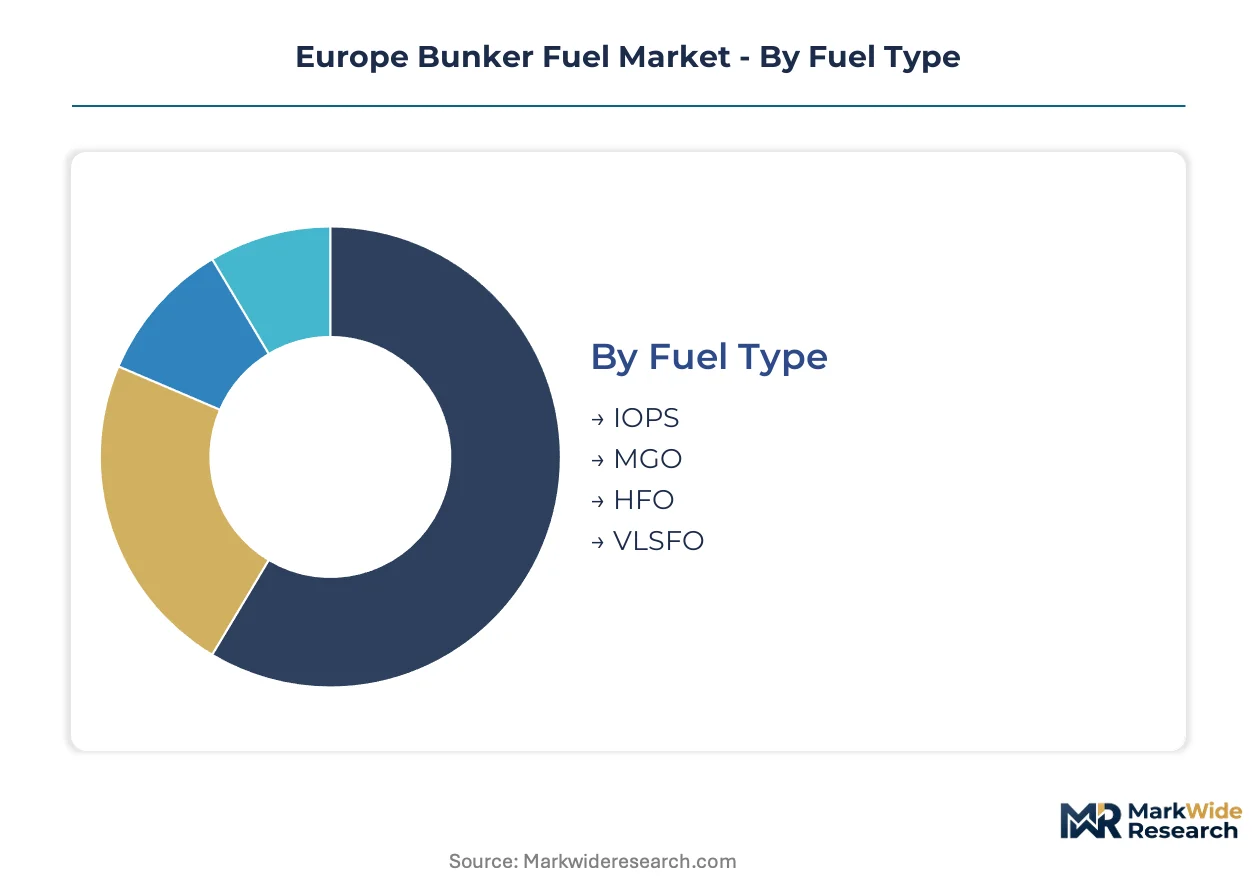
Segmentation in the Europe Bunker Fuel Market exposes how regulatory pressure and vessel technology split procurement patterns across fuel grades and customer types. Suppliers configure blending capacity and storage assets differently for each segment, with ISO 8217 compliance tiers and FuelEU carbon intensity rules creating distinct service requirements.
Fuel Type:
Domestic European demand concentrates on low-sulphur grades for ECAs, while export-oriented deep-sea routes sustain residual fuel volumes at Rotterdam and Barcelona.
- VLSFO:A residual-distillate blend capped at 0.50% sulphur by mass, formulated for two-stroke marine diesel engines. Container lines operating Mediterranean and North Sea routes procure this grade at Rotterdam, Antwerp, and Barcelona terminals to meet IMO 2020 compliance without exhaust gas cleaning systems. The grade dominates volume flows as the default post-regulation standard.
- MGO:Distillate marine gasoil with sub-0.10% sulphur content, specified for emission control areas in the Baltic and North Sea. Ferry operators and cruise lines bunker MGO at Stockholm, Copenhagen, and Hamburg to satisfy stricter ECA limits, absorbing premium pricing for the compliance margin.
- HFO:High-sulphur residual fuel oil above 0.50% sulphur, now restricted to vessels equipped with scrubbers. Scrubber-fitted bulk carriers on Asia-Europe routes lift HFO at Gibraltar and Malta outer anchorage where price differentials against VLSFO justify capital recovery.
- IOPS:Intermediate fuel oils and specialty blends for offshore supply vessels and ice-class tonnage. Norwegian North Sea operators specify IOPS grades with enhanced cold-flow properties at Stavanger and Bergen.
VLSFO commands the established base. The steepest expansion runs through MGO as Baltic and North Sea ECAs tighten sulphur enforcement.
Application:
Cost tier separation is pronounced, with deep-sea shipping absorbing bulk volume at thin margins while offshore and tugboat segments pay premiums for specialized delivery logistics.
- Shipping:Container lines, tankers, and bulk carriers burning VLSFO and MGO for propulsion and auxiliary power. Mediterranean transshipment hubs at Marsaxlokk and Algeciras see concentrated demand from mega-vessel calls requiring 2,000+ metric tonne stems.
- Offshore:Platform supply vessels and drilling units operating on IOPS and MGO blends. North Sea fields off Aberdeen and Esbjerg generate demand for 24/7 delivery windows and dynamic positioning compatibility.
- Fishing:Trawler and purse-seiner fleets in the North Atlantic and Bay of Biscay. Spanish and French Atlantic ports supply smaller stems with seasonal concentration during quota periods.
- Tugboat:Harbor and coastal towage operators with high-frequency, low-volume bunkering needs. Port authorities at Rotterdam and Hamburg coordinate consolidated delivery schedules.
Shipping absorbs the volume base. Offshore applications are climbing the fastest as North Sea decommissioning and wind farm installation intensify.
Distribution Channel:
Volume concentration favors direct and wholesale channels, with retail and online emerging as service differentiators for smaller operators lacking procurement scale.
- Wholesale:Terminals and traders selling ISO 8217-certified product to resellers and large fleet operators. ARA hub wholesalers move 5,000+ tonne parcels to Greek and German liner operators under annual contracts.
- Direct Sales:Integrated suppliers like Shell and TotalEnergies delivering ex-pipe or barge to vessel at berth. Direct relationships dominate container line procurement with FuelEU carbon intensity verification bundled into supply agreements.
- Retail:Smaller ports and coastal depots serving fishing and tugboat fleets. French Atlantic retail points at La Rochelle and Le Havre support biofuel blend distribution.
- Online:Digital platforms for spot charterers and tramp operators seeking real-time pricing. Mediterranean brokers use online channels to match available barges with yacht and short-sea demand.
Wholesale and direct sales command the established base. Online channels are gaining share fastest as digital procurement penetrates fragmented owner-operator segments.
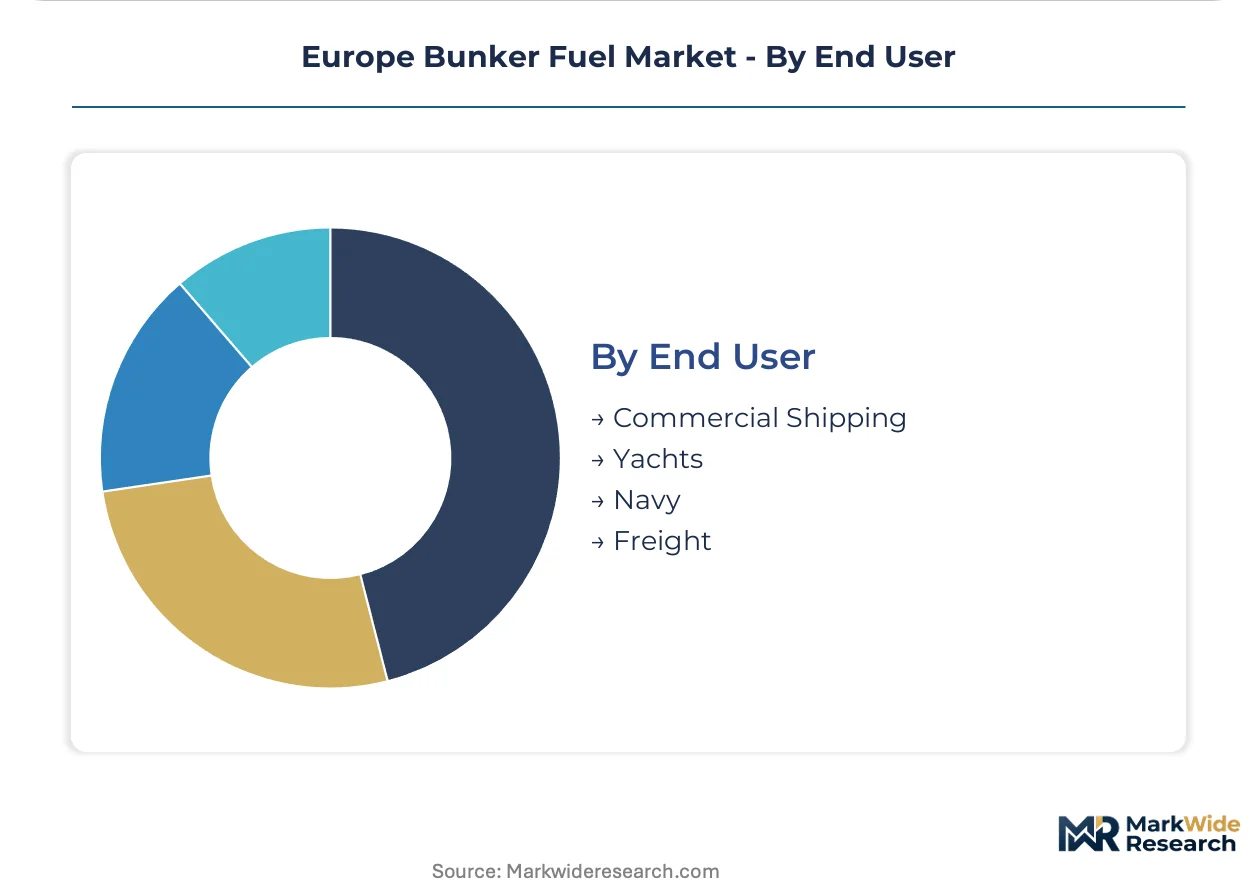
End User:
Customer type determines certification burden, with commercial shipping facing FuelEU mandates while yacht and navy segments operate under exempt or classified procurement regimes.
- Commercial Shipping:Container lines, tankers, and bulk carriers subject to EU ETS and FuelEU Maritime carbon accounting. Greek and German operators have pioneered long-term offtake agreements with renegotiation triggers tied to carbon intensity thresholds.
- Freight:Short-sea and feeder operators on intra-European routes. Baltic ro-ro and ferry companies at Trelleborg and Kiel source MGO for frequent port calls within ECA boundaries.
- Navy:Naval vessels with NATO fuel specifications and strategic stockpile access. British and French naval bases at Portsmouth and Toulon maintain dedicated supply chains outside commercial market pricing.
- Yachts:Superyacht and recreational marine segment with premium MGO requirements. Monaco and Palma de Mallorca terminals specialize in high-specification, low-catfine product with concierge delivery.
Commercial shipping commands the established base. Freight operators are expanding most quickly as short-sea modal shift and Baltic route densification accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FuelEU Maritime's carbon intensity mandates are recalibrating procurement patterns across European port networks. Rotterdam's bunkering infrastructure anchors northwest European supply chains. Mediterranean hubs are expanding alternative fuel capabilities to capture transshipment demand.
Netherlands
Rotterdam's ARA hub terminals process the largest fuel volumes in Europe, with Shell PLC and Vitol Group leveraging integrated refining networks to secure VLSFO supply. The Dutch Authority for Consumers and Markets enforces competition rules while the port authority coordinates LNG infrastructure buildout. Rotterdam's cryogenic bunkering facilities enable dual-fuel vessel conversions at Europe's densest maritime cluster.
Germany
Hamburg and Bremen ports sustain MGO demand from Baltic and North Sea ferry operators facing tightened ECA sulphur limits. The Federal Maritime and Hydrographic Agency enforces IMO 2020 compliance through port state control inspections. German liner operators have pioneered long-term offtake agreements with carbon intensity renegotiation triggers.
France
TotalEnergies SE anchors biofuel blending investments at La Rochelle and Le Havre terminals, capturing FuelEU Maritime's renewable fuel mandates. The French Directorate General for Maritime Affairs implements EU Green Deal regulations across Atlantic port networks. French Atlantic retail points support hydrotreated vegetable oil distribution to fishing and short-sea fleets.
Spain
Barcelona and Algeciras terminals concentrate Mediterranean transshipment demand from mega-vessel calls requiring 2,000+ metric tonne stems. Spain's Directorate General of the Merchant Marine enforces FuelEU Maritime reporting requirements for vessels calling at national ports. The Port of Barcelona is expanding LNG bunkering capacity to service dual-fuel container lines.
United Kingdom
Aberdeen and Southampton ports generate offshore supply vessel demand for IOPS grades with enhanced cold-flow properties. The Maritime and Coastguard Agency enforces ISO 8217 quality standards through fuel sampling protocols. Aberdeen's North Sea cluster supports 24/7 delivery windows for platform supply and wind farm installation vessels.
Europe Bunker Fuel Market Competitive Landscape
Player mix skews toward integrated oil majors and specialized marine fuel traders. The supplier base concentrates around Rotterdam-Amsterdam-Antwerp hub infrastructure, with tiered differentiation between global refiners and regional blenders. Two strategic archetypes dominate: vertically integrated energy majors leveraging captive refining capacity, and independent traders specializing in alternative fuel logistics. Competitive moves center on biofuel blending investments and LNG infrastructure partnerships.
Within the integrated major tier, Shell PLC and BP PLC exemplify scale-driven positioning through ARA terminal networks and direct sales relationships. Among specialized traders, Peninsula Petroleum and Minerva Bunkering occupy positions emphasizing LNG-bunker dual-fuel deliveries at Mediterranean nodes. Bunker Holding represents the independent distributor archetype with multi-port coverage. Gazprom Neft PJSC anchors the Russian-origin supply segment, though substitution patterns are restructuring feedstock flows. Vitol Group and TotalEnergies SE exemplify trading-house and national-champion models respectively.
| Leading Market Players |
|---|
| Gazprom Neft PJSC |
| Peninsula Petroleum |
| Shell PLC |
| Vitol Group |
| Minerva Bunkering |
| BP PLC |
| Bunker Holding |
| Monjasa A/S |
| TotalEnergies SE |
| Others |
Supply & Pricing Matrix
Rotterdam's 45 million cubic metres of liquid bulk storage capacity anchors the lowest delivered-cost position for VLSFO across northwest Europe, compressing price floors for independent blenders lacking equivalent scale. This concentration of tankage and barge fleets at the ARA hub enables integrated majors to cross-subsidize thin-margin spot sales while smaller operators absorb higher per-unit logistics burdens on fragmented coastal routes.
Pricing Analysis
Certification level under ISO 8217 creates the primary spread between premium and distressed product, with sub-0.10% sulphur MGO commanding substantial premiums in Baltic and North Sea ECAs against standard VLSFO. Pricing stratifies across three tiers: benchmark Rotterdam barge quotes for volume contracts, port-specific delivered premiums for Mediterranean transshipment hubs, and distressed off-spec material discounted at peripheral terminals. Cost compression in the standard VLSFO tier intensifies as Russian crude substitution patterns destabilize residual fuel oil feedstock economics. Container lines with annual offtake agreements exhibit lowest price sensitivity, while tramp operators and fishing fleets on spot procurement face acute margin pressure from volatility.
Supply Chain Analysis
Port congestion at Singapore and Houston delays fuel oil cargo rotations, lengthening inventory cycles for European blenders dependent on Atlantic Basin feedstock arrivals. Supply concentrates in the Netherlands, Belgium, and Germany, with ARA hub terminals processing the majority of northwest European volumes. Raw material dependencies rest on Urals crude substitution streams, West African distillate cargoes, and biofuel component imports from Southeast Asia. Single-point vulnerability at Rotterdam-Amsterdam-Antwerp infrastructure exposes the regional system to weather-related barge disruptions or coordinated terminal maintenance. Distribution runs through integrated supplier direct sales for container lines, wholesale parcel traders for mid-size operators, and retail coastal depots for fragmented fishing and tugboat demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FuelEU Maritime's dual-certification burden fragments procurement into separate fossil and renewable fuel streams, creating service niches for specialized blenders and carbon accounting providers that incumbent commodity merchants under-serve.
For Market Incumbents: Shield integrated refining margins by securing long-term biofuel feedstock offtakes before hydrotreated vegetable oil supply tightens. Anchor market position through cryogenic engineering partnerships at northwest European ports, as LNG bunkering infrastructure gaps expose incumbents to specialized traders capturing dual-fuel vessel conversions. Certification investment in FuelEU carbon intensity verification capabilities represents the critical defensive lever against independent traders bundling compliance services. For New Entrants and Emerging Players: Carbon accounting and well-to-wake verification services present the most penetrable white-space opportunity, as FuelEU Maritime mandates outpace incumbent supplier capabilities. Target French Atlantic port retail networks where TotalEnergies' biofuel blending investments have not yet saturated fishing and short-sea fleet coverage. A go-to-market angle bundling ISO 8217 quality testing with FuelEU documentation offers immediate differentiation against commodity traders lacking technical service depth. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors independent blenders with secured biofuel component supply and established Mediterranean transshipment relationships over pure-play fossil fuel traders facing structural demand erosion. Long-term viability across the analysis window hinges on alternative fuel logistics capabilities rather than residual fuel oil storage assets. The signal to watch is charter party renegotiation frequency, as Greek and German liner operators accelerate contracting evolution toward carbon intensity-linked fuel clauses.| Strategic Initiative | Industry Significance |
|---|---|
| Biofuel Blending Capacity Expansion | Captures FuelEU Maritime renewable fuel mandates at French Atlantic terminals. |
| LNG Infrastructure Partnership | Secures cryogenic bunkering access for dual-fuel vessel conversions at Rotterdam. |
| Carbon Accounting Service Launch | Monetizes FuelEU well-to-wake reporting requirements through verification bundling. |
| Backward Integration into Biofeedstock | Locks hydrotreated vegetable oil supply before competition intensifies. |
| Methanol Supply Chain Pilot | Positions at first-mover terminals for Maersk's green methanol vessel orders. |
Research Methodology
Desk research of customs trade data, port authority throughput statistics, and EU regulatory filings preceded structured interviews with marine fuel procurement managers, terminal operations directors, and shipbroker chartering specialists. Primary fieldwork captured bunker procurement contract structures, FuelEU Maritime compliance preparation timelines, and alternative fuel infrastructure investment plans. Secondary validation drew from ECHA REACH documentation, ISO 8217 certification registries, and liner operator sustainability disclosures. Bottom-up vessel call data triangulated against top-down refinery output estimates anchored volume and value projections.
Variance decomposition across fuel type, application segment, distribution channel, and end-user category informed the analytical framework throughout the projection horizon. Segmentation dimensions modeled include sulphur content tier, vessel propulsion architecture, port call frequency band, and regional regulatory cluster. CAGRs derived from trend extrapolation of bunkering volumes at Rotterdam, Antwerp, Barcelona, and Hamburg terminals, calibrated against container shipping fleet expansion schedules and ETS carbon price sensitivity assumptions.
Material uncertainties — Russian crude substitution patterns, biofuel component import cost volatility, and EU ETS marine fuel coverage extension — sit outside the modeled envelope. Forecasts reflect assumptions regarding FuelEU Maritime enforcement consistency and LNG infrastructure deployment timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Middle-East and Africa Defense Aircraft Aviation Fuel Market
Fuels
India Retail Fuel Market
Fuels
Germany Bunker Fuel Market
Fuels
Underground Coal Gasification Market
Fuels
Gas Pooling Mechanism Market
Fuels
Wood Charcoal Market
Fuels
Coal to Liquid Fuel (CTL) Market
Fuels
Global Turbine Oil Market
Fuels
Aviation Fuel Additives Market
Fuels
Australia Coal Market
Fuels
Japan Bunker Fuel Market
Fuels
Renewable Heating Fuels Market
Fuels
India City Gas Distribution (CGD) Market
Fuels
Europe Coal Market
Fuels
White Coal Market
Fuels
LPG Cylinder Manufacturing Market