
 Global Steam Coal Market | 2026-2036
Global Steam Coal Market Size, Share, and Industry Trends Forecast 2026-2036
Global Steam Coal Market Outlook
Long-term offtake bundling with freight and carbon-offset packages is realigning procurement patterns for Atlantic Basin buyers. Glencore PLC leverages its integrated mining-trading footprint to sustain contract flexibility across Australian and Colombian assets. Trafigura Group Pte Ltd competes through logistics control, anchoring freight optimization as a margin driver in spot and term volumes.
Steam coal denotes carbonaceous sedimentary rock with calorific values typically ranging from 4,500 to 6,500 kcal/kg, combusted primarily to generate electricity or industrial process heat through pulverized fuel boilers. Thermal coal dominates seaborne trade volumes, while bituminous grades command premium pricing in Asian power markets due to higher energy density and lower moisture content; lignite remains concentrated in domestic German and Polish power generation where mine-mouth economics offset transport penalties. Cement production and steel manufacturing applications are diverging as alternative fuels and direct reduction technologies displace coal in European industrial clusters.
The EU Green Deal and F-Gas Regulation constrain high-carbon fuel imports into European ports, while China's MEE enforces domestic mine safety and output quotas that ripple through Pacific Basin pricing. EPA mercury and air toxics standards in the United States continue to accelerate coal plant retirements, reshaping export orientation for Powder River Basin producers. Stakeholders must monitor policy divergence between Asian growth markets and OECD decarbonization timelines to calibrate asset exposure and contracting duration.
Market Dynamics
Power utilities in Southeast Asia are extending offtake contracts despite OECD decarbonization timelines, creating a bifurcated demand structure where Pacific Basin procurement volumes expand while Atlantic Basin buyers retreat under emissions compliance pressure.
Growth Catalysts
- Indonesian Mine-Mouth Economics:Kalimantan producers leverage low stripping ratios and riverine transport to deliver sub-$50/tonne landed costs into Vietnamese and Philippine power plants.
- EU Carbon Border Adjustment Mechanism:The phased CBAM implementation shields domestic EU coal burners from import competition, preserving residual baseload demand in Poland and Bulgaria through 2030.
- Ultra-Supercritical Boiler Deployment:Efficiency gains above 45% LHV enable Indian and Chinese utilities to justify new coal capacity while meeting intensity targets under Paris Agreement NDCs.
Market Restraints
- Indonesian Export Licensing Volatility:Domestic Market Obligation quotas and irregular ministry approvals disrupt loading schedules at Samarinda and Banjarmasin terminals.
- EU Green Deal Compliance Costs:F-Gas Regulation restrictions and ETS carbon pricing above €80/tonne render imported steam coal uncompetitive against gas and renewables in German and Dutch power markets.
- Biomass Co-Firing Substitution:Drax and RWE plants in the United Kingdom displace thermal coal with pelletized wood fuel, eroding traditional Atlantic Basin offtake volumes.
Strategic Opportunities
- Vietnamese Power Development Plan VIII:Grid reliability mandates through 2030 sustain coal procurement despite renewable capacity additions, offering contract visibility for Australian 5,500 kcal/kg suppliers.
- Carbon Capture Retrofit Integration:Post-combustion amine scrubbing and oxyfuel combustion retrofits on existing Asian supercritical units create premium pricing tiers for low-ash, low-sulfur bituminous grades.
- Blended Fuel Arbitrage:Indonesian sub-bituminous and Russian high-ash coals mixed at transshipment hubs in Malaysia and the Philippines optimize calorific value for specific boiler configurations.
Industry Challenges
- Geotechnical Engineering Talent Scarcity:Open-pit slope stability and groundwater management expertise concentrates with aging Australian and South African workforces, constraining Indonesian brownfield expansion.
- ESG Due Diligence Complexity:Traceability requirements from the OECD Due Diligence Guidance and downstream utility procurement policies extend certification timelines for Kalimantan suppliers.
- Freight Rate Volatility Absorption:Capesize and Panamax charter markets swing 40% intra-quarter, compressing trader margins on unhedged cargo positions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Steam Coal Market |
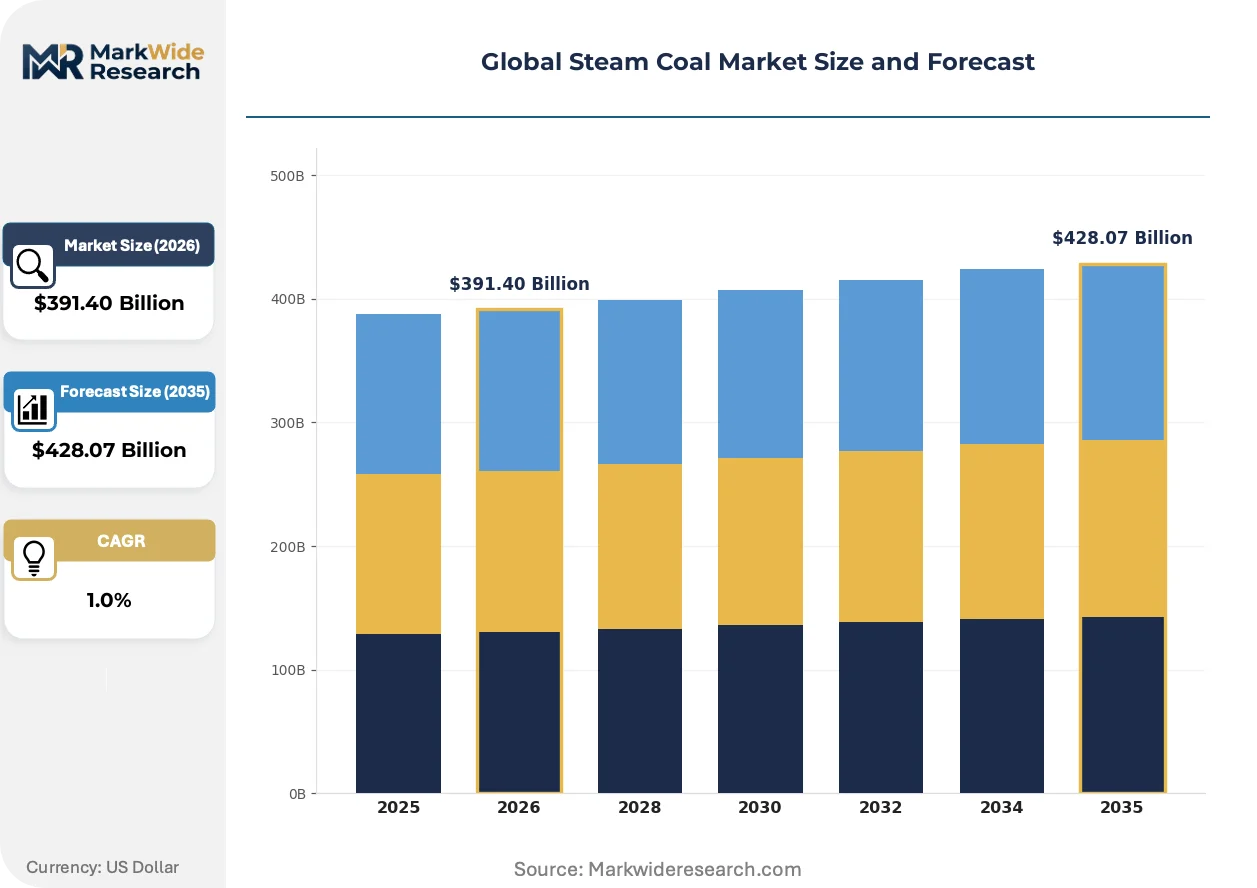
| Market Size in 2026 | $391.40 Billion |
| Market Size in 2035 | $428.07 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Coal, Bituminous Coal, Sub-bituminous Coal, Lignite Application: Electricity Generation, Industrial Heating, Cement Production, Steel Manufacturing End User: Power Plants, Manufacturing Facilities, Bricks Kilns, Chemical Plants Distribution Channel: Direct Sales, Distributors, Online Sales, Others |
| Companies Covered | Glencore PLC, Vitol Holding BV, Trafigura Group Pte Ltd, Mercuria Energy Group, China Shenhua Energy Company Limited, China Coal Energy Company Limited, Borneo Coal Trading, Mitsubishi Corporation, Centennial Coal Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Steam Coal Market Strategic Shifts
Digital freight platforms and emissions monitoring technologies are compressing contracting cycles and forcing price transparency into historically opaque physical coal markets. These tools redistribute bargaining power between miners, traders, and utility buyers.
Blockchain-based cargo documentation is decentralizing title transfer and quality verification processes that previously required bank letters of credit and independent surveyor presence at load ports. Indonesian and Australian miners adopt distributed ledger systems for bills of lading, allowing Vietnamese and Thai utilities to accelerate payment release and reduce working capital requirements. Physical settlement risk disperses across multiple verification nodes rather than concentrating with nominated inspection agencies.
The EU F-Gas Regulation and complementary national coal phase-out statutes in Germany, France, and Italy are accelerating asset stranding for import-dependent terminals. Rotterdam and Amsterdam storage operators pivot to biomass and hydrogen handling infrastructure, while Polish and Czech utilities secure derogations to maintain coal burn through 2034. Contracting duration compresses as buyers refuse multi-year commitments beyond regulatory cliff dates.
Utility procurement desks are consolidating supplier panels and demanding fixed-volume, variable-pricing structures indexed to API2 and Newcastle benchmarks plus carbon offset premiums. Spot market liquidity concentrates in screen-traded instruments, displacing traditional brokered voice markets for standard 6,000 kcal/kg cargoes. This behavioral shift is most visible in Japanese and South Korean power utilities, where trading houses face margin compression on intermediary services.
Global Steam Coal Market Segmentation
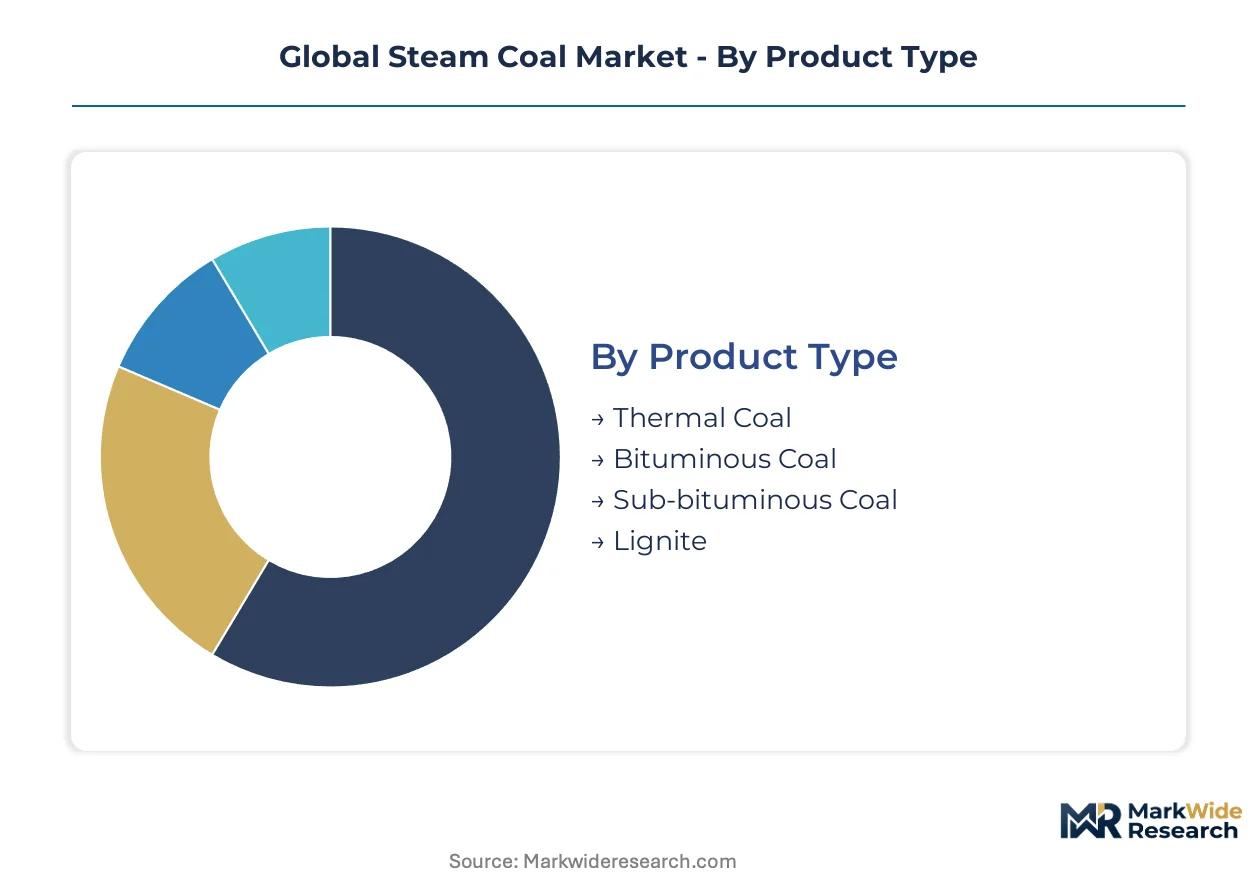
Segmentation in steam coal markets tracks how calorific specifications, combustion technologies, and procurement channels fragment pricing power across supplier tiers. Understanding these divisions reveals where contract premiums concentrate and which buyer segments sustain volume through energy transition pressures.
Product Type:
Supply concentration in Indonesian Kalimantan and Australian Queensland basins favors specific rank categories with favorable stripping ratios and port access.
- Thermal Coal:Standard-grade material with calorific values between 5,000 and 6,000 kcal/kg dominates seaborne contract volumes. Vietnamese and Philippine power plants under Power Development Plan VIII procurement schedules anchor residual demand growth for this specification.
- Bituminous Coal:Higher-rank deposits with energy density above 6,000 kcal/kg and low sulfur content command premium pricing in Japanese and South Korean ultra-supercritical boiler installations. Indian utilities justify import premiums for this grade to meet intensity targets under Paris Agreement NDCs.
- Sub-bituminous Coal:Indonesian producers leverage sub-$50/tonne mine-mouth economics for this lower-rank output.
- Lignite:Domestic German and Polish generation clusters consume this high-moisture grade where transport penalties are eliminated.
Today's leader: Bituminous Coal. Tomorrow's challenger: Sub-bituminous Coal.
Application:
Cost tier differentiation separates baseload power contracts from industrial spot purchases with divergent quality tolerances and carbon offset requirements.
- Electricity Generation:Pulverized fuel boilers in Southeast Asian grids consume the majority of internationally traded volumes. Chinese MEE output quotas and domestic mine safety enforcement ripple through pricing for this application segment.
- Industrial Heating:Process steam for paper, textiles, and food processing sustains niche import demand in economies with limited gas infrastructure.
- Cement Production:Clinker kilns in Vietnam and Indonesia blend coal with alternative fuels as EU Green Deal compliance pressures reshape technology choices in European plants.
- Steel Manufacturing:Pulverized coal injection for blast furnace operations competes with direct reduction technology adoption in OECD clusters.
Electricity Generation retains volume dominance. Cement Production faces the steepest substitution threat from biomass and waste fuels.
End User:
Customer type fragmentation splits procurement between integrated utilities with term contracting power and fragmented industrial buyers exposed to spot volatility.
- Power Plants:State-owned Vietnamese and Thai utilities consolidate supplier panels and demand fixed-volume, variable-pricing structures indexed to API2 and Newcastle benchmarks.
- Manufacturing Facilities:Cement and paper producers with captive power needs purchase smaller parcel sizes through trading house intermediaries.
- Bricks Kilns:Artisanal and small-scale producers in South Asia source through informal distribution networks with limited quality verification.
- Chemical Plants:Ammonia and methanol producers require specific ash and sulfur specifications for syngas production.
Power Plants dictate contract structures. Chemical Plants represent the most quality-sensitive niche with premium tolerance.
Distribution Channel:
Volume concentration in Capesize and Panamax charter markets shapes how logistics control distributes margin capture between miners and intermediaries.
- Direct Sales:Australian and Indonesian miners with integrated trading desks like Glencore PLC ship cargoes directly to Japanese and South Korean utility buyers, compressing intermediary margins.
- Distributors:Regional trading houses in Singapore and Geneva warehouse inventory and manage freight optimization for smaller industrial offtakers.
- Online Sales:Digital freight platforms and screen-traded instruments displace traditional brokered voice markets for standard 6,000 kcal/kg cargoes.
- Others:Blockchain-based cargo documentation and distributed ledger systems for bills of lading accelerate payment release for Vietnamese utilities.
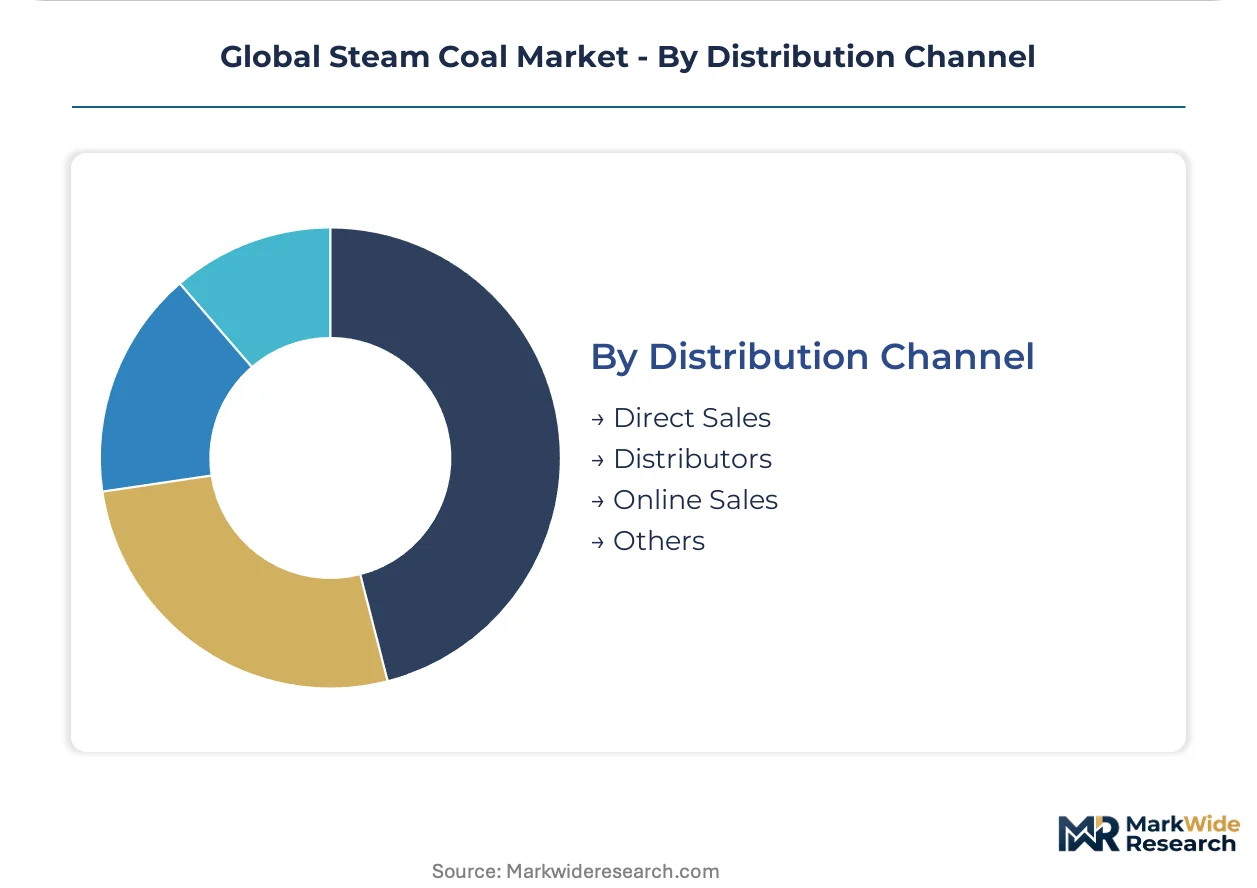
Direct Sales capture margin from relationship concentration. Online Sales are gaining share fastest through transparency pressures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The steam coal trade originated in British industrial ports during the nineteenth century before migrating to American and Australian export terminals. Today, procurement patterns fragment between Asian growth markets sustaining volume and European terminals pivoting to alternative fuels.
China
Power utilities in Shandong and Guangdong provinces sustain import demand for Australian bituminous grades despite domestic production dominance. The Ministry of Ecology and Environment enforces mine safety quotas and output ceilings that tighten seaborne price benchmarks. Tangshan steel clusters and Rizhao power plants anchor northern procurement volumes through state-backed trading desks.
Indonesia
Kalimantan producers leverage riverine transport and low stripping ratios to deliver sub-$50/tonne landed costs into Vietnamese and Philippine markets. Domestic Market Obligation quotas and irregular ministry approvals disrupt loading schedules at Samarinda and Banjarmasin terminals. The East Kalimantan mining corridor concentrates brownfield expansion where geotechnical expertise constrains slope stability programs.
India
Ultra-supercritical boiler deployment in Gujarat and Maharashtra justifies import premiums for 6,000 kcal/kg bituminous coal under Paris Agreement NDC intensity targets. The Central Electricity Authority monitors grid reliability mandates that sustain baseload coal burn through 2030. Mundra and Dahej port terminals anchor western import infrastructure for Adani and Tata power assets.
Germany
Residual coal demand concentrates in Lusatian and Rhenish lignite belts where mine-mouth economics offset transport penalties. The EU Green Deal and F-Gas Regulation accelerate asset stranding for import-dependent Hamburg and Rostock terminals. Berlin-Brandenburg utilities secure derogations to maintain coal burn through 2034 while Rotterdam storage operators pivot to biomass handling.
Vietnam
Power Development Plan VIII sustains procurement visibility for Australian 5,500 kcal/kg suppliers through grid reliability mandates to 2030. State-owned EVN and PVN consolidate supplier panels and demand fixed-volume, variable-pricing structures indexed to Newcastle benchmarks. The Van Phong and Duyen Hai power centers anchor southern demand clusters where blended fuel arbitrage optimizes boiler configurations.
Global Steam Coal Market Competitive Environment
Premium-margin players sit above commodity-margin players across logistics control and contract flexibility dimensions. The vendor base concentrates around integrated mining-trading conglomerates, pure-play commodity traders, and state-backed national champions. Three archetypes dominate: asset-heavy miners with captive export terminals, trading houses optimizing freight and blending arbitrage, and utility-aligned procurement desks with term contracting power. Competitive moves center on backward integration into port infrastructure and portfolio diversification into carbon-offset bundled offerings.
Within the integrated mining-trading tier, Glencore PLC and Trafigura Group Pte Ltd exemplify divergent strategic positions. Glencore leverages Australian and Colombian asset footprints to sustain contract flexibility across Pacific and Atlantic Basin buyers. Trafigura competes through logistics control, anchoring freight optimization as a margin driver in spot and term volumes. Among state-backed Asian producers, China Shenhua Energy Company Limited occupies a position representing captive mine-to-power integration with limited seaborne export orientation. Vitol Holding BV and Mercuria Energy Group sit within the pure-play commodity trader archetype, absorbing Capesize charter volatility to capture blending arbitrage at Malaysian transshipment hubs.
| Leading Market Players |
|---|
| Glencore PLC |
| Vitol Holding BV |
| Trafigura Group Pte Ltd |
| Mercuria Energy Group |
| China Shenhua Energy Company Limited |
| China Coal Energy Company Limited |
| Borneo Coal Trading |
| Mitsubishi Corporation |
| Centennial Coal Company Limited |
| Others |
Value Chain & Pricing Dynamics
Ultra-supercritical boiler deployment across Indian and Chinese power fleets compresses delivered coal costs per megawatt-hour while concentrating procurement power among utilities with technical specifications demanding 6,000 kcal/kg bituminous grades. This technology shift simultaneously elevates premium-tier pricing for high-rank Australian and Indonesian coals and marginalizes sub-5,500 kcal/kg suppliers lacking carbon-offset bundling capabilities.
Pricing Analysis
Contract-based long-term offtake with API2 and Newcastle benchmark indexing dominates utility procurement, with price differentiation driven by calorific grade certification and freight optimization bundles. Premium-mid-economy pricing separates bituminous high-rank material from sub-bituminous Indonesian grades and lignite domestic burn. Pricing pressure stems from EU ETS carbon pricing above €80/tonne rendering imported steam coal uncompetitive against gas and renewables in German and Dutch markets. Industrial cement and paper producers exhibit highest price sensitivity through smaller parcel spot purchases, while Japanese and South Korean ultra-supercritical operators tolerate import premiums for quality consistency.
Supply Chain Analysis
Refurbishment and blending flows at Malaysian and Philippine transshipment hubs recover value from lower-grade Indonesian and Russian coals through quality arbitrage before final utility delivery. Geographic supply concentrates in Indonesian Kalimantan, Australian Queensland, and Russian Far East basins. Raw material dependencies center on diesel fuel for open-pit extraction, ammonium nitrate explosives, and steel for heavy mobile equipment. Single-source vulnerability runs through Indonesian Domestic Market Obligation quotas that disrupt loading schedules at Samarinda and Banjarmasin terminals. Distribution runs through Capesize and Panamax bulk charter markets with integrated mining-trading desks capturing margin from direct utility relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in steam coal markets rests on freight and carbon-offset bundling premiums that utilities now demand as standard contract terms, compressing pure-play trader margins while rewarding integrated asset owners.
For Market Incumbents: Hedge contract exposure through portfolio diversification across Australian high-rank and Indonesian sub-bituminous assets to offset grade-specific demand swings. Secure backward integration into port infrastructure at Van Phong and Duyen Hai terminals to capture logistics margin from Vietnamese Power Development Plan VIII procurement. Carbon capture retrofit partnerships with Indian and Chinese utilities represent the priority defensive lever against biomass substitution and direct reduction technology displacement in OECD steel clusters. For New Entrants and Emerging Players: Artisanal brick kiln operators in South Asia represent an underserved buyer archetype with informal distribution networks and limited quality verification. Target this segment through mobile screening and blending units that deliver calibrated parcel sizes without fixed infrastructure investment. Philippine cement producers with captive power needs offer a secondary white-space target where trading house intermediaries currently extract excess margin. A go-to-market angle anchored on blockchain-based cargo documentation accelerates payment release and reduces working capital requirements for credit-constrained buyers. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play commodity traders absorbing Capesize charter volatility without captive mine assets to anchor margin. Long-term viability across the analysis window favors integrated mining-trading conglomerates with Pacific Basin export terminal control and carbon-offset bundling capabilities. Acquisition targets should concentrate on Indonesian brownfield assets with low stripping ratios and riverine transport access. The signal to watch is Vietnamese and Thai utility consolidation of supplier panels into fixed-volume, variable-pricing structures that compress intermediary count.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit Partnership | Post-combustion amine scrubbing integration secures premium pricing tiers for low-sulfur bituminous grades in Indian ultra-supercritical installations. |
| Freight Optimization Platform Deployment | Digital charter market access compresses Capesize rate volatility absorption and redistributes margin from traditional brokered voice markets. |
| Backward Integration into Port Infrastructure | Captive terminal control at Van Phong and Duyen Hai anchors logistics margin capture from Vietnamese Power Development Plan VIII procurement schedules. |
| Blockchain Cargo Documentation System | Distributed ledger bills of lading accelerate payment release for Vietnamese and Thai utilities with working capital constraints. |
| Blended Fuel Arbitrage Hub Establishment | Malaysian and Philippine transshipment blending optimizes calorific value for specific boiler configurations across Southeast Asian power fleets. |
Study Parameters
Direct dialogue with utility procurement officers, mining operations managers, freight brokers at Singapore and Geneva trading hubs, and geotechnical engineering consultants grounded qualitative findings in operational reality. Secondary validation drew from customs and trade data, IEA coal market reports, EIA international energy statistics, and SEC filings from integrated mining-trading conglomerates. Bottom-up volume modeling across calorific grade tiers and top-down macroeconomic demand projections were triangulated to constrain forecast variance.
Bottom-up modeling tracked mine-level output capacity, stripping ratios, and port loading rates across Indonesian Kalimantan and Australian Queensland basins. Top-down demand projections incorporated grid reliability mandates under Vietnamese Power Development Plan VIII, Chinese MEE output quotas, and EU Green Deal compliance timelines affecting import-dependent terminals. Segmentation dimensions spanned calorific grade tier, combustion technology class, end-use application, and distribution channel structure. CAGRs were derived from regression analysis of historical trade flows against policy scenario assumptions without specific year anchoring.
Inputs from utility procurement databases, mining ministry production statistics, and charter market rate indices were available through the study window; gaps in informal artisanal mining output and unreported blending hub throughput introduce uncertainty bands around sub-bituminous supply estimates. Forecasts reflect documented assumptions regarding policy implementation timelines and technology adoption curves. Practitioners should monitor Indonesian Domestic Market Obligation quota announcements, EU CBAM phase-in schedules, and Vietnamese renewable capacity commissioning rates for early signals of demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Hydrogen Cylinder Market
Fuels
Multifuel Gas Turbine Market
Fuels
South America Aviation Fuel Market
Fuels
Bituminous Coal Market
Fuels
High-Temperature Industrial Burner Market
Fuels
Carbonizers Market
Fuels
No.4 Fuel Oil Market
Fuels
Marine Fuel Optimization Market
Fuels
India Coal Market
Fuels
Global Methane Hydrate Market
Fuels
North America Bunker Fuel Market
Fuels
Composite Overwrapped Pressure Vessels (Copvs) Market
Fuels
Italy Chemical Logistics Market
Fuels
No.2 Diesel Fuel Market
Fuels
Aviation Fuel Additives Market
Fuels
Petroleum Fuel Dyes Sales Market