
 Europe Black and Wood Pellets Market | 2026-2036
Europe Black and Wood Pellets Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Black and Wood Pellets Market Foresight
The EU Green Deal is realigning capital deployment across the European pellet value chain by mandating stricter greenhouse gas savings thresholds for biomass installations. Drax Group plc leverages its port and storage infrastructure to anchor supply security for utility buyers in the United Kingdom and continental Europe. Stora Enso Oyj sustains integrated forest-products-to-energy operations that control feedstock quality from Nordic sawmills through to pellet production. Enviva Inc. competes through transatlantic sourcing flexibility, positioning its European trading arm to navigate feedstock cost volatility.
Europe black and wood pellets comprise compressed biomass cylinders—typically 6-8 mm in diameter and 10-40 mm in length—manufactured via mechanical densification or torrefaction at 200-300°C, serving as direct substitutes for coal in thermal power stations and heating systems. Black pellets, produced through torrefaction of woody biomass, offer enhanced hydrophobicity and grindability that permits seamless co-milling with coal in existing pulverized fuel boilers. The power generation segment dominates volume offtake as utilities retrofit coal plants under national phase-out schedules, while residential heating sustains premium pricing through certified ENplus quality tiers. Wood pellets from forest residues occupy the largest raw material share, though agricultural residues are gaining traction where sustainability certification requirements tighten.
EMA standards for solid biofuel quality, the EU Renewable Energy Directive sustainability criteria, and national building codes in Germany and France collectively determine product eligibility for subsidy schemes and carbon accounting. The F-Gas Regulation and national boiler emission limits in Sweden and Finland further filter which pellet grades qualify for public support programs. Stakeholders must monitor how the EU's upcoming carbon border adjustment mechanism recalibrates the cost advantage of domestic versus imported pellet supply.
Market Dynamics
Coal phase-out deadlines across Northern Europe are compressing procurement timelines for torrefied black pellets, forcing utilities to secure supply contracts before 2030 retrofit windows close. This regulatory pressure is restructuring the entire value chain from Nordic forest feedstocks to port storage infrastructure.
Growth Catalysts
- EU Green Deal sustainability thresholds:The revised Renewable Energy Directive mandates stricter greenhouse gas savings for biomass installations, redirecting capital toward certified pellet producers with verified supply chains.
- German district heating networks:Municipal utilities in Bavaria and Baden-Württemberg are accelerating boiler retrofits for pellet co-firing to meet national building code requirements.
- Torrefaction technology maturation:Commercial-scale torrefaction at 200-300°C now delivers hydrophobic black pellets with coal-equivalent grindability, enabling seamless integration into existing pulverized fuel systems.
Market Restraints
- Baltic Sea port congestion:Concentrated pellet export capacity through Latvian and Estonian terminals creates supply bottlenecks during winter heating demand peaks.
- Forest residue feedstock competition:Nordic sawmills prioritize particleboard and pulp contracts, squeezing pellet producers on raw material access and pricing.
- F-Gas Regulation compliance costs:Stringent emission limits for industrial boilers in Sweden and Finland disqualify lower-grade pellets from public subsidy schemes.
Strategic Opportunities
- Polish coal-dependent power sector:Utilities in Silesia and Małopolska face EU carbon border adjustment exposure, creating first-mover advantage for black pellet suppliers offering direct coal substitution.
- Agricultural residue valorization:Straw and miscanthus pelletization is converging with sustainability certification schemes in Denmark and the Netherlands where forest feedstock constraints tighten.
- Carbon border adjustment mechanism timing:The EU's phased CBAM implementation creates a pricing arbitrage window for domestic European pellet production against imported alternatives.
Industry Challenges
- ENplus certification backlog:Testing laboratory capacity constraints in Germany and Austria delay quality tier verification, blocking residential heating market access for new producers.
- Torrefaction equipment commissioning:First-of-a-kind commercial installations require 18-24 month ramp periods, straining engineering talent pools and project finance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Black and Wood Pellets Market |
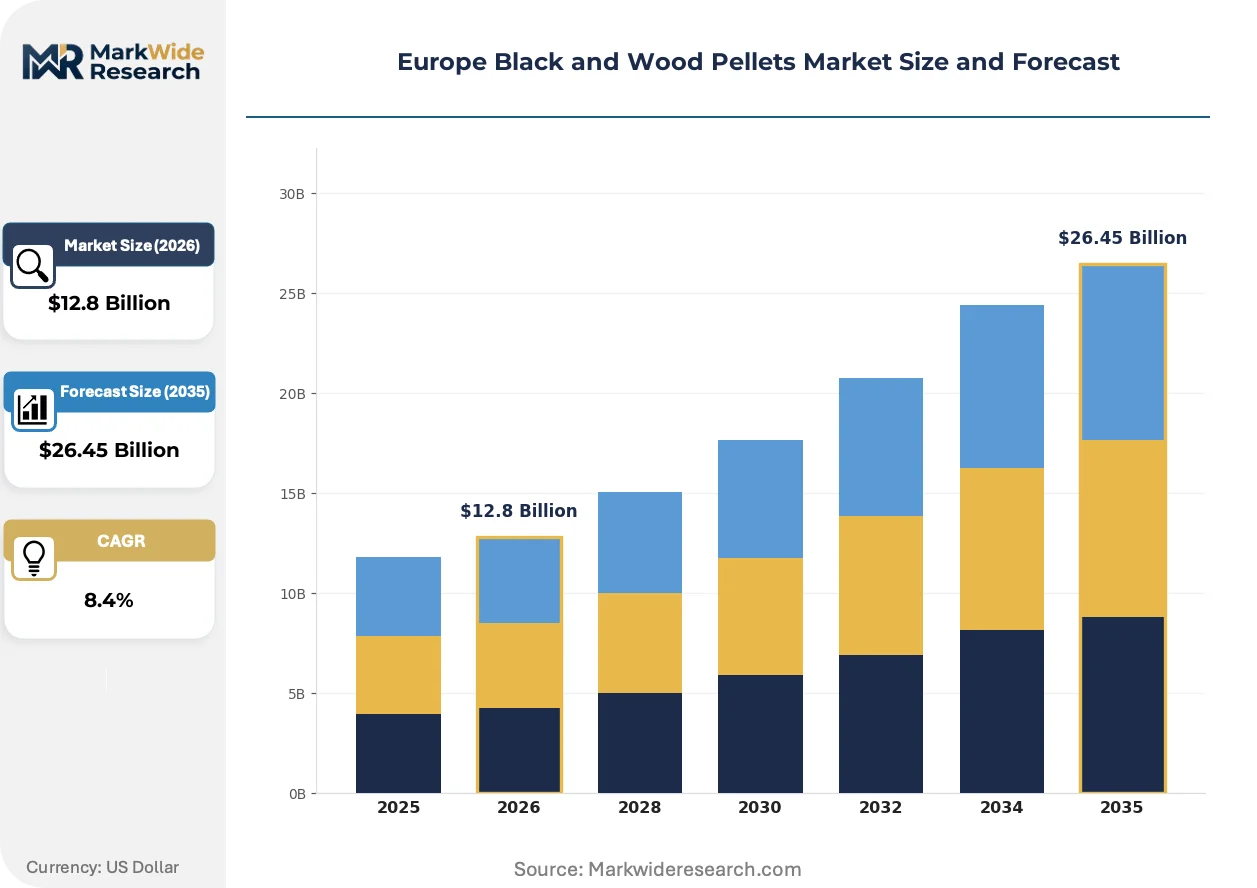
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.45 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Black Pellets, Wood Pellets, Durable Pellets, Standard Pellets End Use Industry: Power Generation, Residential Heating, Industrial Heating, Commercial Applications Raw Material: Wood Residues, Agricultural Residues, Biomass, Recycled Material Distribution Channel: Direct Sales, Wholesalers, Retailers, Online Sales |
| Companies Covered | AS Graanul Invest, Stora Enso Oyj, Drax Group plc, Enviva Inc., Arbaflame, Scandbio AB, PIVETEAUBOIS, BLACKWOOD TECHNOLOGY B.V., Vyborgskaya Cellulose LLC, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Black and Wood Pellets Market Shifts & Advancements
Digital supply chain traceability is converging with sustainability certification requirements, reshaping how European utilities verify feedstock origins. This technological shift is compressing procurement cycles and elevating quality premiums.
Flash torrefaction reactors are converging with conventional pelletization lines to produce black pellets with uniform hydrophobicity. German engineering firms are deploying these integrated systems for utilities in the Rhineland retrofitting coal plants. The technology is converging with existing port infrastructure to reduce storage degradation losses.
The EU F-Gas Regulation is tightening emission benchmarks for biomass combustion equipment. Industrial boiler manufacturers in Sweden must now certify systems below 50 mg NOx per megajoule to qualify for public support. This regulatory compression is favoring premium black pellet grades with predictable combustion profiles over standard wood pellets.
Utility procurement teams are consolidating supplier relationships around long-term offtake agreements with embedded sustainability verification. District heating cooperatives in Finland now require blockchain-tracked feedstock documentation. This behavioral shift is marginalizing spot-market traders and elevating integrated producers with captive forest assets.
Europe Black and Wood Pellets Market Segmentation
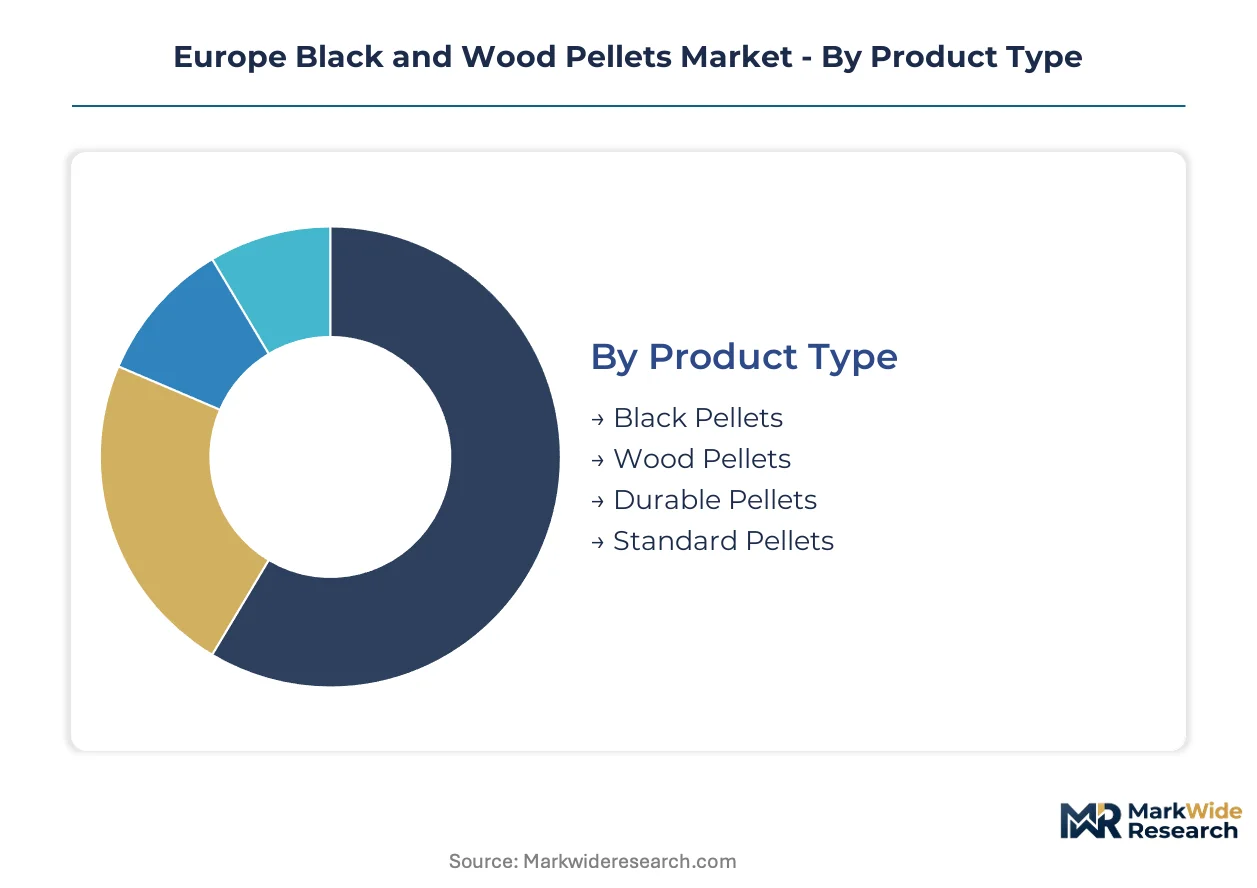
Pellet buyers across Europe calibrate procurement around combustion system compatibility, sustainability certification tiers, and feedstock traceability requirements. Segment boundaries blur where torrefied black pellets substitute directly for coal in retrofitted utilities while standard wood pellets serve distinct residential heating protocols.
Product Type:
Customization intensity spans torrefaction-derived hydrophobic grades at one extreme to commodity-standardized residential fuels at the other, with grindability specifications determining boiler retrofit economics.
- Black Pellets:Torrefied biomass processed at 200-300°C delivers coal-equivalent grindability and moisture resistance, enabling seamless co-milling in existing pulverized fuel systems without capital-intensive boiler modifications. German utilities in the Rhineland and Polish power operators in Silesia are contracting supply ahead of national coal phase-out deadlines, prioritizing black pellets for their 18-24 month commissioning windows.
- Wood Pellets:Mechanically densified sawmill residues and forest chips compressed to 6-8mm diameter serve ENplus-certified residential heating systems and smaller-scale industrial boilers. Swedish district heating networks and Finnish municipal utilities anchor volume demand, though Baltic Sea port congestion strains supply security during winter peaks.
- Durable Pellets:Enhanced-density formulations with reduced fines content target automated bulk-handling systems in commercial and light-industrial installations.
- Standard Pellets:Baseline-grade products without premium durability or certification tiers serve price-sensitive residential markets in Eastern Europe.
Most installed capacity flows through Wood Pellets. Expansion is steepest in Black Pellets.
End Use Industry:
Application scale drives cost structure, with utility-scale procurement commanding volume discounts against premium-certified residential tiers.
- Power Generation:Retrofitted coal plants across Northern Europe constitute the largest volume sink, with Drax Group and similar operators securing long-term offtake agreements tied to EU Green Deal sustainability verification. Torrefaction compatibility eliminates the capital barrier of dedicated biomass boiler installations.
- Residential Heating:ENplus A1 and A2 certification tiers command 15-25% price premiums in Germany, Austria, and France where building codes mandate renewable heat shares. Bavarian and Baden-Württemberg municipalities are accelerating boiler retrofits under national efficiency regulations.
- Industrial Heating:Process heat applications in pulp and paper, food processing, and chemical sectors favor medium-grade pellets with predictable combustion profiles over residential certification premiums.
- Commercial Applications:Hotels, hospitals, and institutional buildings with automated feed systems require consistent pellet geometry and low ash content to minimize maintenance downtime.
Power Generation absorbs the largest volume flows. Residential Heating captures the highest margin per ton.
Raw Material:
Feedstock provenance determines eligibility for EU Renewable Energy Directive subsidies, with sustainability criteria tightening fastest for forest-sourced materials.
- Wood Residues:Sawmill chips, bark, and forest thinning dominate Nordic supply chains controlled by integrated forest-products groups. Stora Enso's captive sawmill network exemplifies upstream quality control from feedstock through finished pellet.
- Agricultural Residues:Straw and miscanthus pelletization is gaining traction in Denmark and the Netherlands where forest residue competition intensifies and sustainability schemes incentivize alternative feedstocks.
- Biomass:Purpose-grown energy crops including short-rotation coppice face land-use competition constraints in densely populated European regions.
- Recycled Material:Post-consumer wood waste streams require extensive contamination screening to meet industrial boiler emission standards under the EU F-Gas Regulation.
Wood Residues supply the majority of current production. Agricultural Residues are climbing the fastest as certification schemes diversify.
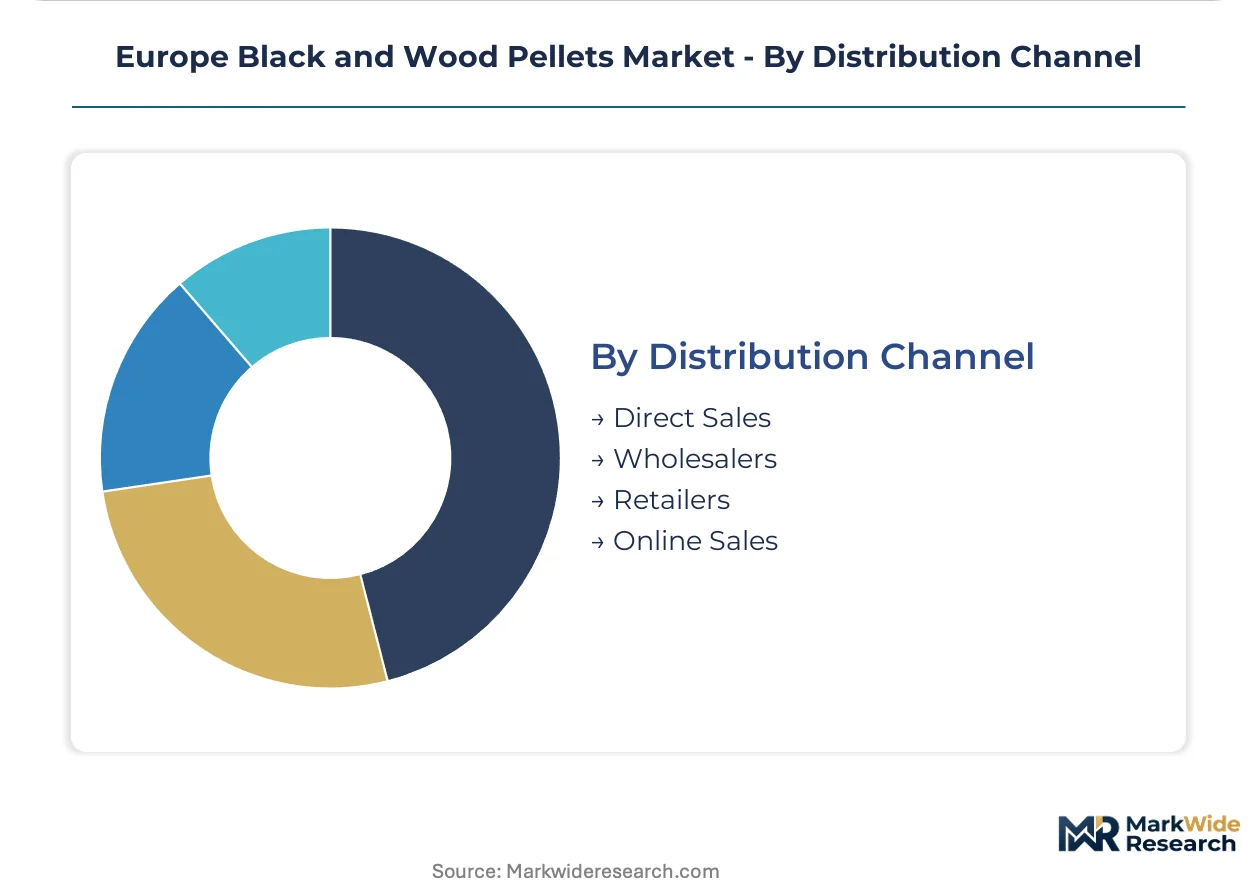
Distribution Channel:
Channel selection reflects buyer scale and inventory risk tolerance, with direct contracting preferred by utilities and fragmented retail serving seasonal residential demand.
- Direct Sales:Long-term offtake agreements between producers and utility buyers embed sustainability verification and port storage commitments, compressing spot market exposure.
- Wholesalers:Regional distributors aggregate supply from multiple Baltic and Nordic producers for delivery to heating oil cooperatives and municipal procurement pools.
- Retailers:Agricultural supply stores and building merchants serve bagged-pellet demand from rural residential customers with seasonal purchasing patterns.
- Online Sales:Digital platforms are emerging for small-lot certified pellet procurement, though logistics complexity limits penetration beyond urban fringe markets.
Direct Sales channels move the largest tonnages. Online Sales are expanding most quickly from a negligible base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled biomass procurement specialists cluster in Nordic port cities and German industrial corridors, anchoring Europe's pellet trade infrastructure.
Germany
Municipal utilities in Bavaria and Baden-Württemberg are retrofitting district heating boilers for pellet co-firing under national building code requirements. The EU Green Deal's greenhouse gas savings thresholds redirect capital toward certified producers. The Rhineland industrial cluster hosts utilities contracting black pellet supply ahead of coal phase-out deadlines.
Sweden
District heating cooperatives in Stockholm and Malmö mandate blockchain-tracked feedstock documentation for procurement contracts. The F-Gas Regulation imposes 50 mg NOx per megajoule emission limits on industrial boilers, filtering eligible pellet grades. Nordic sawmill networks around Växjö control upstream feedstock quality through integrated forest-products operations.
Finland
Municipal utilities anchor volume demand for ENplus-certified wood pellets in Helsinki and Tampere heating networks. National boiler emission standards under the EU F-Gas Regulation disqualify lower-grade products from subsidy schemes. The Lahti region concentrates torrefaction technology development for utility-scale black pellet production.
Poland
Power operators in Silesia and Małopolska face EU carbon border adjustment exposure, accelerating interest in direct coal substitution. The EU Green Deal's sustainability criteria tighten eligibility for biomass installations receiving public support. Katowice-based utilities are evaluating black pellet supply contracts to manage retrofit timelines.
United Kingdom
Drax Group plc leverages port and storage infrastructure to anchor supply security for utility buyers across England and Scotland. The EU Green Deal's revised Renewable Energy Directive influences sustainability verification standards for imported supply. Yorkshire's converted coal plants constitute the largest single demand concentration for torrefied black pellets.
Europe Black and Wood Pellets Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Europe's pellet value chain. The market structure favors integrated forest-products groups with captive sawmill networks over traders dependent on spot procurement. Three archetypes dominate: Nordic integrated producers controlling feedstock from forest to port, transatlantic trading houses managing import logistics, and engineering-led torrefaction technology developers. Capacity expansion and long-term offtake agreements with embedded sustainability verification represent the dominant competitive moves.
Among Nordic integrated producers, Stora Enso Oyj exemplifies the archetype of forest-products-to-energy operations with upstream quality control. Drax Group plc occupies a position anchoring supply security through port and storage infrastructure for utility buyers. Enviva Inc. represents transatlantic sourcing flexibility through its European trading arm. AS Graanul Invest sits within the Baltic production tier. These named entities illustrate how geographic positioning and supply chain configuration determine competitive access.
| Leading Market Players |
|---|
| AS Graanul Invest |
| Stora Enso Oyj |
| Drax Group plc |
| Enviva Inc. |
| Arbaflame |
| Scandbio AB |
| PIVETEAUBOIS |
| BLACKWOOD TECHNOLOGY B.V. |
| Vyborgskaya Cellulose LLC |
| Others |
Supply & Pricing Matrix
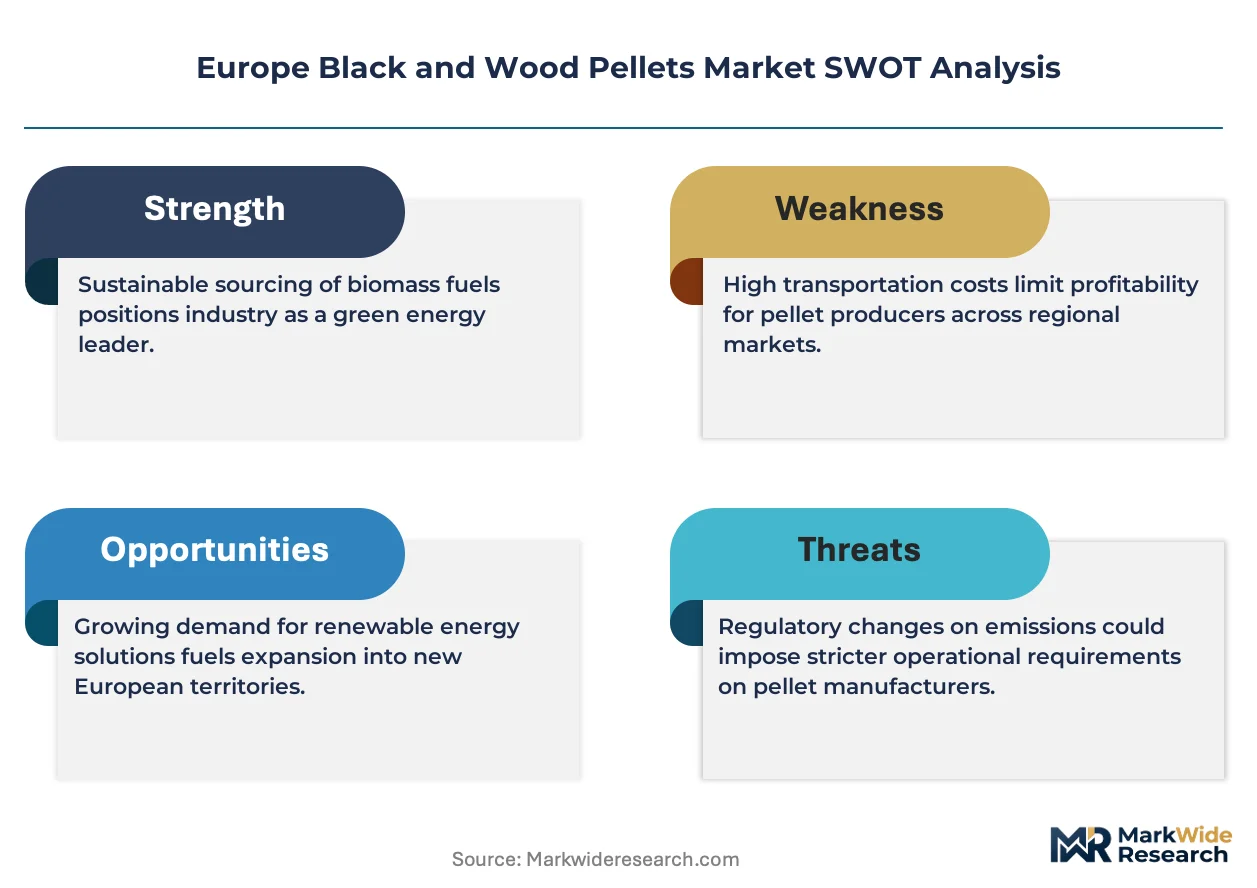
The EU Green Deal's greenhouse gas savings thresholds gate both qualified supply and premium-tier pricing access, compressing margins for uncertified producers while elevating ENplus A1 and torrefied black pellet grades that command 15-25% premiums in German and Austrian residential heating markets.
Pricing Analysis
Bundled long-term offtake agreements with embedded sustainability verification dominate utility procurement, while unbundled spot-market transactions serve seasonal residential demand. Pricing stratifies across ENplus certification tiers, torrefaction-derived grindability grades, and volume-scale discounts for district heating cooperatives. Cost compression in standard-grade wood pellets is intensifying because Baltic Sea port congestion strains supply security during winter peaks. Municipal utilities exhibit the lowest price sensitivity due to mandated renewable heat shares, whereas Eastern European residential buyers face acute price elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Latvian and Estonian terminal operators who control concentrated Baltic Sea export capacity for Nordic pellet production. Manufacturing draws from Swedish sawmill networks, Finnish forest thinning operations, and emerging Danish agricultural residue pelletization. Supply chain risk centers on winter logistics chokepoints that delay deliveries to German district heating networks. Distribution runs through direct producer-to-utility contracts for volume buyers and fragmented wholesaler-retail channels for residential bagged-pellet demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Black and Wood Pellets Market functions as a stable compounder anchored by irreversible coal phase-out deadlines that lock in decade-long demand visibility for certified biomass suppliers.
For Market Incumbents: Anticipate margin compression from agricultural residue pelletization entrants in Denmark and the Netherlands by deepening backward integration into Nordic sawmill networks. Prioritize ENplus certification investment to defend premium-tier positioning against emerging Polish torrefaction developers targeting Silesian utility retrofits.
For New Entrants and Emerging Players: Begin with agricultural residue valorization in straw-abundant Polish and Hungarian regions where forest feedstock competition remains limited. Target district heating cooperatives in Finland and Sweden with blockchain-tracked supply documentation as the most penetrable buyer segment. Pursue engineering partnerships with German flash torrefaction technology developers to bypass 18-24 month equipment commissioning barriers.
For Investors and Strategic Acquirers: Roll-up economics work for Baltic pellet producers with captive port access because terminal capacity constraints create persistent supply bottlenecks that reward consolidated ownership. Five-to-ten year viability hinges on EU carbon border adjustment mechanism implementation timing. Monitor Polish utility black pellet procurement announcements as the critical inflection signal for Silesian retrofit acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Drax Group-style port infrastructure commitments secure utility buyer loyalty across coal phase-out windows. |
| Backward Integration | Stora Enso's captive sawmill network exemplifies upstream quality control from forest residue through finished pellet. |
| Green Certification Program | ENplus A1 tier verification unlocks 15-25% price premiums in German building-code-mandated heating markets. |
| Technology Licensing | German flash torrefaction reactor deployment enables coal-equivalent grindability without dedicated biomass boiler capital. |
| Capacity Expansion | Lahti region torrefication development addresses utility-scale black pellet demand from Rhineland retrofit timelines. |
Research Methodology
Direct dialogue with utility procurement officers, district heating cooperative managers, pellet plant operations directors, and sustainability certification auditors combined with secondary validation from EU Renewable Energy Directive filings, EMA solid biofuel standards documentation, FERC-equivalent grid operator disclosures, and Nordic customs trade data. Bottom-up capacity assessments triangulated against top-down demand modeling from national coal phase-out schedules.
Segmented outputs across product type, end-use industry, raw material source, and distribution channel dimensions produced volume and value trajectories over the projection horizon. CAGRs derived from regression analysis against historical retrofit completion rates and sustainability criteria tightening schedules. Forecast inputs incorporated torrefaction technology commissioning timelines and ENplus certification laboratory capacity constraints.
Several conditions sit outside the modeled scope, including unannounced national biomass subsidy revisions and breakthrough agricultural residue preprocessing technologies. Forecasts reflect documented assumptions about EU carbon border adjustment mechanism implementation sequencing and F-Gas Regulation emission benchmark stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Fuel Oxygenate Market
Fuels
Oil Dispenser Market
Fuels
Liquid Propellants Market
Fuels
Heavy Fuel Oil Market
Fuels
Brazil Bunker Fuel Market
Fuels
City Gas Distribution Market
Fuels
Synthetic Natural Gas (SNG) Market
Fuels
Gas to Liquid (GTL) Market
Fuels
Global Methane Hydrate Market
Fuels
Europe Wood Pellet Market
Fuels
South America Defense Aircraft Aviation Fuel Market
Fuels
Global Gas Cylinder Market
Fuels
Methane Market
Fuels
Waste-Derived Pyrolysis Oil Market
Fuels
United Kingdom Bunker Fuel Market
Fuels
Fuel Grinder Market