
 Signaling Devices Market | 2026-2036
Signaling Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Signaling Devices Market Outlook
Automation engineering talent is rotating toward industrial safety systems as factories integrate smarter hazard-alert architectures. Siemens AG leverages its process automation division to anchor European demand for integrated signaling solutions. Honeywell International Inc. sustains competitive pressure through its building technologies portfolio spanning fire and gas detection ecosystems. Patlite Corporation dominates the Asian factory-automation segment with specialized LED tower light and audible alarm production.
Signaling devices are electromechanical or solid-state apparatus engineered to emit visual, audible, or radio-frequency alerts at specified intensities, frequencies, and protection ratings for hazard communication in commercial and industrial environments. Their primary purpose is to reduce incident response latency by broadcasting standardized warnings across noisy, obscured, or remotely monitored operational zones. LED technology leads the technology dimension due to superior energy efficiency and extended operational lifespan versus incandescent alternatives, while strobe configurations occupy the fastest-expanding niche in high-ambient-light installations such as outdoor construction sites and traffic control corridors. Within applications, industrial operations command the deepest installed base, though emergency services represent the most concentrated margin pool given certification complexity and replacement-cycle rigor.
FCC regulations govern radio-enabled wireless signaling deployments in the United States, while the EU AI Act and Machinery Directive increasingly shape smart-connected alarm system requirements across European manufacturing facilities. OSHA mandates in the United States and REACH compliance obligations in Europe collectively elevate product testing expenditure and extend vendor certification timelines. Stakeholders must monitor how converging cybersecurity standards for networked safety systems reshape procurement criteria and vendor qualification protocols.
Market Dynamics
Industrial automation clusters are tightening integration requirements between signaling devices and plant-wide safety networks, compressing procurement cycles and elevating vendor technical qualification thresholds.
Growth Catalysts
- ATEX certification mandates:European hazardous area directives are expanding the addressable market for explosion-proof signaling equipment across chemical processing and oil and gas facilities.
- LED solid-state technology:Superior lumen-per-watt efficiency and 50,000+ hour operational lifespan are displacing incandescent and halogen alternatives in heavy industrial deployments.
- German industrial automation density:The Ruhr industrial corridor and Bavarian manufacturing belt concentrate demand for integrated visual-audible alarm systems.
Market Restraints
- Rare earth magnet supply concentration:Neodymium and dysprosium sourcing dependence on Chinese processing capacity creates input cost volatility for electromagnetic signaling components.
- IECEx testing backlog:Certification queue lengths at accredited laboratories extend product launch timelines by 8-14 months for hazardous area equipment.
- Wireless substitution pressure:Industrial Wi-Fi and private 5G networks are displacing hardwired signaling architectures in greenfield facility designs.
Strategic Opportunities
- India manufacturing expansion:PLI scheme incentives and domestic electronics production targets are creating localized demand for factory-automation signaling infrastructure.
- Cybersecurity-integrated safety systems:Convergence of IEC 62443 standards with traditional alarm device protocols opens premium positioning for encrypted signaling networks.
- Predictive maintenance integration:Vibration and thermal monitoring embedded within signaling housings enables condition-based service models in process industries.
Industry Challenges
- Functional safety engineering scarcity:SIL-rated system design expertise remains concentrated among a limited pool of certified automation specialists.
- Legacy protocol integration friction:Retrofitting smart-connected signaling devices into existing 4-20mA and relay-based alarm infrastructures demands custom engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Signaling Devices Market |
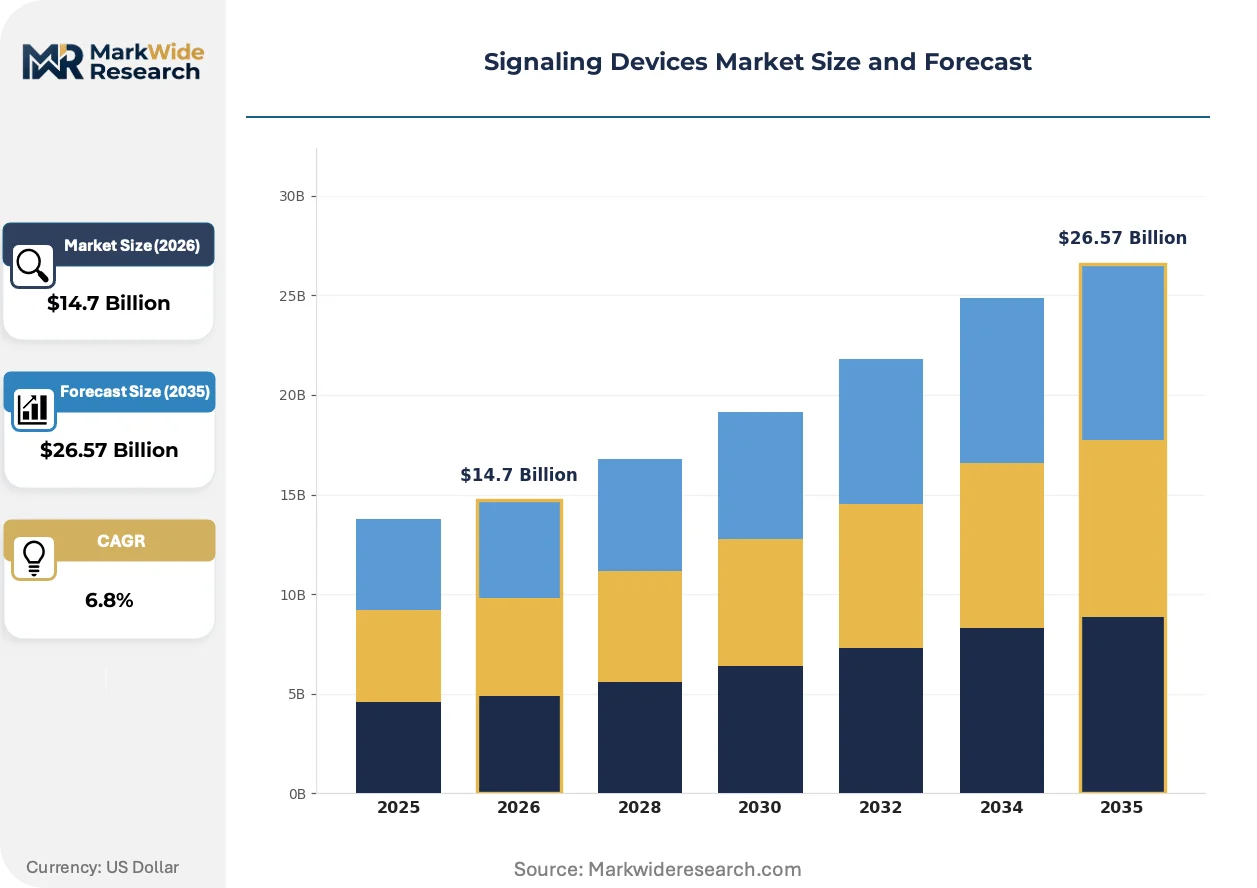
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flashing Lights, Sirens, Beacons, Horns Technology: LED, Strobe, Xenon, Incandescent Application: Emergency Services, Construction Sites, Traffic Control, Industrial Operations Installation: Permanent Mount, Portable, Wireless, Wired |
| Companies Covered | Siemens AG, Honeywell International Inc., ABB Ltd., Rockwell Automation Inc., Eaton Corporation, Emerson Electric Co., Patlite Corporation, R. Stahl AG, E2S Warning Signals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Signaling Devices Market Strategic Shifts
Smart connectivity architectures are compressing the traditional separation between signaling hardware and facility management software, enabling real-time alarm correlation and predictive diagnostics.
Multi-spectral LED arrays are miniaturizing into compact dome and beacon form factors while maintaining candela output ratings previously requiring larger incandescent housings. Offshore oil platforms and pharmaceutical cleanrooms are adopting these reduced-footprint units to resolve space constraints and reduce installation labor. The technology is miniaturizing field device footprints by 40-60% versus legacy strobe configurations, enabling signaling placement in previously inaccessible machinery zones.
REACH substance restrictions are phasing out cadmium-based pigments and certain brominated flame retardants from enclosure plastics, forcing reformulation of housing materials across European-sourced equipment. Compound suppliers are accelerating bio-based polymer qualification programs to maintain CE marking eligibility. German chemical processors and Nordic marine operators face the steepest compliance transition given their combined exposure to RoHS and maritime equipment directives.
Asset-light procurement models are displacing capital-purchase conventions in mid-sized manufacturing facilities, with signaling devices increasingly bundled into multi-year safety-system service agreements. System integrators are capturing alarm lifecycle responsibility that equipment distributors previously held. This transition is most visible in US automotive supplier plants and Mexican maquiladora operations where total-cost-of-ownership metrics dominate vendor selection.
Signaling Devices Market Segmentation
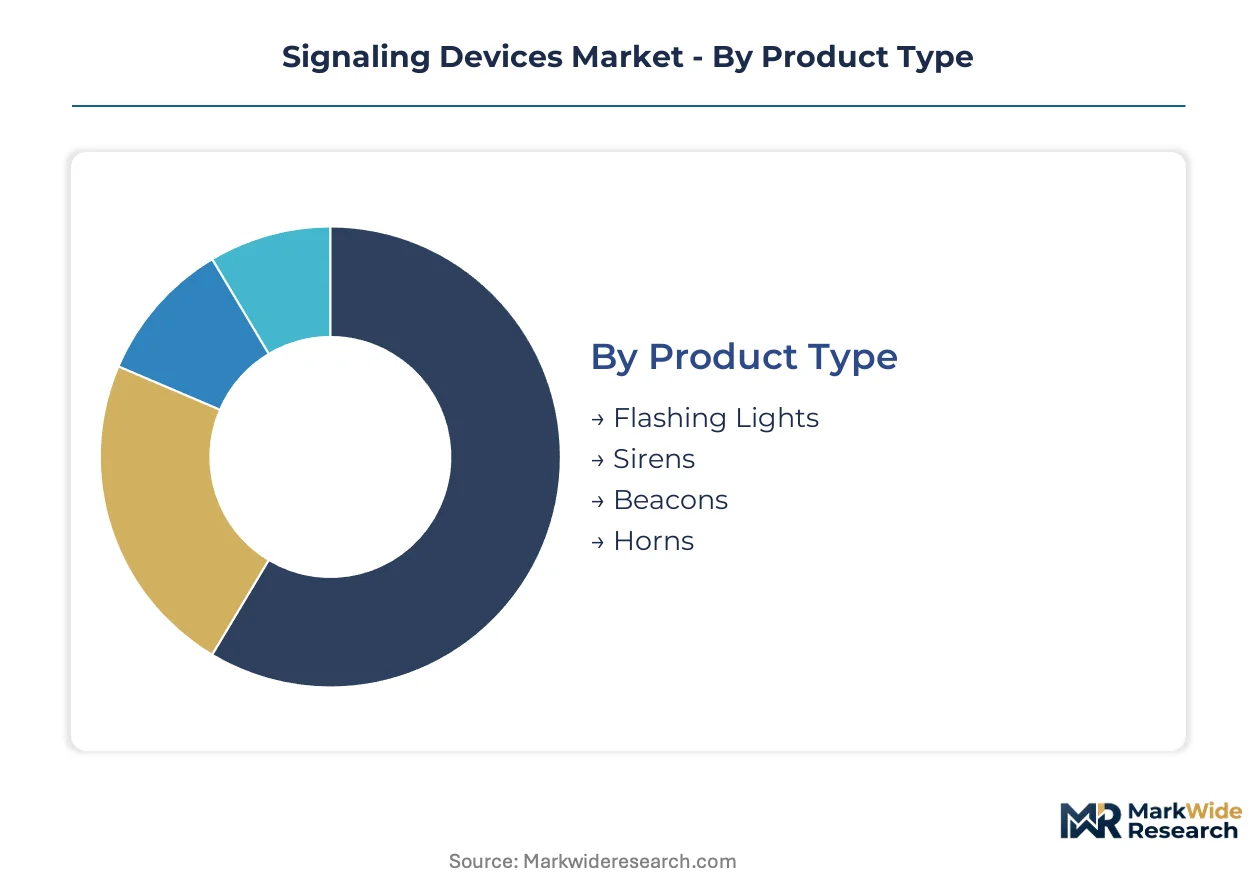
Signaling device procurement diverges sharply across hazard severity, environmental exposure, and integration complexity. Tiered specification requirements create distinct margin architectures that reward certified specialists over commodity suppliers.
Product Type:
Margin pools concentrate in explosion-rated and multi-spectral configurations where certification barriers filter competition.
- Flashing Lights:Solid-state LED arrays with programmable flash patterns dominate hazardous area deployments. Oil and gas refineries in Germany and the Netherlands specify IECEx-certified units for Zone 1 environments, with procurement tied to integrated process safety system upgrades.
- Sirens:Electromechanical and electronic sounders spanning 90-120 decibel output ratings serve high-ambient-noise manufacturing floors. Demand clusters in Indian automotive supplier parks where PLI scheme incentives accelerate factory automation density.
- Beacons:Rotating mirror and LED dome configurations for medium-range visual alerting.
- Horns:Pneumatic and electric diaphragm units for extreme noise penetration in mining and marine applications.
Flashing lights hold installed capacity. Sirens is rotating up the share rankings.
Technology:
Cost tier stratification separates premium solid-state platforms from legacy filament-based alternatives approaching end-of-life.
- LED:Gallium nitride chip-on-board designs deliver 50,000-hour operational lifespan with minimal thermal degradation. REACH compliance mandates in Europe and BIS efficiency standards in India accelerate displacement of incandescent inventories across industrial facilities.
- Strobe:Xenon flash tube and solid-state capacitor discharge systems generate candela outputs exceeding 300 effective intensity units. Outdoor construction corridors in Australia and traffic control installations across the United Arab Emirates specify these units for direct-sunlight visibility.
- Xenon:High-intensity discharge tubes for legacy marine and aviation signaling applications.
- Incandescent:Tungsten filament designs retained in cost-sensitive retrofit scenarios and certain military specification holdouts.
LED holds installed capacity. Strobe is rotating up the share rankings.
Application:
Customer type differentiation separates specification-intensive emergency procurement from volume-driven industrial maintenance cycles.
- Emergency Services:Multi-spectral warning systems combining audible, visual, and radio-alert outputs for fire, ambulance, and disaster response fleets. Compliance with OSHA emergency vehicle standards in the United States and EN 54 fire detection norms across European Union member states elevates testing expenditure and extends vendor qualification timelines.
- Industrial Operations:Process safety alarms integrated with distributed control systems and safety instrumented function loops. Chemical processors along the US Gulf Coast and pharmaceutical manufacturers in Switzerland specify SIL-rated signaling architectures for toxic gas release scenarios.
- Construction Sites:Temporary battery-powered and solar-charged units for mobile hazard perimeter marking.
- Traffic Control:Railroad crossing, intersection, and tunnel signaling governed by national transportation authority specifications.
Industrial operations hold installed capacity. Emergency services is rotating up the share rankings.
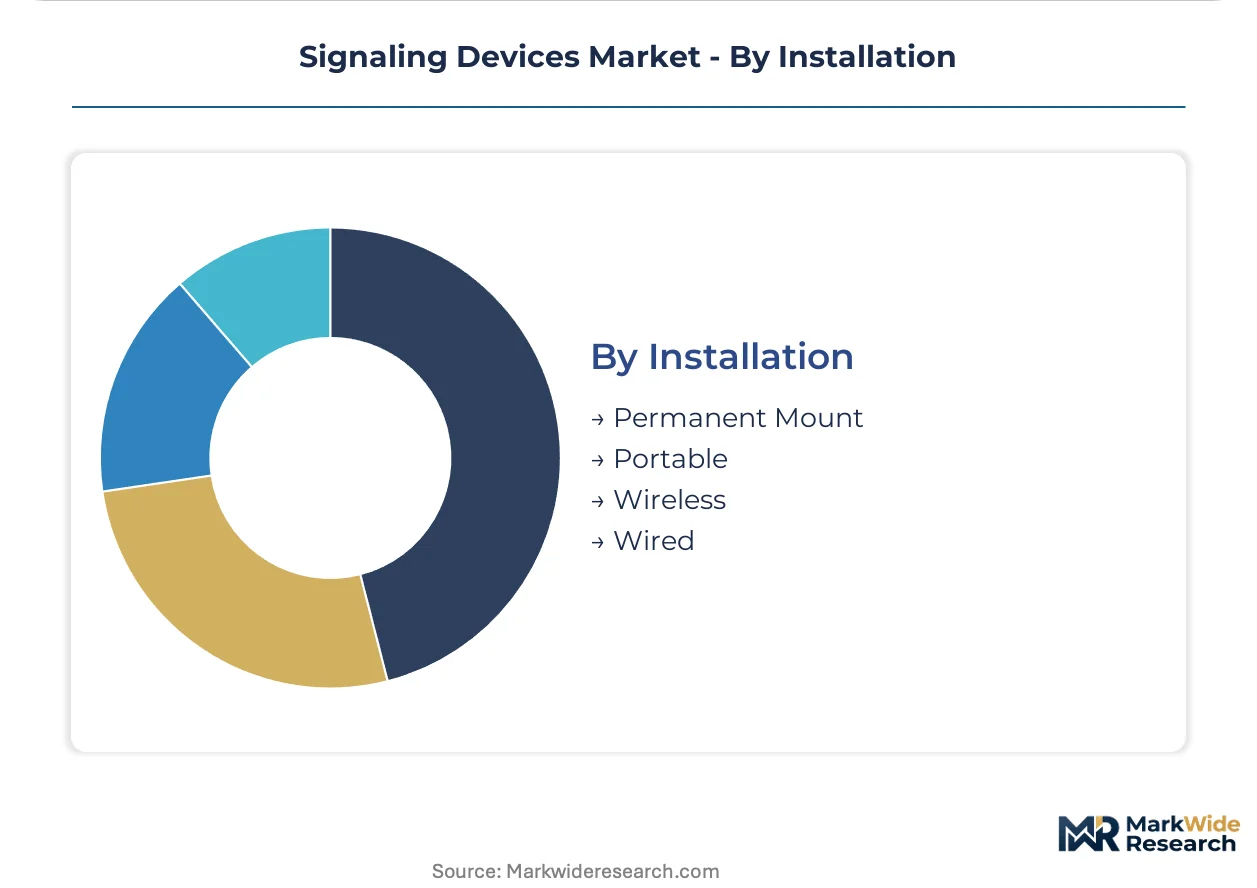
Installation:
Volume concentration favors hardwired architectures while wireless alternatives gain share in greenfield facility designs.
- Permanent Mount:Rigid conduit and cable gland installations in classified hazardous areas requiring ATEX or IECEx equipment protection level compliance. German chemical processors and Norwegian offshore platforms specify these configurations for 20-year asset life cycles.
- Wired:Traditional 4-20mA and relay-contact signaling loops dominating brownfield facility retrofits where wireless infrastructure investment is deferred.
- Portable:Magnetic base and clamp-mounted units for temporary maintenance and confined space entry scenarios.
- Wireless:Battery-powered and energy-harvesting devices leveraging industrial Wi-Fi, LoRa, or private 5G networks. Indian electronics manufacturing clusters and Mexican automotive assembly plants adopt these for flexible production line reconfiguration.
Wired holds installed capacity. Wireless is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA mandates in the United States and ATEX directives across European Union member states establish divergent compliance pathways that shape regional procurement patterns for hazardous area signaling equipment.
United States
Gulf Coast chemical processors and Permian Basin oilfield operators drive specification-intensive demand for SIL-rated alarm systems. OSHA Process Safety Management standards mandate integrated gas detection and signaling architectures across high-hazard facilities. Houston and Port Arthur industrial corridors concentrate procurement of explosion-proof visual-audible units tied to refinery turnaround schedules.
Germany
The Ruhr industrial belt and Bavarian manufacturing clusters anchor European demand for ATEX-certified signaling devices. REACH substance restrictions and RoHS compliance obligations elevate testing expenditure for enclosure materials and LED component suppliers. Siemens AG leverages its Munich-based process automation division to capture integrated safety system contracts across chemical and pharmaceutical facilities.
India
PLI scheme incentives for electronics manufacturing and automotive component production accelerate factory automation density in Pune, Chennai, and Gurugram industrial belts. BIS efficiency standards displace legacy incandescent signaling inventories across brownfield facility retrofits. Domestic electronics production targets create localized demand for LED tower lights and audible alarms in contract manufacturing facilities.
China
Yangtze River Delta petrochemical complexes and Pearl River Delta electronics assembly plants specify GB-standard hazardous area equipment for Zone 1 and Zone 2 environments. MIIT industrial safety directives tighten certification requirements for wireless-enabled signaling devices in smart factory deployments. Ningbo and Suzhou manufacturing hubs concentrate procurement of multi-spectral LED beacons for semiconductor cleanroom applications.
United Arab Emirates
ADNOC offshore platform expansions and Dubai industrial free zone developments drive demand for IECEx-certified signaling equipment in high-temperature, high-salinity environments. MOHAP technical regulations for industrial safety systems align procurement specifications with European ATEX frameworks. Jebel Ali and Kizad industrial zones concentrate installation of solar-powered wireless alarms for remote pipeline monitoring.
Signaling Devices Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in the Signaling Devices Market. Siemens AG and Honeywell International Inc. anchor the upper tier through bundled safety system offerings that combine signaling hardware with distributed control platforms. Mid-tier specialists compete on certification velocity and hazardous area expertise rather than scale. Strategic moves concentrate on backward integration into LED component supply and geographic expansion through local certification partnerships in India and Southeast Asia.
Among Germany-based industrial conglomerates, Siemens AG and R. Stahl AG exemplify divergent positioning archetypes within the premium tier. Siemens leverages its process automation division to anchor integrated safety system contracts across European chemical processors. R. Stahl AG occupies a specialized position focused narrowly on explosion-proof equipment for oil and gas hazardous areas. Japanese specialist Patlite Corporation represents the factory-automation archetype, with its corporate structure reflecting concentrated expertise in LED tower light and audible alarm production for discrete manufacturing environments.
| Leading Market Players |
|---|
| Siemens AG |
| Honeywell International Inc. |
| ABB Ltd. |
| Rockwell Automation Inc. |
| Eaton Corporation |
| Emerson Electric Co. |
| Patlite Corporation |
| R. Stahl AG |
| E2S Warning Signals |
| Others |
Value Chain & Pricing Dynamics
ATEX and IECEx certification regimes gate both supplier qualification timelines and price stratification across hazardous area equipment tiers, compressing margin pools for uncertified competitors while rewarding accredited specialists with premium positioning in oil and gas procurement cycles.
Pricing Analysis
Long-term service contracts dominate procurement in German chemical processors and US Gulf Coast refineries, displacing spot purchasing for explosion-proof signaling architectures. Three-tier pricing structure across SIL-rated premium, ATEX-certified standard, and non-certified economy levels separates Siemens-anchored integrated safety systems from commodity LED beacon suppliers. Cost compression in the economy tier is intensifying because Indian electronics manufacturing clusters are localizing tower light production under PLI scheme incentives. Mid-sized automotive suppliers in Mexico exhibit the sharpest price sensitivity, while Norwegian offshore operators prioritize certification velocity over unit cost.
Supply Chain Analysis
Inventory buffers for gallium nitride LED chips and neodymium permanent magnets have thinned to 6-10 weeks across European distribution hubs, extending quoted lead times for multi-spectral beacon assemblies. Component sourcing concentrates in China for rare earth processing, Taiwan for semiconductor substrates, and Germany for precision electromagnetic assemblies. Single-source vulnerability in Chinese dysprosium refining creates input cost volatility for electromechanical siren manufacturers. Distribution runs through authorized system integrators in hazardous area applications, bypassing traditional electrical distributors for ATEX-certified installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified functional safety engineering talent pools are contracting faster than university programs and vendor training academies can replenish them, concentrating design authority among Siemens, Honeywell, and a narrow specialist tier with captive SIL-rated expertise.
For Market Incumbents: Fortify backward integration into LED component supply and captive IECEx testing capacity to compress certification timelines that currently extend 8-14 months. Wireless substitution pressure from private 5G networks threatens hardwired signaling architectures in greenfield automotive and electronics facilities. Priority investment in cybersecurity-integrated safety protocols per IEC 62443 standards defends premium positioning against commoditization. For New Entrants and Emerging Players: Anchor in Indian electronics manufacturing clusters where PLI scheme incentives and BIS efficiency mandates are accelerating factory automation density and displacing legacy incandescent inventories. Wireless signaling architectures for flexible production line reconfiguration represent the most penetrable white space, with automotive assembly plants in Pune and Chennai seeking battery-powered, energy-harvesting devices. Go-to-market through local system integrators rather than direct OEM relationships to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across cybersecurity-integrated safety system development, as encrypted signaling network R&D demands sustained software engineering investment alongside traditional hardware capabilities. Over the projection horizon, vertically integrated specialists with captive LED component supply and multi-regional certification portfolios offer superior viability versus pure-play hardware assemblers. Monitor IECEx laboratory accreditation expansion as the signal to watch for supply constraint easing and new entrant viability inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Component Supply | Captive gallium nitride chip sourcing insulates margin pools from Taiwanese substrate supply volatility. |
| IECEx Certification Laboratory Partnership | Accredited testing capacity in India compresses product launch timelines for hazardous area equipment. |
| Cybersecurity-Integrated Safety System Development | IEC 62443-compliant encrypted signaling networks command premium positioning in German chemical processors. |
| Wireless Signaling Architecture Launch | Battery-powered LoRa and private 5G devices capture flexible reconfiguration demand in Indian automotive clusters. |
| Predictive Maintenance Module Integration | Vibration and thermal monitoring embedded in signaling housings enables condition-based service contracts with US Gulf Coast refineries. |
Study Parameters
Operator-level perspectives from plant engineers, safety system integrators, hazardous area procurement managers, and aftermarket service directors anchored the qualitative base for this signaling devices analysis. Primary fieldwork combined structured interviews with secondary validation through SEC 10-K filings, IECEx certification registry data, BIS efficiency standard notifications, and customs trade records for LED component flows. Bottom-up unit economics for flashing light, siren, and beacon configurations triangulated against top-down market sizing from industrial automation capex disclosures.
Sensitivity analysis across certification backlog scenarios, rare earth price volatility bands, and wireless adoption curves shaped the analytical framework. Segmentation dimensions modeled include product type, technology platform, application severity tier, installation architecture, and regional regulatory cluster. CAGRs derived from installed base turnover rates, greenfield facility automation intensity, and replacement cycle compression in process industries. Industry-specific forecast inputs incorporated refinery turnaround schedules and PLI scheme disbursement timelines for Indian electronics manufacturing.
Material uncertainties — IECEx laboratory capacity expansion, REACH substance restriction amendments, and private 5G network deployment velocity — sit outside the modeled envelope and could compress or extend growth trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Frequency Counter Market
Detection and Regulation Devices
Digital Attenuators Market
Detection and Regulation Devices
Digital Metal Detector Market
Detection and Regulation Devices
Portable Radar Detectors Market
Detection and Regulation Devices
Smart Water Leak Detector Market
Detection and Regulation Devices
Digital Underground Metal Detector Market
Detection and Regulation Devices
South East Asia Gas Detection Device Market
Detection and Regulation Devices
Hydrogen Detection Transmitters Market
Detection and Regulation Devices
Radar Detector Market
Detection and Regulation Devices
Filter Panels Market
Detection and Regulation Devices
Antistatic Device for Ultrapure Water Market
Detection and Regulation Devices
Temperature Modulation Devices Market
Detection and Regulation Devices
Middle East and Africa Trace Detection Market
Detection and Regulation Devices
Carbon Monoxide (Co) Detector Market
Detection and Regulation Devices
Semiconductor Inspection System Market
Detection and Regulation Devices
Duct Smoke Detectors Market