
 Asia-Pacific Trace Detection Screening Market | 2026-2036
Asia-Pacific Trace Detection Screening Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Trace Detection Screening Market Insights
China's GB standards for explosive trace detection is realigning the cost-of-entry calculus for foreign equipment suppliers. Smiths Detection Group Ltd leverages its ion mobility spectrometry portfolio to sustain technical leadership across Chinese aviation hubs. Bruker Corporation anchors its regional position through mass spectrometry systems calibrated to domestic certification requirements. Leidos Holdings Inc competes on integrated platform solutions that navigate multi-jurisdictional procurement frameworks.
Trace detection screening encompasses instruments that identify microscopic quantities of explosives, narcotics, chemical warfare agents, or contraband through spectral analysis, with detection thresholds typically reaching nanogram or picogram sensitivity. These systems serve critical security screening functions at transportation nodes, military checkpoints, and industrial facilities where conventional inspection methods prove inadequate. Handheld detectors dominate volume shipments due to their deployment flexibility across law enforcement patrols and rapid-response scenarios. Mass spectrometry commands premium positioning in laboratory and military applications where analytical precision justifies capital intensity. Homeland security applications absorb the largest share of public procurement budgets across the region's major economies.
China's SAMR enforces GB standards that dictate calibration protocols and false-alarm thresholds for deployed trace detection equipment. Japan's METI coordinates with transport ministries to mandate screening technology upgrades at Shinkansen terminals and international airports. Australia's TGA and Department of Home Affairs jointly oversee chemical detection standards for border protection infrastructure. Stakeholders must monitor how divergent national certification timelines affect product development roadmaps and regional inventory strategies.
Market Dynamics
Airport security modernization across Southeast Asia is compressing procurement cycles for ion mobility spectrometry systems while India's PLI scheme for defense electronics reconfigures local manufacturing incentives.
Growth Catalysts
- Aviation infrastructure expansion:Southeast Asian governments are mandating upgraded passenger screening protocols at international terminals, creating sustained equipment replacement cycles.
- PLI scheme incentives:India's production-linked incentive framework for defense electronics is attracting component localization investments that reduce import dependency for trace detection subsystems.
- Metropolitan transit hardening:Japan's transport ministries are requiring explosive trace detection deployments at Shinkansen terminals and major subway interchanges.
Market Restraints
- Calibration standard fragmentation:Divergent national certification timelines between China's SAMR, Japan's METI, and Australia's TGA force redundant product development cycles.
- Sensor material cost volatility:Specialized drift tube components and radioactive source materials concentrate supply among limited qualified vendors.
- False-alarm threshold stringency:GB standards enforcement in China demands extensive field validation that extends time-to-revenue for new equipment introductions.
Strategic Opportunities
- Underpenetrated Australian critical infrastructure:Mining facilities and energy distribution networks outside major urban centers lack systematic chemical detection coverage.
- Mass spectrometry-laboratory convergence:Forensic laboratories and military test facilities are integrating portable mass spec units with centralized data analytics platforms.
- Handheld channel expansion:Law enforcement patrol units are bypassing traditional distributor networks through direct government procurement frameworks.
Industry Challenges
- Spectral analysis talent scarcity:Field service engineers capable of calibrating ion mobility and mass spectrometry systems remain concentrated in Japan and Australia.
- Legacy system integration friction:Existing X-ray and millimeter-wave screening infrastructure at major aviation hubs requires costly middleware development for trace detection data fusion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Trace Detection Screening Market |
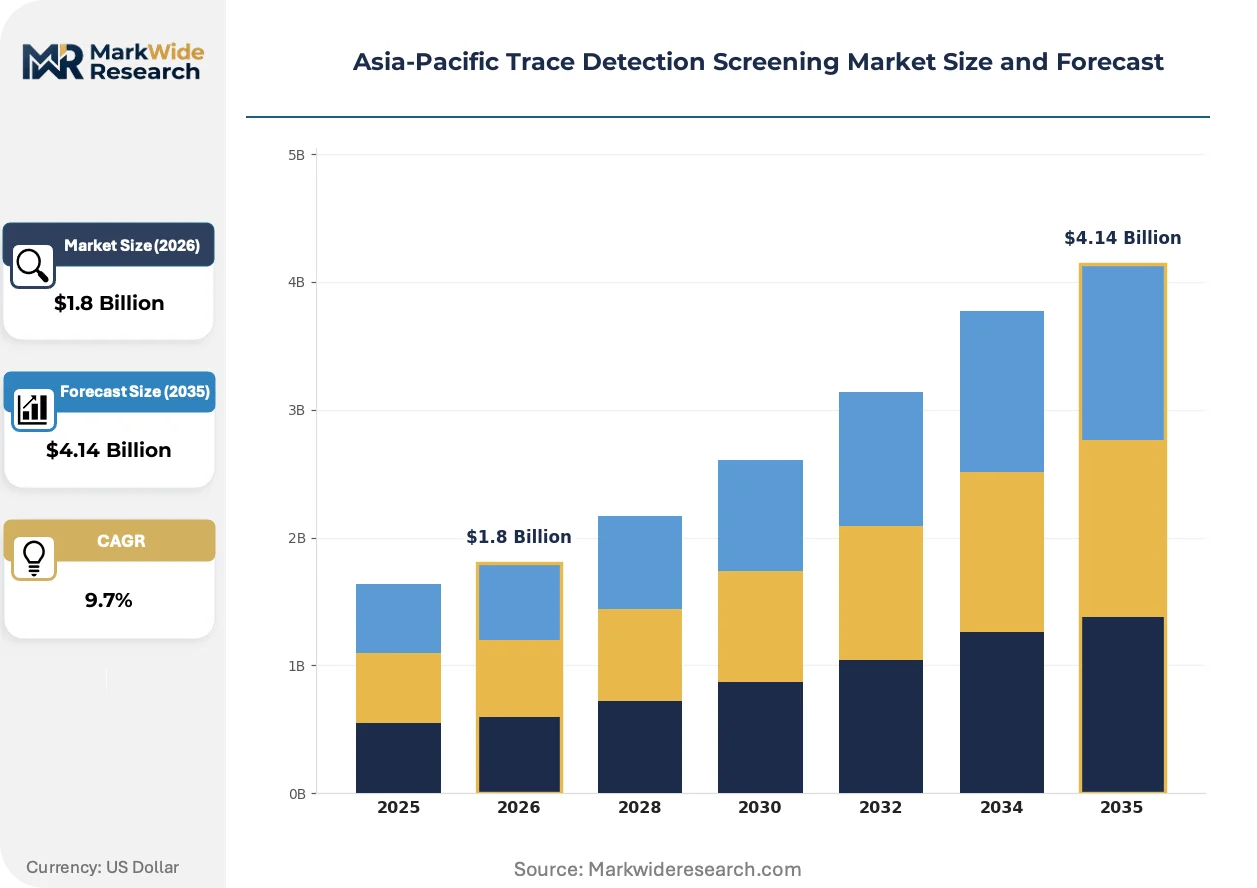
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Detectors, Fixed Detectors, Portable Detectors, Benchtop Detectors Technology: Mass Spectrometry, Ion Mobility Spectrometry, Gas Chromatography, Surface Enhanced Raman Spectroscopy Application: Homeland Security, Industrial Safety, Military Applications, Laboratory Use End User: Government Agencies, Airports, Law Enforcement, Private Security Companies |
| Companies Covered | Autoclear LLC, Thruvision Ltd, Smiths Detection Group Ltd, Evovl Technologies, Linev Systems, Teledyne Flir LLC, Leidos Holdings Inc., Analogic Corporation, Bruker Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Trace Detection Screening Market Trends and Innovations
Artificial intelligence is embedding into detection algorithms while regulatory divergence accelerates regional product variant specialization. Equipment manufacturers are reconfiguring service delivery models to address compressed deployment timelines.
Raman spectroscopy is absorbing expanded analytical workloads in field-deployed narcotics identification, displacing traditional colorimetric test kits at border checkpoints. Australian customs operations and Japanese prefectural police forces are adopting handheld Raman units for rapid substance verification without consumable reagents. This photonics-based approach is absorbing market share from ion mobility systems in law enforcement applications where chemical specificity outweighs explosive detection priority.
China's SAMR is tightening GB standard enforcement for explosive trace detection calibration protocols, forcing foreign suppliers to establish domestic testing facilities. Equipment vendors must now complete in-country validation cycles before aviation authority approval. This regulatory compression most affects European and North American manufacturers serving Chinese airport expansion projects.
Buyer organizations are consolidating vendor relationships through multi-year platform agreements that bundle hardware, software updates, and predictive maintenance. Australian Department of Home Affairs procurement and Japanese transport ministry frameworks favor integrated service contracts over discrete equipment purchases. This consolidation pattern appears most pronounced in aviation security applications where operational continuity outweighs capital cost minimization.
Asia-Pacific Trace Detection Screening Market Segmentation
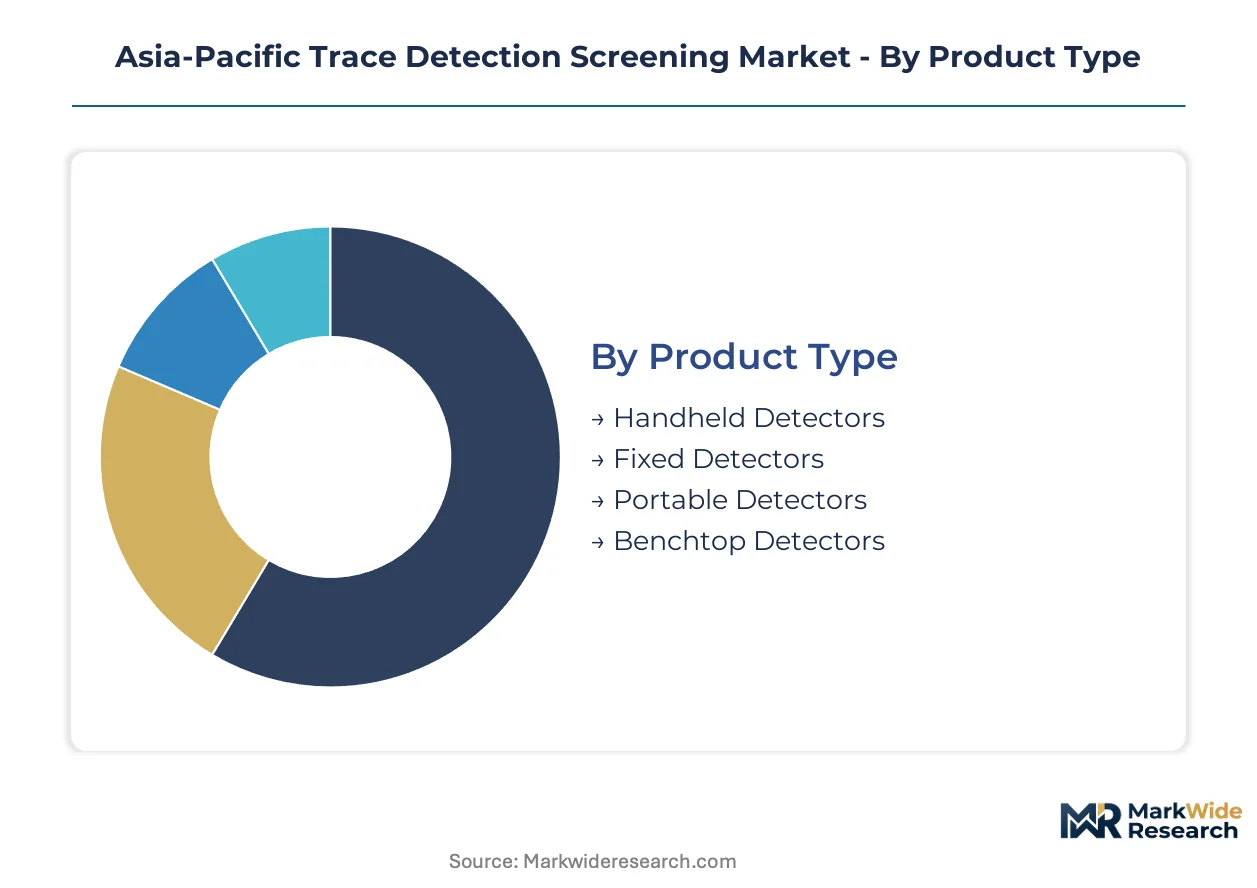
Segmentation in Asia-Pacific trace detection screening reveals distinct procurement patterns across product configurations, detection methodologies, and institutional buyers. Equipment specifications diver sharply between aviation security mandates and field-deployable law enforcement requirements.
Product Type:
Upgrade cycles across Japanese Shinkansen terminals and Australian mining complexes are compressing replacement timelines for portable and fixed installations.
- Handheld Detectors:Battery-powered units weighing under 2kg deliver nanogram sensitivity for explosives and narcotics through ion mobility or Raman spectroscopy. Law enforcement patrols in Japan's prefectural police forces and Australian border checkpoints prioritize these for rapid-deployment scenarios where mobility outweighs analytical precision.
- Fixed Detectors:Permanently installed systems integrate with baggage handling infrastructure and checkpoint architecture at aviation terminals. China's aviation authority procurement at Beijing Daxing and Shanghai Pudong concentrates demand for conveyor-integrated explosive trace portals with centralized alarm management.
- Portable Detectors:Transit-case systems bridge field and laboratory applications with benchtop-equivalent sensitivity. Military test facilities in India and forensic laboratories in Australia deploy these for rapid redeployment between sites.
- Benchtop Detectors:Laboratory-grade instruments with picogram detection thresholds serve reference calibration and evidentiary confirmation functions. These concentrate in Japan's National Police Agency forensic centers and Australian defense research facilities.
Volume placements concentrate in Handheld Detectors; the faster expansion belongs to Fixed Detectors.
Technology:
Cost tiers separate premium analytical precision from field-deployable speed, with calibration requirements diverging across China's SAMR, Japan's METI, and Australia's TGA frameworks.
- Mass Spectrometry:High-resolution molecular identification systems achieve unambiguous chemical specificity through time-of-flight or quadrupole analyzers. Military applications in India and forensic laboratories in Japan absorb these capital-intensive systems where false-alarm consequences justify procurement cost.
- Ion Mobility Spectrometry:Drift-tube-based detection dominates aviation security through rapid response times under 10 seconds. Southeast Asian airport modernization programs in Thailand, Vietnam, and Indonesia standardize on these systems for passenger and baggage screening lanes.
- Gas Chromatography:Separation-based analysis identifies complex chemical mixtures in laboratory environments. Industrial safety applications at Australian petrochemical facilities and Japanese semiconductor fabrication plants deploy these for process monitoring.
- Surface Enhanced Raman Spectroscopy:Plasmonic substrate amplification enables field identification without consumable reagents. Australian customs operations and Japanese prefectural police are absorbing expanded analytical workloads previously handled by colorimetric test kits.
Revenue concentration sits with Ion Mobility Spectrometry; Mass Spectrometry claims the steepest expansion trajectory in military and forensic procurement.
Application:
Customer maturity varies across institutional buyers, with aviation security demonstrating the most standardized procurement specifications.
- Homeland Security:Border protection, critical infrastructure guarding, and public venue screening constitute the largest public procurement category. Australia's Department of Home Affairs and Japan's transport ministries command multi-year platform agreements bundling hardware, software, and predictive maintenance.
- Industrial Safety:Chemical manufacturing, mining, and energy distribution networks require workplace exposure monitoring and perimeter security. Underpenetrated Australian mining facilities outside major urban centers present systematic coverage gaps.
- Military Applications:Chemical warfare agent detection, explosives ordnance disposal support, and field laboratory operations drive specialized requirements. India's PLI scheme for defense electronics is reconfiguring local manufacturing incentives for trace detection subsystems.
- Laboratory Use:Forensic confirmation, reference standard calibration, and research applications demand highest analytical precision. These concentrate in Japan's metropolitan police forensic centers and Australian defense science facilities.
Procurement volume clusters in Homeland Security; Military Applications are climbing the fastest on India's localization incentives.
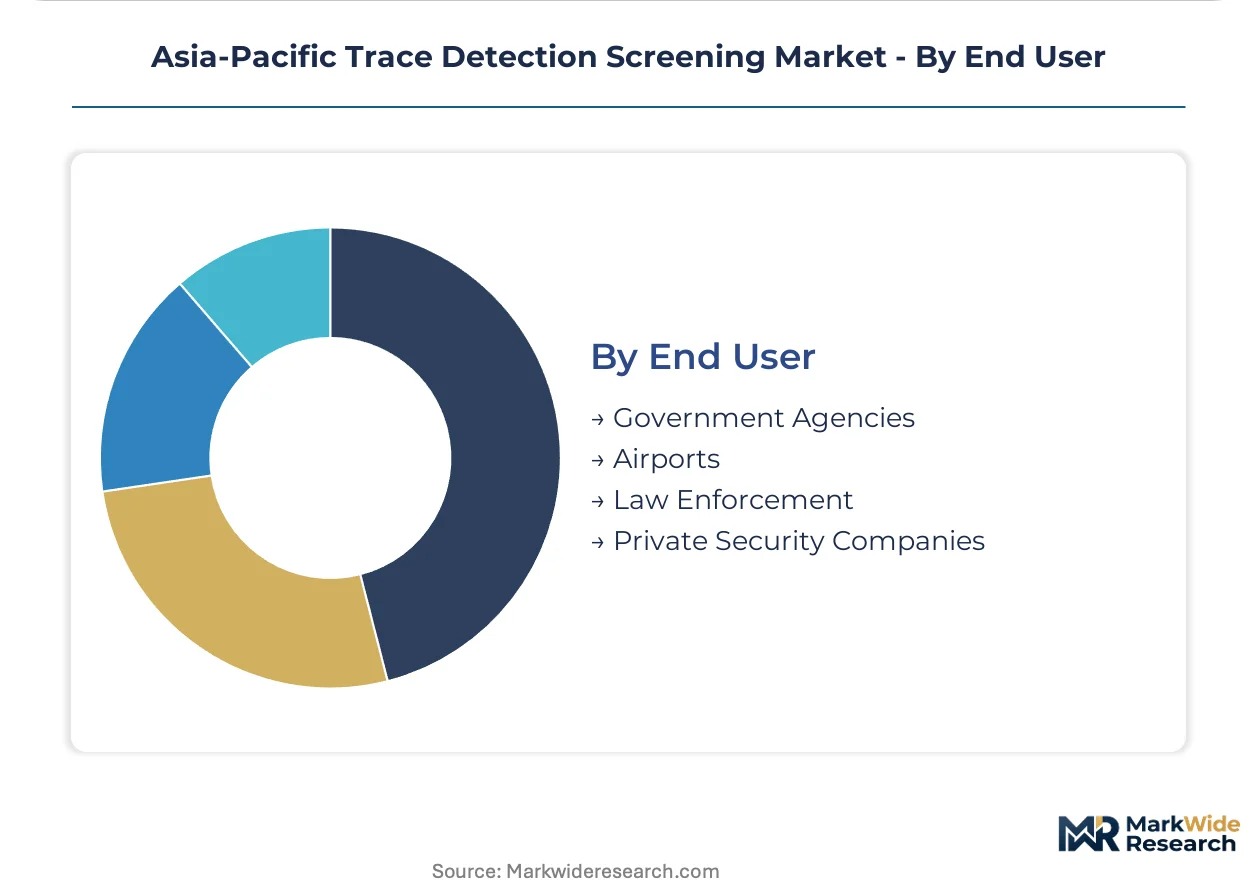
End User:
Supply concentration among qualified vendors shapes distributor relationships, with direct government frameworks bypassing traditional channels for handheld deployments.
- Government Agencies:National security, customs, and transport ministries operate the largest installed bases through centralized procurement frameworks. China's SAMR calibration mandates and Japan's METI coordination create divergent certification timelines.
- Airports:Aviation authorities mandate passenger, baggage, and cargo screening protocols with operational continuity requirements. Southeast Asian terminal expansions in Bangkok, Ho Chi Minh City, and Jakarta compress equipment replacement cycles.
- Law Enforcement:Prefectural and municipal police forces deploy handheld units for patrol and rapid response. Direct procurement frameworks in Japan and Australia are displacing traditional distributor networks.
- Private Security Companies:Critical infrastructure guarding and corporate venue protection generate demand outside public procurement. Australian mining operators and Japanese commercial facilities contract these services for perimeter chemical detection.
Installed base dominance rests with Government Agencies; Private Security Companies are gaining share fastest on Australian critical infrastructure expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for defense electronics has concentrated component localization investments around Bengaluru and Hyderabad special economic zones, reshaping procurement patterns for trace detection subsystems across the Asia-Pacific.
China
Aviation security modernization at Beijing Daxing and Shanghai Pudong drives demand for conveyor-integrated explosive trace portals. SAMR enforces GB standards that mandate in-country validation cycles before equipment approval. Foreign suppliers now establish domestic testing facilities in the Yangtze River Delta to satisfy regulatory compression.
Japan
Shinkansen terminals and metropolitan subway interchanges require upgraded passenger screening protocols under transport ministry mandates. METI coordinates with rail operators to standardize ion mobility spectrometry deployments. Tokyo and Osaka hubs concentrate procurement for integrated platform solutions with predictive maintenance contracts.
India
Defense electronics manufacturing incentives attract trace detection subsystem producers to Bengaluru and Hyderabad clusters. The PLI scheme reduces import dependency for drift tube components and sensor modules. Military test facilities and forensic laboratories drive demand for portable and benchtop configurations.
Australia
Border protection infrastructure and critical mining facilities outside major urban centers present systematic coverage gaps for chemical detection. The Department of Home Affairs and TGA jointly oversee procurement frameworks favoring multi-year service contracts. Western Australia mining complexes and Queensland energy distribution networks absorb expanded analytical workloads.
Southeast Asia
Thailand, Vietnam, and Indonesia compress equipment replacement cycles through airport terminal expansions in Bangkok, Ho Chi Minh City, and Jakarta. National aviation authorities mandate upgraded passenger and baggage screening lanes. Ion mobility spectrometry systems dominate procurement for operational speed requirements.
Asia-Pacific Trace Detection Screening Market Competitive Landscape
North American technology providers anchor the premium-system tier; European specialists hold established positions in analytical precision segments. Market structure concentrates around integrated platform vendors and component specialists serving divergent certification timelines. Two archetypes dominate: multi-jurisdictional compliance navigators and rapid-deployment mobility specialists. Competitive moves center on domestic testing facility establishment and predictive maintenance service bundling.
Within the integrated platform tier, Leidos Holdings Inc. and Smiths Detection Group Ltd occupy positions exemplifying multi-jurisdictional procurement framework navigation. Bruker Corporation represents the analytical precision archetype through mass spectrometry systems calibrated to domestic certification requirements. These three anchors illustrate how geographic origin and company structure correlate with strategic positioning across China's SAMR-mandated validation cycles, Japan's METI-coordinated transport upgrades, and Australia's TGA-Home Affairs joint procurement frameworks.
| Leading Market Players |
|---|
| Autoclear LLC |
| Thruvision Ltd |
| Smiths Detection Group Ltd |
| Evovl Technologies |
| Linev Systems |
| Teledyne Flir LLC |
| Leidos Holdings Inc. |
| Analogic Corporation |
| Bruker Corporation |
| Others |
Pricing and Supply Chain Analysis
Spectral analysis engineer scarcity in Japan and Australia widens labor-cost differentials that translate into tiered pricing spreads across ion mobility and mass spectrometry systems. Procurement officers in Southeast Asian aviation authorities face compressed lead-time premiums as domestic calibration expertise concentrates in metropolitan clusters.
Pricing Analysis
Short lead-time premiums command pricing power for ion mobility spectrometry systems deployed at Bangkok, Ho Chi Minh City, and Jakarta airport terminals. Three-tier pricing structure across premium, standard, and economy levels separates predictive maintenance-bundled platforms from discrete hardware sales and spot inventory clearances. Cost compression in economy tiers intensifies because India's PLI scheme for defense electronics accelerates local component production. Government agencies demonstrate lowest price sensitivity due to operational continuity mandates, while private security companies in Australian mining regions exhibit highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with drift tube component suppliers concentrated in Japan, Germany, and the United States. Radioactive source materials and specialized sensor substrates draw from qualified vendors facing extended certification cycles under China's SAMR and Australia's TGA frameworks. Tariff exposure runs through cross-border shipments of mass spectrometry analyzers subject to divergent national calibration timelines. Distribution runs through integrated platform vendors bundling hardware with predictive maintenance, displacing traditional equipment distributors in Japanese and Australian procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified field service engineers capable of calibrating ion mobility and mass spectrometry systems concentrate in Japan and Australia, creating a capacity bottleneck that sustains pricing power for incumbent service providers.
For Market Incumbents: Cement predictive maintenance contract penetration at Japanese Shinkansen terminals and Australian Department of Home Affairs frameworks before Raman spectroscopy suppliers displace ion mobility share in law enforcement applications. Expand domestic testing facilities in China's Yangtze River Delta to compress SAMR validation cycles. Deepen backward integration into drift tube component production to offset sensor material cost volatility from limited qualified vendors. For New Entrants and Emerging Players: Australian mining facilities outside major urban centers present systematic coverage gaps for chemical detection systems underserved by incumbent platform vendors. Target handheld Raman spectroscopy deployments at Japanese prefectural police forces adopting direct procurement frameworks that bypass traditional distributor networks. Pursue white-label manufacturing partnerships with Indian defense electronics producers qualifying under PLI scheme incentives for trace detection subsystems. For Investors and Strategic Acquirers: Re-rating potential sits with mass spectrometry specialists serving forensic laboratory and military test facility segments given India's localization incentives and Japan's metropolitan transit hardening mandates. Long-term viability hinges on regulatory navigation capabilities across China's GB standards, Japan's METI coordination, and Australia's TGA-Home Affairs joint frameworks. Monitor calibration engineer certification throughput as inflection indicator for service revenue expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Testing Facility Establishment | China's SAMR mandates in-country validation cycles before aviation authority equipment approval. |
| Predictive Maintenance Contract Bundling | Australian Department of Home Affairs and Japanese transport ministries favor multi-year platform agreements. |
| Handheld Channel Direct Procurement | Japanese prefectural police and Australian border checkpoints bypass traditional distributor networks. |
| Backward Integration into Drift Tubes | Specialized drift tube components concentrate supply among limited qualified vendors in Japan and Germany. |
| Raman Spectroscopy Portfolio Expansion | Australian customs and Japanese prefectural police displace colorimetric test kits with photonics-based identification. |
Research Methodology
Independent corroboration across equipment procurement officers at Asian aviation authorities, calibration engineers at Japanese forensic laboratories, and defense electronics manufacturers in India's PLI scheme zones underwrites the qualitative findings. Primary interviews with airport security directors, METI coordination officials, TGA compliance leads, and SAMR validation specialists combined with secondary validation from customs procurement databases, aviation authority tender records, and defense electronics manufacturing disclosures. Bottom-up shipment tallies by product configuration and technology type triangulate against top-down public procurement budget allocations across homeland security applications.
Historical reference periods spanning pre-pandemic baseline through post-recovery normalization anchor the forecast window across the analysis window. Segmentation modeling incorporates product type, detection methodology, application category, and end-user archetype dimensions alongside regional regulatory cluster divergence. CAGRs derive from equipment replacement cycle compression at Southeast Asian airport terminals, PLI scheme localization trajectories in India, and metropolitan transit hardening mandates in Japan. Forecast inputs include drift tube component supply constraints and spectral analysis engineer availability by geography.
Revisions become necessary when China's SAMR accelerates GB standard enforcement timelines, India's PLI scheme expands eligible component categories, or Australia's TGA introduces new chemical detection calibration protocols. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Detection and Regulation Devices
Carbon Monoxide (Co) Detector Market
Detection and Regulation Devices
US Pin and Sleeve Devices Market
Detection and Regulation Devices
Global Noise Detection and Monitoring Market
Detection and Regulation Devices
Water Leak Detector Market
Detection and Regulation Devices
Global Tunnel Diode Detectors Market
Detection and Regulation Devices
Frequency Counter Market
Detection and Regulation Devices
Pedestrian Detection System Market
Detection and Regulation Devices
Pin and Sleeve Devices Market
Detection and Regulation Devices
Betavoltaic Device Market
Detection and Regulation Devices
Temperature Modulation Devices Market
Detection and Regulation Devices
Ultra Low Dropout Regulator (LDO) Market
Detection and Regulation Devices
Arc Fault Detection Devices Market
Detection and Regulation Devices
Semiconductor Leak Detectors Market
Detection and Regulation Devices
Antistatic Device for Ultrapure Water Market
Detection and Regulation Devices
Spark Detector Market
Detection and Regulation Devices
Global Inflation Device Market