
 Epitaxy Equipment Market | 2026-2036
Epitaxy Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Epitaxy Equipment Market Foresight
Japanese gas supply infrastructure is rebalancing around advanced compound semiconductor growth. Veeco Instruments leverages its molecular beam epitaxy specialization to anchor North American research demand. ASM International sustains differentiated process control architectures for silicon carbide production. Aixtron SE dominates GaN-on-silicon metal organic chemical vapor deposition systems for power electronics foundries.
Epitaxy equipment deposits crystalline semiconductor layers with atomic-scale thickness precision, typically operating at temperatures between 500°C and 1,100°C depending on material system, to engineer bandgap structures for optoelectronic and high-frequency devices. Metal organic chemical vapor deposition systems command the largest installed base due to throughput advantages in LED and power device manufacturing, while molecular beam epitaxy retains premium positioning for research-grade quantum structures and defense applications where layer purity thresholds exceed commercial specifications.
The US EPA enforces hazardous chemical handling protocols for precursor materials used in organometallic deposition, while the EU REACH framework governs substance registration and restriction across European tool installations. China's MEE implements emissions controls on fabrication facilities that indirectly shape equipment energy efficiency requirements. Stakeholders must monitor evolving export control classifications for wide-bandgap technologies and precursor supply chain certification timelines.
Market Dynamics
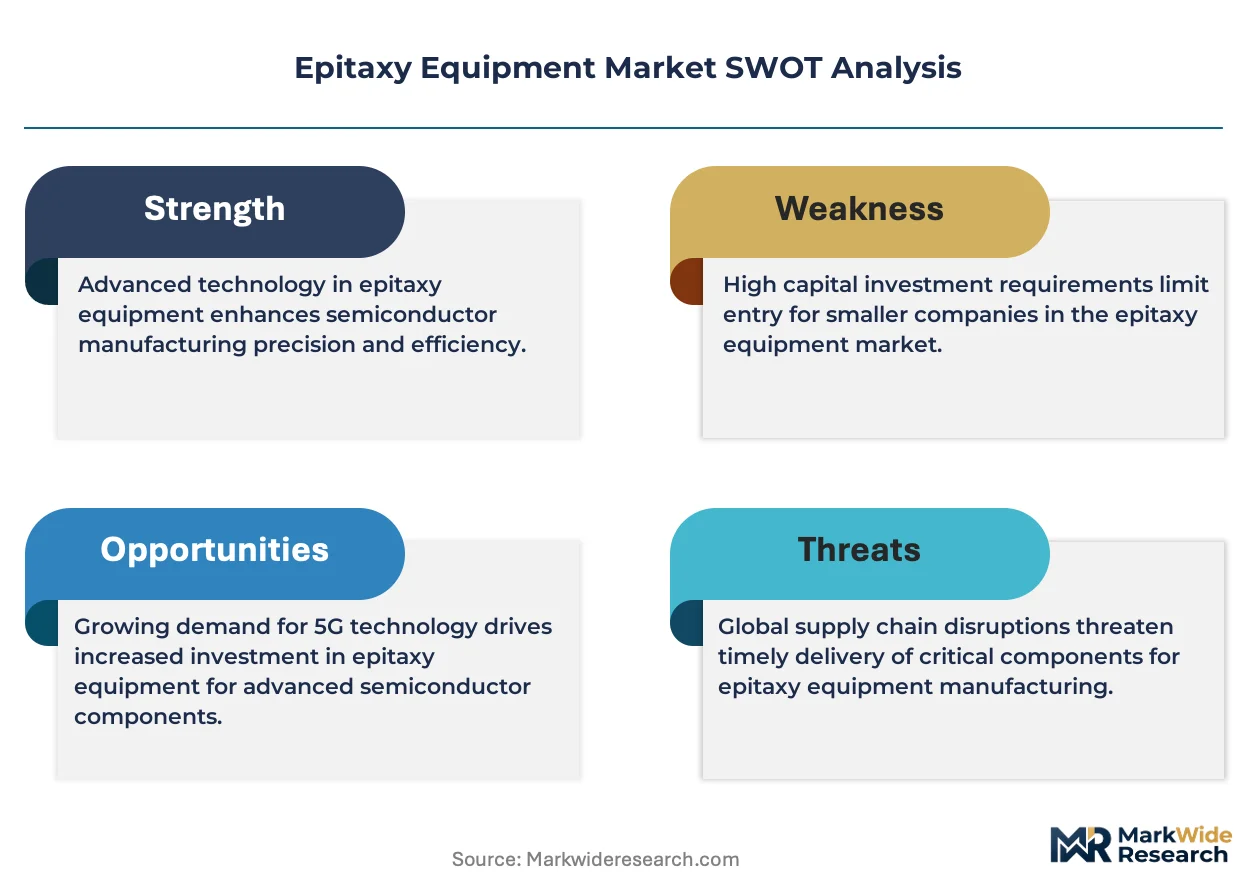
Power electronics manufacturers in electric vehicles are compressing equipment qualification cycles while China's dual carbon goals tighten energy efficiency standards for fabrication tools. This dual pressure is reshaping supplier-customer relationships across metal organic chemical vapor deposition and molecular beam epitaxy system procurement.
Growth Catalysts
- Silicon carbide ramp in traction inverters:Electric vehicle powertrain manufacturers are qualifying 200mm SiC epitaxy platforms for next-generation inverter designs. Tool vendors are configuring multi-wafer batch reactors to meet automotive throughput requirements.
- China's dual carbon goals:Beijing's 2030 emissions peak mandate is accelerating replacement of legacy thermal processing equipment with low-power-consumption epitaxy systems in domestic fabrication facilities.
- GaN-on-silicon for consumer adapters:Fast-charging power supply manufacturers are driving demand for high-throughput metal organic chemical vapor deposition tools capable of depositing gallium nitride on 200mm silicon substrates at consumer price points.
Market Restraints
- Precursor cost volatility:Organometallic gallium and indium compound prices fluctuate with rare earth mining output concentration in Chinese processing facilities, compressing foundry operating margins.
- Single-source component risk:Advanced vacuum pumping systems and quartzware for ultra-high-temperature operation concentrate among Japanese and German suppliers, creating supply vulnerability.
- Substrate diameter transition friction:Migration from 150mm to 200mm silicon carbide substrates requires simultaneous retooling of epitaxy, polishing, and inspection equipment, freezing capital deployment decisions.
Strategic Opportunities
- India's semiconductor fabrication incentives:New Delhi's production-linked incentive scheme for compound semiconductor manufacturing is attracting epitaxy equipment vendors to establish local service infrastructure.
- Photonic integrated circuits:Datacenter optical interconnect demand is creating a new equipment category for indium phosphide epitaxy systems targeting 800G and 1.6T transceiver production.
- Quantum dot display manufacturing:Cadmium-free quantum dot deposition for premium television panels requires precision molecular beam epitaxy tools with enhanced thickness uniformity control.
Industry Challenges
- Process engineer scarcity:Compound semiconductor epitaxy operation requires expertise in both vacuum system physics and organometallic chemistry, with training pipelines lagging equipment installation rates.
- Cleanroom retrofit complexity:Legacy silicon fabrication facilities require structural reinforcement and HVAC upgrades to accommodate the heavier vibration-isolation foundations demanded by modern epitaxy platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Epitaxy Equipment Market |
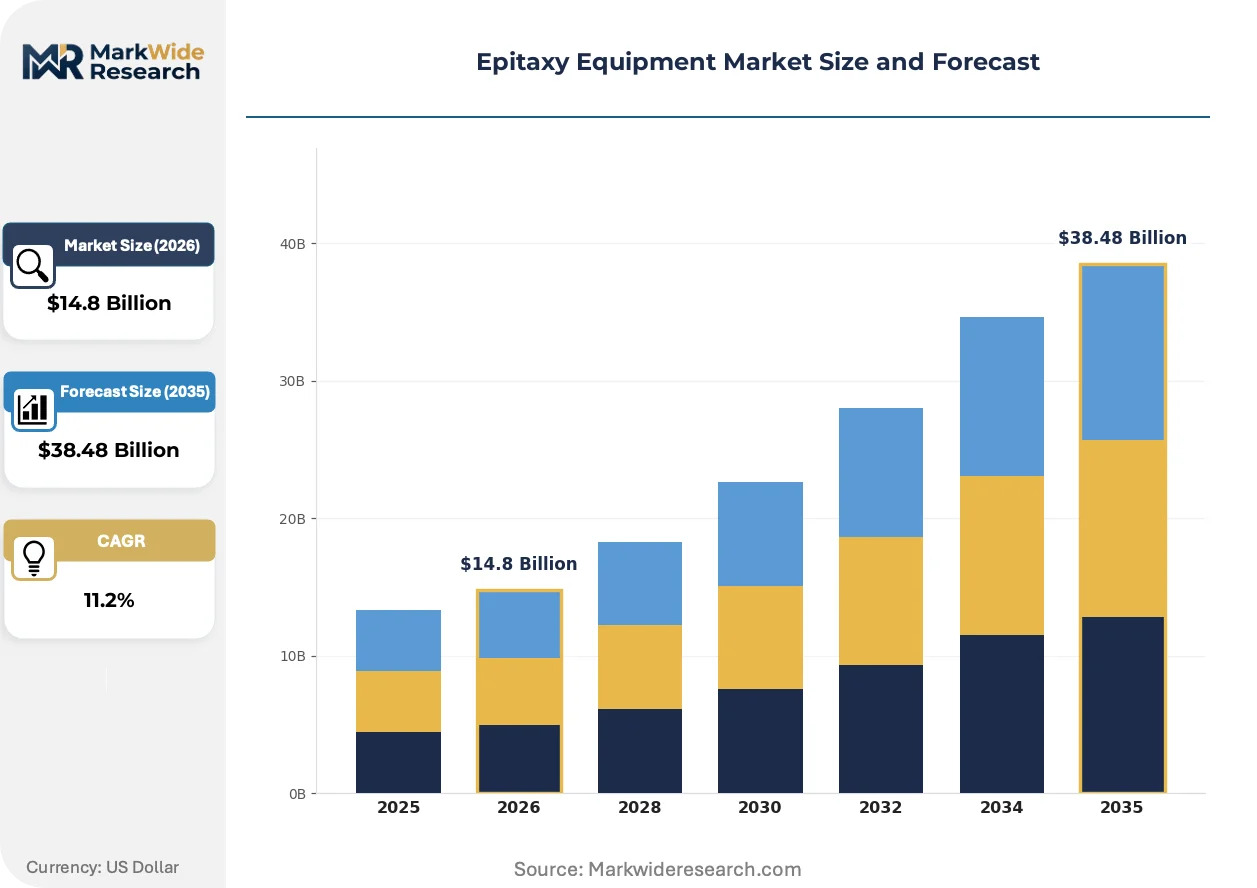
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $38.48 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Organic Chemical Vapor Deposition, Molecular Beam Epitaxy, Hydride Vapor Phase Epitaxy, Liquid Phase Epitaxy Technology: GaN, GaAs, SiC, InP Application: LEDs, Laser Diodes, Solar Cells, RF Devices End User: Semiconductor Manufacturers, Research Institutions, Universities, Device Fabricators |
| Companies Covered | Veeco Instruments, ASM International, Aixtron SE, NuFlare Technology, Taiyo Nippon Sanso, Applied Materials, LPE, Riber, Tokyo Electron Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Epitaxy Equipment Market Shifts & Advancements
Atomic-scale deposition control is converging with real-time metrology integration, enabling closed-loop process adjustment that was previously confined to research environments. Equipment vendors are racing to commercialize these capabilities for high-volume manufacturing.
Hybrid epitaxy platforms combining metal organic chemical vapor deposition with in-situ monitoring via reflectometry and ellipsometry are converging with machine learning-based recipe optimization. Automotive qualification teams at tier-one power module suppliers are adopting these systems to compress development cycles from 18 months to under 9 months. The technology is converging with high-volume manufacturing requirements by enabling predictive maintenance that reduces unplanned downtime in 24/7 foundry operations.
The US EPA hazardous chemical handling protocols for organometallic precursors are tightening manifest documentation and secondary containment requirements for deposition tool installations. Equipment purchasers must now budget 15-20% additional facility infrastructure for precursor storage and abatement systems. Power electronics foundries in Texas and Arizona are responding by consolidating precursor supply agreements with certified chemical handlers to streamline compliance.
After-sales service contracts are unbundling from initial equipment purchases as foundry operators seek to internalize routine maintenance while outsourcing only specialized chamber rebuilds. Japanese and Taiwanese power device manufacturers are leading this shift, negotiating à la carte spare parts pricing rather than comprehensive service agreements. The pattern is most visible in silicon carbide epitaxy operations where process intellectual property sensitivity discourages external technician access to chamber configurations.
Epitaxy Equipment Market Segmentation

Epitaxy equipment purchasing patterns diverge sharply between high-throughput manufacturing and precision research applications. Tool configuration, precursor handling, and service contract structures vary substantially across these divides, forcing vendors to maintain parallel product architectures.
Product Type:
Volume manufacturing favors throughput-optimized platforms while premium positioning attaches to atomic-precision systems with limited wafer capacity.
- Metal Organic Chemical Vapor Deposition:Batch reactor systems deposit compound semiconductor layers using organometallic precursors at atmospheric or reduced pressure. LED and power electronics foundries in Taiwan and China deploy these for 24/7 production cycles where wafer-per-hour metrics dominate procurement decisions.
- Molecular Beam Epitaxy:Ultra-high-vacuum systems evaporate elemental sources onto heated substrates with sub-monolayer thickness control. Defense contractors and quantum research laboratories in the US and Germany specify these for heterostructure devices where interface purity determines device yield.
- Hydride Vapor Phase Epitaxy:Chloride-transport systems achieve rapid growth rates for thick GaN or SiC layers. Device fabricators targeting high-voltage power modules use this for drift region formation where epitaxial thickness exceeds ten micrometers.
- Liquid Phase Epitaxy:Melt-based growth from saturated solutions produces crystalline layers at lower thermal budgets. Solar cell manufacturers and legacy optoelectronic suppliers maintain limited installations for specific alloy compositions.
Mature deployment sits with Metal Organic Chemical Vapor Deposition. Newer deployment is concentrated in Molecular Beam Epitaxy for quantum device prototyping.
Technology:
Material selection tracks end-use voltage requirements and frequency specifications, with wide-bandgap compounds commanding premium tool configurations.
- GaN:Gallium nitride epitaxy on silicon, sapphire, or SiC substrates enables high-electron-mobility transistors and power rectifiers. Fast-charging adapter manufacturers and 5G base station suppliers in South Korea and Japan are expanding GaN-on-silicon capacity for consumer price points.
- SiC:Silicon carbide homoepitaxy on 150mm and 200mm substrates forms the drift layers for traction inverters and grid infrastructure. Electric vehicle powertrain divisions at automotive tier-one suppliers in Germany and the US are qualifying SiC epitaxy platforms for 800V architectures.
- GaAs:Gallium arsenide remains entrenched in RF power amplifiers and infrared optoelectronics. Defense and satellite communication programs sustain demand despite slower growth relative to wide-bandgap alternatives.
- InP:Indium phosphide epitaxy serves datacenter optical interconnects and high-speed photodetectors. Transceiver manufacturers targeting 800G and 1.6T data rates are expanding InP capacity for integrated laser-modulator structures.
GaN is gaining share fastest in consumer power electronics. SiC maintains steepest expansion trajectory in automotive qualification pipelines.
Application:
End-use specifications determine reactor temperature uniformity requirements and wafer size compatibility, with automotive applications imposing the tightest process control standards.
- LEDs:Visible and ultraviolet light-emitting diode manufacturing consumes the largest installed base of metal organic chemical vapor deposition tools. Display backlighting and general illumination suppliers in China operate multi-reactor facilities with matched chamber configurations.
- RF Devices:High-frequency amplifiers and switches for telecommunications infrastructure require precisely controlled doping profiles. 5G macro base station and phased array radar programs are expanding GaN-on-SiC epitaxy capacity.
- Laser Diodes:Edge-emitting and vertical-cavity surface-emitting lasers for optical storage, sensing, and communication. Datacenter interconnect and lidar automotive sensing applications are expanding InP and GaAs laser epitaxy demand.
- Solar Cells:III-V multi-junction photovoltaics for space power and concentrator systems. Satellite manufacturers and terrestrial concentrator installations sustain limited but high-margin epitaxy requirements.
LED application segments show mature equipment saturation. RF Devices represent the fastest-climbing application category for new tool installations.
End User:
Procurement authority splits between integrated device manufacturers with captive epitaxy and merchant foundries serving fabless design houses.
- Semiconductor Manufacturers:Integrated device makers and pure-play foundries operating captive epitaxy lines for internal device fabrication. Power electronics divisions in Japan and automotive-qualified facilities in Germany dominate capital deployment for 200mm SiC platforms.
- Device Fabricators:Merchant suppliers purchasing epitaxial wafers from dedicated epi-houses or operating limited internal capacity. Fabless power semiconductor design houses in the US are consolidating supplier relationships with certified SiC epitaxy vendors.
- Research Institutions:National laboratories and corporate R&D centers developing next-generation material systems. US Department of Energy facilities and European quantum technology flagships maintain molecular beam epitaxy clusters for exploratory heterostructures.
- Universities:Academic materials science and electrical engineering departments training process engineers and investigating novel deposition chemistries. Doctoral programs in Taiwan and Switzerland operate shared-access epitaxy facilities for compound semiconductor education.
Semiconductor Manufacturers concentrate the highest-value tool purchases. Universities represent the entry point for equipment vendor relationship development.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gallium and indium precursor processing facilities in China concentrate raw material supply for epitaxy equipment feedstocks. Equipment demand clusters in East Asian semiconductor manufacturing corridors. Regulatory pressure on fabrication energy efficiency is accelerating tool replacement cycles across key production zones.
China
Domestic foundries are expanding 200mm SiC epitaxy capacity for electric vehicle inverters under Beijing's dual carbon goals. MEE emissions controls on fabrication facilities mandate low-power-consumption equipment retrofits. The Yangtze River Delta hosts multi-reactor metal organic chemical vapor deposition facilities serving LED and power electronics manufacturers.
Japan
Automotive tier-one suppliers are qualifying SiC epitaxy platforms for 800V traction systems. METI industrial policy supports compound semiconductor manufacturing infrastructure. The Kyushu region maintains concentrated vacuum pumping and quartzware supply chains for ultra-high-temperature epitaxy operations.
United States
Defense contractors and quantum research laboratories sustain molecular beam epitaxy demand for heterostructure devices. EPA hazardous chemical handling protocols tighten precursor storage requirements for deposition tool installations. Texas and Arizona power electronics foundries are consolidating precursor supply agreements with certified chemical handlers.
South Korea
5G base station suppliers and fast-charging adapter manufacturers are driving GaN-on-silicon capacity expansion. MFDS coordinates with industrial regulators on fabrication facility standards. Seoul Capital Area foundries operate high-throughput metal organic chemical vapor deposition tools for consumer price-point production.
Germany
Automotive powertrain divisions are qualifying SiC epitaxy platforms for next-generation inverter designs. ECHA REACH framework governs organometallic precursor registration across tool installations. Bavaria hosts precision epitaxy equipment service infrastructure serving automotive-qualified fabrication facilities.
Epitaxy Equipment Market Competitive Landscape
Global majors compete with regional champions across technology specialization and service proximity dimensions. Market structure consolidates around three to four dominant system architectures for high-volume manufacturing while fragmenting across niche research-grade configurations. Strategic archetypes include throughput-optimized batch reactor specialists, ultra-high-vacuum precision tool providers, and hybrid platform integrators combining deposition with in-situ metrology. Competitive moves center on unbundling after-sales service contracts and compressing automotive qualification cycles through predictive maintenance capabilities.
Within the precision research tier, Veeco Instruments and Riber exemplify ultra-high-vacuum system specialization. ASM International occupies a position among process control architecture providers for silicon carbide production. Aixtron SE sits within the GaN-on-silicon metal organic chemical vapor deposition segment serving power electronics foundries. These three represent distinct competitive positioning vectors across the equipment landscape.
| Leading Market Players |
|---|
| Veeco Instruments |
| ASM International |
| Aixtron SE |
| NuFlare Technology |
| Taiyo Nippon Sanso |
| Applied Materials |
| LPE |
| Riber |
| Tokyo Electron Limited |
| Others |
Supply & Pricing Matrix
Family-owned Japanese vacuum component specialists anchor critical supply nodes for ultra-high-temperature epitaxy operations, translating concentrated component sourcing into disciplined pricing power for batch reactor configurations while forcing foundry buyers into long-term service contracts.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium tool vendors from standard-tier competitors in epitaxy equipment procurement. Three-tier pricing structure across premium, standard, and economy levels tracks automation sophistication and chamber count, with automotive-qualified SiC platforms commanding substantial premiums over LED manufacturing equivalents. Cost compression in standard-tier metal organic chemical vapor deposition tools is intensifying because Chinese domestic vendors are qualifying competitive batch reactor designs. Merchant foundries exhibit highest price sensitivity due to capital constraint pressures, while integrated device manufacturers with captive epitaxy lines prioritize qualification speed over unit economics.
Supply Chain Analysis
Organometallic precursor supply rests on Chinese gallium and indium processing facilities, Japanese specialty gas purification operations, and German quartzware fabrication specialists. Advanced vacuum pumping systems, ultra-pure precursor materials, and vibration-isolation foundations constitute critical input dependencies. Single-source vulnerability concentrates in Japanese turbo-molecular pump manufacturers and German high-purity quartz suppliers. Distribution runs through direct vendor-fabricator relationships for high-value systems, with regional service subsidiaries handling spare parts logistics for installed base maintenance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The epitaxy equipment sector sits at a technology-transition inflection, with 200mm silicon carbide platforms displacing legacy 150mm configurations across automotive powertrain qualification pipelines.
For Market Incumbents: Hedge against Chinese domestic equipment vendor emergence by deepening backward integration into precursor supply agreements and accelerating predictive maintenance feature deployment. Threat vectors include Beijing's localization mandates for semiconductor fabrication equipment and margin compression from state-backed competitor financing. Priority levers center on automotive qualification cycle compression and unbundled service contract architectures that preserve high-margin chamber rebuild revenue. For New Entrants and Emerging Players: Launch via photonic integrated circuit equipment specialization targeting indium phosphide epitaxy for 800G datacenter transceiver manufacturing. India's compound semiconductor production-linked incentive scheme offers the most penetrable geography for establishing local service infrastructure. Go-to-market positioning should emphasize rapid recipe transfer capabilities and compressed installation timelines relative to incumbent lead times. For Investors and Strategic Acquirers: Distressed-cycle entries favor molecular beam epitaxy specialists with established US defense contractor relationships and European quantum research laboratory installations. Long-term viability framing favors equipment vendors with dual-use technology applicability spanning commercial power electronics and classified heterostructure device programs. Watch SiC substrate diameter transition completion as inflection indicator for 200mm epitaxy platform demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Automotive Qualification Acceleration | Compresses SiC epitaxy platform validation from 18 months to under 9 months for Tier 1 suppliers. |
| Predictive Maintenance Integration | Enables machine learning-based chamber condition monitoring for 24/7 foundry uptime optimization. |
| Precursor Supply Consolidation | Streamlines EPA hazardous chemical handling compliance for Texas and Arizona power electronics facilities. |
| Photonic Equipment Category Development | Captures indium phosphide epitaxy demand from 800G and 1.6T optical transceiver manufacturers. |
| Regional Service Infrastructure Expansion | Supports India's compound semiconductor fabrication incentive scheme with local technical presence. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews spanning epitaxy process engineers, automotive power module procurement leads, semiconductor fabrication facility managers, and precursor chemical supply specialists. Bottom-up triangulation against top-down equipment shipment validation employed SEC filings from publicly traded tool vendors, EPA hazardous chemical handling protocol documentation, and MEE emissions control filings from Chinese fabrication facilities.
Data-stream reconciliation across shipment volumes, installed base estimates, and capital expenditure disclosures generated segmentation-level projections over the analysis window. Modeled dimensions encompassed product type, material technology, application end-use, and end-user procurement authority. CAGRs derived from historical equipment replacement cycles, substrate diameter transition timelines, and automotive electrification penetration assumptions. Forecast inputs incorporated SiC epitaxy platform qualification pipelines and GaN-on-silicon capacity expansion announcements from fast-charging adapter manufacturers.
The model assumes a particular technology adoption path; alternative pathways for molecular beam epitaxy commercialization in quantum device manufacturing would alter the outlook. Forecasts reflect substrate diameter transition completion rates, automotive powertrain electrification cadence, and Chinese domestic equipment vendor qualification progress as core assumptions. A small set of named triggers—SiC substrate yield improvements, EPA precursor handling protocol amendments, and India's fabrication incentive disbursement velocity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Lithography Systems Market
Semiconductor Equipment
Global Tamping Machine Market
Semiconductor Equipment
Photolithography Equipment Market
Semiconductor Equipment
Electron Beam Lithography Machine Market
Semiconductor Equipment
Lithography Equipment Market
Semiconductor Equipment
Automatic Dicing Saw Market
Semiconductor Equipment
Vacuum Chambers Market
Semiconductor Equipment
Chip Probing Market
Semiconductor Equipment
FOUP Load Port Market
Semiconductor Equipment
Semiconductor Wafer Fab Equipment (WFE) Market
Semiconductor Equipment
Global Soldering Equipment Market
Semiconductor Equipment
Temperature Calibration Equipment Market
Semiconductor Equipment
Global Semiconductor Coolers Market
Semiconductor Equipment
Semiconductor Capital Equipment Market
Semiconductor Equipment
I-Line Lithography Market
Semiconductor Equipment
DUV Lithography Systems Market