
 Smart Power Strips Market | 2026-2036
Smart Power Strips Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Power Strips Market Intelligence
China is reshaping upstream manufacturing dynamics for smart power strips through expanded PCB assembly and IoT module capacity in Shenzhen and Dongguan. APC by Schneider Electric leverages its integrated electrical distribution portfolio to anchor premium positioning across European commercial channels. TP-Link competes aggressively on Wi-Fi chipset integration, sustaining cost leadership in residential smart home ecosystems. Belkin International specializes in USB-C power delivery architectures, differentiating its product line against commodity surge protectors.
Smart power strips are intelligent electrical distribution devices incorporating microcontrollers, relay switches, and communication modules to enable remote switching, energy metering, and load scheduling across multiple outlets; they typically support 120V to 240V input ranges with 15-20A circuit protection and integrate Hall-effect sensors for real-time current monitoring. Their primary purpose is to reduce standby power consumption and enable automated load control in connected buildings. The Wi-Fi technology segment leads volume due to router ubiquity and zero-hub installation, while Zigbee is gaining traction in commercial deployments where mesh reliability and sub-gigahertz penetration matter. USB Hub product types capture elevated margins as device proliferation drives integrated charging demand, and the Energy Management application anchors industrial procurement decisions.
The US Department of Energy enforces standby power limits through appliance efficiency standards, while the EU Ecodesign Directive and CE marking requirements shape product compliance costs for market access. China's GB standards and MIIT radio transmission certifications add layer complexity for imported connectivity modules. Stakeholders must monitor evolving cybersecurity mandates for networked energy devices as regulatory scope expands beyond efficiency into data protection and grid interconnection protocols.
Market Dynamics
Commercial real estate sustainability mandates are forcing facilities managers to seek granular energy visibility through networked power distribution, compressing procurement cycles and elevating specification standards across building automation retrofits.
Growth Catalysts
- EU Ecodesign Directive:Tightening standby power thresholds under EN 50564 are compelling office building operators to replace conventional surge protectors with metered strips.
- Building automation retrofits:Germany's commercial real estate sector is concentrating procurement pull through sustainability-linked loan covenants requiring sub-circuit monitoring.
- Wi-Fi chipset integration:Router ubiquity enables zero-hub installation, collapsing deployment friction for residential and small commercial adopters.
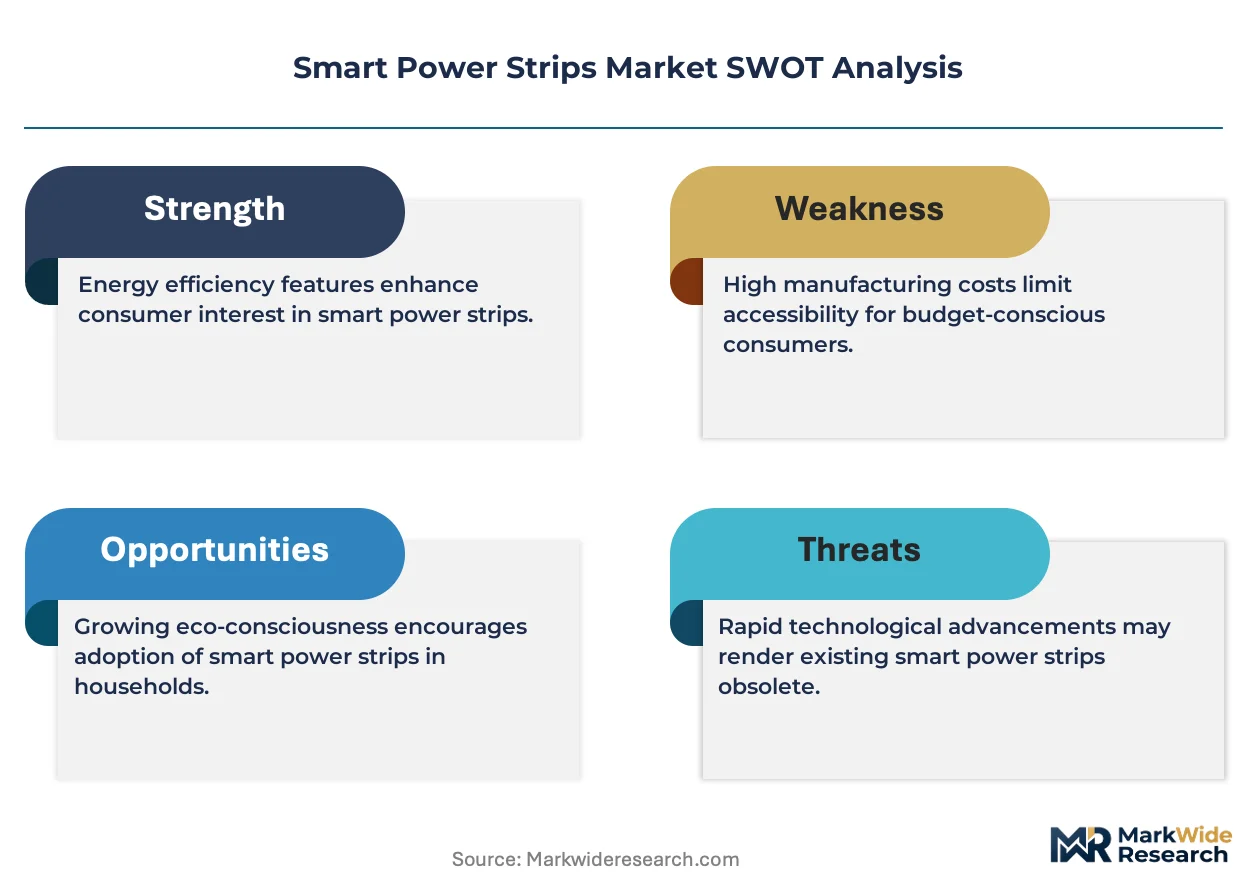
Market Restraints
- PCB assembly concentration:Shenzhen and Dongguan supply chains create geographic vulnerability for microcontroller and relay module sourcing.
- Radio certification layering:China's MIIT transmission approvals and GB standards add compliance cost and timeline uncertainty for imported connectivity modules.
- Hub-based alternatives:Dedicated building management systems with hardwired metering are substituting strip-level intelligence in new construction.
Strategic Opportunities
- USB-C power delivery convergence:Device proliferation is creating elevated-margin demand for integrated charging architectures alongside outlet control.
- Industrial energy management:Manufacturing facilities with ISO 50001 certification are specifying sub-metered strips for load scheduling and demand response.
- Mesh networking adoption:Zigbee's sub-gigahertz penetration is opening commercial deployments where Wi-Fi reliability fails.
Industry Challenges
- Cybersecurity compliance expansion:Networked energy devices face emerging data protection mandates beyond traditional efficiency regulations.
- Legacy electrical infrastructure:Aging panel configurations in commercial buildings complicate Hall-effect sensor calibration and neutral wire access.
- Skill fragmentation:Facilities teams lack cross-training between IT networking and electrical code compliance for integrated deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Power Strips Market |
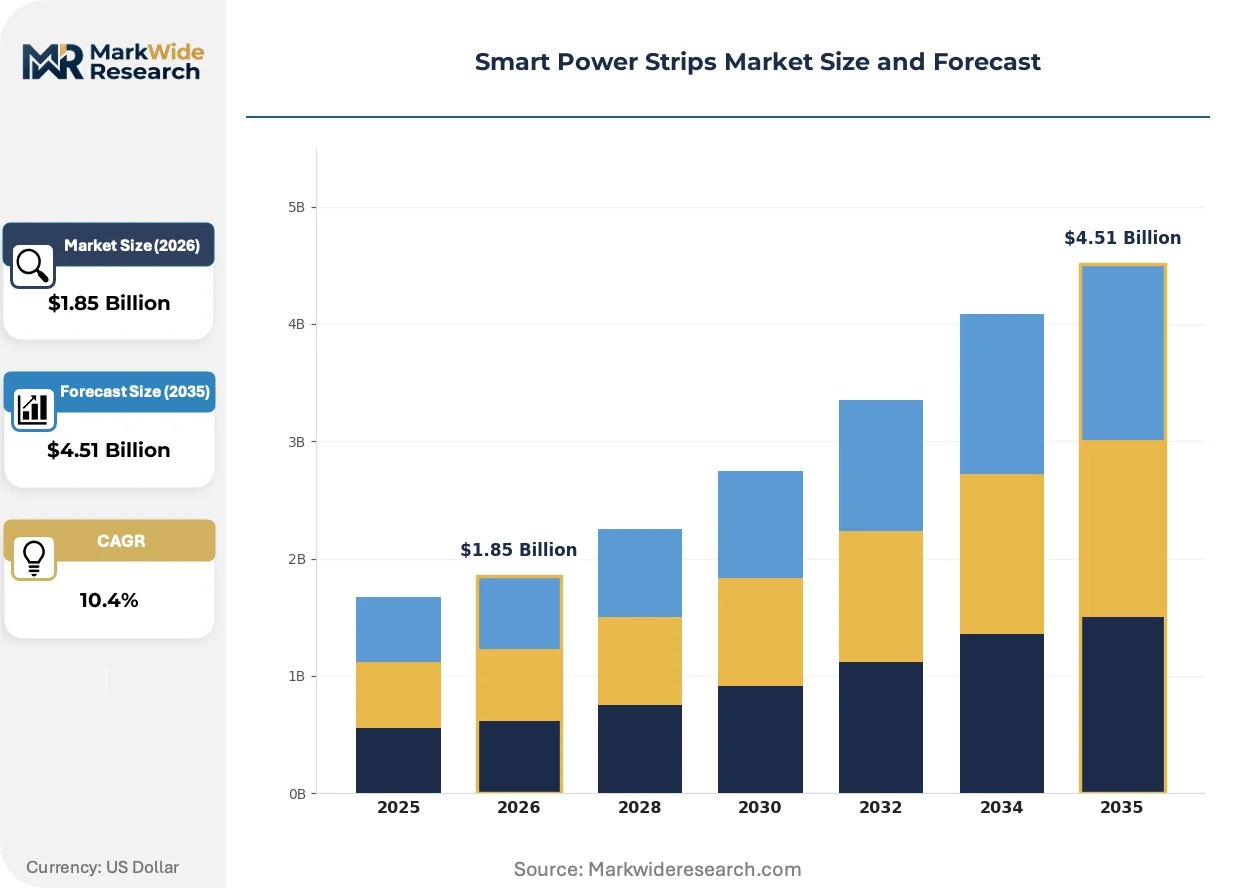
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.51 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surge Protector, Timer, Wireless, USB Hub End User: Residential, Commercial, Industrial, Educational Technology: Wi-Fi, Bluetooth, Zigbee, Z-Wave Application: Energy Management, Home Automation, Device Charging, Smart Homes |
| Companies Covered | CyberPower Systems, APC by Schneider Electric, TP-Link, Eve Energy, Eaton Corporation, Schneider Electric, Tripp Lite, Roku, Belkin International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Power Strips Market Strategic Shifts & Innovations
Edge computing integration is compressing the latency between power measurement and automated response, enabling real-time load shedding without cloud dependency. This shift is redrawing competitive boundaries between electrical hardware vendors and software-defined energy platforms.
GaN (gallium nitride) power semiconductors are reducing heat dissipation in compact multi-outlet enclosures. Premium residential and commercial buyers are specifying these architectures for high-density charging configurations. Silicon-based legacy designs are rendering obsolete in applications above 65W per port.
The EU AI Act's risk classification framework is extending to networked building devices with automated decision capabilities. Manufacturers must document algorithmic transparency for load-scheduling logic. German commercial channels are demanding CE-marked cybersecurity attestations alongside traditional safety certifications.
Subscription-based energy analytics are displacing hardware-only transactions in enterprise procurement. Facilities management firms in the United States are bundling strip hardware with ongoing monitoring services. This preference shift compresses upfront capital outlays while locking in multi-year vendor relationships.
Smart Power Strips Market Segmentation
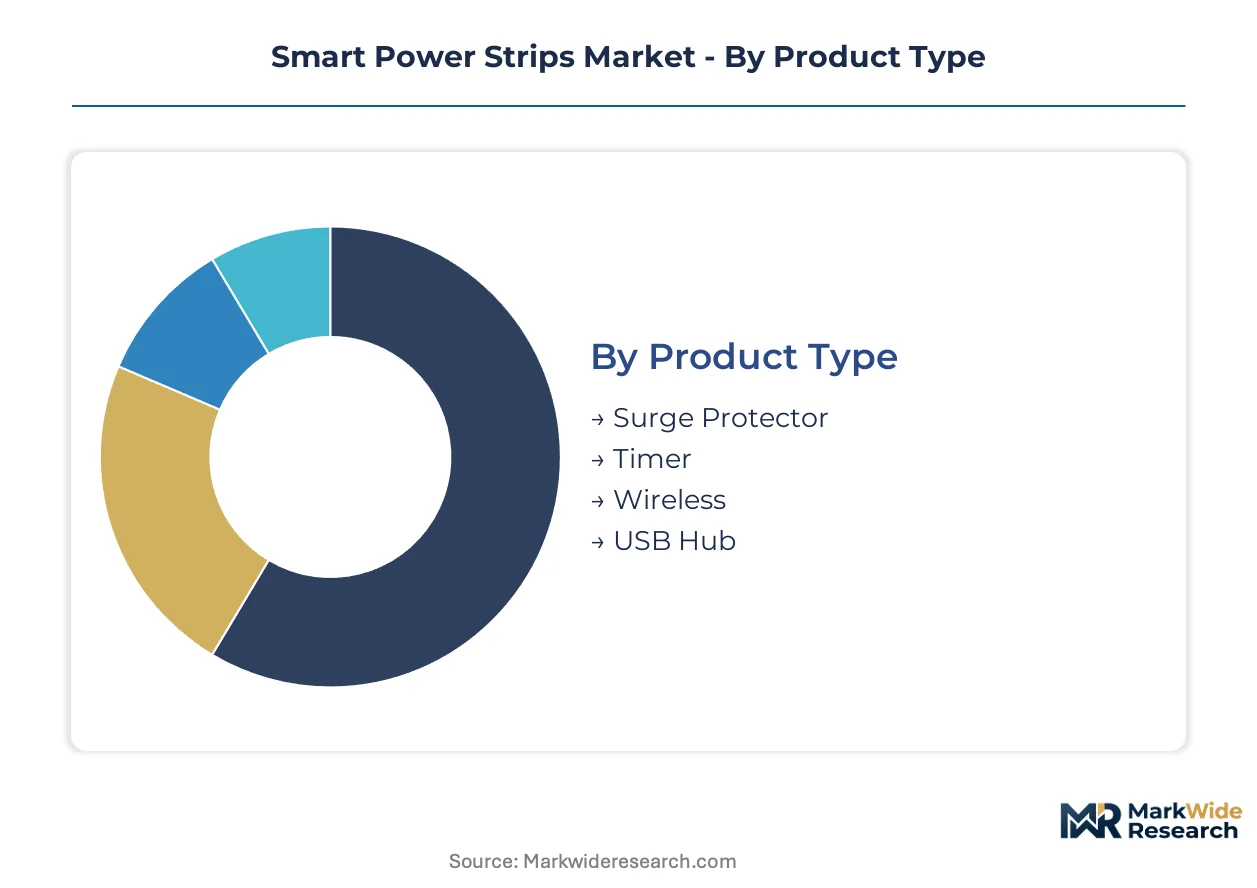
Smart power strip segmentation reveals divergent replacement cycles across product architectures, with consumer-facing electronics turning over every 3-4 years while industrial metering installations persist for 7-10 years. Procurement patterns fragment sharply between residential impulse purchases and commercial specification-driven tenders.
Product Type:
USB Hub variants refresh fastest as charging standards evolve, while Timer-based strips exhibit the longest replacement cycles due to simpler electromechanical construction.
- USB Hub:Integrated USB-C power delivery circuits with GaN semiconductors support 65W-100W per-port output in compact enclosures. German commercial real estate retrofits specify these for workstation densification under sustainability-linked loan covenants.
- Surge Protector:Metal-oxide varistor arrays with joule ratings from 1000-4000J protect sensitive electronics. Residential channels in the United States favor these for home office setups following FCC guidance on equipment protection.
- Timer:Electromechanical or digital relay scheduling enables automated load cycling. Agricultural and light industrial users deploy these for irrigation and ventilation control.
- Wireless:Inductive or resonant charging pads eliminate cable clutter. Premium residential segments in Japan adopt these for aesthetic integration with minimalist interiors.
Surge Protector anchors the volume base while USB Hub gains share at the steepest rate.
End User:
Cost tier stratification separates budget residential units from certified industrial equipment with sub-metering accuracy requirements.
- Commercial:Facilities managers specify metered strips with Hall-effect sensors achieving ±1% accuracy for ISO 50001 compliance. Germany's building automation retrofits concentrate procurement through sustainability mandates.
- Residential:Wi-Fi-enabled units with smartphone control dominate mass-market channels. TP-Link and Belkin compete on router integration and voice assistant compatibility.
- Industrial:Hardened enclosures with IP ratings and surge withstand capacity serve manufacturing floors. Demand concentrates in automotive and electronics assembly plants with demand response programs.
- Educational:Lockable outlet covers and tamper-resistant designs address safety requirements in K-12 environments. Bulk procurement through municipal purchasing cooperatives compresses margins.
Residential commands the shipment volume while Commercial expands most quickly on energy visibility mandates.
Technology:
Volume concentration favors Wi-Fi for its zero-hub deployment, though mesh alternatives penetrate where building materials attenuate signals.
- Wi-Fi:2.4GHz and 5GHz radio modules integrate directly with existing infrastructure. Router ubiquity eliminates gateway costs for residential and small commercial adopters.
- Zigbee:Sub-gigahertz mesh networking penetrates concrete and steel construction where Wi-Fi fails. Commercial building automation systems in Germany specify these for reliability.
- Bluetooth:Low-energy protocols enable phone-proximity control without internet dependency. Short range limits deployment to personal workspace configurations.
- Z-Wave:Proprietary sub-GHz mesh with mandatory interoperability certification. North American smart home ecosystems favor this for security system integration.
Wi-Fi anchors the volume base while Zigbee climbs the fastest on commercial mesh adoption.
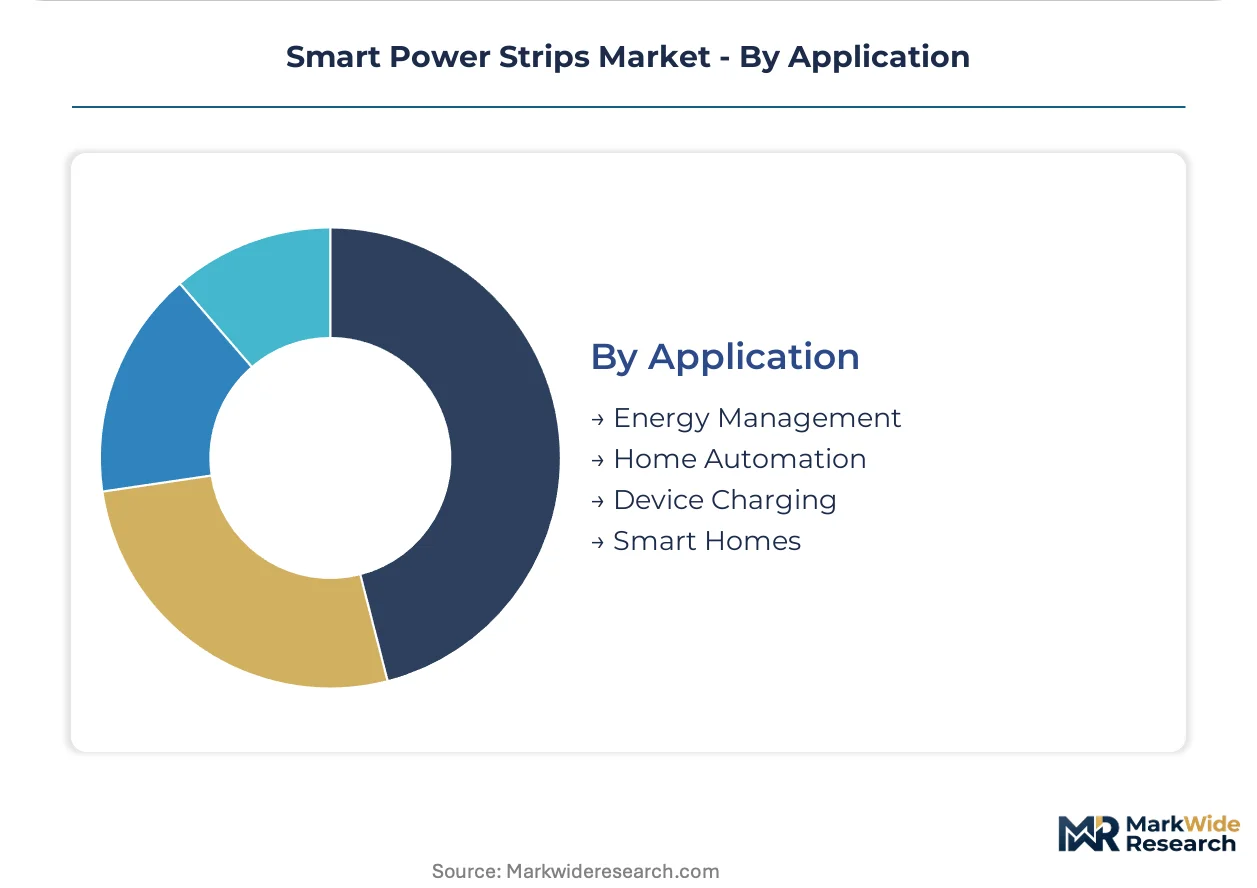
Application:
Margin structure elevates energy management platforms with recurring analytics subscriptions above hardware-only home automation transactions.
- Energy Management:Real-time metering with cloud dashboards and automated load shedding. Industrial ISO 50001-certified facilities specify these for demand response participation.
- Smart Homes:Voice assistant integration and scene programming for residential convenience. Amazon Alexa and Google Home compatibility drives specification.
- Home Automation:Scheduled switching and conditional logic for lighting and appliance control. Entry-level Wi-Fi strips serve this use case.
- Device Charging:Per-port power negotiation and cable elimination. USB-C PD convergence drives premium positioning in consumer electronics retail.
Smart Homes anchors the volume base while Energy Management gains share fastest on enterprise subscription bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Microcontroller and relay module sourcing clusters in Shenzhen and Dongguan create geographic vulnerability for manufacturers worldwide. Germany's building automation retrofit wave concentrates procurement pull through sustainability-linked loan covenants. The United States and Japan anchor demand for premium charging architectures and edge-computing integration.
United States
Facilities management firms bundle strip hardware with subscription-based energy analytics, compressing upfront capital outlays. The Department of Energy enforces standby power limits through appliance efficiency standards while FERC oversees grid interconnection protocols for networked devices. California's commercial real estate sector leads sub-metering adoption under Title 24 building energy codes.
Germany
Sustainability mandates force facilities managers to seek granular energy visibility through networked power distribution. The EU Ecodesign Directive and EN 50564 standby power standards tighten efficiency thresholds for office equipment. Berlin-Brandenburg concentrates building automation retrofits where sustainability-linked loans require sub-circuit monitoring.
China
Expanded PCB assembly and IoT module capacity in Shenzhen and Dongguan reshapes upstream manufacturing dynamics. MIIT radio transmission certifications and GB standards add compliance layers for imported connectivity modules. Dongguan's electronics corridor supplies microcontroller and relay modules to assembly operations worldwide.
Japan
Premium residential segments adopt wireless charging pads for aesthetic integration with minimalist interiors. METI energy efficiency programs incentivize standby power reduction in commercial buildings. Tokyo's Kanto region concentrates smart home ecosystem development with voice assistant compatibility requirements.
South Korea
ISO 50001-certified manufacturing facilities specify sub-metered strips for demand response participation. The Seoul Capital Area drives industrial energy management procurement with automated load scheduling requirements. Busan-Ulsan's electronics assembly plants integrate Hall-effect sensors for real-time current monitoring.
Smart Power Strips Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in semiconductor and sensor supply. The vendor base stratifies across three tiers: diversified electrical conglomerates with distribution portfolios, consumer electronics brands with router integration capabilities, and charging specialists with power delivery architectures. Two dominant competitive moves reshape positioning: GaN semiconductor adoption for thermal management in compact enclosures, and subscription bundling of hardware with ongoing energy analytics services.
Among diversified electrical conglomerates, APC by Schneider Electric and Eaton Corporation exemplify the integrated distribution portfolio archetype. TP-Link occupies a position as a router-ubiquitous consumer electronics brand leveraging Wi-Fi chipset integration for zero-hub deployment. Belkin International anchors the charging specialist tier with USB-C power delivery convergence. These three patterns—system integration, connectivity ubiquity, and charging architecture—define the competitive vectors through which procurement decisions flow.
| Leading Market Players |
|---|
| CyberPower Systems |
| APC by Schneider Electric |
| TP-Link |
| Eve Energy |
| Eaton Corporation |
| Schneider Electric |
| Tripp Lite |
| Roku |
| Belkin International |
| Others |
Cost & Logistics Intelligence
The Shenzhen-Dongguan freight corridor's container rates directly compress margins for microcontroller and relay module shipments, amplifying price differentiation between GaN-equipped premium strips and silicon-based economy units while forcing procurement managers toward consolidated volume contracts.
Pricing Analysis
The EU Ecodesign Directive dictates the pricing tier structure across the European commercial channel, separating CE-marked metering strips with Hall-effect sensors from uncertified residential alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and GaN semiconductor inclusion. Cost compression in the economy tier is intensifying because Shenzhen PCB assembly capacity expansion feeds component oversupply. Educational bulk procurement through municipal cooperatives exhibits the highest price sensitivity, while German facilities managers under sustainability-linked loan covenants show the least.
Supply Chain Analysis
Extended payment terms from Dongguan assembly houses now stretch to 90-120 days, straining working capital for brands without supply-chain finance facilities. Manufacturing gravity centers on China, South Korea, and Taiwan for microcontroller fabrication and GaN wafer production. The supply chain draws from copper busbar, FR-4 substrate, and Hall-effect sensor inputs. Single-source vulnerability concentrates in Shenzhen IoT module suppliers under MIIT certification requirements. Distribution runs through electrical wholesale channels in commercial segments and consumer electronics retail in residential.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as subscription-based energy analytics displace hardware-only transactions, creating niche openings for software-defined platforms alongside legacy electrical distributors.
For Market Incumbents: Harden cybersecurity certification investment as the EU AI Act extends risk classification to networked building devices with automated load-scheduling logic. Deepen backward integration into GaN semiconductor sourcing to defend thermal management advantages against TP-Link's Wi-Fi cost leadership. Channel control through facilities management firm partnerships protects against Eaton Corporation's integrated distribution portfolio expansion.
For New Entrants and Emerging Players: Japan's premium residential wireless charging segment offers underpenetrated white space as aesthetic-driven minimalist interiors displace conventional outlet strips. Target ISO 50001-certified manufacturing facilities in South Korea's Seoul Capital Area for sub-metered industrial procurement. A voice-assistant-agnostic integration strategy bypasses Amazon Alexa and Google Home compatibility barriers that constrain Belkin and TP-Link positioning.
For Investors and Strategic Acquirers: USB-C power delivery specialists with GaN architectures and existing CE marking represent the priority acquisition archetype, as charging standard convergence accelerates replacement cycles. Long-term viability hinges on recurring revenue attachment rates rather than hardware shipment volume. Monitor FERC grid interconnection protocol evolution as the inflection signal for enterprise subscription bundling preference.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN Semiconductor Adoption | Reduces thermal dissipation in compact enclosures above 65W per-port output thresholds. |
| Subscription Analytics Bundling | Locks multi-year vendor relationships with US facilities management firms seeking compressed capital outlays. |
| Cybersecurity Certification Investment | Addresses EU AI Act algorithmic transparency requirements for automated load-scheduling logic. |
| Mesh Networking Specification | Penetrates German commercial concrete and steel construction where Wi-Fi reliability degrades. |
| USB-C PD Convergence | Captures elevated margins as device proliferation drives integrated charging demand in consumer electronics retail. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with facilities managers, electrical contractors, and IoT platform engineers, and secondary validation through customs records, SEC filings from electrical conglomerates, and MIIT certification databases. The stakeholder set included building automation system integrators, procurement leads at commercial real estate firms, and Hall-effect sensor module suppliers. Bottom-up triangulation against top-down regulatory impact modeling anchored volume and value estimates.
Forecast inputs span technology adoption curves for Wi-Fi versus Zigbee, GaN semiconductor cost reduction trajectories, and EN 50564 standby power threshold enforcement timelines across the analysis window. Segmentation dimensions cover product architecture, end-user certification requirements, and regional regulatory cluster. CAGRs derive from installed base turnover rates and replacement cycle compression in USB Hub variants.
Macroeconomic conditions sit as an overlay; deviation in commercial construction lending rates and semiconductor capital expenditure cycles would shift the trajectory. Forecasts incorporate assumptions around EU Ecodesign Directive enforcement consistency and MIIT radio certification processing timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Global DC Power Supply Module Market
Power Systems
Silicon Carbide Power Devices Market
Power Systems
Electric Vehicle Inverter Market
Power Systems
Superconducting Magnet Systems Market
Power Systems
Linear Voltage Regulators Market
Power Systems
Shunt Capacitor Market
Power Systems
Battery Voltage Supervisor Market
Power Systems
Shunt Voltage References Market
Power Systems
MCR Based Static VAR Compensator Market
Power Systems
Electric Vehicle Power Inverter Market
Power Systems
Piezoelectric Energy Harvesting System Market
Power Systems
DC Stabilized Power Supply Market
Power Systems
Insulated Gate Bipolar Transistor (IGBT) Market
Power Systems
Solid-State Relay and Fuse Box Component Platforms Market
Power Systems
North America Micro Inverter Market
Power Systems
Global Next Generation Power Semiconductors Market