
 Pure Play Software Testing Market | 2026-2036
Pure Play Software Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Pure Play Software Testing Market Intelligence
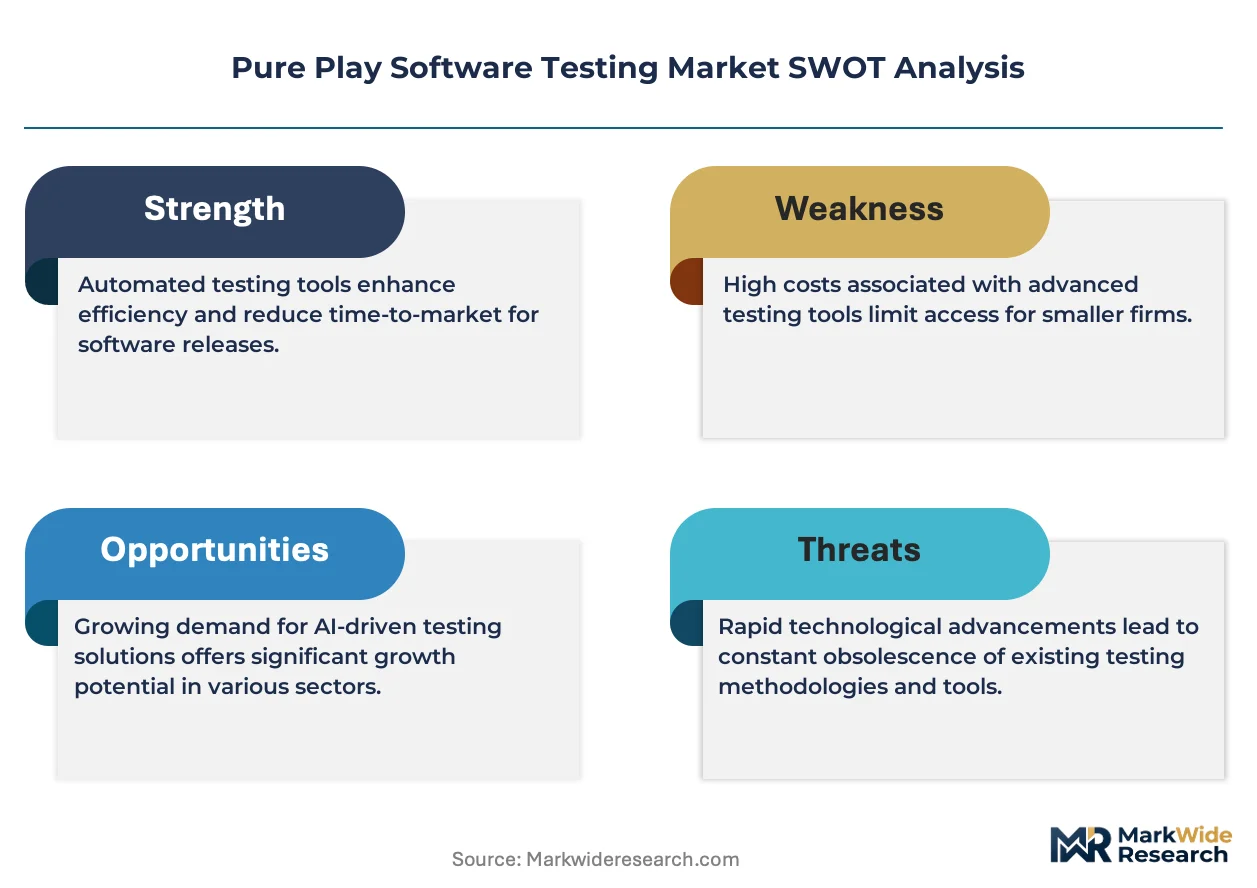
The chronic shortage of certified test automation engineers is unwinding traditional service delivery models across the industry. Qualitest Group leverages its AI-powered quality engineering platform to compete for complex enterprise contracts in regulated sectors. Cigniti Technologies Limited anchors its growth on specialized banking and insurance testing capabilities. DXC Technology Company extends its reach through embedded testing services within broader IT transformation programs.
Pure play software testing denotes independent, third-party quality assurance services that verify software functionality, performance, and security without concurrent development obligations, typically employing scripted automation frameworks, continuous integration pipelines, and synthetic user simulation to reduce defect escape rates below production thresholds. Functional testing retains the largest revenue share as legacy system modernization sustains steady demand, while security testing records the fastest expansion as DevSecOps mandates embed vulnerability scanning earlier in release cycles. Cloud-based deployment models attract the fastest-growing customer cohort, though on-premises solutions still dominate among defense and classified government end users.
FDA software validation requirements for medical devices, EU AI Act conformity assessments for high-risk automated systems, and ISO/IEC 25010 quality standards collectively elevate compliance-driven testing spend across regulated industries. These frameworks compel enterprises to maintain auditable test evidence trails, directly expanding contract values for independent verification services. Stakeholders must weigh specialization depth against platform breadth when allocating capital, as automation tooling commoditizes basic functional testing while premium margins migrate toward security certification and AI governance advisory.
Market Dynamics
AI-augmented test automation is decomposing traditional labor-intensive quality assurance models, forcing pure play vendors to restructure delivery architectures around synthetic test generation and autonomous defect detection rather than manual script maintenance.
Growth Catalysts
- EU AI Act conformity mandates:High-risk automated systems in European financial services require independent verification, expanding contract scopes for third-party testing providers serving algorithmic trading and credit scoring platforms.
- DevSecOps pipeline integration:Embedded security scanning within CI/CD workflows sustains demand for specialized penetration testing and vulnerability validation across cloud-native application deployments.
- Bengaluru-Hyderabad engineering density:India's technology corridors concentrate certified Selenium and Appium specialists, enabling cost-competitive delivery of complex automation frameworks for North American banking clients.
Market Restraints
- Certified automation engineer scarcity:Chronic shortages of ISTQB-Advanced Test Automation Engineers inflate wage costs and extend project onboarding timelines across all delivery geographies.
- Open-source tooling commoditization:Free frameworks including Cypress, Playwright, and Robot Framework compress margins on basic functional testing engagements.
- Defense sector on-premises lock-in:Classified government workloads resist cloud migration, requiring costly private infrastructure maintenance that limits scale economies.
Strategic Opportunities
- Medical device software validation:FDA 21 CFR Part 820 quality system regulations and IEC 62304 standards compel life sciences manufacturers to maintain auditable test evidence, expanding regulated-sector contract values.
- AI governance advisory services:Convergence of machine learning operations with quality engineering creates premium advisory revenue streams around model validation and bias detection protocols.
- Embedded testing in IT transformation:DXC Technology and systems integrators bundle verification services within broader modernization programs, opening channel partnerships for pure play specialists.
Industry Challenges
- ISO/IEC 25010 compliance timelines:Multi-month certification cycles for system quality-in-use metrics delay contract commencement and strain working capital.
- Legacy mainframe integration complexity:COBOL and assembler systems in banking cores resist automated test coverage, requiring hybrid manual-automation approaches that erode margin.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pure Play Software Testing Market |
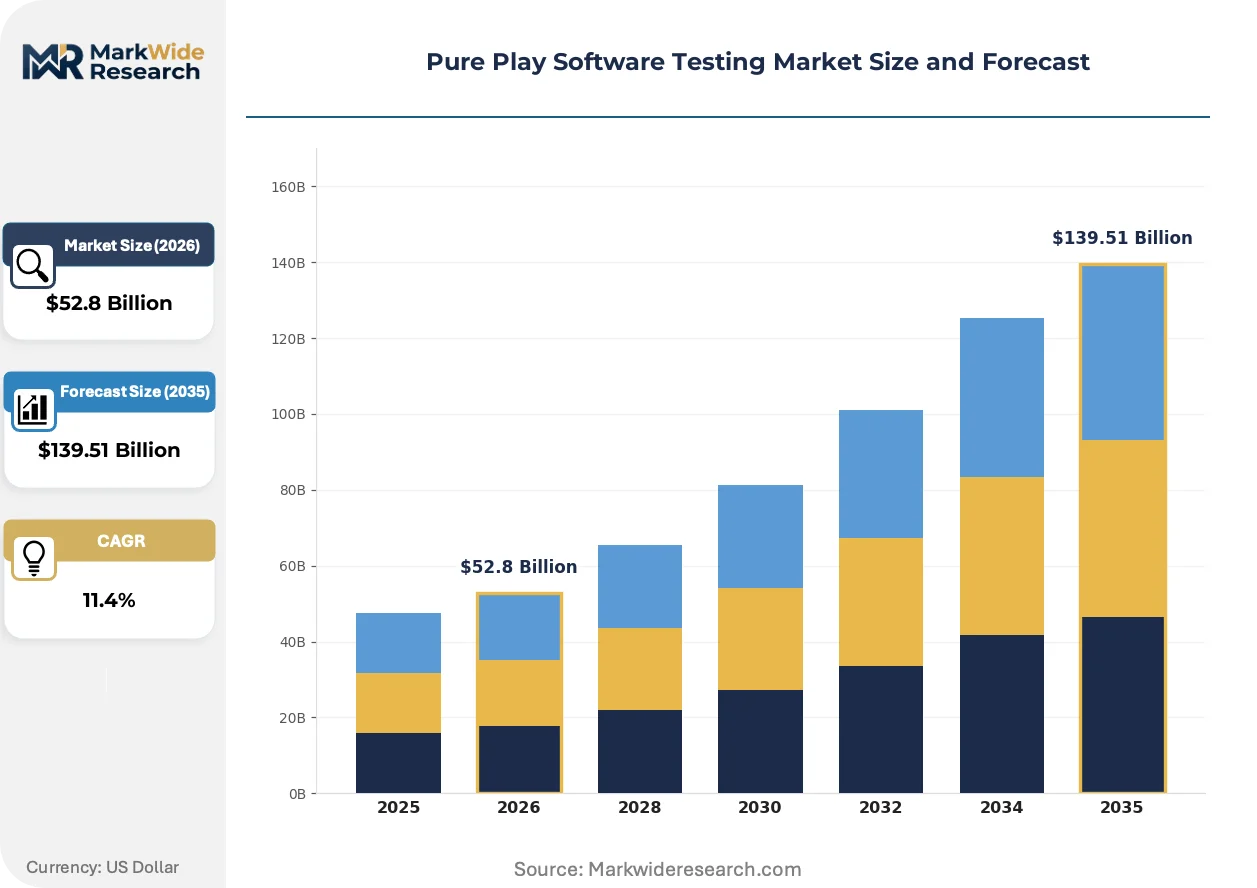
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $139.51 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Functional Testing, Performance Testing, Security Testing, Usability Testing Service Type: Automated Testing, Manual Testing, Continuous Testing, Mobile Testing End User: Enterprise, SMBs, Startups, Government Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS |
| Companies Covered | Qualitest Group, Cigniti Technologies Limited, a1qa, DXC Technology Company, Indium Software, Testhouse Ltd., Accenture plc, Capgemini SE, Wipro Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pure Play Software Testing Market Strategic Shifts & Innovations
Generative AI is compressing test script development cycles while regulatory mandates expand verification scope beyond functional correctness into algorithmic accountability and security posture.
Self-healing test automation is decomposing brittle maintenance overhead that previously consumed forty percent of quality engineering budgets. Banking and insurance buyers in North America are deploying these capabilities within three-month pilot-to-production cycles. The technology is decomposing traditional offshore delivery models by reducing the labor arbitrage advantage of low-cost engineering centers.
FDA software validation requirements for connected medical devices now explicitly address cybersecurity risk management per IEC 81001-5-1 guidance. Device manufacturers must submit documented evidence of threat modeling and penetration testing prior to 510(k) clearance. Neuromodulation and diagnostic imaging segments face the steepest compliance burdens, with sponsors contracting specialized testing houses to manage regulatory submission packages.
Enterprise buyers are unbundling quality assurance from development contracts, issuing standalone RFPs for independent verification services. Financial services procurement teams in the United States now mandate SOC 2 Type II attestation and FedRAMP authorization as baseline vendor qualifications. This certification-driven preference shift concentrates award decisions among testing specialists with pre-existing compliance infrastructure rather than generalist IT services firms.
Pure Play Software Testing Market Segmentation
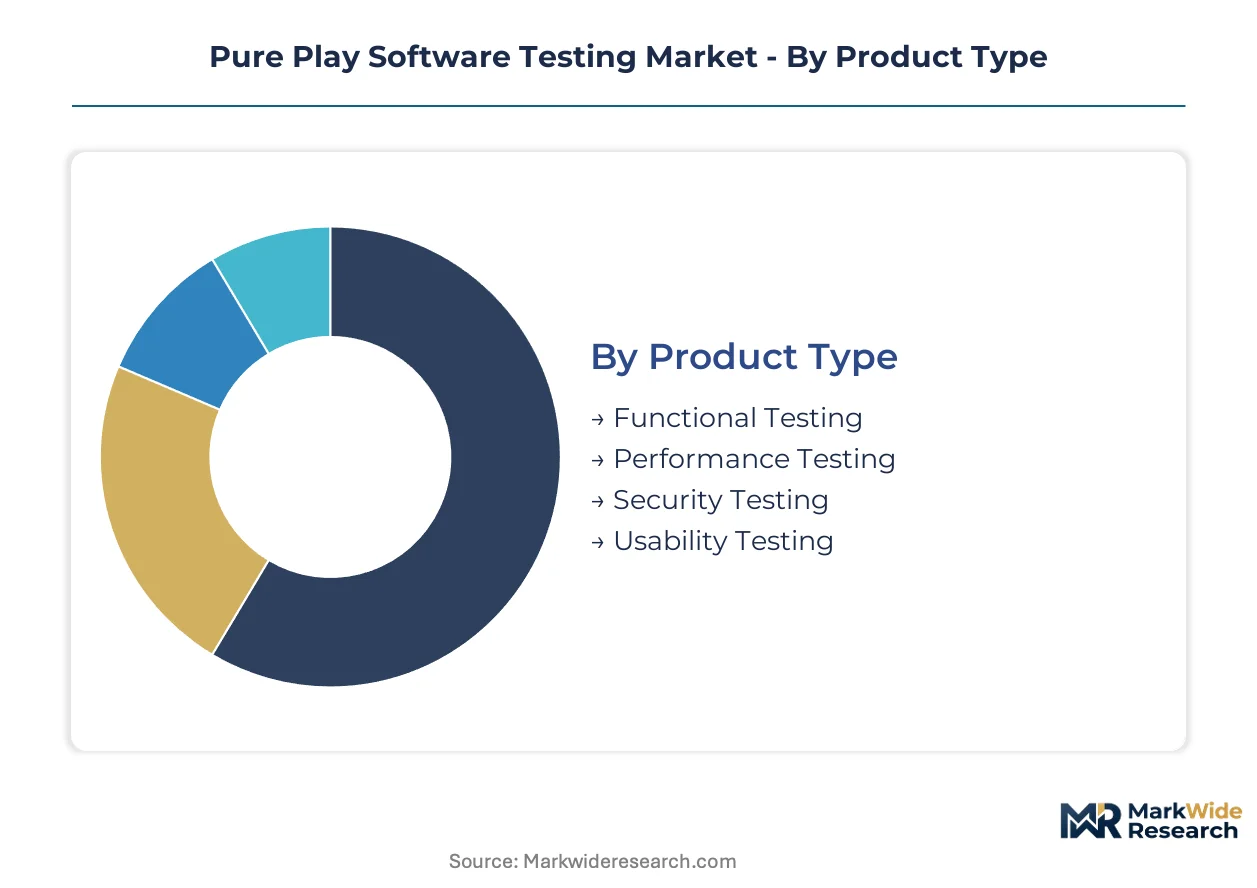
Segmentation in pure play software testing reveals how automation pressure and compliance mandates reshape contract economics across service categories. Testing buyers unbundle quality assurance from development contracts, creating distinct procurement channels for functional verification versus security certification versus performance validation.
Product Type:
Substitution pressure from open-source frameworks and self-healing automation tools compresses margins most severely in commoditized functional verification, while security and specialized testing retain pricing power through certification requirements.
- Functional Testing:Scripted and exploratory verification of business logic, API contracts, and user workflows against specified requirements. Banking core modernization in the United States and Germany sustains contract volumes as COBOL migration demands hybrid manual-automation coverage.
- Performance Testing:Load, stress, and scalability validation under simulated production traffic conditions. Algorithmic trading platforms in the United Kingdom and Singapore require sub-millisecond latency verification, driving specialized tooling investments.
- Security Testing:Penetration testing, vulnerability scanning, and threat modeling per IEC 81001-5-1 and FedRAMP mandates.
- Usability Testing:Synthetic user simulation and accessibility compliance validation against WCAG standards.
Functional testing retains volume leadership; security testing holds the steepest expansion curve.
Service Type:
Delivery cost tiers separate capital-intensive automation platform investments from labor-dependent manual execution, with continuous testing occupying the premium intersection of tooling and embedded expertise.
- Automated Testing:Selenium, Appium, and Playwright frameworks executing regression suites within CI/CD pipelines. India's Bengaluru corridor supplies certified engineers at cost-competitive rates for North American financial services clients.
- Continuous Testing:Shift-left validation integrated from commit through production deployment. DevSecOps mandates in EU financial services expand contract scopes for pipeline-embedded verification.
- Manual Testing:Exploratory and ad-hoc verification for legacy systems resisting automation.
- Mobile Testing:Device fragmentation coverage across iOS and Android form factors.
Automated testing dominates contract volume; continuous testing commands the highest per-engineer rates.
End User:
Customer maturity determines procurement sophistication, with regulated enterprises demanding auditable evidence trails that startups and smaller businesses bypass.
- Enterprise:Fortune 500 manufacturers and financial institutions with dedicated quality engineering budgets. FDA 21 CFR Part 820 compliance for medical device software validation sustains multi-year testing contracts.
- Government:Defense and classified workloads requiring on-premises infrastructure and FedRAMP authorization. SOC 2 Type II attestation serves as baseline vendor qualification.
- SMBs:Mid-market manufacturers adopting cloud-based testing to avoid capital expenditure.
- Startups:Venture-backed technology firms prioritizing speed over comprehensive coverage.
Enterprise clients generate the largest absolute contract values; government segments impose the most stringent qualification barriers.
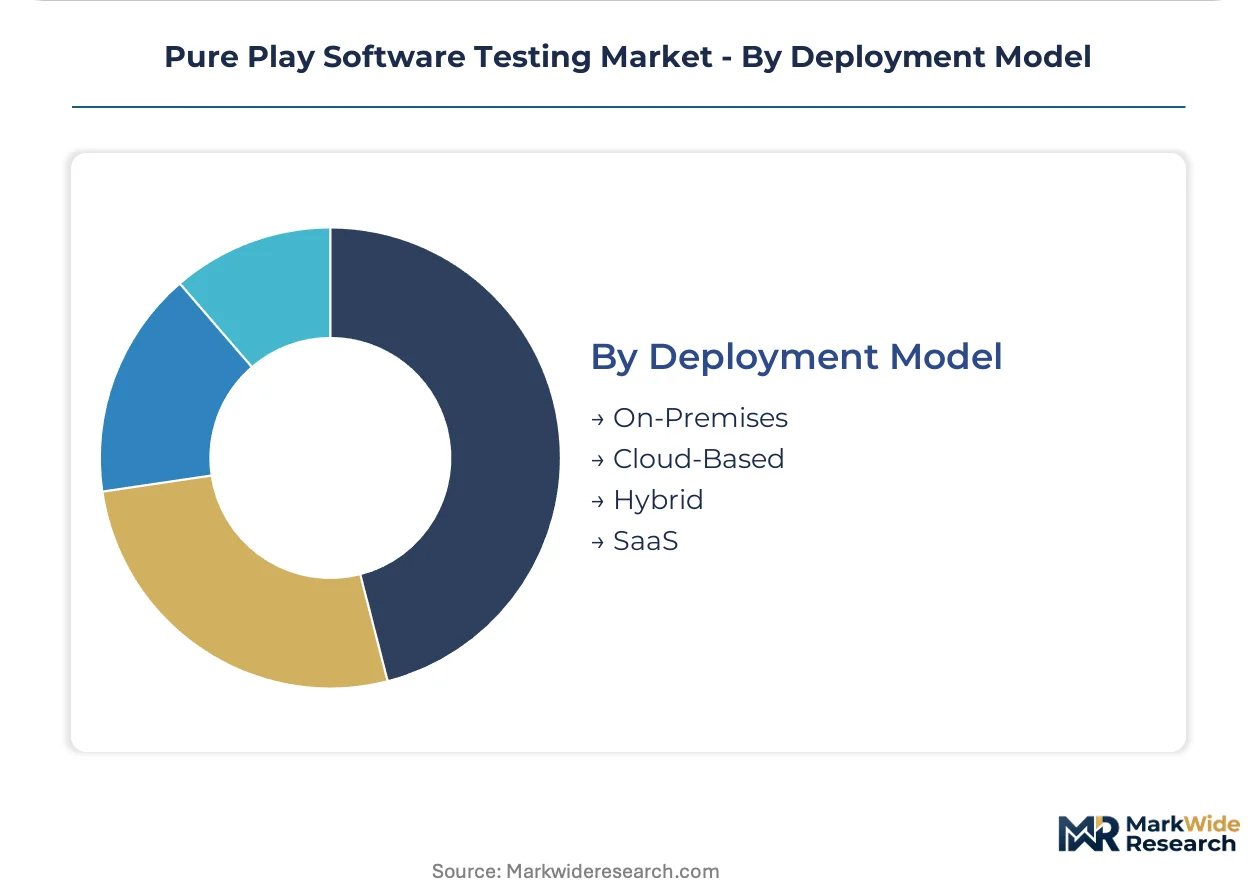
Deployment Model:
Supply concentration in hyperscale cloud infrastructure creates vendor lock-in risks that hybrid architectures attempt to mitigate.
- Cloud-Based:Elastic compute resources for burst testing capacity and parallel execution. SaaS-native delivery attracts the fastest-growing customer cohort among mid-market adopters.
- Hybrid:Sensitive test data remains on-premises while execution leverages cloud scalability. German automotive manufacturers favor this model for proprietary engineering data protection.
- On-Premises:Air-gapped environments for classified government and defense workloads.
- SaaS:Subscription-based access to pre-configured testing platforms with minimal implementation.
Cloud-based deployment gains share fastest; on-premises solutions retain dominance in defense and national security applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA software validation requirements for medical devices anchor the United States as the dominant geography, while EU AI Act conformity mandates reshape European procurement patterns for algorithmic systems. India's technology corridors supply certified engineering talent at scale for North American financial services clients.
United States
Financial services institutions in New York and Chicago drive adoption of AI-augmented test automation for algorithmic trading platforms. FDA 21 CFR Part 820 quality system regulations compel life sciences manufacturers to maintain auditable test evidence trails for 510(k) submissions. The Boston-Cambridge biotechnology cluster sustains multi-year testing contracts for connected medical device validation.
Germany
Automotive manufacturers in Stuttgart and Munich demand hybrid testing architectures for proprietary engineering data protection. EU AI Act conformity assessments for high-risk automated systems expand contract scopes for credit scoring platform verification. The Rhine-Ruhr industrial belt concentrates DevSecOps pipeline integration projects for cloud-native application deployments.
United Kingdom
Algorithmic trading platforms in London require sub-millisecond latency verification under simulated production traffic conditions. FCA conduct rules for AI-driven financial products mandate independent verification of model fairness and bias detection. The Thames Valley technology corridor hosts specialized penetration testing houses serving FTSE 100 insurance clients.
India
Bengaluru and Hyderabad host dense clusters of certified Selenium and Appium specialists serving Fortune 500 banking clients. RBI guidelines for IT governance in financial institutions elevate compliance-driven testing spend among domestic banks and non-banking financial companies. The Hyderabad Financial District anchors delivery centers for North American insurance and wealth management platform modernization.
Singapore
Wealth management platforms and digital banking licenses drive demand for continuous testing within CI/CD pipelines. MAS technology risk management guidelines mandate independent verification of system resilience and cybersecurity controls. The one-north technology precinct concentrates specialized testing engineers serving ASEAN regional headquarters of global financial institutions.
Pure Play Software Testing Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the pure play software testing landscape. The vendor base organizes into three tiers: global systems integrators with embedded testing practices, specialized pure play testing houses with deep sector expertise, and regional delivery specialists competing on engineering cost arbitrage. Dominant competitive moves include AI-powered platform investments that compress script development cycles and strategic partnerships with hyperscale cloud providers to secure preferred marketplace positioning.
Within the specialized pure play tier, Qualitest Group and Cigniti Technologies Limited exemplify archetypes competing for complex enterprise contracts in regulated sectors. DXC Technology Company occupies a position bridging systems integration and embedded testing services within broader IT transformation programs. These three anchors demonstrate how sector-specific certification infrastructure and pre-existing compliance frameworks concentrate award decisions among testing specialists rather than generalist IT services firms.
| Leading Market Players |
|---|
| Qualitest Group |
| Cigniti Technologies Limited |
| a1qa |
| DXC Technology Company |
| Indium Software |
| Testhouse Ltd. |
| Accenture plc |
| Capgemini SE |
| Wipro Limited |
| Others |
Cost & Logistics Intelligence
Self-healing automation tooling is displacing manual script maintenance as the dominant cost input, simultaneously compressing delivery economics in India's technology corridors and eroding the wage-arbitrage premium that previously anchored offshore pricing models.
Pricing Analysis
Hourly rates for certified Selenium engineers span a three-to-one range between Bengaluru delivery centers and onshore United States consulting teams. Three-tier pricing structure across premium security certification, standard functional automation, and economy manual testing segments reflects divergent compliance burdens. Price differentiation hinges on FedRAMP authorization status and ISO 27001 certification depth. Cost compression in economy-tier functional verification is intensifying because open-source Playwright and Cypress frameworks eliminate licensing friction. Startups exhibit the highest price sensitivity, while FDA-regulated medical device manufacturers accept substantial premiums for auditable evidence trails.
Supply Chain Analysis
Containerized shipping costs on the Asia-North America trade lane directly affect hardware provisioning for on-premises testing infrastructure deployments. Talent supply concentrates in India, Poland, and Vietnam, with each corridor feeding distinct buyer segments. Engineering delivery draws from certified ISTQB-Advanced pools, proprietary AI-augmented platforms, and hyperscale cloud compute reserves. Single-source vulnerability in Selenium specialist concentration creates disruption risk during demand surges. Distribution runs through direct enterprise sales teams, systems integrator partnerships, and cloud marketplace listings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise procurement teams are consolidating vendor relationships around pre-qualified testing specialists with embedded compliance infrastructure, shifting negotiation leverage toward buyers with multi-year contract volumes.
For Market Incumbents: Consolidate AI-powered platform investments to defend margin position against open-source tooling commoditization. Acquire boutique security certification specialists in the United Kingdom and Germany to deepen EU AI Act advisory capabilities. Channel control through embedded partnerships with DXC Technology and Accenture plc insulates against direct procurement unbundling. For New Entrants and Emerging Players: ISO 27001 fast-track certification opens regulated-sector contracts that generalist IT services firms cannot pursue. Target medical device software validation in the Boston-Cambridge corridor, where FDA 21 CFR Part 820 compliance creates qualification barriers. Go-to-market positioning as AI governance advisory specialists captures premium pricing unavailable to commoditized functional testing providers. For Investors and Strategic Acquirers: EU AI Act implementation reshapes the acquisition landscape toward algorithmic accountability verification capabilities. Long-term viability rests on regulatory compliance infrastructure rather than labor cost arbitrage. Acquisition target archetype: mid-cap specialists with pre-existing FDA and FedRAMP authorization. The signal to watch is Fortune 500 procurement mandating SOC 2 Type II attestation as a baseline vendor qualification.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Augmented Platform Investment | Self-healing automation compresses script development cycles for banking clients in New York. |
| Security Certification Acquisition | FedRAMP-authorized specialists command premium pricing in government contracting channels. |
| EU AI Act Advisory Service Launch | Conformity assessment mandates expand contract scopes for credit scoring platform verification. |
| Medical Device Validation Partnership | FDA 510(k) submission support sustains multi-year engagements with Boston biotechnology clusters. |
| Cloud Marketplace Integration | Hyperscaler listings reduce customer acquisition friction for mid-market SaaS testing adoption. |
Research Approach
A spread of perspectives from quality engineering directors, IT procurement officers, regulatory affairs leads at medical device manufacturers, and cloud platform integration specialists converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, FDA 510(k) submission databases, hyperscaler capex disclosures, and EU regulatory guidance documents. Bottom-up engineering headcount modeling and top-down contract value triangulation anchored volume estimates.
Segmentation dimensions modeled encompass deployment architecture, organization size tier, vertical regulatory intensity, service type complexity, and regional delivery cost structure. Growth trajectories across the projection horizon reflect adoption curve analysis for AI-augmented tooling, regulatory mandate expansion timelines, and labor supply elasticity in certified automation engineering pools. CAGRs derive from regression against historical contract value patterns and forward-looking procurement intention surveys.
Underlying assumptions cover regulatory enforcement consistency, cloud infrastructure cost trajectories, and certification pipeline throughput, with deviation risk concentrated in EU AI Act implementation timing and defense sector cloud migration policy shifts. Practitioners should keep alternative scenarios live as algorithmic accountability standards and cross-border data governance frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Sports Production Software Market
Software & Services
Trading Software Market
Software & Services
Tableau Services Market
Software & Services
Global Inside Sales Software Market
Software & Services
Global ITSM Software Market
Software & Services
Europe Pharmacy POS Software Market
Software & Services
Office Software Market
Software & Services
Towing Software Market
Software & Services
SAP Digital Services Ecosystem Market
Software & Services
Global Absence and Leave Management Software Market
Software & Services
Global Quoting Software Market
Software & Services
Global Help Desk Software Market
Software & Services
VFX Software Market
Software & Services
Collaboration Software Market
Software & Services
Automotive Design Software Market
Software & Services
Global Online OCR Software Market