
 Sports Production Software Market | 2026-2036
Sports Production Software Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Production Software Market Analytics
The United States is reshaping capacity in sports production software through heavy investment in cloud-native broadcast infrastructure and AI-enhanced live event tooling. Genius Sports leverages deep data integration to anchor its position across professional league partnerships. TeamSnap competes through specialized workflow automation for amateur and youth sports organizations. Stack Sports extends its reach via unified platform architecture spanning registration, scheduling, and video production.
Sports production software encompasses editing suites, streaming platforms, graphics engines, and analytics tools that ingest live audiovisual feeds and output broadcast-ready content with sub-second latency for television and digital distribution. These systems typically process 1080p to 4K HDR signals through SDI or IP-based pipelines, enabling real-time clipping, replay generation, and augmented overlay insertion for live sports consumption. Streaming platforms lead in growth velocity as direct-to-consumer broadcast models displace traditional linear distribution, while graphics creation tools occupy mature margin pools sustained by entrenched broadcaster relationships. Analysis software represents the fastest-expanding segment as coaching staffs and media rights holders demand predictive performance modeling.
The FCC mandates closed captioning, emergency alert compatibility, and spectrum allocation rules that directly constrain software architecture decisions for US-facing products. EMA and CE marking requirements in Europe impose additional clinical-grade data handling standards where athlete biometric monitoring intersects with production systems. ISO 27001 certification shapes vendor selection criteria for leagues handling sensitive competitive intelligence. Stakeholders must monitor how fragmented national broadcast regulations will force modular compliance architectures versus unified global product builds.
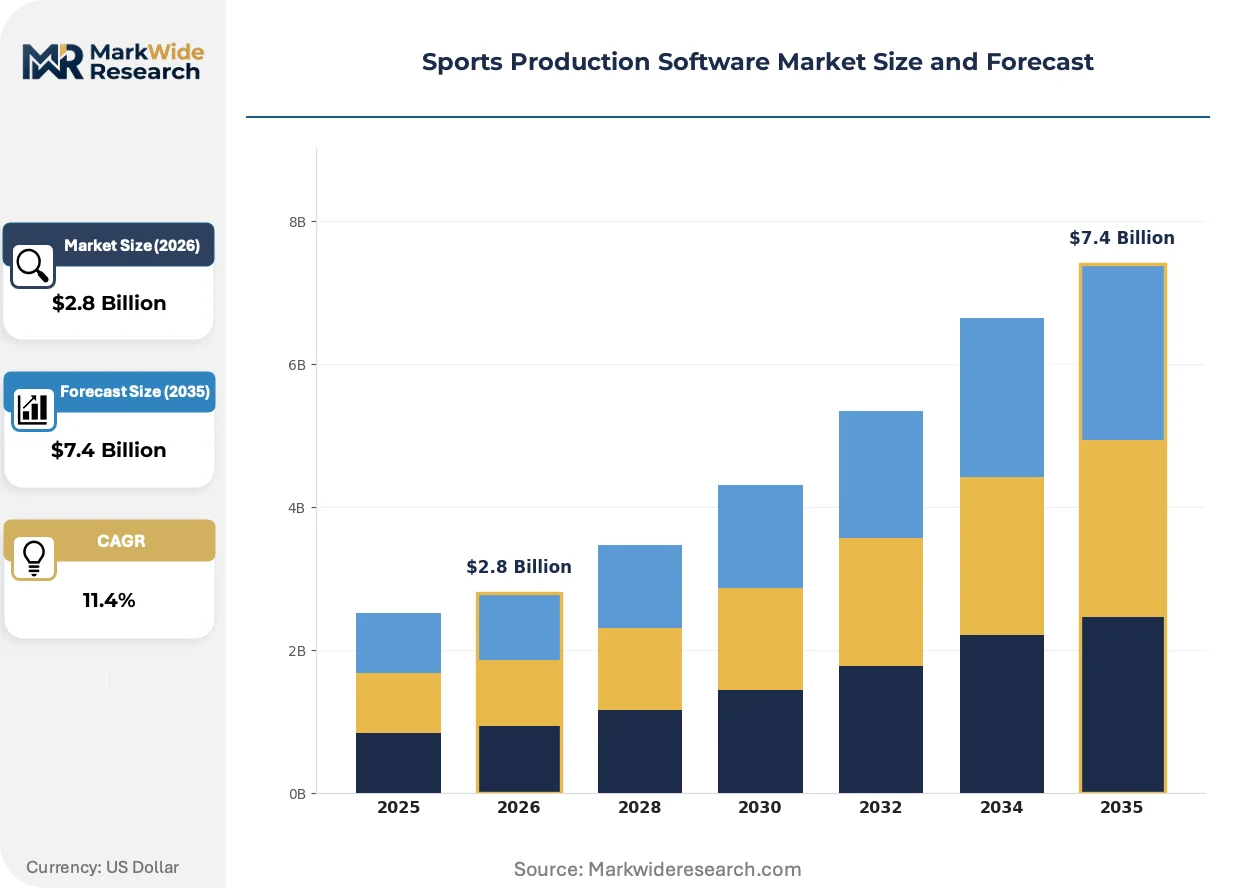
Market Dynamics
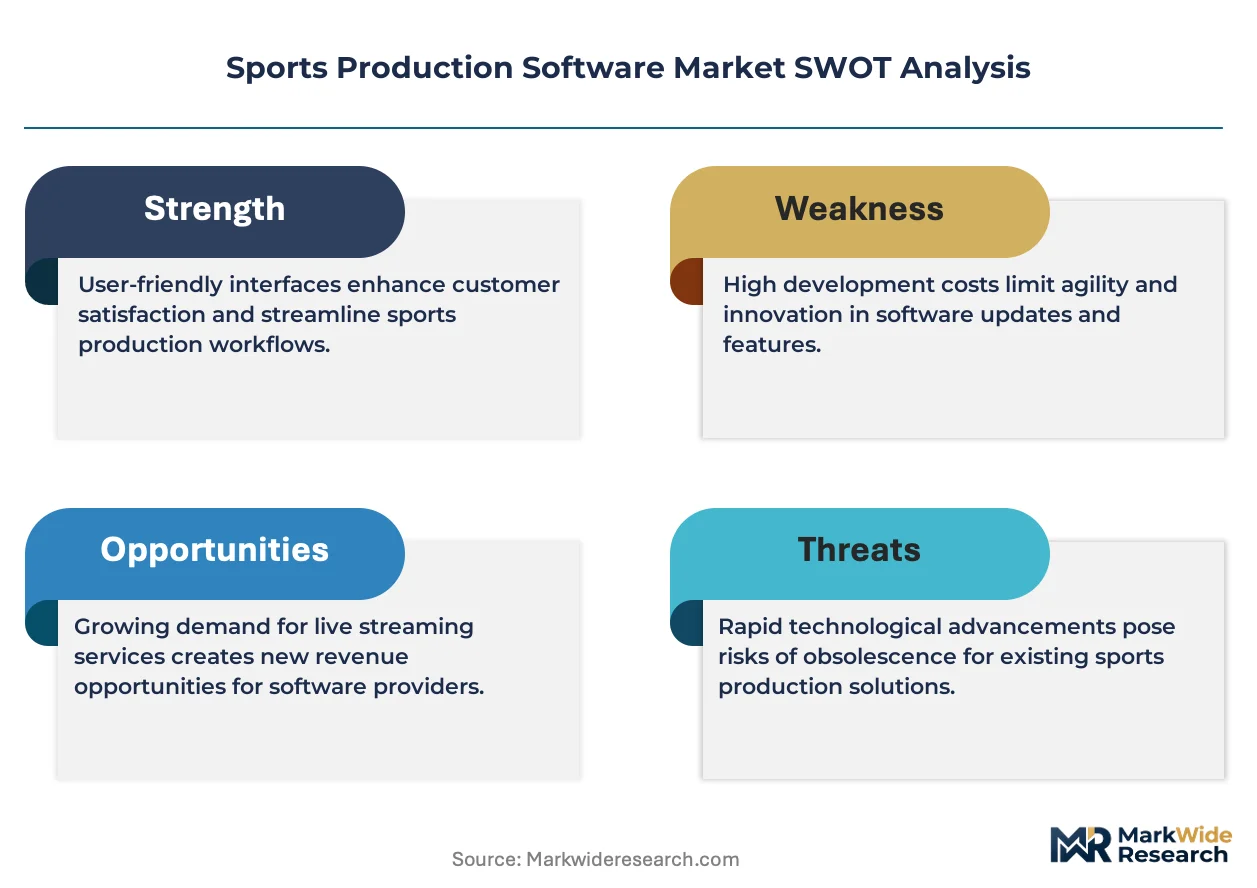
Cloud-native broadcast infrastructure is compressing capital requirements for live sports production, enabling mid-tier leagues and collegiate conferences to deploy broadcast-grade tooling previously reserved for national networks. This democratization is fragmenting the buyer base while accelerating refresh cycles across the installed base.
Growth Catalysts
- SDI-to-IP transition:Internet Protocol-based signal transport eliminates dedicated hardware matrices and enables software-defined routing. Regional sports networks in Germany and Brazil are retrofitting control rooms to IP-native architectures.
- AI-enhanced clipping automation:Machine learning models trained on play-by-play data now auto-generate highlight reels within seconds of live action. Rights holders use these tools to feed social media channels during live events.
- FCC closed captioning mandates:Regulatory requirements for accessibility compliance drive replacement of legacy graphics systems. Vendors must certify real-time caption insertion latency below broadcast thresholds.
Market Restraints
- GPU supply concentration:Rendering engines for augmented reality overlays depend on NVIDIA data center silicon. Foundry capacity constraints in Taiwan create 6-9 month lead times for production hardware refreshes.
- Specialized broadcast engineering talent:Hybrid skill sets combining IP networking, video engineering, and software development command premium compensation. Smaller market stations face recruitment gaps against technology firms.
- Legacy SDI infrastructure lock-in:Major broadcasters amortized copper-based routing investments over 10-15 year cycles. Parallel IP migration requires dual-maintenance budgets that compress near-term software procurement.
Strategic Opportunities
- Collegiate athletic conferences:Division I programs outside Power Five conferences lack centralized production resources. Cloud-based remote production tools allow shared services models across multiple universities.
- Wearable biometric integration:Athlete tracking data from inertial measurement units converges with broadcast graphics. Real-time performance overlays create new inventory for betting-integrated broadcasts.
- ISO 27001 certification arbitrage:Leagues handling sensitive competitive intelligence prioritize certified vendors. Mid-size software firms can differentiate against uncertified competitors in RFP processes.
Industry Challenges
- Sub-second latency engineering:Synchronous multi-camera switching across distributed cloud nodes requires precise timing protocol implementation. Engineering teams struggle to maintain frame-accurate synchronization during peak load events.
- Multi-codec transcoding complexity:Simultaneous output for linear broadcast, OTT streaming, and social platforms demands real-time format adaptation. Integration testing across delivery endpoints extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Production Software Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Editing Software, Streaming Platforms, Graphics Creation Tools, Analysis Software End User: Television Networks, Sports Teams, Event Organizers, Streaming Services Technology: Cloud-Based Solutions, AI-Driven Tools, Virtual Reality Systems, Mobile Applications Distribution Channel: Direct Sales, Online Marketplaces, Software Resellers, Subscription Services |
| Companies Covered | PlayMetrics, Worldcast Live, TeamSnap, Genius Sports, Bolt6, SportsEngine, Stack Sports, BigBro.AI Sports, Waresport, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Production Software Market Evolving Landscape
Real-time graphics rendering is migrating from dedicated hardware appliances to containerized software stacks, compressing both capital deployment and operational footprint for live production facilities.
WebRTC-based contribution protocols are digitizing field acquisition workflows, replacing bonded cellular hardware with browser-based encoders. Freelance camera operators at regional sporting events now stream directly through laptop-based interfaces. This architecture collapses equipment shipping logistics and enables same-day crew deployment.
The FCC's updated emergency alert system requirements impose new software certification burdens on broadcast infrastructure vendors. Compliance testing for IP-based alert insertion now extends product development cycles by 4-6 months. Smaller software vendors without dedicated regulatory affairs staff face competitive disadvantage against established broadcast incumbents.
Subscription-based pricing for production tools is displacing perpetual license models among mid-market sports organizations. Athletic departments and minor league franchises prefer operational expenditure alignment with seasonal revenue patterns. This shift concentrates annual recurring revenue with vendors capable of financing customer acquisition costs over multi-year contract terms.
Sports Production Software Market Segmentation
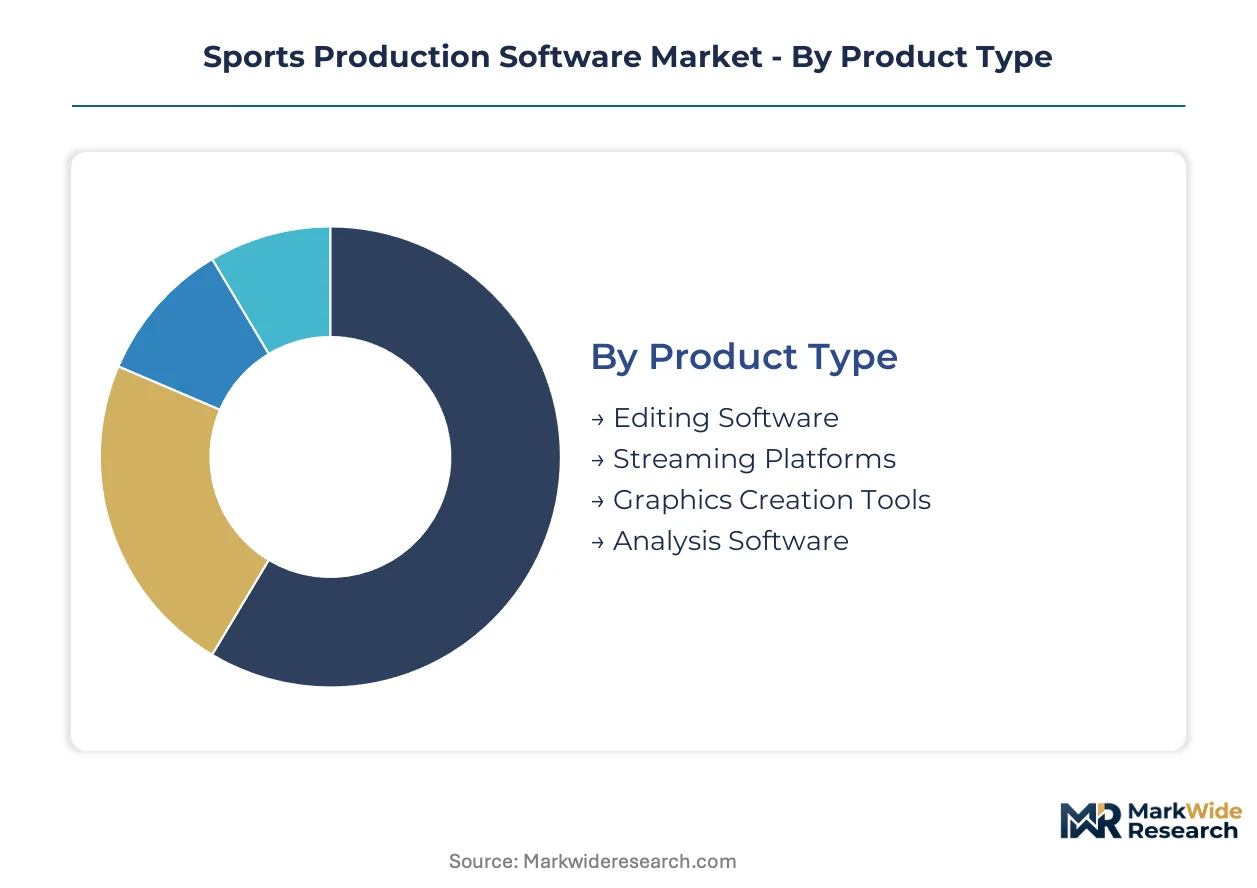
Sports production software vendors configure service architectures around deployment complexity and integration touchpoints. After-sales support intensity varies dramatically across product categories, with live broadcast systems demanding 24/7 technical response while packaged editing tools operate on standard maintenance schedules.
Product Type:
After-sales-service intensity peaks with real-time systems requiring broadcast-continuity guarantees, while packaged software operates through standard ticketing workflows.
- Streaming Platforms:Cloud-native architectures ingest live feeds through SDI or IP pipelines, transcoding 1080p to 4K HDR for multi-platform distribution. Demand concentrates among direct-to-consumer sports networks and collegiate athletic conferences replacing linear broadcast infrastructure with elastic cloud capacity. FCC closed captioning mandates and sub-second latency requirements drive replacement cycles as legacy hardware reaches end-of-life.
- Graphics Creation Tools:Real-time rendering engines generate augmented overlays, scoreboards, and virtual advertisements synchronized to live action. Sports leagues and regional sports networks sustain demand through entrenched broadcaster relationships and multi-year equipment amortization cycles. GPU supply constraints from NVIDIA foundry capacity create procurement bottlenecks for AR-capable hardware refreshes.
- Editing Software:Non-linear editing suites for post-production highlight packages and documentary content.
- Analysis Software:Predictive performance modeling tools for coaching staffs and media rights holders.
Graphics creation tools hold the largest share; momentum sits with streaming platforms.
End User:
Cost tier differentiation separates enterprise broadcast deployments from mid-market athletic department budgets, with pricing scaled to production volume and integration complexity.
- Television Networks:National broadcasters operate redundant production facilities with dedicated engineering staff and multi-million-dollar annual software procurement budgets. The United States market concentrates demand among ESPN, Fox Sports, and NBC Sports divisions amortizing infrastructure over 10-15 year cycles. FCC emergency alert system compliance and spectrum allocation rules constrain vendor selection to established broadcast incumbents with dedicated regulatory affairs staff.
- Streaming Services:Direct-to-consumer platforms deploy cloud-native remote production tools without legacy SDI infrastructure lock-in. Amazon Prime Video, Apple TV+, and DAZN drive adoption of browser-based contribution protocols and AI-enhanced clipping automation. Subscription-based pricing alignment with seasonal revenue patterns accelerates refresh cycles versus perpetual license models.
- Sports Teams:Professional franchises and collegiate programs deploying in-house production capabilities.
- Event Organizers:Tournament operators and venue management companies requiring temporary broadcast infrastructure.
Television networks command the highest contract values; streaming services are expanding most quickly.
Technology:
Application maturity separates deployed cloud infrastructure from emerging AI and VR capabilities still navigating integration complexity.
- Cloud-Based Solutions:Containerized software stacks replace dedicated hardware appliances, compressing capital deployment and operational footprint. Regional sports networks in Germany and Brazil retrofit control rooms to IP-native architectures, eliminating dedicated routing matrices. ISO 27001 certification shapes vendor selection for leagues handling sensitive competitive intelligence.
- AI-Driven Tools:Machine learning models trained on play-by-play data auto-generate highlight reels within seconds of live action. Rights holders feed social media channels during events, creating new inventory for betting-integrated broadcasts. Specialized broadcast engineering talent combining IP networking, video engineering, and software development commands premium compensation.
- Virtual Reality Systems:Immersive viewing experiences requiring headset distribution and specialized camera arrays.
- Mobile Applications:Crew-facing tools for field acquisition and remote production coordination.
Cloud-based solutions dominate deployment volume; AI-driven tools show steepest expansion trajectory.
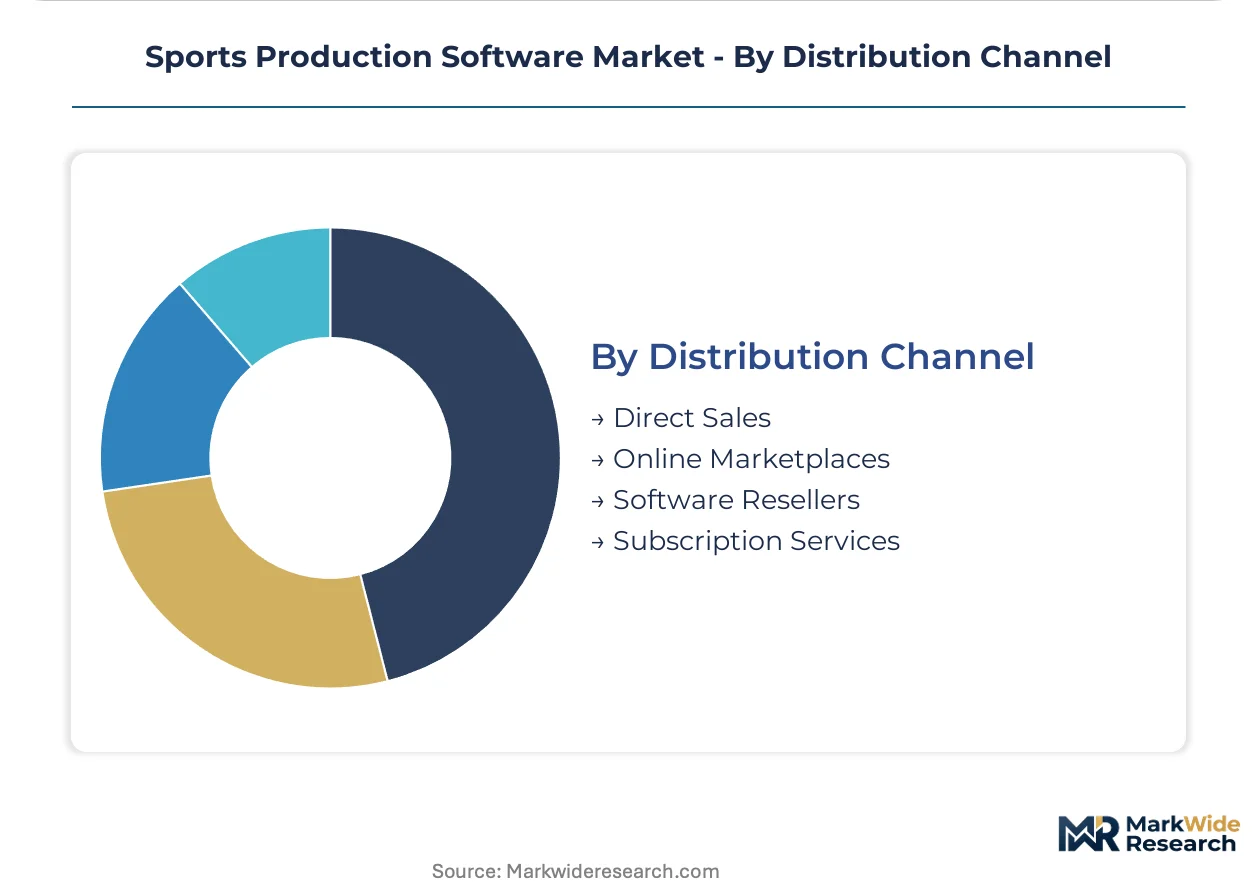
Distribution Channel:
Customer type segmentation separates enterprise direct relationships from transactional mid-market procurement patterns.
- Direct Sales:Enterprise field teams cultivate multi-year relationships with national broadcasters and professional sports leagues. Complex integration requirements and custom compliance certification favor vendor control over implementation timelines. Annual recurring revenue concentration rewards vendors financing customer acquisition costs over extended contract terms.
- Subscription Services:Operational expenditure models align software costs with seasonal revenue patterns for athletic departments and minor league franchises. Mid-market sports organizations prefer predictable monthly payments over capital-intensive perpetual licenses. Self-service onboarding and standardized integration reduce sales engineering touchpoints.
- Software Resellers:Regional systems integrators serving collegiate conferences and local broadcast stations.
- Online Marketplaces:Transactional procurement for standalone editing tools and mobile applications.
Direct sales capture the largest contract values; subscription services are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC broadcast standards in the United States anchor regulatory compliance requirements for sports production software architectures worldwide. Cloud-native infrastructure investments concentrate in North American and European markets where professional leagues command premium production budgets.
United States
Professional sports leagues and collegiate athletic conferences drive demand for AI-enhanced clipping automation and real-time graphics rendering. FCC mandates on closed captioning latency and emergency alert compatibility constrain vendor certification timelines. Production technology clusters in Los Angeles and New York City support broadcast-continuity guarantees for national network deployments.
Germany
Regional sports networks retrofit control rooms to IP-native architectures, eliminating dedicated hardware routing matrices. EMA clinical-grade data handling standards intersect with athlete biometric monitoring integrations in production systems. Broadcasting engineering expertise concentrates in Munich and Cologne, where public-private partnerships accelerate SDI-to-IP transitions.
Brazil
Mid-tier football leagues adopt cloud-based remote production tools to bypass capital-intensive broadcast infrastructure investments. ANVISA regulations on data privacy shape athlete tracking data handling in integrated production workflows. São Paulo anchors Latin American production technology adoption, with regional broadcasters deploying browser-based contribution protocols.
United Kingdom
Streaming services and direct-to-consumer sports platforms expand subscription-based pricing models for production tooling. GDPR compliance requirements impose modular data architectures on cloud-native broadcast systems. London's media technology corridor attracts vendor engineering centers focused on low-latency multi-platform distribution.
Japan
Broadcasters integrate wearable biometric data from inertial measurement units into live graphics overlays for baseball and sumo coverage. METI industrial standards guide software-defined broadcast infrastructure procurement. Tokyo's production facilities lead Asia-Pacific adoption of containerized graphics rendering stacks.
Sports Production Software Market Competitive Landscape
Cloud-native platform providers and legacy broadcast incumbents split the market between elastic infrastructure and entrenched customer relationships. Consolidation pressures favor vendors with ISO 27001 certification and dedicated regulatory affairs capabilities. Three archetypes dominate: league-integrated data specialists, workflow automation platforms for amateur sports, and unified SaaS providers spanning registration to video production. Competitive moves concentrate on strategic partnerships with rights holders and portfolio diversification into adjacent betting-integrated broadcast inventory.
Within the league-integrated tier, Genius Sports occupies a position exemplifying deep data integration across professional partnerships. TeamSnap and Stack Sports represent contrasting archetypes in the amateur and youth sports segment, with the former anchoring workflow automation specialization and the latter occupying unified platform architecture. These three companies illustrate how vendor selection criteria diverge between enterprise broadcast deployments and mid-market athletic department budgets.
| Leading Market Players |
|---|
| PlayMetrics |
| Worldcast Live |
| TeamSnap |
| Genius Sports |
| Bolt6 |
| SportsEngine |
| Stack Sports |
| BigBro.AI Sports |
| Waresport |
| Others |
Value Network & Pricing Analysis
Trans-Pacific fiber routes from Los Angeles to Tokyo and Singapore anchor cloud infrastructure costs for sports production software, compressing margins for vendors serving mid-tier collegiate conferences while amplifying price differentiation between broadcast-grade and entry-tier SaaS offerings.
Pricing Analysis
Geographic price spreads between North American and Latin American deployments exceed those within Europe, reflecting differential cloud egress fees and FCC compliance certification costs. The market operates on subscription-tiered models with premium-mid-economy pricing differentiation anchored by ISO 27001 certification status and after-sales service bundling. Pricing pressure stems from GPU supply constraints extending procurement timelines for AR-capable hardware refreshes. Mid-market athletic departments exhibit highest price sensitivity, while national broadcasters prioritize continuity guarantees over cost optimization.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk for rendering hardware and data center silicon. Manufacturing concentrates in Taiwan, South Korea, and the United States for GPU and FPGA components. Production draws from NVIDIA data center silicon, specialized broadcast encoding chips, and high-bandwidth memory modules. Single-source vulnerability around TSMC foundry capacity creates procurement bottlenecks. Distribution runs through direct enterprise field teams for national broadcasters and cloud marketplaces for mid-market subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sports production software is approaching a platform-economics inflection as WebRTC-based contribution protocols and containerized graphics stacks dissolve hardware-software boundaries, creating interoperability demands that favor vendors with modular API architectures over monolithic legacy systems.
For Market Incumbents: Insulate recurring revenue streams by deepening certification moats around FCC emergency alert compliance and ISO 27001 data handling standards. Acquire specialized AI clipping automation firms to neutralize cloud-native challengers feeding social media highlight demand. Prioritize backward integration into GPU allocation contracts with foundry partners to secure hardware refresh capacity.
For New Entrants and Emerging Players: Brazilian regional football leagues and German second-tier sports networks present underpenetrated demand for cloud-based remote production tools lacking legacy SDI lock-in. Target collegiate athletic conferences outside Power Five structures with shared-services pricing models. Deploy browser-based contribution protocols to collapse equipment logistics and accelerate same-day crew deployment.
For Investors and Strategic Acquirers: FCC's updated emergency alert system requirements reshape the acquisition landscape toward vendors with dedicated regulatory affairs capabilities and certified IP-based alert insertion. Mid-size software firms with ISO 27001 certification and modular compliance architectures offer viable five-to-ten-year platform consolidation targets. Monitor GPU supply allocation announcements as inflection indicators for vendor hardware refresh capacity and margin sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Containerized graphics stacks from Vizrt and Chyron reduce capital deployment for regional sports networks. |
| Strategic Partnership | League-integrated data specialists secure exclusive biometric overlay rights with betting operators. |
| Acquisition of Specialist Firm | AI clipping automation targets enhance real-time social media inventory generation capabilities. |
| Geographic Expansion | Cloud-native remote production tools penetrate Brazilian mid-tier football leagues bypassing broadcast infrastructure. |
| Product Launch | WebRTC-based contribution protocols collapse equipment shipping logistics for freelance camera operators. |
Research Methodology
A standing panel of broadcast engineering directors, collegiate athletic conference technology officers, cloud infrastructure procurement leads, and sports league digital media executives provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with secondary validation against SEC filings from publicly traded vendors, hyperscaler capex disclosures, and FCC equipment authorization databases. Bottom-up triangulation across deployment volume estimates and top-down revenue reconciliation anchored market size calculations.
Scenario-bracketing around GPU supply constraints and regulatory compliance timelines framed the analytical approach across the projection horizon. Segmentation dimensions modeled include deployment architecture, end-user production volume tier, integration complexity level, and regional regulatory cluster. CAGRs derived from fitted growth curves adjusted for technology substitution effects and cloud adoption S-curves. Forecast inputs incorporated collegiate conference consolidation patterns and streaming platform original content commitments.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by cloud hyperscalers into broadcast tooling would shift outcomes substantially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Webinar Software Market
Software & Services
Emotion Recognition and Sentiment Analysis Software Market
Software & Services
Geophysical Software Service Market
Software & Services
Asia-Pacific Communication Platform-As-A-Service Market
Software & Services
Packaged Software Market
Software & Services
BIM Objects Software Market
Software & Services
Calorie Metering Software Market
Software & Services
Stock Footage Software Market
Software & Services
Global Application Management Services Market
Software & Services
Automotive Dealership Software Market
Software & Services
Global Version Control Systems Market
Software & Services
Global SEO Software Market
Software & Services
Embedded Hypervisor Market
Software & Services
Apparel Software Market
Software & Services
App Building Software Market
Software & Services
HACCP Software Market