
 Automotive Design Software Market | 2026-2036
Automotive Design Software Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Design Software Market Outlook
The EU Green Deal is broadening the addressable market for lifecycle design tools that embed carbon accounting from concept through production. Elektrobit leverages its embedded software heritage to anchor European OEM relationships for architecture design platforms. Tata Elxsi sustains competitive differentiation through specialized offshore delivery models for styling and surfacing workflows. KPIT Technologies competes aggressively in powertrain simulation where electrification complexity drives recurring engineering engagements.
Automotive design software comprises digital toolsets that enable geometric modeling, physics-based simulation, and real-time visualization of vehicle systems prior to physical prototyping. These platforms integrate parametric CAD kernels, finite-element meshing engines, and GPU-accelerated rendering pipelines to compress development timelines and reduce prototype tooling expenditure. Cloud-based solutions within the technology dimension represent the fastest-expanding deployment mode as OEMs distribute computational workloads across distributed engineering centers. The end-user structure tilts toward OEMs and Tier-1 suppliers who command the capital budgets for enterprise-wide platform licensing, while design firms occupy specialized niches in concept styling and aesthetic development where project-based procurement prevails.
REACH compliance mandates from ECHA and the EU AI Act from European legislators jointly shape material selection databases and algorithmic design assistants that vendors must certify before market access. FDA-equivalent automotive safety frameworks in key production jurisdictions further constrain how simulation software validates crashworthiness and autonomous system behavior. Stakeholders must monitor how regulatory convergence between emissions accounting and software safety standards reshapes procurement criteria for design platform vendors.
Market Dynamics
Cloud-native architecture is absorbing CAPEX burdens from OEM engineering centers while EU AI Act compliance mandates reshape algorithmic design assistant certification pathways.
Growth Catalysts
- EU Green Deal lifecycle mandates:Carbon accounting embedded from concept through production expands addressable demand for integrated design-to-sustainability platforms.
- GPU-accelerated rendering pipelines:Real-time visualization compresses styling approval cycles, pulling adoption from Stuttgart and Munich engineering clusters.
- Electric vehicle platform proliferation:Dedicated EV architectures require new simulation toolchains for battery pack integration and thermal management.
Market Restraints
- Perpetual-to-subscription license friction:Enterprise procurement committees resist recurring payment structures for core CAD kernels despite cloud migration pressure.
- Specialized talent scarcity:Finite-element meshing expertise concentrates in Germany's automotive corridor, constraining vendor scaling.
- REACH database compliance costs:ECHA-mandated material selection updates impose recurring certification overhead on mid-tier suppliers.
Strategic Opportunities
- India offshore delivery models:Styling and surfacing workflows migrate to Bangalore and Pune engineering centers, reducing cost-to-serve for Western OEMs.
- Generative design-AI convergence:Topology optimization algorithms merge with neural rendering to automate concept generation from performance constraints.
- EU CSRD disclosure requirements:Mandatory sustainability reporting creates pull for design platforms with embedded carbon footprint tracking.
Industry Challenges
- Legacy PLM integration complexity:Siemens Teamcenter and Dassault ENOVIA installations resist API connectivity with modern cloud-native tools.
- Cross-border data residency conflicts:China's GB standards for automotive data localization clash with EU GDPR research collaboration requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Design Software Market |
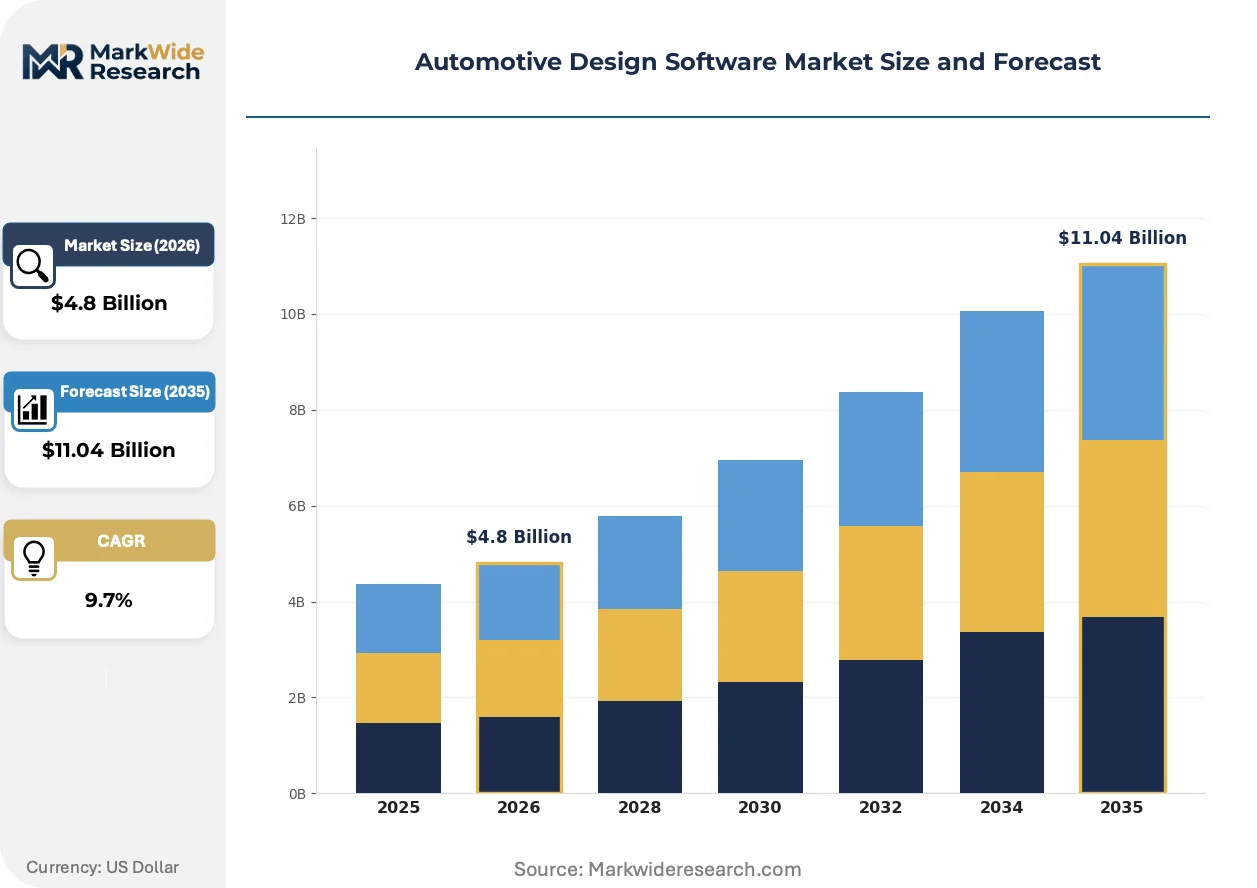
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 3D Modeling, Simulation, Prototyping, Rendering End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Design Firms Technology: CAD, CAM, Virtual Reality, Cloud-Based Solutions Application: Vehicle Design, Interior Design, Exterior Design, Performance Analysis |
| Companies Covered | Elektrobit, DXC Technology, Tata Elxsi, Wipro, EPAM Systems, KPIT Technologies, Vector Informatik, GlobalLogic, HARMAN International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Design Software Market Strategic Shifts
Computational workloads are redistributing across distributed engineering centers as regulatory compliance layers compound software certification requirements.
Digital twin technology is absorbing physics-based simulation into continuous virtual validation environments. Tier-1 suppliers deploy these models for powertrain thermal management and crashworthiness prediction. The technology is absorbing hardware prototype budgets into software licensing expenditure.
REACH compliance mandates from ECHA now require material selection databases to flag restricted substances at the concept stage. Automotive OEMs must certify algorithmic design assistants under the EU AI Act before deployment. German engineering centers face the steepest compliance timeline pressure given their concentration of styling and surfacing workflows.
Subscription pricing for enterprise platform licensing displaces perpetual seat models across Stuttgart and Munich procurement offices. Engineering center managers negotiate consumption-based tiers aligned with project pipeline volatility. France and Italy show similar migration patterns though six to twelve months behind German adoption curves.
Automotive Design Software Market Segmentation
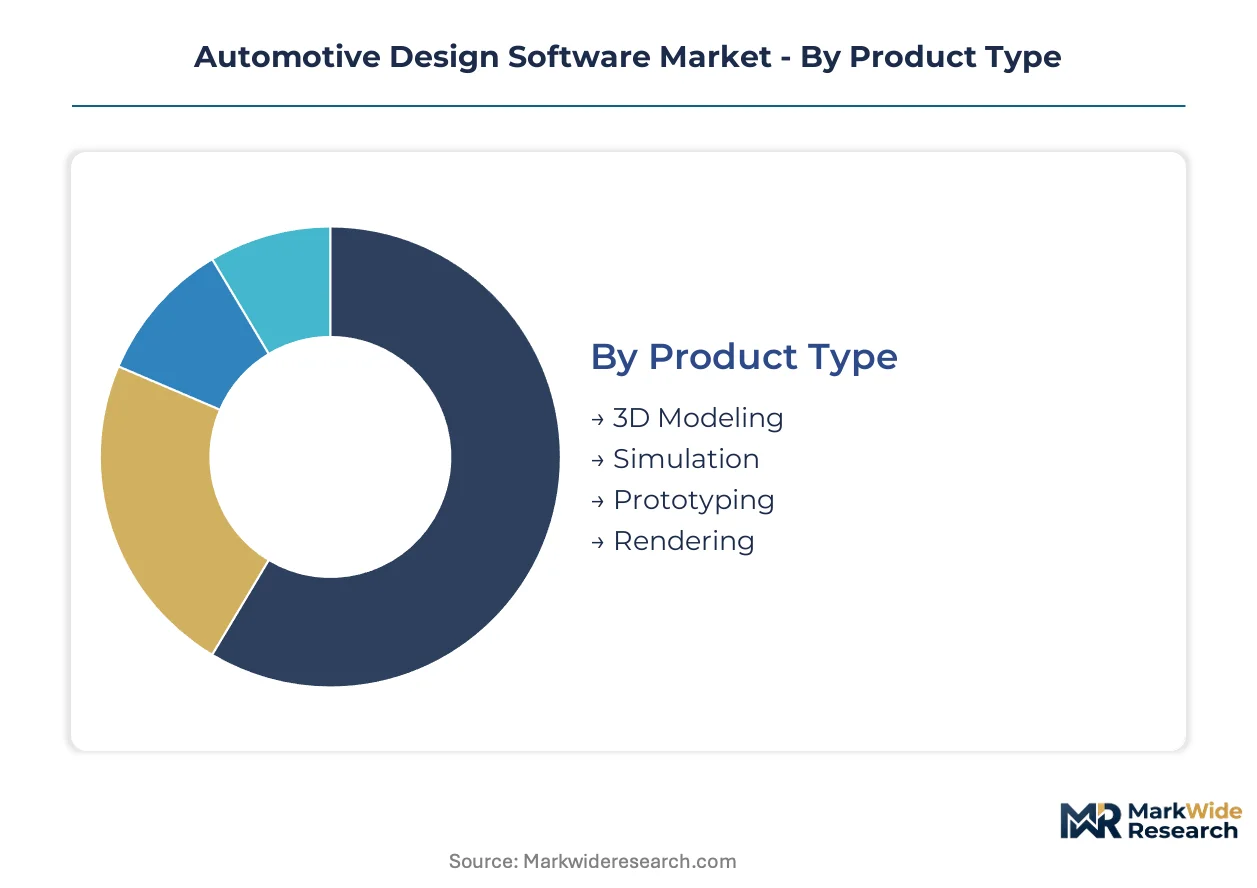
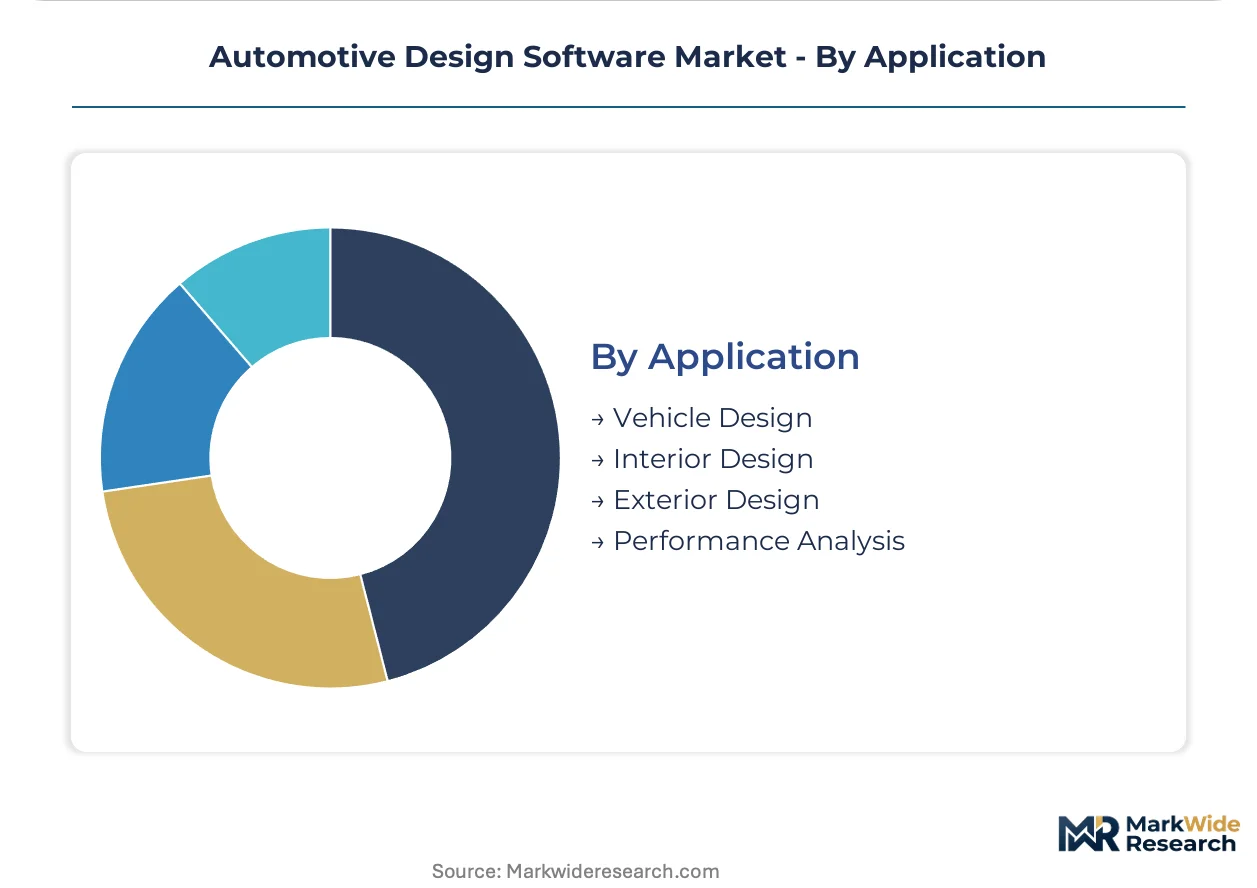
Automotive design software segments reflect divergent procurement priorities across engineering workflows. OEMs concentrate licensing budgets in integrated platforms while specialized vendors capture niche styling and surfacing tasks.
Product Type:
Supply concentration in GPU-accelerated rendering pipelines has shifted vendor R&D toward real-time visualization engines.
- 3D Modeling:Parametric CAD kernels enable geometric surface definition from concept through manufacturing release. Stuttgart and Munich engineering clusters drive demand for direct modeling capabilities that bypass feature history constraints.
- Simulation:Finite-element meshing engines validate structural, thermal, and aerodynamic performance prior to physical prototyping. Powertrain electrification complexity is pulling recurring engineering engagements from battery pack integration specialists.
- Prototyping:Digital twin environments compress hardware validation cycles through continuous virtual testing.
- Rendering:GPU-accelerated pipelines generate photorealistic visualization for stakeholder approval workflows.
Simulation absorbs the bulk of installed capacity; rendering is expanding most quickly.
End User:
Enterprise procurement authority concentrates in OEMs and Tier-1 suppliers with capital budgets for platform-wide deployment.
- OEMs:Volkswagen Group and BMW command multi-year enterprise agreements covering architecture design through manufacturing engineering. Their procurement offices negotiate consumption-based tiers aligned with project pipeline volatility.
- Tier-1 Suppliers:Bosch and Continental deploy specialized modules for powertrain simulation and thermal management validation. These vendors face margin pressure from OEMs pushing cost-to-serve reductions.
- Aftermarket Providers:Customization specialists access lower-tier CAD seats for retrofit design workflows.
- Design Firms:Project-based procurement prevails in concept styling where aesthetic development requires specialized surfacing expertise.
OEMs command the dominant share of licensing expenditure; design firms are climbing the fastest as outsourcing accelerates.
Technology:
Deployment mode differentiation tracks IT infrastructure maturity across engineering center networks.
- CAD:Parametric and direct modeling kernels remain the foundational layer for geometric definition. Dassault Systèmes and Siemens dominate through deep PLM integration.
- CAM:Manufacturing preparation modules bridge design data to CNC programming and additive production workflows.
- Virtual Reality:Immersive review environments compress styling approval cycles through spatial visualization at full scale.
- Cloud-Based Solutions:Distributed computational workloads enable collaboration across engineering centers without on-premise hardware investment. EU AI Act compliance mandates reshape certification pathways for algorithmic design assistants deployed via cloud infrastructure.
CAD retains the deepest installed base; cloud-based solutions are gaining share fastest.
Application:
Engineering resource allocation follows vehicle program lifecycle stages from concept through production release.
- Vehicle Design:System-level architecture platforms integrate chassis, powertrain, and electronics packaging. EU Green Deal lifecycle mandates embed carbon accounting from initial concept.
- Interior Design:Human-machine interface and ergonomics simulation requires specialized surfacing workflows. Haptic feedback and augmented reality displays drive complexity in cockpit development.
- Exterior Design:Aerodynamic optimization and aesthetic surfacing concentrate in Stuttgart and Munich styling centers. Real-time rendering accelerates executive approval cycles.
- Performance Analysis:Multi-physics simulation validates crashworthiness, NVH, and thermal behavior under regulatory test protocols.
Vehicle design anchors platform licensing volumes; performance analysis is expanding most rapidly with electrification complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors automotive design software procurement through Volkswagen Group and Porsche engineering centers. Munich's BMW and Siemens ecosystems drive simulation tool demand. Procurement committees in both cities negotiate consumption-based licensing tiers.
Germany
Baden-Württemberg and Bavaria concentrate GPU-accelerated rendering procurement from Stuttgart and Munich clusters. ECHA REACH compliance mandates reshape material selection database requirements for concept-stage carbon accounting. Engineering centers in Wolfsburg and Ingolstadt deploy digital twin environments for powertrain thermal validation.
United States
Michigan's Detroit-Warren corridor and California's Silicon Valley split demand between legacy OEM engineering and EV-native startups. NHTSA safety frameworks constrain how simulation software validates autonomous system behavior. Austin and Palo Alto engineering centers absorb cloud-native architecture licensing for distributed computational workloads.
China
Shanghai and Shenzhen engineering centers drive adoption for battery pack integration simulation. MIIT GB standards for automotive data localization clash with EU GDPR research collaboration requirements. Yangtze River Delta OEMs procure cloud-based solutions despite cross-border data residency friction.
India
Bangalore and Pune offshore delivery centers capture styling and surfacing workflows from Western OEMs. BIS automotive standards intersect with EU AI Act compliance for algorithmic design assistants deployed via cloud infrastructure. Karnataka's engineering clusters reduce cost-to-serve for European procurement offices through specialized delivery models.
Japan
Nagoya's Toyota engineering ecosystem and Tokyo metro suppliers anchor finite-element meshing demand. METI industrial policy supports digital twin adoption for continuous virtual validation. Osaka-based Tier-1 suppliers deploy specialized modules for NVH simulation under domestic safety certification protocols.
Automotive Design Software Market Competitive Environment
Premium-margin players sit above commodity-margin players across embedded software heritage and offshore delivery specialization. The vendor base stratifies into three tiers: integrated platform providers with deep PLM connectivity, specialized engineering services firms with geographic cost arbitrage, and niche styling boutiques with surfacing workflow expertise. Dominant competitive moves include strategic partnerships between European embedded software specialists and Indian offshore delivery networks, plus portfolio diversification into generative design-AI convergence.
Within the embedded software heritage tier, Elektrobit and Vector Informatik exemplify European OEM relationship anchoring for architecture design platforms. Among offshore delivery specialists, Tata Elxsi and KPIT Technologies occupy positions in styling workflows and powertrain simulation respectively. Wipro represents the scale-driven IT services archetype competing across multiple engineering workflow segments.
| Leading Market Players |
|---|
| Elektrobit |
| DXC Technology |
| Tata Elxsi |
| Wipro |
| EPAM Systems |
| KPIT Technologies |
| Vector Informatik |
| GlobalLogic |
| HARMAN International |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal lifecycle mandates gate qualified supply for carbon-accounting design platforms, restricting premium-tier pricing access to vendors with certified embedded software heritage. Stuttgart and Munich procurement offices pay subscription premiums for REACH-compliant material databases, while mid-tier suppliers absorb recurring certification overhead that compresses their pricing power.
Pricing Analysis
Consumption-based licensing anchored to project throughput dominates enterprise procurement, with pricing stratifying across premium, standard, and economy tiers based on GPU rendering capacity and ECHA database certification levels. Price differentiation hinges on EU AI Act compliance status and embedded carbon tracking granularity. Cost compression in mid-tier seats is intensifying because OEMs push cost-to-serve reductions onto suppliers. Tier-1 suppliers exhibit highest price sensitivity; OEMs with multi-year enterprise agreements show lowest.
Supply Chain Analysis
Regional distribution centers in Germany, India, and the United States anchor hub-and-spoke patterns for software licensing fulfillment and engineering services delivery. The supply chain draws from concentrated GPU semiconductor fabrication, specialized finite-element meshing expertise, and cloud infrastructure provisioning. Single-source vulnerability concentrates in Germany's automotive corridor for styling and surfacing talent. Distribution runs through direct enterprise sales teams, offshore delivery partnerships, and hyperscaler marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Finite-element meshing expertise scarcity in Germany's automotive corridor props pricing for qualified vendors, constraining rapid supply expansion. Capacity bottlenecks in certified algorithmic design assistants sustain margin premiums for early movers.
For Market Incumbents: Extend embedded software heritage into generative design-AI convergence before offshore specialists capture topology optimization workflows. Deepen vertical integration into cloud-native architecture to defend against consumption-based pricing erosion. Prioritize ECHA REACH database certification investments to maintain procurement committee access. For New Entrants and Emerging Players: Begin with styling and surfacing workflows migrating to Bangalore and Pune, where Western OEMs seek cost-to-serve reductions. Target design firm project-based procurement as the most penetrable entry point. Lead with specialized offshore delivery models that undercut Stuttgart engineering center rates. For Investors and Strategic Acquirers: Subscription pricing migration in German procurement offices is the leading indicator that recurring revenue models will dominate capital allocation across European automotive engineering. Long-term viability favors vendors with dual capability in embedded software heritage and offshore delivery scaling. Watch for EU CSRD disclosure requirement enforcement as the inflection signal for carbon-accounting platform demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep PLM connectivity with Siemens Teamcenter and Dassault ENOVIA secures OEM retention. |
| Strategic Partnership | European embedded software specialists pairing with Indian offshore networks compress cost-to-serve. |
| Acquisition of Specialist Firm | GPU-accelerated rendering boutiques add real-time visualization capacity for Stuttgart styling centers. |
| Geographic Expansion | Bangalore and Pune engineering centers capture migrating surfacing workflows from Western OEMs. |
| Product Launch | Algorithmic design assistants certified under EU AI Act unlock procurement committee access. |
Study Parameters
Multi-period observation of subscription pricing migration patterns and cloud deployment rates anchored the trend analysis, supplemented by interviews with OEM platform engineers, Tier 1 supplier procurement leads, design firm creative directors, and hyperscaler marketplace managers. Secondary validation drew from SEC software vendor filings, ECHA REACH database updates, EU AI Act implementation guidance, and vehicle production databases. Bottom-up engineering center demand modeling triangulated against top-down vendor revenue segmentation.
Segment-weighting across deployment mode, end-user tier, and application workflow distributed value projections across the analysis window. Product type splits—3D modeling, simulation, prototyping, rendering—combined with technology dimensions of CAD, CAM, virtual reality, and cloud-based solutions structured the analytical framework. CAGRs derived from fitted growth curves applied to disclosed vendor bookings and procurement committee pipeline data. Electrification complexity indices and regulatory compliance timeline pressure calibrated regional divergence.
Underlying measurement precision varies by segment; cloud-based solutions and rendering pipelines carry tighter precision than legacy CAD installed base estimates. Forecasts reflect documented assumptions around EU AI Act enforcement timing and OEM cloud migration velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Mobile Application Testing Services (MATS) Market
Software & Services
CGI Software Market
Software & Services
Hotel Management Software Market
Software & Services
Exercise and Weight Loss Apps Market
Software & Services
RIP Software Market
Software & Services
Orchestration Tools Market
Software & Services
Runtime Software Market
Software & Services
Global Script Writing Software Market
Software & Services
Adaptive Learning Software Market
Software & Services
Audio and Video Editing Software Market
Software & Services
Global Time and Attendance Management Software Market
Software & Services
Global Customer Success Software Market
Software & Services
Global Membership Management Software Market
Software & Services
RIP Color Management Software Market
Software & Services
Non-Profit Software Market
Software & Services
Photo Editor App Market