
 Office Software Market | 2026-2036
Office Software Market Size, Share, and Industry Trends Forecast 2026-2036
Office Software Market Intelligence
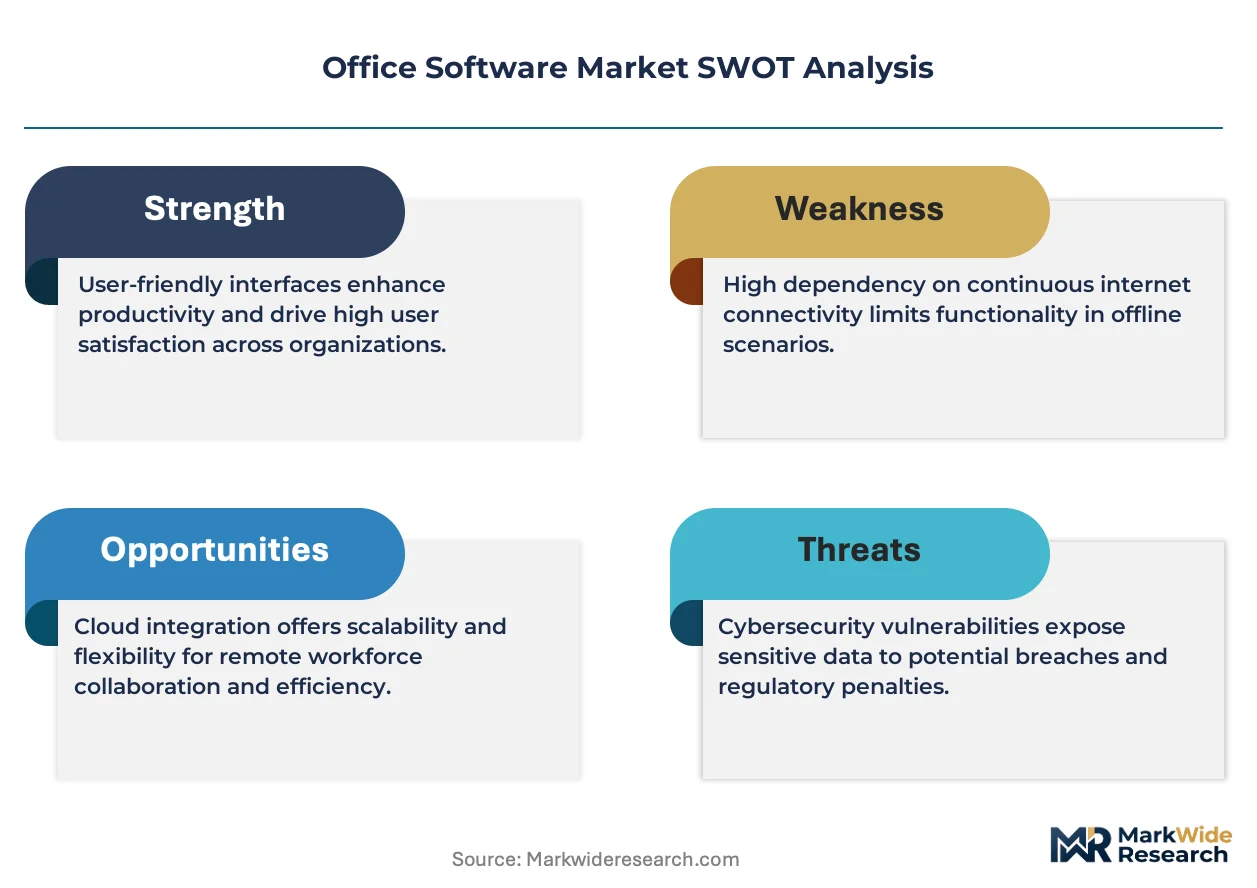
Enterprise-grade security certification is rotating from optional to mandatory in procurement criteria. Microsoft anchors its position through deep integration across productivity and infrastructure layers. Google differentiates via real-time collaboration architectures that reduce version-control friction. IBM sustains relevance in regulated sectors through encryption standards that exceed baseline compliance thresholds.
Office software encompasses applications for document creation, data analysis, visual communication, and electronic correspondence, typically delivered through local installation, browser-based interfaces, or containerized mobile environments. Cloud-based deployment now captures the fastest expansion as IT departments prioritize zero-touch provisioning and automatic security patching over capital-intensive on-premises maintenance. Subscription pricing dominates revenue mechanics among enterprises, while freemium models serve as conversion funnels for freelancer and small-business segments where lifetime value calculations favor gradual monetization.
FCC guidelines on data transmission integrity intersect with SEC disclosure requirements for publicly traded software vendors, creating layered compliance obligations that shape product architecture decisions. ISO 27001 certification functions as a market-access filter for vendors serving healthcare and financial services buyers. Procurement officers must weigh interoperability standards against vendor lock-in risks as AI copilants become embedded in core workflow tools.
Market Dynamics
Enterprise migration to browser-native productivity environments is compressing deployment cycles and collapsing traditional licensing hierarchies as IT departments prioritize automatic security patching over perpetual ownership models.
Growth Catalysts
- GDPR Article 32 mandates:Data processing agreements now require encryption-at-rest for cloud-hosted documents, accelerating certified-provider selection among European enterprises.
- Zero-trust architecture adoption:Federal agencies in the United States are mandating continuous verification protocols, forcing productivity suite vendors to embed identity-per-session controls.
- Containerized mobile deployment:BYOD policies in healthcare and financial services are driving demand for sandboxed application environments that isolate corporate data from personal device storage.
Market Restraints
- Input cost volatility:GPU cluster pricing for AI inference workloads is squeezing margins on freemium tiers, forcing vendors to restrict copilot access to paid subscriptions.
- Supply concentration risk:Hyperscaler cloud infrastructure in the United States dominates hosting capacity, creating single-region dependency for latency-sensitive real-time collaboration features.
- Technical limitation:Offline synchronization protocols remain incompatible with end-to-end encryption standards, forcing trade-offs between accessibility and security certification.
Strategic Opportunities
- Underpenetrated mid-market manufacturing:Industrial firms in Germany lag in cloud productivity adoption due to legacy ERP integration concerns, creating whitespace for middleware specialists.
- EU AI Act compliance services:Risk classification requirements for automated decision-making tools create ancillary revenue streams for audit and documentation automation.
- Convergence of low-code platforms:Citizen developer tools are merging with traditional document editors, enabling workflow automation without dedicated IT resources.
Industry Challenges
- Specialized talent scarcity:Security architects with cross-certification in ISO 27001 and FedRAMP command premium compensation, constraining vendor hiring pipelines.
- Legacy system integration friction:On-premises SharePoint and Lotus Notes environments resist API-based migration, extending sales cycles for replacement vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Office Software Market |
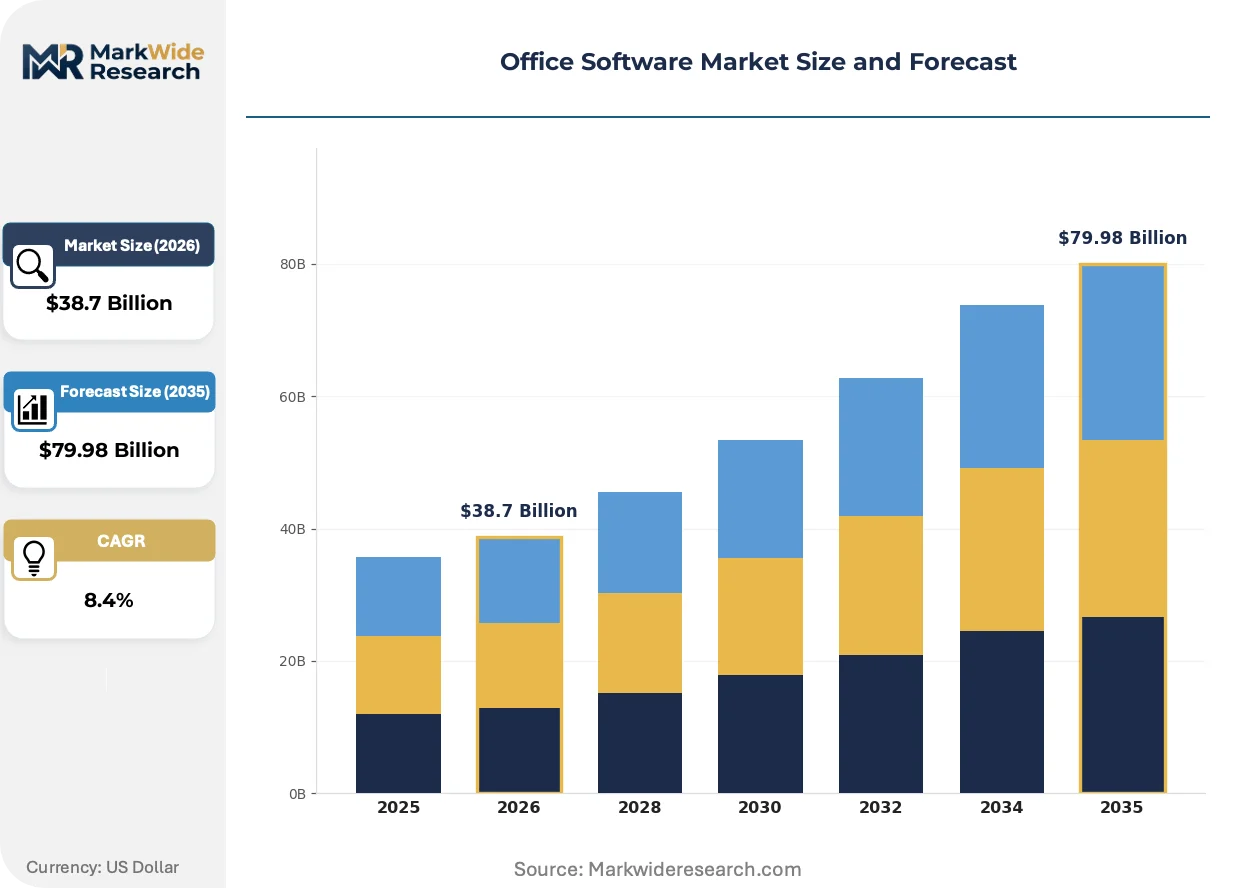
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Word Processing, Spreadsheet, Presentation, Email Client Deployment: On-Premises, Cloud-Based, Hybrid, Mobile End User: Small Businesses, Enterprises, Freelancers, Educational Institutions Pricing Model: Subscription, One-Time Purchase, Freemium, Volume Licensing |
| Companies Covered | Workday, IBM, Microsoft, Smartsheet, Infor, Google, Atlassian, Xerox, Oracle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Office Software Market Strategic Shifts & Innovations
Generative AI capabilities are embedding directly into core document creation interfaces, eliminating the friction of context-switching between standalone tools and collapsing the distinction between authoring and automation layers.
Large language model integration is bifurcating the productivity software landscape. Foundation-model-powered drafting assistants now handle routine correspondence generation for legal and consulting sectors. Mid-market professional services firms are adopting these tools at the fastest pace, replacing junior staff hours with automated first-draft production. This compression of entry-level workflow tasks is bifurcating vendor strategies between premium AI-augmented tiers and stripped-down compliance-focused alternatives.
CSRD disclosure requirements in the European Union are mandating granular reporting on software supply chain emissions. Vendors must now document energy consumption per user-hour across data center operations. Cloud-native providers with renewable energy matching are capturing procurement preference in France and the Netherlands, while legacy on-premises vendors face stranded asset risk as Scope 3 calculations expose hidden infrastructure footprints.
Subscription fatigue among freelance and small-business segments is driving unbundling of productivity suites into modular component purchases. Buyers in the United Kingdom are increasingly selecting standalone document editors and separate video conferencing tools rather than unified packages. Channel partners are responding with curated best-of-breed bundles that mask underlying fragmentation through single-invoice billing, capturing margin from configuration complexity that vendors leave unaddressed.
Office Software Market Segmentation
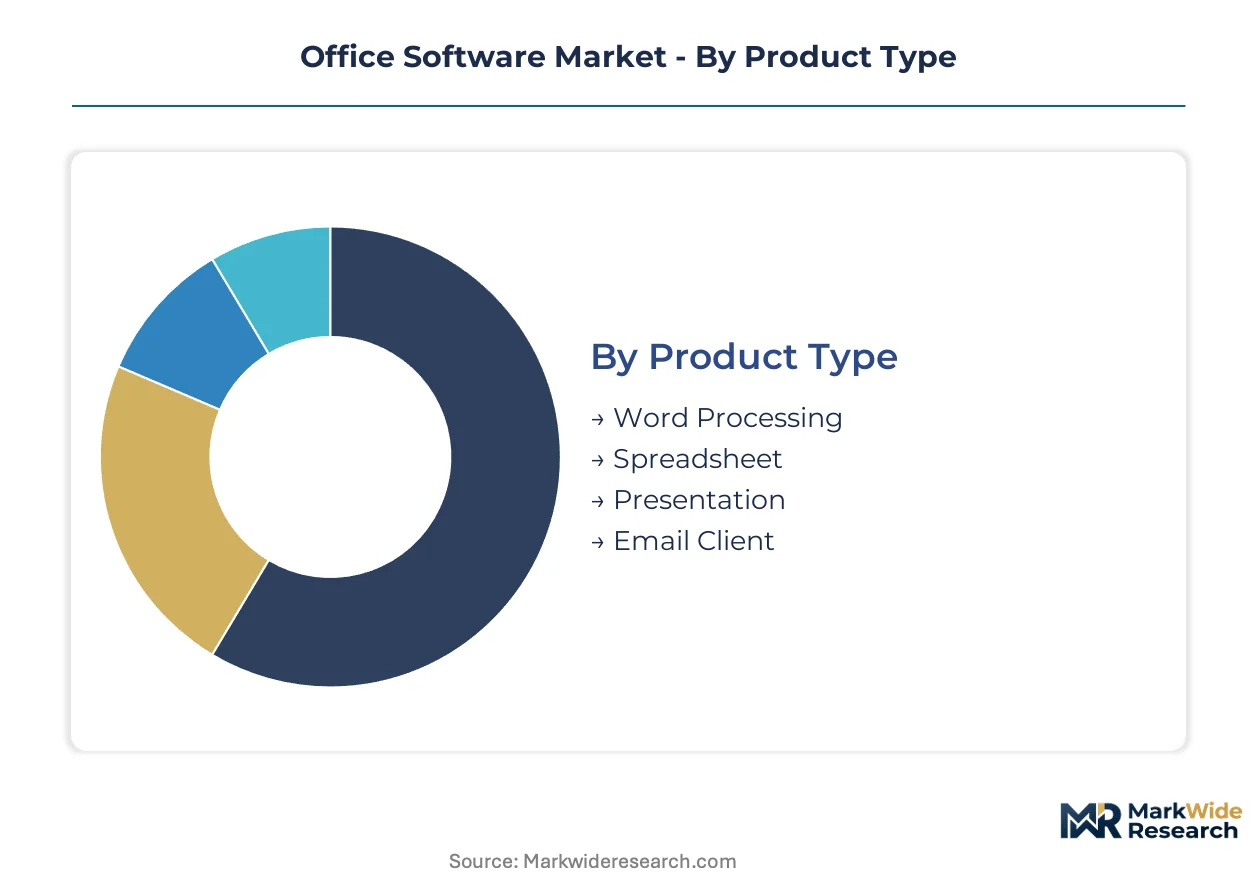
Office software segmentation reveals divergent growth mechanics across delivery modes and buyer economics. Procurement patterns split sharply between capital-constrained segments prioritizing operational flexibility and regulated industries demanding sovereign data control.
Product Type:
Word Processing tools anchor domestic enterprise procurement in the United States and Germany, while Spreadsheet and Presentation segments drive cross-border licensing volumes through multinational standardization mandates.
- Word Processing:Core document creation platforms with real-time collaboration engines and version-control architectures. Demand concentrates in legal services and government contracting clusters across Washington D.C. and Brussels, where audit trails and redaction capabilities satisfy FOIA and GDPR documentation standards.
- Spreadsheet:Data analysis environments featuring pivot-table automation and API connectivity to ERP systems. Financial services buyers in London and Singapore dominate premium licensing, compelled by SEC and MAS audit requirements for model transparency and cell-level change logging.
- Presentation:Visual communication tools with template standardization and brand-asset management. Corporate communications departments in Fortune 500 headquarters drive renewal rates.
- Email Client:Electronic correspondence systems with encryption-at-rest and calendar integration. Healthcare networks in the United States prioritize HIPAA-compliant hosting configurations.
Word Processing commands the established base. The steepest expansion runs through Spreadsheet as financial modeling automation displaces manual analyst workflows.
Deployment:
Cost-tier stratification separates capital-intensive On-Premises installations from operational-expense Cloud models favored by mid-market buyers with constrained IT staffing.
- On-Premises:Local server installations with sovereign data control and air-gapped security architectures. Defense contractors and classified research facilities in the United States mandate FedRAMP-authorized on-premises stacks, rejecting external hosting despite 40-60% higher total cost of ownership.
- Cloud-Based:Browser-native delivery with automatic patching and elastic scaling. Professional services firms in the United Kingdom and Netherlands adopt fastest, drawn by zero-touch provisioning and CSRD-aligned renewable energy disclosures from hyperscaler providers.
- Hybrid:Split architectures keeping sensitive data on-premises while routing collaboration through cloud gateways. German automotive manufacturers favor this model to satisfy works-council data sovereignty requirements.
- Mobile:Containerized smartphone and tablet deployments with sandboxed corporate data. Healthcare BYOD policies in Singapore and UAE drive specialized demand for biometric-secured mobile editors.
Cloud-Based deployment captures the majority of new contract value. Hybrid architectures gain share fastest among regulated European manufacturers reconciling legacy ERP integration with workforce mobility demands.
End User:
Volume concentration varies dramatically: Enterprises generate multi-thousand-seat contracts with 3-5 year terms, while Freelancers drive user-base expansion through viral adoption and low-friction onboarding.
- Small Businesses:Organizations with under 50 employees prioritizing cost predictability and minimal IT overhead. Restaurant chains and retail franchises in India and Brazil favor bundled suites with local-language support and UPI/Pix payment integration.
- Enterprises:Large organizations with dedicated procurement functions and custom integration requirements. Banking and insurance headquarters in New York, London, and Tokyo negotiate enterprise agreements with dedicated customer success teams and SLA-guaranteed uptime.
- Freelancers:Independent contractors and gig-economy workers purchasing individual licenses. Creative professionals in Lisbon and Mexico City drive freemium-to-paid conversion through project-based revenue cycles.
- Educational Institutions:Universities and K-12 districts with volume-discounted academic licensing. State university systems in the United States negotiate system-wide agreements covering faculty, staff, and enrolled students.
Enterprises command the established base. Freelancers represent the fastest-climbing segment as platform economics prioritize land-and-expand viral mechanics over direct sales investment.
Pricing Model:
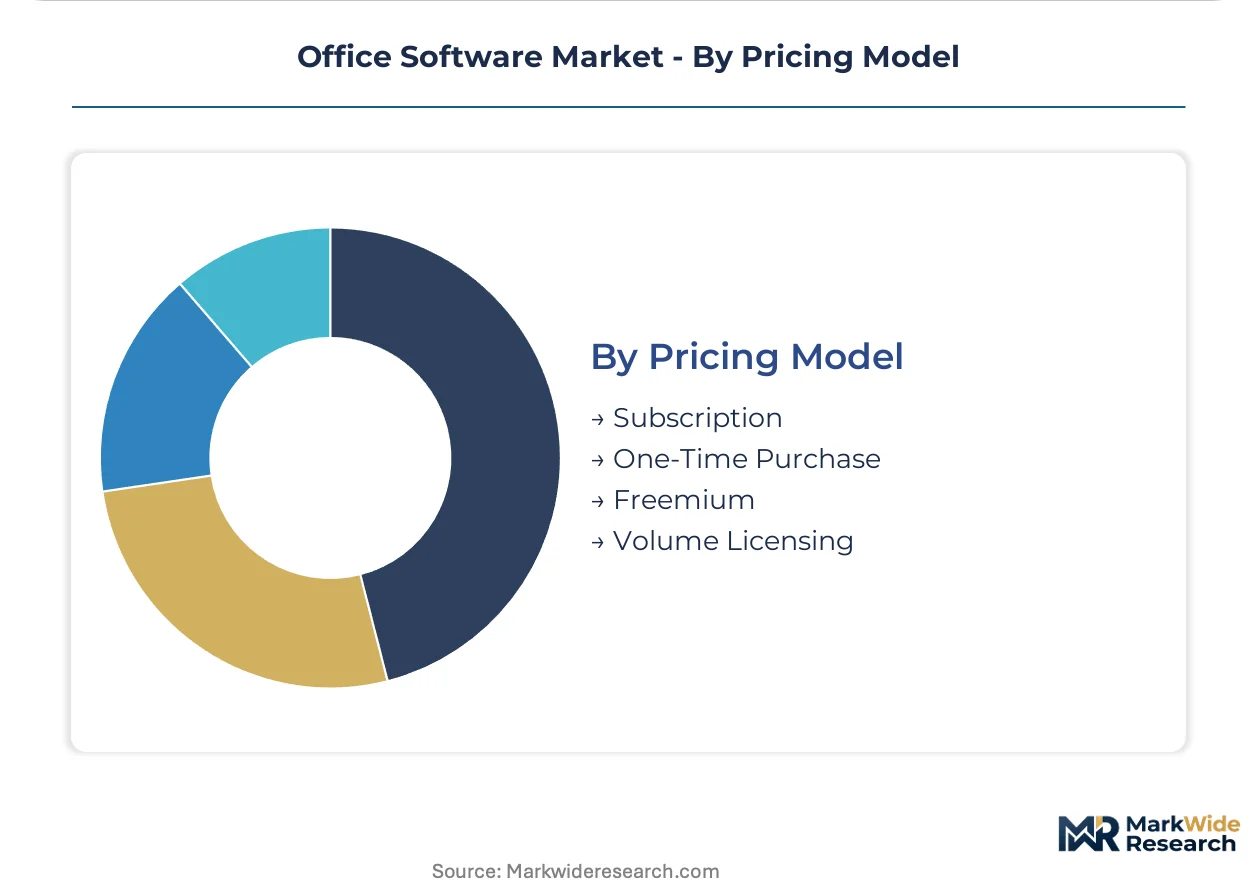
Margin structures diverge sharply between recurring-revenue Subscription models with 85%+ gross margins and transactional One-Time Purchase licenses with front-loaded cash flows but elevated support obligations.
- Subscription:Recurring monthly or annual payments with continuous feature updates and cloud storage inclusion. SaaS-native vendors targeting mid-market professional services in Australia and Canada achieve 120%+ net revenue retention through seat expansion and tier upgrades.
- One-Time Purchase:Perpetual licenses with optional maintenance contracts. Legacy manufacturing firms in Japan and South Korea retain preference for capitalized software assets matching depreciation schedules.
- Freemium:Tiered access with basic functionality at no cost and premium features paywalled. Solo practitioners and micro-agencies in Spain and Italy convert at 3-5% rates to paid tiers.
- Volume Licensing:Negotiated enterprise agreements with tiered discounts based on seat commitments. Federal agencies in the United States procure through GSA schedules with pre-negotiated pricing ceilings.
Subscription pricing commands the established base. Freemium conversion engines deliver the steepest user-base expansion trajectory among digitally native small-business formations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscaler infrastructure concentrates in the United States, creating latency advantages for real-time collaboration vendors while European and Asian markets develop sovereign-cloud alternatives. Procurement patterns diverge sharply between federal-heavy US demand, GDPR-regulated European enterprise upgrades, and mobile-first adoption across Asia-Pacific.
United States
Federal agencies drive premium licensing volumes through zero-trust mandates and FedRAMP certification requirements. SEC disclosure rules intersect with FCC data integrity guidelines, layering compliance obligations on publicly traded software vendors. Washington D.C. and Northern Virginia host concentrated government contracting clusters where audit-trail capabilities command procurement priority.
Germany
Automotive manufacturers and industrial Mittelstand firms lag in cloud migration due to legacy ERP integration concerns and works-council data sovereignty requirements. GDPR Article 32 encryption mandates accelerate certified-provider selection among enterprises. Stuttgart and Munich anchor manufacturing headquarters where hybrid deployment models reconcile workforce mobility with on-premises data control.
United Kingdom
Subscription fatigue drives unbundling of productivity suites into modular component purchases among freelance and small-business segments. Channel partners respond with curated best-of-breed bundles masking underlying fragmentation. London's financial services sector dominates spreadsheet premium licensing, compelled by FCA audit requirements for model transparency.
Japan
Legacy manufacturing firms retain preference for capitalized software assets matching depreciation schedules, slowing subscription-model penetration. METI digital transformation incentives pressure mid-market enterprises toward cloud-native alternatives. Tokyo and Osaka headquarters drive conservative procurement patterns favoring established vendors with localized support infrastructure.
India
Small-business formations and gig-economy workers drive freemium-to-paid conversion through project-based revenue cycles. UPI payment integration and local-language support shape vendor localization strategies. Bangalore and Mumbai host technology services clusters where mid-market professional services firms adopt AI-augmented drafting tools fastest.
Office Software Market Key Industry Players
Concentration sits with hyperscale platform providers embedding productivity suites within broader cloud infrastructure ecosystems. The vendor base stratifies across three tiers: full-stack infrastructure-software integrators, browser-native collaboration specialists, and compliance-focused regulated-sector providers. Dominant competitive moves include API-based ecosystem expansion and vertical industry solution packaging.
Within the infrastructure-integrated tier, Microsoft and Google anchor opposing strategic vectors—Microsoft through deep OS-cloud-application layering, Google through real-time collaboration architectures. IBM occupies a position among regulated-sector specialists, exemplifying encryption-standard differentiation for healthcare and government buyers. Oracle represents the enterprise-application-integrated archetype, leveraging database-to-productivity workflow connectivity.
| Leading Market Players |
|---|
| Workday |
| IBM |
| Microsoft |
| Smartsheet |
| Infor |
| Atlassian |
| Xerox |
| Oracle |
| Others |
Cost & Logistics Intelligence
GPU cluster substitution for on-premises inference hardware simultaneously concentrates supply geography in United States hyperscaler regions and compresses pricing economics for AI-augmented productivity tiers, forcing vendors to restructure subscription bundles around compute-access metering rather than flat per-seat rates.
Pricing Analysis
GDPR Article 32 and FedRAMP certification requirements dictate the pricing tier structure across European and United States government segments. Three-tier pricing separates FedRAMP-authorized enterprise suites from standard commercial tiers and freemium entry levels. Price differentiation hinges on encryption-grade certification and dedicated customer success staffing. Pricing pressure stems from GPU cost inflation squeezing AI feature margins. Freelancers and micro-agencies exhibit highest price sensitivity, while federal agencies accept premium positioning for compliance guarantees.
Supply Chain Analysis
The United States anchors hyperscaler infrastructure concentration for cloud-hosted productivity workloads, while Ireland and Singapore host secondary regions for latency-sensitive real-time collaboration. Supply draws from GPU fabrication in Taiwan, memory modules from South Korea, and specialized encryption hardware from domestic defense contractors. Single-region dependency creates vulnerability for European enterprises requiring sub-50ms latency. Distribution runs through direct enterprise sales teams, GSA schedules for federal buyers, and channel partners masking modular fragmentation for small-business segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflect around API-based ecosystem expansion, where interoperability standards determine vendor lock-in risk and procurement officers weight integration depth against switching costs.
For Market Incumbents: Fortify position through backward integration into GPU cluster capacity and FedRAMP certification pipelines. Deepen vertical control over identity-per-session architectures to defend against browser-native challengers. Prioritize middleware investments that bridge legacy SharePoint environments to cloud gateways, extending replacement cycle friction.
For New Entrants and Emerging Players: Anchor in German automotive Mittelstand hybrid deployment whitespace, where works-council data sovereignty requirements delay hyperscaler adoption. Target mid-market professional services in India and Brazil with UPI-integrated freemium conversion engines. Pursue channel partnerships that bundle standalone document editors with localized payment infrastructure.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors compliance-focused specialists with ISO 27001-FedRAMP cross-certification. Long-term viability centers on AI governance tooling revenue streams as EU AI Act documentation requirements expand. Watch for hyperscaler capex allocation shifts as signal for inference pricing inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API ecosystem depth determines procurement lock-in for enterprise buyers evaluating switching costs. |
| Acquisition of Specialist Firm | Compliance automation vendors with EU AI Act tooling command premium positioning in European markets. |
| Geographic Expansion | Sovereign cloud deployments in Germany and France satisfy GDPR data residency mandates for automotive manufacturers. |
| Strategic Partnership | Channel alliances with ERP integrators accelerate mid-market manufacturing penetration against legacy resistance. |
| Product Launch | Containerized mobile editors with biometric security capture healthcare BYOD procurement in Singapore and UAE. |
Research Approach
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capex disclosures, App Annie mobile adoption metrics, and GSA schedule pricing databases. Primary interviews engaged CTOs at Fortune 500 headquarters, IT procurement officers in federal agencies, platform engineers at collaboration software vendors, and channel partners curating best-of-breed bundles. Bottom-up seat expansion modeling triangulates against top-down enterprise licensing value analysis.
Segmentation dimensions modeled span deployment architecture, organization size tier, vertical industry, integration complexity level, and regional adoption pattern across the analysis window. CAGRs derive from elasticity-adjusted pricing trajectories and seat penetration curves. Forecast inputs incorporate GPU cluster pricing volatility and CSRD-aligned renewable energy disclosure timelines affecting hyperscaler procurement preferences.
Material uncertainties — regulatory fragmentation in AI governance, hyperscaler supply concentration, and subscription fatigue velocity — sit outside the modeled envelope. Forecasts reflect documented assumptions on enterprise migration pace and freemium conversion mechanics. Recalibration cycles align with material shifts in FedRAMP authorization timelines and EU AI Act enforcement thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
North America Saas-Based Expense Management Market
Software & Services
Global App Store Optimization Tools Software Market
Software & Services
Global Inspection Management Software Market
Software & Services
Voice to Text on Mobile Devices Market
Software & Services
Petcare Software Market
Software & Services
Data Migration Software Services Market
Software & Services
Global Molecular Modeling Software for Chemistry Market
Software & Services
Tech Support Services Market
Software & Services
Streaming Server Software Market
Software & Services
Estate Management Software Market
Software & Services
Batch Management Software Market
Software & Services
Global Employee Engagement Software Market
Software & Services
Global Managed Application Services Market
Software & Services
User Retention Software Market
Software & Services
HR Tech Market
Software & Services
Global Manufacturing Operations Management (MOM) Software Market