
 Tableau Services Market | 2026-2036
Tableau Services Market Size, Share, and Industry Trends Forecast 2026-2036
Tableau Services Market Outlook
The gap between premium managed analytics engagements and commodity self-service deployments is broadening. Salesforce leverages its Einstein integration to sustain high-margin consulting relationships. Microsoft anchors enterprise demand through Power BI interoperability with Azure data lakes. SAP differentiates by embedding Tableau workflows into S/4HANA environments for manufacturing clients.
Tableau Services encompass data visualization consulting, platform implementation, user training, and ongoing technical support delivered by certified partners and independent specialists. These services require expertise in SQL-based data preparation, REST API connectivity, and governance frameworks that enforce row-level security across multi-source dashboards. Implementation and consulting command the largest revenue share as enterprises migrate legacy reporting infrastructure. Cloud deployment is expanding fastest among mid-market buyers seeking subscription-based scalability without capital expenditure.
ISO 27001 certification requirements shape vendor selection criteria for European and North American buyers. GDPR and HIPAA frameworks mandate audit trails and access controls that elevate demand for specialized compliance implementation services. Stakeholders must weigh captive in-house capabilities against partner ecosystems as AI-augmented analytics redefines service boundaries.
Market Dynamics
Cloud migration mandates and data sovereignty requirements are fragmenting procurement patterns across enterprise Tableau deployments, forcing service providers to reconfigure delivery architectures around localized infrastructure requirements.
Growth Catalysts
- GDPR audit mandates:European enterprises require specialized compliance implementation services that embed row-level security and audit trails into multi-source dashboards, elevating demand for certified technical support.
- Healthcare analytics expansion:HIPAA frameworks drive hospital systems to replace legacy reporting infrastructure with governed visualization platforms that optimize patient outcomes through real-time operational dashboards.
- Manufacturing S/4HANA integration:Industrial clients embed Tableau workflows directly into ERP environments to unify production metrics with supply chain visibility, requiring specialized implementation consulting.
Market Restraints
- SQL expertise scarcity:Shortage of certified specialists capable of complex data preparation and REST API connectivity elevates labor costs and extends implementation timelines for mid-market buyers.
- Data localization requirements:Sovereignty rules in Germany, France, and India force service providers to maintain redundant infrastructure, compressing margins on standard engagements.
- Power BI substitution pressure:Microsoft's Azure-embedded analytics bundle captures price-sensitive enterprises seeking unified cloud data lake interoperability without separate visualization procurement.
Strategic Opportunities
- India's mid-market cloud acceleration:Subscription-based scalability without capital expenditure attracts regional enterprises seeking rapid deployment without on-premise infrastructure investment.
- ISO 27001 certification arbitrage:Specialized compliance implementation services command premium pricing from North American and European buyers with mandatory vendor security frameworks.
- AI-augmented analytics convergence:Integration of natural language query interfaces with existing visualization platforms creates new service boundaries around automated insight generation and governance.
Industry Challenges
- Row-level security implementation complexity:Multi-source dashboard governance requires specialized expertise that outpaces available certification pipeline capacity, creating delivery bottlenecks.
- Legacy reporting migration friction:Enterprises with decades of embedded Crystal Reports or Business Objects infrastructure face extended parallel-running periods that strain project economics.
- Einstein integration skill gaps:Salesforce's proprietary AI layer demands cross-trained specialists capable of bridging CRM data models with external visualization architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tableau Services Market |
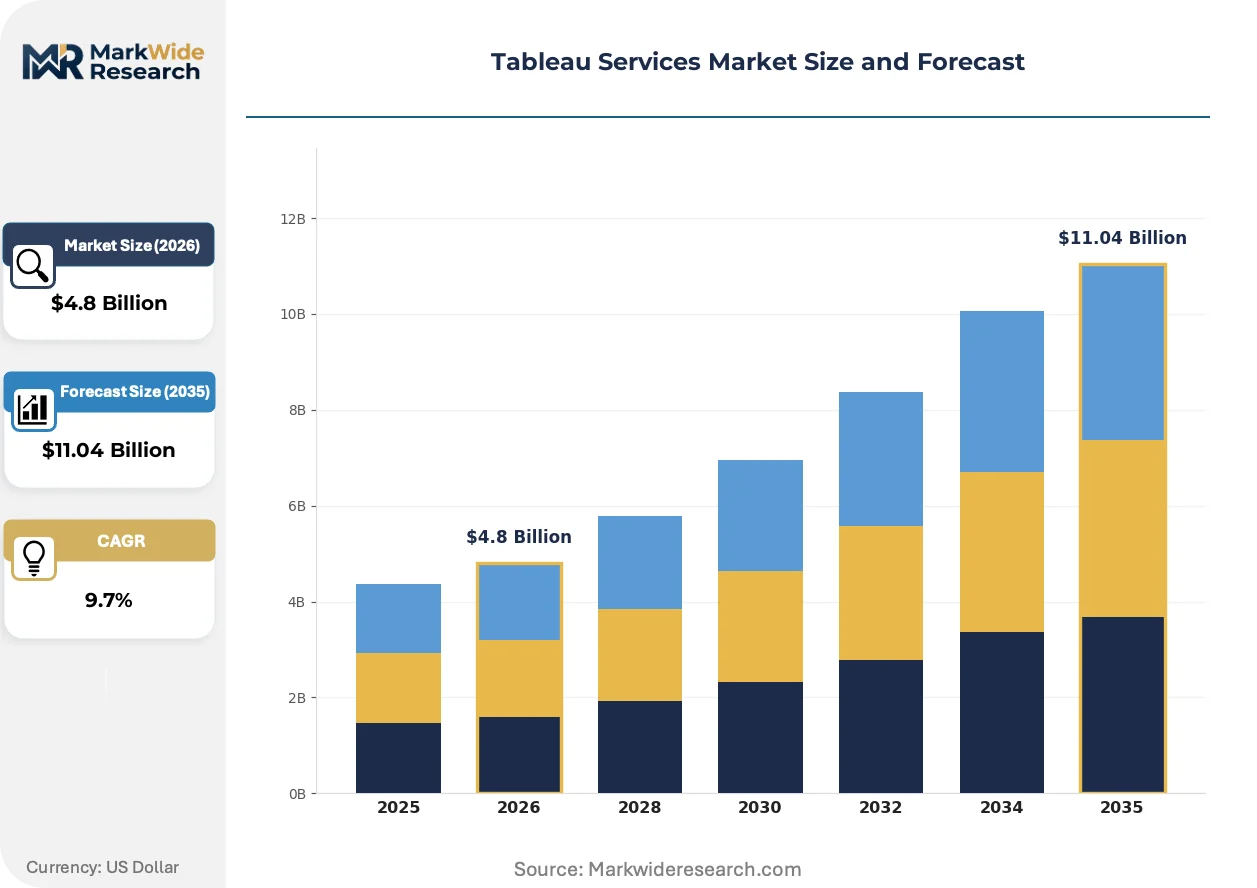
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Training, Implementation, Support Deployment Model: On-Premises, Cloud, Hybrid, Managed End User: SMEs, Large Enterprises, Government, Educational Institutions Industry Vertical: Healthcare, BFSI, Retail, Manufacturing |
| Companies Covered | Salesforce, Microsoft, SAP, IBM, Oracle, Google Cloud, Amazon Web Services, Tata Consultancy Services, Slalom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tableau Services Market Strategic Shifts
Service delivery models are bifurcating between high-touch managed analytics engagements and automated self-service platforms, with AI-augmented capabilities redefining the boundary between consultant and software functionality.
Natural language query interfaces are overtaking traditional drag-and-drop dashboard construction as the primary user interaction mode. Healthcare providers and financial services teams adopt conversational analytics to compress insight generation cycles from hours to minutes. This shift is overtaking conventional training revenue streams as embedded guidance reduces dependency on formal user education programs.
CSRD sustainability disclosure requirements in Europe mandate granular emissions tracking and supply chain transparency reporting. Industrial manufacturers must reconfigure data pipelines to capture Scope 3 carbon metrics across tiered supplier networks. German automotive and chemical clusters face the most acute compliance deadlines, driving concentrated demand for specialized ESG dashboard implementation through 2025.
Subscription-based technical support unbundling is fragmenting traditional annual maintenance contracts. Mid-market buyers in the United States and India prefer consumption-based incident resolution over prepaid entitlement models. This reconfiguration is most visible among SaaS-native companies that treat visualization infrastructure as operational expenditure rather than capital investment.
Tableau Services Market Segmentation
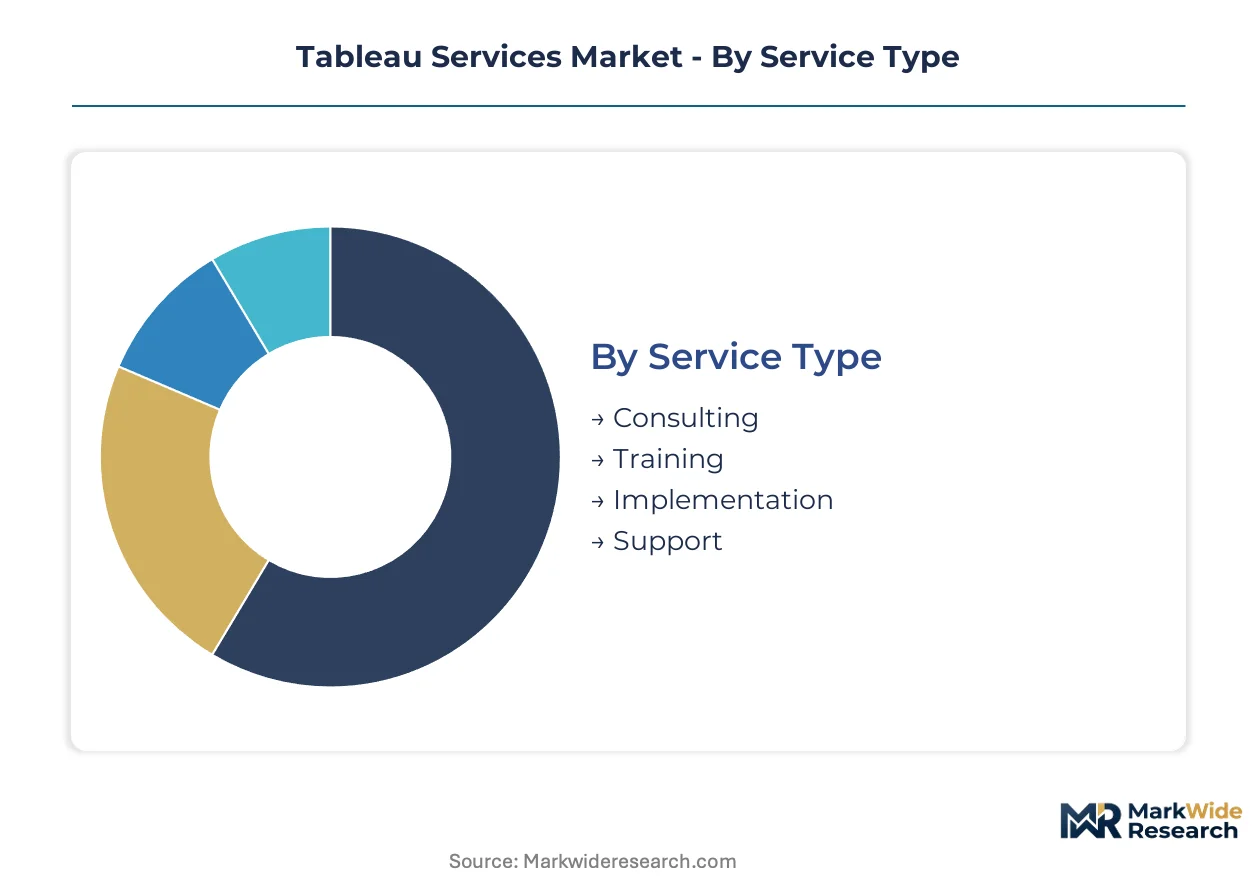
Service segmentation in the Tableau market reveals how procurement patterns diverge between capital-intensive implementation projects and recurring operational expenditures. Understanding these splits enables vendors to align delivery models with client maturity levels and compliance requirements.
Service Type:
Upgrade and replacement cycles vary dramatically across service categories, with legacy reporting migrations driving concentrated consulting demand while cloud-native deployments shift spend toward subscription support models.
- Consulting:Strategic advisory engagements cover data architecture design, governance framework development, and multi-source integration planning. Healthcare systems in the United States and manufacturing clusters in Germany concentrate demand here as HIPAA and GDPR mandates force platform redesigns.
- Implementation:Technical deployment services encompass server configuration, REST API connectivity, and row-level security provisioning. Indian mid-market enterprises and European automotive suppliers are expanding this segment fastest as they migrate from on-premise Crystal Reports infrastructure.
- Training:User enablement programs range from administrator certification to end-user dashboard construction. Natural language query interfaces are compressing traditional classroom revenue as embedded guidance reduces formal education dependency.
- Support:Ongoing technical assistance includes incident resolution, version upgrades, and performance optimization. Consumption-based unbundling is fragmenting annual maintenance contracts among SaaS-native buyers in India and the United States.
Implementation sits at the top of the volume ranking, with Support climbing the fastest as subscription models displace prepaid entitlements.
Deployment Model:
Cost tier differentiation separates buyers seeking capital expenditure avoidance from those requiring sovereign data control.
- Cloud:Subscription-based scalability without infrastructure ownership attracts mid-market buyers and SaaS-native enterprises. India's regional enterprises and United States software companies dominate this tier, prioritizing rapid deployment over customization depth.
- On-Premises:Self-managed server installations persist among defense contractors, financial institutions with legacy mainframe dependencies, and German manufacturers with strict operational technology isolation requirements.
- Hybrid:Split architectures place sensitive data on-premise while leveraging cloud compute for development and testing. European pharmaceutical companies and United States hospital networks favor this model to satisfy GDPR and HIPAA audit mandates.
- Managed:Third-party hosted environments with dedicated operational support. German automotive suppliers and Indian BFSI institutions are expanding this segment to access ISO 27001-certified infrastructure without captive capability investment.
Cloud captures the dominant share of new engagements, with Hybrid expanding most quickly as sovereignty requirements fragment procurement patterns.
End User:
Customer type determines service packaging complexity, from standardized training modules for resource-constrained buyers to bespoke governance frameworks for regulated institutions.
- Large Enterprises:Multi-divisional deployments require dedicated implementation teams, custom security integration, and ongoing managed services. German chemical conglomerates and United States healthcare systems anchor this segment with multi-year consulting relationships.
- SMEs:Mid-market buyers prioritize rapid time-to-value through templated dashboards and subscription-based support. Indian regional enterprises and United States professional services firms are concentrating demand here as cloud economics reduce entry barriers.
- Government:Public sector procurement mandates extended compliance documentation, citizen data sovereignty controls, and audit trail preservation. German federal agencies and Indian state-level administrations drive specialized requirements.
- Educational Institutions:Universities and research organizations leverage academic licensing programs with scaled training components. United States research hospitals and Indian technical universities represent primary demand centers.
Large Enterprises retain the highest absolute spend, with SMEs gaining share fastest as cloud deployment compresses implementation timelines.
Industry Vertical:
Application-specific requirements force service customization around regulatory frameworks, data velocity patterns, and user technical sophistication.
- Healthcare:HIPAA-mandated audit trails, patient outcome optimization, and real-time operational dashboards define implementation scope. United States hospital systems and German university hospitals are replacing legacy reporting infrastructure with governed visualization platforms.
- BFSI:Risk analytics, regulatory reporting, and customer segmentation drive demand for row-level security expertise. Indian regional banks and German insurance conglomerates concentrate procurement as Basel and RBI frameworks tighten data governance.
- Manufacturing:S/4HANA integration, supply chain visibility, and CSRD-mandated emissions tracking require specialized ERP connectivity. German automotive and chemical clusters face acute compliance deadlines through 2025.
- Retail:Customer behavior analytics, inventory optimization, and omnichannel performance tracking shape service requirements. United States e-commerce platforms and Indian consumer goods distributors prioritize self-service deployment speed.
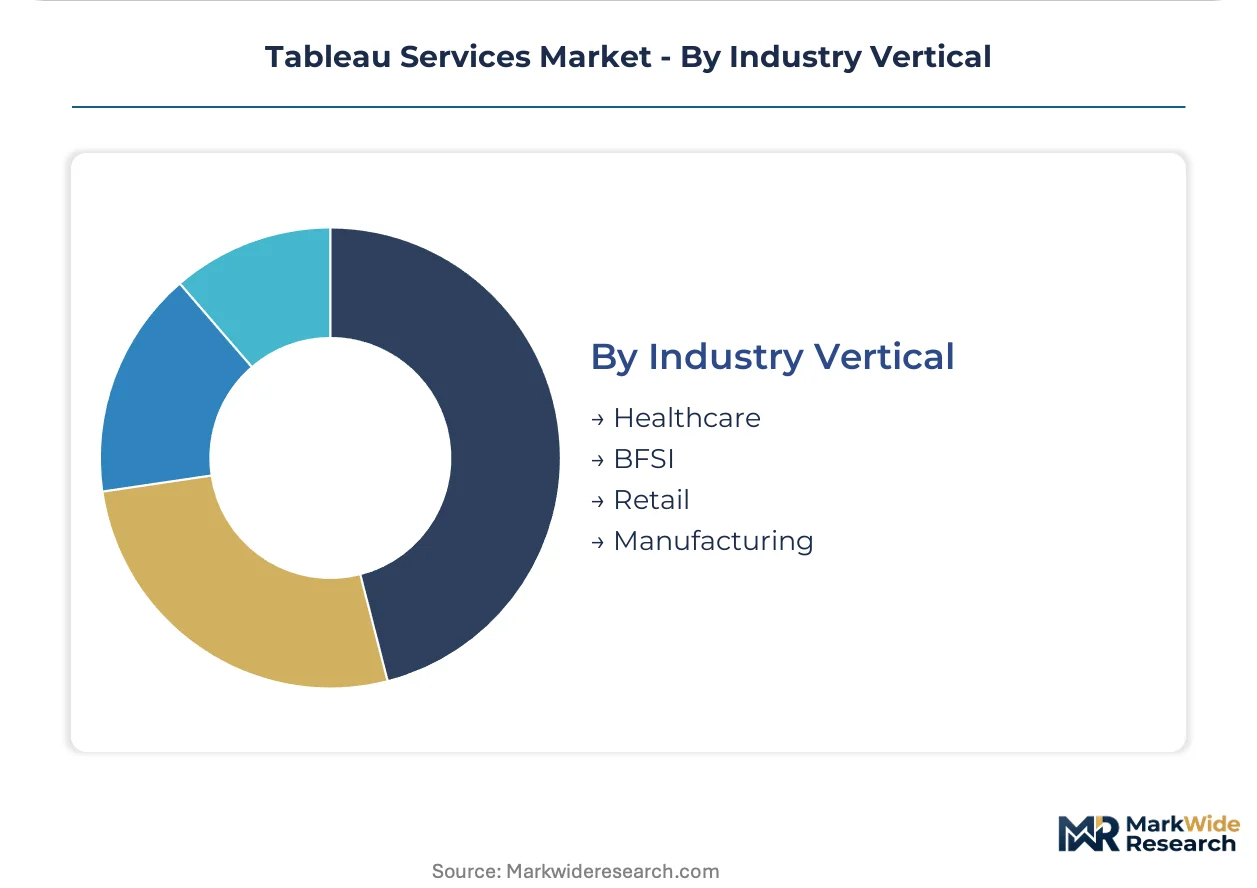
Healthcare leads vertical spend, with Manufacturing expanding most steeply as sustainability disclosure mandates reconfigure data pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified Tableau specialists cluster in the United States, Germany, and India, with each geography anchoring distinct service delivery models shaped by regulatory frameworks and enterprise procurement preferences.
United States
Healthcare systems in Massachusetts and California drive HIPAA-mandated governance implementations, replacing legacy reporting infrastructure with real-time operational dashboards. FDA audit requirements for clinical data visualization elevate demand for specialized compliance consulting. Hospital networks in the Greater Boston area anchor the highest concentration of premium managed analytics engagements.
Germany
Automotive suppliers in Bavaria and chemical conglomerates in North Rhine-Westphalia embed Tableau workflows into S/4HANA environments for CSRD-mandated emissions tracking. GDPR audit mandates from CNIL and BSI certification requirements force redundant localized infrastructure investments. The Stuttgart automotive cluster faces acute sustainability disclosure deadlines through 2025.
India
Mid-market enterprises in Maharashtra and Karnataka prioritize cloud-native deployments to avoid capital expenditure on on-premise infrastructure. RBI data localization guidelines for BFSI institutions drive demand for ISO 27001-certified managed hosting. Mumbai-based regional banks and Bangalore SaaS companies concentrate subscription-based technical support procurement.
United Kingdom
Financial services firms in London and Edinburgh adopt hybrid deployment models to satisfy FCA audit trail requirements while leveraging cloud compute for development. The Information Commissioner's Office enforces GDPR-aligned row-level security implementations. Edinburgh's insurance technology cluster represents the fastest-growing demand center for governance framework consulting.
Japan
Manufacturing headquarters in Tokyo and Osaka integrate visualization platforms with METI-promoted smart factory initiatives. Personal Information Protection Commission mandates restrict cross-border data flows, elevating demand for domestic implementation partners. The Nagoya automotive corridor anchors specialized ERP connectivity services for production metric unification.
Tableau Services Market Competitive Environment
Top-tier vendors anchor enterprise consulting relationships, while mid-tier specialists capture implementation velocity in regulated verticals. The vendor base stratifies across three concentration levels: hyperscale cloud platforms with embedded analytics, certified implementation partners with vertical expertise, and independent training specialists. Strategic archetypes include Salesforce leveraging Einstein integration for high-margin retention, Microsoft bundling Power BI with Azure data lakes for price-sensitive capture, and SAP embedding workflows into S/4HANA for manufacturing lock-in. Dominant competitive moves center on M&A for vertical capability depth and geographic expansion through localized certification pipelines.
Among hyperscale platform operators, Salesforce and Microsoft occupy positions at opposite ends of the pricing spectrum, with the former exemplifying premium managed analytics anchoring and the latter representing bundled substitution pressure. SAP sits within the ERP-embedded specialization tier, while IBM and Oracle exemplify legacy technology vendors repositioning through services arms. Tata Consultancy Services anchors the India-based implementation scale tier, with Slalom representing the boutique consulting archetype focused on rapid deployment velocity.
| Leading Market Players |
|---|
| Salesforce |
| Microsoft |
| SAP |
| IBM |
| Oracle |
| Google Cloud |
| Amazon Web Services |
| Tata Consultancy Services |
| Slalom |
| Others |
Value Chain & Pricing Dynamics
CSRD sustainability disclosure mandates in Europe gate both qualified supply and premium-tier pricing access, as German automotive and chemical clusters demand ISO 27001-certified implementation partners capable of embedding emissions-tracking dashboards into S/4HANA environments. Service providers without localized compliance infrastructure face margin compression while certified specialists capture premium positioning.
Pricing Analysis
The bundled-versus-unbundled service split defines pricing architecture across the Tableau services landscape. Annual maintenance contracts fragment into consumption-based incident resolution models as SaaS-native buyers in India and the United States prefer operational expenditure treatment. Three-tier pricing structure across premium managed analytics, standard implementation, and economy self-service tiers separates Salesforce's Einstein-anchored consulting relationships from commodity deployment shops. Cost compression in mid-market cloud engagements intensifies because Power BI's Azure bundling captures price-sensitive procurement, leaving pure-play Tableau specialists exposed. Healthcare systems exhibit least price sensitivity due to HIPAA-mandated governance requirements, while Indian regional enterprises demonstrate highest elasticity.
Supply Chain Analysis
Domestic-content mandates in Germany, India, and Japan reshape sourcing patterns for certified implementation talent. Supply concentrates among United States-based hyperscale platforms, German ERP-embedded specialists, and India-scale delivery organizations. The talent pipeline draws from SQL-certified data engineers, REST API integration specialists, and governance framework architects. Single-source vulnerability runs through Salesforce's Einstein integration certification pathway, which constrains cross-trained specialist availability. Distribution runs through direct enterprise sales, certified partner networks, and hyperscaler marketplaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as cloud migration mandates across healthcare, manufacturing, and financial services institutionalize recurring analytics infrastructure spend. Regulatory compliance requirements create durable demand floors.
For Market Incumbents: Cement high-margin retention through captive certification pipelines in Germany and India that lock in S/4HANA-embedded workflows and HIPAA-compliant managed services. Deepen backward integration into AI-augmented analytics tooling to offset natural language query compression of traditional training revenue. Defend against Microsoft's Azure-embedded bundling by emphasizing governance depth that Power BI's standardized security models cannot replicate.
For New Entrants and Emerging Players: AI-augmented natural language interfaces offer a technology-first wedge into mid-market healthcare and manufacturing segments underserved by incumbent consulting density. Target India's subscription-preferring SaaS companies with rapid-deployment implementation templates that bypass legacy migration complexity. Pursue ISO 27001 certification arbitrage as the primary go-to-market angle, positioning compliance implementation as premium-tier entry point.
For Investors and Strategic Acquirers: Roll-up economics work for boutique Tableau specialists because vertical expertise scarcity in healthcare HIPAA implementations and German CSRD compliance creates pricing power for certified regional players. Acquire targets with established S/4HANA integration practices or healthcare operational dashboard portfolios. Watch for inflection when AI-augmented analytics crosses 30% of new engagements, signaling automation-driven margin restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pipeline Investment | ISO 27001 and GDPR-specialized talent pools in Germany and India capture premium pricing from regulated buyers. |
| AI-Augmented Analytics Integration | Natural language query interfaces embedded in existing platforms compress implementation timelines for mid-market buyers. |
| Vertical Capability Acquisition | Healthcare HIPAA and manufacturing CSRD expertise deepens consulting margins through compliance-mandated redesigns. |
| Cloud-Native Deployment Expansion | Subscription-based managed hosting in India satisfies RBI data localization without client capital expenditure. |
| Hyperscaler Partnership Structuring | Salesforce Einstein and Azure interoperability agreements anchor enterprise relationships against substitution pressure. |
Study Parameters
Multiple input streams — primary interviews with data architecture directors, IT procurement officers, and certified Tableau implementation partners; secondary validation through SEC filings, hyperscaler capex disclosures, and healthcare system procurement databases; plus customs records on software services trade — were reconciled to construct market estimates. Bottom-up project pipeline analysis and top-down enterprise IT spend allocation were triangulated to cross-check volume assumptions.
Data-stream reconciliation across deployment model, organization size, vertical industry, integration complexity, and regional adoption pattern dimensions shaped the analytical framework. CAGRs were derived from segment-level growth rate reconciliation against macro IT services expansion benchmarks. Forecast inputs included cloud migration velocity indices and regulatory compliance deadline clustering.
The model holds under stable regulatory enforcement of GDPR, HIPAA, and CSRD mandates; deviation in data sovereignty rule relaxation or AI automation acceleration would shift service mix assumptions. Forecasts reflect documented assumptions on certification pipeline capacity and hyperscaler bundling intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Managed File Transfer Software Market
Software & Services
Global User Research and User Testing Software Market
Software & Services
Global Microscopy Software Market
Software & Services
Automotive Design Software Market
Software & Services
SMS Marketing Software Market
Software & Services
Electromagnetic Simulation Software Market
Software & Services
Europe Servicenow Store Apps Market
Software & Services
US Digital Marketing Software Market
Software & Services
Contract Abstraction Software Market
Software & Services
Strategy Management Software Market
Software & Services
Global Restaurant POS Software Market
Software & Services
Cloud-Based ERP Software Market
Software & Services
Construction Estimating Software Market
Software & Services
Cemetery Software Market
Software & Services
Parametric Design Software Market
Software & Services
Global Maintenance Management Software Market