
 Global Online OCR Software Market | 2026-2036
Global Online OCR Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Online OCR Software Market Foresight
Transformer-based language models paired with computer vision pipelines is rewriting how online OCR platforms process low-quality scans and handwritten forms. ABBYY sustains leadership in document intelligence through deep vertical specialization in financial services and insurance workflows. Google leverages its Tensor Processing Unit infrastructure to offer sub-second inference on multilingual documents at enterprise scale. Nanonets competes by anchoring its platform in no-code training interfaces that reduce deployment timelines for mid-market customers.
Global Online OCR Software refers to cloud-accessible platforms that apply optical character recognition algorithms—typically achieving accuracy rates above 99 percent on printed text—to convert scanned images, PDFs, and photographs into machine-readable and editable formats for downstream automation. The primary commercial purpose centers on eliminating manual data entry in high-volume document processing environments such as accounts payable, patient intake, and customs declaration. Cloud-Based deployment leads in new customer acquisition because subscription models lower capital barriers for small businesses entering automated workflows. Enterprises increasingly demand Hybrid configurations that route sensitive documents through on-premises nodes while pushing routine extraction tasks to public cloud endpoints. Text Recognition functionality remains the largest revenue pool, though Multilingual Support is expanding fastest as cross-border trade documentation and regulatory filing requirements multiply across jurisdictions.
The EU AI Act and GDPR impose strict requirements on automated decision systems processing personal data in document workflows, compelling vendors to implement explainability layers and data residency controls. FDA 21 CFR Part 11 shapes demand in pharmaceutical quality assurance, where OCR outputs must meet electronic record integrity standards for audit trails. BIS certification requirements in India and GB standards in China further fragment compliance architectures for vendors seeking multi-country deployment. Stakeholders must monitor how divergent national AI governance frameworks reshape product roadmaps and localization investments without assuming regulatory convergence.
Market Dynamics
Transformer-based vision-language models are compressing accuracy thresholds for degraded document inputs, forcing incumbent vendors to retrain pipelines on synthetic data or cede enterprise contracts to cloud-native challengers. This architectural shift is redistributing competitive advantage toward hyperscale infrastructure operators.
Growth Catalysts
- EU AI Act compliance mandates:Automated document processing systems handling personal data must embed explainability layers, creating replacement demand for opaque legacy OCR stacks in European banking and insurance workflows.
- Pharmaceutical quality assurance digitization:FDA 21 CFR Part 11 record-integrity requirements are compelling drug manufacturers to deploy validated OCR systems for batch records and laboratory notebooks.
- Japanese manufacturing documentation automation:METI-mandated technical drawing digitization for supplier quality certificates is driving specialized OCR adoption among automotive and electronics component producers.
Market Restraints
- GPU compute cost volatility:Training and inference for multimodal document models depends on NVIDIA H100 availability, with spot pricing fluctuations compressing margins for independent software vendors without cloud credits.
- Training data concentration:High-quality labeled document corpora for low-resource languages and specialized domains remain concentrated among a handful of academic institutions and enterprise archives.
- Regulatory fragmentation:Divergent national AI governance frameworks in India, China, and Brazil force vendors to maintain separate compliance architectures, inflating localization costs.
Strategic Opportunities
- Indian SME digitization gap:RBI's push for financial inclusion and digital lending has created unmet demand for vernacular-language OCR among regional banks and cooperative credit societies.
- Edge deployment for sensitive documents:Hybrid architectures routing classified government and healthcare records through on-premises inference nodes while pushing routine extraction to cloud endpoints.
- Computer vision-NLP convergence:Multimodal transformers that jointly process layout, handwriting, and contextual semantics are opening document understanding applications beyond pure text extraction.
Industry Challenges
- Document engineering talent scarcity:Pipeline optimization for degraded scans and complex layouts requires rare combinations of computer vision and information retrieval expertise, elongating product development cycles.
- Validation timeline compression:Pharmaceutical and medical device customers demand FDA 21 CFR Part 11 qualification packages within 90-day procurement windows, straining vendor quality assurance bandwidth.
- Legacy system integration friction:Mainframe-based enterprise content management systems in financial services require custom middleware development, inflating implementation costs and failure rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Online OCR Software Market |
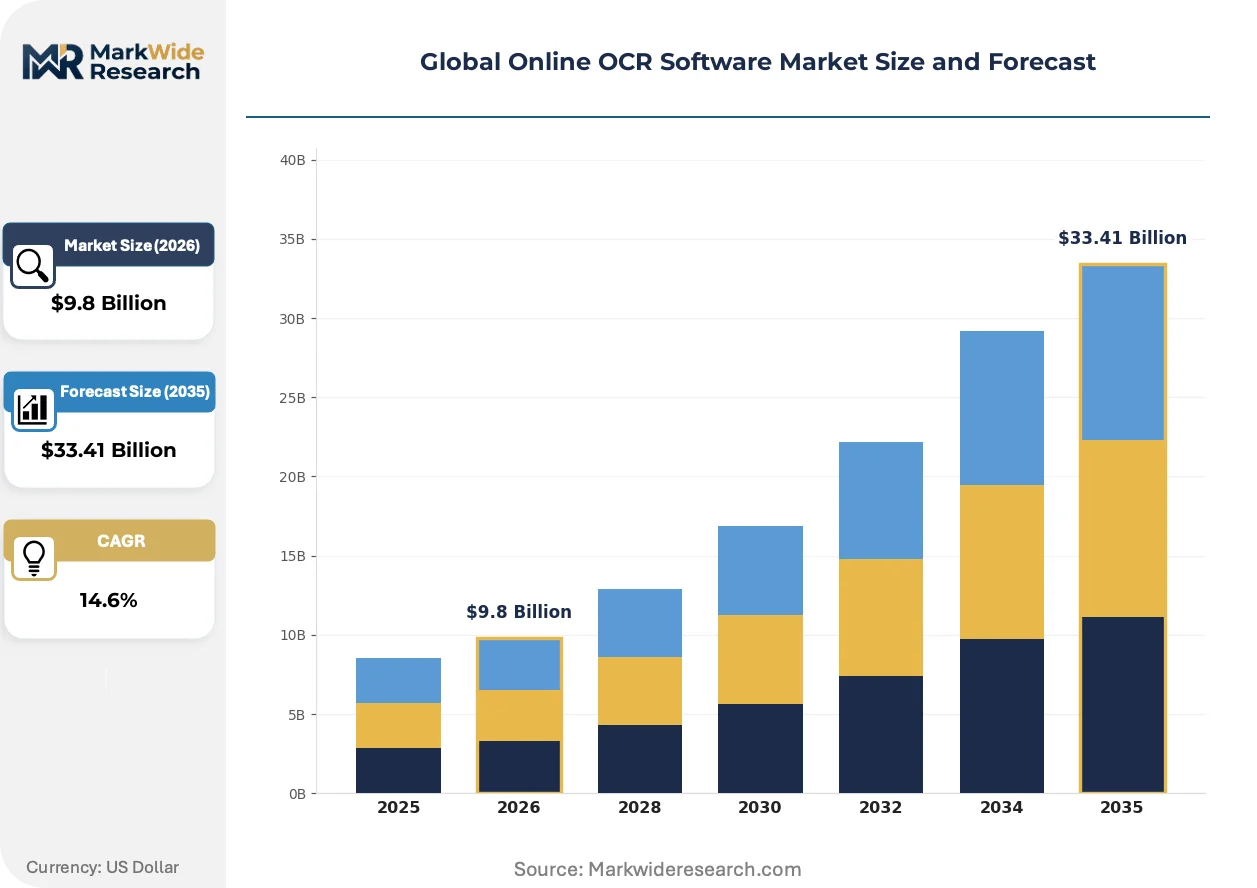
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $33.41 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS End User: Small Businesses, Enterprises, Educational Institutions, Government Agencies Functionality: Text Recognition, Image Processing, Multilingual Support, PDF Conversion Pricing Model: Subscription, Pay-Per-Use, Freemium, Licensing |
| Companies Covered | Adobe Systems Incorporated, ABBYY, Google LLC, Microsoft Corporation, Tungsten Automation (Kofax), Amazon Web Services, Parsio, Nanonets, Readiris, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Online OCR Software Market Shifts & Advancements
Foundation models trained on billions of document-image pairs are collapsing the traditional pipeline of layout analysis, text detection, and recognition into single-pass inference. This compression is lowering deployment barriers while raising performance floors across degraded input conditions.
Vision-language architectures are hybridizing document understanding by fusing transformer-based text encoders with convolutional visual feature extractors in unified end-to-end training regimes. Pharmaceutical quality assurance teams are adopting these systems for simultaneous extraction of handwritten annotations, printed batch codes, and tabular stability data from single scanned records. The structural consequence is collapsing the vendor landscape into two tiers: hyperscalers with pre-trained foundation models and specialized consultancies with vertical fine-tuning expertise.
GDPR Article 22 and the EU AI Act's automated decision-making provisions are mandating human-in-the-loop verification for high-risk document processing workflows. Financial institutions in Germany and France must now maintain audit trails showing which OCR outputs triggered material decisions and how human reviewers overrode machine classifications. Banks are responding by purchasing explainability modules that highlight attention weights and confidence distributions, treating regulatory compliance as a product differentiator rather than cost center.
Subscription-based API consumption is displacing perpetual license models in mid-market procurement, with buyers preferring per-page pricing that aligns costs with actual document volumes. Regional banks in Spain and Italy are abandoning on-premise installations for metered cloud services that scale with seasonal loan application surges. This shift is most visible in Southern European markets where IT capital constraints and regulatory uncertainty favor operational expenditure flexibility over ownership.
Global Online OCR Software Market Segmentation
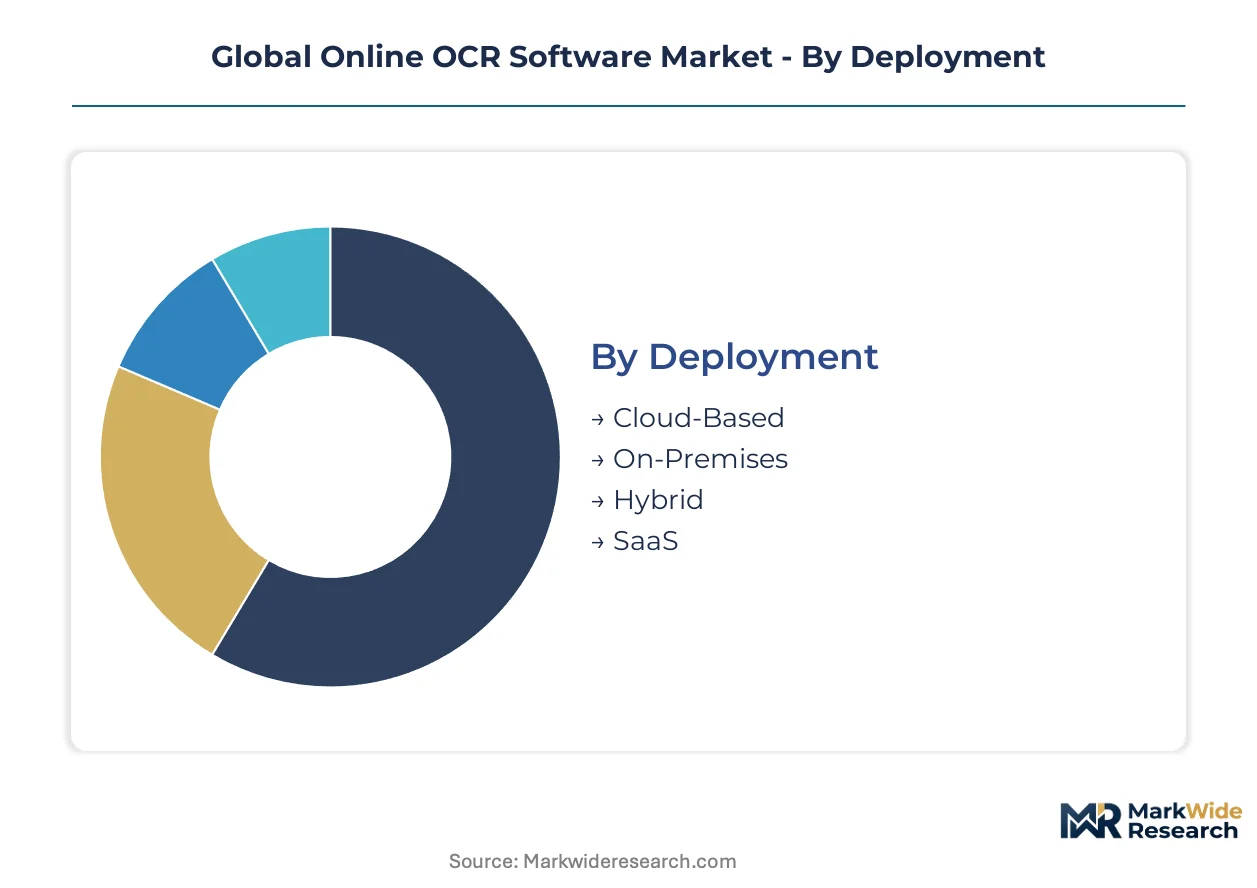
Online OCR software segments reflect divergent infrastructure constraints and procurement capabilities across customer tiers. Deployment mode determines latency, compliance posture, and total cost of ownership in regulated industries. Functionality depth separates commodity text extraction from premium document intelligence workflows.
Deployment:
Use-case spectrum spans latency-sensitive manufacturing floors to elastic financial services workloads.
- Cloud-Based:Public cloud endpoints deliver sub-second inference on multilingual documents without capital expenditure. North American banking workflows favor this model for seasonal volume spikes in mortgage processing.
- On-Premises:Air-gapped installations process classified government records and pharmaceutical batch documentation under FDA 21 CFR Part 11 audit requirements. German automotive suppliers deploy these for technical drawing archives bound by METI-mandated retention rules.
- Hybrid:Sensitive documents route through on-premises nodes while routine extraction tasks push to public cloud endpoints. Japanese electronics manufacturers use this architecture for supplier quality certificates with mixed confidentiality levels.
- SaaS:Browser-accessible platforms with pre-trained models eliminate infrastructure management for mid-market legal and accounting practices.
Established volume favors Cloud-Based; emerging adoption favors Hybrid.
End User:
Customer maturity and procurement sophistication shape solution complexity.
- Enterprises:Global banks and insurers demand API architectures with 99.9% uptime SLAs, custom model retraining, and dedicated compliance documentation. These customers drive multimodal transformer adoption for degraded scan processing.
- Small Businesses:Regional accounting firms and independent medical practices prioritize no-code interfaces and per-page pricing without IT staff requirements. Indian cooperative credit societies represent concentrated demand for vernacular-language capabilities.
- Educational Institutions:University archives and research libraries digitize historical manuscript collections with specialized handwriting recognition.
- Government Agencies:National customs authorities and tax administrations require data residency guarantees and explainability layers under GDPR Article 22 and EU AI Act mandates.
Procurement scale concentrates with Enterprises; deployment velocity climbs fastest among Small Businesses.
Functionality:
Technical depth separates commodity extraction from premium document understanding.
- Text Recognition:Core OCR engines achieving 99%+ accuracy on printed text remain the revenue foundation. Pharmaceutical quality teams depend on validated outputs for electronic batch records.
- Multilingual Support:Cross-border trade documentation and regulatory filings across jurisdictions drive expansion. Brazilian customs operations and UAE free zone authorities require Arabic-Portuguese-English triangulation.
- Image Processing:Pre-processing pipelines correct skew, noise, and illumination variance before recognition. Manufacturing quality documentation from degraded supplier scans depends on this layer.
- PDF Conversion:Structural reconstruction of scanned documents into searchable, editable formats with preserved formatting.
Revenue concentration rests with Text Recognition; capability investment flows toward Multilingual Support.
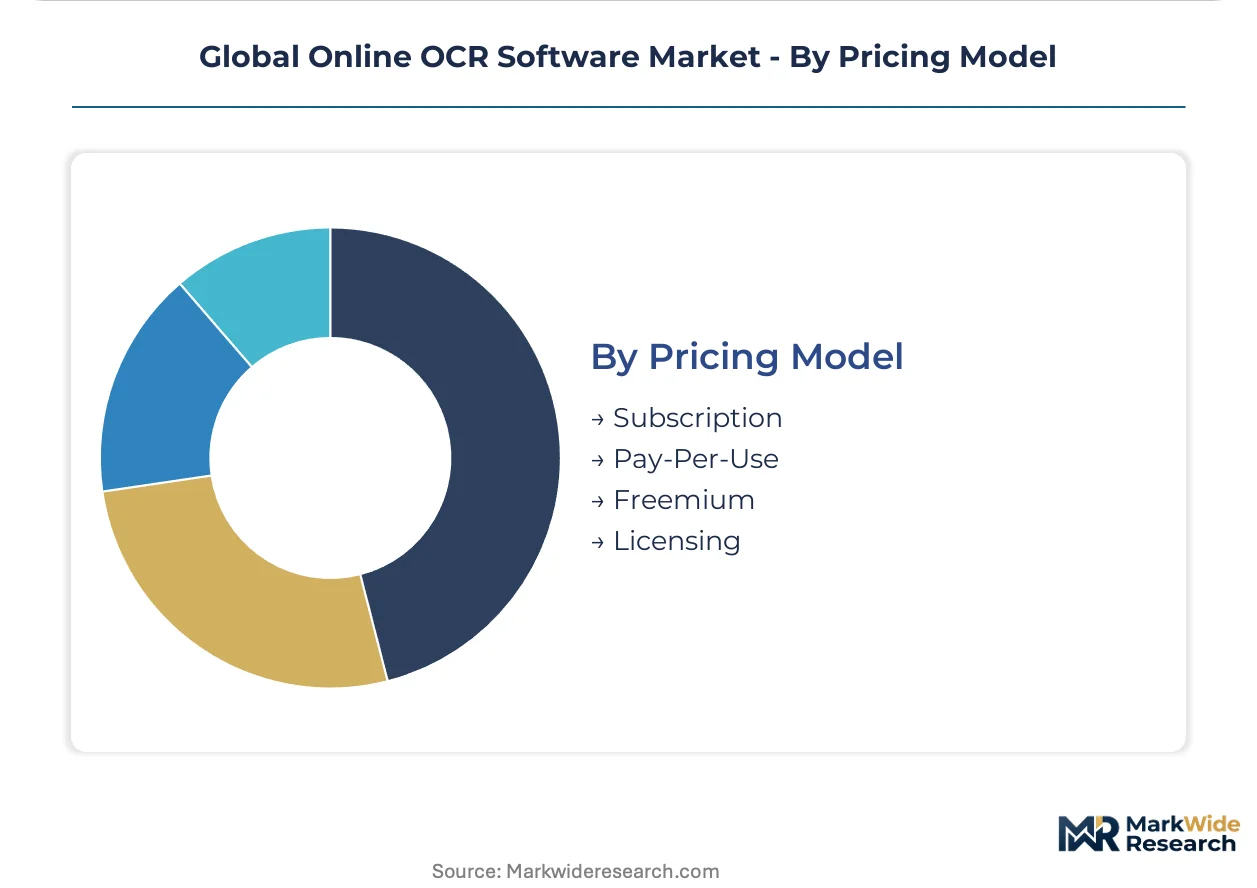
Pricing Model:
Procurement flexibility aligns vendor cash flow with customer operational expenditure preferences.
- Subscription:Monthly or annual fixed fees with tiered page volumes dominate mid-market acquisition. Spanish and Italian regional banks abandoned perpetual licenses for this structure.
- Pay-Per-Use:Metered consumption aligns costs with actual document throughput. Seasonal loan application surges in agricultural finance favor this model.
- Freemium:Limited-page free tiers convert individual professionals and micro-businesses to paid plans.
- Licensing:Perpetual software licenses with maintenance contracts persist in defense and intelligence sectors with multi-year procurement cycles.
Customer acquisition favors Subscription; margin protection depends on Pay-Per-Use adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement concentrates in financial centers with stringent documentation mandates. Manufacturing hubs drive specialized adoption for technical drawing digitization. Government digitization programs accelerate deployment in emerging economies with vernacular-language requirements.
United States
Financial services compliance workflows and pharmaceutical quality assurance dominate enterprise demand. FDA 21 CFR Part 11 record-integrity requirements compel drug manufacturers to deploy validated OCR systems for batch records. Boston's biotech cluster anchors specialized adoption for laboratory notebook digitization.
Germany
Automotive supplier documentation and banking compliance drive specialized requirements. EU AI Act explainability mandates force replacement of opaque legacy OCR stacks in Frankfurt and Munich financial centers. Stuttgart's manufacturing belt deploys METI-influenced technical drawing digitization for quality certificates.
Japan
Electronics component producers and automotive suppliers lead manufacturing documentation automation. METI-mandated technical drawing digitization creates concentrated demand among Toyota and Honda supply chains. Nagoya's industrial corridor specializes in supplier quality certificate processing with hybrid cloud architectures.
India
RBI's financial inclusion push and digital lending expansion create vernacular-language OCR demand. BIS certification requirements fragment compliance architectures for multi-country vendors. Mumbai and Bangalore anchor deployment among regional banks and cooperative credit societies processing vernacular loan applications.
United Kingdom
Insurance workflow automation and legal document digitization sustain mid-market demand. GDPR Article 22 audit trail requirements shape procurement for explainability modules. London's financial district drives API-first adoption for seasonal mortgage processing volume spikes.
Global Online OCR Software Market Competitive Landscape
Channel-controlling players compete with product-specialist players across deployment modes and vertical applications. The market structures around hyperscale infrastructure operators, established document intelligence vendors, and no-code challengers. Three archetypes dominate: cloud-native API platforms, vertical-specialist suites, and infrastructure-backed generalists. Competitive moves concentrate on multimodal transformer retraining and hybrid architecture certification.
Within the infrastructure-backed tier, Google LLC and Amazon Web Services occupy positions defined by TPU-scale inference and cloud credit ecosystems. ABBYY anchors the vertical-specialist archetype through financial services and insurance workflow depth. Nanonets exemplifies the no-code challenger segment with mid-market deployment velocity. Adobe Systems Incorporated and Microsoft Corporation sit within productivity-suite bundling strategies that distribute OCR as embedded capability rather than standalone product.
| Leading Market Players |
|---|
| Adobe Systems Incorporated |
| ABBYY |
| Google LLC |
| Microsoft Corporation |
| Tungsten Automation (Kofax) |
| Amazon Web Services |
| Parsio |
| Nanonets |
| Readiris |
| Others |
Supply & Pricing Matrix
GPU compute cost volatility tied to NVIDIA H100 availability determines both tiered pricing spreads across cloud-native and on-premise deployment modes and supply chain resilience for independent software vendors lacking hyperscaler cloud credits.
Pricing Analysis
Cost-plus contracts with NVIDIA spot pricing indexation dominate infrastructure procurement for training and inference workloads. Pricing stratifies across premium enterprise API tiers with 99.9% uptime SLAs, standard mid-market SaaS subscriptions, and economy freemium conversions for individual professionals. Cost compression in the standard tier is intensifying because GPU spot pricing fluctuations compress margins for vendors without committed use discounts. Small businesses exhibit highest price sensitivity, while pharmaceutical enterprises accept premium pricing for FDA 21 CFR Part 11 validated outputs.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from hyperscalers anchor vendor working capital management for compute-intensive model training. Hardware supply concentrates in Taiwan for advanced semiconductor fabrication, the United States for NVIDIA GPU design and cloud infrastructure, and China for edge device manufacturing. Raw material dependencies span high-bandwidth memory from SK Hynix and Samsung, advanced packaging substrates from Japanese suppliers, and rare earth elements for magnetic components in server farms. Single-source vulnerability around NVIDIA GPU allocation creates bottleneck risk for independent vendors. Distribution runs through direct API sales to enterprise developers and channel partnerships with systems integrators in regulated verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise buyer power is concentrating through procurement consortiums in European banking and insurance, fragmenting vendor pricing autonomy and compressing implementation timelines.
For Market Incumbents: Insulate recurring revenue streams by embedding explainability modules that satisfy EU AI Act audit requirements before regulatory deadlines force replacement cycles. Deepen backward integration into proprietary training data pipelines for low-resource languages, reducing dependency on academic corpus licensing. Anchor defensive positioning against no-code challengers through pre-certified FDA 21 CFR Part 11 validation packages that elongate competitor qualification timelines. For New Entrants and Emerging Players: Establish a beachhead in Indian vernacular-language OCR demand where RBI financial inclusion mandates outpace incumbent localization roadmaps. Target cooperative credit societies and regional banks with per-page pricing models that align with seasonal agricultural lending cycles. Deploy channel partnerships with local systems integrators possessing existing BIS certification relationships rather than direct enterprise sales approaches. For Investors and Strategic Acquirers: Specialized consultancies with vertical fine-tuning expertise in pharmaceutical quality assurance and automotive technical documentation represent the most defensible acquisition archetype. Long-term viability hinges on multimodal transformer retraining capabilities and hybrid architecture certification depth rather than commodity text extraction scale. Watch FDA validation timeline compression as an inflection indicator—vendors delivering 90-day qualification packages will capture pharmaceutical procurement windows before competitors adapt quality assurance bandwidth.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Architecture Certification | FDA 21 CFR Part 11 and EU AI Act compliance opens pharmaceutical and banking procurement channels. |
| Multimodal Transformer Retraining | Vision-language convergence enables simultaneous extraction from handwritten annotations, printed codes, and tabular data. |
| Vernacular Language Expansion | RBI-mandated financial inclusion in India creates unmet demand for regional language document processing. |
| Edge Deployment Partnership | On-premises inference nodes for classified government records complement cloud-native volume scaling. |
| Explainability Module Development | GDPR Article 22 audit trail requirements transform regulatory compliance into product differentiation. |
Research Methodology
Cross-validation between executive interviews at OCR platform vendors and secondary analysis of hyperscaler infrastructure disclosures anchors the qualitative findings. Primary research encompassed conversations with CTOs at financial services institutions, IT procurement officers in pharmaceutical quality assurance, platform engineers at cloud-native challengers, and integration specialists serving government digitization programs. Secondary sources included SEC filings from publicly traded document intelligence vendors, EU regulatory guidance on AI Act implementation, FDA 21 CFR Part 11 inspectional observation databases, and RBI circulars on digital lending infrastructure. Bottom-up segmentation modeling triangulated against top-down market sizing from infrastructure capacity expansion announcements.
Calibration against historical adoption curves in comparable enterprise software categories shaped the projection framework. The analytical framework modeled deployment mode, organization size tier, vertical application, integration complexity, and regional regulatory cluster across the analysis window. CAGRs derived from segment-level growth rate assumptions weighted by revenue concentration. Industry-specific inputs encompassed pharmaceutical validation timeline compression rates, GPU spot pricing volatility bands, and vernacular language corpus availability indices.
Sensitivities concentrate around NVIDIA H100 supply allocation shifts, EU AI Act enforcement timeline acceleration, and FDA inspectional focus changes for electronic record systems. Forecasts reflect documented assumptions regarding enterprise procurement cycle durations and cloud migration velocity in regulated verticals. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Airline Route Profitability Software Market
Software & Services
Global Reporting Software Market
Software & Services
Testing As a Service (Taas) Market
Software & Services
Vacation Rental Software Market
Software & Services
Global Big Data Software Market
Software & Services
Application Virtualization Market
Software & Services
HACCP Software Market
Software & Services
Global Time Tracking Software Market
Software & Services
User Retention Software Market
Software & Services
Stock Media Software Market
Software & Services
Customer Self-Service Software Market
Software & Services
PCB CAD Software Market
Software & Services
Global Electrical Computer-Aided Design (ECAD) Market
Software & Services
APAC Workforce Management Software Market
Software & Services
Global Customer Communications Management (CCM) Software Market
Software & Services
Train Reservation Software Market