
 Global Help Desk Software Market | 2026-2036
Global Help Desk Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Help Desk Software Market Foresight
The EU Green Deal is expanding compliance obligations for data center energy efficiency across software vendors serving European enterprises. Zendesk leverages its AI-native workflow engine to compete in automated ticket routing for mid-market buyers. ServiceNow anchors the enterprise segment with deep IT service management integration and custom workflow orchestration. Freshworks differentiates through localized pricing and multilingual support interfaces targeting emerging market deployments.
Help desk software constitutes a digital platform that centralizes incident logging, request tracking, and knowledge base management through configurable workflows, API integrations, and real-time analytics dashboards. Cloud-based deployment leads segment growth as organizations retire on-premises infrastructure to reduce capital expenditure and accelerate remote support capabilities. IT firms represent the dominant end-user category, though healthcare providers are the fastest-growing buyer segment as HIPAA-compliant ticketing becomes essential for patient data handling. Incident management solutions command the largest solution-type share, while knowledge management tools are gaining traction as self-service deflection strategies mature.
The US FDA and HIPAA frameworks impose strict audit trails and access controls on help desk platforms processing healthcare records, while the EU AI Act mandates transparency disclosures for automated decision-making in customer support chatbots. ISO 27001 certification has become a baseline procurement filter for enterprise buyers evaluating vendor security postures. Stakeholders must monitor evolving AI liability frameworks in the European Union and United States, as these jurisdictions are likely to set the compliance benchmarks that reshape platform architecture and vendor qualification criteria across all deployment models.
Market Dynamics
Cloud migration and AI automation are compressing deployment cycles while HIPAA and EU AI Act compliance requirements are forcing platform architecture redesigns across vendor portfolios.
Growth Catalysts
- Healthcare digitization:HIPAA-compliant ticketing platforms are becoming essential infrastructure as US hospitals consolidate patient service workflows into unified digital channels.
- EU AI Act transparency mandates:Automated decision-making disclosure requirements are accelerating investment in explainable AI routing engines for European enterprise buyers.
- IT service management convergence:Mid-market organizations are retiring siloed point solutions in favor of integrated platforms that unify incident, problem, and change management.
Market Restraints
- Data residency requirements:GDPR localization rules and emerging sovereign cloud mandates in France, Germany, and India are fragmenting vendor infrastructure strategies.
- Legacy system integration costs:Mainframe and on-premises ERP connectivity consumes 30-40% of implementation budgets for enterprise deployments.
- AI liability uncertainty:Unresolved questions around automated ticket misrouting accountability are slowing procurement decisions in regulated industries.
Strategic Opportunities
- India's PLI scheme for IT services:Production-linked incentives for software exports are attracting vendor development centers and localized pricing models.
- Edge computing convergence:Distributed ticket processing at branch locations is converging with 5G network slicing to enable real-time field service orchestration.
- Self-service knowledge deflection:Generative AI search interfaces are opening white space in SMB segments previously priced out of enterprise automation.
Industry Challenges
- ISO 27001 certification timelines:Six-to-twelve month audit cycles are delaying enterprise go-live dates and compressing vendor delivery margins.
- Multilingual NLP development:Scarce talent for Arabic, Hindi, and Southeast Asian language model training is constraining emerging market expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Help Desk Software Market |
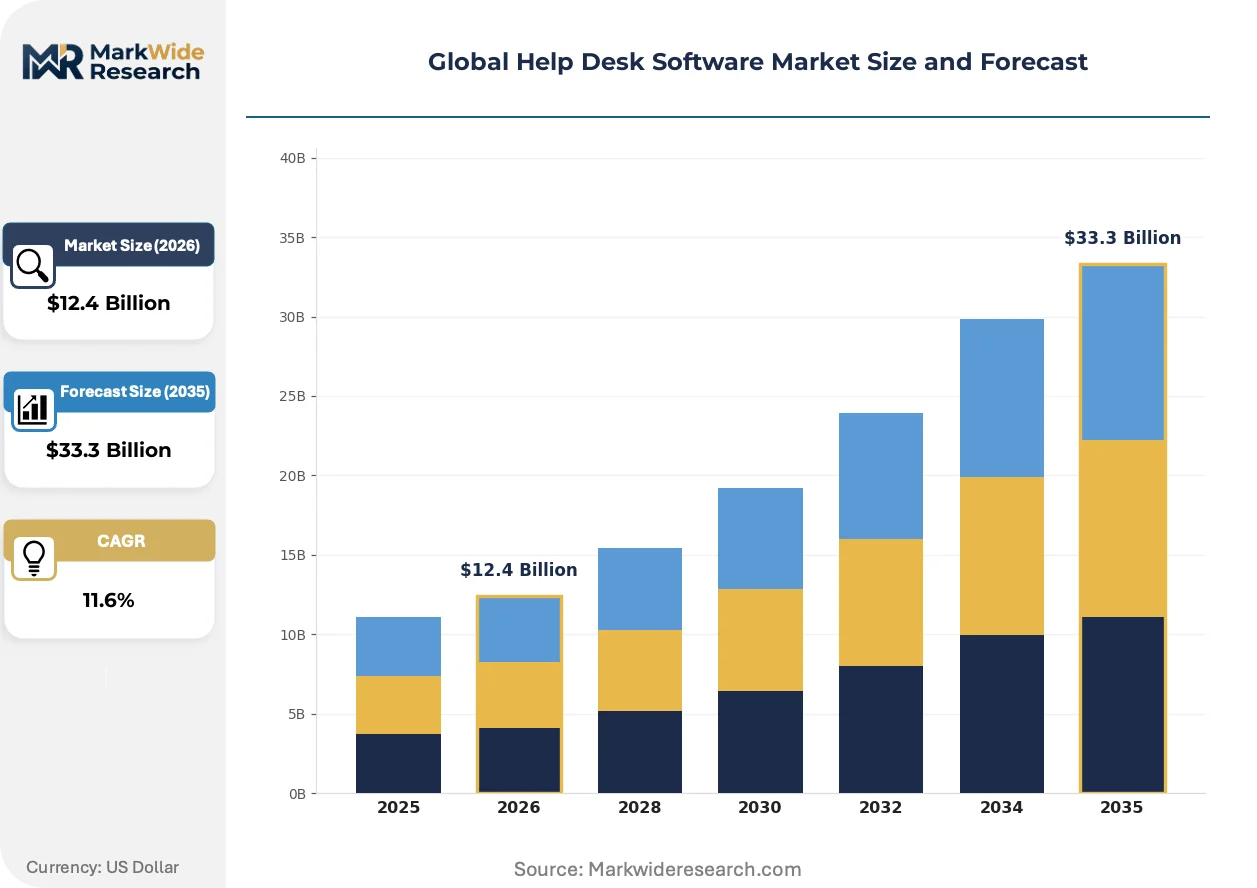
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $33.3 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS End User: IT Firms, Retail Companies, Healthcare Providers, Educational Institutions Service Type: Technical Support, Customer Support, IT Services, Managed Services Solution Type: Incident Management, Request Management, Problem Management, Knowledge Management |
| Companies Covered | Zoho Desk, Jira Service Management, Zendesk, Freshworks, HubSpot Service Hub, Freshdesk, Salesforce Service Cloud, Help Scout, ServiceNow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Help Desk Software Market Shifts & Advancements
Generative AI is rewriting interaction paradigms while regulatory fragmentation forces modular compliance architectures. Vendors are racing to embed predictive capabilities without triggering algorithmic accountability thresholds.
Natural language processing for ticket classification is converging with sentiment analysis engines to prioritize emotionally charged customer interactions. Healthcare providers and financial services firms are deploying these hybrid models fastest. This convergence is compressing first-response SLAs from hours to minutes while raising infrastructure costs.
The EU AI Act's risk-based classification system is forcing vendors to document decision logic for high-risk automated support functions. Platform providers must now maintain technical file documentation and human oversight protocols. Enterprise buyers in Germany and France are demanding these compliance artifacts as standard procurement prerequisites.
Subscription fatigue among mid-market buyers is driving unbundling of knowledge base, chat, and ticketing modules. Point solutions are reclaiming share from suites as procurement teams prioritize best-of-breed interoperability over single-vendor consolidation. This pattern is most pronounced in the United States, where IT modernization budgets support multi-tool stacks.
Global Help Desk Software Market Segmentation
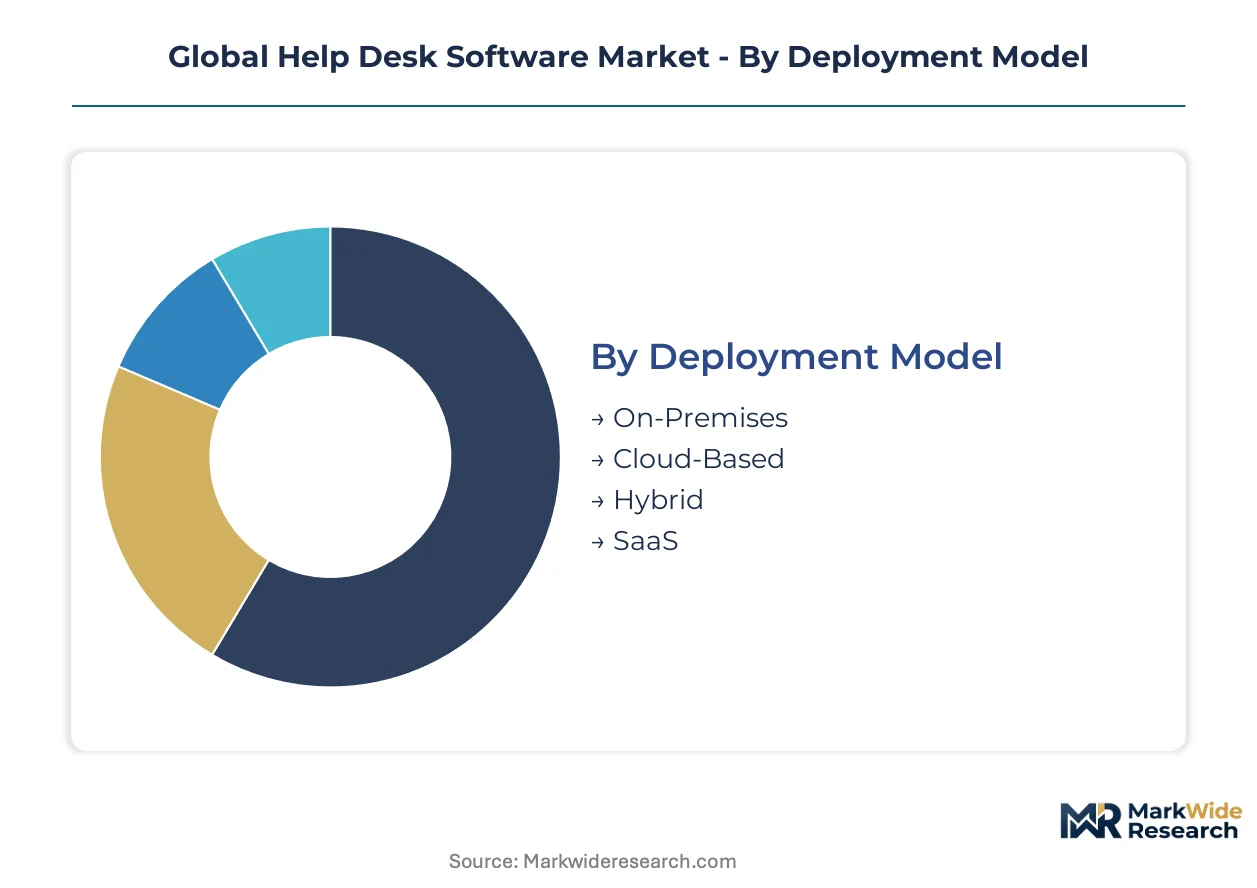
Help desk software procurement patterns diverge sharply across deployment models and end-user verticals, with compliance requirements and integration complexity dictating buyer preferences. Understanding these fault lines reveals where vendor R&D investments generate the highest returns and which segments resist commoditization.
Deployment Model:
Capital intensity varies dramatically across deployment architectures, with on-premises installations demanding the heaviest upfront infrastructure commitment while cloud alternatives shift spending toward recurring operational expenditure.
- On-Premises:Requires dedicated server hardware, perpetual licensing, and internal IT maintenance staff. Financial services firms in Germany and Japan retain this model to satisfy strict data sovereignty mandates from BaFin and FSA regulators.
- Cloud-Based:Eliminates capital expenditure on physical infrastructure while enabling elastic scaling. US healthcare providers are migrating here fastest to satisfy HIPAA Business Associate Agreement requirements without owning data center assets.
- Hybrid:Combines on-premises control for sensitive workloads with cloud burst capacity for peak demand. This architecture attracts European manufacturers navigating GDPR localization rules alongside operational flexibility needs.
- SaaS:Delivers fully managed multi-tenant platforms with subscription pricing. India's IT services exporters favor this model under PLI scheme incentives that reward asset-light operational structures.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in SaaS.
End User:
Buyer sophistication and procurement timelines create distinct margin profiles across vertical segments, with regulated industries tolerating longer sales cycles in exchange for compliance depth.
- IT Firms:Represent the largest addressable base, consuming platforms for internal service desks and client-facing managed services. These buyers prioritize API extensibility and custom workflow engines over out-of-box functionality.
- Healthcare Providers:Fastest-growing vertical as HIPAA audit trail requirements and FDA 21 CFR Part 11 obligations reshape ticketing infrastructure. US hospital systems are consolidating patient service channels into unified digital workflows.
- Retail Companies:Demand high-volume transaction handling and seasonal elasticity for peak shopping periods. These buyers emphasize self-service deflection to reduce per-contact support costs.
- Educational Institutions:Price-sensitive segment with complex stakeholder matrices spanning students, faculty, and administrative staff. Procurement concentrates in summer deployment windows between academic terms.
IT Firms absorb the greatest absolute platform volume. Healthcare Providers are climbing the fastest.
Service Type:
Service delivery models segment by technical depth and contractual structure, with buyers selecting engagement frameworks that match internal capability gaps.
- Technical Support:Hardware and software troubleshooting with escalation protocols to engineering teams. Manufacturing clusters in Stuttgart and Detroit rely heavily on these services for production line continuity.
- Customer Support:Frontline interaction handling across voice, chat, and email channels. E-commerce operators in the United Kingdom and Netherlands are automating these functions fastest under EU AI Act transparency pressures.
- IT Services:Comprehensive infrastructure management spanning incident, problem, and change disciplines. Enterprise buyers in Singapore and Sydney favor this model for regional hub consolidation.
- Managed Services:Outcome-based outsourcing with SLA-backed performance guarantees. This structure appeals to mid-market firms in Brazil and Mexico lacking internal IT scale.
IT Services commands the deepest existing footprint. Managed Services shows the steepest upward trajectory.
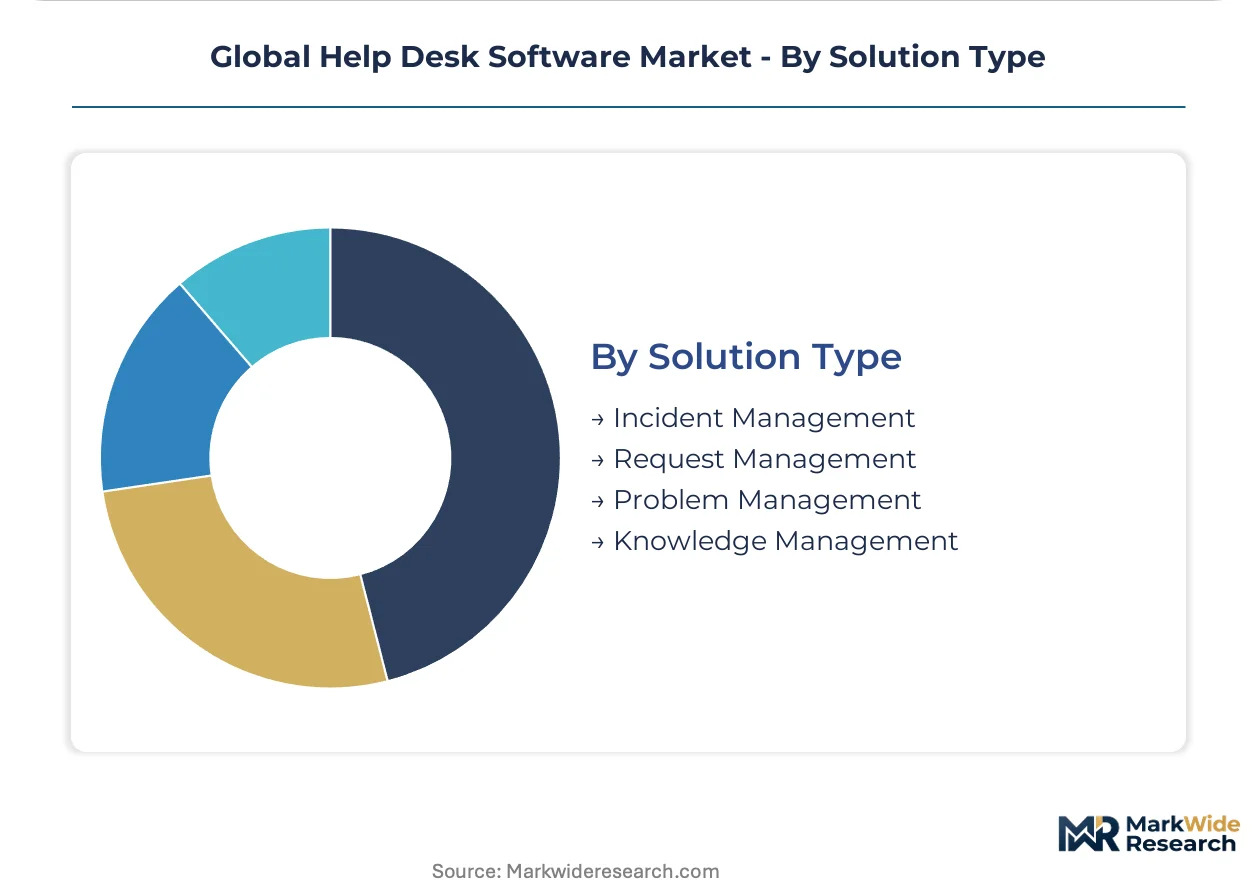
Solution Type:
Functional modules within help desk platforms compete for budget allocation based on automation potential and integration complexity with adjacent enterprise systems.
- Incident Management:Core ticketing functionality for service disruption logging and resolution tracking. This module dominates procurement in telecommunications and utilities where uptime metrics drive executive compensation.
- Knowledge Management:Self-service repository and generative AI search interfaces. Financial services firms in Switzerland and Luxembourg are investing here fastest to deflect routine inquiries from relationship managers.
- Request Management:Service catalog and fulfillment workflows for standard change types. Government agencies in Canada and Australia standardize on this capability for citizen service modernization.
- Problem Management:Root cause analysis and known error database maintenance. This discipline sees concentrated adoption in aviation and pharmaceutical manufacturing where recurrence prevention carries regulatory weight.
Incident Management retains the broadest deployment base. Knowledge Management is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Help desk software traces its commercial roots to Silicon Valley's enterprise IT boom of the 1990s, when American technology firms pioneered digital ticketing systems for internal support operations. This heritage established the United States as the foundational market for platform architecture and buyer sophistication standards.
United States
Enterprise IT modernization budgets and HIPAA-compliant healthcare digitization drive procurement velocity. FDA and HIPAA frameworks impose strict audit trail requirements on platforms processing patient records. Hospital systems in Boston and Minneapolis are consolidating patient service workflows into unified digital channels.
Germany
Industrial manufacturing clusters and stringent data sovereignty mandates sustain on-premises deployment preferences. BaFin regulations and GDPR localization rules compel vendors to maintain sovereign cloud infrastructure. Stuttgart's automotive sector relies on hybrid architectures for production line continuity.
India
IT services export growth and government PLI scheme incentives accelerate SaaS adoption among software vendors. RBI guidelines on data localization shape vendor infrastructure strategies. Development centers in Bengaluru and Hyderabad are attracting localized pricing models and multilingual platform investments.
United Kingdom
E-commerce operator density and EU AI Act transparency pressures automate customer support functions fastest. Financial Conduct Authority oversight extends to automated decision-making in financial services ticketing. London's fintech cluster demands explainable AI routing engines for regulatory compliance.
Japan
Financial services conservatism and METI industrial digitization programs sustain premium platform investments. FSA data sovereignty requirements preserve on-premises installations for core banking systems. Tokyo's insurance sector maintains hybrid deployments for sensitive claims processing workflows.
Global Help Desk Software Market Competitive Landscape
Capital-heavy platform developers compete with asset-light workflow integrators for enterprise mindshare, creating a tiered competitive structure where infrastructure ownership separates strategic positioning. The vendor landscape organizes around three archetypes: cloud-native specialists with AI-native engines, legacy ITSM incumbents with deep enterprise integration capabilities, and regional price-optimizers with localized interface portfolios. Consolidation pressures concentrate among mid-market suites, while M&A activity targets workflow automation capabilities and geographic compliance certifications.
Within the cloud-native tier, Zendesk and Freshworks exemplify divergent geographic strategies for mid-market penetration. ServiceNow anchors the enterprise integration segment with ITSM convergence positioning. These three companies occupy distinct competitive spaces: workflow engine specialization, emerging market localization, and enterprise orchestration depth respectively.
| Leading Market Players |
|---|
| Zoho Desk |
| Jira Service Management |
| Zendesk |
| Freshworks |
| HubSpot Service Hub |
| Freshdesk |
| Salesforce Service Cloud |
| Help Scout |
| ServiceNow |
| Others |
Supply & Pricing Matrix
Enterprise-midmarket tier divergence in help desk software manifests in both subscription pricing and infrastructure deployment choices, with HIPAA-compliant healthcare platforms commanding premium SaaS rates while asset-light SMB tools compete on per-seat economy pricing across India and Southeast Asia.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates vendor portfolios, with ISO 27001 certification and AI-native workflow depth driving differentiation between tiers. Healthcare providers in the United States absorb the highest per-seat costs due to FDA audit trail requirements, while Indian IT services exporters exploit PLI scheme incentives to access discounted SaaS tiers. Cost compression in the midmarket segment is intensifying because subscription fatigue drives unbundling of knowledge base and ticketing modules.
Supply Chain Analysis
Freight costs for data center hardware shipments from Taiwan and South Korea to European sovereign cloud facilities are rising alongside energy price volatility, compressing margins for vendors maintaining physical infrastructure. Software development talent concentrates in India, the United States, and Poland, with NLP model training expertise remaining scarce for Arabic and Hindi language support. Single-source vulnerability in GPU supply for AI training clusters threatens explainable AI routing engine deployment timelines. Distribution runs through direct enterprise sales teams for regulated verticals and self-serve digital channels for SMB adoption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Help desk software functions as a stable compounder where recurring SaaS revenue from IT service management convergence sustains predictable cash generation across economic cycles.
For Market Incumbents: To counter unbundling pressure from best-of-breed point solutions, incumbents should deepen API extensibility investments and acquire workflow automation specialists with proven HIPAA compliance artifacts. Channel control through certified implementation partners in Germany and Japan defends against localized price-optimizers.
For New Entrants and Emerging Players: The gap between premium enterprise orchestration platforms and economy-tier SMB tools creates entry space for vertical specialists targeting healthcare providers in secondary US hospital markets. India's PLI scheme eligibility offers a go-to-market angle through asset-light SaaS structures with localized multilingual interfaces.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-market suites lack AI-native engines and EU AI Act compliance documentation. Long-term viability favors platforms with embedded explainable AI routing and established sovereign cloud footprints in France and Germany. Watch for ISO 27001 certification backlogs as an inflection signal for vendor delivery margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Native Workflow Engine Launch | Explainable AI routing satisfies EU AI Act transparency mandates for German enterprise buyers. |
| HIPAA Compliance Certification | FDA audit trail capabilities unlock US hospital system procurement pipelines in Boston and Minneapolis. |
| Strategic Partnership with Hyperscaler | Sovereign cloud infrastructure addresses BaFin data localization requirements for Stuttgart manufacturers. |
| Acquisition of NLP Specialist | Arabic and Hindi language models accelerate emerging market penetration under India's PLI incentives. |
| Geographic Expansion to Southeast Asia | Localized pricing models capture IT services export growth from development centers in Bengaluru. |
Research Methodology
Multiple input streams — CTO interviews at US healthcare systems, regulatory affairs consultations with EU AI Act compliance officers, and platform engineering discussions with Indian IT services exporters — were reconciled against SEC filings from publicly traded vendors, hyperscaler capex disclosures, and hospital procurement database extracts. Bottom-up triangulation across deployment model adoption curves and top-down validation against IT modernization budget flows ensured segmentation integrity.
Cross-referencing historical subscription revenue patterns against panel input from IT procurement officers and integration specialists anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, organization size tier, vertical regulatory intensity, integration complexity with legacy ERP systems, and regional adoption patterns. CAGRs were derived from elasticity-adjusted growth curves incorporating AI automation penetration rates and compliance-driven replacement cycles.
Caveats apply where EU AI Act enforcement timelines or HIPAA audit interpretation shifts could materially shift the outlook for automated decision-making platform adoption. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Image Analysis Software Market
Software & Services
Configuration Management (CM) Tools Market
Software & Services
Change Control Management Software Market
Software & Services
Vending Software Market
Software & Services
Tenant Billing Software Market
Software & Services
Graphical User Interface (GUI) Design Software Market
Software & Services
Collaboration Software Market
Software & Services
Global Wedding Invitations Software Market
Software & Services
API Design Software Market
Software & Services
Machine Translation Software Market
Software & Services
Personal Budgeting Software Market
Software & Services
Collaborative Office Software Market
Software & Services
Computer Software Market
Software & Services
Global Directory Software Market
Software & Services
Global Salesforce Appexchange Tools Market
Software & Services
Asia-Pacific ERP Software Market