
 Android Cloud Phone Market | 2026-2036
Android Cloud Phone Market Size, Share, and Industry Trends Forecast 2026-2036
Android Cloud Phone Market Insights
Market Context
Multi-source cloud virtualization procurement is shifting toward consolidated platform partnerships as enterprise buyers reduce vendor fragmentation. Google leverages its Android ecosystem dominance to anchor cloud-native mobile workloads within enterprise Google Workspace deployments. Huawei competes through proprietary Kirin-cloud integration and captive data center infrastructure across Asia. Microsoft extends Azure Virtual Desktop capabilities into mobile endpoints, positioning Windows-cloud interoperability as a counterweight to pure Android plays.
Technical Definition and Segment Structure
An Android cloud phone streams the Android operating system from remote servers to local display devices, rendering compute-intensive applications via GPU-accelerated virtualization while maintaining sub-50ms latency thresholds for interactive usability. Virtual phone deployments currently dominate commercial traction due to lower infrastructure overhead and centralized security patching, though hybrid phone architectures are gaining fastest among regulated industries requiring local data residency. Subscription services capture the deepest margin pools through recurring revenue predictability, while managed services segments show structural expansion as enterprises outsource endpoint administration entirely.
Regulatory Environment
China's MIIT and SAMR enforce data localization for cloud-rendered mobile environments, compelling foreign operators to establish domestic server presence. India's TRAI cloud service frameworks and BIS device certification standards shape product compliance requirements for imported virtualization platforms. GDPR and EU AI Act provisions in Europe extend to biometric authentication flows within cloud phone architectures, affecting cross-border identity management design. Stakeholders must monitor evolving data sovereignty interpretations as jurisdictions fragment cloud jurisdiction rules faster than interoperability standards can harmonize them.
Market Dynamics
Enterprise IT consolidation around unified endpoint management platforms is compressing vendor ecosystems, forcing virtualization providers to embed security orchestration and identity federation directly into cloud phone stacks rather than relying on third-party integrations.
Growth Catalysts
- India's PLI scheme for cloud infrastructure:Domestic data center buildouts receive production-linked incentives, lowering compute costs for SME-facing Android cloud phone services. Local providers leverage subsidized server capacity to undercut foreign competitors on price.
- GPU virtualization advances:Hardware-accelerated Android rendering on NVIDIA A100 and H100 clusters enables console-grade gaming and CAD workloads previously impossible on thin clients. Mobile workstation demand from architecture and media firms accelerates.
- Financial services compliance mandates:SEC and FINRA record-keeping requirements for mobile communications push banks toward centralized cloud phone logging. Audit trail centralization trumps bring-your-own-device flexibility.
Market Restraints
- Cross-border latency physics:Sub-50ms interactive thresholds require edge nodes within 500 kilometers of users, constraining expansion into infrastructure-sparse regions like Central Africa and rural Southeast Asia.
- MIIT data localization enforcement:Foreign operators must establish domestic Chinese server presence, raising capital requirements and operational complexity for non-domestic virtualization platforms.
- Silicon supply concentration:Advanced GPU availability depends on TSMC's N4 and N3 foundry capacity in Taiwan, creating chokepoint vulnerability for GPU-heavy cloud rendering services.
Strategic Opportunities
- Indonesia's SME digitization gap:64 million micro-enterprises lack dedicated IT staff, creating white space for fully managed cloud phone subscriptions with bundled support. Local telco partnerships unlock distribution.
- EU AI Act biometric compliance:Facial authentication flows in cloud phone architectures face new audit requirements, favoring providers with pre-certified identity pipelines over retrofitting competitors.
- 5G network slicing integration:Quality-of-service guarantees from mobile operators enable guaranteed latency tiers for enterprise cloud phone deployments, differentiating premium subscriptions from best-effort consumer tiers.
Industry Challenges
- Android version fragmentation management:Supporting Android 10 through 14 across heterogeneous device fleets strains testing matrices and security patch propagation, particularly for regulated industries with extended support obligations.
- Legacy enterprise mobility integration:Existing mobile device management deployments from VMware and BlackBerry require complex API bridging to cloud phone control planes, extending sales cycles and implementation risk.
Report Scope
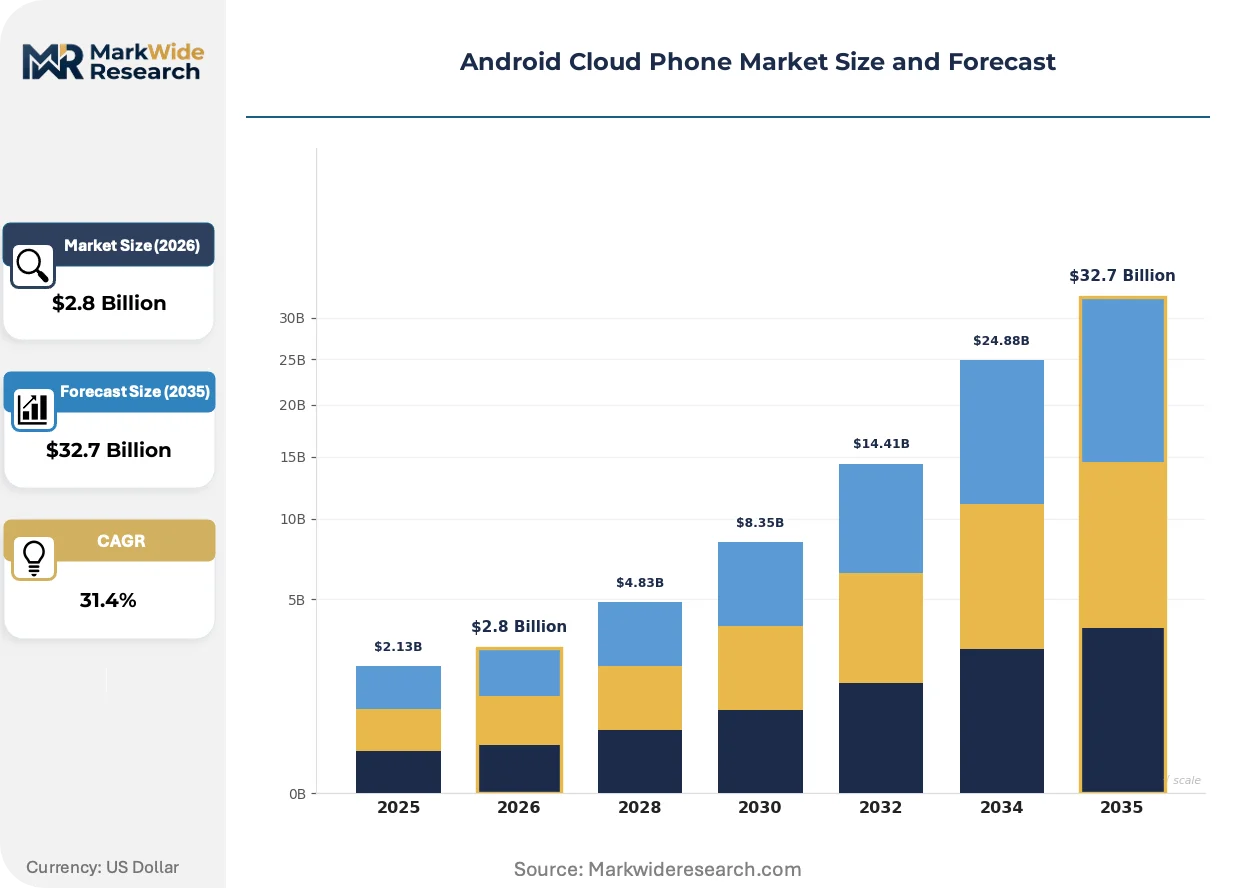
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Android Cloud Phone Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $32.7 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Virtual Phone, Hybrid Phone, Cloud-Based Device, IoT Phone Service Type: Subscription Services, One-Time Purchase, Freemium Model, Managed Services Deployment: Public Cloud, Private Cloud, Hybrid Deployment, Edge Computing End User: Enterprises, Small Businesses, Freelancers, Remote Workers |
| Companies Covered | Redfinger, Hippo Cloud Phone, Microsoft, Google, Huawei, Baidu, Aiyuntu, Duoduo Cloud Phone, VMOS Cloud, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Android Cloud Phone Market Trends and Innovations
Virtualization architectures are bifurcating between centralized cloud rendering and edge-hybrid models, with regulatory pressure and latency requirements driving divergent technical investments across geographic markets.
ARM-based server silicon is converging with Android-native virtualization stacks to eliminate x86 translation overhead. Hyperscalers including AWS and Google deploy Graviton and Axion instances specifically for mobile workload hosting. Financial services buyers in Singapore and London pilot these configurations for reduced per-stream licensing costs.
GDPR Article 44 transfer mechanism rulings are forcing architectural redesigns for cloud phone identity data. Schrems II decisions invalidated Privacy Shield adequacy, compelling providers to implement EU-isolated authentication shards. German enterprise procurement now mandates data residency attestations before contract execution.
Subscription unbundling is fragmenting traditional all-inclusive pricing. Indian and Indonesian buyers increasingly separate compute, storage, and management tiers, comparing unit economics across specialized providers rather than accepting bundled platform fees. Channel partners respond with multi-vendor orchestration layers that abstract underlying infrastructure heterogeneity.
Android Cloud Phone Market Segmentation
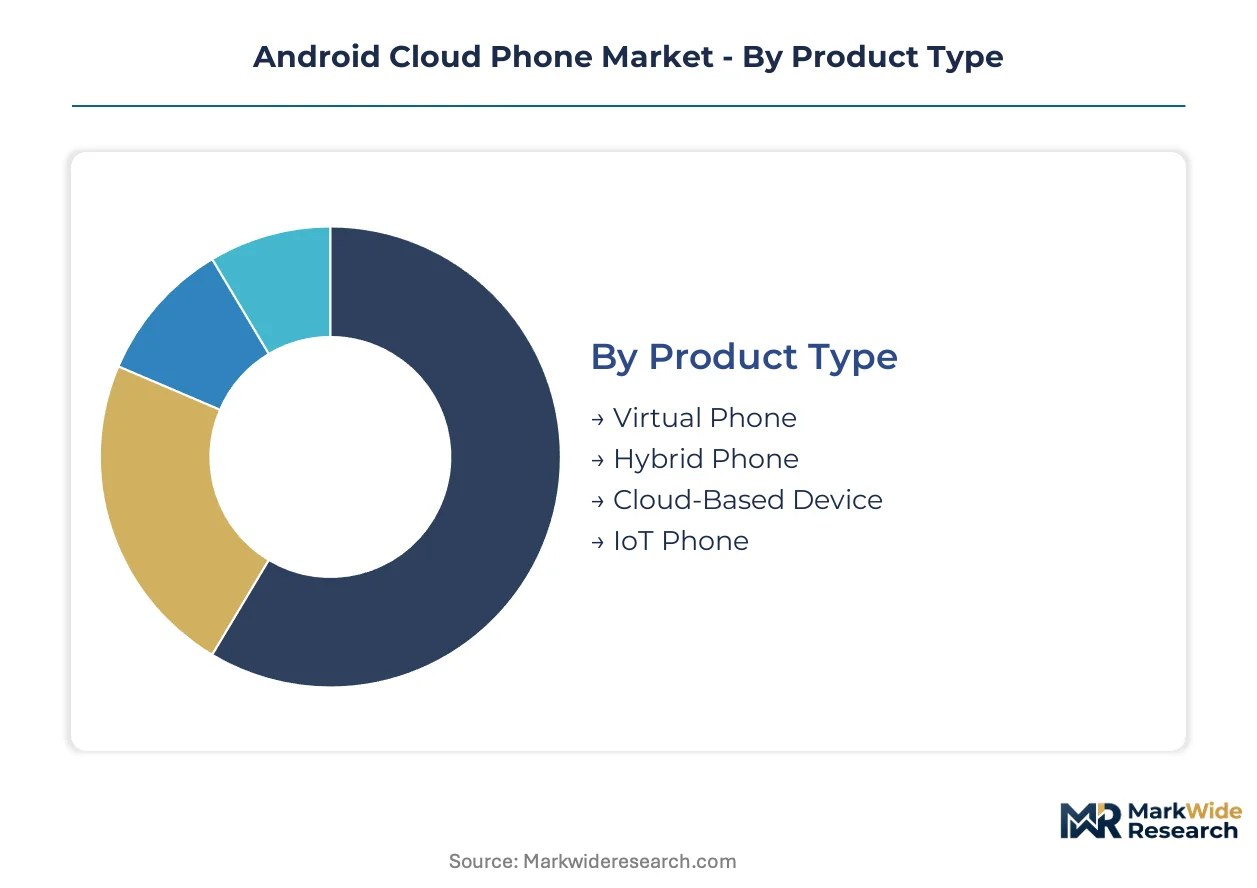
Segmentation in the Android cloud phone market reveals divergent profit pools and technical requirements across virtualization architectures. Buyers prioritize latency performance, compliance posture, and total cost of ownership differently depending on organizational scale and regulatory exposure.
Product Type:
Enterprise procurement teams weight infrastructure overhead against data residency requirements when selecting hardware-software configurations.
- Virtual Phone:Streams Android OS entirely from remote GPU-accelerated servers with centralized security patching. Financial services compliance mandates in Singapore and London drive demand for audit-logging integration and immutable call recording.
- Hybrid Phone:Combines local processing for sensitive data with cloud rendering for compute-intensive workloads. Regulated industries across Germany and France favor this architecture for GDPR Article 44 compliance and biometric data isolation.
- Cloud-Based Device:Thin-client hardware with minimal local storage, optimized for cost-sensitive SME deployments in India.
- IoT Phone:Specialized form factors for industrial fieldwork and logistics tracking, prevalent in warehouse automation projects across the Netherlands.
Volume sits with Virtual Phone; growth tilts toward Hybrid Phone.
Service Type:
Pricing model selection correlates with IT staff availability and preference for operational versus capital expenditure treatment.
- Subscription Services:Recurring revenue structures dominate enterprise accounts seeking predictable budgeting and automatic feature updates. Indian SME digitization programs accelerate adoption of monthly billing cycles over upfront hardware investment.
- Managed Services:Complete endpoint administration outsourcing attracts organizations lacking dedicated mobile IT staff. Indonesian micro-enterprises leverage bundled support through telco distribution partnerships.
- One-Time Purchase:Perpetual licensing persists in government sectors with restricted recurring payment authority.
- Freemium Model:Tiered entry points convert individual freelancers and solopreneurs in Brazil and Mexico.
Revenue concentrates in Subscription Services; margin expansion favors Managed Services.
Deployment:
Latency physics and data sovereignty rules determine architectural choices more than cost optimization alone.
- Public Cloud:Shared infrastructure delivers lowest per-stream economics for non-sensitive workloads. Indian PLI-subsidized data centers enable aggressive pricing for SME-facing services.
- Private Cloud:Dedicated server environments satisfy China's MIIT localization mandates and financial services audit requirements. Capital intensity limits adoption to regulated multinationals with domestic Chinese operations.
- Hybrid Deployment:Workload-specific routing between public and private tiers optimizes cost-compliance tradeoffs for EU-based enterprises.
- Edge Computing:Sub-50ms latency guarantees through localized rendering nodes support real-time gaming and CAD applications in Seoul and Tokyo metro markets.
Public Cloud carries volume leadership; Edge Computing climbs the fastest on 5G network slicing integration.
End User:
Organizational scale dictates feature complexity, security tier, and support intensity requirements.
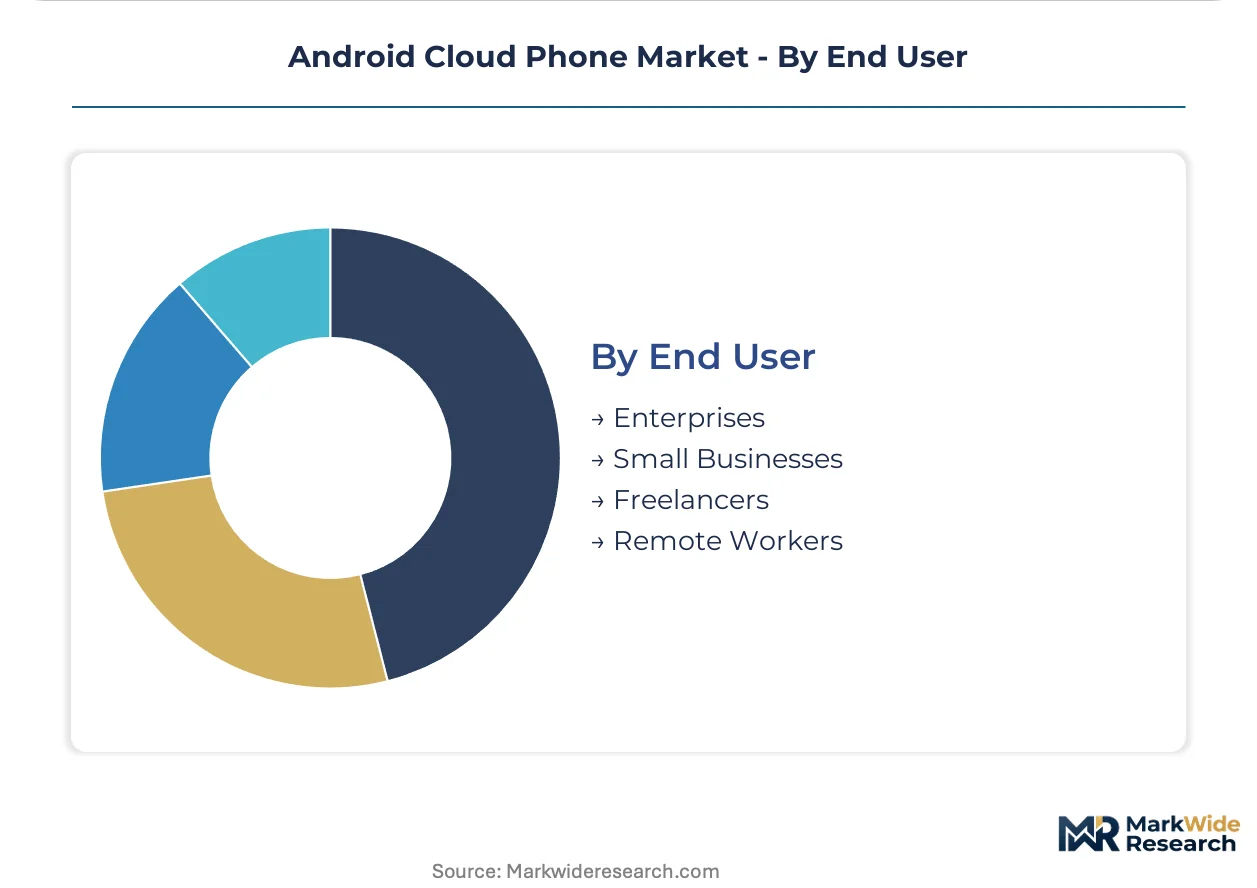
- Enterprises:Unified endpoint management integration and identity federation dominate procurement criteria. SEC and FINRA record-keeping rules push banking sector buyers toward centralized logging architectures.
- Remote Workers:Bring-your-own-device replacement strategies accelerate as employers seek control over communications compliance. Distributed teams across Australia and Canada drive demand for cross-border low-latency access.
- Small Businesses:Price sensitivity and minimal IT staffing favor fully managed subscription tiers with bundled support.
- Freelancers:Individual productivity tools and flexible billing cycles characterize this price-conscious segment.
Enterprises anchor current revenue; Remote Workers represent the steepest expansion trajectory as distributed work policies institutionalize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon foundry capacity in Taiwan anchors GPU virtualization hardware for cloud phone infrastructure, while data center buildouts across India and Indonesia reshape regional deployment economics.
China
MIIT cloud computing standards and SAMR data localization rules compel domestic server presence for foreign operators. Shanghai and Beijing host the densest concentration of edge nodes serving financial services compliance mandates. Huawei and Baidu leverage captive infrastructure to undercut multinational pricing.
India
TRAI cloud service frameworks and PLI-subsidized data center buildouts lower compute costs for SME-facing services. Mumbai and Bangalore clusters see aggressive expansion from local providers leveraging subsidized server capacity. BIS device certification standards shape import compliance for virtualization platforms.
United States
SEC and FINRA record-keeping requirements push banking sector buyers toward centralized logging architectures. Northern Virginia and Dallas-Fort Worth data center corridors anchor latency-sensitive financial services deployments. Google and Microsoft extend workspace virtualization into mobile endpoints.
Germany
GDPR Article 44 transfer mechanism rulings and Schrems II decisions force EU-isolated authentication shards for identity data. Frankfurt and Munich host hybrid phone pilots for biometric compliance under EU AI Act provisions. German enterprise procurement mandates data residency attestations pre-contract.
Indonesia
64 million micro-enterprises lacking dedicated IT staff create white space for fully managed subscriptions. Jakarta and Surabaya telco partnerships unlock distribution for bundled support services. Central bank digital payment integration accelerates cloud phone adoption for merchant transactions.
Android Cloud Phone Market Competitive Landscape
Global majors compete with regional champions across infrastructure ownership and compliance certification dimensions. The vendor base stratifies between hyperscale cloud operators, captive hardware-software integrators, and specialized virtualization pure-plays. Three archetypes dominate: ecosystem-anchored platforms leveraging mobile OS dominance, vertically integrated infrastructure owners with data center assets, and agile regional specialists targeting price-sensitive SME segments. Competitive moves concentrate on geographic licensing partnerships and edge node co-location agreements with mobile operators.
Within the ecosystem-anchored tier, Google and Microsoft occupy positions leveraging workspace productivity integration, while Huawei exemplifies the vertically integrated archetype through proprietary silicon-cloud coupling. Redfinger and Hippo Cloud Phone sit among regional specialists targeting cost-optimized streaming tiers in Asian markets.
| Leading Market Players |
|---|
| Redfinger |
| Hippo Cloud Phone |
| Microsoft |
| Huawei |
| Baidu |
| Aiyuntu |
| Duoduo Cloud Phone |
| VMOS Cloud |
| Others |
Pricing and Supply Chain Analysis
Enterprise procurement consolidation around unified endpoint management platforms compels virtualization providers to absorb security orchestration and identity federation costs previously borne by third-party integrators, compressing margins and forcing tier unbundling across subscription tiers.
Pricing Analysis
Service-bundling configurations separate compute, storage, and management tiers as Indian and Indonesian buyers reject all-inclusive platform fees. Three-tier pricing structure across premium, standard, and economy levels reflects latency guarantees, GDPR certification status, and GPU allocation density. Cost compression in economy tiers intensifies because PLI-subsidized Indian data centers enable local providers to undercut foreign competitors. Small businesses and freelancers exhibit highest price sensitivity; financial services enterprises prioritize compliance-grade tiers regardless of premium positioning.
Supply Chain Analysis
Regional distribution centers cluster around hyperscale cloud corridors in Northern Virginia, Frankfurt, Mumbai, and Singapore to minimize edge node deployment latency. GPU virtualization hardware draws from TSMC's Taiwan foundries for NVIDIA A100 and H100 clusters, ARM-based Graviton and Axion silicon from AWS and Google, and captive Kirin-cloud integration from Huawei's domestic Chinese facilities. Single-source vulnerability concentrates in advanced node semiconductor access, where geopolitical friction threatens rendering capacity expansion. Distribution runs through telco partnership channels across Indonesia and India, with direct hyperscaler sales dominating enterprise accounts in North America and Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around platform-scale players as compliance certification burdens and edge infrastructure capital requirements squeeze subscale virtualization pure-plays from procurement shortlists.
For Market Incumbents: Acquire edge node real estate within 500 kilometers of financial services corridors in Singapore, London, and New York to defend latency positioning against emerging GPU-cloud specialists. Absorb identity federation and audit-logging capabilities in-house to eliminate third-party integration friction extending sales cycles. Prioritize MIIT-compliant server presence in China before SAMR enforcement hardens further. For New Entrants and Emerging Players: GPU virtualization optimization for CAD and console-grade gaming workloads offers entry traction against incumbent productivity-focused positioning. Indonesia's 64 million micro-enterprises lacking IT staff present the most penetrable geography, accessible through telco distribution partnerships bundling managed support. Lead with freemium conversion funnels targeting Brazilian and Mexican freelancers before upselling to SME tiers. For Investors and Strategic Acquirers: The window for entry favors vertically integrated infrastructure owners with captive data center assets and pre-certified compliance pipelines over software-only virtualization plays. Long-term viability hinges on regulatory certification moats deepening faster than interoperability standards can commoditize them. Monitor Schrems II rulings and MIIT enforcement patterns as inflection signals for EU and China market access viability.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Node Co-location Agreement | Secures sub-50ms latency guarantees through 5G network slicing partnerships with mobile operators. |
| GDPR Article 44 Compliance Certification | Enables German enterprise procurement requiring data residency attestations pre-contract execution. |
| GPU-Accelerated Rendering Cluster Expansion | Supports console-grade gaming and CAD workloads for architecture and media firm demand. |
| MIIT Domestic Server Presence Establishment | Satisfies China's data localization mandates for foreign virtualization platform operators. |
| Unified Endpoint Management Platform Integration | Compresses vendor ecosystems by embedding security orchestration directly into cloud phone stacks. |
Research Methodology
Multi-period observation of hyperscaler capex disclosures, GPU cluster deployment announcements, and regulatory filing patterns anchored the trend analysis, supplemented by interviews with enterprise IT procurement officers, cloud infrastructure architects, telco partnership leads, and virtualization platform product managers. Secondary validation drew from SEC filings, MIIT and TRAI regulatory publications, hyperscaler data center expansion announcements, and EU AI Act implementation guidance. Bottom-up segmentation modeling triangulated against top-down market sizing from infrastructure investment flows.
Input-output matrices mapped subscription tier adoption rates, latency-sensitive workload migration patterns, and compliance-driven procurement criteria across product type, service model, deployment architecture, and end-user scale dimensions. CAGRs derived from fitted growth curves incorporating GPU virtualization cost trajectories, 5G network slicing penetration timelines, and data sovereignty rule fragmentation intensity. Industry-specific forecast inputs included PLI scheme subsidy utilization rates and edge node density projections.
Forecast precision tightens around the base case; tail outcomes carry wider variance under MIIT enforcement escalation, TSMC foundry capacity constraints, or Schrems II ruling expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cloud Computing
SME Cloud Market
Cloud Computing
Germany Cloud Computing Market
Cloud Computing
Web Scale IT Market
Cloud Computing
Bare Metal Cloud Market
Cloud Computing
Cloud Computing Services Market
Cloud Computing
Hybrid Cloud in BFSI Market
Cloud Computing
Nigeria Cloud Computing Market
Cloud Computing
Cloud Enterprise Content Management Market
Cloud Computing
Cloud Calling Market
Cloud Computing
Spain Cloud Computing Market
Cloud Computing
Global Cloud/Mobile Backend AS a Service (Baas) Market
Cloud Computing
Industrial Cloud Market
Cloud Computing
Public Cloud in BFSI Market
Cloud Computing
Cloud API and Management Platforms and Middleware Market
Cloud Computing
Asia Pacific Multi-Cloud Management Market
Cloud Computing
Cloud Management Platform Market