
 Europe Pharmacy POS Software Market | 2026-2036
Europe Pharmacy POS Software Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pharmacy POS Software Market Foresight
Subscription-based feature modules is decoupling hardware sales from recurring software revenue in European pharmacy retail. NCR Corporation leverages its self-service kiosk heritage to anchor cloud-migration contracts with mid-sized pharmacy chains. Cegedim Group specializes in health-data interoperability, sustaining long-term client retention across French-speaking markets. Omnicell, Inc. competes on automated dispensing integration, extending its POS footprint into hospital outpatient pharmacies.
Europe Pharmacy POS Software comprises transaction-processing platforms engineered for pharmaceutical retail compliance, typically integrating GS1 barcode verification, prescription audit trails, and real-time stock-level monitoring with national reimbursement systems. These systems serve the dual commercial purpose of streamling checkout workflows while enforcing anti-counterfeiting traceability mandated under the EU Falsified Medicines Directive. Cloud-based deployment leads segment share as independent pharmacies in Italy and Spain abandon capital-intensive on-premise servers for SaaS models with automatic regulatory patching. The Feature Set dimension concentrates margin pools in inventory management modules that synchronize with wholesaler EDI networks, while Payment Processing functions face commoditization from non-specialized fintech entrants.
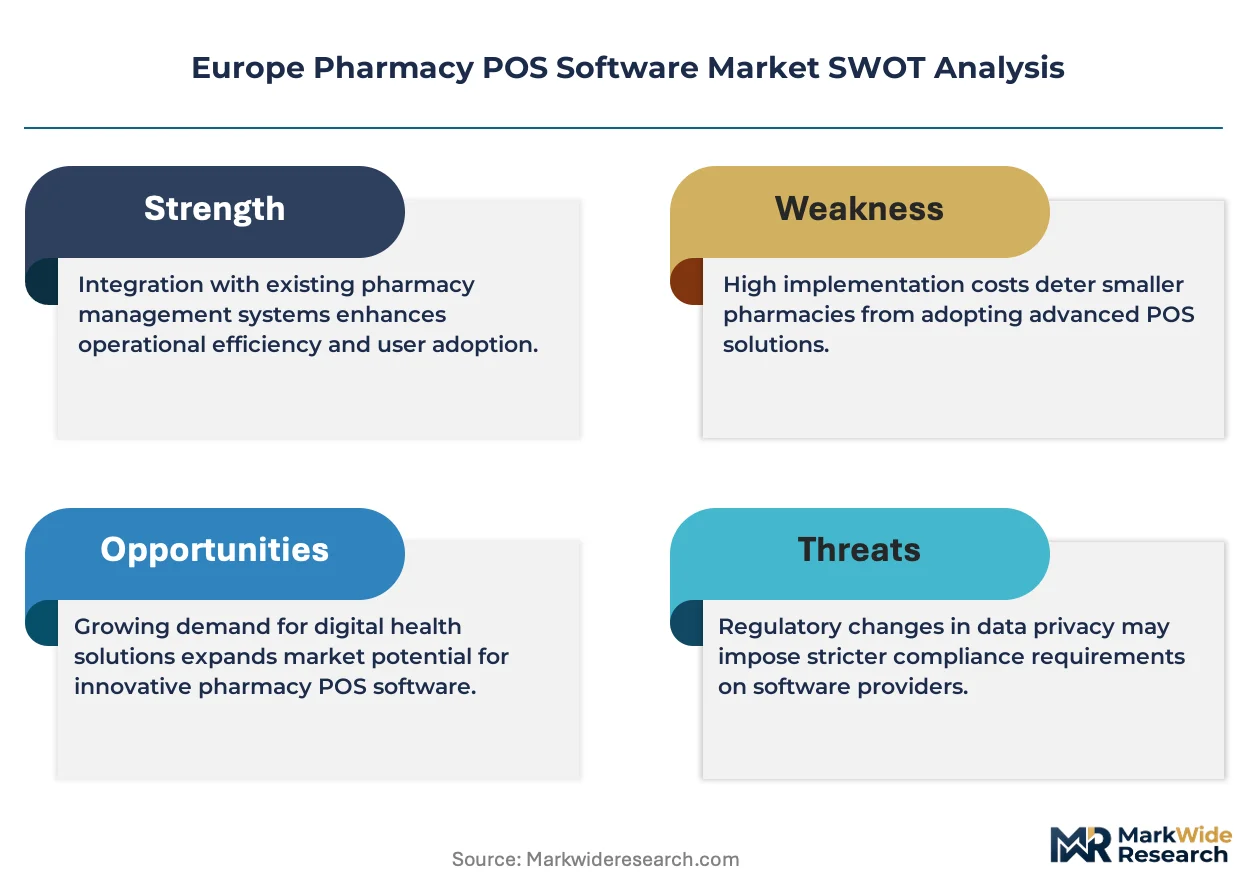
The EU Green Deal's digitalization incentives, EMA pharmacovigilance reporting standards, and national data-protection authorities enforcing GDPR-compliant patient-data handling collectively elevate compliance costs for software vendors seeking multi-country deployment. REACH chemical-tracking extensions into pharmaceutical logistics further complicate inventory-module certification requirements. Stakeholders must monitor divergence between EU harmonized standards and member-state reimbursement-system APIs when evaluating cross-border platform scalability.
Market Dynamics
The EU Falsified Medicines Directive serialization mandates are forcing pharmacy chains to replace legacy POS systems with compliance-integrated platforms, compressing upgrade cycles from seven years to under four.
Growth Catalysts
- EMA pharmacovigilance reporting standards:Real-time adverse-event tracking requirements are driving pharmacy software investments that automate regulatory submission workflows and reduce manual audit preparation.
- Hospital outpatient pharmacies:These facilities are expanding automated dispensing integration with POS terminals to manage high-volume specialty medication fulfillment under tighter reimbursement controls.
- Cloud migration:Italian and Spanish independent pharmacies are abandoning on-premise servers for SaaS models that deliver automatic GDPR-compliant security patching without capital expenditure.
Market Restraints
- GDPR compliance costs:Patient-data handling certification requirements elevate software vendor development expenses, particularly for multi-country deployment scenarios involving divergent national data-protection authority interpretations.
- Wholesaler EDI network concentration:Inventory management module functionality depends on proprietary electronic data interchange protocols controlled by dominant pharmaceutical distributors in Germany and France.
- REACH chemical-tracking extensions:Certification complexity for inventory modules handling pharmaceutical logistics is expanding development timelines and raising barriers for new market entrants.
Strategic Opportunities
- Eastern European digitization funding gaps:Polish and Romanian pharmacy markets remain underpenetrated by integrated POS-inventory platforms relative to Western European adoption rates, creating first-mover expansion potential.
- EU Green Deal digitalization incentives:Sustainability-linked public procurement criteria are favoring cloud-native software vendors that demonstrate reduced server-energy consumption in pharmacy retail operations.
- GS1 barcode verification convergence:Integration of anti-counterfeiting traceability with payment processing workflows is opening margin pools in compliance-as-a-service subscription tiers.
Industry Challenges
- Member-state reimbursement-system API fragmentation:Cross-border platform scalability requires maintaining separate integration modules for each national health insurance authority, multiplying engineering complexity.
- Legacy system interoperability:Hospital outpatient pharmacies face extended deployment timelines when connecting modern POS terminals to decades-old hospital information systems lacking standardized data exchange protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pharmacy POS Software Market |
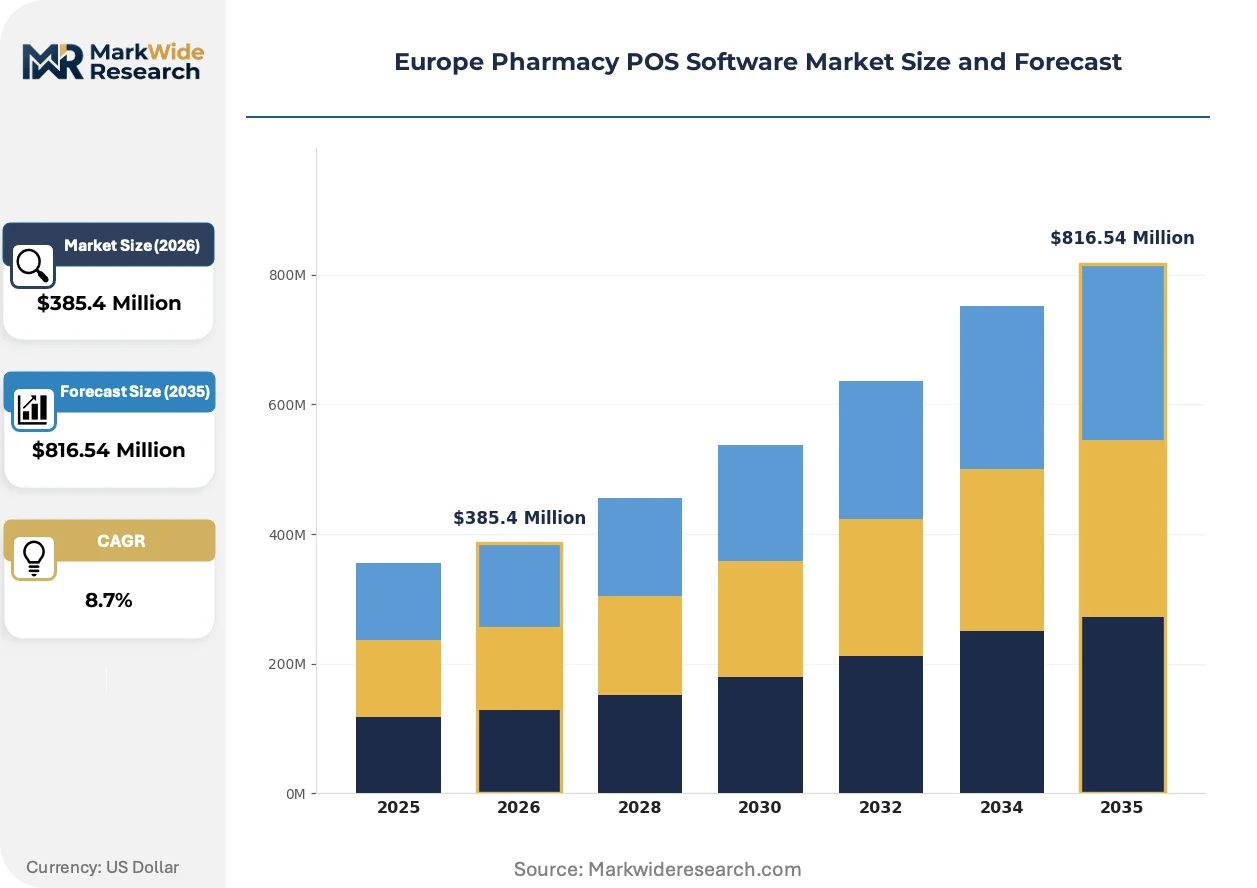
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-based, On-premise, Mobile, Hybrid End User: Independent Pharmacies, Chain Pharmacies, Drug Stores, Healthcare Providers Deployment Model: Self-hosted, SaaS, Managed Service, Subscription Feature Set: Inventory Management, Sales Analytics, Customer Management, Payment Processing |
| Companies Covered | NCR Corporation, Omnicell, Inc., Epicor Software Corporation, Cegedim Group, Cegid Group, Cerner Corporation, PDX, Inc., Bouygues Telecom Entreprises, McKesson Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pharmacy POS Software Market Shifts & Advancements
Pharmacy retail software architecture is pivoting from transaction recording toward real-time compliance orchestration, embedding regulatory verification directly into checkout workflows rather than treating it as a back-office function.
Artificial intelligence-powered demand forecasting is integrating prescription pattern analysis with seasonal disease surveillance data to optimize inventory positioning. Mid-sized pharmacy chains in France and Germany are deploying these modules fastest, compressing stockout rates while reducing working capital tied to slow-moving generics. The technology is integrating predictive analytics directly into procurement workflows, displacing manual reorder-point calculations.
REACH chemical-tracking extensions into pharmaceutical logistics are mandating serialization at the individual package level for controlled substances. ECHA compliance deadlines are forcing software vendors to recertify inventory modules for hazardous-material handling documentation. German pharmacy chains face the steepest recertification burden given their volume of opioid and psychotropic dispensing.
Subscription-based feature unbundling is fragmenting traditional perpetual-license sales into modular recurring revenue streams. Independent pharmacies in Italy are purchasing inventory-management and payment-processing capabilities separately rather than accepting bundled suites. This pattern concentrates margin pressure on commoditized payment functions while preserving pricing power in specialized compliance modules.
Europe Pharmacy POS Software Market Segmentation
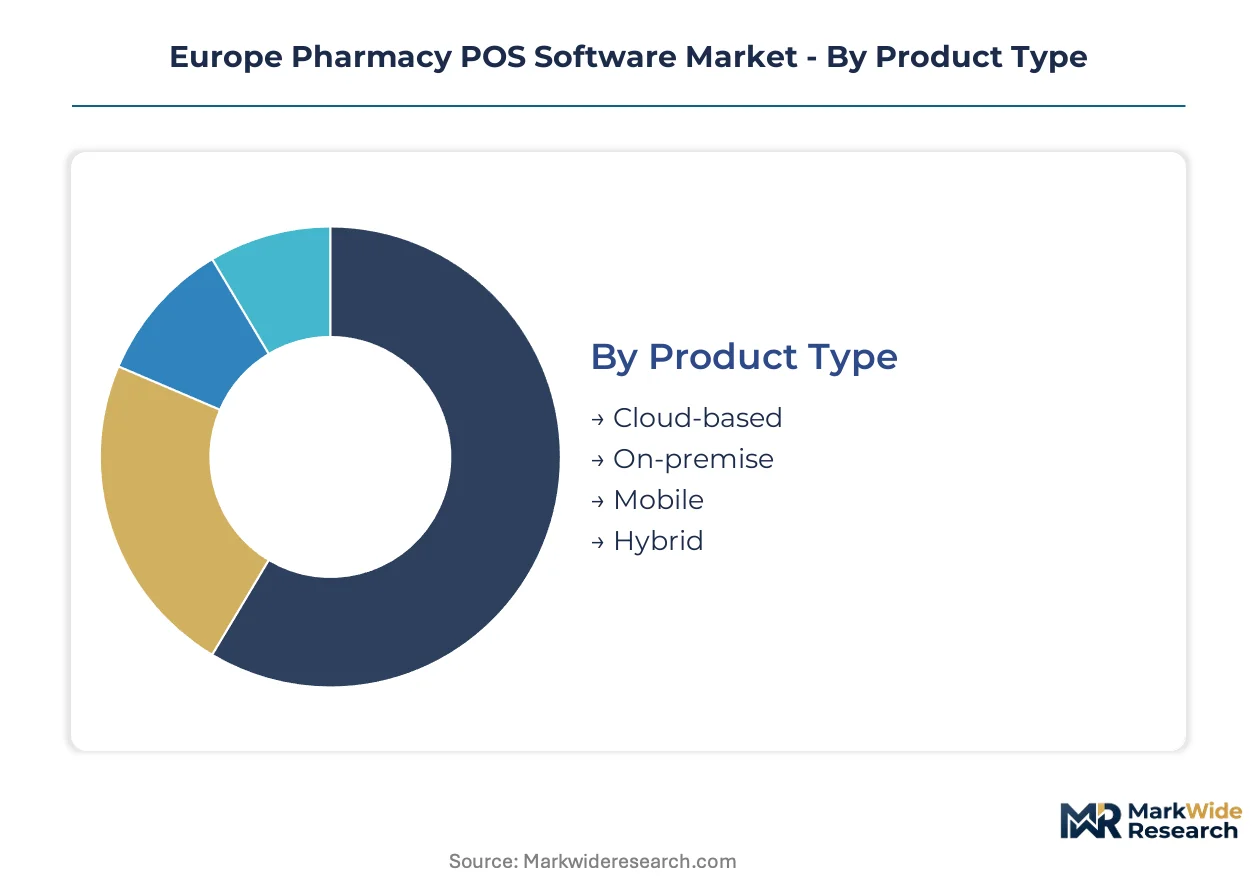
Pharmacy POS software segmentation reveals divergent technology adoption patterns between compliance-heavy Western European markets and cost-sensitive Eastern European operators. Deployment preferences directly shape vendor margin structures and customer lifetime value calculations across the region.
Product Type:
The customization-vs-standardization spectrum spans from configurable cloud platforms to rigid on-premise installations, with hybrid architectures occupying the middle ground for pharmacies seeking phased migration paths.
- Cloud-based:Multi-tenant SaaS architectures deliver automatic EMA regulatory patching and GDPR-compliant data residency through EU-based server clusters. German and French chain pharmacies dominate demand, driven by EU Falsified Medicines Directive serialization mandates that require continuous software updates without capital expenditure cycles.
- On-premise:Perpetual-license server installations retain appeal among Italian and Spanish independent pharmacies with unreliable broadband infrastructure or legacy hardware dependencies. These deployments face extended replacement cycles as GDPR compliance costs erode total cost of ownership advantages.
- Mobile:Tablet-native checkout applications support roaming prescription counseling and queue-busting during peak hours. Polish pharmacy operators are piloting these for rural branch networks.
- Hybrid:Split architectures maintain sensitive patient data on local servers while offloading payment processing to cloud gateways. Hospital outpatient pharmacies in Belgium and the Netherlands favor this model for segregation of clinical and commercial systems.
Leading the category by volume: Cloud-based. Growing fastest: Hybrid.
End User:
Customer scale determines integration complexity, with enterprise chains demanding wholesaler EDI connectivity while independents prioritize standalone simplicity.
- Independent Pharmacies:Single-location operators across Italy and Spain are abandoning capital-intensive server purchases for subscription SaaS models with automatic security patching. These customers drive feature unbundling trends, purchasing inventory management separately from payment processing.
- Chain Pharmacies:Multi-location networks in Germany and France require centralized inventory visibility across dozens of sites with real-time synchronization to national reimbursement systems. Their procurement power compresses per-seat pricing while demanding custom API development for proprietary wholesaler connections.
- Drug Stores:Health-and-beauty retailers with pharmacy licenses operate dual-category POS requirements balancing OTC retail velocity with prescription compliance workflows.
- Healthcare Providers:Hospital outpatient pharmacies integrate dispensing automation with POS terminals under tighter reimbursement controls from national health insurance authorities.
Dominating procurement volume: Chain Pharmacies. Expanding most quickly: Healthcare Providers.
Deployment Model:
Commercial arrangements range from capital-intensive ownership to fully outsourced operations, with subscription structures fragmenting traditional license revenue into recurring streams.
- Self-hosted:Customer-operated infrastructure demands internal IT competency for GDPR compliance and EMA pharmacovigilance reporting. Romanian pharmacy chains retain this model due to limited local SaaS vendor presence.
- SaaS:Software-as-a-service delivery eliminates server maintenance burdens while embedding automatic regulatory updates. Spanish independent pharmacies are migrating fastest to this model.
- Managed Service:Outsourced infrastructure operations with vendor-managed security patching and backup recovery. French pharmacy cooperatives deploy this for member networks lacking technical staff.
- Subscription:Modular feature access permits pharmacies to activate inventory management, payment processing, or compliance tools independently. Italian operators are driving unbundling adoption.
Highest revenue concentration: SaaS. Steepest expansion trajectory: Subscription.
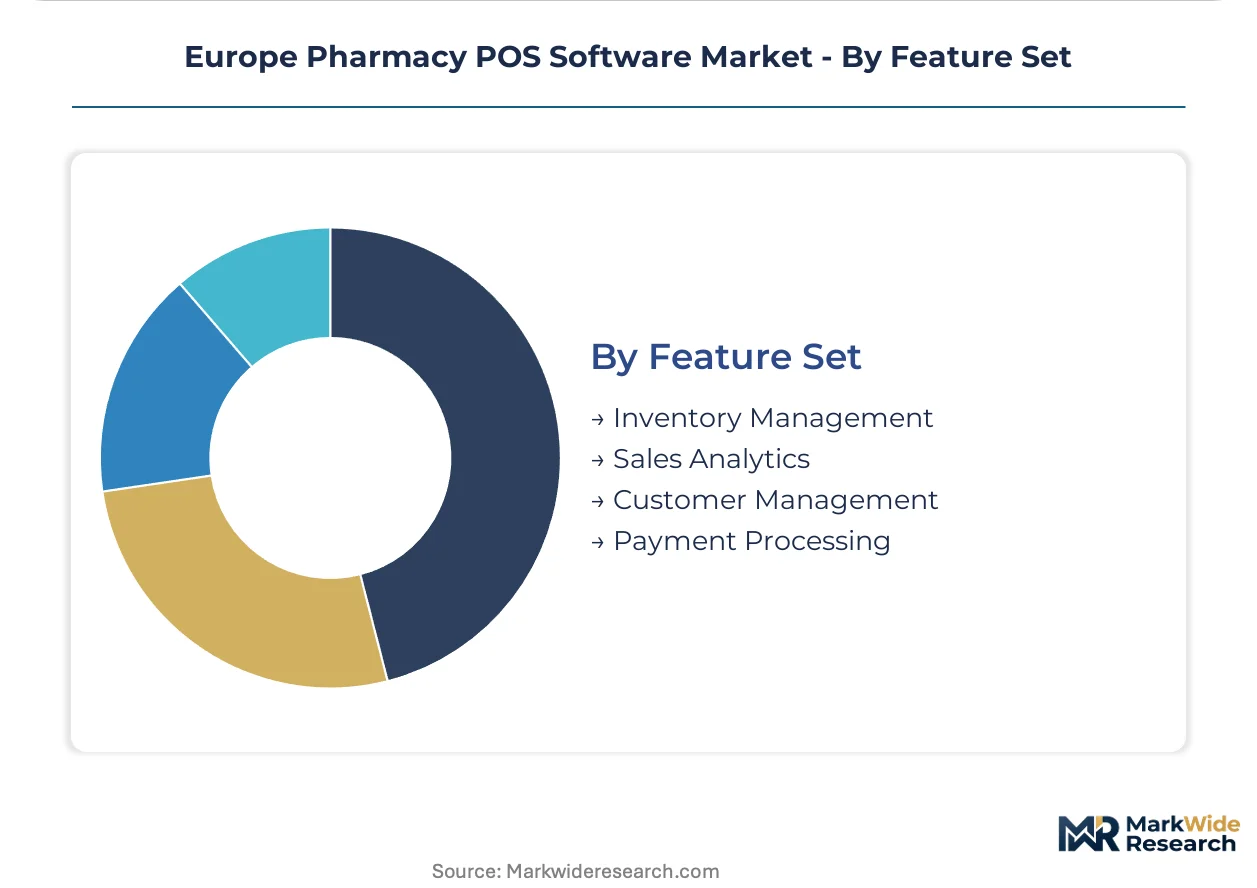
Feature Set:
Functional modules separate into high-margin specialized compliance tools and commoditized transaction processing, with inventory synchronization commanding premium pricing.
- Inventory Management:Real-time stock-level monitoring integrates with wholesaler EDI networks and GS1 barcode verification for anti-counterfeiting traceability. German pharmacy chains invest heavily here to optimize working capital across slow-moving generics and high-value specialty medications.
- Sales Analytics:Prescription pattern analysis combined with seasonal disease surveillance enables predictive procurement. French mid-sized chains deploy AI-powered demand forecasting modules fastest.
- Customer Management:GDPR-compliant patient-data handling with consent management and medication adherence tracking. Required for loyalty program operation under CNIL and national data-protection authority guidance.
- Payment Processing:Transaction routing and reconciliation functions face margin compression from non-specialized fintech entrants. Commoditization pressures concentrate vendor attention on compliance-integrated alternatives.
Commanding highest margins: Inventory Management. Gaining share fastest: Sales Analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software development concentrates in Western European technology corridors while consumption spreads across the continent's pharmacy networks. Germany and France generate the bulk of vendor revenue through chain pharmacy procurement power. Eastern European markets lag in digitization funding but present expansion vectors for cloud-native platforms.
Germany
Chain pharmacies in North Rhine-Westphalia and Bavaria drive demand for centralized inventory visibility across multi-site networks. The Federal Institute for Drugs and Medical Devices enforces stringent serialization requirements under the EU Falsified Medicines Directive. Berlin's health-tech cluster hosts several vendors developing reimbursement-system APIs for the national health insurance framework.
France
Pharmacy cooperatives in Île-de-France and Auvergne-Rhône-Alpes favor managed-service deployment models for member networks lacking technical staff. The National Agency for Food, Environmental and Occupational Health Safety coordinates with CNIL on GDPR-compliant patient-data handling standards. Lyon hosts a concentration of health-data interoperability specialists serving French-speaking markets.
Italy
Independent pharmacies in Lombardy and Lazio are abandoning on-premise servers for SaaS models with automatic security patching. The Italian Medicines Agency aligns with EMA pharmacovigilance reporting standards that automate regulatory submission workflows. Milan's pharmaceutical retail software ecosystem benefits from proximity to northern European wholesaler networks.
Spain
Independent operators in Madrid and Catalonia migrate fastest to subscription-based feature unbundling, purchasing inventory management separately from payment processing. The Spanish Agency for Medicines and Health Products enforces anti-counterfeiting traceability mandates at the regional level. Barcelona's digital health cluster supports cloud-native pharmacy platform development.
Poland
Rural pharmacy networks in Masovia and Silesia pilot mobile tablet-native checkout applications for queue-busting during peak hours. The Office for Registration of Medicinal Products oversees serialization compliance with limited local SaaS vendor presence. Warsaw's emerging health-tech sector attracts Western European platforms seeking first-mover expansion into underpenetrated markets.
Europe Pharmacy POS Software Market Competitive Landscape
Capital-heavy infrastructure vendors compete with asset-light software specialists across the European pharmacy technology stack. The vendor base organizes around three strategic tiers: enterprise-grade platform providers serving multinational chains, mid-market SaaS operators targeting independent pharmacies, and healthcare-focused specialists integrating clinical systems. Consolidation pressures favor vendors with established reimbursement-system API libraries. Dominant competitive moves include geographic expansion into Eastern European markets and portfolio diversification through modular subscription offerings.
Within the enterprise platform tier, NCR Corporation leverages self-service kiosk heritage to anchor cloud-migration contracts, while Omnicell, Inc. extends its footprint through automated dispensing integration. Cegedim Group exemplifies the health-data interoperability specialist archetype, sustaining long-term client retention across French-speaking markets through regulatory compliance depth. These three anchors represent distinct competitive vectors: hardware-originated platform breadth, clinical-system integration, and regional regulatory specialization.
| Leading Market Players |
|---|
| NCR Corporation |
| Omnicell, Inc. |
| Epicor Software Corporation |
| Cegedim Group |
| Cegid Group |
| Cerner Corporation |
| PDX, Inc. |
| Bouygues Telecom Entreprises |
| McKesson Corporation |
| Others |
Supply & Pricing Matrix
GDPR compliance certification costs flow from specialized auditor fees through subscription pricing tiers, compressing margins for SaaS vendors serving multi-country pharmacy chains while elevating entry barriers for new software entrants.
Pricing Analysis
Price erosion across payment-processing modules traces to non-specialized fintech entrants commoditizing transaction routing functions. Pricing stratifies across compliance-heavy premium tiers, mid-market subscription bundles, and economy self-hosted licenses. Cost-down pressure on standalone payment features accelerates because pharmacy operators unbundle inventory management from checkout processing. Independent pharmacies in Italy exhibit highest price sensitivity, while German chain pharmacies prioritize regulatory depth over per-seat cost.
Supply Chain Analysis
Regional distribution centers in Germany, France, and the Netherlands anchor software delivery to pharmacy networks across Western Europe. Development talent concentrates in Berlin, Lyon, and Barcelona health-tech clusters, with implementation services drawing from local IT consultancies. Single-source vulnerability sits with dominant pharmaceutical distributors controlling proprietary EDI protocols in Germany and France. Distribution runs through vendor-direct sales for enterprise chains and cooperative-managed service arrangements for independent pharmacy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressures favor vendors with established reimbursement-system API libraries, as member-state fragmentation forces weaker players toward exit or niche specialization.
For Market Incumbents: Deploy modular subscription architectures to capture recurring revenue from Italian and Spanish independents abandoning perpetual licenses. Deepen API integration with Germany's national health insurance framework before EMA pharmacovigilance reporting deadlines tighten. Counter fintech payment commoditization by embedding GS1 barcode verification into checkout workflows as a compliance-differentiated premium tier. For New Entrants and Emerging Players: Rural pharmacy networks in Poland and Romania represent the most penetrable white-space opportunity, with limited local SaaS vendor presence and pilot-ready mobile deployment demand. Prioritize cloud-native platforms with automatic GDPR patching to bypass legacy infrastructure dependencies. Pursue cooperative-managed service partnerships rather than direct enterprise sales to overcome established vendor relationships in Western European chain pharmacies. For Investors and Strategic Acquirers: Accelerating chain pharmacy consolidation in Germany and France is the leading indicator that reimbursement-system API libraries will command acquisition premiums within the mid-market vendor tier. Long-term viability hinges on regulatory compliance depth rather than feature breadth, favoring targets with EMA pharmacovigilance automation and multi-country GDPR certification track records. Monitor divergence between EU harmonized standards and member-state implementation timelines as the critical inflection signal for platform scalability risk.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Platform Migration | Automatic EMA regulatory patching eliminates capital expenditure cycles for Italian independents. |
| Reimbursement System API Expansion | German national health insurance framework integration secures multi-year chain pharmacy contracts. |
| Modular Feature Unbundling | Inventory management subscriptions separate from payment processing to capture Italian demand. |
| GDPR Compliance Certification Investment | CNIL and national data-protection authority alignment enables French cooperative network expansion. |
| Eastern European Geographic Expansion | Polish and Romanian first-mover positioning exploits underpenetrated SaaS vendor presence. |
Research Methodology
EMA pharmacovigilance reporting guidelines, EU Falsified Medicines Directive implementation documents, and national reimbursement system API specifications formed the secondary backbone. Primary interviews with pharmacy IT directors, health-data interoperability specialists, and cooperative procurement managers combined with bottom-up and top-down triangulation. SEC filings from listed pharmacy technology vendors and GPO contract databases provided financial validation.
Bottom-up modeling aggregated segment-level deployment data across cloud, on-premise, mobile, and hybrid architectures. Top-down validation cross-referenced vendor revenue disclosures against pharmacy operator procurement surveys. Segmentation dimensions spanned deployment model, pharmacy scale, feature set modularization, and regional regulatory cluster complexity. CAGR derivation incorporated EMA compliance deadline impacts and cloud migration adoption curves throughout the forecast period.
Revisions become necessary when member-state reimbursement system API divergence accelerates, EMA pharmacovigilance reporting standards expand scope, or GDPR enforcement interpretations harden across national data-protection authorities. Forecasts reflect documented assumptions regarding regulatory timeline adherence and pharmacy operator technology refresh cycles. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Latin America Cloud Workforce Management Software Market
Software & Services
Lighting Control Software Market
Software & Services
Enterprise MLC (Emlc) Market
Software & Services
Language Translation Software Market
Software & Services
Construction Software As A Service Market
Software & Services
Executive Search (Headhunting) Software Market
Software & Services
Desktop Publishing Software Market
Software & Services
Global Configuration Management Software Market
Software & Services
Tech Support Services Market
Software & Services
Database Monitoring Software Market
Software & Services
Geophysical Software Service Market
Software & Services
Remote Browser Market
Software & Services
Sales Coaching Software Market
Software & Services
Drone Mapping Software Market
Software & Services
Account Reconciliation Software Market
Software & Services
Scanning and Migration Software Market