
 Trading Software Market | 2026-2036
Trading Software Market Size, Share, and Industry Trends Forecast 2026-2036
Trading Software Market Outlook
The EU AI Act is restructuring compliance requirements for algorithmic trading systems across European venues. Charles Schwab Corporation leverages its branch-brokerage hybrid model to sustain retail dominance. Interactive Brokers LLC anchors institutional flow through low-cost API access and multi-asset connectivity.
Trading software encompasses applications that execute, route, and analyze financial instrument orders with sub-millisecond latency thresholds and FIX protocol compatibility. These systems serve commercial purposes spanning price discovery, liquidity provision, and regulatory reporting automation. Algorithmic Trading and High-Frequency Trading segments command premium infrastructure spending due to co-location and direct market access requirements. Cloud-Based deployment is expanding fastest as hedge funds and brokers migrate tick databases and backtesting environments away from captive data centers.
SEC market access rules and MiFID II best execution mandates shape platform architecture decisions across US and European jurisdictions. FINRA supervision guidelines and FCA SYSC requirements further constrain order routing logic and audit trail retention. Stakeholders must weigh latency optimization against escalating compliance automation costs as regulatory granularity intensifies.
Market Dynamics
Cloud migration is compressing infrastructure ownership timelines across buy-side and sell-side institutions, forcing platform vendors to rearchitect latency-critical execution stacks for elastic deployment.
Growth Catalysts
- EU AI Act algorithmic governance:Compliance mandates for explainable trading models are accelerating procurement of audit-ready platforms across European venues.
- Self-directed retail brokerage:Commission compression and mobile-native interfaces are pulling individual investors toward direct market access tools previously reserved for professionals.
- Co-location density:Proximity hosting at major exchange data centers in the United States continues to drive premium infrastructure commitments from quantitative funds.
Market Restraints
- FIX protocol fragmentation:Venue-specific message extensions and custom tags inflate integration costs for multi-asset connectivity.
- Tick data storage economics:Petabyte-scale historical datasets require specialized compression and tiered retention policies that strain operational budgets.
- SEC market access rule liability:Broker-dealers face direct regulatory exposure for downstream algorithmic errors, elevating risk management overhead.
Strategic Opportunities
- India SEBI algorithmic trading framework:Formalized co-location guidelines and API standardization are opening institutional-grade infrastructure to domestic asset managers.
- Crypto-derivatives convergence:Unified risk engines spanning traditional and digital asset classes offer cross-margin efficiencies for multi-asset brokers.
- Serverless backtesting environments:On-demand compute for strategy simulation is displacing captive data center footprints among emerging hedge funds.
Industry Challenges
- Low-latency engineering talent scarcity:Kernel-bypass networking and FPGA programming expertise commands compensation premiums that strain vendor hiring pipelines.
- Multi-jurisdiction audit trail harmonization:Reconciling MiFID II transaction reporting with FINRA supervision requirements demands redundant data pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trading Software Market |
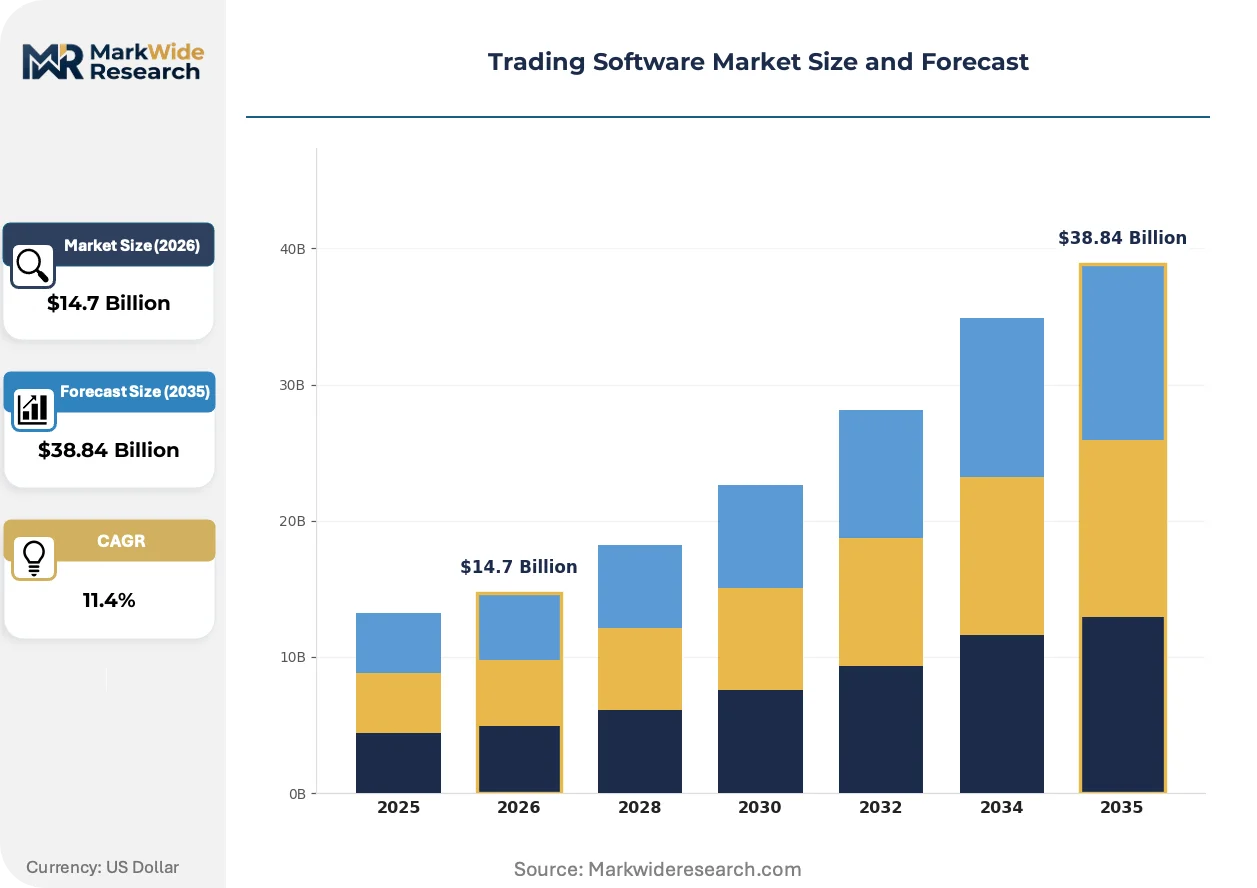
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $38.84 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Algorithmic Trading, High-Frequency Trading, Desktop Platforms, Mobile Trading Solution: Risk Management, Portfolio Management, Execution Management, Analytics Tools End User: Retail Traders, Institutional Investors, Hedge Funds, Brokers Deployment: Cloud-Based, On-Premises, Hybrid Solutions, Software as a Service |
| Companies Covered | Charles Schwab Corporation, Interactive Brokers LLC, IG Group Holdings plc, TD Ameritrade Holding Corporation, Robinhood Markets Inc., Oracle, SAP, Shark Technologies, TradeStation Group, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trading Software Market Strategic Shifts
Platform architecture is bifurcating between sub-millisecond execution engines and analytics-heavy cloud environments, with vendors forced to maintain dual competency or cede segments.
FPGA-based tick-to-trade pipelines are absorbing order flow from software-only stacks at major quantitative funds. These reconfigurable logic arrays process market data and generate signals in single-digit microseconds. The structural consequence is compressing latency differentiation among co-located participants.
EU AI Act risk management obligations are mandating algorithmic documentation and human oversight protocols for automated trading systems. Investment firms must maintain model inventories and conduct regular stress testing. European systematic strategies are responding by embedding compliance checkpoints directly into execution workflows.
Retail order flow monetization is fragmenting traditional commission structures, with zero-commission brokers capturing revenue through payment-for-order-flow arrangements. Institutional routing logic is adapting to this bifurcation. The United States exhibits the most pronounced channel separation between retail and wholesale execution quality tiers.
Trading Software Market Segmentation
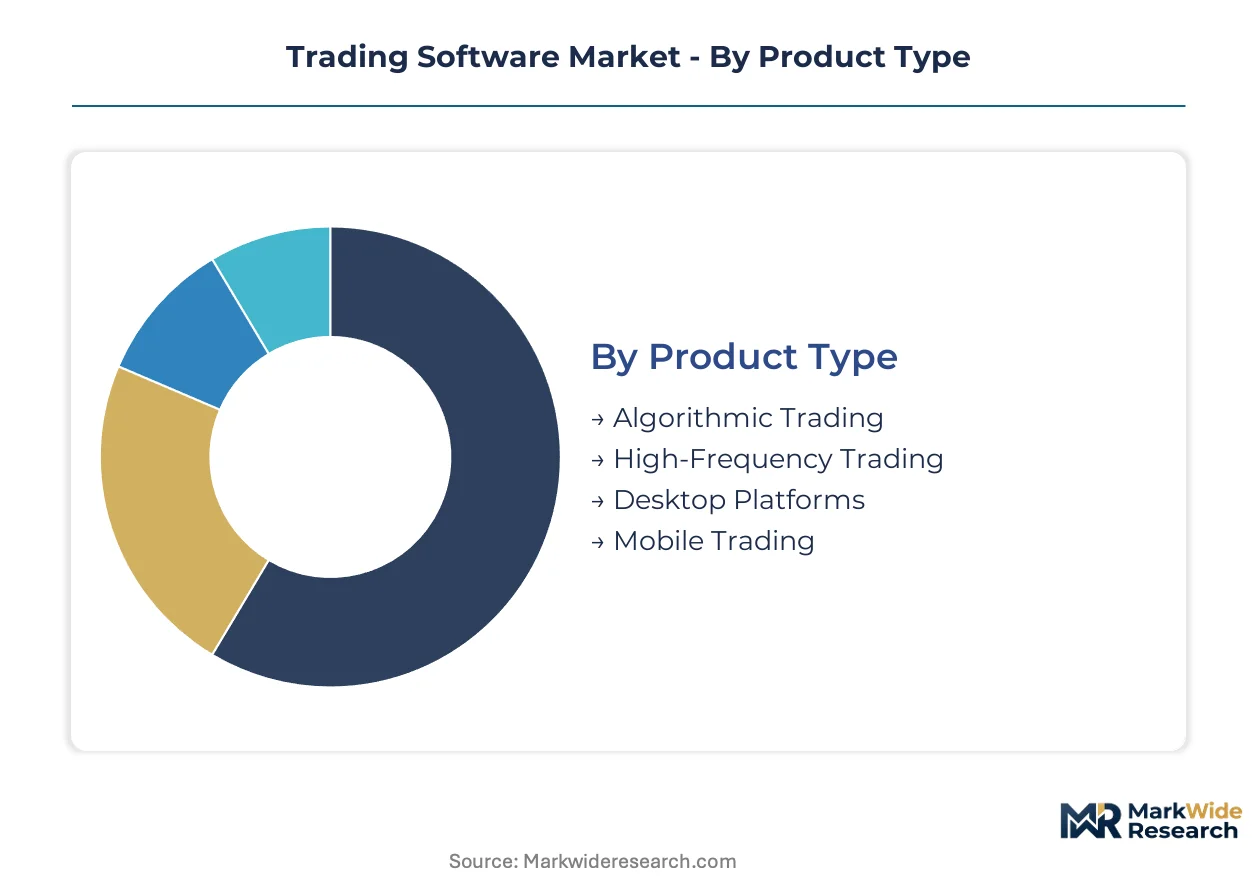
Trading software procurement diverges sharply by latency tolerance, regulatory burden, and infrastructure ownership preferences. Vendors must maintain parallel competency across sub-millisecond execution stacks and analytics-heavy cloud environments to capture spend across buyer types.
Product Type:
Buyers in this category separate by infrastructure intensity and co-location requirements, with quantitative funds prioritizing hardware proximity while retail platforms optimize for accessibility.
- Algorithmic Trading:Rule-based execution systems process market signals through pre-programmed logic gates with minimal human intervention. Hedge funds in the United States drive procurement volume, compelled by SEC market access rules that assign broker-dealer liability for downstream errors.
- High-Frequency Trading:FPGA-accelerated tick-to-trade pipelines achieve single-digit microsecond latencies through kernel-bypass networking and direct exchange connectivity. Co-location density at major data centers concentrates demand among quantitative specialists seeking proximity hosting advantages.
- Desktop Platforms:Installed workstation software delivers advanced charting and order routing for active retail traders.
- Mobile Trading:Native iOS and Android applications prioritize execution simplicity and biometric authentication for smartphone-native investors.
Volume sits with Algorithmic Trading; growth tilts toward Mobile Trading.
Solution:
Functional requirements in this category map to organizational maturity, with sophisticated institutions demanding integrated risk engines while emerging managers prioritize standalone analytics.
- Risk Management:Real-time position monitoring and pre-trade limit enforcement systems prevent regulatory breaches and catastrophic losses. EU AI Act compliance mandates are accelerating European procurement of audit-ready platforms with embedded model governance.
- Execution Management:Order routing logic optimizes venue selection and market impact across fragmented liquidity pools. MiFID II best execution requirements in Europe and FINRA supervision guidelines in the United States shape architecture decisions.
- Portfolio Management:Multi-asset allocation tools track performance attribution and tax optimization across holdings.
- Analytics Tools:Backtesting environments and visualization dashboards support strategy development without live capital deployment.
Revenue concentrates in Risk Management; portfolio construction tools are climbing the fastest.
End User:
Customer scale in this category determines pricing models and support structures, with retail aggregators demanding zero-commission economics while institutions pay premium fees for API reliability.
- Institutional Investors:Asset managers and pension funds require FIX protocol compatibility and multi-venue connectivity for block execution. Regulatory reporting automation and audit trail retention drive platform selection among compliance-constrained organizations.
- Hedge Funds:Systematic strategies prioritize co-located infrastructure and direct market access for alpha capture. Emerging managers are displacing captive data centers with serverless backtesting environments to compress fixed costs.
- Retail Traders:Self-directed investors access markets through commission-compressed mobile interfaces with payment-for-order-flow economics.
- Brokers:Intermediary platforms balance proprietary technology with white-label vendor solutions to serve downstream clients.
Brokerage aggregators capture the largest user base; hedge fund technology spending shows the steepest expansion trajectory.
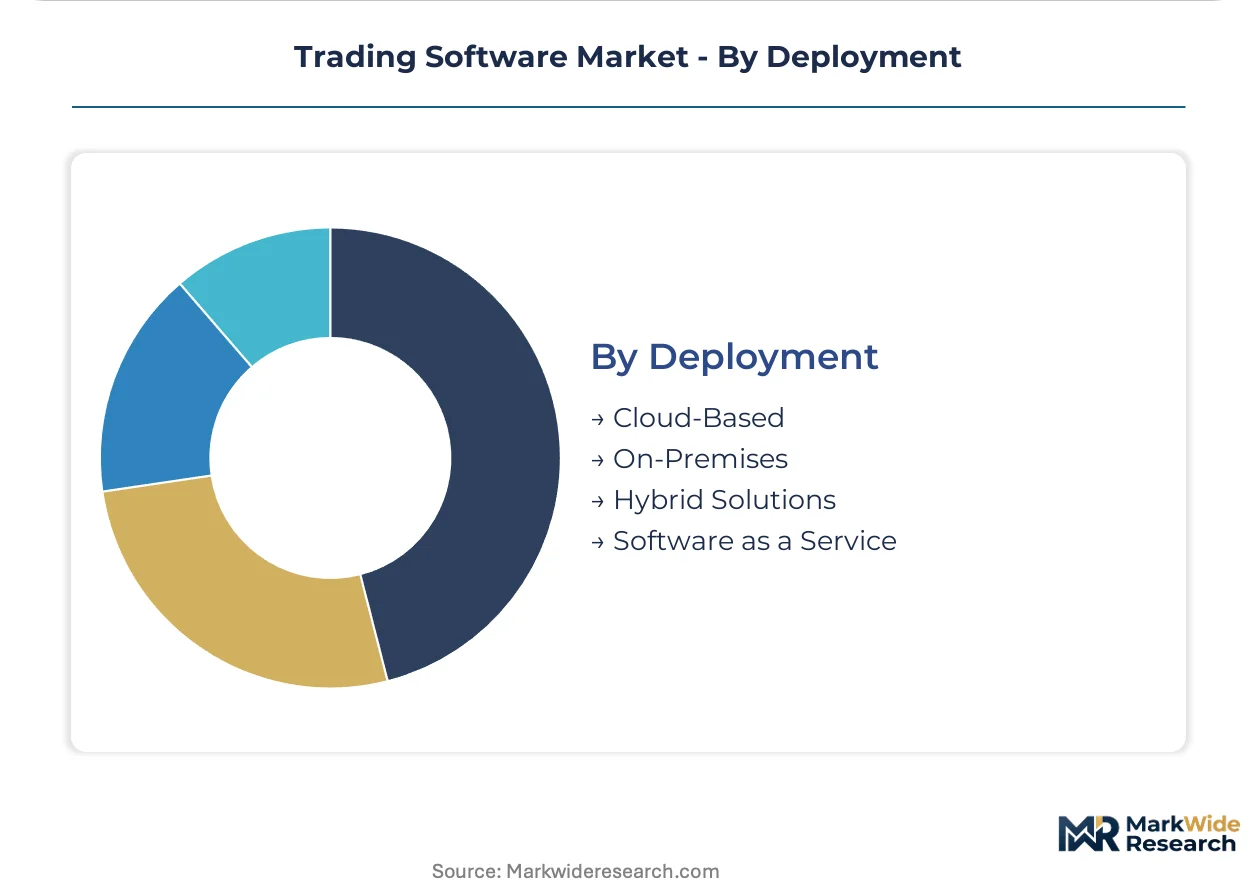
Deployment:
Infrastructure preferences in this category reflect data sovereignty requirements and latency sensitivity, with regulated entities maintaining on-premises control while agile funds embrace elasticity.
- Cloud-Based:Elastic compute and storage resources enable hedge funds to scale tick databases and simulation workloads without capital-intensive data center commitments. Migration momentum is compressing vendor timelines to rearchitect latency-critical stacks for distributed deployment.
- Hybrid Solutions:Split architectures maintain sensitive execution engines on-premises while offloading analytics to public cloud infrastructure. Financial institutions in the United States leverage this model to satisfy FINRA audit requirements while capturing cloud cost efficiencies.
- On-Premises:Captive hardware installations persist among latency-arbitrage strategies requiring deterministic performance.
- Software as a Service:Subscription pricing lowers barriers for emerging managers with limited infrastructure capital.
On-Premises retains the installed base; Cloud-Based deployment is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manhattan's Financial District anchors institutional trading software demand, hosting dense concentrations of hedge funds and broker-dealers that drive infrastructure procurement decisions across the United States.
United States
SEC market access rules and FINRA supervision guidelines compel broker-dealers to maintain audit-ready execution stacks with direct liability for algorithmic errors. The Chicago Mercantile Exchange co-location facility in Aurora, Illinois concentrates high-frequency trading infrastructure spending, with quantitative funds competing for microsecond proximity advantages.
United Kingdom
MiFID II best execution mandates and FCA SYSC requirements shape platform architecture for asset managers operating across European liquidity pools. London's Square Mile hosts dense clusters of systematic hedge funds and prime brokerage operations, with vendors maintaining dual compliance pipelines for UK-EU regulatory divergence post-Brexit.
Germany
EU AI Act algorithmic governance obligations are accelerating procurement of explainable trading models among Frankfurt-based asset managers. The Deutsche Börse co-location ecosystem in Eschborn attracts proximity hosting commitments from quantitative specialists seeking deterministic performance for Xetra and Eurex connectivity.
Singapore
Monetary Authority of Singapore guidelines on technology risk management drive institutional adoption of cloud-resilient execution infrastructure. The Marina Bay financial district hosts regional headquarters for global hedge funds, with vendors rearchitecting latency-critical stacks for Asia-Pacific tick data sovereignty requirements.
India
SEBI's formalized co-location framework and API standardization are opening institutional-grade infrastructure to domestic asset managers in Mumbai. The Bandra-Kurla Complex concentrates technology spending from emerging systematic funds, with vendors adapting tick-to-trade pipelines for NSE and BSE connectivity protocols.
Trading Software Market Competitive Environment
Premium-margin players sit above commodity-margin players across latency-performance and regulatory-automation dimensions. The vendor base separates into three tiers: sub-millisecond execution specialists, cloud-native analytics platforms, and hybrid infrastructure providers serving dual compliance jurisdictions. Consolidation pressure intensifies as FIX protocol fragmentation elevates integration costs for multi-venue connectivity. Dominant competitive moves include strategic partnerships for exchange co-location access and portfolio diversification into crypto-derivatives risk engines.
Within the retail brokerage archetype, Charles Schwab Corporation and Robinhood Markets Inc. occupy positions at opposite ends of the branch-versus-digital spectrum. Interactive Brokers LLC exemplifies the institutional API-access tier, anchoring multi-asset connectivity for systematic strategies. These three entities represent divergent margin structures: hybrid physical-digital infrastructure, zero-commission mobile-native economics, and low-cost institutional flow capture respectively.
| Leading Market Players |
|---|
| Charles Schwab Corporation |
| Interactive Brokers LLC |
| IG Group Holdings plc |
| TD Ameritrade Holding Corporation |
| Robinhood Markets Inc. |
| Oracle |
| SAP |
| Shark Technologies |
| TradeStation Group, Inc. |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up execution infrastructure specialists have consolidated co-location hosting and FPGA acceleration layers across the United States and Europe, compressing vendor margins while anchoring premium pricing for sub-millisecond latency tiers. Their ownership concentration feeds directly into supply-side discipline and tiered SaaS contracting power.
Pricing Analysis
Value-based pricing anchored to execution throughput and tick-to-trade latency thresholds dominates procurement contracts for quantitative funds. Three-tier pricing structure across premium co-located, standard cloud-deployed, and economy SaaS levels separates hedge fund commitments from retail brokerage white-label arrangements. Price differentiation rests on certification grade for EU AI Act compliance and kernel-bypass networking performance guarantees. Pricing pressure stems from commission compression in retail channels and cloud infrastructure commoditization. Retail aggregators exhibit highest price sensitivity; systematic strategies with direct market access requirements show lowest.
Supply Chain Analysis
India's domestic-content mandates for financial technology infrastructure are reshaping sourcing patterns for SEBI-registered vendors serving Mumbai's Bandra-Kurla Complex. Hardware supply concentrates in Taiwan for FPGA fabrication, the United States for kernel-bypass network interface cards, and Germany for precision timing equipment. Component dependencies include Xilinx/AMD programmable logic arrays, Mellanox InfiniBand adapters, and atomic clock synchronization modules. Single-source vulnerability runs through TSMC's advanced node capacity for latency-critical silicon. Distribution runs through prime brokerage technology divisions and direct vendor relationships with quantitative funds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of kernel-bypass networking and FPGA programming expertise props pricing for latency-optimized execution stacks, constraining vendor capacity expansion and sustaining margin premiums for qualified engineering teams.
For Market Incumbents: Hedge against cloud-native disruptors by deepening captive co-location relationships at CME Aurora and Deutsche Börse Eschborn facilities. Acquire compliance-automation specialists to embed EU AI Act documentation workflows directly into execution engines. Prioritize certification investment for explainable model governance to defend against audit-ready platform challengers. For New Entrants and Emerging Players: Serverless backtesting environments offer a technology-first wedge into emerging hedge fund segments displacing captive data center footprints. Target India's SEBI-regulated domestic asset managers with API-standardized connectivity for NSE and BSE protocols. Pursue white-label partnerships with regional brokers seeking zero-commission mobile economics without proprietary development costs. For Investors and Strategic Acquirers: Distressed-cycle entries favor hybrid infrastructure providers with dual US-EU compliance pipelines in London and Frankfurt. Long-term viability hinges on cross-margin capabilities spanning traditional and crypto-derivative asset classes. Monitor SEBI co-location framework formalization as inflection signal for Indian market infrastructure consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified risk engines spanning traditional and digital assets capture cross-margin efficiencies for multi-asset brokers. |
| Strategic Partnership | Exchange co-location access agreements at CME Aurora and Deutsche Börse Eschborn secure microsecond proximity advantages. |
| Acquisition of Specialist Firm | Compliance-automation vendors with EU AI Act model governance capabilities address accelerating European procurement requirements. |
| Geographic Expansion | India SEBI framework alignment opens institutional-grade infrastructure to domestic asset managers in Mumbai. |
| Product Launch | Serverless backtesting environments displace captive data center footprints among emerging hedge funds seeking cost compression. |
Study Parameters
Multi-period observation of FIX protocol adoption rates, co-location density metrics, and cloud migration timelines anchored the trend analysis, supplemented by interviews with trading platform CTOs, hedge fund technology officers, exchange infrastructure directors, and regulatory compliance leads at broker-dealers. Secondary validation drew from SEC market access rule filings, FINRA supervision guideline updates, MiFID II transaction reporting databases, and SEBI algorithmic trading framework circulars. Bottom-up vendor revenue triangulation against top-down exchange connectivity spending estimates calibrated market sizing.
Segment-weighting across deployment models, end-user categories, and solution types shaped the analytical framework throughout the forecast period. Latency tolerance thresholds, regulatory automation requirements, and infrastructure ownership preferences informed cross-segment allocation. CAGRs derived from historical procurement patterns and projected technology refresh cycles. Industry-specific inputs included FPGA acceleration adoption curves and EU AI Act compliance spending trajectories.
Several conditions sit outside the modeled scope, including black-swan regulatory interventions, exchange technology outages affecting co-location economics, and quantum computing disruptions to encryption-dependent trading protocols. Forecasts reflect documented assumptions about cloud infrastructure cost trajectories and talent scarcity persistence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
VFX Software Market
Software & Services
Landing Page Creation Software Market
Software & Services
Global Sweepstakes Software Market
Software & Services
Lawn Care Software Market
Software & Services
Global Permit Management Software Market
Software & Services
Lab Automation Software Market
Software & Services
Global SEO Software Market
Software & Services
Software Containers Market
Software & Services
Federal Government Software Market
Software & Services
Banking Team Collaboration Software Market
Software & Services
Global Architecture Software Market
Software & Services
Audio and Video Editing Software Market
Software & Services
Specification Management Software Market
Software & Services
Application Performance Management (APM) Software Market
Software & Services
3D Modeling Software Market
Software & Services
North America Saas-Based Expense Management Market