
 Pulp Molding Machines Market | 2026-2036
Pulp Molding Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Pulp Molding Machines Market Intelligence
The shift toward high-precision, fully automatic systems is reorganizing the competitive landscape for pulp molding machines. Brødrene Hartmann A/S leverages its integrated position as a machine user and packaging producer. HGHY Pulp Molding Pack Co., Ltd. competes on manufacturing scale and technology offerings for high-volume applications. DKM Machine Manufacturing Inc. specializes in custom solutions for industrial components packaging.
Pulp molding machines are industrial systems designed to manufacture three-dimensional packaging and products from fibrous materials like recycled paper, bagasse, or virgin pulp. These machines typically utilize a vacuum forming process where a slurry of pulp is drawn onto a screen mesh mold and then dried to a rigid state. Fully automatic machines command the highest value, driven by demand from large-scale packaging manufacturers. While food packaging represents the largest application segment, electronics packaging offers higher margins for custom-engineered solutions.
Regulations including the EU's Corporate Sustainability Reporting Directive (CSRD) and single-use plastic bans in Canada and India create structural demand for plastic alternatives. Food-contact material standards from the US FDA and Europe's EFSA govern material choices and machine hygiene protocols. Consequently, vendor selection hinges on a machine's capability to process varied non-wood fiber inputs and achieve necessary certifications.
Market Dynamics
Intensifying regulatory pressure against single-use plastics is the central force shaping the pulp molding machines market. This creates structural, non-cyclical demand from the food and electronics packaging sectors for viable, fiber-based alternatives, directly influencing machine design and material compatibility requirements.
Growth Catalysts
- Regulatory Mandates:Directives like the EU Green Deal and plastic bans in Canada and India are compelling brand owners to transition packaging portfolios, creating a direct pull for pulp molding machinery capable of producing sustainable alternatives.
- Food Sector Demand:The quick-service restaurant and grocery sectors are major drivers, seeking molded fiber solutions for items like clamshell containers, cup carriers, and egg trays to replace expanded polystyrene and plastic counterparts.
- Material Innovation:The increasing commercial viability of non-wood fibers, such as bagasse, bamboo, and wheat straw, expands the raw material base, lowering input cost dependency on recycled paper and opening new application possibilities.
Market Restraints
- Capital Intensity:The high initial investment required for fully automatic, high-capacity pulp molding lines presents a significant barrier to entry for small and medium-sized enterprises, concentrating the market among larger, well-capitalized converters.
- Input Cost Volatility:The price and quality of recycled paper, the primary raw material, are subject to significant fluctuations based on collection rates and competing demand from other paper-based industries, impacting production costs.
- Technical Limitations:Molded pulp struggles to replicate the barrier properties of plastic, particularly against moisture and oxygen, which limits its use for certain long-shelf-life food products without additional costly coatings or liners.
Strategic Opportunities
- High-Margin Niches:The electronics packaging segment offers opportunities for custom-engineered, high-density molded pulp solutions designed for shock absorption, commanding premium pricing compared to commodity food packaging products.
- Emerging Market Manufacturing:Establishing production facilities in India and Southeast Asian nations allows machinery manufacturers to tap into local demand, reduce logistics costs, and serve a growing regional manufacturing base for consumer goods.
- Energy Efficiency Technologies:Developing and integrating advanced drying systems, including microwave and radio frequency technologies, presents an opportunity to significantly reduce energy consumption, a major operational cost for packaging converters.
Industry Challenges
- Compliance Complexity:Adhering to stringent food-contact material standards from bodies like the US FDA and Europe's EFSA requires extensive testing and certification, prolonging the time-to-market for new machine models and material formulations.
- Skilled Labor Scarcity:A shortage of technicians and operators with the expertise to run and maintain sophisticated, fully automated pulp molding systems can limit productivity and increase operational downtime for packaging manufacturers.
- Energy Price Exposure:The energy-intensive drying process, a critical step in pulp molding, exposes manufacturers to significant volatility in electricity and natural gas prices, directly compressing operating margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pulp Molding Machines Market |
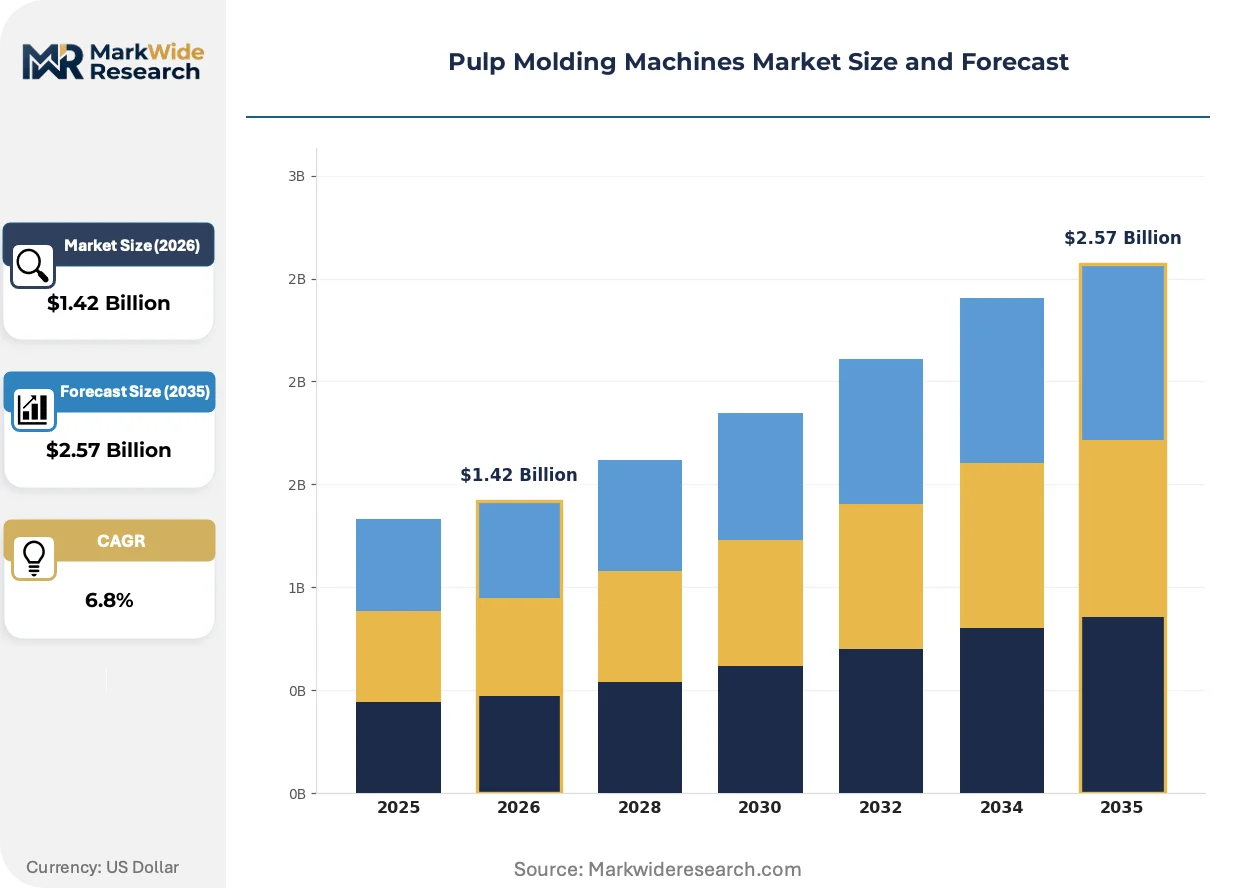
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Machine Type: Automatic, Semi-Automatic, Fully Automatic, Manual Technology: Vacuum Forming, Press Molding, Thermoforming, Injection Molding Application: Food Packaging, Electronics Packaging, Consumer Goods Packaging, Industrial Components End User Industry: Packaging Manufacturers, Electronics Suppliers, Food Processors, Industrial Fabricators |
| Companies Covered | DKM Machine Manufacturing Inc., Inmaco BV, BeSure Technology Co., Ltd., HGHY Pulp Molding Pack Co., Ltd., Brødrene Hartmann A/S, Sodaltech, Southern Pulp Machinery, Taiwan Pulp Moulding Co., Ltd., Beston Group Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pulp Molding Machines Market Strategic Shifts & Innovations
Automation and material science are advancing in parallel to meet regulatory demands for sustainable packaging. Innovation focuses on enhancing machine efficiency, expanding the range of processable fibers, and achieving properties that allow molded pulp to displace plastics in more demanding applications.
The integration of Industry 4.0 technologies like IoT sensors and predictive maintenance analytics is a key development. Large-scale packaging converters are adopting these systems to monitor slurry consistency, drying temperatures, and mechanical stress in real time. This digital oversight is bifurcating the market, separating high-throughput automated lines with data-driven process control from less efficient, manually-adjusted legacy equipment.
Mandates such as the EU's Corporate Sustainability Reporting Directive (CSRD) are creating new value drivers. This regulation requires large corporations to provide detailed disclosures on their supply chain's environmental impact, including packaging choices. Consequently, the electronics and consumer goods sectors are prioritizing machinery vendors who can deliver certified data on water and energy consumption per unit of output.
Sourcing strategies are diversifying beyond traditional recycled paper pulp. This shift toward a broader portfolio of agricultural fibers, including bagasse and wheat straw, disrupts established supply chains for raw materials. The trend is most visible in agricultural economies across Asia and South America, where machine vendors capable of handling these varied, often inconsistent, inputs gain a competitive advantage.
Pulp Molding Machines Market Segmentation
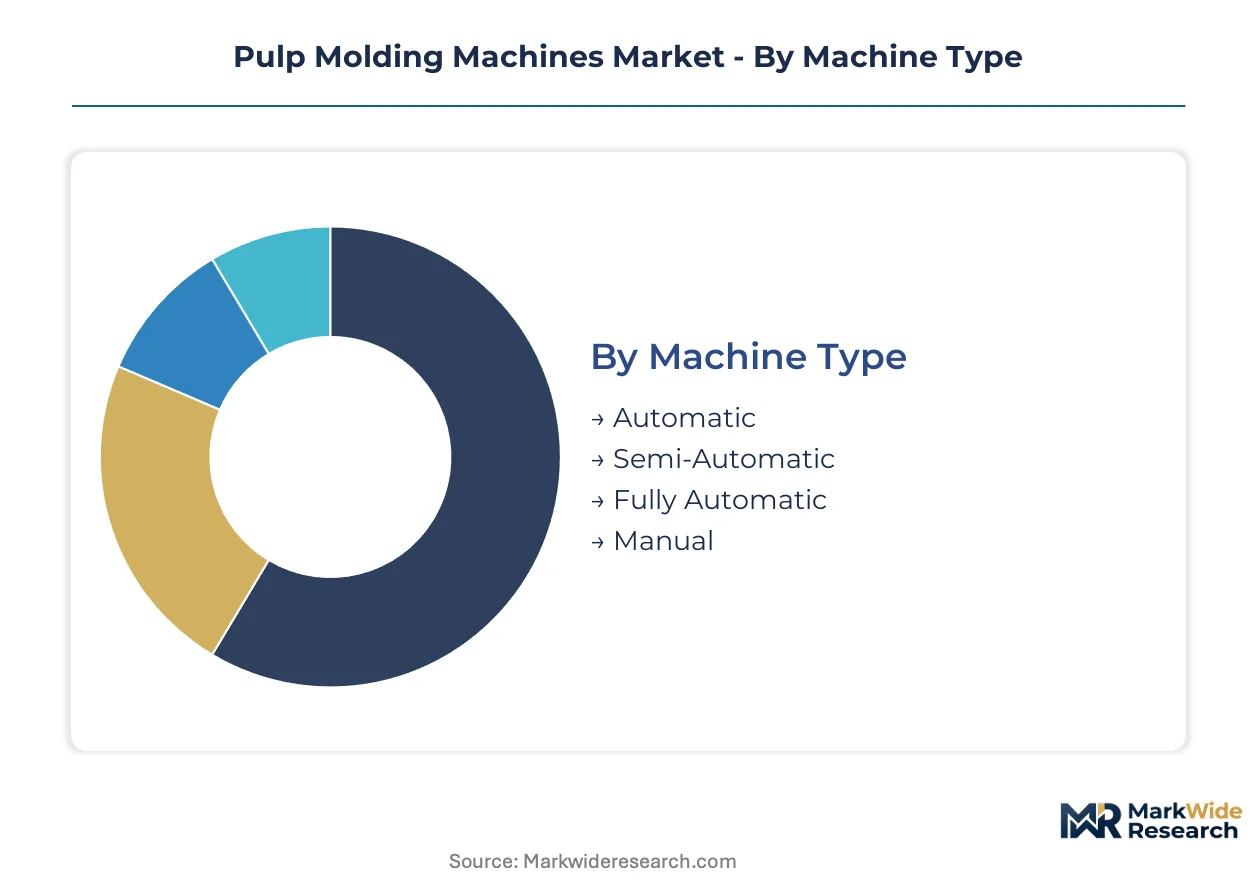
The pulp molding machines market segments across distinct categories, reflecting diverse operational needs and end-product specifications. Understanding these divisions helps stakeholders identify areas of concentrated demand, technological advancement, and strategic investment. Market segmentation clarifies where value accrues within the production chain, from raw material processing to final product delivery.
Machine Type:
The geographic spread of machine types often aligns with local labor costs and market maturity, with advanced economies favoring automated systems while developing regions may still utilize manual options for smaller-scale operations or niche products.
- Fully Automatic:These systems integrate pulp preparation, molding, drying, and stacking into a continuous, high-speed process, minimizing human intervention. Demand for fully automatic machines is concentrating in manufacturing centers like China and India to serve large-scale packaging manufacturers requiring consistent output for both domestic and export markets.
- Automatic:Automatic machines perform core molding and drying functions with automated controls, but may require manual loading or unloading steps. These machines are crucial for mid-sized packaging converters in regions like Southeast Asia, balancing efficiency with a more accessible capital investment compared to fully integrated systems.
- Semi-Automatic:Semi-automatic machines require significant operator involvement for loading, unloading, and process monitoring. These systems find utility in smaller production runs or for specialized product designs where flexibility is prioritized over sheer volume.
- Manual:Manual pulp molding machines are basic systems where most operations, including pulp feeding and product removal, are performed by hand. These machines are typically employed for very low-volume production or artisanal applications in localized markets.
Automatic machines command the established base. The steepest expansion runs through Fully Automatic systems.
Technology:
The choice of pulp molding technology often correlates with the desired density and surface finish of the final product, influencing both material costs and aesthetic appeal for consumer-facing goods.
- Vacuum Forming:This is the most common technology, drawing a pulp slurry onto a screen mesh mold using vacuum pressure, forming a fibrous layer. Vacuum forming is widely adopted by food packaging manufacturers for producing egg cartons and cup holders due to its efficiency and versatility with various pulp types.
- Press Molding:Press molding involves compressing the wet pulp against a heated mold, resulting in a denser, smoother, and more precise product. Electronics packaging manufacturers increasingly utilize press molding for custom inserts that require high shock absorption and a refined finish.
- Thermoforming:While primarily associated with plastics, thermoforming principles are adapted for pulp by using heat and pressure to shape pre-formed wet pulp sheets into complex designs. This technology offers enhanced structural integrity for premium consumer goods packaging.
- Injection Molding:Traditionally a plastic processing method, injection molding for pulp involves injecting a highly concentrated pulp slurry into a mold cavity under pressure. This method is explored for producing intricate pulp components with fine details, though it is less common than other pulp molding techniques.
Vacuum Forming technology holds the largest share. Press Molding is gaining share fastest due to its precision capabilities.
Application:
Application segments are differentiated by the specific functional requirements of the packaged goods, ranging from protective cushioning to food-grade hygiene standards.
- Food Packaging:This segment encompasses molded pulp products designed for direct and indirect contact with food items, such as egg cartons, fruit trays, and takeaway containers. Regulatory mandates like the EU Green Deal are compelling brand owners to transition their portfolios towards fiber-based food packaging.
- Electronics Packaging:Custom-engineered pulp solutions for electronics provide shock absorption and secure positioning for sensitive components during transit. This segment commands higher margins for manufacturers capable of producing high-density, precision-molded inserts.
- Consumer Goods Packaging:Molded pulp is utilized for packaging a wide array of non-food consumer products, including cosmetics, toiletries, and small household items. This application benefits from pulp's aesthetic appeal and sustainable branding opportunities.
- Industrial Components:This segment involves molded pulp used for protective packaging of industrial parts, tools, and automotive components. These solutions offer cost-effective cushioning and are often preferred for their recyclability in manufacturing supply chains.
Food Packaging represents the largest application volume. Electronics Packaging offers superior margin opportunities.
End User Industry:
End-user industries directly influence the scale and technical specifications of pulp molding machines, driven by their internal production volumes and specific product handling needs.
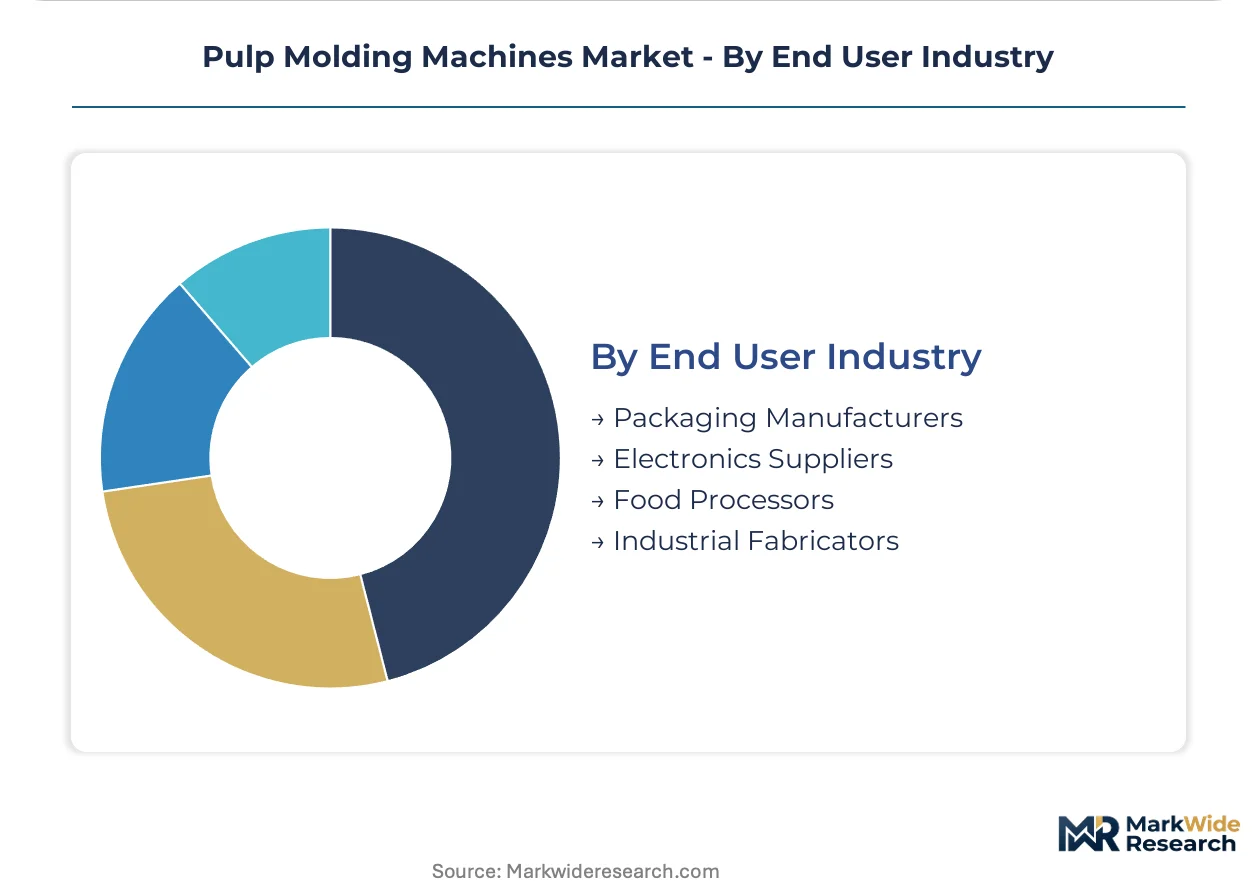
- Packaging Manufacturers:These companies operate dedicated facilities to produce a wide range of molded pulp packaging solutions for various clients across sectors. Packaging manufacturers are the primary purchasers of high-capacity, fully automatic pulp molding lines to meet diverse customer demands.
- Electronics Suppliers:Electronics suppliers integrate pulp molding machines into their supply chains to produce custom protective inserts for their sensitive products. These users prioritize precision, material compatibility with ESD requirements, and localized production capabilities.
- Food Processors:Food processors, including quick-service restaurants and grocery chains, increasingly adopt molded pulp machines to produce their own sustainable packaging on-site or through dedicated contract manufacturers. This shift is driven by consumer preference and regulatory pressures from bodies like the US FDA and Europe's EFSA regarding food-contact materials.
- Industrial Fabricators:Industrial fabricators use molded pulp for internal component protection or as part of their outbound logistics for manufactured goods. Their demand often centers on robust, cost-effective solutions for heavy or irregularly shaped items.
Packaging Manufacturers represent the largest purchasing segment. Food Processors are showing significant expansion in demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The pulp molding machines market exhibits a nuanced global trade dynamic, with certain regions emerging as net exporters of machinery while others drive significant import demand for packaging solutions. This export-import balance heavily influences localized manufacturing investments and technological adoption rates. Regional regulatory landscapes and raw material availability further shape market development.
China
China's pulp molding machine market experiences robust demand from its expansive food and electronics packaging sectors. The country's dual carbon goals and national plastic reduction policies drive fiber-based alternatives. Manufacturing clusters in the Yangtze River Delta are hubs for high-volume, fully automatic machine production.
India
India demonstrates increasing demand for pulp molding machines, fueled by its fast-growing consumer goods market and a national ban on single-use plastics. The Bureau of Indian Standards (BIS) promotes sustainable packaging materials. States like Maharashtra are seeing concentrated investments in machinery manufacturing and packaging conversion facilities.
United States
The United States market for pulp molding machines is characterized by a strong shift towards sustainable packaging solutions across quick-service restaurant and e-commerce sectors. US FDA food-contact material standards necessitate advanced machine hygiene. The Midwest is expanding capacity for molded fiber production to serve large CPG companies.
Germany
Germany's pulp molding machine segment is driven by stringent EU Green Deal regulations and a robust industrial manufacturing base. The Corporate Sustainability Reporting Directive (CSRD) compels detailed environmental disclosures. Bavaria houses advanced engineering firms developing high-precision, automated pulp molding technologies.
Brazil
Brazil offers significant opportunities for pulp molding machines, particularly with the commercial viability of bagasse and other agricultural fibers. Local regulations promoting sustainable forestry and waste valorization support this material diversification. The states of São Paulo are developing as key centers for both raw material supply and packaging manufacturing.
Pulp Molding Machines Market Key Industry Players
Listed leaders compete with private specialists across the full spectrum of pulp molding machine capabilities, from basic manual systems to advanced fully automatic lines. The market structure is tiered, with larger players focusing on integrated solutions for high-volume producers, while niche providers target custom applications. Companies are increasingly pursuing both technological innovation in advanced drying systems and strategic partnerships to expand their global footprint, particularly in emerging markets.
Specialists in custom-engineered solutions, DKM Machine Manufacturing Inc. exemplifies providers catering to high-margin niches like industrial components packaging. On the other hand, HGHY Pulp Molding Pack Co., Ltd., a China-based Co., Ltd., occupies a position among high-volume, scale-driven manufacturers, offering extensive technology for mass production. Brødrene Hartmann A/S, a Denmark-based A/S, anchors the integrated producer-user archetype, leveraging its dual role as both a machine supplier and a packaging producer.
| Leading Market Players |
|---|
| DKM Machine Manufacturing Inc. |
| Inmaco BV |
| BeSure Technology Co., Ltd. |
| HGHY Pulp Molding Pack Co., Ltd. |
| Brødrene Hartmann A/S |
| Sodaltech |
| Southern Pulp Machinery |
| Taiwan Pulp Moulding Co., Ltd. |
| Beston Group Co., Ltd. |
| Others |
Cost & Logistics Intelligence
The displacement of single-use plastics by fiber-based alternatives reshapes pulp molding machine supply chains and pricing economics. This shift concentrates manufacturing in Asian hubs like China and India, influencing global cost structures.
Pricing Analysis
Industrial OEM buyers anchor pricing that stratifies across premium, standard, and economy tiers. Price differentiation stems from customization levels for specialized applications and comprehensive after-sales service packages. Pricing softness runs through standard models due to increased competition from high-volume manufacturers in China. Small and medium-sized enterprises exhibit the highest price sensitivity, while large packaging manufacturers prioritize reliability and throughput.
Supply Chain Analysis
China and Germany anchor pulp molding machine manufacturing, with specialized components also sourced from Denmark. The production process relies on inputs such as recycled paper, bagasse, and specialized screen meshes. Commodity price volatility for non-wood fibers presents a structural supply chain risk. Distribution runs through direct sales channels to large packaging converters, supplemented by regional distributors for smaller-scale operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pulp molding machines market is experiencing a cyclical recovery, driven by intensifying regulatory pressure against single-use plastics. This structural shift stimulates new investment cycles in sustainable packaging production.
For Market Incumbents: Consolidate market position by acquiring niche technology firms specializing in advanced drying systems. Expand capacity in emerging markets like India to counter rising competition and localize production. Invest in R&D for enhanced barrier properties to mitigate the threat from advanced bio-based plastics. Secure critical certifications like US FDA food-contact material standards to maintain premium market access.
For New Entrants and Emerging Players: Unmet demand for small-batch custom solutions offers a significant entry point for new players. Target the semi-automatic machine segment for specialized industrial components packaging, where flexibility outweighs sheer volume. Focus on developing regional expertise in processing diverse agricultural fibers like bagasse. A go-to-market angle emphasizing localized technical support and flexible financing can attract underserved small and medium-sized converters.
For Investors and Strategic Acquirers: The market sits at a growth acceleration phase that favors technology-forward machine manufacturers. Long-term viability remains strong for the next decade, driven by sustained regulatory and consumer pressure for sustainable packaging. Target vertically integrated mid-cap specialists with strong IP in energy-efficient drying or non-wood fiber processing. Accelerated adoption of non-wood fiber inputs, particularly in Asia, serves as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in India | Increases manufacturing footprint to serve India's growing consumer goods market and plastic ban mandates. |
| R&D in Advanced Drying Systems | Reduces energy consumption, a major operational cost for packaging converters, enhancing machine efficiency. |
| Partnership for Non-Wood Fiber Sourcing | Secures diversified raw material supply, reducing dependency on volatile recycled paper markets. |
| Acquisition of Custom Mold Designer | Expands capabilities for high-margin electronics packaging, requiring precision-engineered solutions. |
| Certification for Food-Contact Materials | Ensures compliance with US FDA and EFSA standards, opening access to critical food packaging applications. |
Research Approach
A standing panel of packaging engineers, procurement managers, regulatory compliance officers, and machine operators provided ongoing calibration. This study combined extensive primary interviews with rigorous secondary validation from industry association reports, government environmental policies, company financial filings, and trade publications. Bottom-up and top-down triangulation ensured data consistency across all market segments.
Outputs were validated against external benchmarks and competitive intelligence to ensure analytical consistency. The analytical framework modeled market dynamics across the analysis window, segmenting by machine type, technology, application, end-user industry, and regional regulatory cluster. Compound Annual Growth Rates (CAGRs) derived from historical data analysis and projected market drivers. Key forecast inputs included plastic substitution rates and industrial production indices.
Forecasts assume regulatory continuity in the EU, US, and India; material policy shifts would require re-modeling. Energy price volatility and raw material supply disruptions represent specific risk factors. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Sliding Injection Molding Machine Market
Packaging Machinery
Face Mask Machines Market
Packaging Machinery
Soap Stamping Machine Market
Packaging Machinery
Lamination Systems Market
Packaging Machinery
Robotic Carton Loading Machine Market
Packaging Machinery
EPS Pre-Expander Machines Market
Packaging Machinery
Product Dispensing Machinery Market
Packaging Machinery
Lidding Machines Market
Packaging Machinery
Tray Sealing Machines Market
Packaging Machinery
Form-Fill-Seal Equipment Market
Packaging Machinery
Tamper Evidence Machinery Market
Packaging Machinery
Kitchen/ Toilet Roll Converting Machines Market
Packaging Machinery
Global Blow Molding Machine Market
Packaging Machinery
Auger Powder Filling Machines Market
Packaging Machinery
Packaging Conveyors Market
Packaging Machinery
Paper Napkin Converting Lines Market