
 Lidding Machines Market | 2026-2036
Lidding Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Lidding Machines Market Analytics
ISO 15378 certification for primary packaging materials is collapsing the supplier base for pharmaceutical-grade lidding equipment, forcing smaller fabricators toward contract assembly or exit. MULTIVAC Sepp Haggenmüller SE & Co. KG leverages its thermoforming-lidding integration to dominate high-throughput meat and dairy lines in Central Europe. GEA Group anchors pharmaceutical applications through aseptic sealing validation and cleanroom-compatible machine architectures. Delkor Systems, Inc. competes in North American retail-ready tray formats with servo-driven indexing systems that cut changeover intervals.
Lidding machines apply pre-cut or reel-fed substrates to trays, cups, or containers using heat, pressure, vacuum, or ambient sealing to create hermetic closures with oxygen transmission rates often specified below 0.1 cc per square meter per day. The equipment serves food preservation, pharmaceutical sterility maintenance, and electronics moisture barrier functions across automated packaging lines. Heat sealing occupies the largest installed base due to its compatibility with polyethylene and polypropylene tray structures, though vacuum sealing is gaining share in premium protein and modified-atmosphere produce applications where shelf-life extension justifies capital intensity. Composite materials including aluminum-plastic laminates concentrate margin pools because substrate suppliers and machine builders co-develop sealing profiles that lock in dual-source arrangements.
FDA food contact notification requirements and EU Regulation 1935/2004 on materials intended for food contact shape substrate selection and sealing temperature validation protocols for equipment sold into regulated markets. OSHA lockout-tagout standards and EU Machinery Directive 2006/42/EC compliance costs are widening the specification gap between entry-level Asian-built units and European-certified systems. Buyers must weigh total cost of ownership against regional regulatory exposure when sourcing lidding lines for multi-territory deployment.
Market Dynamics
Tray-sealing automation upgrades in dairy and ready-meal processing are compressing changeover windows and forcing machine builders to integrate vision systems and servo-driven indexing. FDA food contact material rules and EU packaging waste directives are simultaneously tightening substrate compliance requirements, collapsing the supplier base for pharmaceutical-grade equipment.
Growth Catalysts
- Modified-atmosphere packaging:Premium protein processors specify vacuum sealing for shelf-life extension above fifteen days, pulling capital toward high-barrier lidding lines.
- EU Green Deal packaging targets:The directive mandates recyclable or compostable substrates by 2030, accelerating equipment retrofits compatible with mono-material structures.
- China's dairy automation:Tray-sealing throughput targets in liquid milk and yogurt segments are expanding automated lidding line installations.
Market Restraints
- Aluminum laminate price volatility:Composite substrate costs swing with aluminum ingot and polymer resin indices, squeezing margin pools for mid-tier fabricators.
- German equipment concentration:High-throughput thermoforming-lidding integration capabilities cluster in Central European suppliers, creating single-source risk for buyers outside the region.
- Heat sealing temperature limits:Polyethylene and polypropylene tray structures cap sealing windows, restricting adoption in high-temperature sterilization applications.
Strategic Opportunities
- India pharmaceutical packaging:CDSCO serialization mandates and cold-chain expansion create white space for aseptic lidding validation in injectable and biologic formats.
- Reel-fed substrate convergence:Integration of laser scoring and easy-peel adhesion layers enables single-machine flexibility across cup, tray, and container formats.
- US retail-ready tray formats:Servo-driven indexing systems that cut changeover intervals below four minutes capture share in private-label protein and produce segments.
Industry Challenges
- ISO 15378 certification timelines:Pharmaceutical-grade validation protocols extend delivery schedules by eight to fourteen months, compressing working capital cycles for smaller fabricators.
- Cleanroom-compatible architecture integration:Aseptic sealing validation requires HEPA filtration and particle monitoring systems that conflict with legacy line layouts.
- Multi-territory compliance stacking:Buyers deploying across US, EU, and Asian markets must reconcile OSHA lockout-tagout, EU Machinery Directive 2006/42/EC, and divergent national electrical codes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lidding Machines Market |
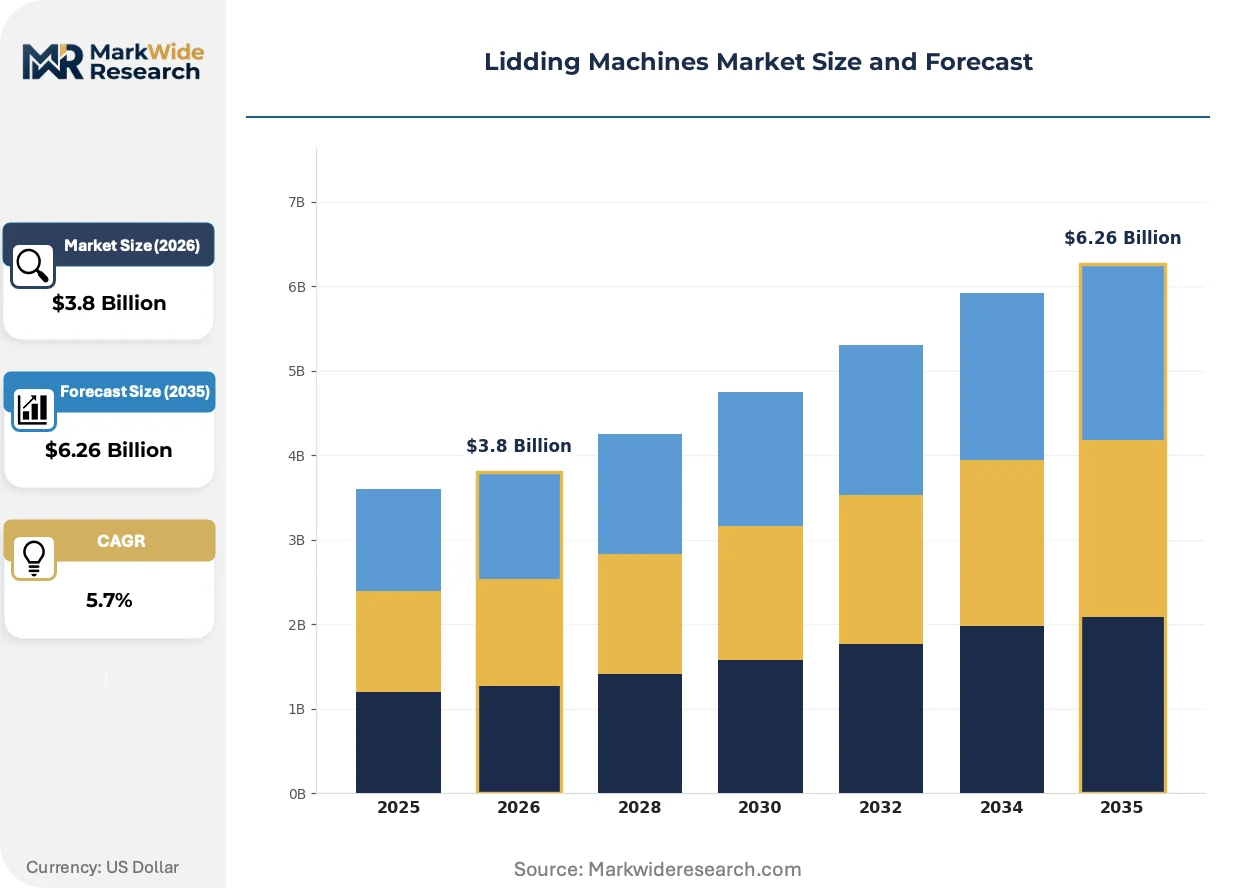
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heat Sealing, Pressure Sealing, Cold Sealing, Vacuum Sealing Material: Aluminum Foil, Plastic Films, Paperboard, Composite Materials Application: Food Packaging, Pharmaceuticals, Cosmetics, Electronics End User: Food Manufacturers, Pharmaceutical Companies, Cosmetic Brands, Electronics Suppliers |
| Companies Covered | MULTIVAC Sepp Haggenmüller SE & Co. KG, Delkor Systems, Inc., ILPRA S.p.A., GEA Group, Proseal America Inc., ULMA Packaging, ATP-Engineering & Packaging, S.L, Budé Group bv, Smurfit Kappa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lidding Machines Market Evolving Landscape
Active laser scoring and digital print integration are compressing substrate development cycles and enabling lot-level traceability. Machine builders now co-develop sealing profiles with material suppliers to lock in dual-source arrangements for oxygen transmission specifications below 0.1 cc per square meter per day.
Ultrasonic sealing technology is miniaturizing. The process uses high-frequency mechanical vibration to bond thermoplastics without thermal degradation, preserving barrier properties in thin-gauge films. Ready-meal processors in Germany and the United States are adopting it for mono-material tray structures at pilot scale. The technology is miniaturizing equipment footprints and displacing heated platen systems in cleanroom-constrained pharmaceutical lines.
EU Regulation 1935/2004 on materials intended for food contact is tightening migration testing protocols for sealing layers. Equipment sold into European markets now requires documented temperature validation across the full sealing jaw surface. Dairy and ready-meal segments face the steepest compliance costs, with substrate suppliers accelerating co-development timelines to secure dual-source machine builder partnerships.
Buyer consolidation among contract packers is compressing equipment specification cycles. Large dairy processors now demand modular lidding lines with sub-four-minute changeover intervals, unbundling after-sales service contracts from initial capital purchases. This pattern concentrates procurement leverage in Germany, China, and the United States, where tray-sealing automation upgrades are accelerating fastest.
Lidding Machines Market Segmentation
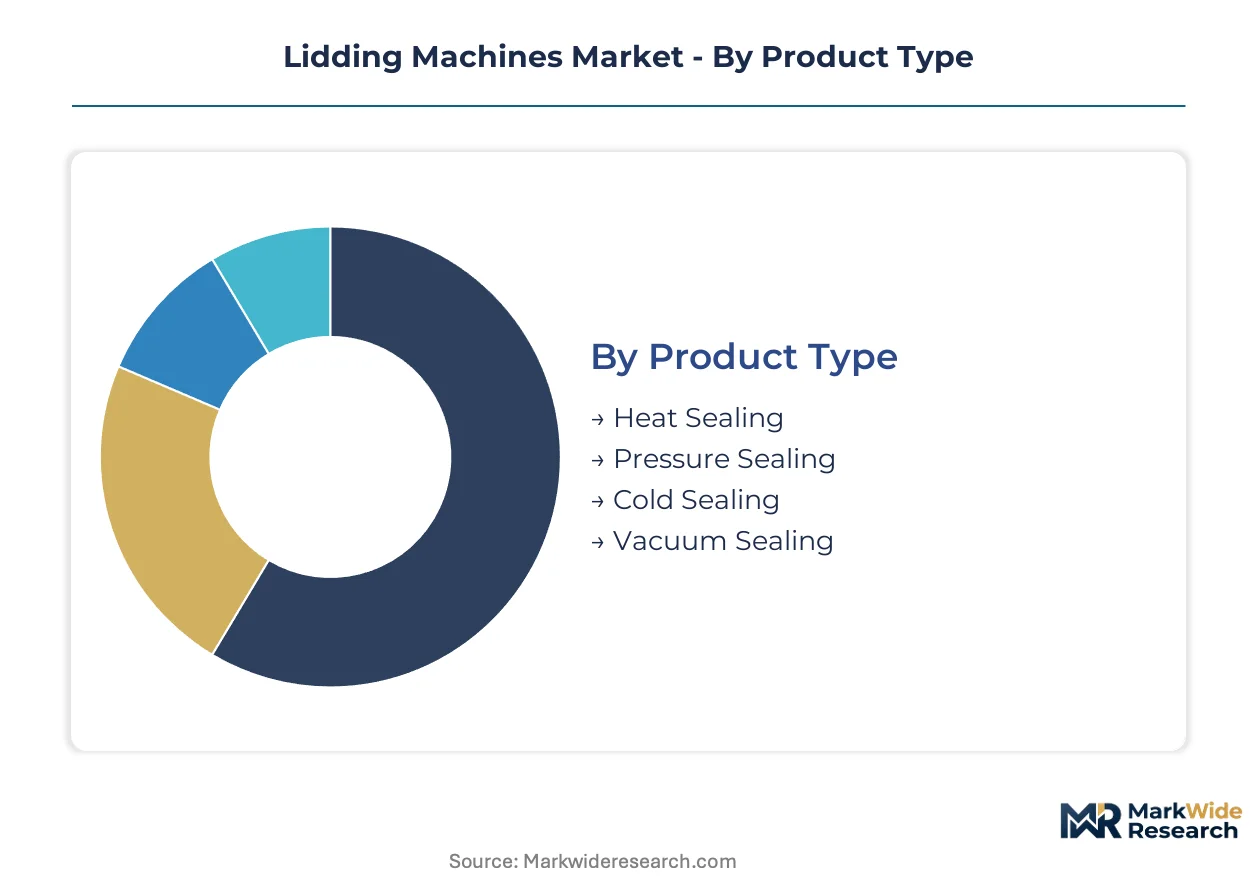
Lidding machine specifications diverge sharply across sealing technologies and substrate requirements. Equipment selection hinges on oxygen transmission targets, regulatory compliance tiers, and line integration complexity.
Product Type:
Channel flow splits between high-volume dairy and ready-meal lines demanding rapid indexing versus pharmaceutical cleanroom installations requiring validation documentation.
- Heat Sealing:Polyethylene and polypropylene tray structures bond through heated platens at controlled dwell times. Dairy processors in Germany and the United States specify heat sealing for yogurt and fresh cheese lines where throughput exceeds 200 units per minute.
- Vacuum Sealing:Chamber evacuation precedes heat bonding to achieve oxygen transmission below 0.1 cc per square meter per day. Premium protein processors in China deploy vacuum systems for shelf-life extension beyond fifteen days in modified-atmosphere formats.
- Pressure Sealing:Ambient-temperature bonding through mechanical compression suits heat-sensitive pharmaceutical blister packs.
- Cold Sealing:Adhesive-coated substrates activate at room temperature, preserving barrier properties in thin-gauge electronics moisture barriers.
Heat sealing dominates installed base. Vacuum sealing is where expansion concentrates.
Material:
Cost tiers stratify between commodity substrates and co-developed composite laminates locking in dual-source supply arrangements.
- Composite Materials:Aluminum-plastic laminates concentrate margin pools through proprietary sealing profiles developed jointly with machine builders. EU Green Deal packaging targets are accelerating equipment retrofits compatible with recyclable mono-material alternatives.
- Aluminum Foil:High-barrier metal layers deliver oxygen and moisture protection for pharmaceutical sterility maintenance. FDA food contact notification requirements shape substrate selection protocols for equipment sold into regulated markets.
- Plastic Films:Polyethylene terephthalate and polypropylene structures serve cost-sensitive food segments with shorter shelf-life requirements.
- Paperboard:Fiber-based lidding gains traction in ready-meal segments targeting compostable packaging mandates.
Composite materials command premium positioning. Aluminum foil anchors pharmaceutical-grade specifications.
Application:
Volume concentration tracks automation intensity across dairy, protein, and injectable packaging lines.
- Food Packaging:Tray-sealing automation upgrades in dairy and ready-meal processing compress changeover windows below four minutes. China's liquid milk and yogurt segments are expanding automated lidding line installations fastest.
- Pharmaceuticals:Aseptic sealing validation requires HEPA filtration and particle monitoring systems that conflict with legacy line layouts. CDSCO serialization mandates in India create white space for cold-chain lidding equipment.
- Cosmetics:Premium jar and tub formats demand precise torque control and tamper-evident sealing.
- Electronics:Moisture barrier bags for semiconductors specify ultra-low water vapor transmission rates through aluminum-composite structures.
Food packaging leads unit volume. Pharmaceuticals is climbing the fastest on compliance-driven replacement cycles.
End User:
Procurement leverage concentrates among contract packers unbundling after-sales service from capital purchases.
- Food Manufacturers:Large dairy processors demand modular lines with vision-integrated servo indexing. Tray-sealing throughput targets in Germany and the United States are accelerating automation upgrades.
- Pharmaceutical Companies:ISO 15378 certification timelines extend delivery schedules by eight to fourteen months, compressing working capital for equipment fabricators.
- Cosmetic Brands:Private-label packers specify quick-changeover formats for seasonal product rotations.
- Electronics Suppliers:Cleanroom-constrained lines favor miniaturized ultrasonic sealing displacing heated platen systems.
Food manufacturers anchor demand scale. Pharmaceutical companies concentrate margin through validation-intensive specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large dairy processors and contract packers concentrate procurement leverage in Germany, China, and the United States, where tray-sealing automation upgrades are accelerating fastest. Equipment specification cycles compress as buyers unbundle after-sales service from capital purchases. Regulatory divergence across FDA, EU, and CDSCO jurisdictions shapes substrate selection and validation protocols.
Germany
Thermoforming-lidding integration capabilities cluster in Central European suppliers serving meat and dairy lines. EU Machinery Directive 2006/42/EC compliance costs widen the specification gap between entry-level imports and certified systems. Bavaria anchors high-throughput equipment fabrication, with Stuttgart-area fabricators dominating servo-driven indexing exports.
China
Liquid milk and yogurt segments are expanding automated lidding line installations to meet throughput targets. SAMR food contact material standards and GB technical regulations tighten substrate compliance requirements. Yangtze River Delta dairy processors are deploying vacuum sealing systems for shelf-life extension beyond fifteen days.
United States
Retail-ready tray formats in private-label protein and produce segments demand sub-four-minute changeover intervals. FDA food contact notification requirements and OSHA lockout-tagout standards shape equipment validation protocols. Wisconsin and California dairy cooperatives are unbundling service contracts from capital purchases, compressing vendor margins.
India
CDSCO serialization mandates and cold-chain expansion create white space for aseptic lidding validation in injectable formats. FSSAI packaging regulations and PLI scheme incentives accelerate pharmaceutical-grade equipment adoption. Maharashtra and Gujarat pharmaceutical clusters are specifying HEPA-compatible cleanroom architectures for biologic packaging lines.
Japan
Premium protein processors specify vacuum sealing for modified-atmosphere packaging with ultra-low oxygen transmission rates. METI industrial automation subsidies and JIS standards compliance requirements favor equipment retrofits compatible with mono-material substrates. Osaka-area machinery distributors are consolidating procurement for electronics moisture barrier applications.
Lidding Machines Market Competitive Landscape
Player mix skews toward integrated thermoforming-lidding specialists and pharmaceutical-grade validation experts. The vendor base concentrates in Central European fabricators with dual-source substrate partnerships, while Asian entrants compete on entry-level heat sealing units. Two archetypes dominate: high-throughput dairy line integrators and cleanroom-constrained pharmaceutical specialists. Competitive moves center on co-development of proprietary sealing profiles and modular line architectures that compress changeover windows.
Among Germany-based fabricators, MULTIVAC Sepp Haggenmüller SE & Co. KG exemplifies the integrated thermoforming-lidding archetype, occupying a position in high-throughput meat and dairy automation. GEA Group represents the pharmaceutical-grade validation specialist, anchoring aseptic sealing and cleanroom-compatible machine architectures. Delkor Systems, Inc. sits within the North American retail-ready tray format segment, reflecting servo-driven indexing capabilities. These three companies illustrate the geographic and functional stratification that defines competitive positioning in lidding equipment supply.
| Leading Market Players |
|---|
| MULTIVAC Sepp Haggenmüller SE & Co. KG |
| Delkor Systems, Inc. |
| ILPRA S.p.A. |
| GEA Group |
| Proseal America Inc. |
| ULMA Packaging |
| ATP-Engineering & Packaging, S.L |
| Budé Group bv |
| Smurfit Kappa |
| Others |
Value Network & Pricing Analysis
Eight-to-fourteen-month ISO 15378 certification lead times compress working capital cycles for smaller fabricators while concentrating pricing power among Central European suppliers with established validation protocols. This lead-time band locks buyers into dual-source substrate partnerships that inflate equipment premiums and shield incumbent machine builders from entry-level Asian competition.
Pricing Analysis
Cost-plus contracts with aluminum ingot and polymer resin indexation dominate composite substrate procurement, exposing mid-tier fabricators to margin compression when commodity indices spike. Three-tier pricing structure across pharmaceutical-grade, food-grade, and entry-level equipment segments separates buyers by certification burden and cleanroom compatibility requirements. Pricing pressure stems from dairy processor unbundling of after-sales service contracts, which squeezes vendor margins on initial capital sales. Contract packers exhibit highest price sensitivity due to volume procurement leverage, while pharmaceutical companies accept premiums for validated aseptic architectures.
Supply Chain Analysis
Strait of Hormuz transit risk for aluminum ingot shipments from Gulf smelters concentrates raw material vulnerability for European laminate suppliers serving pharmaceutical-grade equipment lines. Component fabrication clusters in Germany, Italy, and China, with servo-drive systems and HEPA filtration modules drawing from Japanese and German precision engineering sources. Single-source vulnerability runs through Central European thermoforming-lidding integration specialists, where proprietary sealing profile co-development locks substrate suppliers into exclusive arrangements. Distribution runs through machinery distributors in Bavaria and the Yangtze River Delta, with aftermarket parts fulfillment anchored in regional service hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Validated cleanroom architecture expertise sits with fewer than a dozen fabrication groups globally, creating acute scarcity for buyers deploying across FDA, EU, and CDSCO jurisdictions simultaneously. This capability gap rewards early certification investment and punishes speculative entrants lacking regulatory navigation experience.
For Market Incumbents: Compound thermoforming-lidding integration advantages by securing exclusive substrate co-development partnerships that lock oxygen transmission specifications below competitor reach. Defend against ultrasonic sealing substitution by embedding digital print and laser scoring capabilities into modular line architectures. Prioritize capacity addition in the Yangtze River Delta to capture China's dairy automation wave before regional fabricators close the validation gap. For New Entrants and Emerging Players: Lead with aseptic lidding validation for India's CDSCO-mandated injectable and biologic formats, where cold-chain expansion outpaces incumbent service coverage. Target Maharashtra and Gujarat pharmaceutical clusters with HEPA-compatible cleanroom architectures priced below European certification premiums. Pursue joint development agreements with domestic substrate suppliers to circumvent dual-source lock-in arrangements. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial parent companies with under-monetized pharmaceutical-grade equipment divisions lacking ISO 15378 certification depth. Long-term viability hinges on regulatory navigation capabilities across converging FDA, EU, and Asian pharmaceutical packaging mandates. Monitor CDSCO serialization enforcement intensity as the inflection signal for Indian market acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Line Architecture Development | Sub-four-minute changeover intervals capture dairy processor procurement in Germany and Wisconsin. |
| Substrate Co-Development Partnership | Proprietary sealing profiles lock dual-source arrangements and defend oxygen transmission specifications. |
| Cleanroom Validation Investment | HEPA-compatible architectures open CDSCO-mandated injectable packaging in Maharashtra clusters. |
| Ultrasonic Sealing Pilot Scale | Miniaturized equipment footprints displace heated platen systems in cleanroom-constrained pharmaceutical lines. |
| Service Contract Unbundling Response | Aftermarket parts and remote diagnostics offset margin compression from capital sale unbundling. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with equipment fabricators, dairy procurement directors, pharmaceutical packaging engineers, and aftermarket service heads; and secondary validation against SEC filings of listed machinery groups, EU Machinery Directive compliance registries, and FDA food contact notification databases. Bottom-up triangulation across sealing technology installations and top-down reconciliation against regional automation expenditure patterns anchored volume and value estimates.
Across the analysis window, projections incorporated segmentation by sealing technology, substrate material tier, application vertical, and end-user procurement archetype. CAGRs derived from equipment replacement cycle analysis, regulatory compliance-driven upgrade intensity, and throughput expansion targets in liquid milk and injectable packaging. Model inputs included aluminum-plastic laminate price indices, ISO 15378 certification timeline distributions, and tray-sealing automation penetration rates by dairy processor scale tier.
The analysis sits within stated boundaries; outcomes outside sustained aluminum price stability, CDSCO enforcement continuity, or EU Green Deal packaging target adherence would require recalibration. Forecasts reflect documented assumptions regarding certification timeline compression and substrate supplier consolidation trajectories. Practitioners should keep alternative scenarios live as pharmaceutical serialization mandates and mono-material packaging transitions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Global Blister Packaging Machinery Market
Packaging Machinery
Lid Applicator Machine Market
Packaging Machinery
Cutter-Box Packaging Market
Packaging Machinery
Tray and Sleeve Packing Machines Market
Packaging Machinery
Extrusion Press Market
Packaging Machinery
Cigarette Packaging Machine Market
Packaging Machinery
Stretch Blow Molding Machines Market
Packaging Machinery
Bakery Packaging Machine Market
Packaging Machinery
Vial Filling and Capping Machines Market
Packaging Machinery
Foil Embossing Machine Market
Packaging Machinery
Polyester Strapping Machines Market
Packaging Machinery
Meal Tray Sealing Machines Market
Packaging Machinery
Pallet Strapping Machines Market
Packaging Machinery
Laminating Machines Market
Packaging Machinery
Liquid Capsule Filling Machines Market
Packaging Machinery
Liquid Filling Machines Market