
 Tray Sealing Machines Market | 2026-2036
Tray Sealing Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Tray Sealing Machines Market Outlook
Automation in sealing mechanics is tilting tray packaging from pneumatic to servo-driven motion control, cutting changeover times and film waste. MULTIVAC leverages its in-house tooling division to supply complete lines from thermoforming to final seal. Ilpra anchors its position in modified atmosphere packaging through proprietary gas-flushing architectures. Omori Machinery dominates high-speed rotary sealers for Japanese convenience store chains.
Tray sealing machines apply heat and pressure to bond lidding film to pre-formed trays, typically operating at temperatures between 120°C and 200°C with seal dwell times of 0.5 to 3 seconds depending on material gauge. The equipment serves food preservation, pharmaceutical sterility maintenance, and electronics moisture barrier functions across manufacturing and distribution chains. Automatic systems command the largest installed base but robotic loading cells represent the fastest expansion path as labor costs rise in European protein processing plants. Vacuum sealing retains the deepest margin pool among application types due to precision pump requirements and aftermarket service contracts.
FDA food contact notification rules and EU MDR material traceability standards shape machine specifications on both sides of the Atlantic, forcing builders to document every heated surface alloy and lubricant grade. Japan's METI energy efficiency benchmarks push OEMs toward regenerative servo drives and standby power reduction below 0.5 kW. Stakeholders must weigh capital deployment between fully integrated lines and modular retrofits as sustainability reporting obligations from CSRD expand to cover packaging equipment carbon footprints.
Market Dynamics
Servo-driven motion control is displacing pneumatic sealing mechanics across automated tray lines, compressing changeover windows from hours to minutes while slashing film waste rates. This mechanical transition concentrates investment among protein processors and ready-meal manufacturers seeking OEE gains.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants is forcing cold chain operators to adopt hermetic tray seals that extend shelf life without temperature abuse, directly lifting vacuum sealing system demand.
- Fresh food retail chains:German, Japanese, and American supermarket operators are expanding modified atmosphere packaging lines to reduce spoilage losses in premium protein and produce categories.
- Gas-flushing architectures:Proprietary nitrogen-CO2 mixture systems now enable sub-1% residual oxygen levels in sealed trays, unlocking week-long shelf stability for sliced deli meats.
Market Restraints
- Stainless steel alloy volatility:Grade 316L price swings for heated sealing platens and tooling frames compress OEM margins during contract negotiation windows.
- Precision pump supply concentration:Dry vacuum pump manufacturing clusters in southern Germany create single-source vulnerability for high-throughput sealing systems.
- Seal integrity validation limits:Current non-destructive testing methods cannot reliably detect micro-leaks below 10 microns in lidding film welds.
Strategic Opportunities
- Robotic loading cells:European protein processing plants facing labor cost escalation represent immediate retrofit demand for automated tray infeed systems.
- CSRD carbon footprint reporting:The EU Corporate Sustainability Reporting Directive mandates equipment-level emissions disclosure, creating aftermarket service contracts for energy audits and servo drive upgrades.
- Pharmaceutical sterility maintenance:Aseptic tray sealing for biologic drug delivery devices remains underpenetrated versus food applications, with barrier validation protocols now converging with ISO 15378 standards.
Industry Challenges
- Multi-material compatibility engineering:Operators struggle to calibrate heat-pressure profiles across shifting substrate combinations—rPET trays with bio-based lidding films, aluminum foil hybrids, and paperboard alternatives.
- FDA food contact notification timelines:Heated surface alloy documentation and lubricant grade traceability requirements extend machine qualification periods by four to eight months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tray Sealing Machines Market |
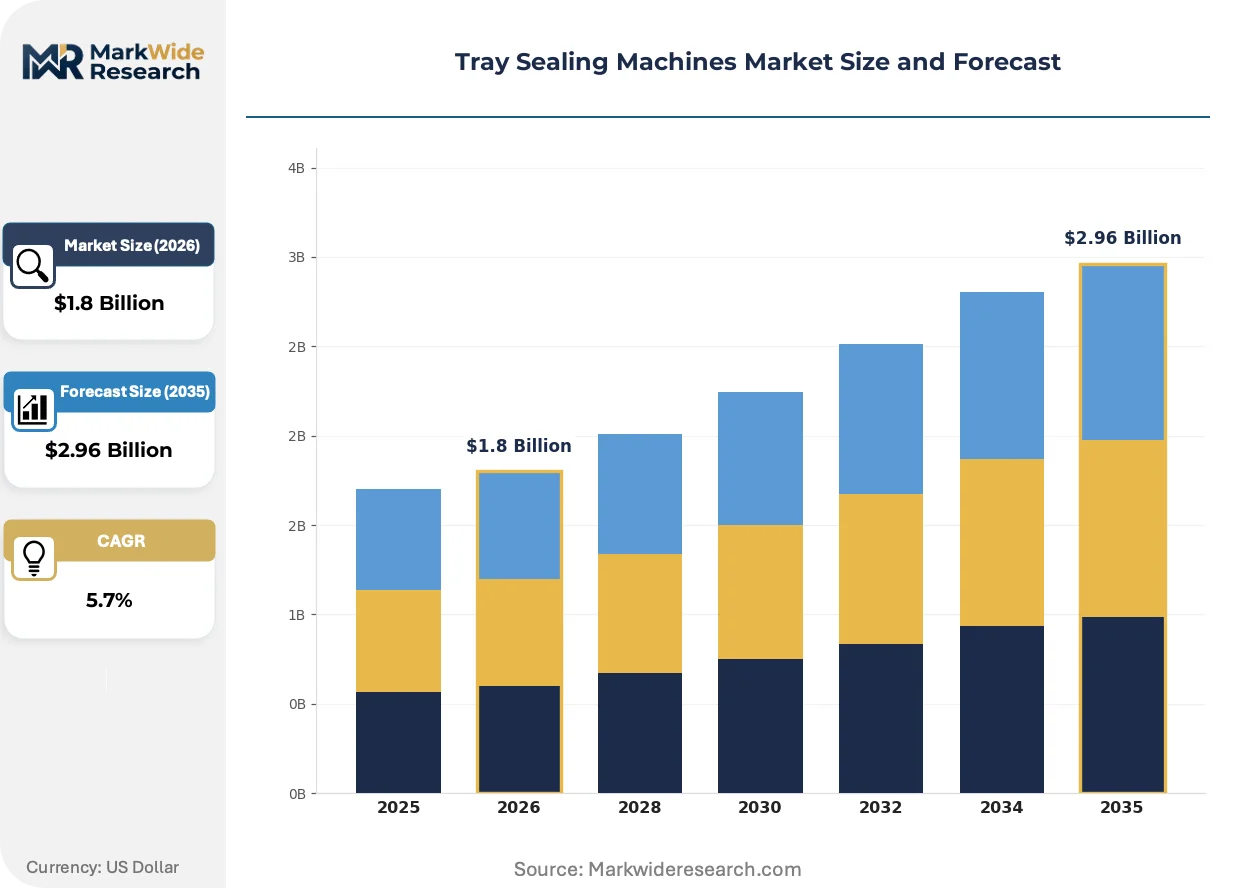
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Machine Type: Automatic, Semi-Automatic, Manual, Robotic End User: Food Packaging, Pharmaceutical, Electronics, Cosmetics Material: Plastic, Aluminum, Paper, Composite Application: Vacuum Sealing, Skin Packaging, MAP, Retort |
| Companies Covered | MULTIVAC, Ilpra, Webomatic, Omori Machinery, ISHIDA CO., LTD., Ossid, Packaging Automation, ULMA Packaging, Proseal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tray Sealing Machines Market Strategic Shifts
Digital thread integration across sealing lines is compressing quality feedback loops from hours to seconds. Equipment builders now embed sensor networks that correlate seal temperature, pressure, and dwell time against downstream leak detection results.
Machine vision inspection is digitizing quality assurance protocols in high-speed rotary sealers. Japanese convenience store suppliers deploy multi-camera arrays that capture 100% of seal perimeter images at 300 trays per minute. The resulting data streams enable predictive maintenance on heated tool stations before deviation thresholds trigger rejects.
Japan's METI energy efficiency benchmarks are forcing regenerative servo drive adoption across OEM product lines. Standby power consumption must now fall below 0.5 kW, compelling redesigns of heating element insulation and control system sleep states. Korean and Taiwanese contract manufacturers are responding fastest, shipping compliant architectures six months ahead of EU equivalents.
Aftermarket service unbundling is fragmenting traditional maintenance contracts. Protein processors in the US and Germany now purchase vacuum pump overhauls, heated platen replacements, and software upgrades through separate vendor channels rather than single-source OEM agreements. This disaggregation pressures original equipment margins while opening independent service provider entry points.
Tray Sealing Machines Market Segmentation
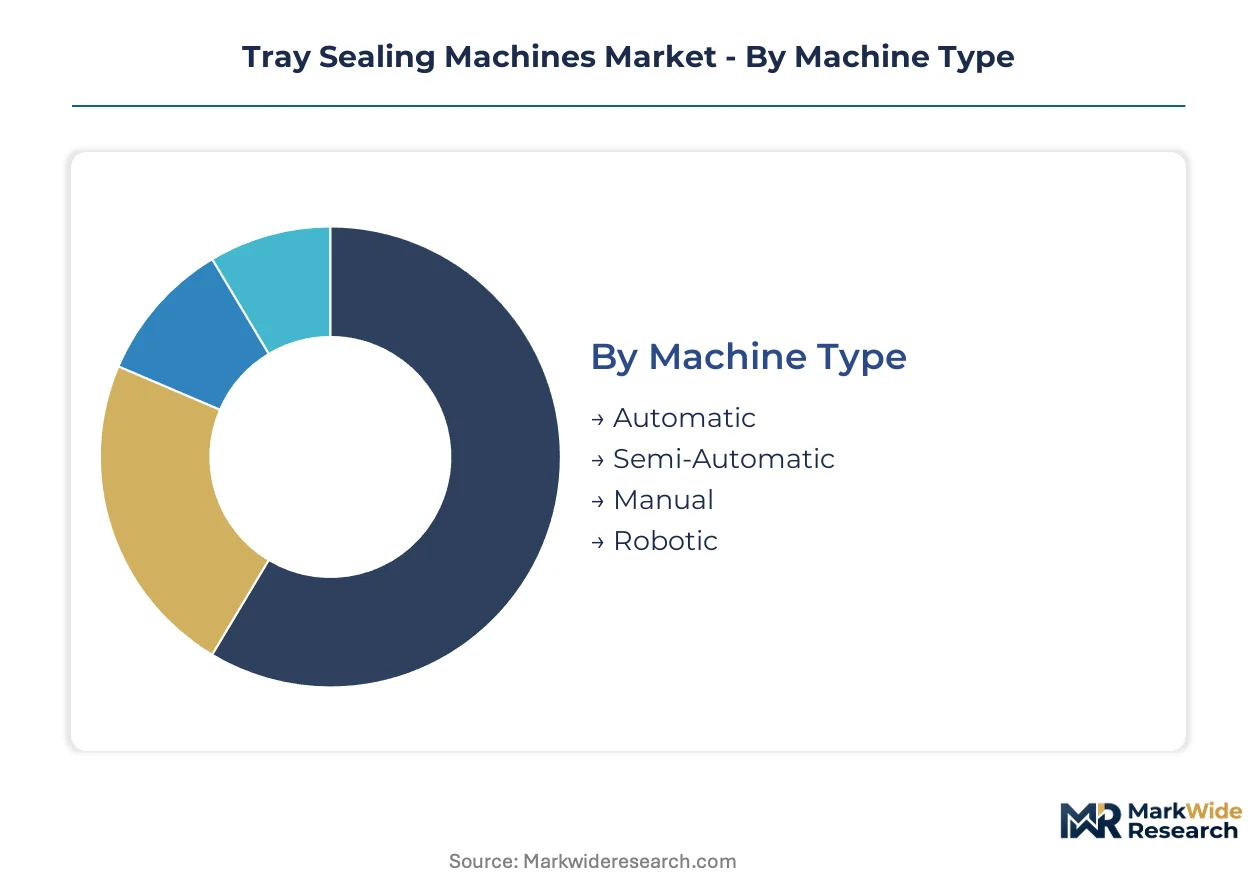
Tray sealing machines serve divergent operational requirements across protein processing, pharmaceutical sterility, and electronics moisture protection. Segmentation reveals where capital deployment concentrates and which technology transitions offer margin expansion.
Machine Type:
Automation intensity separates equipment tiers by throughput, changeover speed, and labor substitution economics.
- Automatic:Servo-driven systems dominate high-volume protein and ready-meal lines, compressing changeover windows from hours to minutes while slashing film waste. German and US fresh food retail chains deploy these for modified atmosphere packaging at 150-300 trays per minute.
- Robotic:Automated loading cells address labor cost escalation in European protein processing plants, representing the steepest expansion path as retrofit demand accelerates. Vision-guided pick-and-place modules integrate with existing seal stations.
- Semi-Automatic:Mid-scale processors balance throughput with operator oversight for batch-flexible operations.
- Manual:Entry-level benchtop units serve artisan food producers and pilot-scale pharmaceutical runs.
Automatic systems command the established base. The steepest expansion runs through Robotic.
End User:
Regulatory stringency and shelf-life requirements fragment demand across contamination-sensitive industries.
- Food Packaging:Modified atmosphere and vacuum sealing for protein, produce, and ready-to-eat meals consumes the largest equipment volume. EU F-Gas Regulation is forcing cold chain operators toward hermetic seals that extend shelf life without temperature abuse.
- Pharmaceutical:Aseptic tray sealing for biologic drug delivery devices remains underpenetrated versus food applications, with barrier validation protocols converging with ISO 15378 standards.
- Electronics:Moisture barrier protection for semiconductors and sensitive components drives precision heat-pressure calibration.
- Cosmetics:Premium skincare and fragrance sampling trays demand aesthetic seal quality with minimal material distortion.
Food Packaging anchors installed capacity. Pharmaceutical offers the deepest margin expansion trajectory.
Material:
Substrate compatibility determines heat-pressure profile engineering and tooling changeover complexity.
- Plastic:rPET and polypropylene trays dominate fresh protein and produce applications, with bio-based lidding films forcing recalibration of seal temperature windows.
- Aluminum:Foil hybrids and pure aluminum trays serve retort applications and pharmaceutical barrier requirements where oxygen and light exclusion are critical.
- Paper:Fiber-based alternatives are gaining traction in European sustainability-driven retail chains, demanding modified platen surfaces to prevent fiber adhesion.
- Composite:Multi-layer structures combining plastic barrier layers with paper or aluminum substrates maximize shelf life in premium categories.
Plastic retains the broadest installed base. Paper is climbing the fastest on sustainability mandates.
Application:
Atmosphere control sophistication separates commodity sealing from precision preservation systems.
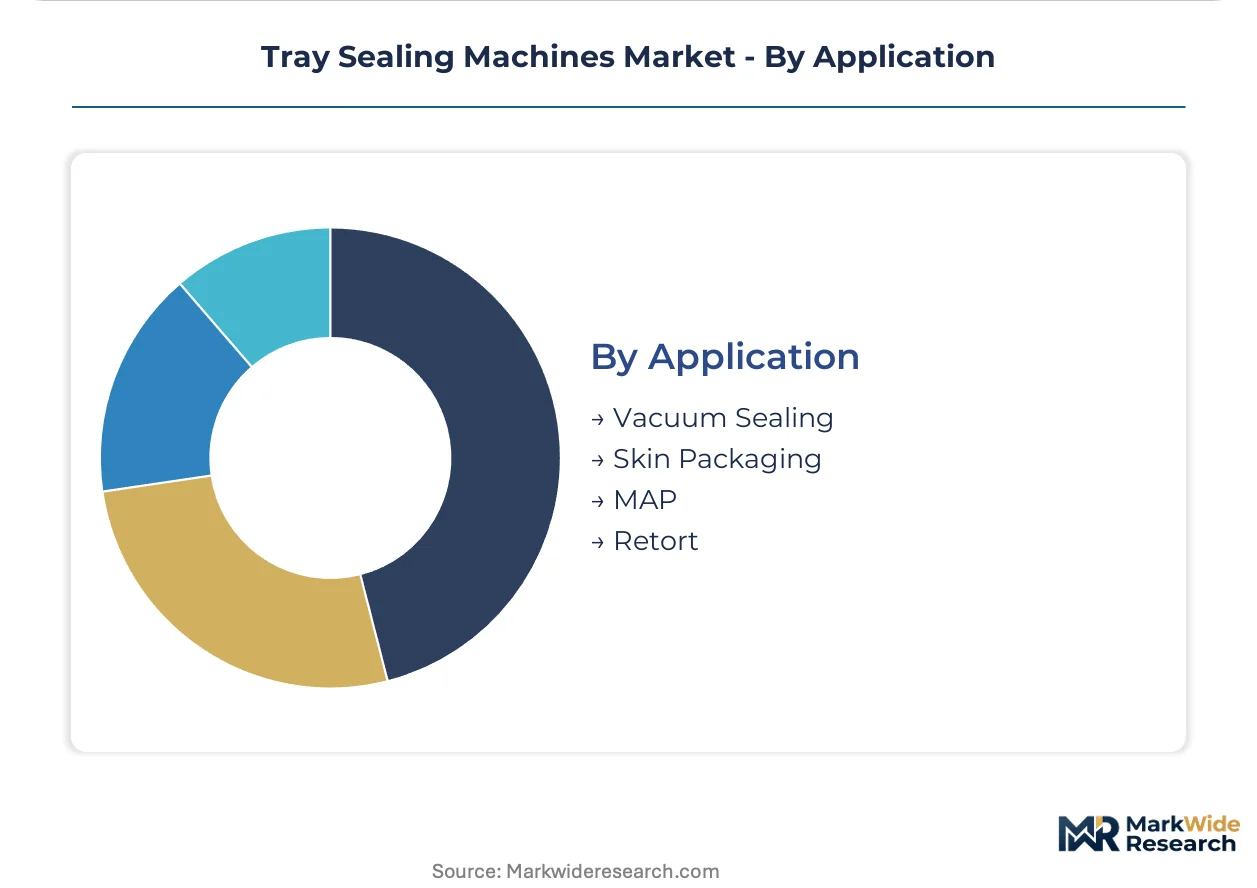
- Vacuum Sealing:Precision dry vacuum pump requirements and aftermarket service contracts generate the deepest margin pool. Protein processors in Germany and the United States specify sub-1% residual oxygen for extended shelf stability.
- MAP (Modified Atmosphere Packaging):Proprietary nitrogen-CO2 mixture systems enable week-long shelf stability for sliced deli meats. Japanese convenience store chains deploy high-speed rotary sealers with integrated gas-flushing architectures.
- Skin Packaging:Film conforming tightly to product contours maximizes retail presentation for premium proteins and seafood.
- Retort:High-temperature sterilization compatibility requires specialized seal integrity for shelf-stable meals and pharmaceutical preparations.
Vacuum Sealing holds the premium revenue concentration. MAP is gaining share fastest on fresh retail chain expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German OEMs export servo-driven sealing systems to protein processors across the United States and Japan, while Japanese manufacturers supply high-speed rotary sealers to convenience store chains throughout East Asia. This trade-flow corridor shapes regional equipment specifications and regulatory compliance requirements.
United States
Fresh food retail chains in California and the Midwest are expanding modified atmosphere packaging lines for premium protein categories. FDA food contact notification rules extend machine qualification periods by documenting heated surface alloys and lubricant grades. Chicago-area processing plants deploy automated vacuum sealing systems to meet cold chain shelf-life demands.
Germany
Protein processors in Bavaria and North Rhine-Westphalia specify sub-1% residual oxygen levels for extended shelf stability. EU F-Gas Regulation phases down hydrofluorocarbon refrigerants, forcing operators toward hermetic tray seals. Stuttgart and Munich host concentrated clusters of dry vacuum pump suppliers serving high-throughput sealing system builders.
Japan
Convenience store chains in Tokyo and Osaka deploy high-speed rotary sealers at 300 trays per minute. METI energy efficiency benchmarks mandate regenerative servo drives and standby power below 0.5 kW. Nagoya-area machinery builders dominate gas-flushing architectures for nitrogen-CO2 mixture systems.
China
Domestic food processors in Shanghai and Guangzhou retrofit semi-automatic lines with servo-driven motion control. The country's national packaging equipment standards emphasize energy consumption metrics alongside seal integrity validation. Shenzhen contract manufacturers ship METI-compliant architectures six months ahead of European equivalents.
India
Mid-scale processors in Maharashtra and Gujarat balance throughput with batch-flexible operations using semi-automatic systems. FSSAI food safety regulations tighten seal integrity documentation for dairy and ready-to-eat categories. Ahmedabad and Mumbai host emerging clusters of independent service providers unbundling aftermarket maintenance contracts.
Tray Sealing Machines Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base organizes around three strategic archetypes: integrated line builders with captive tooling divisions, MAP technology specialists with proprietary gas-flushing architectures, and high-speed rotary sealer manufacturers serving convenience store supply chains. Dominant competitive moves include backward integration into heated platen manufacturing and strategic partnerships for robotic loading cell distribution.
Within the integrated-line-builder archetype, MULTIVAC exemplifies channel control through in-house tooling supply from thermoforming to final seal. Ilpra occupies a position among MAP specialists, representing proprietary gas-flushing expertise. Omori Machinery anchors the high-speed rotary segment, exemplifying Japanese precision engineering for convenience store chain requirements.
| Leading Market Players |
|---|
| MULTIVAC |
| Ilpra |
| Webomatic |
| Omori Machinery |
| ISHIDA CO., LTD. |
| Ossid |
| Packaging Automation |
| ULMA Packaging |
| Proseal |
| Others |
Value Chain & Pricing Dynamics
The Hamburg-Rotterdam container corridor channels servo drive and heated platen components from southern Germany to OEM assembly plants, with freight cost volatility amplifying price spreads between integrated line builders and modular retrofit suppliers while compressing margins for stainless steel-dependent tooling fabricators.
Pricing Analysis
Servo-driven sealing systems command 40-60% premiums over pneumatic equivalents, while next-generation regenerative drive architectures with sub-0.5 kW standby power carry additional certification premiums. Pricing stratifies across premium, standard, and economy tiers based on automation intensity and METI compliance status. Cost compression in mid-tier equipment is intensifying as Korean contract manufacturers scale METI-compliant production. Protein processors in Germany exhibit lowest price sensitivity due to F-Gas Regulation compliance deadlines, while Indian mid-scale processors prioritize capital efficiency over feature depth.
Supply Chain Analysis
German export-control restrictions on precision motion control components limit servo drive flows to certain Asian contract manufacturers, forcing supply chain reconfigurations. Manufacturing clusters concentrate in Germany, Japan, and South Korea for high-throughput systems, with China scaling rapidly in mid-tier servo retrofits. Critical inputs include Grade 316L stainless steel for heated platens, dry vacuum pumps from Bavarian suppliers, and regenerative drive controllers. Single-source vulnerability in southern German vacuum pump manufacturing creates supply chain risk. Distribution runs through OEM direct sales for integrated lines and independent service providers for aftermarket unbundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tray sealing equipment penetration remains below saturation across pharmaceutical aseptic applications and emerging Asian protein processing markets, with regulatory tailwinds from EU F-Gas phases and CSRD carbon disclosure mandates accelerating replacement cycles.
For Market Incumbents: Harden aftermarket revenue streams against independent service provider encroachment by bundling predictive maintenance software with heated platen replacement contracts. Deepen backward integration into vacuum pump refurbishment capabilities to capture margin pools currently leaking to third-party channels.
For New Entrants and Emerging Players: Build out robotic loading cell integration expertise targeting European protein processors facing labor cost escalation and retrofit demand. The pharmaceutical aseptic segment offers lowest competitive density relative to food packaging saturation; pursue ISO 15378 certification partnerships as entry credential.
For Investors and Strategic Acquirers: EU F-Gas Regulation reshapes the acquisition landscape toward hermetic seal technology specialists and gas-flushing architecture owners. Five-to-ten year viability favors targets with proprietary nitrogen-CO2 mixture IP and established pharmaceutical validation protocols. Monitor dry vacuum pump supply consolidation in southern Germany as inflection signal for upstream margin capture opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Servo Drive Retrofit Programs | Converts installed pneumatic base to METI-compliant architectures, extending asset life for EU protein processors. |
| Proprietary Gas-Flushing Development | Sub-1% residual oxygen systems unlock week-long shelf stability for premium deli meat categories. |
| Robotic Loading Cell Integration | Vision-guided pick-and-place modules address labor cost escalation in Bavarian and North Rhine-Westphalia plants. |
| Aftermarket Service Unbundling | Separate vacuum pump overhaul and software upgrade channels pressure OEM margins while opening independent entry points. |
| Pharmaceutical Barrier Validation | ISO 15378 convergence for biologic drug delivery devices expands addressable market beyond food applications. |
Study Parameters
A standing panel of plant engineers at protein processing facilities, OEM procurement directors, aftermarket service heads, and regulatory compliance officers provided ongoing calibration against secondary validation from FDA food contact notification databases, EU MDR material traceability filings, METI energy efficiency benchmark disclosures, and trade flow records through Hamburg-Rotterdam corridors. Bottom-up equipment shipment tallies triangulated against top-down protein processing capacity expansion announcements.
Scenario-bracketing framed demand projections across the analysis window, modeling machine type automation intensity, end-user regulatory stringency tiers, material substrate compatibility requirements, and application atmosphere control sophistication. CAGRs derived from segment-level adoption curves weighted by replacement cycle timing and capital expenditure pipeline visibility from fresh food retail chain expansion announcements and pharmaceutical sterility maintenance investment disclosures.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Asian contract manufacturers into European premium segments would shift outcomes. Material shifts in EU F-Gas Regulation enforcement intensity or Grade 316L stainless steel alloy pricing volatility would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Vacuum Chamber Packaging Machines Market
Packaging Machinery
Oil Packing Machine Market
Packaging Machinery
Cosmetic Filling Machines Market
Packaging Machinery
Tablet Packing Machine Market
Packaging Machinery
Flow Wrap Machines Market
Packaging Machinery
Piston Fillers Market
Packaging Machinery
Vacuum Sealing Machine Market
Packaging Machinery
Pouch Packaging Machine Market
Packaging Machinery
Tray Former Machines Market
Packaging Machinery
Cup Filling Machine Market
Packaging Machinery
Labeling Machines Market
Packaging Machinery
Horizontal Flow Wrapping Machines Market
Packaging Machinery
Bakery Packaging Machine Market
Packaging Machinery
Hardgel Liquid Capsule Filling Machines Market
Packaging Machinery
Automated Poly Bagging Machines Market
Packaging Machinery
Meal Tray Sealing Machines Market