
 Packaging Conveyors Market | 2026-2036
Packaging Conveyors Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Conveyors Market Analytics
Skilled conveyor technicians is unwinding capacity expansion at mid-tier OEMs across the sector. Dorner Mfg. Corp. leverages its modular platform architecture to serve cleanroom and washdown environments. Multi-Conveyor, LLC anchors its position through extensive custom engineering capabilities for complex product handling. mk Technology Group specializes in aluminum-frame precision conveyors for lightweight packaging applications.
Packaging conveyors are material handling systems engineered to transport, accumulate, orient, and stage packaged goods through production and distribution workflows, typically constructed from aluminum extrusion, stainless steel, or polymer composite frames with belt pitches ranging from 12.7 mm to 50.8 mm depending on load and speed requirements. Their primary purpose is to synchronize filling, sealing, labeling, and case-packing operations while minimizing manual touchpoints and product damage. Modular belt conveyors command the largest installed base due to their repairability and open-hinge designs that tolerate caustic washdowns in dairy and meat plants. Automated technology segments are capturing disproportionate capital allocation as warehouse labor costs climb and order profiles fragment toward e-commerce batch sizes. Roller bed conveyors retain dominance in distribution center outbound lanes where carton weights and throughput velocities favor low-friction, high-load designs.
FDA food contact surface regulations and EU Machinery Directive 2006/42/EC compliance requirements are elevating stainless steel specification rates and mandating traceable component sourcing for export-bound equipment. ISO 22000 and HACCP alignment now function as baseline qualifiers for vendor selection in North American and European food processing procurement. Stakeholders must monitor how CE marking evolution under the EU Green Deal intersects with embedded carbon disclosure rules for capital equipment.
Market Dynamics
Food and beverage automation mandates are compressing replacement cycles for legacy belt systems while elevating stainless steel specifications across dairy, meat, and ready-meal processing lines. Equipment buyers now treat hygienic design as a non-negotiable procurement filter rather than a premium upgrade.
Growth Catalysts
- EU Machinery Directive 2006/42/EC:CE marking requirements for traceable component sourcing are accelerating modular conveyor adoption in export-bound European food plants.
- Aluminum extrusion frames:Lightweight precision conveyors are capturing pharmaceutical and cosmetic packaging lines where floor load limits constrain heavier steel alternatives.
- Stuttgart-Cologne corridor:Dense clustering of packaging machinery OEMs in southwestern Germany is creating localized supplier ecosystems that shorten delivery lead times.
Market Restraints
- Stainless steel price volatility:Raw material cost swings for 304 and 316 grades are compressing margin buffers for mid-tier equipment fabricators.
- Skilled technician scarcity:Conveyor system commissioning and maintenance expertise is concentrating at top-tier OEMs, constraining capacity expansion.
- Legacy roller bed substitution:Established distribution center outbound lanes resist modular belt conversion due to high-load, low-friction performance requirements.
Strategic Opportunities
- Cleanroom specifications:Semiconductor and medical device packaging lines in South Korea and Taiwan are creating demand for washdown-rated precision conveyors.
- EU Green Deal carbon disclosure:Embedded emissions reporting requirements for capital equipment are opening premium positioning for low-carbon aluminum frame suppliers.
- E-commerce batch fragmentation:Warehouse automation for small-parcel sortation is driving interest in narrow-pitch modular belts with accumulation capability.
Industry Challenges
- ISO 22000 certification timelines:Third-party food safety audits for conveyor component suppliers are extending vendor qualification cycles by four to eight months.
- HACCP alignment complexity:Integrating open-hinge belt designs with existing CIP systems requires custom engineering that strains OEM technical resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging Conveyors Market |
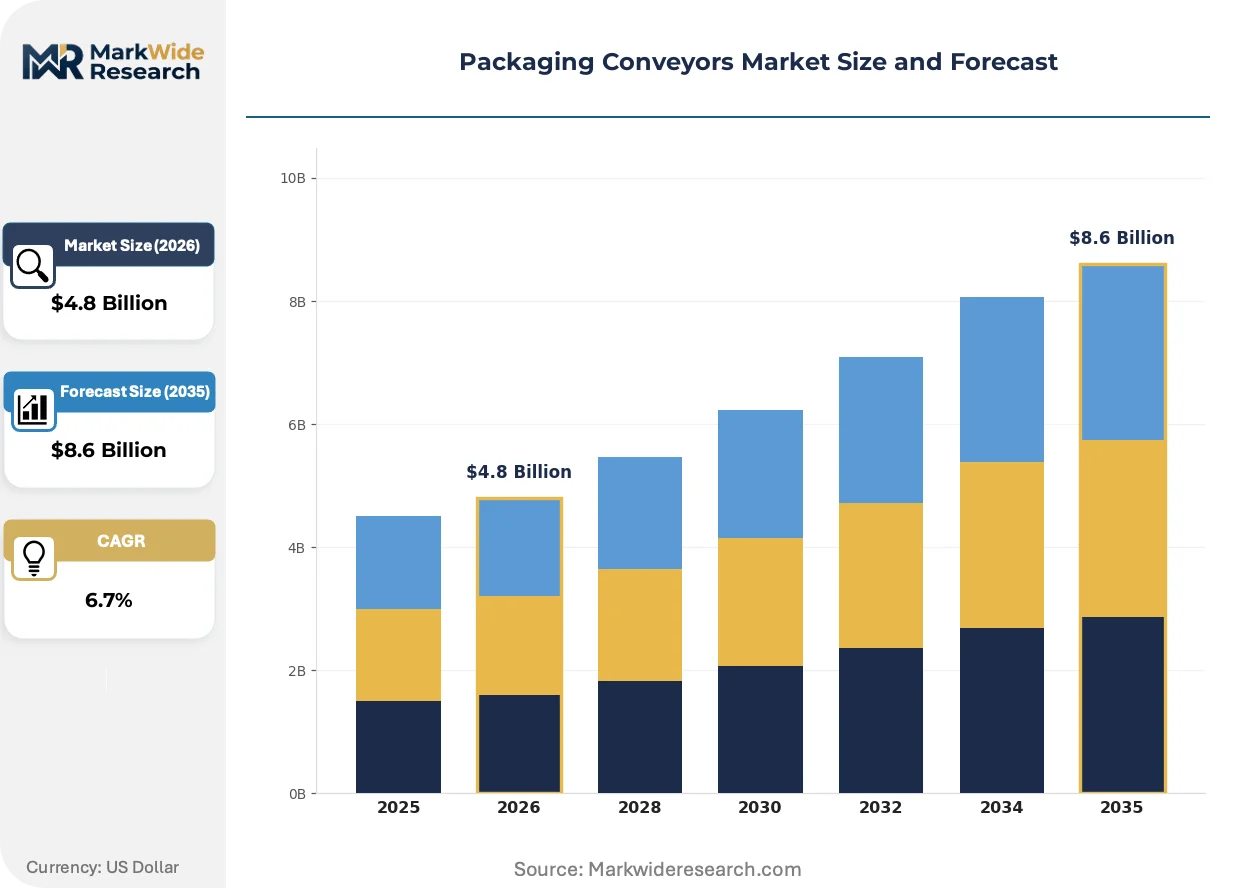
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
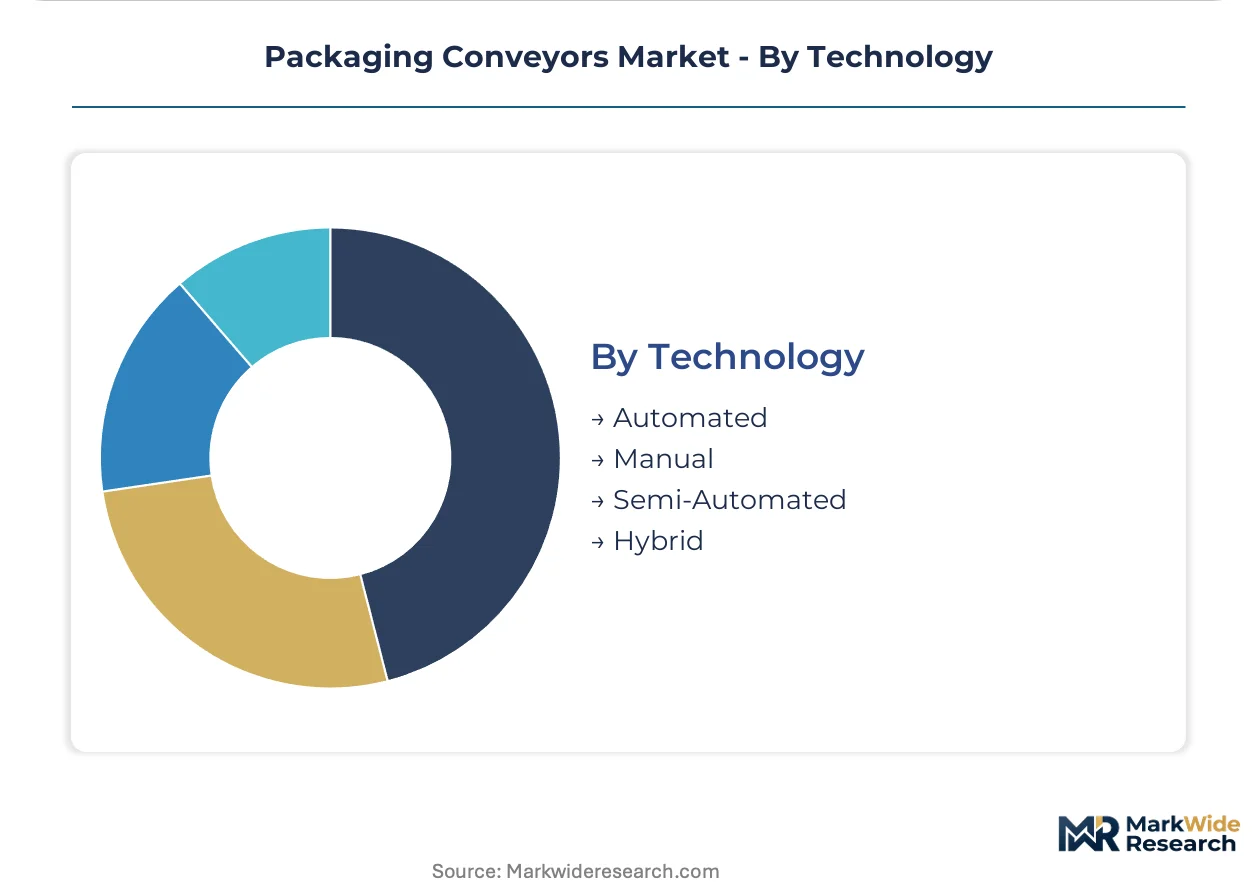
| Segmentation | Product Type: Modular Belt Conveyors, Chain Conveyors, Roller Bed Conveyors, Belt Conveyors Application: Food & Beverage, Pharmaceuticals, Electronics, Personal Care End User: Manufacturing, Warehousing, Retail, Distribution Centers Technology: Automated, Manual, Semi-Automated, Hybrid |
| Companies Covered | Dorner Mfg. Corp., Multi-Conveyor, LLC, mk Technology Group, Conveyor Units Ltd., Crawford Packaging, Nercon Eng. and Mfg. Inc., Hytrol Conveyor Company, Interroll, Daifuku, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Conveyors Market Evolving Landscape
Material science advances and regulatory disclosure mandates are converging to reshape conveyor specification patterns. Buyers increasingly prioritize hygienic design certification and lifecycle carbon data alongside traditional throughput metrics.
Polymer composite frame segments are supplanting painted steel in washdown environments. Dairy and meat processors in Denmark and the Netherlands are specifying these materials to eliminate corrosion risks during caustic cleaning cycles. FDA food contact surface regulations are accelerating this transition by de-risking compliance audits.
REACH substance restrictions are forcing reformulation of belt coatings and lubricants used in European food plants. Manufacturers must now document SVHC-free status for all polymer components. German and French dairy cooperatives are leading this compliance push, treating chemical safety documentation as a procurement gate.
Outcome-based maintenance contracts are displacing traditional break-fix service models in high-throughput distribution centers. Third-party logistics operators in the US and Germany are bundling conveyor uptime guarantees with equipment leases. Amazon and DHL fulfillment networks are driving this shift, treating conveyor availability as a operational KPI rather than a capital asset.
Packaging Conveyors Market Segmentation
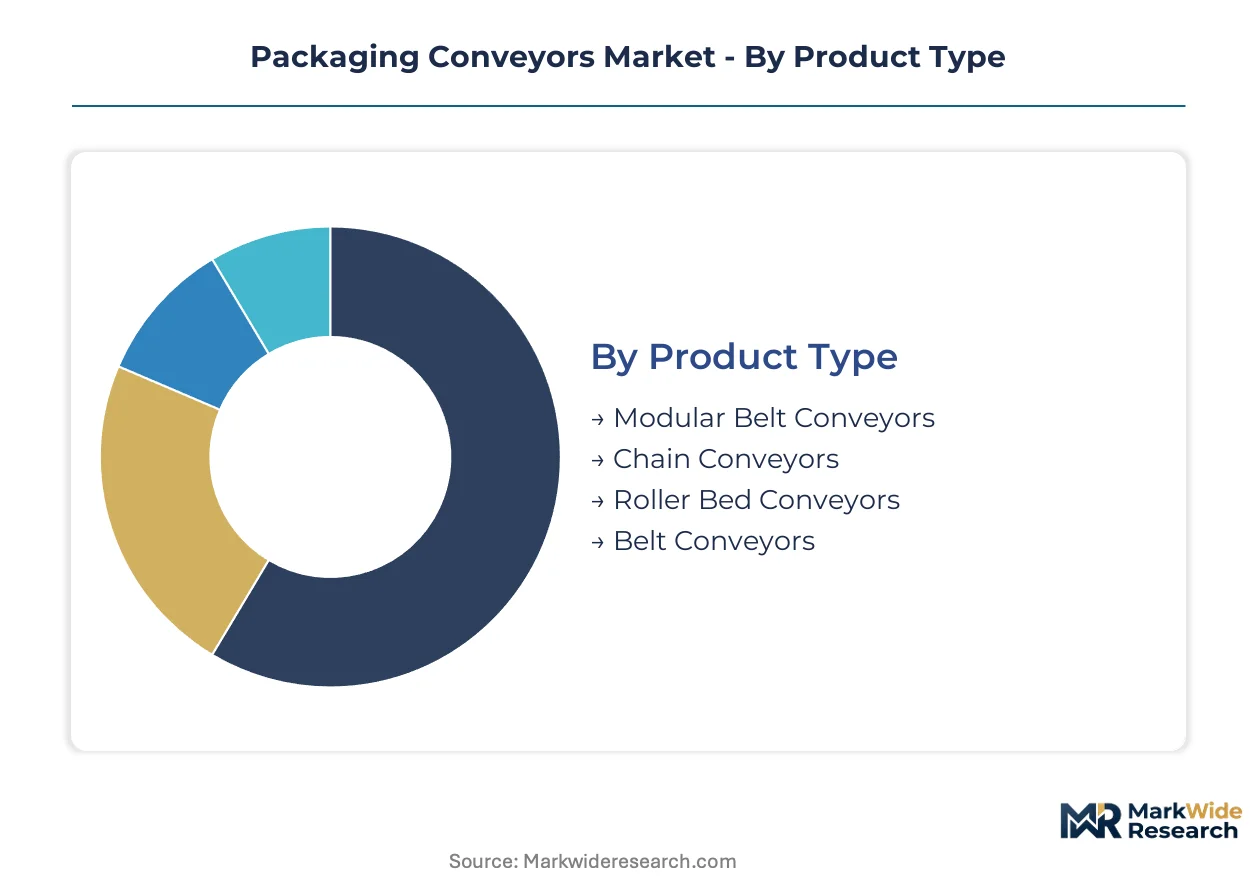
Packaging conveyor purchasing patterns diverge sharply across operational contexts. Product handling requirements, regulatory exposure, and labor cost structures each reshape specification priorities for equipment buyers.
Product Type:
Roller bed designs face intensifying substitution pressure from modular alternatives in washdown-intensive environments, while legacy belt configurations confront obsolescence from open-hinge hygiene standards.
- Modular Belt Conveyors:Open-hinge polymer belts tolerate caustic washdown cycles without corrosion degradation. Dairy cooperatives in Denmark and the Netherlands specify these configurations to satisfy FDA food contact surface regulations during CIP protocols.
- Roller Bed Conveyors:Low-friction steel or aluminum rollers handle carton weights exceeding 50 kg in high-velocity distribution lanes. Amazon and DHL fulfillment networks retain these systems for outbound sorting where load capacity trumps hygienic design requirements.
- Chain Conveyors:Engineered for palletized loads and heavy-duty industrial packaging with positive-drive engagement.
- Belt Conveyors:Continuous flat or cleated belts serve lightweight product transport in cost-sensitive applications.
Roller bed configurations retain volume leadership in distribution infrastructure; modular belt systems hold the steepest expansion curve in food processing installations.
Application:
Margin compression varies dramatically by end-use sector, with pharmaceutical lines commanding specification premiums that consumer goods applications cannot sustain.
- Food & Beverage:Hygienic design mandates from EU Machinery Directive 2006/42/EC and FDA regulations dominate procurement criteria. Meat and ready-meal processors prioritize stainless steel frames with traceable component sourcing for export qualification.
- Pharmaceuticals:Cleanroom-rated aluminum extrusion conveyors satisfy ISO 14644 particulate limits. South Korean and Taiwanese semiconductor packaging facilities specify washdown-rated precision systems for medical device assembly.
- Electronics:Anti-static belt materials and precision accumulation controls protect sensitive components during final packaging stages.
- Personal Care:Cosmetic filling lines favor lightweight aluminum frames where floor load constraints prohibit heavier steel alternatives.
Food and beverage applications absorb the largest capital allocation; pharmaceutical lines generate the highest margin premiums per installed meter.
End User:
Customer scale determines service model viability, with enterprise operators demanding outcome-based contracts that mid-tier manufacturers reject.
- Distribution Centers:Third-party logistics operators bundle conveyor uptime guarantees with equipment leases. US and German fulfillment networks treat availability as an operational KPI rather than capital asset ownership.
- Manufacturing:OEM integration requirements drive custom engineering for complex product handling sequences. Stuttgart-Cologne corridor machinery builders source localized supplier ecosystems to compress delivery lead times.
- Warehousing:E-commerce batch fragmentation drives interest in narrow-pitch modular belts with accumulation capability for small-parcel sortation.
- Retail:Back-of-store replenishment systems prioritize compact footprints and rapid reconfiguration for seasonal volume swings.
Distribution centers command the largest installed base; warehousing operations are climbing fastest on e-commerce automation investment.
Technology:
Automation intensity correlates directly with labor cost exposure and throughput velocity requirements across facility types.
- Automated:Sensor-integrated systems with PLC-controlled accumulation and diverting functions synchronize with robotic palletizing and case-packing cells. Warehouse labor cost escalation in Germany and the US accelerates capital substitution.
- Hybrid:Manual loading zones transition to automated transport and sortation, preserving flexibility for variable product mixes. Mid-tier food processors deploy these configurations to balance capital constraints with throughput targets.
- Semi-Automated:Operator-assisted indexing and manual quality stations bridge gaps in fully automated lines.
- Manual:Basic gravity or hand-push configurations persist in low-volume, high-mix operations with minimal capital budgets.
Automated systems capture disproportionate investment flow; hybrid configurations gain share fastest among capital-constrained mid-tier operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging conveyor consumption patterns diverge sharply by geography. German food processors prioritize stainless steel hygiene compliance, while US distribution centers optimize for throughput velocity and uptime guarantees. Asian electronics packaging lines demand precision aluminum systems distinct from heavy-load European configurations.
Germany
Meat and dairy cooperatives drive specification toward modular open-hinge belts with traceable component sourcing. EU Machinery Directive 2006/42/EC mandates CE marking compliance for export-bound equipment. The Stuttgart-Cologne corridor concentrates packaging machinery OEMs sourcing localized supplier ecosystems to compress delivery lead times.
United States
Third-party logistics operators bundle conveyor uptime guarantees with equipment leases, treating availability as an operational KPI. FDA food contact surface regulations elevate stainless steel specification rates in food processing procurement. Amazon and DHL fulfillment networks dominate distribution center automation investment across the Midwest and Southeast.
China
E-commerce warehouse automation accelerates capital substitution as labor costs climb in coastal provinces. GB standards and SAMR equipment safety regulations shape domestic procurement criteria. The Yangtze River Delta and Pearl River Delta concentrate electronics packaging lines demanding precision aluminum-frame conveyors for lightweight applications.
Denmark
Dairy processors specify polymer composite frames to eliminate corrosion risks during caustic CIP cycles. REACH substance restrictions force reformulation of belt coatings and lubricants for SVHC-free documentation. Danish cooperatives lead chemical safety compliance pushes, treating documentation as a procurement gate for equipment vendors.
South Korea
Semiconductor and medical device packaging lines create demand for cleanroom-rated precision conveyors. MFDS medical device regulations and ISO 14644 particulate limits govern equipment specification. The Seoul Capital Area concentrates pharmaceutical automation investment requiring washdown-rated systems for medical device assembly.
Packaging Conveyors Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in packaging conveyor supply. The upper tier commands premium positioning through modular platform architectures and outcome-based service contracts. Mid-tier fabricators compete on custom engineering capabilities for complex product handling sequences. Strategic moves concentrate on geographic expansion through distributor partnerships and backward integration into aluminum extrusion and polymer belt manufacturing.
Within the modular platform archetype, Dorner Mfg. Corp. and mk Technology Group exemplify precision-engineered system suppliers. Multi-Conveyor, LLC occupies a position among custom engineering specialists addressing complex handling requirements. These three entities represent distinct competitive vectors: standardized modular architectures, lightweight aluminum-frame precision, and application-specific custom fabrication.
| Leading Market Players |
|---|
| Dorner Mfg. Corp. |
| Multi-Conveyor, LLC |
| mk Technology Group |
| Conveyor Units Ltd. |
| Crawford Packaging |
| Nercon Eng. and Mfg. Inc. |
| Hytrol Conveyor Company |
| Interroll |
| Daifuku |
| Others |
Value Network & Pricing Analysis
Capacity utilization at German stainless steel extrusion plants shapes margin structures across the European packaging conveyor base, compressing price floors for mid-tier fabricators while elevating premiums for traceable-component suppliers serving export-bound food processors.
Pricing Analysis
Long-term offtake contracts dominate procurement between major food processors and modular conveyor OEMs, insulating tier-one suppliers from spot-market volatility in 304 and 316-grade stainless steel. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked hygienic systems with full ISO 22000 documentation from basic aluminum-frame configurations. Cost compression in mid-tier equipment is intensifying because raw material price swings are eroding margin buffers for fabricators lacking backward integration into polymer belt manufacturing. Enterprise distribution operators exhibit lowest price sensitivity due to outcome-based uptime guarantees, while small-scale dairy cooperatives in Eastern Europe remain most cost-constrained.
Supply Chain Analysis
Germany and Italy anchor precision aluminum extrusion and polymer belt manufacturing for European packaging conveyor assembly, with China supplying cost-optimized roller components and motor drives. Stainless steel frame production draws from Swedish and Finnish mills, while open-hinge belt polymers source from specialized compounders in the Netherlands and Belgium. Single-source vulnerability concentrates in high-grade 316 stainless steel for pharmaceutical cleanroom specifications, where limited European mill capacity creates allocation risk during demand surges. Distribution runs through OEM-direct channels for large food processors and machinery-builder networks for mid-tier manufacturing integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Machinery Directive compliance deadlines and FDA hygiene mandates are accelerating replacement cycles, creating a high-growth disruption window for suppliers with certified modular platforms and traceable component sourcing.
For Market Incumbents: Compound defensive positioning by deepening backward integration into aluminum extrusion and polymer belt manufacturing to offset raw material volatility, while accelerating CE-marking certification investments to capture export-bound European food processor demand before smaller competitors qualify. Modular platform architectures with washdown-rated open-hinge designs represent the critical lever against substitution from roller bed systems in distribution lanes. For New Entrants and Emerging Players: Lead with narrow-pitch modular belt systems targeting e-commerce warehousing operations in the US Midwest and Southeast, where batch fragmentation and labor cost escalation create penetrable white space lacking incumbent saturation. Custom engineering capabilities for complex pharmaceutical handling sequences in South Korean semiconductor packaging lines offer a second entry vector, with outcome-based maintenance contracts as the preferred go-to-market mechanism. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among modular platform OEMs with installed base service contracts and spare parts provisioning, indicating superior cash-flow quality for long-term viability assessment across the five-to-ten year window. Acquisition targets should display captive aluminum extrusion capacity or exclusive polymer belt compound relationships. The signal to watch is outcome-based contract penetration rates among third-party logistics operators, as this metric indicates pricing power migration from equipment sales to operational guarantees.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Captive frame production insulates margin buffers from German mill price volatility. |
| CE Marking Acceleration for Export Equipment | Traceable component sourcing satisfies EU Machinery Directive 2006/42/EC compliance deadlines. |
| Outcome-Based Maintenance Contract Expansion | Uptime guarantees align revenue models with Amazon and DHL operational KPI frameworks. |
| Cleanroom Specification Development | ISO 14644-rated systems capture South Korean semiconductor packaging automation investment. |
| Narrow-Pitch Modular Belt Launch | Accumulation capability addresses e-commerce batch fragmentation in US fulfillment networks. |
Research Methodology
Cross-validation between primary interviews with plant engineers, OEM procurement teams, aftermarket service directors, and food safety compliance officers anchors the qualitative findings, while secondary validation incorporates EU Machinery Directive filings, FDA food contact surface registrations, customs data on aluminum extrusion trade flows, and SEC disclosures from listed packaging machinery OEMs. Bottom-up segment sizing triangulates against top-down macroeconomic indicators for capital equipment investment.
Sensitivity analysis on stainless steel price trajectories and labor cost escalation assumptions shapes the analytical framework across the projection horizon, with segmentation dimensions spanning product type, application sector, end-user scale, and automation intensity. CAGRs derive from installed base growth rates and replacement cycle compression in food processing, supplemented by warehouse automation capex trends and pharmaceutical cleanroom buildout pipelines.
Forecasts assume regulatory continuity in EU Machinery Directive enforcement and FDA food contact surface standards; material policy shifts would require re-modeling. Specific risk factors include REACH substance restriction expansions affecting belt coatings and extended ISO 22000 certification timelines elongating vendor qualification cycles. Recalibration cycles align with material shifts in stainless steel pricing volatility and e-commerce fulfillment network expansion rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Cutter-Box Packaging Market
Packaging Machinery
Box Sealing Machines Market
Packaging Machinery
Bakery Packaging Machine Market
Packaging Machinery
Wraparound Case Packers Market
Packaging Machinery
Envelope Sealing Machines Market
Packaging Machinery
Sliding Injection Molding Machine Market
Packaging Machinery
Pouch Packaging Machine Market
Packaging Machinery
Global Vial Cap Sealing Machines Market
Packaging Machinery
Thermoform Fill Sealing Machine Market
Packaging Machinery
Global Hand Wrapping Machine Market
Packaging Machinery
Paper Napkins Converting Machines Market
Packaging Machinery
Wicketed Bagging Machines Market
Packaging Machinery
Emboss Coding Machine Market
Packaging Machinery
Europe Blow Molding Machine Market
Packaging Machinery
Tray Sealer Machines Market
Packaging Machinery
Overwrapping Machines Market