
 Face Mask Machines Market | 2026-2036
Face Mask Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Face Mask Machines Market Insights
China's expanding nonwoven converting capacity is reshaping supply dynamics for face mask machines. Han's Laser Technology Industry Group Co., Ltd. leverages its ultrasonic welding expertise to dominate precision tooling for automated lines. NCM Nonwoven Converting Machinery Co. Ltd. anchors high-volume output through integrated die-cutting and sealing platforms. Cera Engineering competes on customized European-built systems with shorter changeover cycles for specialty mask formats.
Face mask machines are automated or semi-automated production systems that form, weld, and cut nonwoven polypropylene layers into disposable or reusable masks, typically operating at speeds of 60–120 pieces per minute with ultrasonic bonding at 20 kHz frequency. These systems serve healthcare procurement, industrial safety programs, and retail private-label supply chains. Fully automatic lines capture the largest equipment spend as hospital systems and government stockpile programs prioritize throughput over capital flexibility. Ultrasonic welding technology leads unit deployment because melt-blown fabric integrity depends on cold-seal adhesion without thermal degradation. Manual and semi-automatic configurations retain share among small-batch cosmetic and fashion mask producers where changeover speed outweighs labor cost.
FDA device registration requirements and China's NMPA medical device classification rules shape which machine architectures qualify for regulated output, pushing manufacturers toward validated cleanroom-compatible designs. The EU MDR and REACH frameworks constrain adhesive and elastic material choices, forcing equipment builders to accommodate alternative ear-loop attachment methods. Stakeholders must monitor how ECHA substance restrictions and evolving ISO filtration standards redefine machine specification sheets before committing to platform investments.
Market Dynamics
Ultrasonic welding technology at 20 kHz frequency is compressing machine design cycles as melt-blown fabric integrity demands cold-seal adhesion without thermal degradation. Hospital systems and government stockpile programs now prioritize throughput-validated cleanroom-compatible architectures over capital-flexible configurations.
Growth Catalysts
- EU MDR compliance mandates:Medical device classification rules in Europe are forcing equipment builders toward validated cleanroom-compatible designs that qualify for regulated mask output.
- Vietnam's industrial corridor concentration:Manufacturers relocating capacity from higher-cost origins are scaling automated production lines near Ho Chi Minh City, pulling demand for high-speed integrated systems.
- Ultrasonic bonding platforms:Cold-seal adhesion technology preserves melt-blown fabric filtration integrity, making 20 kHz welding the default specification for healthcare procurement.
Market Restraints
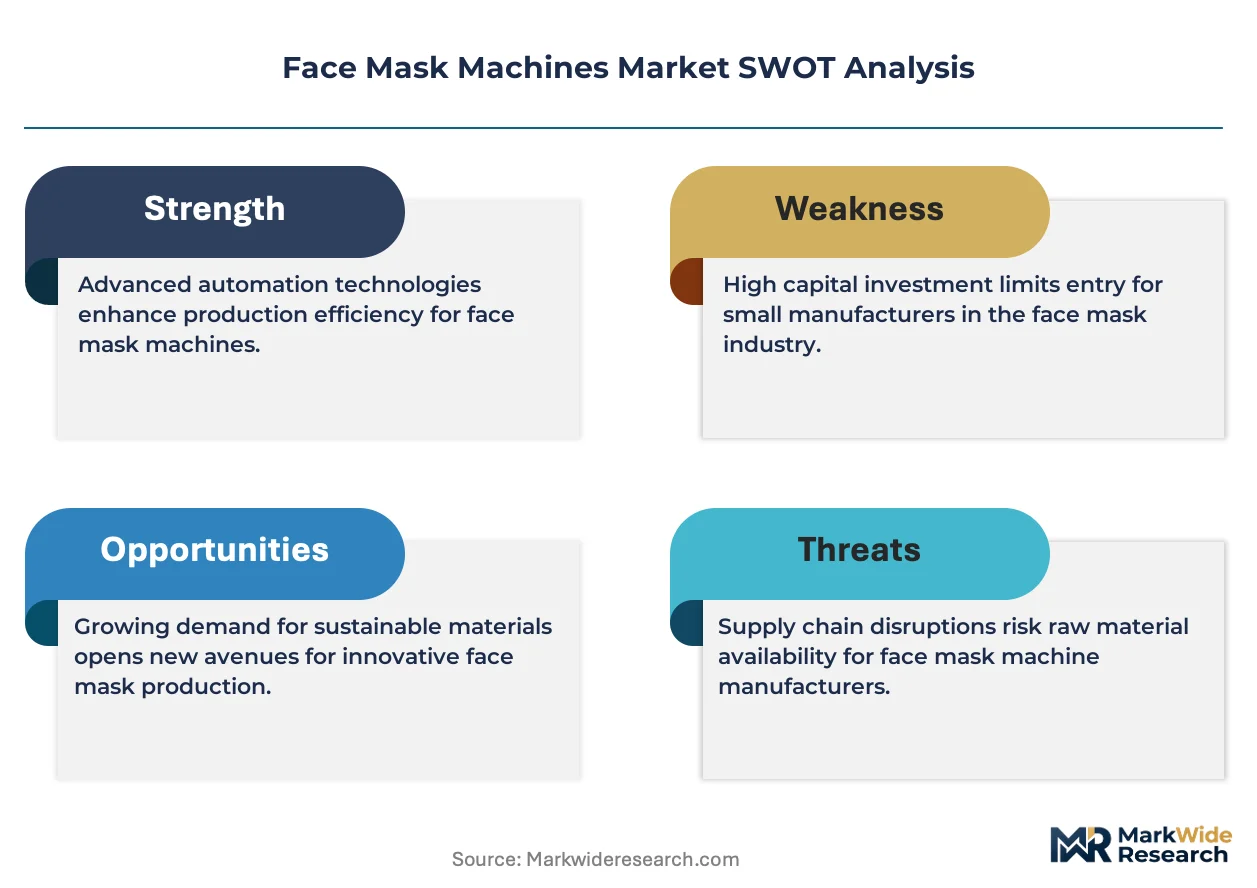
- Polypropylene feedstock volatility:Spunbond and melt-blown nonwoven input costs fluctuate with petrochemical pricing, squeezing machine ROI calculations for small-batch producers.
- China's GB standards tightening:National medical device manufacturing standards and SAMR compliance requirements are raising technical barriers for equipment qualification.
- Manual configuration persistence:Small-batch cosmetic and fashion mask producers retain semi-automatic lines where changeover speed outweighs labor cost advantages of full automation.
Strategic Opportunities
- REACH framework adaptation:ECHA substance restrictions on adhesives and elastics are creating demand for alternative ear-loop attachment methods that equipment builders can patent.
- Reusable mask formats:Industrial safety programs and retail private-label supply chains are expanding specifications for washable multi-layer designs requiring modified die-cutting platforms.
- ISO filtration standard evolution:Anticipated revisions to particulate filtration benchmarks will force machine specification sheet rewrites, favoring builders with modular upgrade paths.
Industry Challenges
- Cleanroom certification timelines:FDA device registration and NMPA medical device classification validation cycles extend 12-18 months, delaying revenue recognition for platform investments.
- Multi-frequency welding integration:Equipment builders face engineering complexity combining 15 kHz heavy-gauge sealing with 20 kHz precision bonding in single-line architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Face Mask Machines Market |
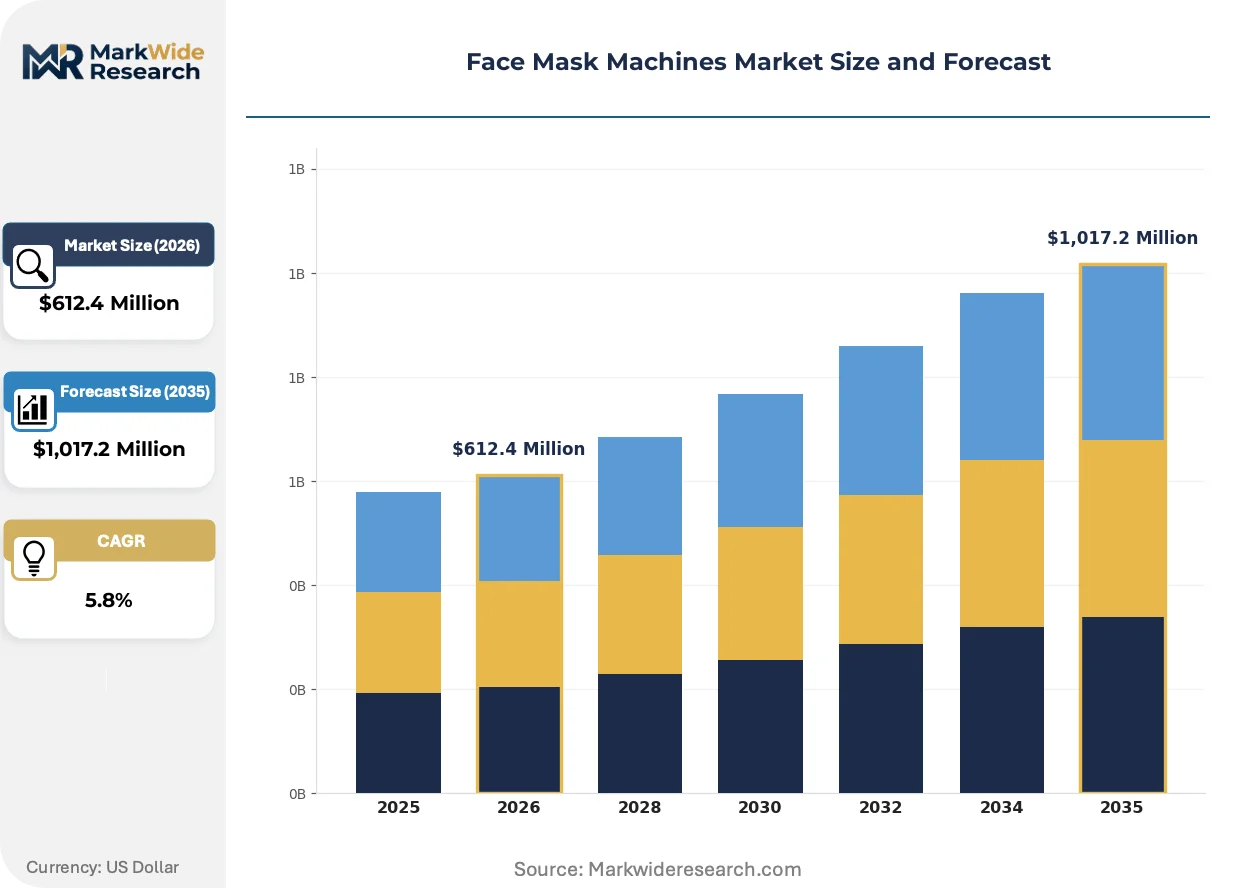
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,017.2 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fully Automatic, Semi-Automatic, Manual, Customized Technology: Ultrasonic Welding, Heat Sealing, Injection Molding, Die Cutting End User: Healthcare Facilities, Industrial Manufacturers, Retail Stores, Distributors Application: Medical Use, Personal Protection, General Use, Disposable |
| Companies Covered | Aman Impex, Han's Laser Technology Industry Group Co., Ltd., OREE LASER, TESTEX INSTRUMENT LTD, NCM Nonwoven Converting Machinery Co. Ltd., Engelmann & Buckham Ltd, Cera Engineering, KYD, Intamac Packaging Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Face Mask Machines Market Trends and Innovations
Machine architecture is pivoting toward modular platforms that accommodate rapid format switching between surgical, N95, and reusable mask specifications without full line revalidation.
Servo-driven tension control systems are migrating from mechanical clutch arrangements to digital closed-loop architectures. Tier-one hospital procurement groups in Germany and Japan are specifying these platforms for lines above 100 pieces per minute. This migration from analog to digital control is compressing changeover intervals from four hours to under forty-five minutes, enabling same-day format switches.
REACH substance restrictions on phthalate-based elastic compounds are compelling equipment redesigns for silicone and TPU ear-loop attachment modules. ECHA's 2023 candidate list expansion forced European system builders to validate ultrasonic staking methods that avoid chemical adhesives entirely. Medical device OEMs in France and Italy are now sourcing machines with pre-certified material compatibility documentation.
Hospital consortiums are consolidating equipment procurement through group purchasing organizations, displacing direct manufacturer relationships. This channel compression concentrates specification-setting power with IDN procurement committees in the US and NHS supply chain hubs in England. Equipment builders must now maintain dedicated contract negotiation teams rather than regional sales coverage.
Face Mask Machines Market Segmentation
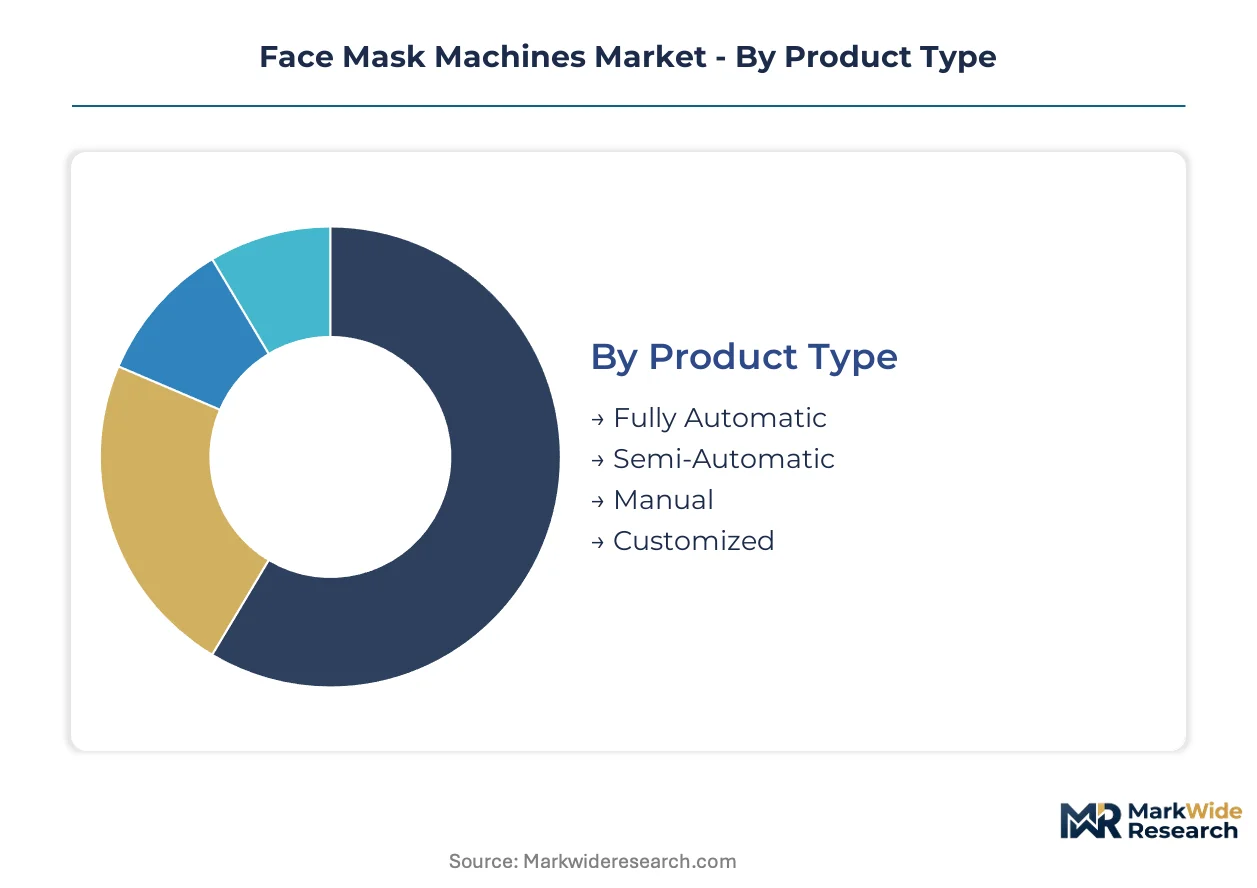
Face mask machine architectures diverge sharply across automation tiers and bonding technologies, with procurement patterns in hospital systems and industrial corridors pulling specifications in distinct directions. Understanding these segment boundaries clarifies where capital deployment concentrates versus where flexibility premiums command pricing power.
Product Type:
Mature configurations dominate hospital procurement while emerging formats capture niche flexibility premiums.
- Fully Automatic:These lines integrate servo-driven tension control with continuous ultrasonic bonding at 60–120 pieces per minute, validated for FDA device registration and NMPA medical device classification. Hospital systems and government stockpile programs in Vietnam's industrial corridors near Ho Chi Minh City specify these architectures for throughput over capital flexibility.
- Semi-Automatic:Modular platforms with operator-fed material loading and automated welding stations balance labor input with format adaptability. Small-batch cosmetic and fashion mask producers retain these configurations where changeover speed outweighs full automation labor savings.
- Manual:Benchtop units with hand-actuated cutting and sealing tools serve prototype development and ultra-low-volume specialty runs.
- Customized:Purpose-built systems accommodate specialty mask formats with modified die-cutting platforms for reusable multi-layer designs.
Fully Automatic retains volume leadership; Customized holds the steepest expansion curve.
Technology:
Cost tier stratification separates precision bonding platforms from commodity sealing alternatives.
- Ultrasonic Welding:Cold-seal adhesion at 20 kHz frequency preserves melt-blown fabric filtration integrity without thermal degradation. This technology leads unit deployment across healthcare procurement chains where ISO filtration standard compliance is mandatory.
- Heat Sealing:Thermal compression bonding suits general-use disposable masks with lower filtration requirements, offering lower capital entry points for price-sensitive industrial safety programs.
- Injection Molding:Plastic component fabrication for nose bridges and structural reinforcements integrates with downstream assembly lines.
- Die Cutting:Precision contour cutting for ear-loop attachment points and facial fit patterns enables rapid format switching between surgical and N95 specifications.
Ultrasonic Welding commands the premium tier; Die Cutting is climbing the fastest on modularity demand.
End User:
Customer type fragmentation concentrates specification-setting power with consolidated procurement channels.
- Healthcare Facilities:Hospital consortiums and IDN procurement committees specify cleanroom-compatible architectures with pre-certified material compatibility documentation for EU MDR compliance.
- Industrial Manufacturers:Corporate safety programs and private-label supply chains drive demand for washable reusable mask production lines with modified sealing parameters.
- Retail Stores:Private-label sourcing teams prioritize quick-changeover platforms for seasonal fashion mask collections.
- Distributors:Inventory-holding intermediaries aggregate demand across fragmented small-batch producers, favoring semi-automatic configurations with broad format compatibility.
Healthcare Facilities anchor capital deployment; Industrial Manufacturers are gaining share fastest on reusable format expansion.
Application:
Volume scale separates regulated medical output from commodity personal protection.
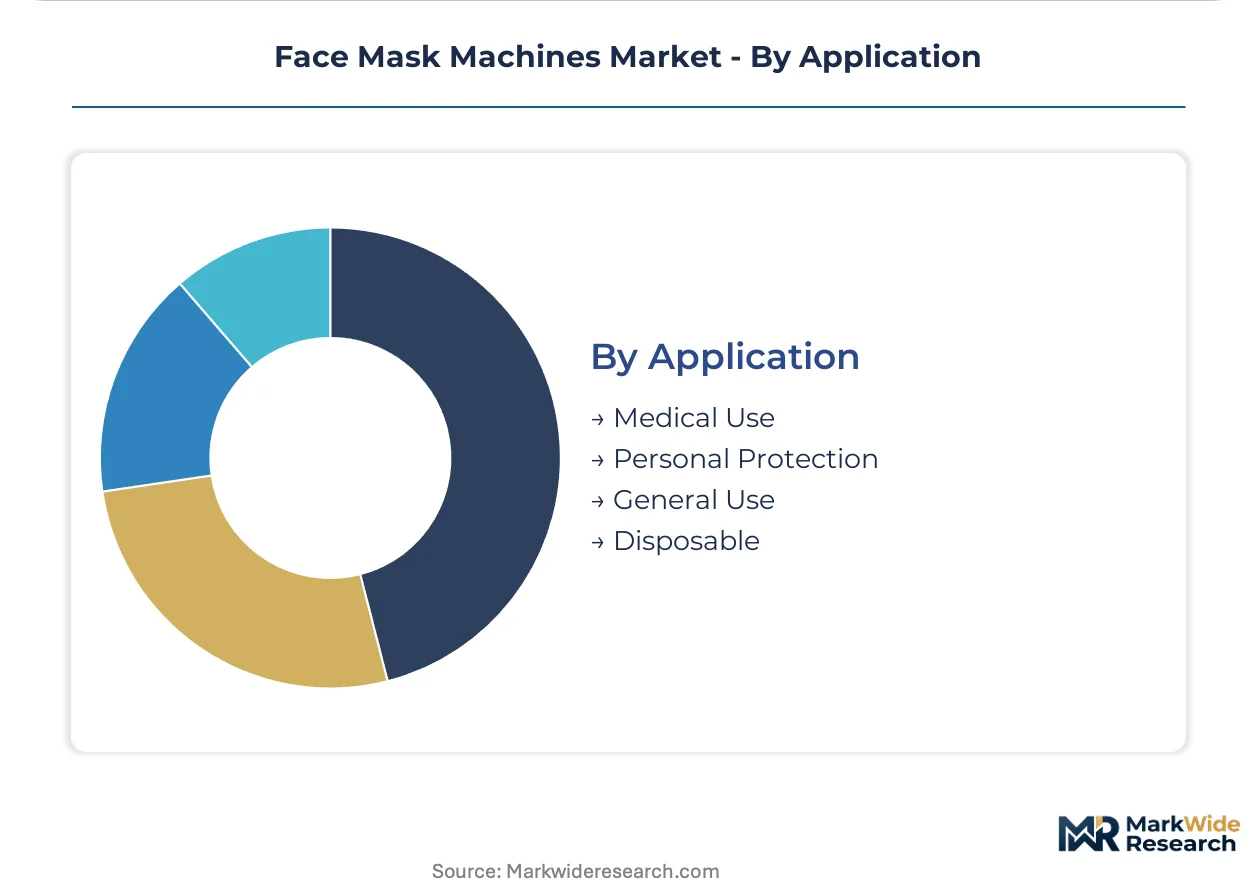
- Medical Use:Surgical and N95 formats requiring validated cleanroom-compatible designs dominate equipment spend through FDA device registration and China's GB standards compliance mandates.
- Personal Protection:Industrial safety and consumer respiratory protection specifications emphasize durability and fit consistency over filtration certification.
- General Use:Non-medical disposable masks for retail and hospitality applications prioritize throughput economics over precision bonding.
- Disposable:Single-use formats across all end-use categories drive the majority of machine operating hours, with melt-blown fabric integrity requirements defaulting to ultrasonic welding specifications.
Medical Use retains specification leadership; Personal Protection is expanding most quickly on industrial safety program growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NMPA medical device classification rules anchor equipment qualification standards across China, while FDA device registration requirements shape procurement specifications in the United States. Vietnam's industrial corridors near Ho Chi Minh City concentrate new capacity deployment as manufacturers relocate from higher-cost origins.
China
GB standards for medical device manufacturing and SAMR compliance requirements are tightening technical barriers for equipment qualification. MIIT industrial policy directives prioritize ultrasonic welding technology upgrades for melt-blown fabric integrity. The Yangtze River Delta and Pearl River Delta clusters host the majority of domestic machine fabricators serving both regulated medical output and export markets.
United States
Hospital procurement committees and IDN consolidation are compressing vendor relationships toward group purchasing organization channels. FDA device registration validation cycles extend 12-18 months for cleanroom-compatible architectures. The Midwest industrial belt and Southeast manufacturing corridors concentrate equipment deployment for government stockpile programs and hospital system supply chains.
Vietnam
Industrial zones near Ho Chi Minh City are scaling automated production lines as manufacturers relocate capacity from China and other higher-cost origins. The country's national pharmaceutical regulator aligns medical device classification with ASEAN harmonization frameworks. Binh Duong and Dong Nai provinces host the densest concentrations of new nonwoven converting capacity.
Germany
EU MDR compliance mandates and ECHA REACH substance restrictions are forcing equipment builders toward validated cleanroom-compatible designs with pre-certified material compatibility. The national medical device regulator enforces strict validation protocols for machines producing regulated mask output. Baden-Württemberg and Bavaria anchor precision tooling fabrication for European-built systems with shorter changeover cycles.
Japan
PMDA medical device classification rules and METI industrial standards shape equipment specifications for domestic hospital procurement. JIS standards for filtration performance default to 20 kHz ultrasonic welding specifications to preserve melt-blown fabric integrity. The Kanto region around Tokyo and the Chubu region near Nagoya concentrate servo-driven tension control system integration for lines above 100 pieces per minute.
Face Mask Machines Market Competitive Landscape
Laser technology specialists and nonwoven converting machinery fabricators split the market between precision welding platforms and integrated production systems. The vendor base clusters around three strategic archetypes: ultrasonic welding technology providers, full-line system integrators, and customized European-built specialists. Consolidation pressure runs through group purchasing organization channel compression and hospital consortium procurement consolidation. Competitive moves center on modular platform development for rapid format switching and cleanroom certification pre-validation to compress revenue recognition timelines.
Among Chinese laser technology providers, Han's Laser Technology Industry Group Co., Ltd. represents the precision tooling archetype for automated lines. NCM Nonwoven Converting Machinery Co. Ltd. exemplifies the full-line system integrator position with die-cutting and sealing platforms. Cera Engineering occupies a position within the customized European-built specialist tier, anchoring shorter changeover cycle capabilities for specialty mask formats. These three entities illustrate how geographic origin and company structure map to distinct competitive positioning without requiring specific product or strategic claims.
| Leading Market Players |
|---|
| Aman Impex |
| Han's Laser Technology Industry Group Co., Ltd. |
| OREE LASER |
| TESTEX INSTRUMENT LTD |
| NCM Nonwoven Converting Machinery Co. Ltd. |
| Engelmann & Buckham Ltd |
| Cera Engineering |
| KYD |
| Intamac Packaging Systems |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in China's Yangtze River Delta ultrasonic welding component sector is compressing margins for precision tooling suppliers while simultaneously expanding pricing leverage for full-line system integrators in Vietnam's industrial corridors. This utilization asymmetry between component oversupply and integrated system scarcity is reshaping procurement negotiations for hospital consortiums and government stockpile programs.
Pricing Analysis
Price spreads between European-built customized systems and Chinese full-line platforms exceed three-to-one at equivalent throughput specifications. Three-tier pricing structure across premium certified, standard validated, and economy non-medical levels stratifies the market, with FDA and NMPA certification tiers commanding substantial premiums. Cost compression in the economy tier is intensifying as spunbond polypropylene feedstock volatility squeezes small-batch producer ROI calculations. Industrial safety programs exhibit highest price sensitivity, while hospital IDN procurement committees prioritize throughput validation over capital expenditure minimization.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for ultrasonic generator and servo-drive subassemblies. Component fabrication concentrates in China, Germany, and Japan, with precision welding transducers drawing from Japanese ceramics specialists and German piezoelectric suppliers. Single-source vulnerability in 20 kHz ultrasonic stack assemblies creates procurement bottlenecks for lines above 100 pieces per minute. Distribution runs through group purchasing organization channels in the United States and NHS supply chain hubs in England, displacing direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through cleanroom certification pre-validation creates defensive moats that extend revenue recognition timelines and compress competitive entry windows for equipment builders.
For Market Incumbents: Pre-empt emerging modular platform competitors by accelerating cleanroom certification pre-validation investments that compress 12-18 month FDA and NMPA timelines. Anchor capacity addition in Vietnam's Binh Duong and Dong Nai provinces to capture manufacturer relocation demand from higher-cost origins. Vertical integration into servo-driven tension control system production reduces dependency on Japanese precision motion suppliers.
For New Entrants and Emerging Players: Southeast Asian industrial corridors outside Vietnam's Ho Chi Minh City concentration present the most penetrable geography for semi-automatic platform deployment. Target small-batch cosmetic and fashion mask producers in Indonesia and Thailand where changeover speed premiums outweigh full automation labor savings. Pursue equipment-as-a-service financing models to lower capital barriers for private-label retail sourcing teams.
For Investors and Strategic Acquirers: Capital is best deployed toward precision welding technology specialists with captive ultrasonic transducer capabilities and established EU MDR technical documentation libraries. Long-term viability hinges on modular upgrade path architectures that accommodate anticipated ISO filtration standard revisions. Monitor ECHA candidate list expansions for silicone and TPU ear-loop attachment method patent filings as inflection indicators for material compatibility positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Certification Pre-Validation | Compresses FDA and NMPA approval timelines from 18 months toward 12 months for hospital procurement eligibility. |
| Modular Platform Development | Enables same-day format switching between surgical, N95, and reusable mask specifications without line revalidation. |
| Backward Integration into Servo Systems | Reduces dependency on Japanese precision motion suppliers and protects margins against component tariff exposure. |
| Geographic Manufacturing Footprint Expansion | Vietnam's Binh Duong province captures manufacturer relocation demand from China's higher-cost Yangtze River Delta. |
| Material Compatibility Patent Portfolio | ECHA REACH restrictions on phthalate-based elastics create defensible intellectual property in silicone staking methods. |
Research Methodology
The analysis maps fully automatic, semi-automatic, manual, and customized machine configurations, each validated through equipment procurement managers at hospital systems, biomedical engineers specifying cleanroom architectures, GPO contracts managers consolidating vendor relationships, and aftermarket service heads maintaining ultrasonic welding platforms. Primary intelligence combined with secondary validation from FDA device registration databases, NMPA medical device classification filings, EU MDR technical documentation repositories, and ASEAN harmonization framework directives. Bottom-up line deployment counts triangulated against top-down capital expenditure estimates from industrial zone investment authorities.
Assumptions held fixed include prevailing GB standards compliance requirements, SAMR enforcement intensity, and REACH substance restriction scope, while variables included polypropylene feedstock cost trajectories and ISO filtration standard revision timing. Segmentation dimensions spanned automation tier, bonding technology, end-user procurement channel, and application regulatory classification. CAGRs derived from equipment shipment volumes and average selling price trajectories across the projection horizon, with melt-blown fabric integrity specifications and ultrasonic frequency adoption curves as industry-specific forecast inputs.
Practitioners should monitor NMPA medical device reclassification initiatives and ECHA candidate list expansion schedules for early signals of specification sheet disruption. Forecasts reflect assumptions about cleanroom certification timeline stability and ASEAN regulatory harmonization momentum. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Banding Machine Market
Packaging Machinery
Paper Napkins Converting Machines Market
Packaging Machinery
Injectable Liquid Filling Machines Market
Packaging Machinery
Cling Wrap Machine Market
Packaging Machinery
Side Sealer Machines Market
Packaging Machinery
Cup Filling Machine Market
Packaging Machinery
CCL Laminating Machine Market
Packaging Machinery
Bagging Machine Market
Packaging Machinery
Flow Wrapper Market
Packaging Machinery
Pouch Packaging Machine Market
Packaging Machinery
Glazing Machine Market
Packaging Machinery
Sanitizer Filling Machine Market
Packaging Machinery
Tamper Evidence Machinery Market
Packaging Machinery
Global Blow Molding Machine Market
Packaging Machinery
Bottle Capping Machines Market
Packaging Machinery
Cigarette Packaging Machine Market