
 Soap Stamping Machine Market | 2026-2036
Soap Stamping Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Soap Stamping Machine Market Insights
Private label brands and artisanal soap makers are rotating demand away from legacy bulk manufacturers toward flexible, lower-volume equipment configurations. FusionTech International leverages its export network to serve mid-scale cosmetics companies across multiple continents. Sakun Engineers anchors its position through specialized manual and semi-automatic lines tailored to emerging market workshops. Mazzoni LB competes on hydraulic technology leadership and European regulatory compliance depth.
A soap stamping machine mechanically embosses logos, patterns, or brand identifiers onto solid soap bars using dies, presses, and controlled pressure systems operating at outputs from 50 to 5,000 bars per hour depending on configuration. The equipment serves soap manufacturers, cosmetics companies, contract manufacturers, and private label brands seeking product differentiation and brand recognition on retail shelves. Fully automatic machines dominate volume shipments to large-scale industrial soap producers, while custom machines command premium positioning among boutique and organic brands requiring unique die geometries and rapid changeover capability. Pneumatic and electric technologies are gaining share in new installations as energy efficiency and precision control become purchase criteria, though hydraulic systems retain installed-base dominance in heavy-duty applications.
CE marking and REACH compliance shape equipment material selection and surface finish standards for European-bound exports, while FDA cosmetic GMP guidelines influence validation documentation and cleanability design for US-market suppliers. India's BIS machinery safety standards and PLI scheme incentives for domestic manufacturing are redirecting some procurement toward local producers such as Adhisakthi Projects Private Limited and Kailash Engineering Works. Stakeholders must monitor how evolving ESG disclosure rules and carbon border adjustments reshape total cost of ownership calculations for cross-border equipment sourcing.
Market Dynamics
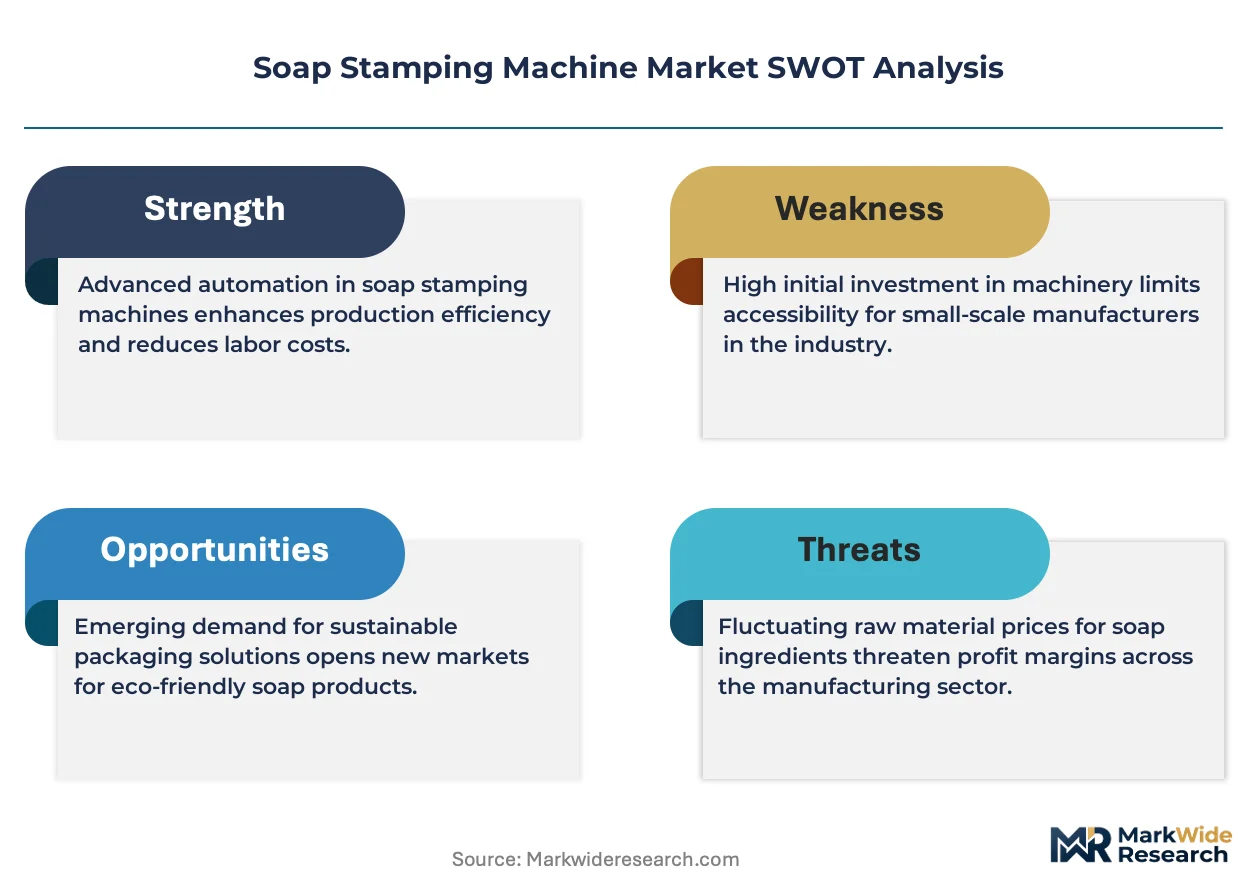
Artisanal soap brands and private label manufacturers are fragmenting demand away from bulk industrial producers, forcing equipment suppliers to reconfigure for shorter production runs and rapid die changeovers. This demand bifurcation is compressing margins on standardized hydraulic units while elevating pricing power for customizable pneumatic and electric systems.
Growth Catalysts
- REACH surface-contact mandates:European regulatory pressure on material composition is accelerating replacement cycles for legacy equipment in export-oriented Indian and Italian workshops.
- Private label cosmetics expansion:Contract manufacturers serving supermarket and pharmacy chains are scaling semi-automatic capacity to accommodate SKU proliferation.
- India PLI scheme incentives:Domestic machinery producers are capturing procurement previously directed toward imported European systems.
Market Restraints
- Stainless steel price volatility:Grade 304 and 316 input costs swing unpredictably, squeezing fabricator margins on fixed-price contracts.
- European vendor concentration:Hydraulic press technology and precision die manufacturing remain concentrated among northern Italian and German suppliers.
- Manual labor substitution ceiling:Irregular soap bar shapes and artisanal batch sizes resist full automation, capping throughput gains.
Strategic Opportunities
- United States craft soap segment:Small-batch organic producers in Colorado, Vermont, and Oregon lack access to mid-scale equipment between manual presses and industrial lines.
- CE marking plus FDA dual certification:Equipment validated for both regulatory regimes commands premium positioning in transatlantic contract manufacturing.
- Electric-pneumatic hybrid architectures:Converging servo motor precision with pneumatic cost structures opens new price-performance tiers.
Industry Challenges
- Multi-jurisdiction validation timelines:Simultaneous FDA cosmetic GMP documentation and CE technical file preparation extends sales cycles by 6-12 months.
- Legacy hydraulic integration:Retrofitting digital control systems into 1980s-1990s installed base requires proprietary adapter engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soap Stamping Machine Market |
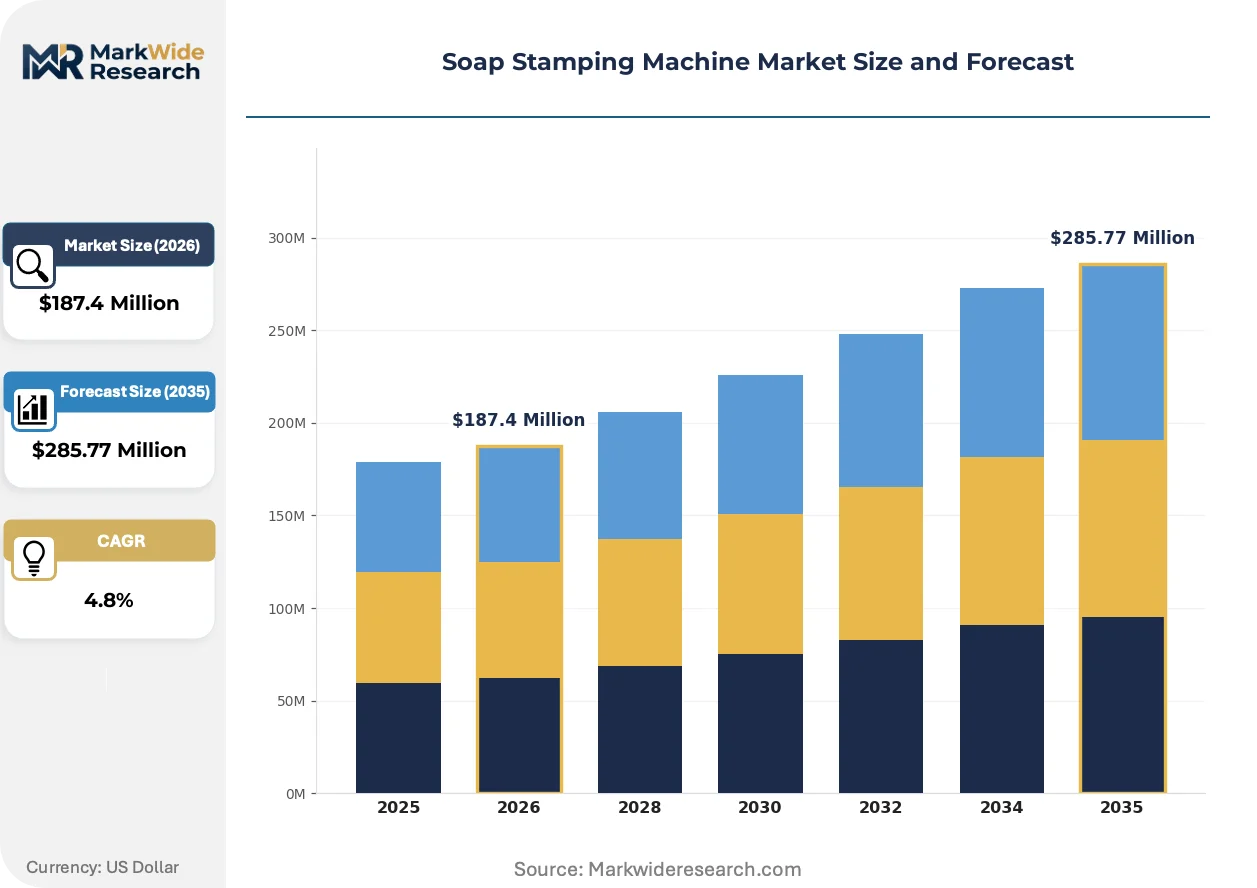
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Machines, Semi-Automatic Machines, Fully Automatic Machines, Custom Machines End User: Soap Manufacturers, Cosmetics Companies, Contract Manufacturers, Private Label Brands Technology: Pneumatic, Hydraulic, Mechanical, Electric Capacity: Small Scale, Medium Scale, Large Scale, Industrial Scale |
| Companies Covered | Adhisakthi Projects Private Limited, FusionTech International, Sakun Engineers, Amarnath Engineering, Binacchi, SMALL SOAP MACHINES, Kailash Engineering Works, Rameshwar Steel Fab, Mazzoni LB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soap Stamping Machine Market Trends and Innovations
Equipment architecture is splitting between precision electric systems for premium cosmetic applications and ruggedized pneumatic units for emerging market volume production. This technical divergence is reshaping supplier specialization and R&D allocation across the vendor base.
Servo-electric stamping technology is bifurcating the installed base. These systems deliver repeatable pressure curves within 0.5% variance, enabling intricate embossing on shea and glycerin formulations. Luxury hotel amenity suppliers and boutique skincare brands in France and Japan are adopting electric units at 15-20% annual replacement rates. The technology is compressing demand for entry-level hydraulic presses while creating premium pricing tiers for precision-engineered equipment.
REACH Annex XVII restrictions on nickel release are forcing die surface treatment upgrades. Chromium plating and PVD coating processes now dominate European-bound equipment specifications. Italian machinery exporters are absorbing certification costs into base pricing, while Indian competitors face margin pressure from third-party surface finishing requirements. Cosmetic GMP validation documentation has become a standard tender requirement for US pharmaceutical contract manufacturers.
Equipment-as-a-service models are displacing outright purchase in mid-scale operations. Monthly fee structures covering maintenance, die storage, and software updates are penetrating the United States and United Kingdom craft soap segments. California and Texas-based equipment lessors are building captive die libraries to accelerate customer onboarding. This financing innovation is most visible among 2,000-10,000 bar per day producers seeking to preserve working capital for ingredient and packaging investments.
Soap Stamping Machine Market Segmentation
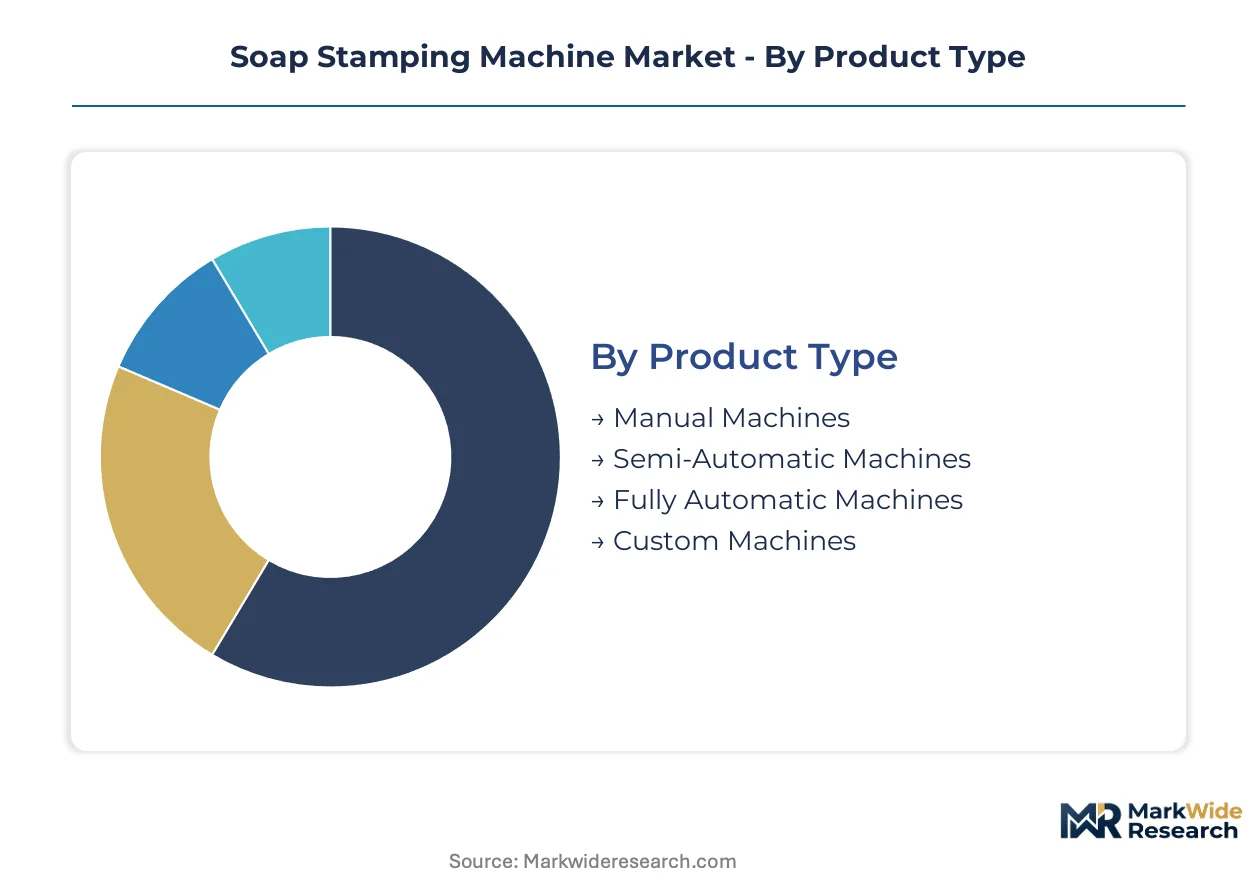
Segmentation in soap stamping equipment reveals how regulatory pressure and production scale reshape procurement patterns. Buyers sort across automation level, end-use application, and power technology based on validation requirements and batch economics.
Product Type:
CE marking and FDA cosmetic GMP validation timelines diverge sharply across automation tiers, with documentation burden scaling inversely to manual content.
- Fully Automatic Machines:Continuous rotary presses with servo-controlled die positioning process 3,000-5,000 bars hourly. Large-scale Indian and Italian contract manufacturers favor these for supermarket private label runs where throughput amortizes validation costs.
- Semi-Automatic Machines:Operator-fed systems with pneumatic or hydraulic actuation deliver 800-2,500 bars per hour with 15-minute die changeover. Colorado and Vermont craft soap workshops are expanding orders for these units to balance labor costs against batch flexibility.
- Manual Machines:Lever-operated benchtop presses suit sub-500 bar daily output with minimal capital outlay.
- Custom Machines:Bespoke die geometries and rapid tooling systems serve boutique organic brands requiring unique embossing patterns.
Fully automatic systems handle the majority of throughput; custom machines are expanding most quickly on share as artisanal brands proliferate.
End User:
Customer procurement authority varies by whether equipment serves captive production or toll manufacturing, with contract manufacturers imposing stricter validation documentation.
- Contract Manufacturers:Third-party producers serving supermarket and pharmacy chains operate multi-SKU lines requiring rapid changeover and dual FDA-REACH certification. These buyers concentrate in northern Italy and Mumbai, where machinery clusters support export-oriented validation expertise.
- Private Label Brands:Supermarket and pharmacy chains sourcing toll production demand equipment with documented cleanability and batch traceability. Their procurement is fragmenting toward semi-automatic configurations to accommodate SKU proliferation without full automation economics.
- Soap Manufacturers:Integrated producers with captive brands prioritize throughput and die longevity over flexibility.
- Cosmetics Companies:Skincare and hotel amenity suppliers favor electric precision systems for glycerin and shea formulations.
Contract manufacturers represent the steepest expansion trajectory; soap manufacturers retain the largest installed base.
Technology:
Power system selection increasingly tracks energy cost exposure and precision requirements rather than legacy hydraulic dominance.
- Electric:Servo motor drives with programmable pressure curves within 0.5% variance enable intricate embossing on soft formulations. French and Japanese luxury amenity suppliers are adopting these at accelerated replacement rates.
- Pneumatic:Compressed air systems offer lower capital cost and simpler maintenance for emerging market volume producers. Indian domestic manufacturers are capturing share with pneumatic lines optimized for local compressed air infrastructure.
- Hydraulic:High-force oil-pressure systems retain dominance in heavy-duty applications and legacy installed base.
- Mechanical:Cam-driven presses persist in lowest-cost manual and semi-automatic configurations.
Hydraulic technology anchors the installed base; electric systems are climbing the fastest on new order share.
Capacity:
Scale classification maps directly to labor substitution economics and the automation ceiling imposed by irregular artisanal batch sizes.
- Industrial Scale:Systems exceeding 3,000 bars per hour with continuous feed and automated packaging integration serve Unilever and Procter & Gamble tier producers. These installations concentrate in Maharashtra and Lombardy machinery corridors.
- Large Scale:1,500-3,000 bar hourly output with semi-automated downstream handling suits mid-tier contract manufacturers scaling private label operations.
- Medium Scale:500-1,500 bar daily capacity with manual loading and automatic stamping dominates Oregon and Texas craft soap equipment-as-a-service deployments.
- Small Scale:Sub-500 bar output with full manual operation persists in emerging market workshop clusters and hobbyist segments.
Industrial scale equipment processes the greatest volume; medium scale configurations are gaining share fastest through leasing models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Machinery fabrication clusters in India, Italy, and the United States supply the bulk of installed soap stamping capacity. Each concentration serves distinct demand profiles shaped by regulatory exposure and production scale economics.
India
Domestic soap manufacturers and export-oriented contract producers drive equipment procurement across Maharashtra and Gujarat. The PLI scheme for machinery manufacturing redirects public and private procurement toward local fabricators such as Adhisakthi Projects and Kailash Engineering Works. Mumbai and Ahmedabad host dense supplier networks serving both Indian consumer brands and Middle Eastern export markets.
Italy
Precision hydraulic press technology and REACH-compliant surface finishing capabilities anchor Italian competitiveness. Mazzoni LB and Binacchi supply European cosmetics companies and pharmaceutical contract manufacturers with validated equipment. Northern Italian machinery corridors around Milan and Bologna concentrate die engineering expertise and CE marking documentation services.
United States
Craft soap producers in Colorado, Vermont, and Oregon generate demand for mid-scale semi-automatic configurations between manual presses and industrial lines. FDA cosmetic GMP validation requirements shape procurement documentation for equipment serving pharmaceutical contract manufacturers. Equipment-as-a-service models are penetrating the 2,000-10,000 bar per day segment in California and Texas.
Germany
Industrial automation suppliers serve large-scale detergent and personal care manufacturers with integrated rotary press systems. German engineering standards influence specification templates across European procurement. Stuttgart and Düsseldorf machinery exhibitors set technical benchmarks for precision die positioning and servo-controlled pressure curves.
Japan
Luxury hotel amenity suppliers and boutique skincare brands adopt electric stamping systems for glycerin and shea formulations. METI energy efficiency guidelines accelerate replacement of legacy pneumatic units in cosmetics applications. Osaka and Nagoya equipment distributors specialize in precision-engineered systems for premium cosmetic embossing.
Soap Stamping Machine Market Competitive Landscape
Concentration sits with mid-scale regional fabricators serving distinct geographic demand pools. The vendor base splits between Indian domestic producers capturing PLI-incentivized procurement, Italian precision engineering specialists, and export-oriented generalists spanning multiple continents. Three archetypes dominate: regulatory compliance specialists, cost-optimized volume producers, and flexible configuration providers serving artisanal batch requirements. Competitive dynamics center on dual-certification capability for transatlantic contract manufacturing and equipment-as-a-service financing innovation.
Among Indian fabricators, Adhisakthi Projects Private Limited and Kailash Engineering Works exemplify the PLI-scheme beneficiary archetype. FusionTech International occupies a position as an export-oriented generalist spanning multiple continents. Mazzoni LB anchors the European precision engineering tier. Sakun Engineers represents the emerging market workshop specialist configuration. These named entities serve as reference points for understanding how geographic origin and organizational structure map to competitive positioning without asserting specific strategic actions or market shares.
| Leading Market Players |
|---|
| Adhisakthi Projects Private Limited |
| FusionTech International |
| Sakun Engineers |
| Amarnath Engineering |
| Binacchi |
| SMALL SOAP MACHINES |
| Kailash Engineering Works |
| Rameshwar Steel Fab |
| Mazzoni LB |
| Others |
Pricing and Supply Chain Analysis
Rotary press throughput economics at 3,000-5,000 bars hourly anchor pricing power among Indian and Italian machinery clusters, compressing margins for sub-scale fabricators while elevating floor prices for REACH-compliant surface finishing. This scale concentration funnels procurement toward Maharashtra and Lombardy corridors, where die engineering density validates premium positioning for dual-certified equipment.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates servo-electric precision systems from pneumatic mid-range units and legacy hydraulic base configurations. Price differentiation hinges on CE-FDA dual certification status and die changeover speed, with validation documentation costs compressing margins on economy tiers. Pricing pressure stems from Indian PLI-scheme domestic producers capturing mid-market share with simplified pneumatic architectures. Contract manufacturers in northern Italy show least price sensitivity due to amortization across high-volume private label runs, while Colorado craft workshops exhibit acute sensitivity to capital outlay.
Supply Chain Analysis
Inventory lead times for Grade 304 and 316 stainless steel fluctuate with commodity exchange volatility, forcing fabricators toward just-in-time sourcing or buffer stock strategies. Die manufacturing concentrates in Italy, Germany, and India, with precision hydraulic press components drawing from northern Italian supplier networks. Supply chain risk centers on single-source vulnerability for servo motor drives sourced from Japanese distributors. Distribution runs through machinery exhibition corridors—Milan, Mumbai, Stuttgart—where specification templates and validation documentation transfer alongside equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dual-certification engineering capability—simultaneous CE marking and FDA cosmetic GMP validation—represents the binding constraint limiting vendor expansion, with documentation timelines extending sales cycles beyond smaller competitors' working capital endurance.
For Market Incumbents: Shield installed base relationships by retrofitting digital control adapters for 1980s-1990s hydraulic presses, capturing upgrade revenue while blocking pneumatic new entrants. Deepen backward integration into die surface finishing—chromium plating and PVD coating—to absorb REACH Annex XVII compliance costs internally and deny margin to third-party finishers. For New Entrants and Emerging Players: Differentiate on rapid die changeover architecture for the 2,000-10,000 bar per day craft segment in Oregon, Vermont, and Colorado, where equipment-as-a-service financing gaps persist. Penetrate the United States mid-scale market through captive die library partnerships with California and Texas-based lessors, offering monthly fee structures that preserve customer working capital for ingredient investments. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors electric-pneumatic hybrid specialists with validated servo precision and emerging-market cost structures. Long-term viability rests on transatlantic dual-certification capability and equipment-as-a-service financing infrastructure. Monitor FDA cosmetic GMP documentation backlog as inflection signal—queue lengthening indicates accelerating contract manufacturer procurement, while clearance acceleration suggests market saturation.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | CE-FDA simultaneous validation captures transatlantic contract manufacturing premiums in Italy and India. |
| Equipment-as-a-Service Launch | Monthly fee structures with captive die libraries penetrate California and Texas craft soap capital constraints. |
| Die Surface Finishing Integration | In-house chromium plating and PVD coating absorbs REACH Annex XVII costs for European-bound exports. |
| Servo-Electric Hybrid Development | Converging precision control with pneumatic cost structures opens mid-market price-performance tiers. |
| Retrofit Adapter Engineering | Digital control integration for legacy hydraulic installed base blocks pneumatic substitution threats. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of trade customs data, machinery exhibition disclosures, and regulatory filing databases. Interviews with plant engineers at Indian and Italian contract manufacturers, procurement leads at United States craft soap workshops, and aftermarket service heads at European precision engineering firms informed demand segmentation. Secondary validation drew from BIS machinery safety standards documentation, FDA cosmetic GMP guidance publications, and REACH Annex XVII restriction updates. Bottom-up equipment shipment tallies triangulated against top-down soap production capacity estimates across Maharashtra, Lombardy, and Colorado clusters.
Segmentation dimensions modeled include automation tier, power technology, production capacity scale, and end-use application across the projection horizon. CAGRs derive from regression against validated installation bases and replacement cycle assumptions, with electric system adoption curves and PLI-scheme procurement shifts as industry-specific inputs. The analytical framework weights regulatory compliance burden against throughput economics for each configuration tier.
Forecasts assume regulatory continuity in REACH, FDA cosmetic GMP, and India's PLI scheme; material policy shifts would require re-modeling. Stainless steel commodity volatility and multi-jurisdiction validation timeline extensions represent specific revision risks. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Global Vial Cap Sealing Machines Market
Packaging Machinery
Toilet Roll Converting Lines Market
Packaging Machinery
Blown Film Extrusion Machine Market
Packaging Machinery
Binding & Lamination Machines Market
Packaging Machinery
CCL Laminating Machine Market
Packaging Machinery
Poly Bagging Machines Market
Packaging Machinery
Paper Embossing Machine Market
Packaging Machinery
Sack Fillers Market
Packaging Machinery
Corrugated Paper Machine Market
Packaging Machinery
Folder Gluer Machines Market
Packaging Machinery
Induction Sealing Machine Market
Packaging Machinery
Bottle Capping Machines Market
Packaging Machinery
Packaging Conveyors Market
Packaging Machinery
Tray and Sleeve Packing Machines Market
Packaging Machinery
Strapping Machine Market
Packaging Machinery
Tissue Paper Unwinding Machine Market