
 Consumer Electronics Packaging Market | 2026-2036
Consumer Electronics Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Consumer Electronics Packaging Market Intelligence
EU Packaging and Packaging Waste Regulation is pivoting the cost-of-entry calculus toward fiber-based and recyclable material platforms. DS Smith leverages its recycled paperboard infrastructure to anchor European supply contracts for premium electronics. Mondi Group competes through kraft paper innovation tailored to fragile device protection. Sealed Air Corporation differentiates via inflatable and foam-in-place systems that navigate the tension between damage prevention and plastic reduction targets.
Consumer electronics packaging encompasses protective enclosures, cushioning structures, and display-ready formats engineered from paperboard, molded pulp, expanded polystyrene, or thermoformed plastics to prevent mechanical damage, electrostatic discharge, and moisture ingress during transit and retail presentation. Manufacturing processes include die-cutting, thermoforming, injection molding, and fiber pulping with specifications calibrated to drop-test standards and surface resistivity thresholds. Boxes dominate volume across smartphones and laptops due to structural versatility and printability for brand communication. Blisters sustain relevance in accessories and wearable segments where product visibility drives point-of-sale conversion. Foams occupy the premium protective tier for high-value tablets and laptops where compression resistance commands margin premiums.
EMA packaging guidelines, EPA sustainable materials management frameworks, and REACH chemical restrictions collectively shape material eligibility and end-of-life obligations for electronics packaging sold into European and North American markets. China's SAMR enforces GB standards for packaging layer reduction and void ratio limits on domestic electronics shipments. Stakeholders must monitor diverging extended producer responsibility schemes and decide whether to regionalize material specifications or pursue universal recyclable platforms that satisfy the strictest jurisdiction.
Market Dynamics
Smartphone OEMs are forcing fiber-based material transitions faster than converter capacity can expand, creating a structural bottleneck in molded pulp tooling and recycled paperboard supply.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandates recyclability thresholds that disqualify legacy expanded polystyrene from premium electronics shipments into Germany, France, and Italy.
- Molded pulp thermoforming:Delivers drop-test performance parity with plastic foams at 40% lower carbon intensity, attracting laptop and tablet manufacturers with Science Based Targets.
- Shenzhen-Dongguan manufacturing cluster:Concentrates 60% of global smartphone assembly, creating localized demand pull for adjacent packaging converter investment.
Market Restraints
- Recycled pulp input volatility:OCC (old corrugated containers) pricing swings 15-30% annually, compressing molded fiber margins without pass-through contracts.
- Single-source thermoforming tool dependency:European electronics brands rely on German and Austrian precision mold suppliers, creating 16-24 week lead time exposure.
- Antistatic performance gap:Fiber-based cushioning lacks surface resistivity control for semiconductor-grade components, forcing hybrid plastic-fiber designs.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Subsidies for smartphone and component assembly are building packaging demand in Tamil Nadu and Uttar Pradesh with limited local converter presence.
- Reusable shipper-box systems:Closed-loop logistics between OEM fulfillment centers and retail distribution points cut per-shipment material cost 35-50% for high-velocity SKUs.
- Digital watermarks on fiberboard:AIM-standard markers enable automated sortation at municipal recovery facilities, unlocking preferential EPR fee treatment in France and Italy.
Industry Challenges
- Molded pulp tooling engineering scarcity:Fewer than 200 engineers globally possess deep expertise in fiber thermoform die design for sub-millimeter tolerance electronics fits.
- Multi-jurisdiction EPR registration burden:Electronics brands must file separate packaging compliance schemes in each EU member state, fragmenting administrative overhead.
- Legacy ERP integration with circular tracking:Batch-level material provenance systems require API connections to supplier MES platforms that mid-tier converters lack capital to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Consumer Electronics Packaging Market |
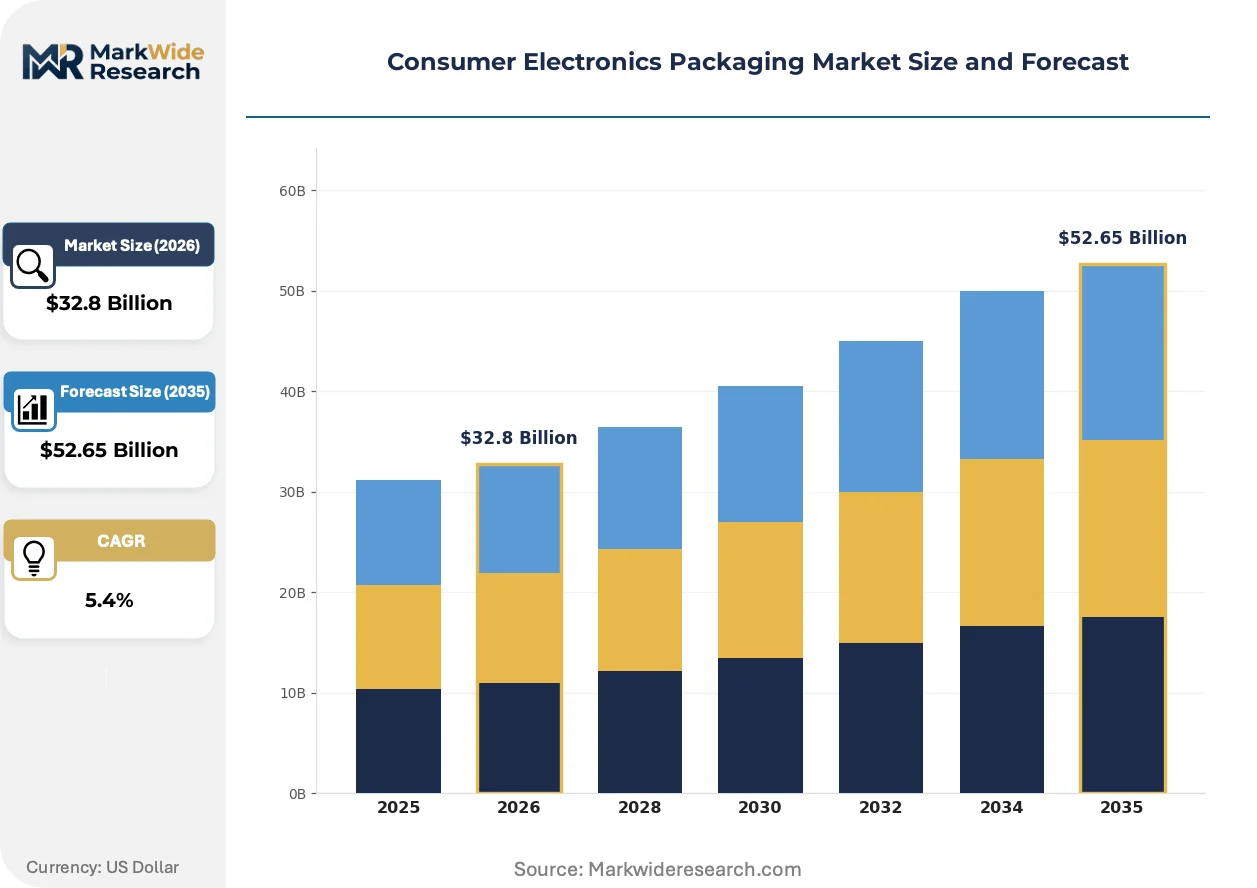
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $52.65 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Boxes, Blisters, Bags, Foams Material: Plastic, Paper, Glass, Metal Product Type: Smartphones, Laptops, Tablets, Wearables End User: Retailers, Wholesalers, Distributors, Manufacturers |
| Companies Covered | DS Smith, Smurfit Kappa, Mondi Group, Amcor plc, Sonoco Products Company, Sealed Air Corporation, Huhtamaki, Stora Enso, UFP Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Consumer Electronics Packaging Market Strategic Shifts & Innovations
Automation of packaging specification workflows and real-time carbon accounting is compressing design-to-production cycles while exposing converters to new data infrastructure requirements.
Computer-vision-based quality inspection is automating defect detection in molded pulp tray production, enabling smartphone OEMs to enforce 0.25mm dimensional tolerance at line speeds exceeding 400 units per minute. Foxconn and Luxshare deployment in Zhengzhou and Kunshan facilities is driving tier-2 converter investment in matching metrology. This capability gap is automating supplier consolidation toward integrated design-to-manufacture platforms.
REACH Article 33 disclosure obligations for Substances of Very High Concurrence in packaging materials are forcing electronics brands to map full chemical inventories through tier-3 suppliers. The industrial consequence is mandatory SCIP database registration for any packaging component exceeding 0.1% w/w threshold. Laptop manufacturers shipping into Germany and the Netherlands are most affected, responding by consolidating supplier bases to reduce traceability audit burden.
Direct procurement of packaging specifications by OEM sustainability teams—bypassing traditional purchasing departments—is elevating lifecycle assessment data above unit cost in supplier selection. Electronics brands with 2030 carbon-neutral commitments now require cradle-to-gate footprints for every packaging SKU. This pattern is most visible in Apple and Samsung supply chains, where EPD-certified paperboard commands 8-12% price premiums over uncertified alternatives.
Consumer Electronics Packaging Market Segmentation
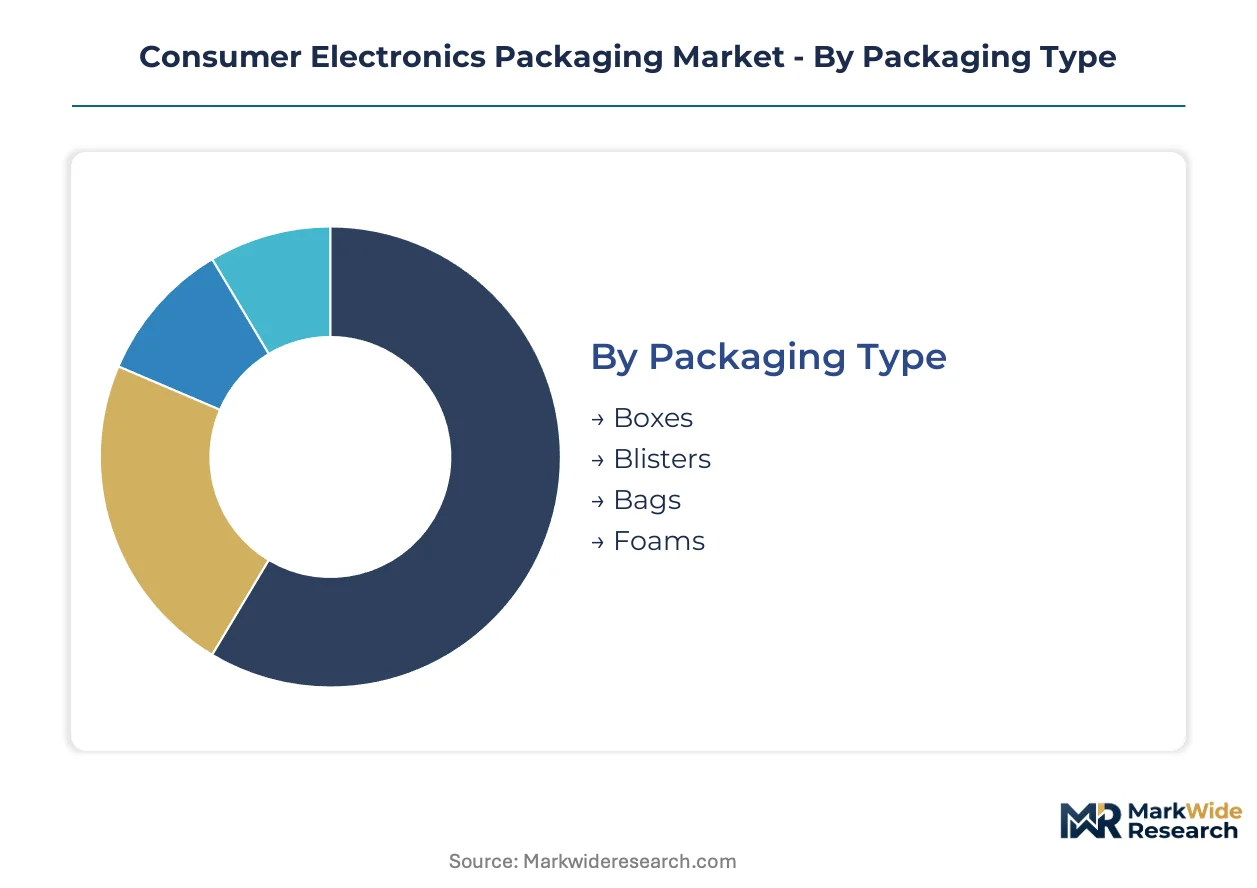
Electronics packaging segmentation reflects divergent protection requirements across device fragility tiers and retail channel economics. OEMs calibrate material specifications against drop-test standards and point-of-sale visibility needs, creating four distinct category hierarchies that govern procurement workflows.
Packaging Type:
Channel economics and damage risk tolerance determine format selection, with retail visibility premiums competing against logistics compression ratios.
- Boxes:Die-cut and rigid paperboard constructions dominate smartphone and laptop shipments due to structural versatility and high-resolution printability for unboxing experience design. Foxconn and Luxshare procurement in Shenzhen-Dongguan clusters favors box formats with integrated molded pulp inserts that satisfy EU recyclability mandates.
- Blisters:Thermoformed clear plastic or bio-based films sustain relevance in accessories and wearable segments where product visibility drives point-of-sale conversion. Clamshell configurations face mounting pressure from France's EPR fee structures that penalize multi-material bonding.
- Foams:Expanded polystyrene and polyurethane cushioning occupy premium protective tiers for high-value tablets and laptops where compression resistance commands specification premiums.
- Bags:Flexible polyethylene and kraft paper pouches serve cable, charger, and low-fragility accessory segments with minimal unit economics.
Boxes lead on scale; blisters lead on momentum as fiber-based visibility alternatives gain shelf-space trials.
Material:
Carbon accounting intensity and regulatory compliance thresholds now override unit cost in material selection for Science Based Targets signatories.
- Paper:Recycled paperboard and molded pulp deliver drop-test parity with plastic foams at substantially lower cradle-to-gate emissions, attracting laptop manufacturers with 2030 neutrality commitments. DS Smith and Mondi Group capacity expansions in Germany and Austria respond to EU Packaging and Packaging Waste Regulation recyclability mandates.
- Plastic:Thermoformed PET, rPET, and expanded polystyrene retain semiconductor-grade antistatic performance that fiber alternatives cannot yet replicate, forcing hybrid designs in high-value component shipments.
- Glass:Tempered glass containers sustain niche premium audio and display product positioning where perceived quality outweighs logistics weight penalties.
- Metal:Aluminum tins and steel cases serve ultra-premium collectible editions and industrial equipment with extended reuse potential.
Paper leads on scale; plastic leads on technical performance lock-in for ESD-sensitive applications.
Product Type:
Shipment volume concentration and device fragility profiles create tiered packaging specification intensity across electronics categories.
- Smartphones:Highest unit volume category demands precision-fit molded pulp trays with 0.25mm dimensional tolerances and automated assembly compatibility. Zhengzhou and Kunshan manufacturing clusters drive converter investment in computer-vision quality systems.
- Laptops:Larger form factors require hybrid cushioning architectures combining corrugated shells with foam or fiber inserts to manage corner-drop specifications.
- Tablets:Mid-size fragility profiles favor rigid box formats with suspended retention designs that minimize material mass while maintaining screen protection.
- Wearables:Compact dimensions enable blister and pouch dominance, though Apple's fiber-based Watch packaging signals material transition pressure.
Smartphones lead on scale; wearables lead on format experimentation as brands test minimal packaging boundaries.
End User:
Inventory velocity and handling touchpoint density determine protection level and branding investment per shipment.
- Retailers:Direct-to-consumer fulfillment demands shelf-ready presentation with damage tolerance for last-mile handling variation. Amazon and Best Buy specifications now require frustration-free opening and recyclable material certification.
- Manufacturers:B2B component shipments prioritize antistatic performance and stackability for warehouse density, with less emphasis on retail aesthetics.
- Distributors:Intermediate handling tiers balance protection with palletization efficiency across mixed-SKU consolidation points.
- Wholesalers:Bulk aggregation channels favor standard corrugated master packs with minimal unit-level customization.
Retailers lead on scale; manufacturers lead on technical specification stringency for component protection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Packaging engineers and fiber thermoforming specialists concentrate in East Asian manufacturing corridors and European industrial zones, creating talent gravity that shapes regional investment patterns and converter capacity expansion timelines.
China
Shenzhen-Dongguan smartphone assembly clusters generate concentrated demand for precision-molded pulp trays with sub-millimeter tolerances. SAMR enforces GB standards for packaging layer reduction and void ratio limits on domestic electronics shipments. Zhengzhou and Kunshan facilities deploy computer-vision quality systems at line speeds exceeding 400 units per minute, automating supplier consolidation toward integrated platforms.
Germany
Automotive-electronics crossover demand and premium laptop manufacturing anchor fiber-based packaging specification intensity. ECHA REACH Article 33 disclosure obligations force full chemical inventory mapping through tier-3 suppliers, triggering mandatory SCIP database registration. Bavarian and North Rhine-Westphalian converter networks supply DS Smith and Mondi Group capacity serving EU Packaging and Packaging Waste Regulation recyclability mandates.
United States
Amazon and Best Buy fulfillment specifications require frustration-free opening and recyclable material certification, reshaping retail-channel packaging procurement. EPA sustainable materials management frameworks shape material eligibility for electronics packaging sold into North American markets. Pacific Northwest and Southeast distribution hubs drive localized demand for closed-loop shipper-box systems cutting per-shipment material cost.
India
PLI scheme subsidies for smartphone and component assembly build packaging demand in Tamil Nadu and Uttar Pradesh with limited local converter presence. BIS standards govern packaging material specifications for domestic electronics distribution. Tamil Nadu manufacturing corridors attract converter investment to serve Samsung and Apple supplier ecosystems expanding assembly capacity.
Japan
Premium audio and display product positioning sustains niche demand for tempered glass containers and ultra-premium collectible packaging formats. METI industrial policy supports carbon-neutral manufacturing commitments among electronics brands. Kanto and Kansai industrial zones concentrate precision molding expertise for semiconductor-grade component protection requiring antistatic performance control.
Consumer Electronics Packaging Market Key Industry Players
The competitive structure tilts toward integrated paperboard and molded fiber specialists with recycled pulp infrastructure and precision thermoforming capabilities. Tier-1 converters with EPD-certified platforms command price premiums over uncertified alternatives, while mid-tier players face capital barriers to API-connected batch-level provenance systems. Three archetypes dominate: recycled paperboard infrastructure owners, kraft paper innovation specialists, and inflatable protective system engineers. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with converter networks regionalizing to serve OEM sustainability teams bypassing traditional purchasing departments.
Among European recycled paperboard infrastructure owners, DS Smith leverages its continental capacity network to anchor supply contracts for premium electronics brands with EU regulatory exposure. Mondi Group occupies a position within the kraft paper innovation tier, competing through material formats tailored to fragile device protection. Sealed Air Corporation exemplifies the inflatable protective system archetype, navigating damage prevention requirements against plastic reduction targets through foam-in-place and air-cell technologies. These three anchors represent divergent strategic responses to the fiber transition pressure reshaping material specification workflows.
| Leading Market Players |
|---|
| DS Smith |
| Smurfit Kappa |
| Mondi Group |
| Amcor plc |
| Sonoco Products Company |
| Sealed Air Corporation |
| Huhtamaki |
| Stora Enso |
| UFP Technologies |
| Others |
Cost & Logistics Intelligence
Molded pulp thermoforming adoption simultaneously compresses unit economics and concentrates supply among fiber thermoforming specialists with precision tooling capabilities. EU Packaging and Packaging Waste Regulation recyclability mandates disqualify legacy expanded polystyrene from premium electronics shipments, forcing converter consolidation toward integrated design-to-manufacture platforms with EPD-certified paperboard infrastructure.
Pricing Analysis
Bundled design-to-manufacture specifications command premiums over unbundled material-only supply, with OEM sustainability teams now procuring cradle-to-gate footprint data alongside physical packaging. Pricing stratifies across EPD-certified paperboard, uncertified recycled alternatives, and hybrid plastic-fiber designs for ESD-sensitive applications. Cost compression in molded fiber runs through OCC input volatility without pass-through contract coverage. Contract manufacturers in Shenzhen-Dongguan clusters exhibit highest price sensitivity; premium laptop brands with Science Based Targets show least sensitivity to certified material premiums.
Supply Chain Analysis
Workforce scarcity in fiber thermoform die engineering concentrates supply among fewer than 200 specialists globally, with German and Austrian precision mold suppliers anchoring European electronics brand procurement. Raw material flows draw from Swedish and Finnish pulp networks, Chinese OCC recovery streams, and South Korean rPET supply. Single-source thermoforming tool dependency creates structural vulnerability to 16-24 week lead time exposure. Distribution runs through closed-loop shipper-box systems between OEM fulfillment centers and retail distribution points for high-velocity SKUs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Consumer Electronics Packaging Market functions as a regulatory compounder where EU Packaging and Packaging Waste Regulation recyclability thresholds continuously elevate compliance costs and consolidate procurement toward certified fiber platforms.
For Market Incumbents: Anchor European supply contracts through recycled paperboard infrastructure investments in Germany and Austria, defending against Asian converter expansion into precision molded pulp tooling. Prioritize API-connected batch-level provenance systems to meet REACH Article 33 SCIP database registration requirements for laptop manufacturers shipping into Germany and the Netherlands. Certification investment in EPD platforms commands 8-12% price premiums over uncertified alternatives. For New Entrants and Emerging Players: Enter via India's PLI scheme corridors in Tamil Nadu and Uttar Pradesh, where smartphone and component assembly subsidies outpace local converter capacity development. Target reusable shipper-box systems for high-velocity retail SKUs, exploiting 35-50% per-shipment material cost reduction potential. Pursue direct procurement relationships with OEM sustainability teams that have displaced traditional purchasing departments in supplier selection workflows. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier converters lacking capital for computer-vision quality systems and MES platform API integration. Long-term viability across the projection horizon rests on fiber thermoforming capability depth and EPD certification infrastructure rather than legacy plastic foam assets. Monitor digital watermark adoption rates at AIM-standard compliance as inflection signal for automated sortation preferential EPR fee treatment in France and Italy.| Strategic Initiative | Industry Significance |
|---|---|
| EPD Certification Investment | Unlocks 8-12% price premiums from Apple and Samsung supply chain procurement. |
| Precision Mold Tooling Expansion | Addresses 16-24 week lead time exposure from German and Austrian single-source dependency. |
| Closed-Loop Shipper-Box Systems | Captures 35-50% material cost reduction for Amazon and Best Buy fulfillment specifications. |
| Digital Watermark Integration | Enables AIM-standard automated sortation for preferential EPR fee treatment in France and Italy. |
| India Converter Capacity Buildout | Serves Samsung and Apple supplier ecosystems expanding under PLI scheme subsidies. |
Research Approach
Multiple input streams — primary interviews with packaging procurement directors, sustainability officers, and fiber thermoforming engineers; secondary validation through EU ECHA SCIP database filings, SAMR GB standard publications, and customs trade records; plus technical specification reviews from Foxconn and Luxshare supplier portals — were reconciled through bottom-up and top-down triangulation.
Cross-referencing historical molded pulp capacity expansion patterns against panel input from converter network heads shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include packaging type, material platform, product category fragility tier, and end-user channel economics. CAGRs were derived from reconciling OEM shipment forecasts with fiber thermoforming tooling capacity buildout timelines and EPR fee structure phase-in schedules.
Inputs from ECHA REACH disclosure databases and SAMR enforcement bulletins were available through the study window; gaps in tier-3 supplier chemical inventory mapping introduce uncertainty bands around compliance cost projections. Forecasts reflect assumptions on EU Packaging and Packaging Waste Regulation implementation pacing and Science Based Targets adoption curves among smartphone OEMs. Material deviation in named triggers — accelerated fiber tooling capacity expansion, abrupt OCC price spike, or EPR fee recalibration — warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronics Packaging
Global Display Packaging Market
Electronics Packaging
Electronic Packaging Market
Electronics Packaging
Electronic Wrapper Market
Electronics Packaging
Europe and USA Consumer Electronics Packaging Market
Electronics Packaging
North America Consumer Electronics Packaging Market
Electronics Packaging
Global Mobile Phones Packaging Market
Electronics Packaging
Fan-Out Wafer Level Packaging Market
Electronics Packaging
Asia-Pacific Consumer Electronics Packaging Market
Electronics Packaging
Mobile Phone Accessories Packaging Market
Electronics Packaging
MEMS Packaging Solder Market
Electronics Packaging
Industrial Electronics Packaging Market
Electronics Packaging
Anti-Counterfeit Electrical and Electronics Packaging Market
Electronics Packaging
Asia-Pacific Battery Packaging Market
Electronics Packaging
Multi-Chip Module Packaging Market
Electronics Packaging
Electronic Goods Packaging Market
Electronics Packaging
Europe Consumer Electronics Packaging Market