
 EPS Pre-Expander Machines Market | 2026-2036
EPS Pre-Expander Machines Market Size, Share, and Industry Trends Forecast 2026-2036
EPS Pre-Expander Machines Market Insights
Packaging manufacturers is collapsing into construction insulation specialists as the dominant buyer archetype for EPS pre-expander machines. Kurtz Ersa leverages its German engineering heritage to dominate high-precision continuous-type systems for automotive suppliers. Cannon Group anchors Mediterranean and Latin American markets through localized service networks and thermal process expertise. Hangzhou Epsole Technologies Co., Ltd. competes aggressively on cost-adjusted output for batch-type units serving China's domestic construction sector.
EPS pre-expander machines heat expandable polystyrene beads using pressurized steam at 100–120°C to achieve controlled volumetric expansion of 40–80 times original density before molding. The equipment regulates bead size distribution, moisture content, and bulk density to ensure uniform fusion in subsequent shape molding for protective packaging and thermal insulation blocks. Automatic type systems command the widest margin pools due to integrated PLC-controlled density feedback and labor substitution economics. Steam expansion technology leads installed capacity globally, though air expansion variants gain traction where boiler infrastructure is constrained or chemical sensitivity thresholds apply. Batch type configurations remain the mature volume base, while continuous type architectures represent the fastest-growing segment for high-throughput construction board producers.
China's SAMR enforces GB standards for styrene emissions and equipment energy labeling that filter market access for imported pre-expander systems. The EU Green Deal and REACH chemical registration requirements compel European manufacturers to validate bead expansion agents and document circularity pathways for end-of-life EPS. India's BIS certification mandates for plastics processing machinery create incremental compliance layers for subcontinent market entry. Stakeholders must monitor how fragmented national chemical regulations and divergent carbon accounting protocols reshape total cost of ownership calculations across equipment procurement decisions.
Market Dynamics
Steam boiler infrastructure constraints and tightening styrene emission thresholds are bifurcating equipment procurement decisions between steam-based and air-expansion architectures across packaging and insulation value chains.
Growth Catalysts
- Cold-chain logistics expansion:Pharmaceutical and fresh-food distribution networks in Germany and China's eastern coastal belt are mandating higher-performance thermal packaging, pulling batch-type pre-expander capacity additions.
- EU Green Deal packaging directives:REACH chemical registration requirements and circularity documentation mandates are filtering equipment specifications toward recyclable bead formulations and lower-emission expansion agents.
- Construction board automation:Continuous-type architectures are capturing share from batch systems as high-throughput insulation producers in China's manufacturing belt prioritize labor substitution and density uniformity.
Market Restraints
- Steam infrastructure dependency:Boiler installation costs and natural gas price volatility in European manufacturing clusters are compressing total cost of ownership calculations for steam-based systems.
- Styrene supply concentration:Expandable polystyrene bead production concentrates in Northeast Asian petrochemical complexes, exposing equipment buyers to feedstock logistics disruptions and currency fluctuation risk.
- Air expansion throughput ceilings:Thermal efficiency limitations of air-based expansion technologies constrain volumetric output rates for high-density construction board applications versus steam alternatives.
Strategic Opportunities
- India's BIS certification pipeline:Subcontinent plastics processing machinery standards are creating first-mover advantages for pre-expander vendors establishing localized compliance documentation and service networks.
- Automotive component lightweighting:German automotive suppliers are expanding molded EPS protective packaging for electric vehicle battery modules and precision electronics, opening specification windows for high-precision continuous systems.
- PLC-integrated density feedback:Convergence of process control automation with real-time moisture sensing is enabling outcome-based equipment contracting models that shift buyer risk to performance guarantees.
Industry Challenges
- Multi-jurisdiction chemical compliance:Equipment vendors must simultaneously validate expansion agents against China's GB standards, EU REACH registrations, and India's BIS plastics machinery mandates, stretching certification timelines.
- Legacy batch-to-continuous migration:Construction insulation specialists face integration complexity when retrofitting continuous-type pre-expanders into existing shape-molding lines designed around batch-process bead handling workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EPS Pre-Expander Machines Market |
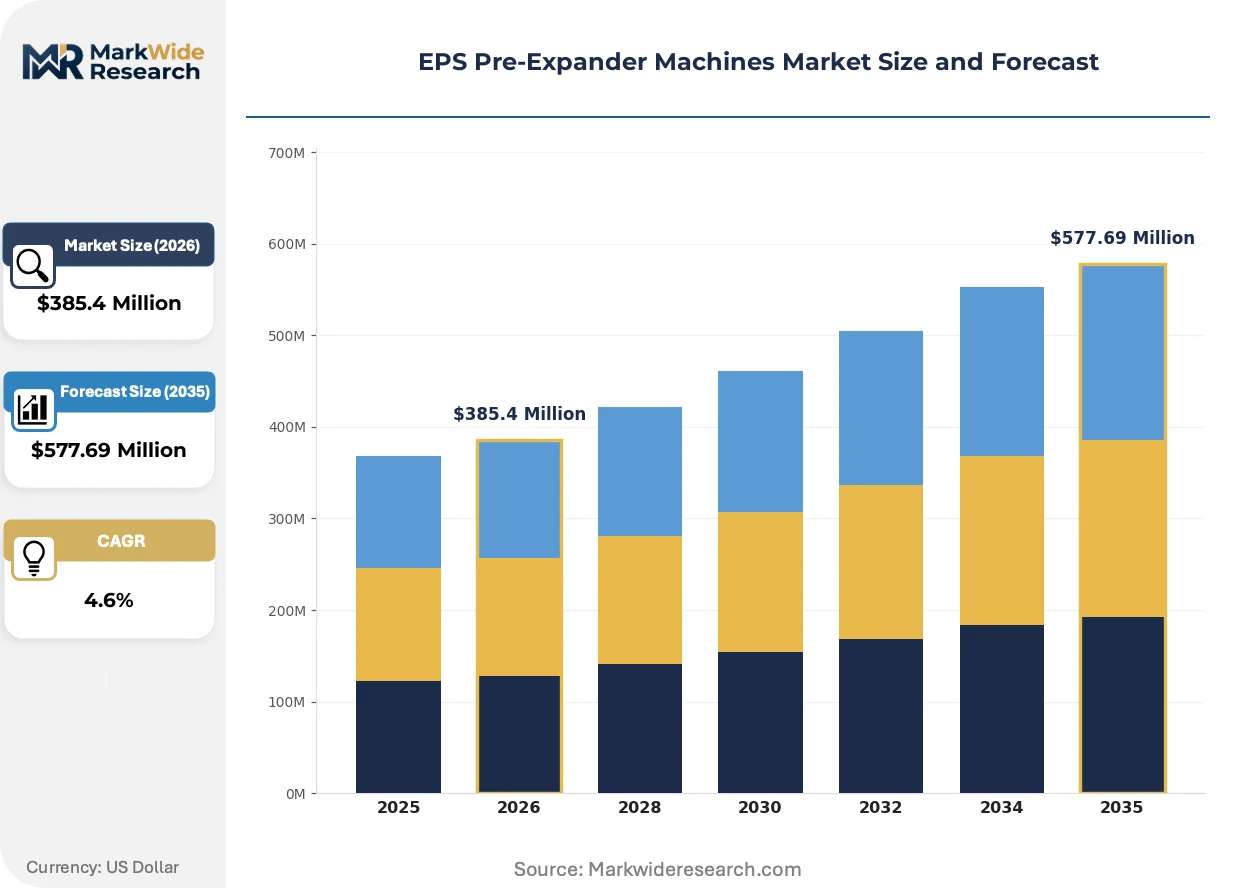
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $577.69 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Type, Continuous Type, Manual Type, Automatic Type End User: Manufacturers, Suppliers, Distributors, OEMs Technology: Steam Expansion, Chemical Expansion, Air Expansion, Mechanical Expansion Application: Packaging, Construction, Automotive, Insulation |
| Companies Covered | Hangzhou Bes Technology Co., Ltd., Cannon Group, Polystyron, DKM, Kurtz Ersa, PROMASS SRL, VIRO EPS-SYSTEMS, Hangzhou Sutuan Machinery Co., Ltd., Hangzhou Epsole Technologies Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EPS Pre-Expander Machines Market Trends and Innovations
Process control digitization and emission-monitoring integration are redefining equipment specification criteria, with buyers prioritizing traceability infrastructure over base mechanical throughput ratings.
Air expansion technology is decomposing the historical steam-dominance in pre-expander installed capacity. Pharmaceutical packaging manufacturers in Switzerland and medical device suppliers in Germany are piloting air-based systems to eliminate boiler infrastructure and reduce chemical sensitivity risks in cleanroom environments. This shift is compressing margin pools for traditional steam equipment vendors while opening specification windows for thermal process specialists with air-handling expertise.
China's SAMR energy labeling mandates for plastics processing machinery are forcing equipment redesign cycles. Manufacturers must now document per-bead energy consumption and validate expansion agent thermal efficiency under standardized test protocols. European pre-expander exporters face particular compliance friction as GB standards diverge from CE marking requirements on styrene emission thresholds during the expansion cycle.
Service unbundling is fragmenting traditional equipment procurement patterns. German automotive suppliers and Chinese construction board producers are separating pre-expander hardware purchases from installation, commissioning, and density calibration services. This pattern concentrates in high-volume continuous-type installations where buyers possess in-house thermal process engineering capabilities and prefer direct relationships with specialized calibration technicians over bundled OEM service contracts.
EPS Pre-Expander Machines Market Segmentation
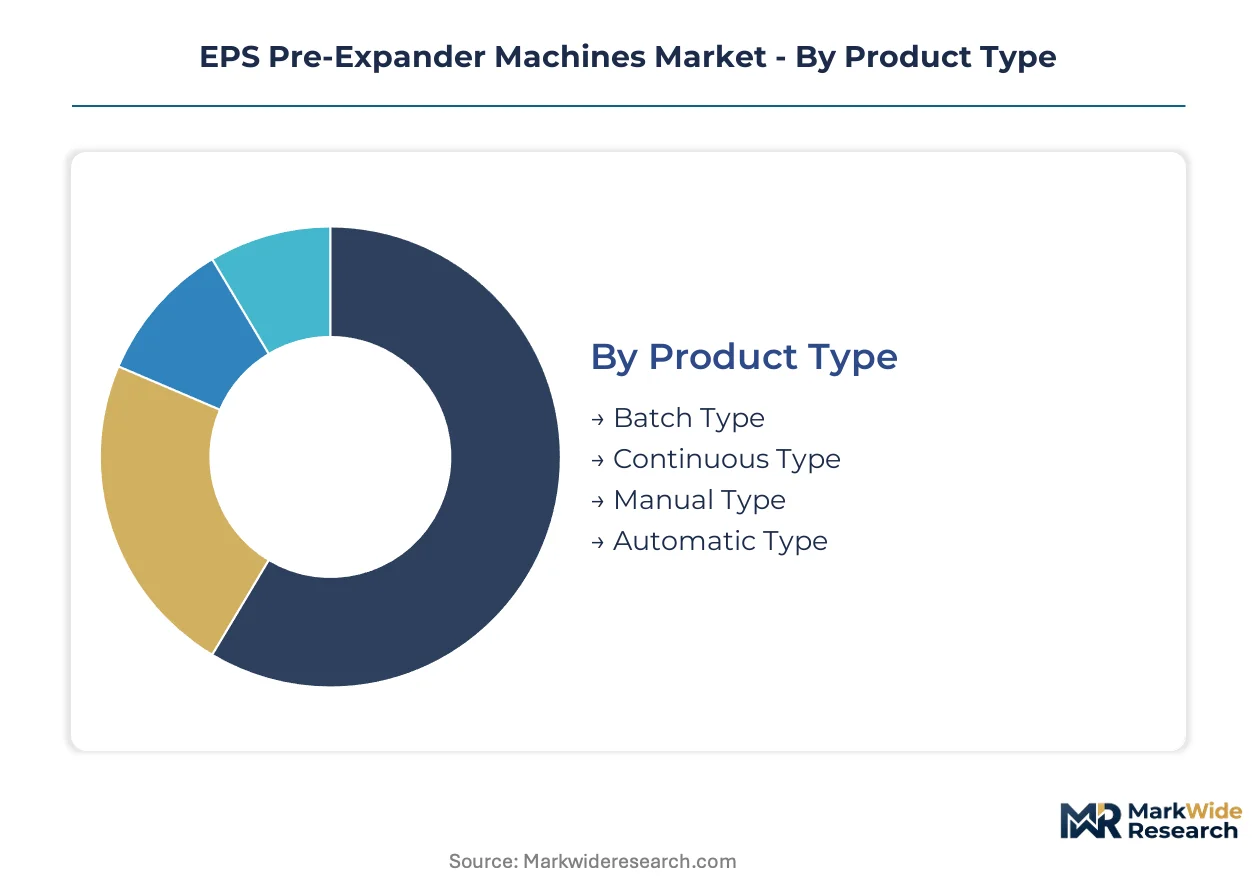
Segmentation in the EPS pre-expander machines market reveals how equipment specifications diverge across thermal process requirements, regulatory compliance burdens, and buyer engineering capabilities. Procurement patterns cluster sharply around automation levels and expansion technologies, with margin pools concentrating where density control precision intersects with high-throughput demand.
Product Type:
Margin pools concentrate in systems offering integrated process control and labor substitution economics, with automation tier driving the steepest price differentiation.
- Batch Type:These systems process discrete bead loads in cyclic operations, typically achieving 40-60 times volumetric expansion through controlled steam injection cycles. Packaging manufacturers in Germany's automotive component cluster and China's eastern coastal belt favor batch configurations for cold-chain thermal packaging where flexibility across bead grades outweighs throughput maximization.
- Continuous Type:Architectures enable uninterrupted bead flow through sequential expansion chambers, delivering superior density uniformity via real-time feedback loops. High-throughput construction board producers in China's manufacturing belt are migrating toward continuous systems to capture labor substitution savings and meet tightening EU Green Deal circularity documentation requirements for insulation materials.
- Manual Type:Entry-level configurations require operator intervention for loading, timing, and discharge sequences, serving small-scale distributors with limited capital budgets.
- Automatic Type:PLC-controlled systems integrate density sensing, moisture regulation, and automated discharge, commanding premium positioning where technical staffing constraints apply.
The dominant share belongs to Batch Type, while Continuous Type is closing the gap fastest.
End User:
Procurement authority concentrates with entities possessing in-house thermal process engineering capabilities and direct regulatory compliance accountability.
- Manufacturers:Integrated EPS shape-molding operations source pre-expanders as captive production assets, prioritizing density calibration precision for subsequent fusion processes. German automotive suppliers and Chinese construction insulation specialists dominate this tier, leveraging technical staff to unbundle hardware purchases from specialized commissioning services.
- OEMs:Original equipment manufacturers specify pre-expander modules for integration into complete EPS production lines, requiring standardized interfaces and documented energy efficiency under China's SAMR labeling mandates.
- Suppliers:Independent equipment vendors serve fragmented regional markets, often bundling installation and calibration services for buyers lacking process engineering depth.
- Distributors:Resale channels concentrate in emerging markets where localized service networks substitute for direct manufacturer presence.
Manufacturers capture the largest procurement volume, though OEMs are expanding specification influence fastest through integrated line contracting.
Technology:
Technology selection increasingly bifurcates between steam infrastructure availability and emission sensitivity thresholds across end-use environments.
- Steam Expansion:Pressurized steam at 100-120°C remains the dominant thermal medium, delivering optimal heat transfer efficiency for high-density construction board applications. Boiler infrastructure requirements constrain adoption in European manufacturing clusters facing natural gas price volatility, while China's eastern coastal belt maintains steam dominance through centralized industrial steam networks.
- Air Expansion:Thermal air systems eliminate boiler dependency and reduce chemical sensitivity risks, gaining traction among pharmaceutical packaging manufacturers in Switzerland and medical device suppliers in Germany operating cleanroom environments. Throughput ceilings versus steam alternatives limit penetration in high-density insulation applications.
- Chemical Expansion:Expansion agent formulations using volatile hydrocarbons serve niche applications where steam or air thermal profiles damage sensitive bead coatings.
- Mechanical Expansion:Physical agitation methods without thermal input address specialty low-temperature requirements, occupying minimal installed capacity.
Steam Expansion retains the dominant installed base, while Air Expansion is gaining specification momentum fastest in emission-sensitive segments.
Application:
Application mix determines bead density targets, moisture tolerance, and regulatory compliance intensity across equipment specifications.
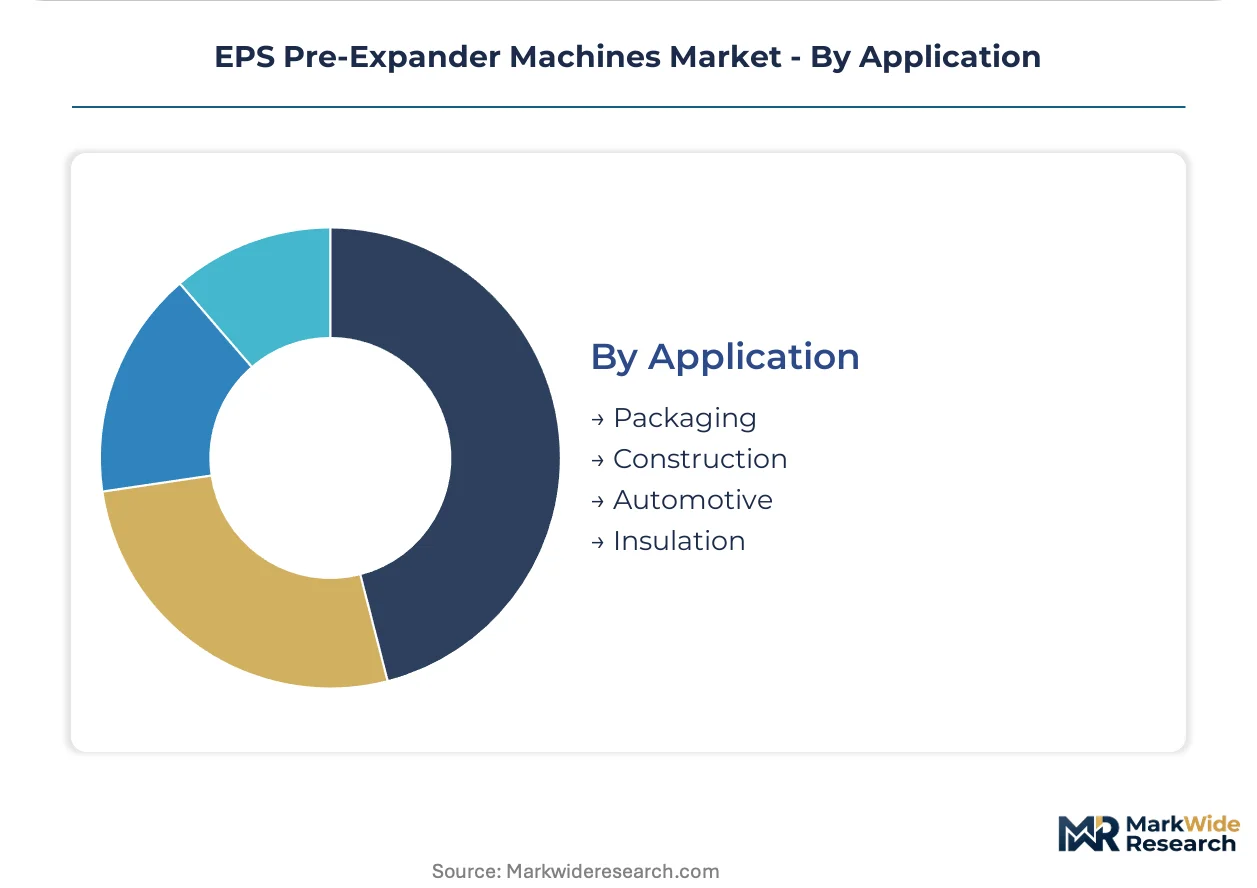
- Construction:Thermal insulation block production demands consistent bulk density for structural integrity, pulling continuous-type pre-expander adoption. China's construction board automation drive and EU Green Deal packaging waste directives are reshaping equipment specifications toward recyclable bead formulations and documented circularity pathways.
- Packaging:Protective molded shapes for cold-chain logistics require precise bead size distribution to ensure uniform fusion. German pharmaceutical distribution networks and Chinese fresh-food logistics are mandating higher-performance thermal packaging, expanding batch-type capacity additions.
- Automotive:Lightweight molded EPS protective packaging for electric vehicle battery modules and precision electronics requires high-precision density control, opening specification windows for advanced continuous systems among German automotive suppliers.
- Insulation:Specialty thermal barrier applications overlap with construction but emphasize fire-retardant bead formulations and expanded service temperature ranges.
Construction commands the dominant application share, while Automotive is climbing the fastest as electric vehicle production scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction insulation specialists and packaging manufacturers concentrate procurement authority in Germany, China, and Switzerland, with regulatory divergence across SAMR, EU Green Deal, and REACH frameworks reshaping equipment specifications.
Germany
Automotive suppliers in Bavaria and Baden-Württemberg are expanding molded EPS protective packaging for electric vehicle battery modules. KBA vehicle safety standards and EU Green Deal circularity documentation mandates filter equipment specifications toward recyclable bead formulations. The automotive component cluster around Stuttgart anchors high-precision continuous-type pre-expander demand.
China
Construction board producers in the Yangtze River Delta and Pearl River Delta are automating batch-to-continuous system migrations. SAMR energy labeling mandates for plastics processing machinery enforce per-bead energy consumption documentation under GB standards. Hangzhou and Suzhou manufacturing belts concentrate domestic pre-expander fabrication capacity.
Switzerland
Pharmaceutical packaging manufacturers are piloting air-expansion systems to eliminate boiler infrastructure in cleanroom environments. Swissmedic medical device regulations and chemical sensitivity thresholds drive emission-monitoring integration specifications. Basel and Zurich clusters anchor thermal packaging demand for pharmaceutical distribution networks.
India
Construction insulation specialists in Maharashtra and Gujarat are evaluating pre-expander capacity additions as building code enforcement tightens. BIS certification mandates for plastics processing machinery create compliance documentation requirements for subcontinent market entry. The Mumbai-Pune industrial corridor concentrates early specification activity.
United States
Cold-chain logistics operators in the Midwest and Southeast are expanding thermal packaging capacity for fresh-food distribution networks. EPA styrene emission thresholds and OSHA workplace exposure limits shape equipment procurement criteria. Chicago and Atlanta distribution hubs anchor batch-type pre-expander demand for protective packaging applications.
EPS Pre-Expander Machines Market Competitive Landscape
Player mix skews toward European engineering heritage specialists and Chinese cost-adjusted fabricators, with mid-tier regional vendors filling service gaps. The structure concentrates around three strategic archetypes: precision-engineering continuous-system specialists, high-volume batch-type fabricators, and localized service-integrated regional players. Competitive moves center on geographic licensing partnerships for regulatory compliance documentation and backward integration into control system software development.
Among European precision-engineering specialists, Kurtz Ersa and Cannon Group occupy positions exemplifying high-precision continuous-system architecture. Kurtz Ersa anchors German engineering heritage positioning for automotive supplier specifications, while Cannon Group represents Mediterranean and Latin American market access through thermal process expertise. Hangzhou Epsole Technologies Co., Ltd. sits within the Chinese cost-adjusted fabricator tier, competing on output economics for domestic construction sector demand. These three companies illustrate how geographic origin and organizational structure map to distinct specification windows across automation tiers and expansion technologies.
| Leading Market Players |
|---|
| Hangzhou Bes Technology Co., Ltd. |
| Cannon Group |
| Polystyron |
| DKM |
| Kurtz Ersa |
| PROMASS SRL |
| VIRO EPS-SYSTEMS |
| Hangzhou Sutuan Machinery Co., Ltd. |
| Hangzhou Epsole Technologies Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
EU REACH chemical registration requirements gate both supplier qualification and price differentiation simultaneously, forcing equipment vendors to absorb certification costs into base pricing while enabling premium positioning for documented circularity pathways.
Pricing Analysis
Cost-plus contracts with natural gas indexation dominate steam-based system procurement, insulating European buyers from boiler fuel volatility while compressing vendor margins during price spikes. Three-tier pricing structure across premium continuous-type, standard batch-type, and economy manual configurations reflects automation grade and density control precision. Pricing pressure stems from Chinese domestic fabricators competing on output-adjusted economics for construction sector demand. Small-scale distributors exhibit highest price sensitivity, while German automotive suppliers prioritize performance guarantees over unit cost.
Supply Chain Analysis
China and Germany anchor pre-expander fabrication capacity, with Hangzhou and Suzhou manufacturing belts feeding domestic construction demand and Stuttgart-area engineering clusters serving automotive precision specifications. Critical inputs include expandable polystyrene beads from Northeast Asian petrochemical complexes, PLC control systems from German automation specialists, and pressure-rated expansion chambers from Italian thermal equipment foundries. Single-source vulnerability concentrates in specialty bead formulations compliant with EU Green Deal circularity mandates. Distribution runs through OEM-integrated line contracting for high-volume buyers and independent equipment vendors with bundled service networks for fragmented regional markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
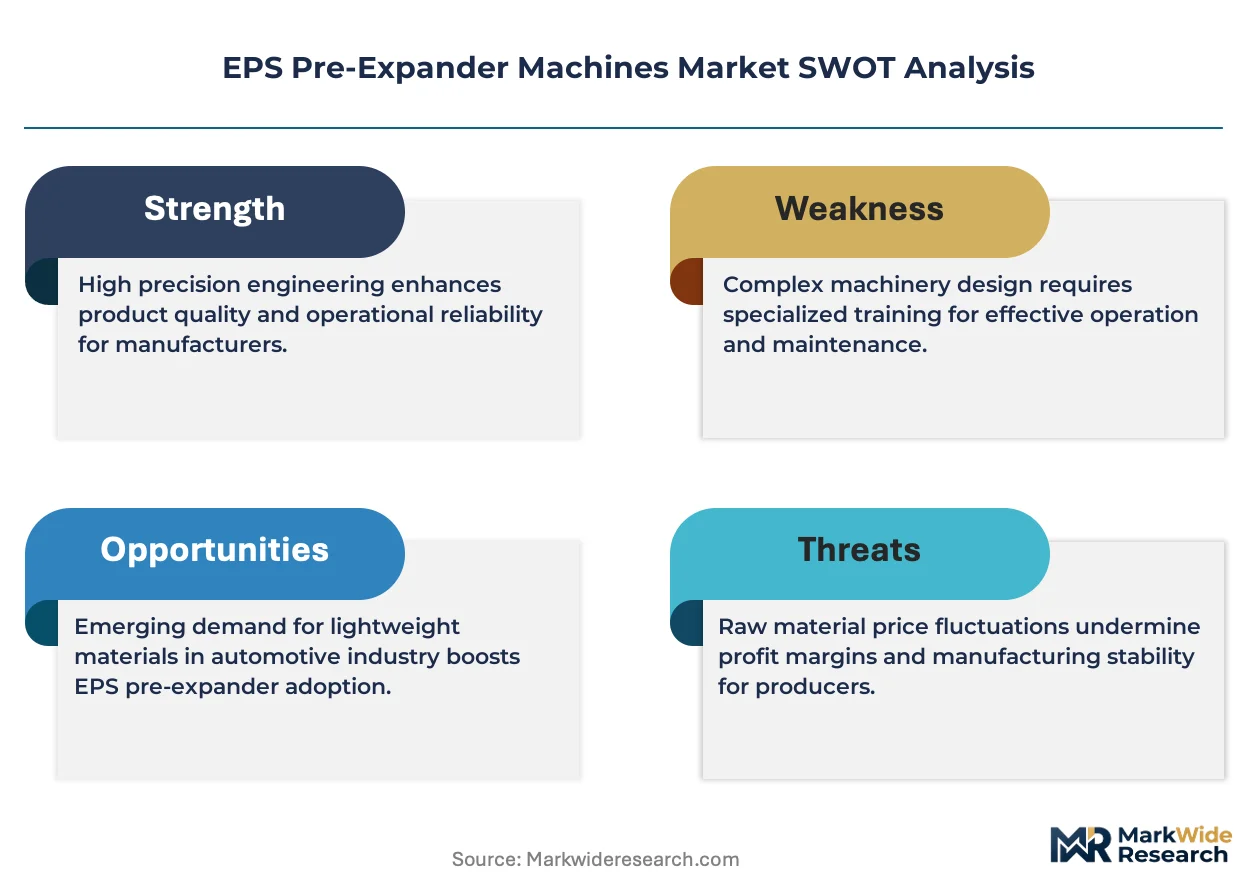
PLC-integrated density feedback systems are creating platform-economics inflection, enabling outcome-based equipment contracting that shifts buyer risk to performance guarantees and locks in recurring calibration service revenue.
For Market Incumbents: Secure backward integration into control system software development to defend against modular hardware commoditization. Kurtz Ersa and Cannon Group should deepen captive supply of density sensing algorithms, while expanding service unbundling options for buyers with in-house thermal process capabilities. Air expansion technology specialists represent an emerging entrant archetype threatening steam-dominant installed bases.
For New Entrants and Emerging Players: Lead with air expansion architectures targeting pharmaceutical packaging cleanroom specifications in Switzerland and medical device suppliers in Germany, where boiler elimination commands specification priority. India's BIS certification pipeline offers the most penetrable geography, with construction insulation specialists in Maharashtra and Gujarat evaluating first pre-expander capacity additions. Position through localized compliance documentation partnerships rather than direct fabrication investment.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across air expansion system development, reducing barrier-to-entry for thermal process specialists with compressed air handling expertise versus steam boiler infrastructure. Acquisition targets should cluster around mid-tier regional vendors with established India BIS documentation and service networks. Monitor divergence between China's SAMR energy labeling mandates and EU REACH emission thresholds as inflection indicator for compliance-cost arbitrage opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Control Software | Captures density algorithm revenue streams that hardware margins cannot sustain under Chinese cost competition. |
| Air Expansion Technology Licensing | Opens specification windows in Swiss pharmaceutical cleanrooms where Swissmedic regulations restrict boiler infrastructure. |
| India BIS Certification Pre-Positioning | Creates first-mover documentation advantages before Maharashtra construction insulation demand inflects. |
| Outcome-Based Equipment Contracting | Shifts buyer risk to performance guarantees while locking in recurring calibration service revenue. |
| Localized Service Network Expansion | Substitutes for direct manufacturer presence in emerging markets where distributors currently dominate. |
Research Methodology
A spread of perspectives from plant engineers at construction board producers, procurement leads at German automotive suppliers, aftermarket service heads at regional equipment vendors, and thermal process R&D directors at bead formulation specialists converged on the working assumptions. Primary fieldwork combined with secondary validation from customs/trade data, SEC filings of listed machinery manufacturers, SAMR energy labeling documentation, and EU ECHA REACH registration databases. Bottom-up equipment shipment tracking and top-down end-use demand modeling provided triangulation across the analysis window.
Segmentation dimensions modeled include automation tier, expansion technology, end-use application, and regional regulatory cluster. CAGRs derived from equipment shipment trajectories and replacement cycle analysis across the projection horizon. Industry-specific forecast inputs encompass SAMR energy labeling compliance timelines and EU Green Deal circularity documentation adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained natural gas price volatility or abrupt REACH emission threshold revisions would require recalibration. Forecasts reflect documented assumptions regarding batch-to-continuous migration rates and air expansion technology throughput improvements. Recalibration cycles align with material shifts in SAMR labeling mandate enforcement and BIS certification pipeline completion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Tablet Packing Machine Market
Packaging Machinery
Tray Former Machines Market
Packaging Machinery
Volumetric Filling Machines Market
Packaging Machinery
Packaging Machine Heaters Market
Packaging Machinery
Meter-Mix Dispensing Machine Market
Packaging Machinery
Blow Fill Seal (BFS) Technology Market
Packaging Machinery
Automatic Auger Fillers Market
Packaging Machinery
Tissue Paper Unwinding Machine Market
Packaging Machinery
Auger Powder Filling Machines Market
Packaging Machinery
Bottle Filling Machine Market
Packaging Machinery
Pillow Packing Machine Market
Packaging Machinery
Tray Sealing Machines Market
Packaging Machinery
Metal Banding Machine Market
Packaging Machinery
Global Film Coating Machine Market
Packaging Machinery
Piston Fillers Market
Packaging Machinery
Palletizing Machines Market