
 Robotic Carton Loading Machine Market | 2026-2036
Robotic Carton Loading Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Robotic Carton Loading Machine Market Intelligence
The European Union's Green Deal, with its focus on optimizing logistics and reducing material waste, is broadening the business case for automated packaging solutions. This shift favors suppliers with advanced integration capabilities. FANUC Corporation leverages its extensive background in vision systems and controls to offer precise and high-speed solutions for complex packing tasks. KUKA AG differentiates with its portfolio of high-payload articulated robots, which are essential for handling heavy or bulk items in large-scale manufacturing plants. Meanwhile, Universal Robots specializes in collaborative models designed for safe operation alongside human workers.
Robotic carton loading machines are automated systems that utilize multi-axis robotic arms, equipped with specialized end-of-arm tooling, to pick products and place them into secondary containers like cartons or cases. These systems integrate vision systems and force sensors to ensure accurate placement and gentle handling of delicate items. While articulated robots continue to represent a major product type due to their speed and flexibility, collaborative robots are the fastest-growing segment, particularly for end users like contract packaging providers. The food and beverage packaging application remains the largest consumer, demanding solutions that comply with strict hygiene standards.
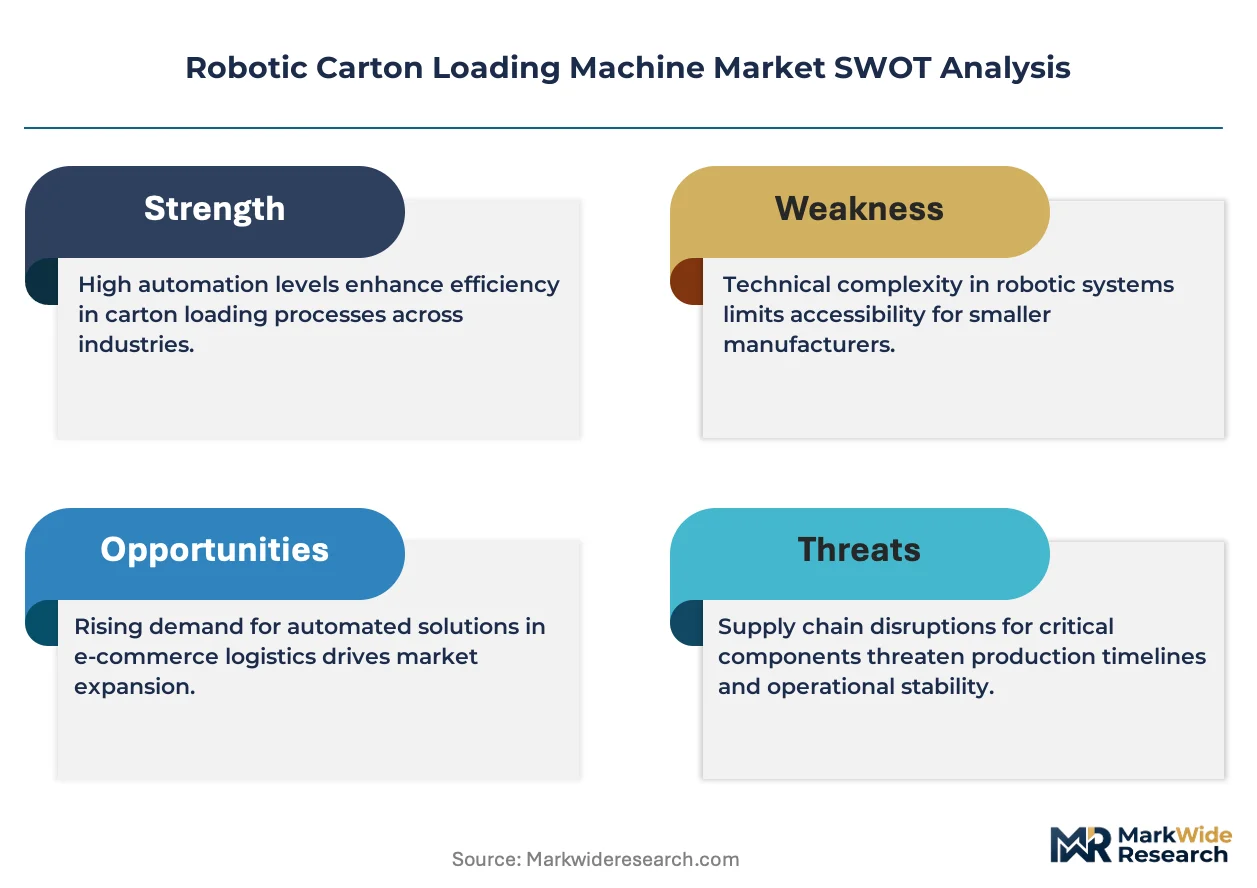
The market operates within a framework of stringent safety and operational standards. Global standards like ISO 10218 set safety requirements for industrial robots and their integration. National regulators, including OSHA in the United States and bodies enforcing the EU Machinery Directive, mandate comprehensive risk assessments and safety features like light curtains and emergency stops. These regulations directly influence robot design and system layout. For end-users, the key strategic consideration revolves around selecting automation technology that aligns with future production scalability and labor force strategy.
Market Dynamics
The central force shaping the market is the dual pressure from stringent worker safety mandates, such as those from OSHA, and the operational necessity for higher throughput in e-commerce fulfillment centers and food production lines, compelling a structural shift toward automation.
Growth Catalysts
- E-commerce Expansion:The relentless growth of e-commerce, particularly in North American and European logistics hubs, creates sustained demand for automated systems that can operate continuously to meet demanding delivery timelines and manage fluctuating order volumes.
- Regulatory Frameworks:Policies like the European Union's Green Deal encourage optimized logistics to reduce waste and energy consumption, strengthening the business case for precise and efficient robotic packaging solutions over less-consistent manual processes.
- Advanced Vision Systems:The integration of AI-driven 3D vision systems enables robots to handle a wider variety of product shapes, sizes, and materials, including delicate or irregularly shaped items, expanding their applicability in sectors like fresh produce packaging.
Market Restraints
- High Initial Investment:The significant upfront capital required for purchasing, integrating, and commissioning a robotic carton loading system remains a substantial barrier for many small and medium-sized enterprises (SMEs) and contract packagers.
- Integration Complexity:Interfacing robotic systems with disparate legacy software, such as older Warehouse Management Systems (WMS) or Enterprise Resource Planning (ERP) platforms, can be technically challenging, costly, and time-consuming for end-users.
- Component Supply Bottlenecks:The supply chain for critical components, including specialized end-of-arm tooling (EOAT), high-precision sensors, and robot controllers, is concentrated among a few vendors, creating potential for price volatility and lead-time extensions.
Strategic Opportunities
- Pharmaceutical Applications:The pharmaceutical industry presents a significant opportunity, where robotic systems can ensure sterile handling, precise counting, and support for track-and-trace serialization requirements, enhancing product safety and regulatory compliance.
- Emerging Market Penetration:Manufacturing and logistics sectors in Southeast Asian economies are expanding rapidly, creating greenfield opportunities for automation suppliers to establish a footprint in markets with nascent adoption of robotic loading technologies.
- Robotics-as-a-Service (RaaS) Models:Offering robotic systems through a subscription or usage-based RaaS model can lower the barrier to entry for smaller companies, converting a large capital expenditure into a more manageable operational expense.
Industry Challenges
- Skilled Labor Scarcity:A persistent shortage of technicians and engineers with the requisite skills in robotics programming, system integration, and maintenance hampers the ability of end-users to effectively operate and support advanced automation.
- Risk Assessment Burden:Conducting the comprehensive, site-specific risk assessments required by safety standards like ISO 10218 for every new installation is a complex and time-intensive process that can delay project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotic Carton Loading Machine Market |
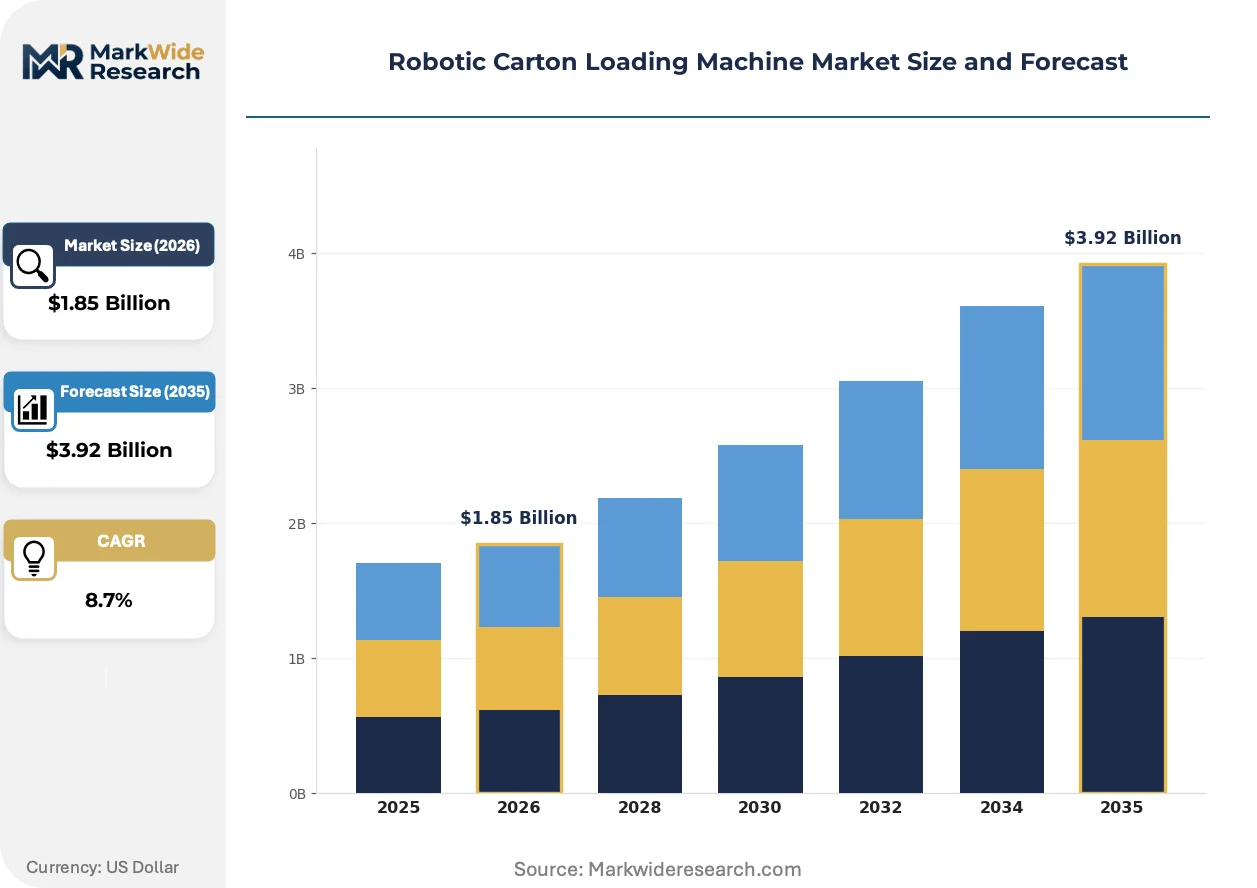
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pick & Place Robots, Collaborative Robots, Articulated Robots, SCARA Robots Technology: Vision Systems, Machine Learning, Force Sensors, Automated Grippers, Pneumatic Actuators Application: Food & Beverage Packaging, Consumer Electronics Handling, Pharmaceutical Packing, Cosmetic Cartoning End User: Contract Packaging Providers, Third-Party Logistics, E-Commerce Fulfillment, Manufacturing Plants |
| Companies Covered | ABB Ltd., FANUC Corporation, KUKA AG, Yaskawa Electric, Universal Robots, Brenton Engineering, Bosch Packaging Technology, Syntegon Technology, Mitsubishi Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotic Carton Loading Machine Market Strategic Shifts & Innovations
The fusion of advanced sensing technologies and more sophisticated software is creating robotic systems that are not just faster, but also more adaptable and intelligent. This evolution allows automation to tackle complex, variable tasks that were previously beyond its reach.
AI-powered 3D vision systems provide real-time object recognition and orientation detection for mixed-product streams. End-users in consumer-packaged goods and e-commerce are adopting this for complex kitting and packing tasks. This advanced sensing capability is unifying the previously separate processes of product identification, picking, and quality inspection into a single, fluid robotic motion.
The EU Machinery Directive, and its successor the Machinery Regulation, imposes strict requirements for risk assessment and functional safety on integrated robotic systems. This regulation compels system integrators to incorporate certified safety components like light curtains and safety PLCs by default. The food and beverage sector is most affected, driving demand for robots with hygienic designs that also meet these stringent safety mandates.
A move towards Robotics-as-a-Service (RaaS) models is gaining traction, allowing end-users to pay for automation based on usage rather than a large upfront capital purchase. This shift disrupts the traditional equipment sales model, particularly for small to medium-sized enterprises and contract packaging organizations. The trend is most visible in North American logistics, where seasonal peaks make scalable, opex-based automation highly attractive.
Robotic Carton Loading Machine Market Segmentation
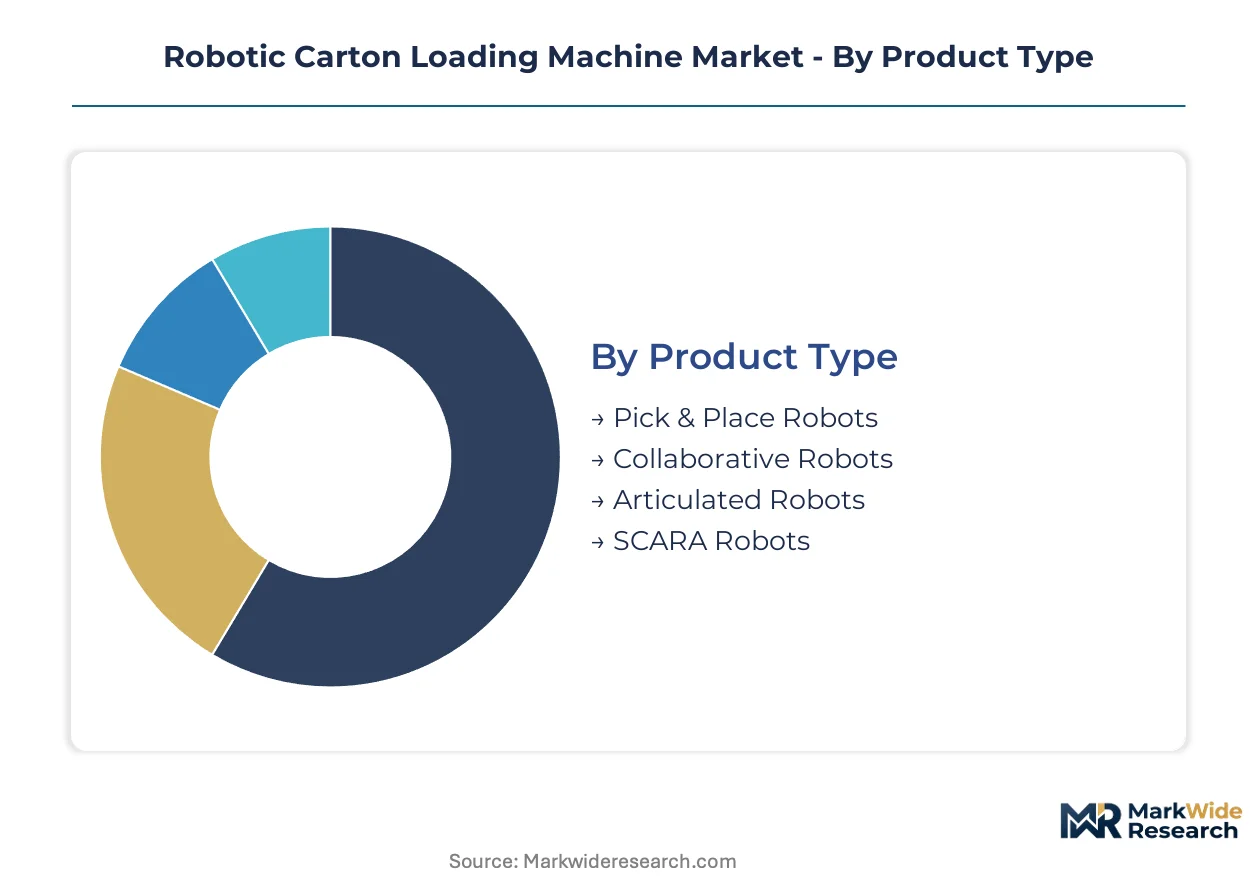
The robotic carton loading machine market is segmented to reflect the diverse technological capabilities and varied operational demands of end-users. Understanding these distinct segments allows businesses to identify specific growth vectors and tailor automation strategies effectively. This granular view highlights where innovation is critical and where market penetration is most impactful.
Product Type:
The upgrade and replacement cycles within robotic carton loading systems are significantly influenced by the evolving product type offerings. Manufacturers are continually enhancing robot capabilities, prompting end-users to consider more advanced models for improved efficiency and flexibility in packaging operations.
- Articulated Robots:These multi-axis robotic arms offer high speed and flexibility, making them a major product type for general industrial automation. Demand concentrates in large-scale manufacturing plants for handling heavy or bulk items, where their payload capacity and reach are critical for high-throughput operations.
- Collaborative Robots:Designed for safe interaction alongside human workers without extensive safety caging, these models feature integrated force sensors and intuitive programming. Contract packaging providers and small to medium-sized enterprises are driving their adoption, seeking flexible automation solutions for diverse tasks and worker safety compliance.
- Pick & Place Robots:These systems are optimized for rapid, repetitive tasks of picking individual products and placing them precisely into cartons.
- SCARA Robots:Known for their high speed and precision in horizontal movements, SCARA robots are widely used for assembly and pick-and-place operations in confined spaces.
Volume placements concentrate in Articulated Robots; the faster expansion belongs to Collaborative Robots.
Technology:
The application of advanced technologies within robotic carton loading machines directly correlates with enhanced operational precision and broader product handling capabilities. Integrators leverage these innovations to meet increasingly complex packaging demands across industries.
- Vision Systems:These integrated camera and software systems provide real-time object recognition, orientation detection, and quality inspection for diverse product streams. End-users in consumer-packaged goods and e-commerce fulfillment centers adopt these for complex kitting and precise placement of varied items.
- Machine Learning:This technology enables robots to adapt to new product variations and optimize picking and packing strategies through continuous data analysis. Pharmaceutical packing and food processing facilities utilize machine learning for improved accuracy and reduced error rates in handling delicate or irregularly shaped items.
- Force Sensors:Integrated into end-of-arm tooling, force sensors allow robots to detect contact and apply appropriate pressure, ensuring gentle handling of delicate items.
- Automated Grippers:These specialized end-of-arm tools are designed for efficient and secure handling of specific product types or carton formats, reducing product damage.
- Pneumatic Actuators:Utilizing compressed air, these components provide rapid and powerful movement for robotic arms and grippers, essential for high-speed packaging lines.
Advanced Vision Systems provide foundational capabilities; Machine Learning offers the most significant leap in adaptability.
Application:
Customer type demands significantly influence the configuration and features required for robotic carton loading machine applications. Different industries necessitate tailored solutions to comply with specific regulatory, hygiene, or handling requirements.
- Food & Beverage Packaging:This sector demands robotic systems that comply with stringent hygiene standards, often requiring washdown-capable designs and precise handling of perishable goods. The need for high throughput to meet consumer demand and reduce waste drives automation in this largest consumer segment.
- Pharmaceutical Packing:Robotic systems in this application ensure sterile handling, precise counting, and support for track-and-trace serialization requirements, enhancing product safety and regulatory compliance. Pharmaceutical manufacturers prioritize accuracy and validation for sensitive products.
- Consumer Electronics Handling:Robots manage delicate and often varied electronic components, requiring advanced vision and gentle gripping to prevent damage during packing.
- Cosmetic Cartoning:This application focuses on aesthetic presentation and precise placement of diverse cosmetic products into retail-ready cartons.
Food & Beverage Packaging remains the primary volume driver, while Pharmaceutical Packing demonstrates robust expansion potential.
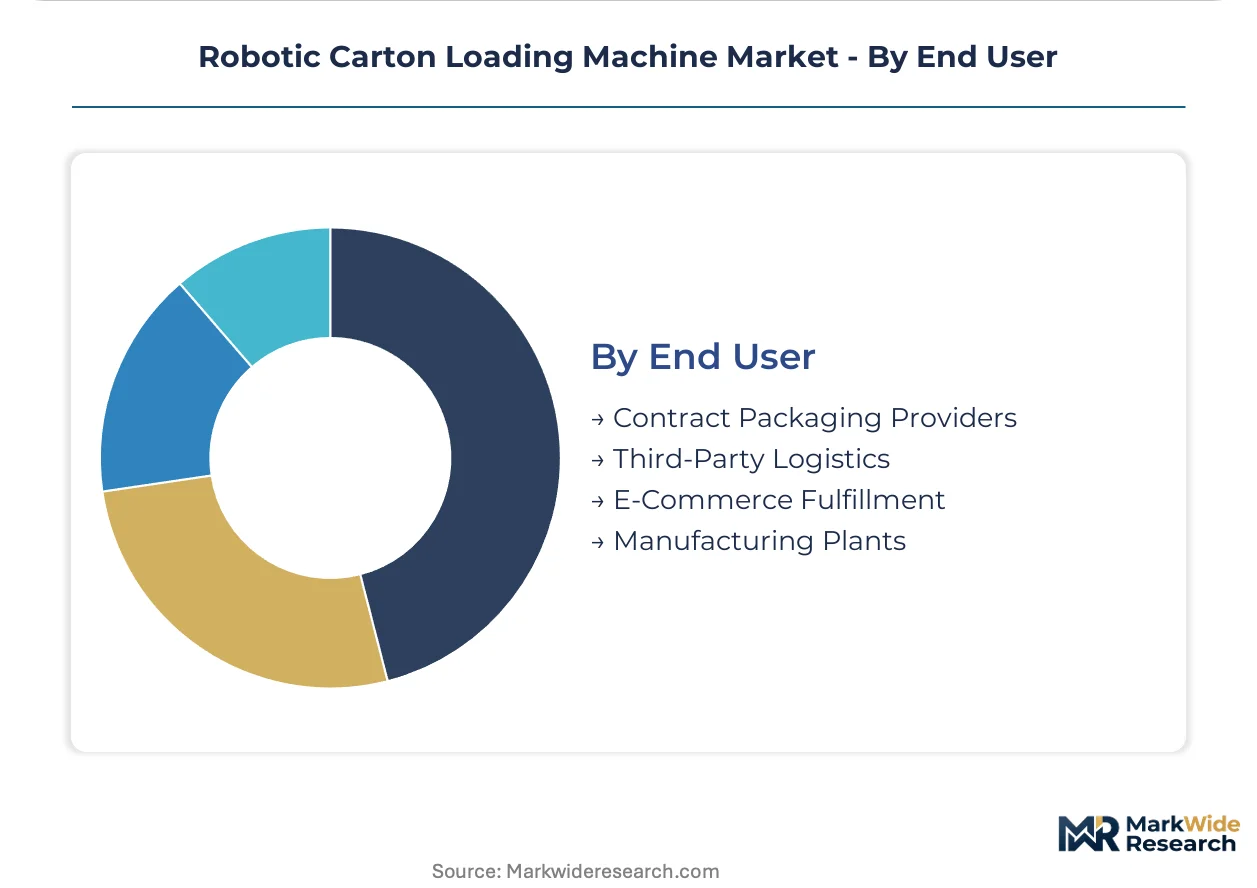
End User:
The overall volume of goods processed by end-users dictates the scale and integration complexity of robotic carton loading machine deployments. High-volume operations specifically benefit from advanced automation to maintain efficiency and manage fluctuating demands.
- E-Commerce Fulfillment:These centers require automated systems capable of continuous operation, managing fluctuating order volumes, and meeting demanding delivery timelines. North American and European logistics hubs represent significant demand concentrations for these high-throughput solutions.
- Contract Packaging Providers:These companies benefit from flexible, adaptable robotic systems to handle diverse product lines for multiple clients. The adoption of collaborative robots and Robotics-as-a-Service models is particularly attractive for managing variable project demands.
- Third-Party Logistics:3PL providers deploy robotic systems to optimize warehouse operations, improve order accuracy, and enhance overall supply chain efficiency for their clients.
- Manufacturing Plants:Large-scale manufacturing facilities integrate robotic carton loaders to automate repetitive packaging tasks, improving production line speed and worker safety.
E-Commerce Fulfillment centers exhibit the highest demand intensity; Contract Packaging Providers are rapidly adopting flexible robotic solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr metropolitan region in Germany, a central European logistics hub, drives significant demand for robotic carton loading solutions. This area benefits from established manufacturing industries and a strong focus on automated logistics. Its strategic location supports high-volume e-commerce fulfillment operations across the continent.
United States
United States e-commerce expansion and food processing facilities create sustained demand for high-throughput robotic carton loading. OSHA worker safety mandates accelerate the shift from manual labor to automated systems. The Atlanta, Georgia logistics corridor serves as a major hub for fulfillment centers integrating advanced automation.
Germany
Germany's advanced manufacturing sector and stringent food safety standards fuel the adoption of robotic carton loading machines. The EU Green Deal encourages efficient logistics, strengthening the business case for automated packaging solutions. Bavaria's industrial heartland is a key region for integrating high-precision robotic systems in diverse production lines.
Japan
Japan's focus on high-speed production and precision handling in electronics and consumer goods packaging drives robotic carton loading machine demand. METI industrial automation policies support technological advancements and wider robot deployment across manufacturing sectors. The Tokyo-Nagoya industrial belt concentrates companies leveraging advanced vision systems for complex packing tasks.
China
China's massive e-commerce growth and expanding manufacturing output necessitate scalable robotic carton loading solutions. National intelligent manufacturing initiatives promote the adoption of automation technologies across various industries. The Yangtze River Delta region is a major center for integrating robotic systems in high-volume production and logistics.
Netherlands
Dutch logistics hubs and advanced food processing facilities demand efficient robotic carton loading for rapid distribution. The EU Machinery Directive ensures high safety standards for integrated robotic systems within packaging operations. The Port of Rotterdam logistics ecosystem increasingly deploys automation to handle vast cargo volumes and optimize supply chain efficiency.
Robotic Carton Loading Machine Market Key Industry Players
Premium-margin players sit above commodity-margin players across integration capabilities and specialized product offerings within the robotic carton loading machine market. The market structure is tiered, with highly specialized automation providers distinguishing themselves through advanced technology. Key archetypes include providers of high-speed industrial robots, collaborative systems, and integrated vision solutions. Strategic partnerships and portfolio diversification are dominant competitive moves, alongside the exploration of Robotics-as-a-Service models.
Specialists in advanced integration and high-speed industrial robotics include FANUC Corporation, a Japanese entity known for its extensive background in vision systems and controls. KUKA AG, a German-based company, occupies a position among providers of high-payload articulated robots essential for large-scale manufacturing. Meanwhile, Universal Robots, a Danish firm, exemplifies the collaborative robot segment, focusing on safe human-robot interaction. These companies anchor distinct segments of the market, catering to varied end-user requirements for speed, payload, and operational safety.
| Leading Market Players |
|---|
| ABB Ltd. |
| FANUC Corporation |
| KUKA AG |
| Yaskawa Electric |
| Universal Robots |
| Brenton Engineering |
| Bosch Packaging Technology |
| Syntegon Technology |
| Mitsubishi Electric |
| Others |
Cost & Logistics Intelligence
Vertical integration among key robot manufacturers anchors their supply position and grants significant pricing power across the robotic carton loading machine market. This control extends from core robotic components to advanced software.
Pricing Analysis
Throughput optimization serves as a primary value-based pricing anchor for robotic carton loading systems. Project-based pricing dominates for large-scale installations, while subscription or usage-based RaaS models gain traction for smaller enterprises. Customization level and after-sales service quality are critical price differentiation drivers. Pricing pressure stems from increasing competition in the collaborative robot segment. Contract packaging providers exhibit the highest price sensitivity.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke networks manage the physical flow of robotic carton loading systems to end-users. Component supply concentrates in Japan, Germany, and China for high-precision sensors and robot controllers. The market relies on specialized end-of-arm tooling, often custom-made. Single-source vulnerability for specific components presents a structural supply chain risk. Direct sales channels and system integrators form the dominant downstream distribution model.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The robotic carton loading machine market is in a technology-transition phase, with AI-driven 3D vision systems rapidly displacing older, less adaptable product identification methods. This shift enables robots to handle previously unmanageable complex tasks.
For Market Incumbents:Lock in existing customer bases by deepening integration capabilities and expanding global service networks. This counters the threat from RaaS models and new entrants offering niche solutions. Invest heavily in R&D for AI vision and advanced force-sensing technologies. Prioritize certification investments to maintain compliance with evolving safety standards like ISO 10218.
For New Entrants and Emerging Players:Collaborative robot technology offers a strong technology-first wedge into underserved segments like contract packaging providers and small to medium-sized enterprises. Target emerging markets in Southeast Asia with flexible, scalable solutions. A Robotics-as-a-Service model provides a compelling go-to-market angle, lowering the initial investment barrier for these customers.
For Investors and Strategic Acquirers:Exit pathways concentrate in specialized system integrators and RaaS platform providers, offering strong long-term viability over a 5-10 year window. These targets often possess unique software capabilities or deep application expertise. Watch for accelerating RaaS adoption rates and significant advancements in AI vision system capabilities as key inflection indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop next-generation AI-driven vision systems | Enhances robotic adaptability for mixed-product streams, crucial for e-commerce fulfillment. |
| Expand Robotics-as-a-Service (RaaS) offerings | Lowers entry barriers for SMEs and contract packagers, driving market penetration. |
| Form strategic alliances with logistics software providers | Improves system integration with existing WMS/ERP platforms, reducing complexity for end-users. |
| Invest in hygienic design for food and beverage robots | Ensures compliance with stringent hygiene standards, expanding market share in a key application. |
| Target greenfield opportunities in Southeast Asian markets | Establishes early market presence in rapidly expanding manufacturing and logistics sectors. |
Research Approach
Industry reports, company financial filings, and academic journals formed the secondary backbone for this analysis. Primary interviews with robotics engineers, plant managers, logistics directors, and procurement specialists provided granular insights. This approach combined bottom-up data collection with top-down market validation. Triangulation across these diverse sources ensured robust data integrity.
Historical trendline analysis established foundational growth patterns across the analysis window. The quantitative model segmented the market by product type, technology, application, end-user, and regional adoption. Compound annual growth rates were derived through a comprehensive regression analysis. E-commerce growth rates and labor cost changes served as critical industry-specific forecast inputs over the projection horizon.
Several conditions sit outside the modeled scope, including unforeseen geopolitical shifts and rapid shifts in global trade policies. Forecasts reflect assumptions documented regarding technological advancements and regulatory stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Aerosol Filling Machines Market
Packaging Machinery
Molded Pulp Packaging Machines Market
Packaging Machinery
Auger Powder Filling Machines Market
Packaging Machinery
Liquid Capsule Filling Machines Market
Packaging Machinery
Wraparound Case Packers Market
Packaging Machinery
Pallet Stretch Wrapping Machines Market
Packaging Machinery
Tray and Sleeve Packing Machines Market
Packaging Machinery
Extrusion Press Market
Packaging Machinery
Autofill Drums & Totes Machines Market
Packaging Machinery
Thermal Laminating Machine Market
Packaging Machinery
Global Food and Beverage Packaging Machinery Market
Packaging Machinery
Carton Folding and Gluing Machine Market
Packaging Machinery
Cartridge Filling System Market
Packaging Machinery
Triangle Tea Bag Packaging Machinery Market
Packaging Machinery
Shrink - Sleeve Wrapping Machinery Market
Packaging Machinery
Strapping Machine Market