
 Form-Fill-Seal Equipment Market | 2026-2036
Form-Fill-Seal Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Form-Fill-Seal Equipment Market Intelligence
German packaging machinery builders is recalibrating production schedules to address backlogs in pharmaceutical-grade vertical systems. Syntegon leverages its Stuttgart engineering base to dominate aseptic pouch lines for injectable drugs. Robert Bosch GmbH sustains R&D intensity in servo-driven horizontal platforms for high-speed confectionery. GEA Group AG anchors its position through captive supply of integrated filling valves and film transport modules.
Form-fill-seal equipment comprises automated packaging machinery that forms a container from flat or tubular stock, fills it with product, and seals the package in a continuous or indexed motion cycle, typically operating at 30–300 cycles per minute depending on pouch format and product viscosity. Thermoforming systems lead technology adoption in fresh protein and ready-meal applications where extended shelf life justifies capital intensity, while modified atmosphere packaging commands premium positioning in pre-washed salad and cut-fruit segments where oxygen scavenging preserves organoleptic quality. Automatic vertical platforms dominate unit volume in the food and beverages end-user category, though pharmaceutical buyers increasingly specify horizontal configurations with isolator integration for powder and granular drug forms.
FDA 21 CFR Part 11 and EMA Annex 15 shape validation protocols for pharmaceutical installations, forcing equipment suppliers to embed audit trails and electronic signature capture in control architectures. REACH restrictions on perfluorinated substances and EU Packaging and Packaging Waste Regulation recyclability targets are redirecting film specification conversations toward mono-PE and mono-PP structures compatible with existing heat-seal jaws. Stakeholders must monitor whether China's GB standards for food-contact materials will harmonize with Codex Alimentarius frameworks or create parallel certification burdens for multinational equipment deployments.
Market Dynamics
Cleanroom-compatible packaging lines are reshaping capital allocation as pharmaceutical manufacturers in Germany and the United States expand sterile filling capacity to meet EMA and FDA validation protocols. Equipment suppliers now embed audit trails and electronic signature capture in control architectures as standard features rather than optional upgrades.
Growth Catalysts
- EMA Annex 15 sterility mandates:Pharmaceutical manufacturers in Germany's Baden-Württemberg cluster are retrofitting existing lines with isolator-integrated horizontal platforms to comply with updated guidance on aseptic processing.
- Recyclable mono-material films:EU Packaging and Packaging Waste Regulation recyclability targets are redirecting film specifications toward mono-PE and mono-PP structures compatible with existing heat-seal jaw geometries.
- China's Yangtze Delta pharmaceutical corridor:Domestic drug manufacturers are deploying high-speed vertical systems to serve contract manufacturing demand from multinational biopharma clients.
Market Restraints
- Specialized servo motor supply concentration:Precision motion control components for high-speed pouch forming remain concentrated among Japanese and German suppliers, creating lead time vulnerability.
- REACH perfluorinated substance restrictions:Barrier coating reformulation for high-oxygen-resistance films is compressing available material options and extending qualification timelines.
- Thermoforming capex intensity:Extended shelf-life protein packaging requires multi-million dollar forming systems with integrated modified atmosphere capabilities, limiting buyer pools to large processors.
Strategic Opportunities
- India's Maharashtra food processing belt:Dairy and spice packaging cooperatives represent underpenetrated demand for mid-speed automatic vertical platforms with quick format changeover.
- Convergence of vision inspection and AI-driven seal verification:Real-time defect detection systems are opening premium positioning for equipment suppliers who integrate machine learning-based quality gates.
- US Inflation Reduction Act domestic manufacturing incentives:Pharmaceutical packaging line reshoring is creating demand for FDA 21 CFR Part 11 compliant systems with localized service support.
Industry Challenges
- Control system cybersecurity certification:IEC 62443 compliance for industrial automation networks is extending commissioning timelines and requiring specialized validation documentation.
- Retrofit integration with legacy SCADA architectures:Pharmaceutical buyers face protocol translation complexity when connecting new servo-driven platforms to existing manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Form-Fill-Seal Equipment Market |
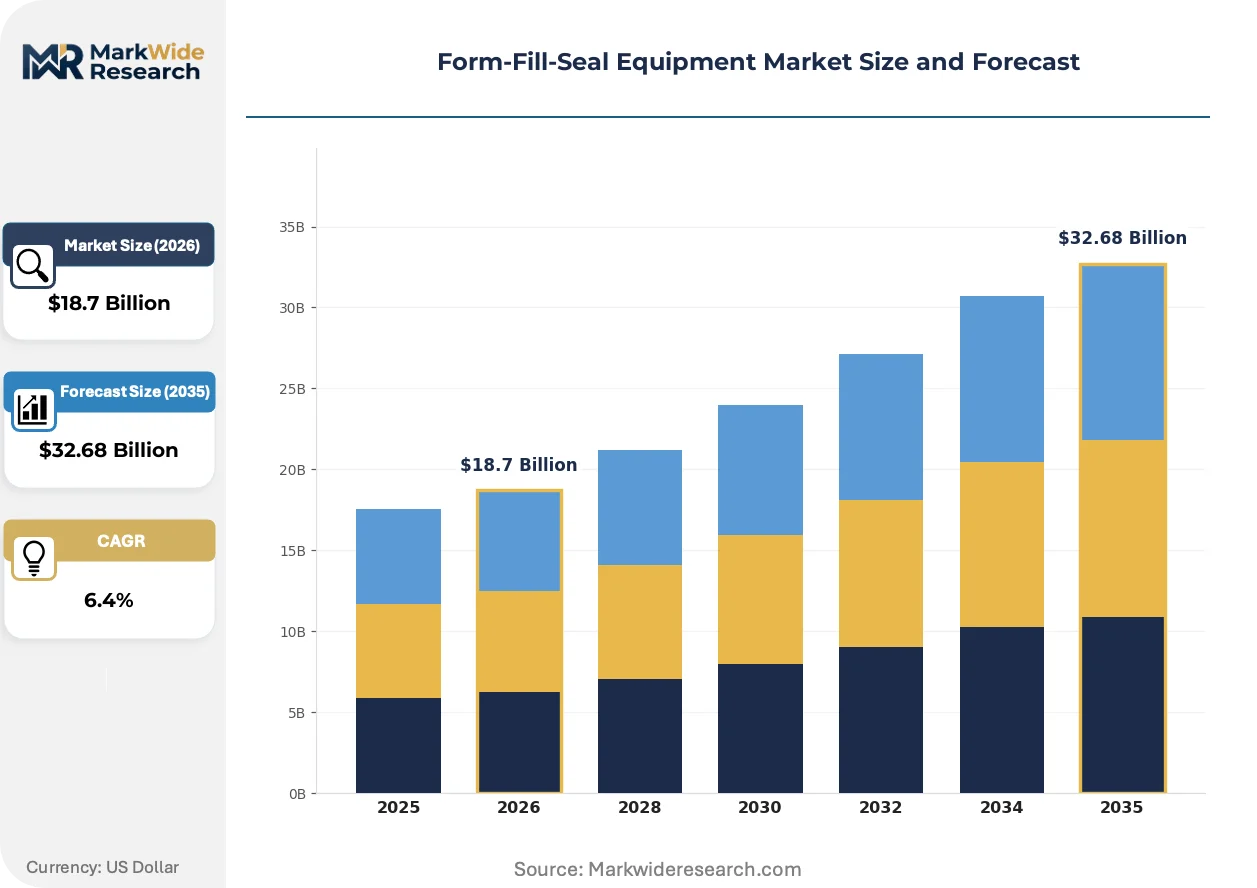
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
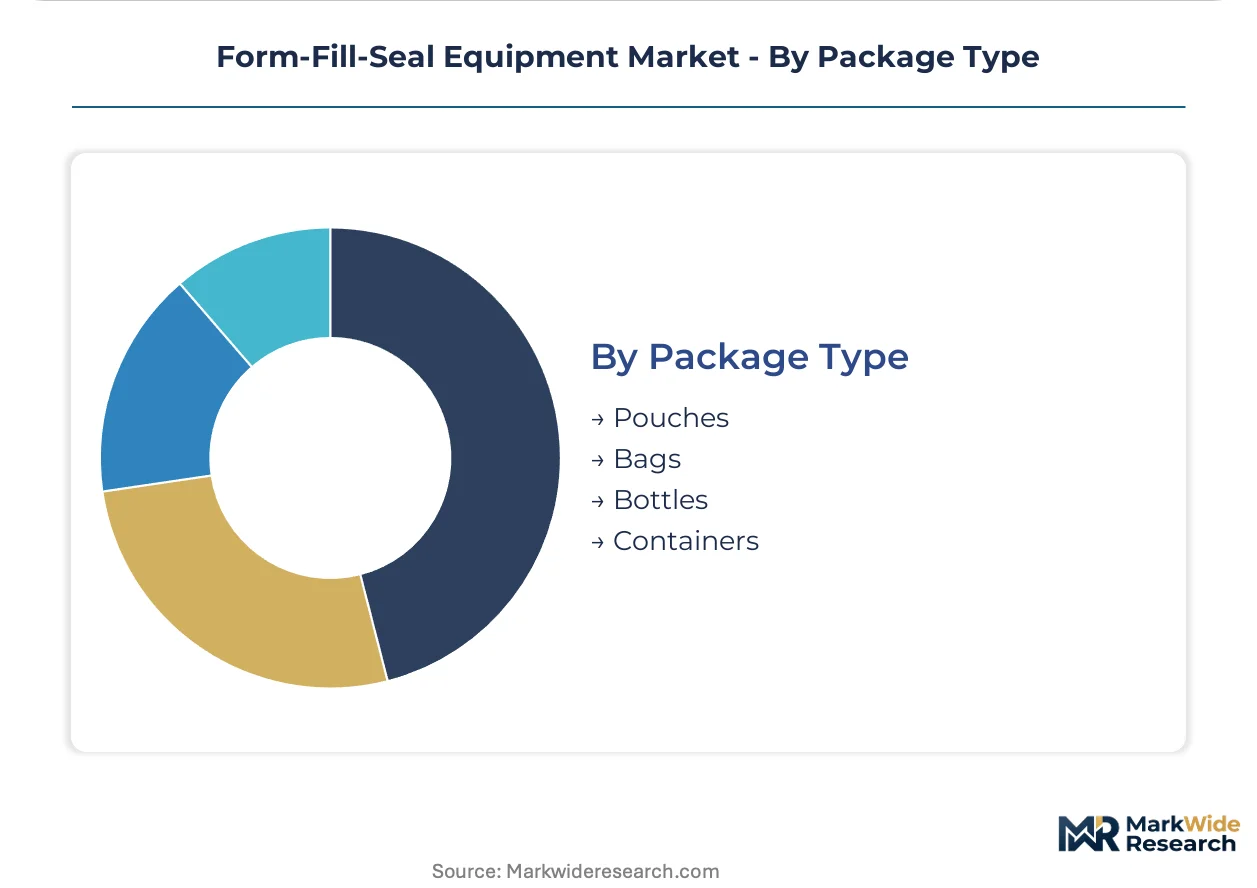
| Segmentation | Product Type: Vertical Form-Fill-Seal, Horizontal Form-Fill-Seal, Semi-Automatic, Automatic Technology: Thermoforming, Vacuum Packaging, Modified Atmosphere Packaging, Stretch Film End User: Food & Beverages, Pharmaceuticals, Cosmetics, Cleaning Products Package Type: Pouches, Bags, Bottles, Containers |
| Companies Covered | ProMach, Syntegon, Robert Bosch GmbH, IMA Industria Macchine Automatiche S.p.A., Barry-Wehmiller Companies, Inc., Bossar Packaging S.A., SACMI Imola S.C., Duravant, GEA Group AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Form-Fill-Seal Equipment Market Strategic Shifts & Innovations
Digital thread integration across design, production, and validation is compressing equipment commissioning cycles while raising the technical bar for supplier engineering capabilities. Real-time performance monitoring and predictive maintenance modules are becoming standard expectations rather than premium options.
Ultrasonic sealing technology is rewriting heat-seal jaw design paradigms by eliminating temperature-dependent dwell times and enabling hermetic seals through mono-material films with inconsistent thickness. Pharmaceutical manufacturers in Switzerland and Germany are specifying ultrasonic modules for temperature-sensitive biologic packaging. The technology is compressing cycle time variability and reducing seal validation documentation burden.
EU F-Gas Regulation phase-down schedules are accelerating adoption of CO2-based transcritical refrigeration in modified atmosphere packaging systems for fresh protein applications. Equipment suppliers must redesign gas mixing and distribution manifolds to handle higher operating pressures. German and Dutch ready-meal processors are leading this transition due to national carbon accounting requirements.
Outcome-based equipment performance contracts are displacing traditional capital purchase models among multinational food processors seeking to transfer uptime risk to OEMs. Service agreements now tie payment to verified operational availability metrics rather than spare parts consumption. This shift is most visible in France and the United Kingdom where processor consolidation has concentrated buyer negotiating power.
Form-Fill-Seal Equipment Market Segmentation
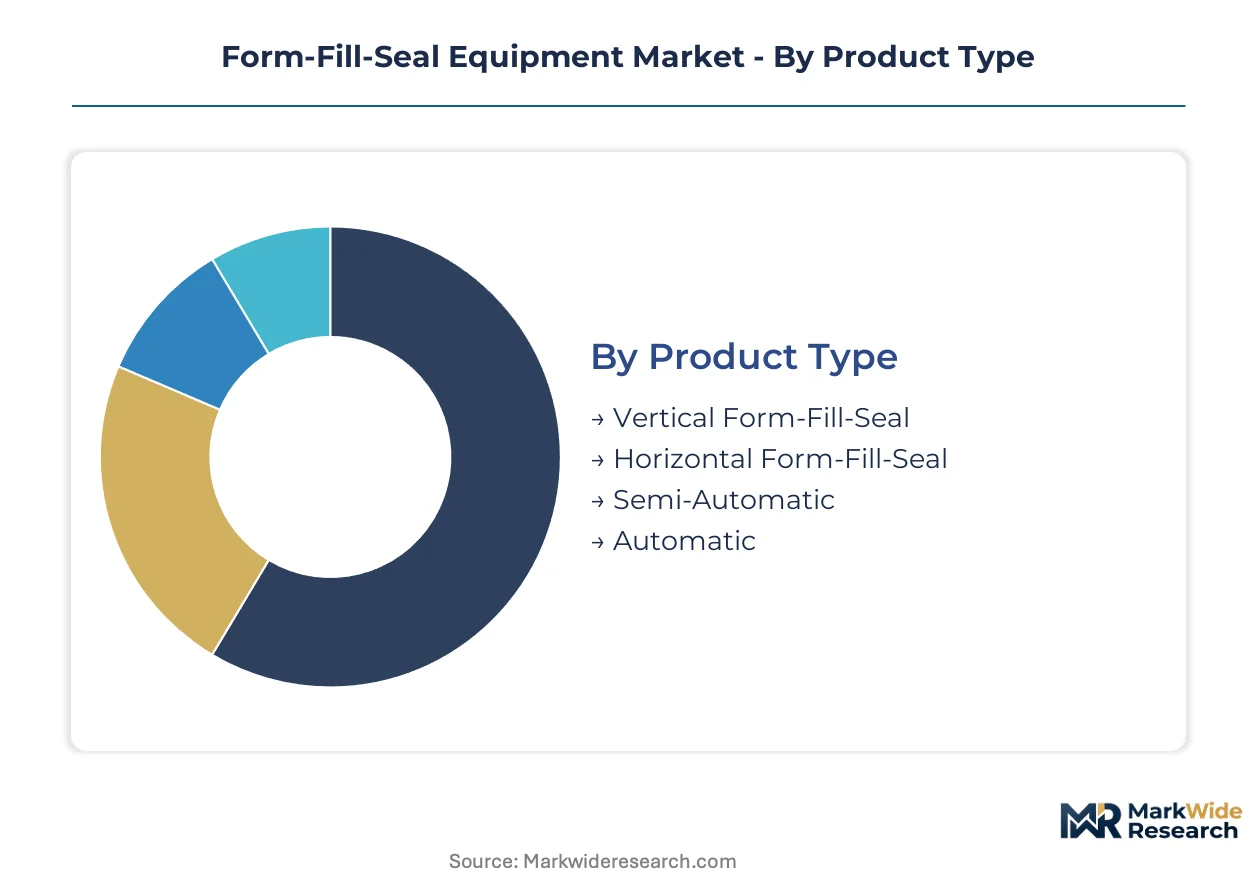
Form-fill-seal equipment segmentation reveals divergent compliance burdens across product categories. Pharmaceutical-grade systems demand FDA 21 CFR Part 11 and EMA Annex 15 validation, while food packaging lines navigate EU Packaging and Packaging Waste Regulation recyclability mandates.
Product Type:
Certification intensity varies sharply across product configurations, with pharmaceutical horizontal platforms requiring isolator integration and electronic signature capture that automatic vertical food systems rarely need.
- Vertical Form-Fill-Seal:These systems dominate high-speed pouch production for granular and liquid food products, operating at 100–300 cycles per minute with gravity-fed filling mechanisms. Demand concentrates in China's Yangtze Delta pharmaceutical corridor and India's Maharashtra food processing belt, where contract manufacturers prioritize footprint efficiency over isolator compatibility.
- Horizontal Form-Fill-Seal:Servo-driven platforms with isolator integration serve aseptic pharmaceutical applications, embedding audit trails and electronic batch records as standard architecture. German manufacturers in Baden-Württemberg anchor supply for EMA-compliant installations, though lead times extend due to specialized motion control component sourcing.
- Semi-Automatic:Mid-speed units serve small-batch spice and dairy cooperatives in emerging markets, offering quick format changeover without full automation capital burden.
- Automatic:Fully integrated lines with SCADA connectivity dominate multinational food processor deployments, particularly in French and British ready-meal manufacturing.
Automatic platforms sit at the top of the volume ranking, with Horizontal Form-Fill-Seal climbing the fastest on pharmaceutical sterility mandate expansion.
Technology:
Technology selection tracks directly to shelf-life extension requirements and barrier performance specifications, with capex intensity creating distinct buyer tiering.
- Thermoforming:Deep-draw forming systems with integrated cutting stations produce rigid trays for fresh protein and ready-meal applications. German and Dutch processors lead adoption as EU F-Gas Regulation phase-downs force CO2-based transcritical refrigeration redesigns in modified atmosphere configurations.
- Modified Atmosphere Packaging:Gas-flush systems with oxygen scavenging capabilities preserve organoleptic quality in pre-washed salads and cut fruits. Swiss and German pharmaceutical manufacturers specify these modules for biologic stability, though barrier coating reformulation under REACH perfluorinated restrictions compresses material options.
- Vacuum Packaging:Chamber-based systems dominate cured meat and cheese applications, with ultrasonic sealing modules displacing heat-seal jaws in mono-material film transitions.
- Stretch Film:Hooding and wrapping systems serve palletized logistics, with demand tied to e-commerce fulfillment center expansion rather than primary packaging lines.
Thermoforming commands the highest unit value, with Modified Atmosphere Packaging expanding most quickly on fresh protein shelf-life extension demand.
End User:
End-user concentration determines service model economics, with pharmaceutical buyers demanding localized validation support that food processors rarely require.
- Food & Beverages:The largest addressable base spans dairy, confectionery, and ready-meal manufacturing. Outcome-based performance contracts are displacing capital purchases among French and British multinational processors, tying OEM payments to verified uptime metrics.
- Pharmaceuticals:Injectable drug and powder packaging drives specification for isolator-integrated horizontal platforms with IEC 62443 cybersecurity certification. US Inflation Reduction Act domestic manufacturing incentives are accelerating reshoring demand for FDA-compliant systems with localized service support.
- Cosmetics:Premium skincare and fragrance packaging favors compact vertical systems with quick format changeover for seasonal SKU proliferation.
- Cleaning Products:Aggressive chemical compatibility requirements favor specialized film transport modules and corrosion-resistant filling valves in concentrated detergent applications.
Food & Beverages holds the installed base lead, with Pharmaceuticals gaining share fastest on sterility mandate expansion and reshoring incentives.
Package Type:
Package geometry dictates forming mechanism selection and film specification, with sustainability regulations accelerating mono-material transitions across all formats.
- Pouches:Flexible formats with spout and zipper integration dominate beverage and sauce applications. EU recyclability targets are redirecting specifications toward mono-PE and mono-PP structures compatible with existing heat-seal jaw geometries or ultrasonic sealing modules.
- Bags:Pillow and gusseted configurations serve bulk dry goods, with demand concentrated in Indian spice processing and Chinese grain packaging.
- Bottles:Blow-fill-seal integration serves pharmaceutical oral liquid and ophthalmic applications, requiring specialized sterile forming environments.
- Containers:Rigid cup and tray formats for fresh protein and ready-meals require thermoforming systems with integrated lid-sealing stations and modified atmosphere capabilities.
Pouches lead in unit volume, with Containers expanding fastest on ready-meal and fresh protein shelf-life extension demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States operate divergent investment cycles in pharmaceutical-grade packaging infrastructure, while China and India scale mid-speed vertical systems for domestic food processing demand.
United States
Domestic pharmaceutical manufacturers are reshoring sterile filling capacity under Inflation Reduction Act manufacturing incentives. FDA 21 CFR Part 11 validation protocols are forcing control architecture upgrades with embedded audit trails. The Greater Boston biopharma corridor anchors demand for isolator-integrated horizontal platforms serving injectable drug packaging.
Germany
EMA Annex 15 sterility mandates are retrofitting existing lines in the Baden-Württemberg machinery cluster with isolator-compatible configurations. REACH perfluorinated substance restrictions are compressing barrier coating options for high-oxygen-resistance films. Stuttgart-based engineering groups dominate aseptic pouch line supply for European pharmaceutical clients.
China
Domestic drug manufacturers in the Yangtze Delta pharmaceutical corridor are deploying high-speed vertical systems for multinational biopharma contract manufacturing. GB standards for food-contact materials are creating parallel certification burdens alongside Codex Alimentarius frameworks. Shanghai and Suzhou industrial zones concentrate cleanroom-compatible packaging line deployment.
India
Dairy and spice packaging cooperatives in the Maharashtra food processing belt represent underpenetrated demand for mid-speed automatic vertical platforms. FSSAI compliance requirements are accelerating equipment specification conversations toward quick format changeover capabilities. Mumbai-Pune industrial corridor processors are upgrading from semi-automatic to fully integrated lines.
Switzerland
Swissmedic-regulated biologic manufacturers are specifying ultrasonic sealing modules for temperature-sensitive pharmaceutical packaging. The Basel pharmaceutical hub anchors precision packaging equipment demand with isolator integration requirements. Domestic processors lead European adoption of hermetic seal technologies for mono-material film transitions.
Form-Fill-Seal Equipment Market Key Industry Players
German producers anchor one tier; Italian specialists hold positions in ceramic-based forming systems and beverage packaging configurations. The vendor base separates into consolidated multi-platform conglomerates and focused regional fabricators. Three strategic archetypes dominate: full-line integrators with captive component supply, regional specialists in format-specific applications, and private-equity-backed roll-up platforms. Competitive moves center on geographic expansion into underpenetrated emerging markets and technology licensing agreements for ultrasonic sealing modules.
Among Germany-based engineering groups, Robert Bosch GmbH and Syntegon occupy positions at the premium-system tier, while GEA Group AG anchors the integrated-component supply archetype. ProMach and Barry-Wehmiller Companies, Inc. exemplify the North American roll-up consolidation model with distributed brand portfolios. IMA Industria Macchine Automatiche S.p.A. represents Italian specialization in pharmaceutical and cosmetic packaging configurations.
| Leading Market Players |
|---|
| ProMach |
| Syntegon |
| Robert Bosch GmbH |
| IMA Industria Macchine Automatiche S.p.A. |
| Barry-Wehmiller Companies, Inc. |
| Bossar Packaging S.A. |
| SACMI Imola S.C. |
| Duravant |
| GEA Group AG |
| Others |
Cost & Logistics Intelligence
EU F-Gas Regulation phase-down schedules are gating qualified supply for modified atmosphere packaging systems while compressing premium-tier pricing access for CO2-compatible refrigeration architectures. German and Dutch processors now pay material premiums for transcritical manifold redesigns that comply with national carbon accounting requirements.
Pricing Analysis
Capacity additions in China's Yangtze Delta are reshaping price floors for mid-speed vertical platforms serving contract pharmaceutical manufacturing. Three-tier pricing structure across pharmaceutical-grade, food-grade, and semi-automatic economy levels separates isolator-integrated horizontal systems from standard vertical configurations. Cost compression in entry-level segments is intensifying because domestic Chinese suppliers are scaling servo-driven production. Small-batch dairy cooperatives in India exhibit highest price sensitivity, while Swiss biologic manufacturers show least sensitivity due to Swissmedic validation requirements.
Supply Chain Analysis
FDA 21 CFR Part 11 and EMA Annex 15 certification gating concentrates qualified component supply among German and Japanese precision motion control specialists. Servo motors, heat-seal jaw assemblies, and isolator modules draw from Baden-Württemberg engineering clusters and Tokyo-Osaka automation corridors. Single-source vulnerability in specialized filling valve architectures creates lead time exposure for pharmaceutical-grade platform builders. Distribution runs through OEM-direct service networks for validated installations and regional distributor channels for standard food-grade equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Form-Fill-Seal Equipment Market functions as a regulatory compounder where EMA Annex 15 sterility mandate expansion continuously regenerates replacement demand across European pharmaceutical infrastructure.
For Market Incumbents: Hedge exposure to REACH perfluorinated substance restrictions by accelerating ultrasonic sealing module R&D and securing captive supply of mono-material-compatible heat-seal jaw geometries. Acquire regional service capabilities in India's Maharashtra belt before domestic competitors consolidate aftermarket relationships with dairy cooperatives. For New Entrants and Emerging Players: FDA 21 CFR Part 11 compliance requirements in the United States open a window for specialized validation documentation services and cybersecurity certification consulting. Target mid-speed automatic vertical platforms for Indian spice processing cooperatives seeking FSSAI-compliant quick format changeover. Lead with outcome-based performance contracts that transfer uptime risk from processors to equipment suppliers. For Investors and Strategic Acquirers: Roll-up economics work for private-equity platforms because the vendor base fragments between full-line German integrators and regional Asian fabricators with limited export capabilities. Prioritize targets with installed base density in pharmaceutical corridors where regulatory requalification cycles generate recurring service revenue. Watch for IEC 62443 cybersecurity certification becoming mandatory inflection point in pharmaceutical buyer specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Ultrasonic Sealing Module Integration | Eliminates temperature-dependent dwell times for mono-material pharmaceutical packaging in Swiss and German facilities. |
| Isolator-Compatible Horizontal Platform Expansion | Captures EMA Annex 15 retrofit demand across Baden-Württemberg pharmaceutical manufacturing cluster. |
| CO2 Transcritical Refrigeration Redesign | Aligns modified atmosphere systems with EU F-Gas Regulation phase-down schedules in Dutch protein processing. |
| Outcome-Based Performance Contracting | Transfers uptime risk to OEMs among consolidated French and British ready-meal multinational processors. |
| Regional Service Network Buildout | Secures aftermarket relationships with Maharashtra dairy cooperatives upgrading from semi-automatic systems. |
Research Approach
Coverage spans Germany, United States, China, India, and Switzerland, with primary inputs from each market's pharmaceutical and food processing corridors. Equipment engineering directors, plant validation managers at sterile drug manufacturers, procurement leads at dairy cooperatives, and aftermarket service heads contributed structured interviews. Secondary validation drew from FDA 510(k) filings for packaging equipment, EMA GMP inspection databases, FSSAI equipment compliance circulars, and customs trade records for motion control component flows. Bottom-up unit economics triangulated against top-down sector spending estimates from pharmaceutical capital expenditure disclosures and food processor annual reports.
Granularity-level modeling distinguished pharmaceutical-grade horizontal platforms with isolator integration from standard vertical food systems across product type, technology, end-user, and package format dimensions. CAGRs were derived from segment-level unit shipment trajectories and average selling price evolution over the projection horizon. Forecast inputs incorporated REACH regulatory timeline assumptions, GB standards harmonization probability for Chinese food-contact materials, and Inflation Reduction Act domestic manufacturing incentive uptake rates in U.S. biopharma.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU Packaging and Packaging Waste Regulation enforcement or abrupt servo motor supply disruptions from Japanese component specialists. Model assumptions reflect documented regulatory trajectories and validated equipment procurement patterns. A model refresh is warranted upon material change in FDA cybersecurity guidance for industrial automation networks or Chinese GB standards convergence with Codex Alimentarius frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Injectable Liquid Filling Machines Market
Packaging Machinery
Tea Packing Machine Market
Packaging Machinery
CCL Laminating Machine Market
Packaging Machinery
Tissue Paper Unwinding Machine Market
Packaging Machinery
Automated Poly Bagging Machines Market
Packaging Machinery
Foil Embossing Machine Market
Packaging Machinery
Paper Slitting Machine Market
Packaging Machinery
Corrugated Box Printer Slotter Machine Market
Packaging Machinery
Precision Dispensing Machine Market
Packaging Machinery
Powder Auger Fillers Market
Packaging Machinery
Bottle Blowing Machine Market
Packaging Machinery
Bottle Capping Machines Market
Packaging Machinery
Product Dispensing Machinery Market
Packaging Machinery
Toilet Roll Converting Lines Market
Packaging Machinery
Automatic Liquid Filling Machines Market
Packaging Machinery
Cigarette Packaging Machine Market