
 Asia-Pacific Manual Resuscitators Market | 2026-2036
Asia-Pacific Manual Resuscitators Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Manual Resuscitators Market Outlook
Single-use silicone molding technology is reshaping how manual resuscitators achieve clinical-grade performance at lower unit costs. Laerdal Medical leverages its Nordic engineering heritage to dominate premium reusable segments across Australian tertiary hospitals. Ambu A/S sustains competitive positioning through vertical control over disposable bag production in Malaysia. ASIA CONNECTION anchors regional distribution networks, competing on price-accessibility for clinics in Vietnam and the Philippines.
Manual resuscitators are handheld ventilation devices comprising a self-inflating or flow-inflating bag, unidirectional valve assembly, and patient connector, typically manufactured from medical-grade silicone or PVC to deliver positive pressure breaths during respiratory arrest or insufficiency. Disposable bags command volume leadership due to infection control protocols, while silicone reusable variants retain margin concentration in Japanese and South Korean surgical centers. Emergency services represent the fastest-growing end user category, driven by ambulance fleet modernization and pre-hospital care expansion across Thailand and Malaysia.
China's NMPA enforces GB standard compliance for Class II medical devices, while India's CDSCO mandates BIS certification for imported resuscitation equipment, directly conditioning market entry timelines and local partnership requirements. Australia's TGA alignment with EU MDR technical documentation standards adds a third regulatory layer for suppliers seeking pan-regional scale. Stakeholders must monitor evolving ASEAN medical device harmonization talks, as unified technical standards would reshape competitive access across Southeast Asian procurement channels.
Market Dynamics
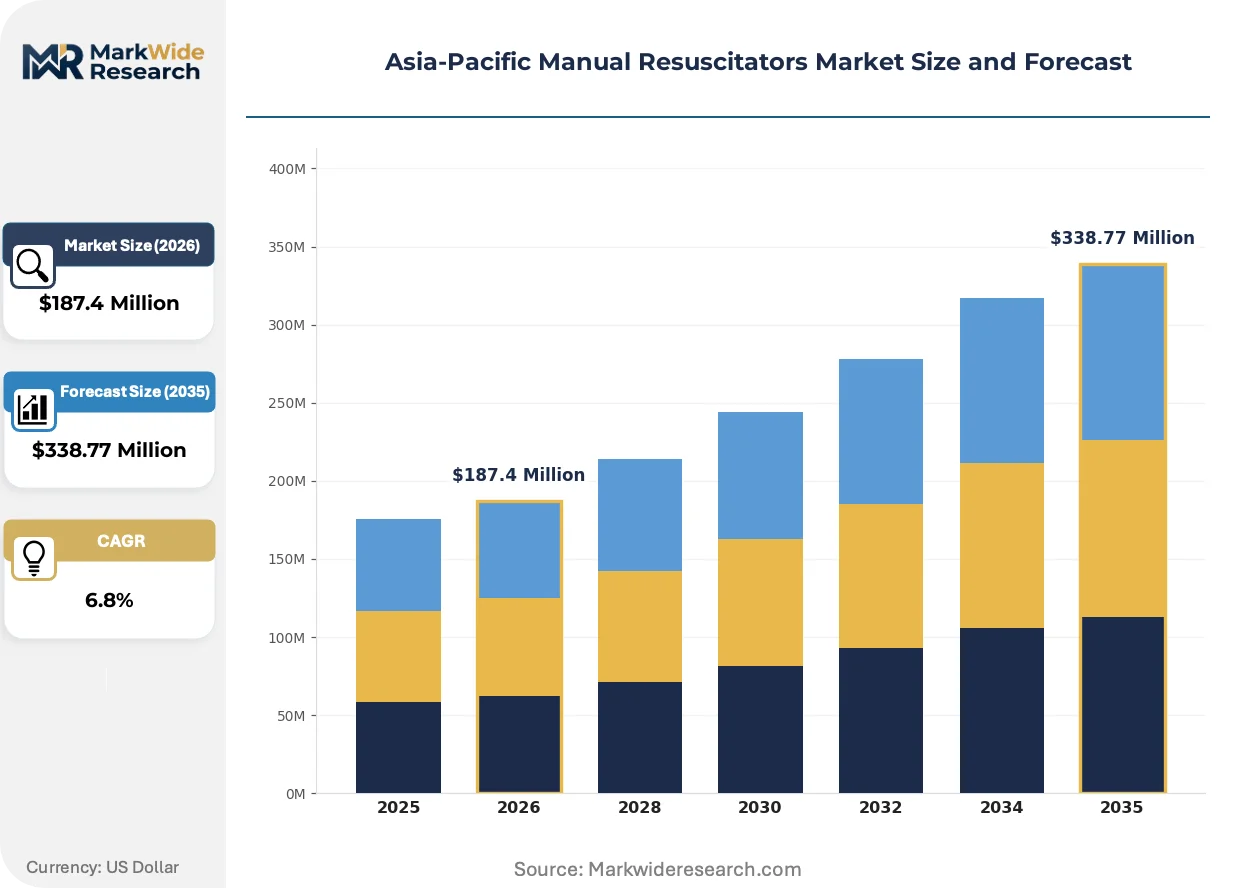
Single-use silicone molding is compressing unit economics across Asia-Pacific manual resuscitator manufacturing, forcing suppliers to recalibrate capacity allocation between premium reusable lines and high-volume disposable output.
Growth Catalysts
- CDSCO registration pathway streamlining:India's revised medical device rules are accelerating import clearances for Class II respiratory equipment, shortening hospital procurement cycles in tier-2 cities.
- Ambulance fleet electrification mandates:Thailand and Malaysia are expanding pre-hospital emergency networks, creating dedicated equipment budgets for portable ventilation devices.
- Silicone-to-PVC hybrid molding:Advances in co-extrusion bonding are lowering per-unit material costs while maintaining compliance with NMPA GB standards for patient-contact surfaces.
Market Restraints
- Medical-grade silicone price volatility:Petrochemical feedstock fluctuations are compressing margins for Malaysian and Thai bag manufacturers dependent on imported raw materials.
- NMPA technical documentation requirements:China's Class II device registration demands extensive clinical validation data, extending market entry timelines for non-domestic suppliers.
- Mechanical ventilator miniaturization:Portable emergency ventilators are encroaching on manual resuscitator use cases in Australian and Japanese tertiary transport settings.
Strategic Opportunities
- Indonesian provincial hospital networks:Underpenetrated emergency departments outside Java are consolidating procurement through regional health authorities, favoring bundled disposable resuscitator contracts.
- ASEAN medical device harmonization:Pending unified technical standards would eliminate redundant certification requirements across Vietnam, Philippines, and Cambodia distribution channels.
- Telemedicine-integrated pre-hospital care:Convergence of cellular telemetry and bag-valve monitoring is enabling real-time respiratory parameter transmission during ambulance transport.
Industry Challenges
- Biocompatibility testing backlog:ISO 10993 cytotoxicity validation queues at accredited laboratories are delaying product launches for new material formulations.
- Legacy equipment interoperability:Connecting disposable resuscitator monitoring outputs to existing hospital information systems requires custom interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Manual Resuscitators Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-expanding Bag, Flow-inflating Bag, Reusable Bag, Disposable Bag End User: Hospitals, Clinics, Emergency Services, Homecare Delivery Mode: Manual, Automated, Hybrid, Transport Material: Silicone, PVC, Thermoplastic, Rubber |
| Companies Covered | Laerdal Medical, Ambu A/S, Teleflex, Medline Industries, ASIA CONNECTION, ANGIPLAST, AirLife, VYAIRE, ResMed, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Manual Resuscitators Market Strategic Shifts
Pressure sensor integration and material science advances are redefining performance benchmarks for manual resuscitation devices across the Asia-Pacific region.
Embedded flow sensors within bag-valve assemblies are digitizing tidal volume and airway pressure capture during manual ventilation. Australian emergency medical services are piloting these systems for quality assurance documentation. This capability is digitizing retrospective performance analysis that previously relied on clinician estimation.
China's NMPA is enforcing stricter GB standard compliance for imported Class II respiratory devices, requiring localized clinical testing data. Domestic manufacturers are accelerating substitution of foreign suppliers in provincial tender processes. Japanese and South Korean surgical centers are responding by demanding dual-certified products meeting both NMPA and PMDA requirements.
Hospital procurement departments are consolidating resuscitator purchases through group purchasing organizations, displacing direct manufacturer relationships. Vietnamese and Philippine clinic networks are adopting this model fastest, shifting volume toward distributors with regional warehousing capabilities. Indonesia's provincial emergency networks represent the most visible concentration of this behavioral change.
Asia-Pacific Manual Resuscitators Market Segmentation
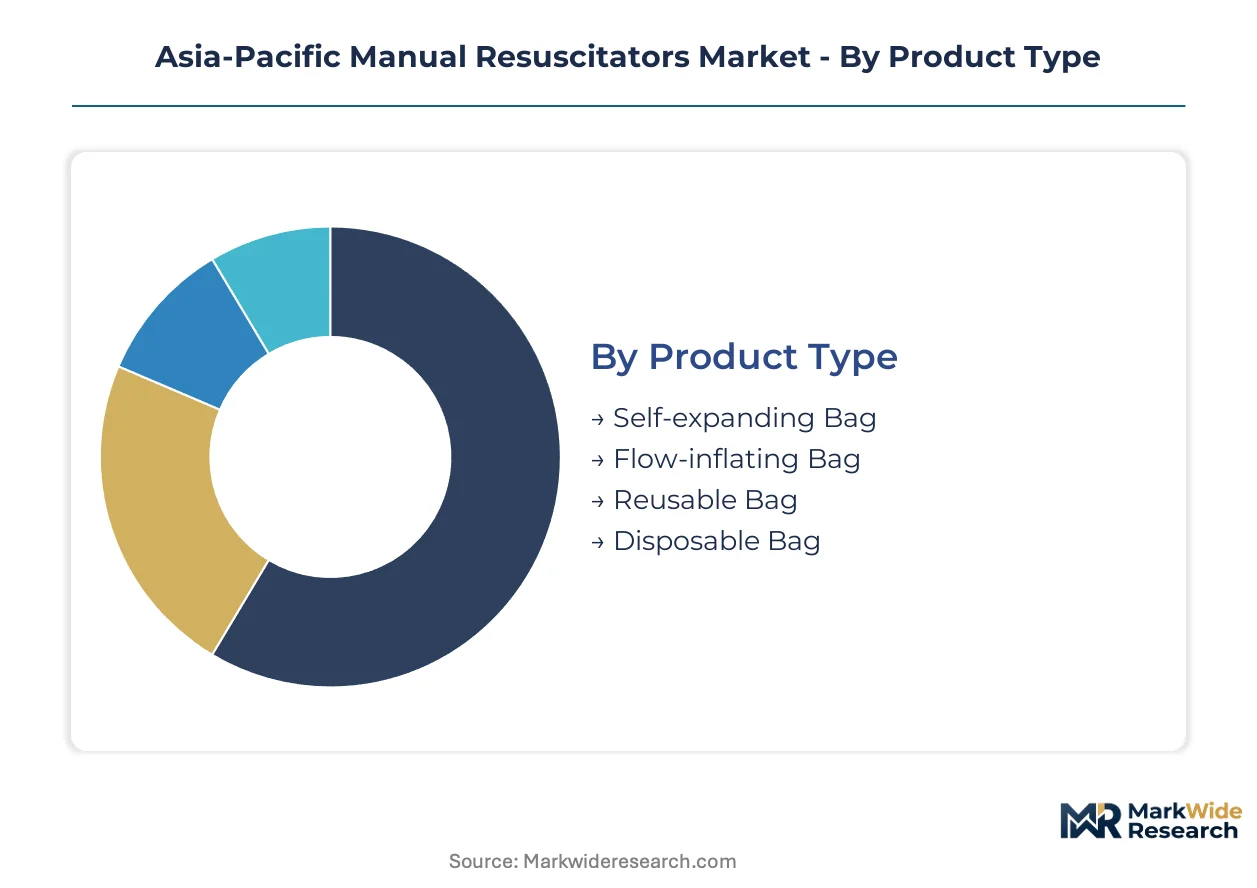
Segmentation in manual resuscitators reveals distinct procurement cycles and margin structures across product configurations, end-user environments, and material specifications. Understanding these divisions exposes where inventory velocity concentrates versus where long-term contracts lock in supplier relationships.
Product Type:
Disposable bags turn over fastest through infection-control protocols, while reusable silicone variants cycle slowly through sterilization departments and capital depreciation schedules.
- Self-expanding Bag:A self-inflating design incorporating a compressible reservoir that refills automatically between breaths, eliminating external gas source dependency. Demand concentrates in pre-hospital settings across Thailand and Malaysia where ambulance crews require equipment independence from onboard oxygen systems.
- Flow-inflating Bag:Requires continuous oxygen flow to maintain reservoir inflation, delivering precise FiO2 control through adjustable entrainment ports. Japanese and South Korean surgical centers specify these for operating room induction sequences where anesthetic gas mixing demands exact concentration management.
- Reusable Bag:Medical-grade silicone construction withstands repeated autoclave cycles, amortizing higher upfront cost across extended service life. Australian tertiary hospitals maintain centralized sterilization workflows for these units.
- Disposable Bag:Single-use PVC or silicone-blend construction eliminates cross-contamination risk between patients. Provincial emergency networks in Indonesia and Vietnam prioritize bulk procurement of these units.
Disposable Bag anchors the volume base while Flow-inflating Bag gains share at the steepest rate.
End User:
Procurement scale and decision velocity diverge sharply between institutional buyers with centralized purchasing authority versus distributed networks with fragmented equipment budgets.
- Hospitals:Tier-2 clusters in India and provincial facilities in Indonesia drive bulk disposable resuscitator contracts through group purchasing organizations with standardized technical specifications.
- Clinics:Smaller patient volumes and limited storage capacity favor compact disposable units procured through regional distributors with short replenishment cycles.
- Emergency Services:Ambulance fleet modernization across Thailand and Malaysia is expanding dedicated equipment budgets for portable ventilation devices with ruggedized construction and rapid deployment features.
- Homecare:Palliative respiratory support applications in Japan and Australia require lightweight designs with simplified valve mechanics for caregiver operation outside clinical supervision.
Emergency Services anchors the volume base while Homecare gains share at the steepest rate.
Delivery Mode:
Capital intensity and training requirements create a spectrum from basic manual operation through sensor-augmented systems with telemetry integration.
- Manual:Unassisted bag-valve-mask technique dependent on operator skill for tidal volume and rate control. Remains dominant in resource-constrained settings across the Philippines and Cambodia.
- Automated:Mechanical compression mechanisms deliver consistent ventilation parameters, reducing operator fatigue during extended resuscitation. Australian emergency medical services are piloting these for quality assurance documentation.
- Hybrid:Combines manual override capability with automated backup cycling, bridging skill gaps in mixed-credential response teams. Indian tier-2 hospitals specify these for emergency department staffing flexibility.
- Transport:Compact designs with integrated monitoring outputs for ambulance and aeromedical evacuation applications. Malaysian pre-hospital networks are consolidating procurement around these specifications.
Manual anchors the volume base while Hybrid gains share at the steepest rate.
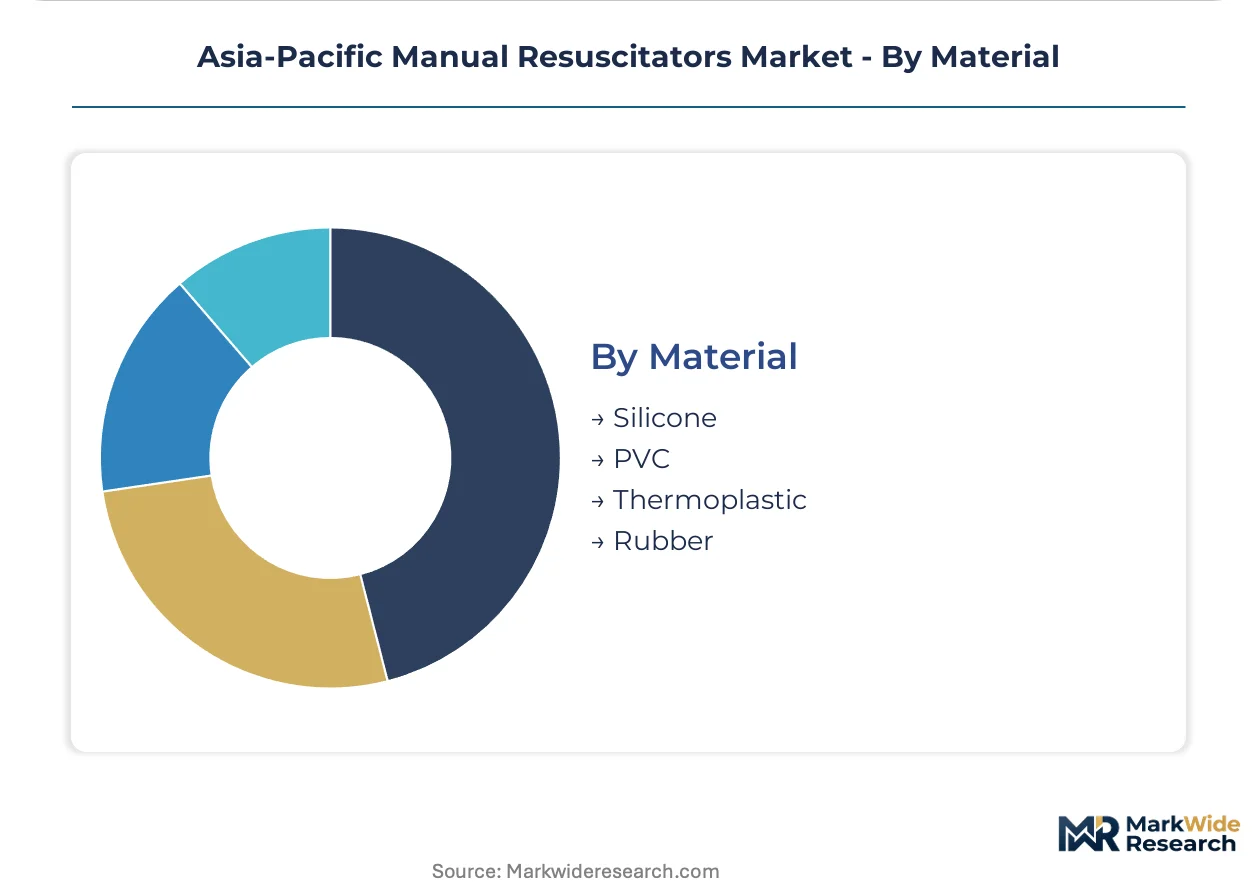
Material:
Raw material cost structures and biocompatibility certification burdens stratify supplier capabilities across the polymer spectrum.
- Silicone:Platinum-cured medical-grade formulation delivers superior biocompatibility and temperature resistance for reusable applications. Japanese surgical centers demand dual-certified products meeting both PMDA and NMPA requirements.
- PVC:Lower material cost enables high-volume disposable production, though plasticizer migration concerns drive formulation evolution toward DEHP-free alternatives. Malaysian manufacturers face margin pressure from petrochemical feedstock volatility.
- Thermoplastic:Injection-moldable elastomers offer design flexibility for complex valve geometries with reduced assembly labor. Emerging adoption in Chinese domestic manufacturing for provincial tender processes.
- Rubber:Natural and synthetic latex formulations persist in legacy equipment fleets, though allergy prevalence is displacing demand toward synthetic alternatives. Limited to replacement parts in established Australian hospital systems.
PVC anchors the volume base while Silicone gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments and ambulance fleet operators drive equipment demand across the Asia-Pacific region, with regulatory frameworks from NMPA, CDSCO, and TGA conditioning market access timelines and partnership requirements.
China
Provincial hospital networks outside tier-1 cities are consolidating respiratory equipment purchases through centralized tender processes. NMPA enforces GB standard compliance for Class II medical devices, requiring localized clinical validation data for imported resuscitators. Domestic manufacturers in the Yangtze River Delta are accelerating substitution of foreign suppliers in provincial procurement channels.
India
Tier-2 hospital clusters in Maharashtra and Gujarat are expanding emergency department capacity with standardized disposable resuscitator contracts. CDSCO medical device rules mandate BIS certification for imported equipment, shortening import clearance timelines for compliant suppliers. Delhi-NCR distributors are building regional warehousing networks to serve clinic procurement consolidation.
Japan
Surgical centers in Kanto and Kansai regions maintain demand for dual-certified reusable silicone resuscitators meeting both PMDA and NMPA requirements. METI industrial standards support precision manufacturing capabilities for medical-grade silicone molding. Osaka-based sterilization service providers are extending equipment lifecycle management contracts to tertiary hospitals.
Australia
TGA alignment with EU MDR technical documentation standards creates a dual-compliance pathway for suppliers seeking pan-regional scale. New South Wales and Victoria emergency medical services are piloting sensor-integrated bag-valve systems for quality assurance documentation. Sydney distributors are consolidating procurement for regional hospital networks through group purchasing organizations.
Indonesia
Provincial emergency networks outside Java are consolidating procurement through regional health authorities, favoring bundled disposable resuscitator contracts. The national health ministry is expanding pre-hospital care budgets for ambulance fleet modernization. Surabaya and Medan distribution hubs are capturing volume from fragmented clinic procurement in Eastern Indonesia.
Asia-Pacific Manual Resuscitators Market Competitive Environment
Channel-controlling players compete with product-specialist players across a bifurcated structure where premium reusable segments and high-volume disposable lines operate on distinct margin profiles. The vendor base separates into three tiers: Nordic-engineered premium specialists, vertically integrated disposable manufacturers, and regional price-accessibility distributors. Consolidation pressures favor backward integration into silicone molding capacity and strategic partnerships with group purchasing organizations.
Within the premium-engineering tier, Laerdal Medical exemplifies heritage-driven positioning in tertiary hospital segments. Among vertically integrated disposable specialists, Ambu A/S anchors manufacturing scale through captive bag production. On the regional distribution vector, ASIA CONNECTION occupies a price-accessibility position for clinic networks in Southeast Asian markets. These three archetypes represent the dominant competitive vectors shaping procurement relationships across the region.
| Leading Market Players |
|---|
| Laerdal Medical |
| Ambu A/S |
| Teleflex |
| Medline Industries |
| ASIA CONNECTION |
| ANGIPLAST |
| AirLife |
| VYAIRE |
| ResMed |
| Others |
Value Chain & Pricing Dynamics
Medical-grade silicone price volatility driven by petrochemical feedstock fluctuations determines both the spread between premium reusable and economy disposable tiers and the geographic configuration of bag manufacturing across Southeast Asia. Malaysian and Thai producers face margin compression that accelerates backward integration into captive silicone compounding while tier-2 Indian hospitals exploit procurement consolidation to compress distributor markups.
Pricing Analysis
Cost-plus contracts indexed to silicone resin spot markets dominate bulk procurement agreements for disposable resuscitators across Indonesian provincial networks. Price differentiation separates platinum-cured silicone reusable units with dual PMDA-NMPA certification from DEHP-free PVC disposables procured through group purchasing organizations. Pricing pressure stems from Chinese domestic manufacturers undercutting imported Class II devices in provincial tender processes. Tier-2 hospital clusters in India exhibit highest price sensitivity, while Japanese surgical centers prioritize certification grade over unit cost.
Supply Chain Analysis
Upstream medical-grade silicone compounding concentrates in Japan, Germany, and select Chinese Yangtze River Delta facilities, with Malaysian and Thai bag manufacturers drawing from imported feedstock. Raw material dependencies include platinum catalyst systems, DEHP-free plasticizer formulations, and precision valve elastomers. Single-source vulnerability persists for platinum-cured silicone grades meeting dual-certification requirements. Distribution runs through regional health authority tenders in Indonesia, GPO contracts in India, and specialized emergency equipment distributors in Australia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
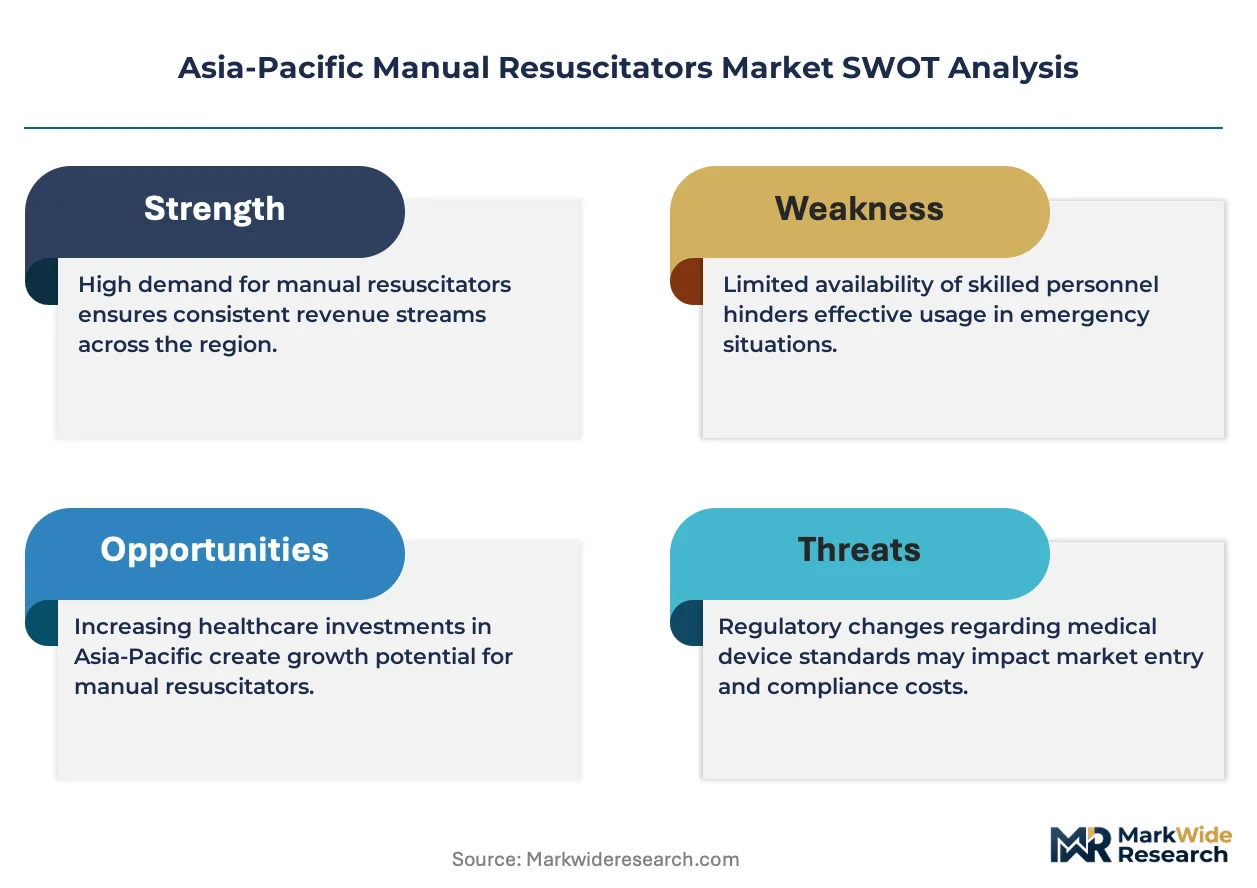
Scarcity of biocompatibility testing capacity at ISO 10993-accredited laboratories creates bottlenecks that favor incumbents with established validation queues and partnerships with certified testing facilities.
For Market Incumbents: Pre-empt displacement by portable emergency ventilators through embedding pressure sensor telemetry into bag-valve assemblies for quality assurance documentation. Secure backward integration into silicone molding capacity in Malaysia or Thailand to insulate margins from petrochemical feedstock volatility. Prioritize CDSCO registration pathway investments to accelerate import clearances before India's tier-2 hospital consolidation hardens supplier relationships. For New Entrants and Emerging Players: Pursue white-space positioning in Indonesian provincial emergency networks outside Java where regional health authority bundling favors price-accessible disposable contracts. Target Vietnamese clinic networks adopting group purchasing organization procurement models fastest. Enter through regional distribution partnerships with Surabaya or Medan warehousing capabilities rather than direct manufacturer relationships. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated disposable manufacturers with captive bag production and established GPO relationships. Long-term viability hinges on regulatory compliance capabilities across NMPA, CDSCO, and TGA frameworks rather than pure manufacturing scale. Acquisition targets should demonstrate ISO 10993 validation partnerships and regional distributor control. Monitor ASEAN medical device harmonization talks as the signal for cross-border procurement rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Registration Fast-Track | Accelerates market entry timelines before India's tier-2 hospital procurement consolidation solidifies. |
| Silicone Molding Capacity Expansion | Captures margin compression relief from petrochemical feedstock volatility in Malaysian manufacturing. |
| Sensor-Integrated Bag-Valve Development | Differentiates against portable ventilator substitution in Australian emergency medical services pilots. |
| GPO Partnership Consolidation | Locks in volume commitments from Vietnamese and Philippine clinic network procurement shifts. |
| Dual-Certification Investment | Opens Japanese surgical center demand requiring simultaneous PMDA and NMPA compliance. |
Study Parameters
Cross-validation between primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and emergency medical services equipment officers anchors the qualitative findings. Secondary validation draws from CDSCO medical device registration databases, NMPA Class II device approval records, Australian TGA conformity assessment documentation, and ASEAN medical device harmonization working papers. Bottom-up demand modeling across product configurations, end-user environments, and material specifications triangulates against top-down market sizing from regional procurement data.
Calibration against historical CAGRs from comparable respiratory device categories and sensitivity testing across regulatory approval timeline scenarios shapes the projection framework. Segmentation dimensions span self-expanding versus flow-inflating designs, disposable versus reusable construction, emergency services versus hospital versus homecare end users, and silicone versus PVC versus thermoplastic materials. Growth trajectories incorporate ambulance fleet electrification mandates in Thailand and Malaysia, CDSCO pathway streamlining effects, and silicone-to-PVC hybrid molding adoption curves.
Sensitivities concentrate around NMPA technical documentation requirement changes, medical-grade silicone price volatility, and mechanical ventilator miniaturization encroachment. Forecasts reflect assumptions regarding ASEAN harmonization implementation timing and provincial tender process consolidation rates. Cross-checking against hospital procurement database benchmarks and GPO contract disclosure patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
MRI Safe Biopsy Needle Market
Medical Devices
Endoscope Procedure Kits Market
Medical Devices
Transcranial Magnetic Stimulation System Market
Medical Devices
Breast Lesion Localization Device Market
Medical Devices
Global Blood Ketone Meter Market
Medical Devices
Active Implantable Devices Market
Medical Devices
Sharps Destruction Device Market
Medical Devices
Canada Digital X-Ray Devices Market
Medical Devices
Ultrasound Biometry Devices Market
Medical Devices
US Nurse Call Systems Market
Medical Devices
Cryosurgery Devices Market
Medical Devices
Foot and Ankle Allograft Market
Medical Devices
Global Transradial Access Market
Medical Devices
Medical LED Headlight Market
Medical Devices
Manual Resuscitators Market
Medical Devices
Artificial Cartilage Implant Market