
 Oscillating Positive Expiratory Pressure (OPEP) Devices Market | 2026-2036
Oscillating Positive Expiratory Pressure (OPEP) Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Oscillating Positive Expiratory Pressure (OPEP) Devices Market Analytics
European medical device manufacturers is expanding OPEP production capacity to serve the EU MDR transition timeline. Trudell Medical International leverages its respiratory specialization to sustain premium positioning across North American and European channels. PARI GmbH anchors German engineering credibility in nebulizer-adjacent device categories. Smiths Medical competes through hospital-system contracts and critical-care channel control.
Oscillating Positive Expiratory Pressure devices generate oscillating airflow resistance during exhalation, typically operating at frequencies between 10–30 Hz to mobilize airway secretions through vibratory shear forces on mucus. These devices serve primarily as adjunctive therapy for obstructive pulmonary conditions where retained secretions compromise gas exchange and increase infection risk. Handheld devices dominate unit volume due to low cost and patient self-administration suitability, while portable units capture faster growth as travel-friendly designs expand addressable use cases beyond stationary home settings. Healthcare facilities remain the largest value channel despite home care's accelerating volume expansion, reflecting institutional procurement scale and clinical staff training infrastructure.
FDA 510(k) premarket notification governs US market entry for OPEP devices, while the EU MDR requires updated technical documentation and clinical evaluation reports for CE marking continuity. Japan's PMDA enforces QMS conformity assessments that extend approval timelines relative to US pathways, creating staggered launch sequencing across major markets. Stakeholders must monitor reimbursement code revisions in Medicare and national health systems, as coding coverage directly determines patient out-of-pocket exposure and physician prescribing behavior.
Market Dynamics
Home care migration is compressing traditional hospital procurement cycles as patients self-administer OPEP therapy under remote monitoring protocols, forcing manufacturers to redesign devices for unsupervised use while maintaining clinical efficacy standards.
Growth Catalysts
- EU MDR compliance deadlines:European manufacturers are accelerating CE marking renewals ahead of regulatory cutoffs, expanding production lines to capture market share from laggards facing documentation gaps.
- Post-acute respiratory rehabilitation:Hospital discharge protocols now integrate OPEP devices for COPD and bronchiectasis patients, creating institutional pull-through into home settings.
- Aging demographics in Japan:METI's silver economy initiatives prioritize respiratory homecare infrastructure, with PMDA streamlining QMS assessments for established device categories.
Market Restraints
- Medical-grade polymer supply concentration:Specialized thermoplastics for biocompatible mouthpieces source predominantly from German and US chemical suppliers, exposing margins to petrochemical volatility.
- EU MDR clinical evidence requirements:Updated technical documentation and post-market surveillance obligations extend CE marking timelines by 12-18 months for legacy device portfolios.
- Mechanical percussion substitutes:High-frequency chest wall oscillation vests retain institutional preference for severe secretion management, limiting OPEP penetration in ICU step-down units.
Strategic Opportunities
- Remote patient monitoring integration:Bluetooth-enabled OPEP devices feeding data to cloud-based adherence platforms align with Medicare's expanding remote therapeutic monitoring reimbursement codes.
- Pediatric asthma maintenance:Gamified device designs for children aged 6-12 address an underserved segment with distinct oscillation frequency and mask interface requirements.
- India's PLI scheme for medical devices:Domestic manufacturing incentives reduce import duty exposure for multinational entrants establishing local assembly operations.
Industry Challenges
- Biomedical engineering talent scarcity:Respiratory device R&D requires hybrid expertise in fluid dynamics and human factors design, with specialized programs concentrated at RWTH Aachen and MIT.
- FDA 510(k) predicate device drift:Evolving substantial equivalence standards for oscillation mechanism claims demand iterative clinical validation studies, extending US market entry timelines.
- Legacy hospital inventory amortization:Health system capital budgets prioritize MRI and ventilator replacements over OPEP fleet upgrades, delaying next-generation device adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oscillating Positive Expiratory Pressure (OPEP) Devices Market |
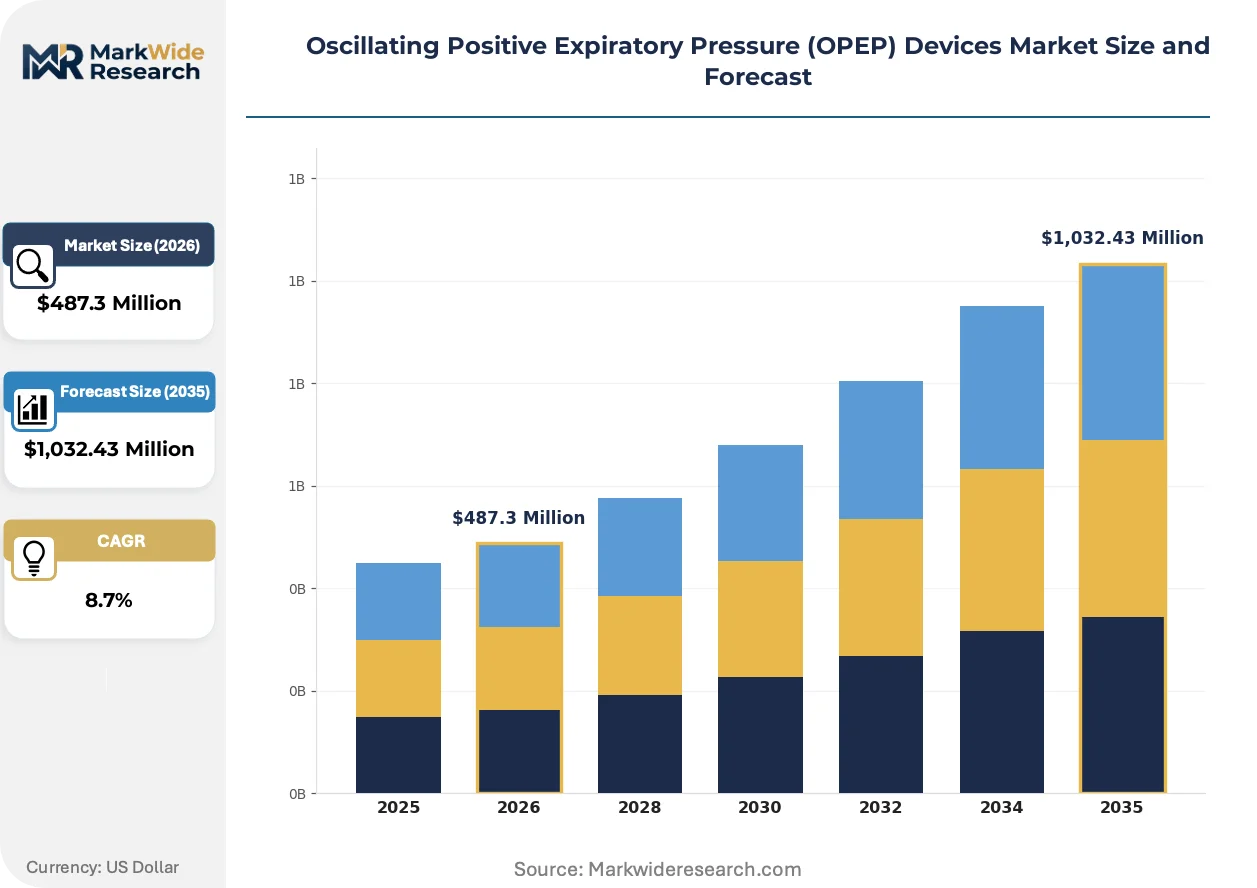
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Devices, Portable Units, Tabletop Models, Animated Devices End User: Pediatric Patients, Adult Patients, Home Care Providers, Healthcare Facilities Application: COPD Management, Asthma Treatment, Lung Rehabilitation, Post-operative Care Distribution Channel: Pharmacies, Online Retailers, Hospitals, Medical Supply Stores |
| Companies Covered | Trudell Medical International, Allergan Plc, PARI GmbH, Smiths Medical, AirPhysio, D-R Burton Healthcare, Medica Holdings, LLC, Monaghan Medical, Mercury Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oscillating Positive Expiratory Pressure (OPEP) Devices Market Evolving Landscape
Connected health architectures and materials science advances are redefining device form factors, while regulatory frameworks on both sides of the Atlantic force portfolio rationalization decisions.
Smart OPEP devices with embedded pressure sensors and real-time feedback displays are electrifying the boundary between passive mechanical therapy and active digital health engagement. Home care providers and accountable care organizations are piloting these units for high-risk COPD cohorts. The technology is compressing adherence monitoring costs while opening subscription revenue streams previously captured by telehealth platforms.
Japan's PMDA has tightened QMS conformity assessment intervals for Class II respiratory devices, requiring annual manufacturing site audits rather than triennial reviews. Domestic manufacturers are consolidating supplier bases to reduce audit complexity. Foreign entrants face extended approval sequencing as PMDA prioritizes applications from companies with established Japanese pharmacovigilance infrastructure.
Direct-to-patient subscription models are displacing durable medical equipment distributor networks for premium OPEP devices. Sleep apnea device veterans entering respiratory therapy are leveraging existing e-commerce fulfillment capabilities. This channel rotation is most visible in Germany and the United States, where out-of-pocket thresholds for DME coverage drive cash-pay adoption among commercially insured households.
Oscillating Positive Expiratory Pressure (OPEP) Devices Market Segmentation
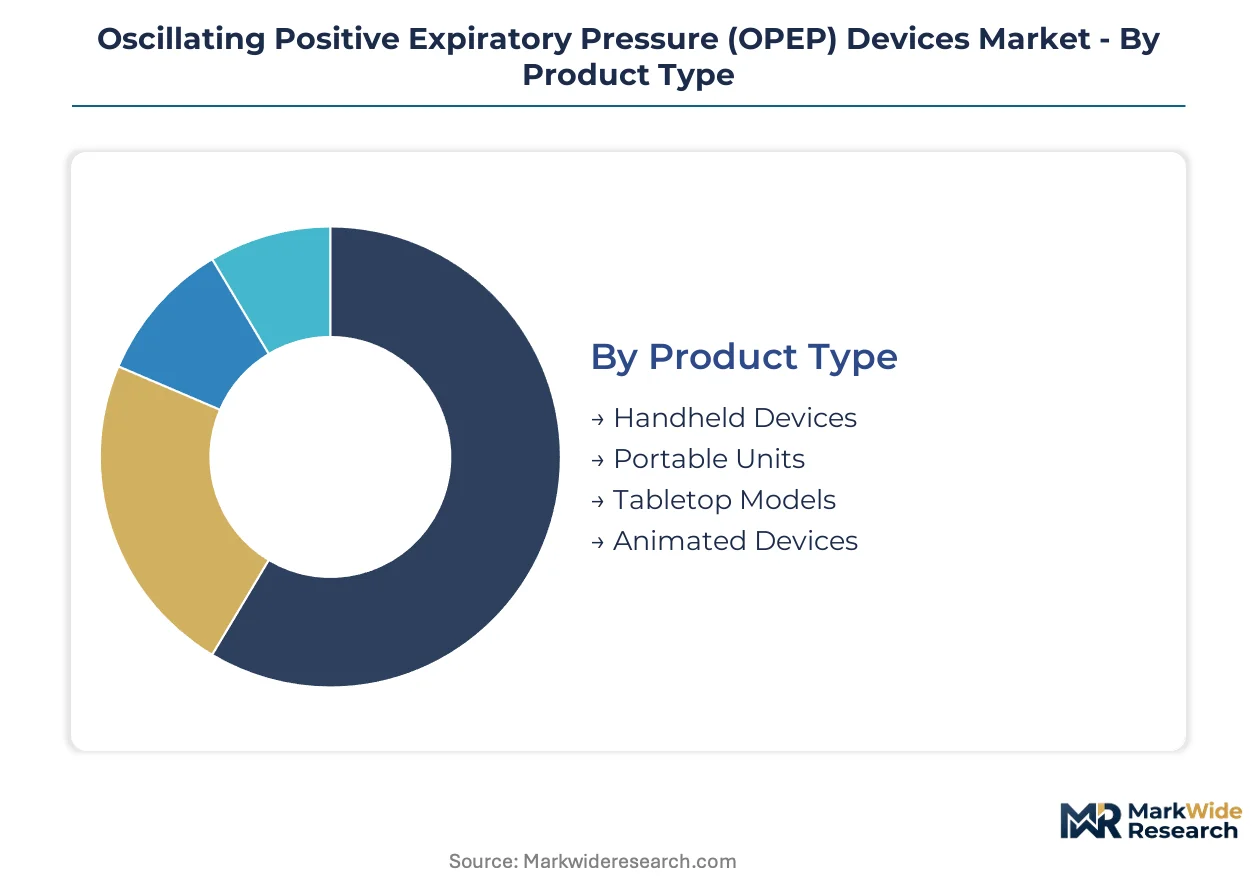
OPEP device segmentation reveals divergent upgrade cycles across mechanical and electronic product tiers. Pediatric and home care applications are compressing replacement timelines as manufacturers integrate connected health features.
Product Type:
Replacement cycles vary sharply between passive mechanical designs and sensor-enabled electronic units, with warranty periods and battery life dictating refresh economics.
- Handheld Devices:Spring-loaded or gravity-dependent mechanisms generate oscillating backpressure without power requirements. Demand clusters in Germany and Japan where outpatient COPD protocols emphasize patient self-administration and cost containment.
- Portable Units:Battery-powered oscillators with adjustable frequency settings enable travel-compatible therapy. Home care providers in the United States are standardizing on these for remote monitoring integration.
- Tabletop Models:Clinic-grade units with calibrated pressure displays serve pulmonary rehabilitation centers.
- Animated Devices:Gamified interfaces with visual feedback targets pediatric adherence improvement.
Volume placements concentrate in Handheld Devices; the faster expansion belongs to Portable Units.
End User:
Procurement authority is fragmenting across clinical settings as reimbursement shifts from facility-based billing to patient-directed durable medical equipment allowances.
- Pediatric Patients:Age-appropriate mask interfaces and reduced oscillation amplitudes address anatomical constraints. Germany's pediatric pulmonology networks are expanding device lending libraries to reduce family out-of-pocket exposure.
- Adult Patients:Standard mouthpiece configurations dominate COPD and bronchiectasis maintenance protocols. United States Medicare Advantage plans are piloting direct-to-patient shipping for chronic condition management.
- Home Care Providers:Multi-patient device fleets with disposable mouthpiece protocols serve post-acute respiratory therapy.
- Healthcare Facilities:Capital equipment budgets prioritize ventilator and imaging upgrades over OPEP fleet refreshes.
Healthcare Facilities retain the largest procurement scale; Home Care Providers are climbing the fastest.
Application:
Clinical evidence requirements differ across acute intervention versus chronic maintenance indications, shaping regulatory submission strategies.
- COPD Management:Long-term secretion clearance protocols reduce exacerbation frequency and hospital readmission rates. Japan's METI silver economy initiatives are subsidizing home-based respiratory therapy for elderly COPD cohorts.
- Asthma Treatment:Adjunctive mucus mobilization for severe persistent cases complements inhaled corticosteroid regimens. Pediatric asthma programs in Germany are integrating OPEP into school-based care coordination.
- Lung Rehabilitation:Pre- and post-operative conditioning protocols in thoracic surgery units.
- Post-operative Care:Prophylactic secretion management following abdominal or cardiac procedures.
COPD Management anchors installed base volume; Asthma Treatment shows the steepest expansion trajectory.
Distribution Channel:
Channel margins compress as direct-to-patient subscription models displace traditional durable medical equipment distributor networks.
- Pharmacies:Community-based respiratory therapist counseling supports device selection and technique training. Japan's pharmacy reimbursement codes now cover OPEP instruction fees.
- Online Retailers:E-commerce fulfillment enables cash-pay bypass of insurance prior authorization delays. United States sleep apnea device veterans are leveraging existing direct-to-consumer infrastructure.
- Hospitals:Discharge planning departments coordinate device provisioning for post-acute transitions.
- Medical Supply Stores:Regional durable medical equipment dealers with respiratory specialization.
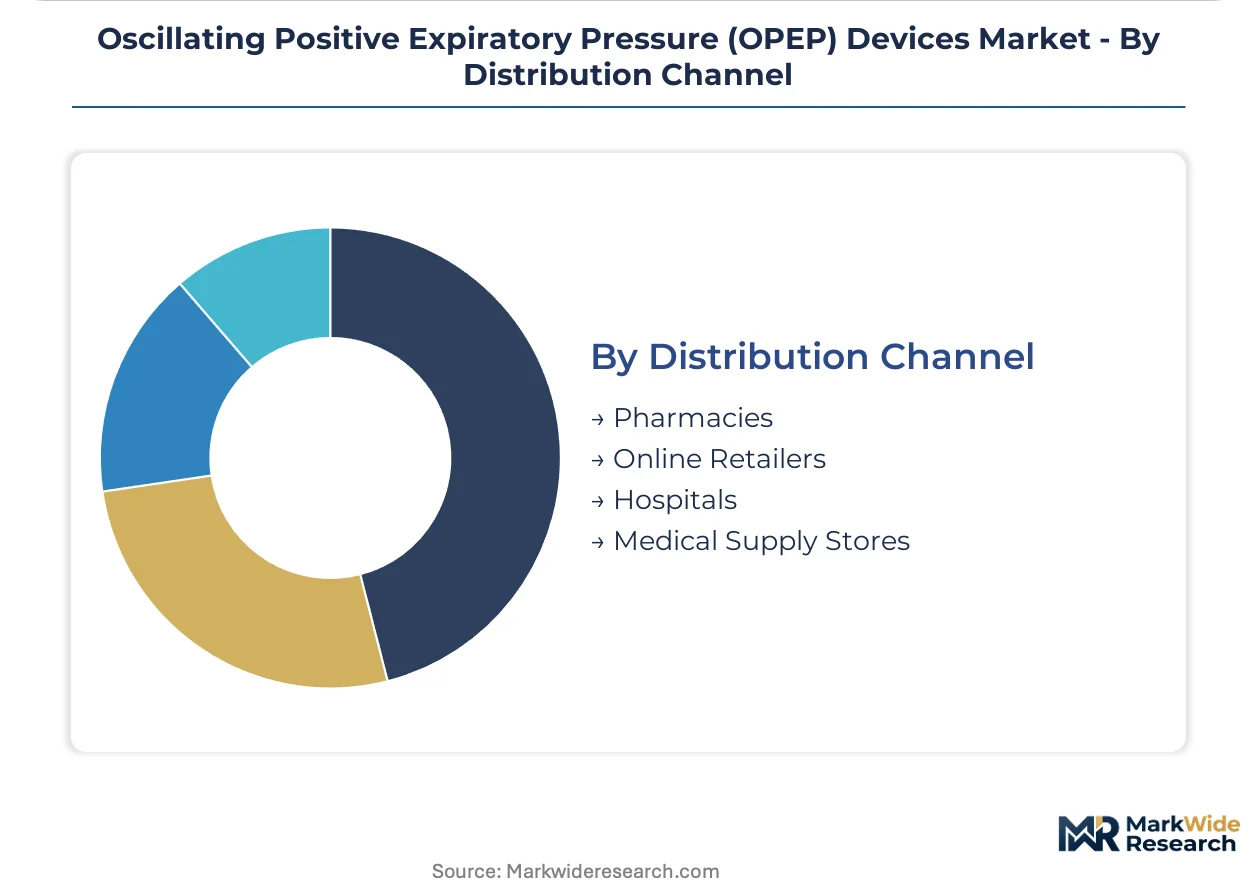
Hospitals process the highest transaction values; Online Retailers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade polymer supply chains in Germany's Ruhr industrial corridor anchor European OPEP manufacturing capacity, with specialized thermoplastic mouthpiece production concentrating near Leverkusen and Düsseldorf chemical clusters.
United States
Medicare Advantage remote therapeutic monitoring expansion drives home care device procurement from pulmonary rehabilitation discharge protocols. FDA 510(k) premarket notification pathways govern oscillation mechanism claims, with predicate device standards tightening for new entrants. Minnesota's Twin Cities medical device corridor hosts respiratory technology R&D clusters serving hospital-system contract channels.
Germany
Outpatient COPD cost-containment protocols prioritize patient self-administered secretion clearance therapy. EU MDR clinical evidence requirements and post-market surveillance obligations compress CE marking timelines for legacy device portfolios. Baden-Württemberg's precision engineering clusters around Stuttgart supply oscillating valve components to domestic manufacturers.
Japan
METI silver economy infrastructure subsidies accelerate home-based respiratory therapy penetration among elderly COPD cohorts. PMDA tightened QMS conformity assessment intervals to annual manufacturing site audits, extending foreign entrant approval sequencing. Osaka-Kobe medical device production zones concentrate pediatric mask interface manufacturing for regional export.
India
PLI scheme domestic manufacturing incentives reduce import duty exposure for multinational assembly operations targeting price-sensitive hospital procurement. CDSCO medical device rules harmonize with IMDRF standards for Class II respiratory device registration. Gujarat's Special Economic Zones host emerging medical plastics molding capacity serving South Asian distribution networks.
United Kingdom
NHS long-term plan respiratory disease targets expand community-based mucus clearance therapy provision. MHRA post-Brexit regulatory autonomy maintains CE marking recognition while building UKCA capacity for dual-market device submissions. Cambridge-Oxford medical technology corridor attracts connected health startups integrating pressure sensor feedback architectures.
Oscillating Positive Expiratory Pressure (OPEP) Devices Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance capabilities and home care channel penetration, producing a tiered structure where respiratory specialization separates premium positioning from commodity mechanical device suppliers. Market concentration reflects FDA 510(k) clearance accumulation and EU MDR technical documentation capacity rather than scale economics alone. Three archetypes dominate: dedicated respiratory device specialists leveraging clinical evidence libraries; diversified medical technology conglomerates accessing hospital-system procurement contracts; and direct-to-consumer entrants exploiting e-commerce fulfillment infrastructure. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with manufacturers securing polymer supply agreements and cloud platform alliances for remote monitoring integration.
Among North American respiratory specialists, Trudell Medical International and Monaghan Medical exemplify dedicated device archetypes with accumulated predicate device portfolios, while Smiths Medical occupies a diversified conglomerate position accessing critical-care channel infrastructure. PARI GmbH anchors German engineering credibility in nebulizer-adjacent categories, representing regional precision manufacturing advantages. These named entities illustrate how geographic origin and corporate structure shape competitive positioning without determining specific strategic outcomes.
| Leading Market Players |
|---|
| Trudell Medical International |
| Allergan Plc |
| PARI GmbH |
| Smiths Medical |
| AirPhysio |
| D-R Burton Healthcare |
| Medica Holdings, LLC |
| Monaghan Medical |
| Mercury Medical |
| Others |
Value Network & Pricing Analysis
Medical-grade polymer resin costs cascade through OPEP device manufacturing tiers, with biocompatible thermoplastic pricing for mouthpiece components separating premium electronic units from economy mechanical designs. German and US chemical suppliers anchor upstream material costs, while downstream buyers in Medicare Advantage and Japan's METI-subsidized programs absorb tiered pricing through reimbursement differentials.
Pricing Analysis
Warranty bundling and calibration service packages distinguish clinic-grade tabletop models from disposable handheld alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status and Bluetooth connectivity inclusion. Pricing pressure stems from direct-to-patient subscription models bypassing durable medical equipment distributor markups. Home care providers exhibit highest price sensitivity due to multi-patient fleet procurement volumes, while hospital systems tolerate premium tiers for integrated remote monitoring capabilities.
Supply Chain Analysis
Dual-sourcing mandates from Japanese PMDA and EU MDR compliance auditors require manufacturers to qualify secondary polymer suppliers for mouthpiece production. Component sourcing concentrates in Germany's Ruhr corridor for thermoplastics, US Gulf Coast for specialty resins, and Osaka-Kobe zones for pediatric mask interfaces. Raw material dependencies include medical-grade polypropylene, silicone elastomers, and lithium-ion cells for electronic units. Supply chain risk centers on petrochemical price volatility feeding into biocompatible material costs. Distribution runs through hospital-system procurement contracts, direct-to-patient e-commerce platforms, and pharmacy respiratory therapist networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OPEP device manufacturing is consolidating around regulatory compliance scale, with EU MDR documentation burdens and FDA 510(k) predicate drift forcing sub-scale mechanical device suppliers toward exit or acquisition.
For Market Incumbents: Lock in polymer supply agreements with Leverkusen and Düsseldorf chemical clusters to secure mouthpiece material allocation ahead of EU MDR production surges. Acquire CE marking technical documentation capabilities from laggard manufacturers facing 12-18 month renewal gaps. Bluetooth-enabled remote monitoring integration represents the priority R&D lever against sleep apnea device veterans entering respiratory therapy through direct-to-consumer channels. For New Entrants and Emerging Players: Enter via India's PLI scheme medical device incentives to establish tariff-shielded assembly operations targeting price-sensitive hospital procurement in South Asian markets. Pediatric asthma maintenance with gamified adherence interfaces offers the most penetrable white-space segment, underserved by incumbent mechanical designs. Partner with existing e-commerce fulfillment infrastructure from sleep therapy veterans to bypass durable medical equipment distributor gatekeeping. For Investors and Strategic Acquirers: Distressed-cycle entries favor EU MDR-compliant device portfolios in Germany and Japan where regulatory documentation scarcity creates acquisition discounts. Five-to-ten year viability hinges on remote therapeutic monitoring reimbursement code expansion in Medicare and national health systems. Watch for PMDA QMS audit interval tightening as signal for Japanese market access premium realization.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Premarket notification clearance unlocks Medicare reimbursement eligibility and hospital-system contract access. |
| CE Marking Pathway | EU MDR technical documentation renewal captures market share from laggards facing compliance gaps. |
| Hospital System Partnership | Discharge protocol integration creates institutional pull-through into home care settings. |
| Software Companion Development | Bluetooth-enabled adherence platforms align with Medicare remote therapeutic monitoring expansion. |
| Reimbursement Strategy | Coding coverage optimization directly determines patient out-of-pocket exposure and physician prescribing behavior. |
Research Methodology
Multi-period observation of FDA 510(k) clearance timelines, EU MDR CE marking renewal rates, and Medicare reimbursement code revisions anchored the trend analysis, supplemented by interviews with respiratory therapists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA device registration databases, EUDAMED CE marking records, CMS Medicare claims data, and hospital procurement contract filings. Bottom-up patient population modeling triangulated against top-down manufacturer revenue estimates.
Input-output matrices mapped oscillation mechanism production costs through polymer supply tiers to end-user pricing across handheld, portable, and tabletop form factors. Segmentation dimensions modeled include product type, end user category, clinical application, and distribution channel, with geographic regulatory cluster as an additional cross-cutting dimension. CAGRs were derived from installed base replacement cycles and home care migration penetration curves, incorporating PMDA QMS audit interval impacts on Japanese market entry sequencing.
Revisions become necessary when EU MDR compliance deadlines accelerate, polymer supply disruptions materialize, or Medicare remote therapeutic monitoring reimbursement codes expand coverage criteria. Forecasts reflect documented assumptions regarding patient self-administration adoption rates and hospital discharge protocol standardization. A model refresh is warranted upon material change in FDA substantial equivalence standards for oscillation mechanism claims.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Bronchial Thermoplasty Market
Respiratory Therapy
Global Oxygen Therapy Market
Respiratory Therapy
Viral Pneumonia Treatment Market
Respiratory Therapy
Oxygen Therapy Equipment Market
Respiratory Therapy
Cough Systems Market
Respiratory Therapy
US Respiratory Assist Devices EUA Market
Respiratory Therapy
Diaphragm Pacing Therapy System Market
Respiratory Therapy
Severe Acute Respiratory Syndrome Treatment Market
Respiratory Therapy
Breathing Disorders Treatment Market
Respiratory Therapy
Idiopathic Pulmonary Fibrosis (IPF) Treatment Market
Respiratory Therapy
Global Pulmonary Surfactant Market
Respiratory Therapy
Pleural Effusion Treatment Market
Respiratory Therapy
Artificial Lung Market
Respiratory Therapy
Nitric Oxide Management Systems Market
Respiratory Therapy
Virus-Induced Asthma Treatment Market
Respiratory Therapy
Asthma and COPD Biomarkers Market