
 Global Oxygen Therapy Market | 2026-2036
Global Oxygen Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Oxygen Therapy Market Foresight
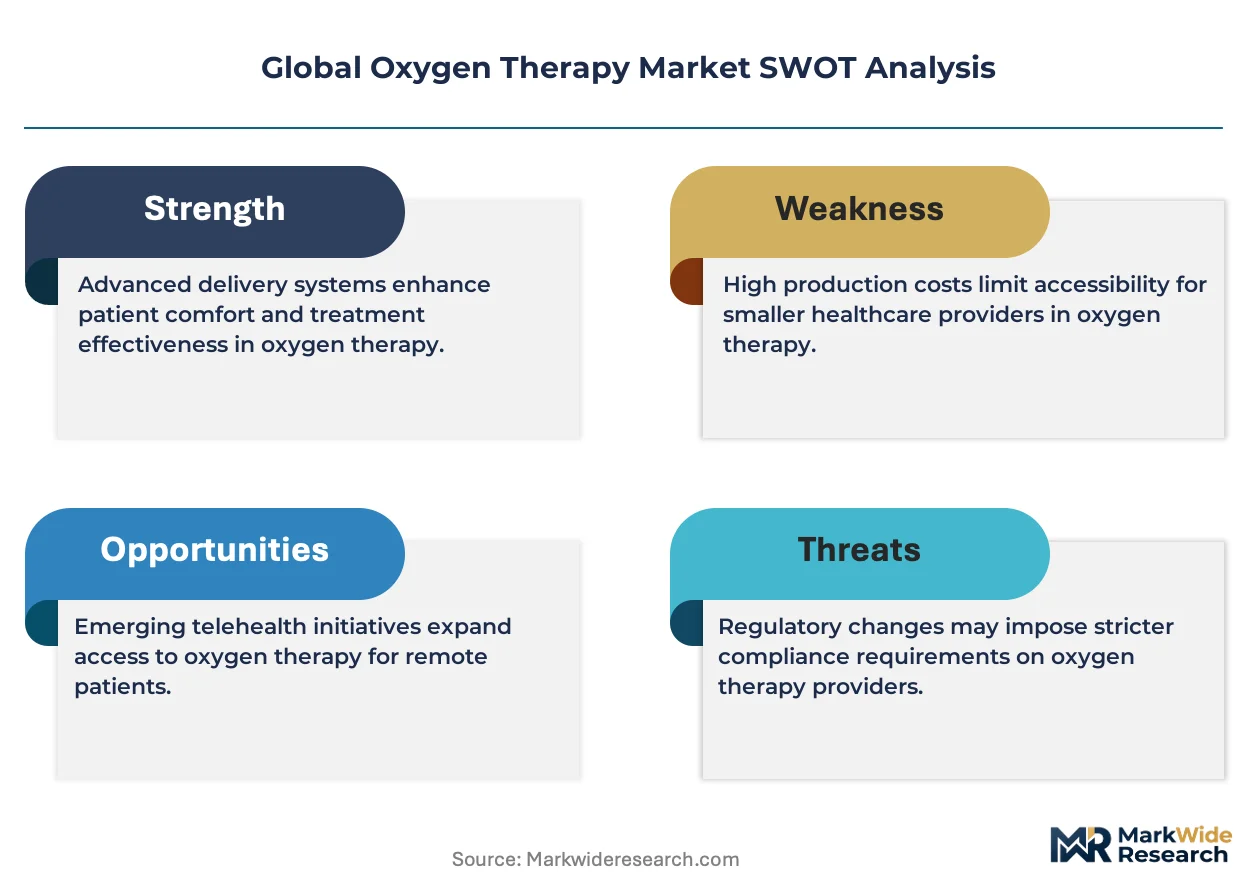
Remote monitoring subscriptions and predictive maintenance contracts are expanding what oxygen therapy suppliers sell beyond hardware. Philips leverages its cloud-connected Care Orchestrator platform to sustain recurring revenue from home care patients. Linde Healthcare anchors its position through gas logistics networks that dominate bulk liquid oxygen distribution across Europe. ResMed competes by integrating software-defined pressure algorithms into its portable concentrator portfolio.
Oxygen therapy encompasses the clinical administration of supplemental oxygen via mechanical devices to patients with hypoxemia or chronic respiratory insufficiency, typically delivering flow rates from 1 to 15 liters per minute through nasal cannulas, masks, or transtracheal catheters. The primary purpose is to maintain arterial oxygen saturation above 90 percent in conditions such as COPD, pulmonary fibrosis, and heart failure. Portable oxygen concentrators command the fastest growth trajectory among product types as lithium-ion battery density improves and travel mobility restrictions ease. Home care patients represent the deepest margin pool within end users because reimbursement codes favor long-term rental models over acute facility billing. Nasal cannula delivery methods retain volume leadership due to patient tolerance and lower equipment cost, though oxygen masks capture higher per-procedure revenue in sleep disorder centers.
FDA 510(k) clearance requirements and EMA Medical Device Regulation standards shape device design, software validation, and post-market surveillance obligations for manufacturers seeking multi-regional access. The EU F-Gas Regulation and EPA refrigerant phase-down rules are forcing concentrator makers to redesign compressor cooling systems around lower-global-warming-potential alternatives. Stakeholders must monitor how WHO oxygen access initiatives in low-resource settings reshape procurement specifications and volume commitments from emerging country tenders.
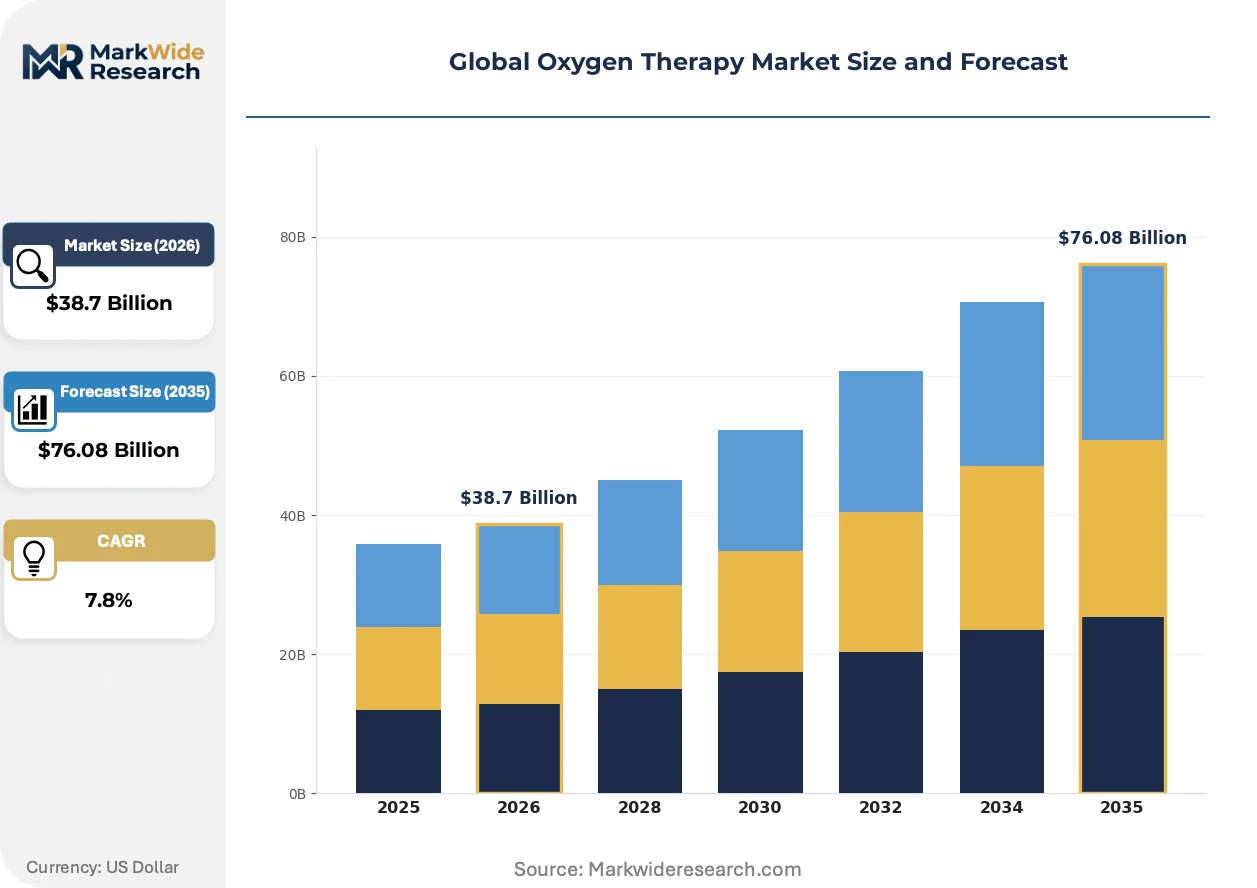
Market Dynamics
Post-acute care migration outside hospital walls is compressing device procurement cycles and forcing manufacturers to redesign service models around home-based patient monitoring rather than institutional sales channels.
Growth Catalysts
- FDA 510(k) pathway convergence with EMA MDR:Harmonized portable device standards are accelerating multi-regional product launches and reducing duplicate clinical validation costs for concentrator manufacturers.
- Lithium-ion battery density improvements:Extended runtime in portable oxygen concentrators is eliminating the range anxiety that previously constrained patient mobility and travel.
- COPD prevalence clusters:Aging patient populations in the United States, Germany, and Japan are generating sustained replacement demand for nasal cannula systems and pulse-dose delivery devices.
Market Restraints
- Liquid oxygen logistics concentration:Bulk distribution networks in Europe remain controlled by incumbent gas suppliers, creating barriers for new device entrants seeking bundled service contracts.
- EU F-Gas Regulation compliance costs:Refrigerant phase-down mandates are forcing compressor cooling system redesigns that add 18-24 months to product development timelines.
- Reimbursement code rigidity:Medicare and national health service billing structures favor rental models over outright purchase, limiting patient upgrade flexibility.
Strategic Opportunities
- WHO oxygen access initiatives:Low-resource procurement tenders in sub-Saharan Africa and South Asia are opening volume commitments for simplified, ruggedized concentrator designs.
- Predictive maintenance contracts:Cloud-connected device fleets enable recurring revenue streams from remote diagnostic subscriptions that hardware sales cannot match.
- Software-defined pressure algorithms:Integration of adaptive flow control with sleep disorder therapy is creating hybrid device categories that capture margin from adjacent respiratory markets.
Industry Challenges
- Post-market surveillance obligations:EMA MDR adverse event reporting requirements demand dedicated regulatory affairs teams that mid-scale manufacturers struggle to staff.
- Legacy institutional salesforce retraining:Field organizations built around hospital procurement committees require complete restructuring to call on home care distributors and durable medical equipment dealers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Oxygen Therapy Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $76.08 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stationary Oxygen Concentrators, Portable Oxygen Concentrators, Oxygen Cylinders, Liquid Oxygen Systems Therapy Area: Chronic Obstructive Pulmonary Disease, Pneumonia Treatment, Pulmonary Fibrosis, Heart Failure Management End User: Home Care Patients, Respiratory Clinics, Sleep Disorder Centers, Rehabilitation Facilities Delivery Method: Nasal Cannula, Oxygen Masks, Transtracheal Catheters, Oxygen Hoods |
| Companies Covered | Koninklijke Philips N.V., Linde Healthcare, ResMed Inc., Invacare Corporation, Chart Industries, Inc., Fisher & Paykel Healthcare Limited, Drägerwerk AG & Co. KGaA, Inogen, Inc., Medtronic plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Oxygen Therapy Market Shifts & Advancements
Digital connectivity is unifying hardware, software, and service layers into single patient-relationship platforms that extend manufacturer influence deep into the home care episode.
Closed-loop oxygen titration is unifying pulse oximetry sensors with variable-flow concentrators into autonomous delivery systems. Home care patients with nocturnal desaturation are adopting these integrated platforms fastest. The technology is unifying diagnostic and therapeutic functions into single reimbursable events that compress the traditional multi-vendor care pathway.
REACH chemical safety registration and EPA refrigerant phase-down rules are forcing compressor manufacturers to qualify lower-global-warming-potential cooling chemistries. Industrial gas suppliers in Germany and the Netherlands are piloting propane-based systems ahead of regulatory deadlines. Portable concentrator product lines targeting EU markets are absorbing the bulk of redesign costs and timeline delays.
After-sales service unbundling is separating device maintenance from gas supply contracts that historically locked patients into single suppliers. Durable medical equipment dealers in the United States are capturing disaggregated service revenue previously retained by gas logistics networks. This channel fragmentation is most visible in Medicare Advantage plans where patients exercise plan-switching mobility annually.
Global Oxygen Therapy Market Segmentation
Oxygen therapy segmentation reveals divergent margin structures across stationary versus portable modalities, with reimbursement codes and patient mobility requirements dictating where hardware economics outperform service revenue. Manufacturers must align R&D portfolios to the specific regulatory and clinical validation burdens that each segment imposes.
Product Type:
Standalone oxygen generation systems dominate clinical workflows, while embedded portable units integrate into broader patient mobility platforms.
- Stationary Oxygen Concentrators:These mains-powered units extract oxygen from ambient air through pressure swing adsorption, delivering continuous flow up to 10 liters per minute. Demand concentrates in Medicare-reimbursed home care installations across the United States, where rental billing codes favor multi-year equipment leases over capital purchase.
- Portable Oxygen Concentrators:Battery-operated devices weighing under five pounds enable ambulatory therapy through pulse-dose delivery algorithms. Adoption clusters in Germany and Japan where aging COPD populations prioritize travel mobility and airline portability certification drives product selection.
- Oxygen Cylinders:Compressed gas vessels remain essential for emergency backup and transport scenarios where electrical reliability is uncertain.
- Liquid Oxygen Systems:Cryogenic storage dewars serve high-flow patients requiring continuous delivery beyond concentrator capacity.
Volume placements concentrate in stationary concentrators; the faster expansion belongs to portable oxygen concentrators.
Therapy Area:
Chronic indication management generates recurring device utilization, while acute interventions create episodic procurement cycles with distinct margin profiles.
- Chronic Obstructive Pulmonary Disease:Progressive airflow limitation necessitates long-term supplemental oxygen for hypoxemic patients, with arterial saturation targets above 90 percent driving daily device dependence. The United States, Germany, and Japan account for the deepest installed base as smoking prevalence histories and diagnostic penetration create sustained replacement demand.
- Pneumonia Treatment:Acute hypoxemia in infectious lung consolidation requires temporary oxygen support until antibiotic therapy resolves inflammation.
- Pulmonary Fibrosis:Interstitial lung disease with irreversible parenchymal scarring mandates escalating flow rates as diffusion capacity deteriorates.
- Heart Failure Management:Cardiogenic pulmonary edema produces oxygenation deficits addressed through nocturnal and exertional supplementation protocols.
Reimbursement stability favors COPD; the steepest expansion trajectory sits with heart failure management as comorbidity protocols integrate respiratory support.
End User:
Institutional procurement committees evaluate total cost of ownership, while individual patient selection prioritizes portability and noise tolerance.
- Home Care Patients:Domiciliary therapy recipients represent the deepest margin pool as long-term rental models generate recurring revenue streams and remote monitoring subscriptions extend manufacturer relationships beyond hardware delivery. Medicare Advantage plans in the United States and statutory health insurance in Germany drive volume through favorable durable medical equipment reimbursement.
- Respiratory Clinics:Outpatient pulmonary practices require versatile equipment portfolios addressing diagnostic titration and ambulatory transition.
- Sleep Disorder Centers:Nocturnal desaturation protocols in polysomnography labs create demand for integrated oxygen-CPAP hybrid systems.
- Rehabilitation Facilities:Post-acute respiratory therapy programs utilize concentrators during weaning from mechanical ventilation.
Patient census concentrates in home care; sleep disorder centers are gaining share fastest as diagnostic referral networks expand.
Delivery Method:
Interface selection balances patient tolerance against oxygenation efficiency, with nasal routes dominating ambulatory use and sealed systems reserved for high-flow requirements.
- Nasal Cannula:Dual-prong plastic tubing delivering low-to-medium flow rates dominates home care utilization due to patient comfort, speech preservation, and minimal equipment cost. Japanese and German elderly populations show highest acceptance as cosmetic discretion and eating compatibility influence adherence.
- Oxygen Masks:Reservoir and non-rebreather configurations capture higher per-procedure revenue in sleep disorder centers where precise FiO2 control justifies disposable supply billing.
- Transtracheal Catheters:Surgically placed direct tracheal access reduces flow requirements and improves cosmetic outcomes for long-term users.
- Oxygen Hoods:Enclosure systems serve neonatal and pediatric populations requiring humidified high-flow delivery without facial contact.
Clinical volume concentrates in nasal cannula deployment; transtracheal catheters are climbing the fastest as cosmetic outcomes drive patient preference in affluent markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing concentrates in Germany and the United States, while patient demand clusters in aging populations across Japan, Germany, and the United States where COPD prevalence drives clinical adoption.
United States
Medicare reimbursement codes favor long-term rental models for home care patients, creating sustained replacement demand for nasal cannula systems. FDA 510(k) clearance requirements shape device design and software validation obligations for manufacturers seeking market access. Philips anchors its position through cloud-connected platforms in the Northeast corridor, while durable medical equipment dealers in the Southeast capture disaggregated service revenue from gas logistics networks.
Germany
Statutory health insurance drives volume through favorable durable medical equipment reimbursement for aging COPD populations. EMA Medical Device Regulation standards enforce post-market surveillance obligations that demand dedicated regulatory affairs teams. Linde Healthcare dominates bulk liquid oxygen distribution across North Rhine-Westphalia, with industrial gas suppliers in Bavaria piloting propane-based cooling systems ahead of EU F-Gas deadlines.
Japan
Elderly populations prioritize travel mobility and cosmetic discretion, accelerating adoption of portable concentrators with airline portability certification. METI standards and PMDA device approvals create distinct regulatory pathways separate from Western frameworks. Tokyo-based sleep disorder centers generate demand for integrated oxygen-CPAP hybrid systems as diagnostic referral networks expand.
United Kingdom
National Health Service procurement committees evaluate total cost of ownership for stationary concentrator installations in domiciliary settings. MHRA convergence with EMA MDR standards accelerates multi-regional product launches for manufacturers. London and Southeast England concentrate respiratory clinic demand for versatile equipment portfolios addressing diagnostic titration and ambulatory transition.
India
WHO oxygen access initiatives in low-resource settings reshape procurement specifications for simplified, ruggedized concentrator designs. CDSCO medical device registration requirements create compliance burdens for importers seeking hospital procurement contracts. Maharashtra and Karnataka host emerging manufacturing clusters targeting sub-Saharan African and South Asian tender volumes.
Global Oxygen Therapy Market Competitive Landscape
Top-tier vendors anchor gas logistics and device manufacturing, while mid-scale specialists compete on portable technology and regional service networks. The vendor base stratifies across industrial gas incumbents with distribution infrastructure, diversified healthcare conglomerates with software platforms, and focused concentrator manufacturers with pulse-dose engineering capabilities. Strategic archetypes include gas logistics dominators leveraging bulk liquid networks, software-integrated device makers monetizing remote monitoring subscriptions, and portable specialists exploiting lithium-ion density improvements. Competitive moves center on predictive maintenance contract expansion and compressor cooling system redesigns around lower-global-warming-potential refrigerants.
Within the diversified healthcare technology tier, Koninklijke Philips N.V. and ResMed Inc. exemplify platform-based competition where cloud connectivity extends manufacturer influence into patient homes. Among industrial gas specialists, Linde Healthcare occupies a position defined by European distribution infrastructure. At the portable device end, Inogen, Inc. represents the pulse-dose engineering archetype targeting patient mobility requirements.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Linde Healthcare |
| ResMed Inc. |
| Invacare Corporation |
| Chart Industries, Inc. |
| Fisher & Paykel Healthcare Limited |
| Drägerwerk AG & Co. KGaA |
| Inogen, Inc. |
| Medtronic plc |
| Others |
Supply & Pricing Matrix
Lithium carbonate price indices cascade through portable oxygen concentrator manufacturing into three-tier pricing structures across premium, standard, and economy levels, with battery chemistry costs compressing mid-tier margins while refrigerant compliance expenses push EU-bound products toward premium positioning.
Pricing Analysis
Cost-down pressure on standard-tier portable concentrators accelerates because Medicare reimbursement code rigidity caps rental rates while lithium-ion cell procurement draws from volatile commodity markets. Pricing stratifies across premium, standard, and economy tiers based on FAA airline certification status and compressor cooling system refrigerant grade—REACH-registered propane-based units command premium positioning against legacy HFC designs. Price erosion runs through economy-tier stationary concentrators as durable medical equipment dealers disaggregate service contracts from hardware sales. Home care patients in Medicare Advantage plans exhibit highest price sensitivity; sleep disorder centers purchasing integrated oxygen-CPAP hybrid systems show least.
Supply Chain Analysis
Dual-sourcing requirements for compressor motors and molecular sieve beds mandate qualification of suppliers across Germany, China, and the United States, with FDA and EMA MDR documentation burdens extending vendor onboarding timelines. Raw material dependencies center on lithium carbonate from South American brine operations, synthetic zeolite from specialized chemical manufacturers, and rare-earth magnets for miniaturized compressor drives. Single-source vulnerability concentrates in medical-grade zeolite production where German and Japanese suppliers dominate capacity. Distribution runs through Linde Healthcare's bulk liquid oxygen networks in Europe and durable medical equipment dealer channels in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EMA MDR post-market surveillance obligations create regulatory moats that mid-scale manufacturers cannot scale, entrenching advantage for incumbents with dedicated regulatory affairs infrastructure.
For Market Incumbents: Extend predictive maintenance subscription penetration among home care patient fleets to lock in recurring revenue streams insulated from hardware commoditization. Acquire specialized software-defined pressure algorithm capabilities to defend against ResMed's integrated device-service platform expansion. Prioritize backward integration into lithium-ion battery pack assembly to secure supply continuity against cell chemistry volatility. For New Entrants and Emerging Players: Capture WHO oxygen access initiative tenders in sub-Saharan Africa and South Asia where simplified, ruggedized concentrator specifications bypass Western regulatory complexity. Target India's emerging manufacturing clusters in Maharashtra and Karnataka as production footholds for low-resource market export. Lead with direct hospital procurement relationships in CDSCO-registered facilities rather than competing through established gas logistics networks. For Investors and Strategic Acquirers: Distressed-cycle entries favor portable concentrator specialists with FAA-certified pulse-dose engineering capabilities in the United States and Japan. Long-term viability hinges on software-integrated device platforms capable of monetizing remote monitoring subscriptions beyond hardware replacement cycles. Watch FDA 510(k) clearance velocity for adaptive flow control systems as inflection indicator for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| EMA MDR Certification Pathway | Accelerates multi-regional product launches while excluding undercapitalized competitors from EU market access. |
| Predictive Maintenance Platform Development | Transforms Philips and ResMed into recurring-revenue software businesses beyond device manufacturing economics. |
| Propane-Based Cooling System Transition | Positions German and Dutch industrial gas suppliers ahead of EU F-Gas Regulation phase-down deadlines. |
| Hospital System Partnership | Enables Linde Healthcare to bundle bulk liquid oxygen contracts with stationary concentrator installations. |
| Reimbursement Strategy Alignment | Captures Medicare Advantage plan switching mobility through durable medical equipment dealer channel control. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs while primary interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and durable medical equipment dealers validated demand-side assumptions. Bottom-up triangulation against top-down macroeconomic indicators reconciled volume projections across product type, therapy area, end user, and delivery method segmentation.
Data-stream reconciliation integrated Medicare reimbursement code analysis, FDA 510(k) clearance databases, and EMA MDR technical documentation filings across the projection horizon. Segmentation dimensions modeled included stationary versus portable modality, chronic versus acute indication, home care versus institutional setting, and nasal cannula versus mask versus transtracheal interface. CAGRs derived from weighted average of historical replacement demand curves and lithium-ion battery density improvement trajectories, with compressor cooling system redesign timelines and WHO tender award patterns as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU F-Gas Regulation enforcement timing and Medicare reimbursement rate revisions. Deviation in FAA airline portability certification standards would shift portable concentrator demand outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Oscillating Positive Expiratory Pressure (OPEP) Devices Market
Respiratory Therapy
Respiratory Biologics Market
Respiratory Therapy
Asthma and COPD Biomarkers Market
Respiratory Therapy
Pediatric Respiratory Disease Therapeutics Market
Respiratory Therapy
Pediatric Respiratory Disease Treatment Market
Respiratory Therapy
Lung (Pulmonary) Airway Disease Treatment Market
Respiratory Therapy
Cough Systems Market
Respiratory Therapy
Global Positive Airway Pressure Market
Respiratory Therapy
Interventional Pulmonology Market
Respiratory Therapy
Idiopathic Pulmonary Fibrosis (IPF) Treatment Market
Respiratory Therapy
Respiratory Antiviral Treatment Market
Respiratory Therapy
Chronic Obstructive Pulmonary Disease Treatment Market
Respiratory Therapy
Brazil Therapeutic Respiratory Devices Market
Respiratory Therapy
Croup Treatment Market
Respiratory Therapy
Pneumonia Treatment Market
Respiratory Therapy
Emphysema Treatment Market