
 Diaphragm Pacing Therapy System Market | 2026-2036
Diaphragm Pacing Therapy System Market Size, Share, and Industry Trends Forecast 2026-2036
Diaphragm Pacing Therapy System Market Intelligence
Home care settings is rotating toward center stage as the dominant buyer archetype, displacing traditional hospital-centric procurement for diaphragm pacing systems. Synapse Biomedical leverages its implantable platform technology to anchor the invasive device segment. Avery Biomedical Devices sustains long-standing clinical relationships with academic medical centers. Lungpacer Medical differentiates through minimally invasive catheter-based approaches that reduce surgical burden.
A diaphragm pacing therapy system delivers rhythmic electrical stimulation to the phrenic nerve or diaphragm muscle to restore autonomous breathing in patients with ventilator dependency, typically operating at pulse frequencies between 10-20 Hz with implantable electrodes constructed from platinum-iridium alloys. Implantable devices capture the largest margin pool due to recurring battery replacement and programming services, while external stimulators expand access in cost-sensitive reimbursement environments. The neuromuscular conditions therapy area generates the most intensive clinical utilization, whereas congenital diaphragmatic hernia applications represent an emerging pediatric niche with specialized regulatory pathways.
FDA premarket approval requirements and EU MDR technical documentation standards govern device commercialization, with FDA breakthrough device designations compressing review timelines for indications addressing unmet respiratory needs. The country's national pharmaceutical regulator in Japan mandates local clinical trials for phrenic nerve stimulators, creating staggered market entry patterns across OECD markets. Stakeholders must monitor reimbursement code consolidation for home-based neurostimulation as payers recalibrate coverage policies between institutional and ambulatory settings.
Market Dynamics
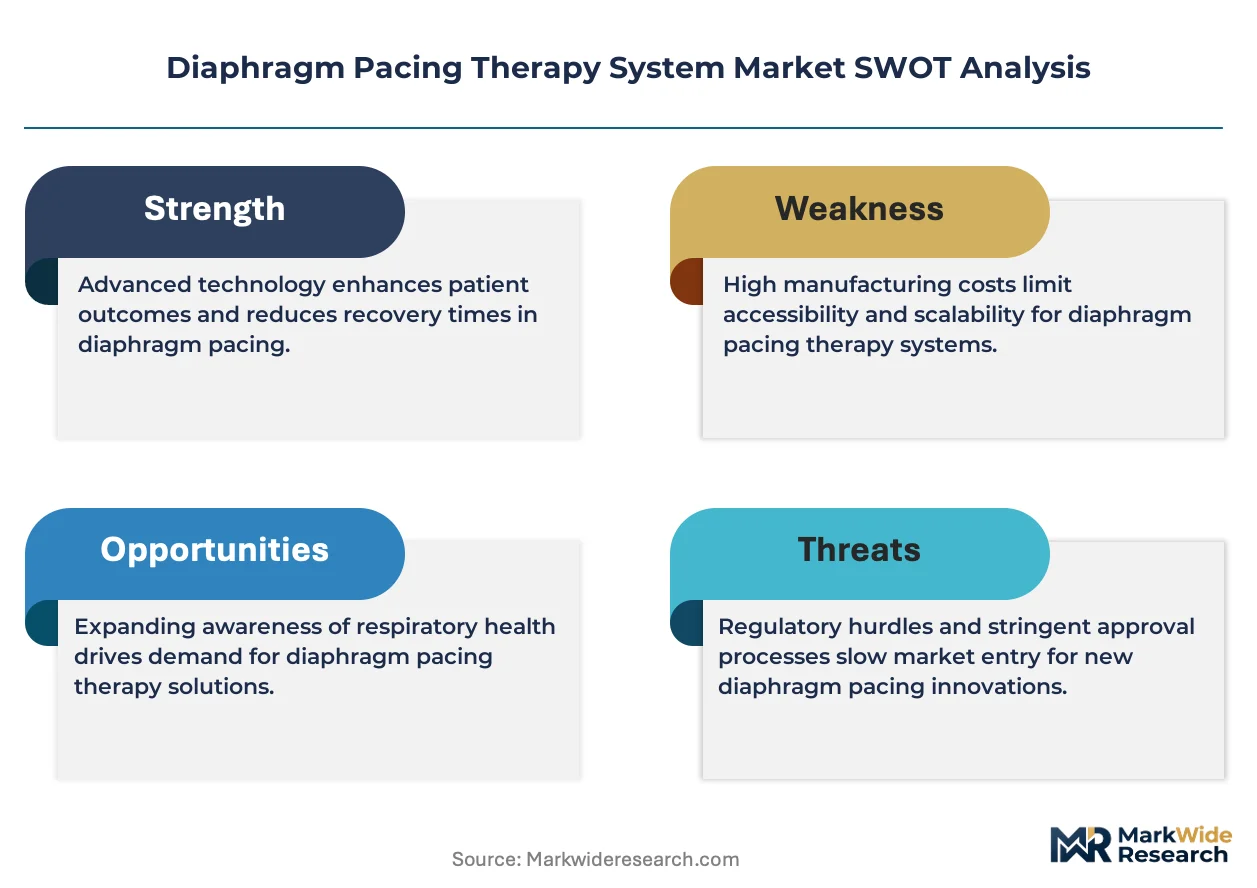
The migration of diaphragm pacing therapy from institutional settings to home-based care is restructuring procurement patterns, reimbursement frameworks, and device design priorities across the respiratory neuromodulation sector.
Growth Catalysts
- FDA Breakthrough Device Designation:Compressed review timelines for phrenic nerve stimulators addressing ventilator-dependent respiratory failure accelerate commercialization pathways for novel implantable systems.
- Home Care Infrastructure Expansion:Remote patient monitoring platforms and telehealth reimbursement codes enable safe deployment of external diaphragm pacing devices outside acute care facilities.
- Platinum-Iridium Electrode Biocompatibility:Advanced alloy compositions extend electrode functional lifespan in chronically implanted phrenic nerve interfaces, reducing replacement surgical burden.
Market Restraints
- Specialized Surgical Skill Scarcity:Phrenic nerve mapping and electrode implantation require fellowship-trained thoracic surgeons, constraining procedure volume in secondary markets.
- Battery Replacement Cost Concentration:Implantable pulse generator battery depletion drives recurring expenditure clusters every 4-7 years, limiting adoption in capitated reimbursement environments.
- Mechanical Ventilation Path Dependence:Established intensive care protocols and respiratory therapist training curricula perpetuate invasive ventilation as default standard of care.
Strategic Opportunities
- Pediatric Congenital Diaphragmatic Hernia:Specialized regulatory pathways for neonatal phrenic nerve stimulation create first-mover positioning in an underserved congenital indication segment.
- Catheter-Based Minimally Invasive Delivery:Transvenous electrode placement techniques reduce surgical morbidity and expand candidacy to patients excluded from open implantation.
- Japan PMDA Local Trial Requirements:Staggered market entry timelines create partnership opportunities for Western device developers seeking licensed distribution through domestic manufacturers.
Industry Challenges
- Neurophysiology Specialist Recruitment:Clinical specialists capable of programming phrenic nerve stimulators and troubleshooting electrode impedance issues remain concentrated at academic medical centers.
- EU MDR Technical Documentation Burden:Expanded clinical evidence requirements for active implantable medical devices extend certification timelines and inflate regulatory compliance expenditure.
- Legacy Ventilator Integration Complexity:Synchronization protocols between diaphragm pacing systems and existing mechanical ventilation hardware require proprietary interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diaphragm Pacing Therapy System Market |
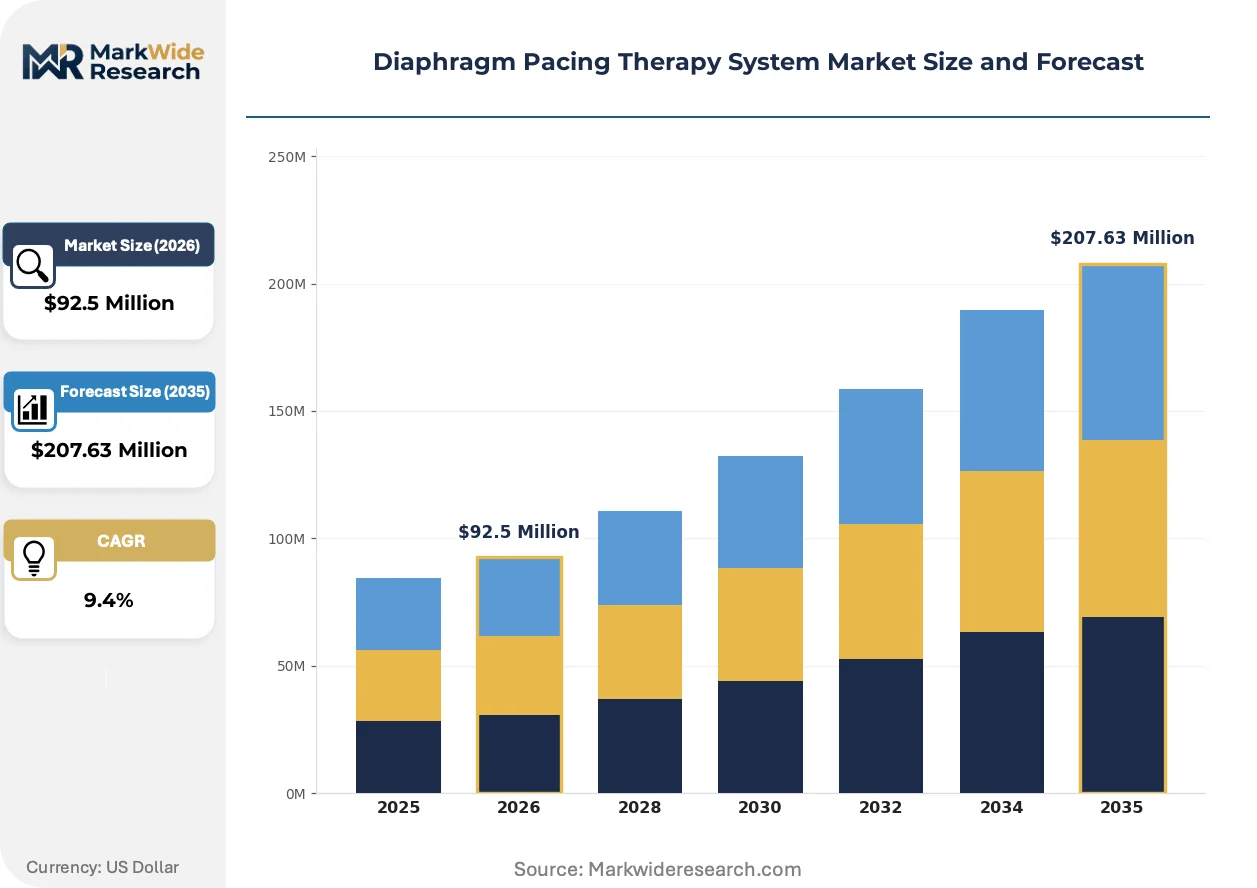
| Market Size in 2026 | $92.5 Million |
| Market Size in 2035 | $207.63 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Implantable Devices, External Stimulators, Accessories, Wiring Systems End User: Hospitals, Rehabilitation Centers, Home Care Settings, Clinics Therapy Area: Respiratory Disorders, Neuromuscular Conditions, Sleep Apnea, Congenital Diaphragmatic Hernia Delivery Mode: Invasive Procedures, Non-invasive Techniques, Surgical Approaches, Remote Monitoring |
| Companies Covered | Synapse Biomedical, Avery Biomedical Devices, Lungpacer Medical, Atrotech, ZOLL Medical Corporation, Astrotech Corp., Arahelio, Respironics, Pulmonx, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diaphragm Pacing Therapy System Market Strategic Shifts & Innovations
Device miniaturization and closed-loop feedback architectures are redefining therapeutic efficacy benchmarks, while regulatory convergence and shifting care delivery models reshape competitive positioning across the respiratory neuromodulation landscape.
Wireless power transfer architectures are displacing transcutaneous charging systems in next-generation implantable diaphragm pacemakers. Home care providers and long-term acute care facilities are prioritizing fully implanted systems that eliminate percutaneous lead infection risk. This displacement is compressing market share for external stimulator platforms and elevating R&D investment in inductive coupling efficiency and thermal management.
EU MDR Article 54 clinical evaluation requirements are intensifying post-market surveillance obligations for phrenic nerve stimulator manufacturers. Device sponsors must now submit periodic safety update reports with real-world performance data, forcing restructuring of quality management systems. The invasive implantable segment bears the heaviest documentation burden, with notified bodies demanding extended follow-up intervals for novel electrode geometries.
Hospital purchasing consortia are consolidating procurement authority for high-cost respiratory devices under centralized value analysis committees. Individual physician preference is yielding to standardized formulary decisions driven by total cost-of-ownership modeling and outcomes guarantees. This behavioral shift is most pronounced in United States integrated delivery networks, where neuromodulation device contracts now span multi-hospital systems rather than single institutions.
Diaphragm Pacing Therapy System Market Segmentation
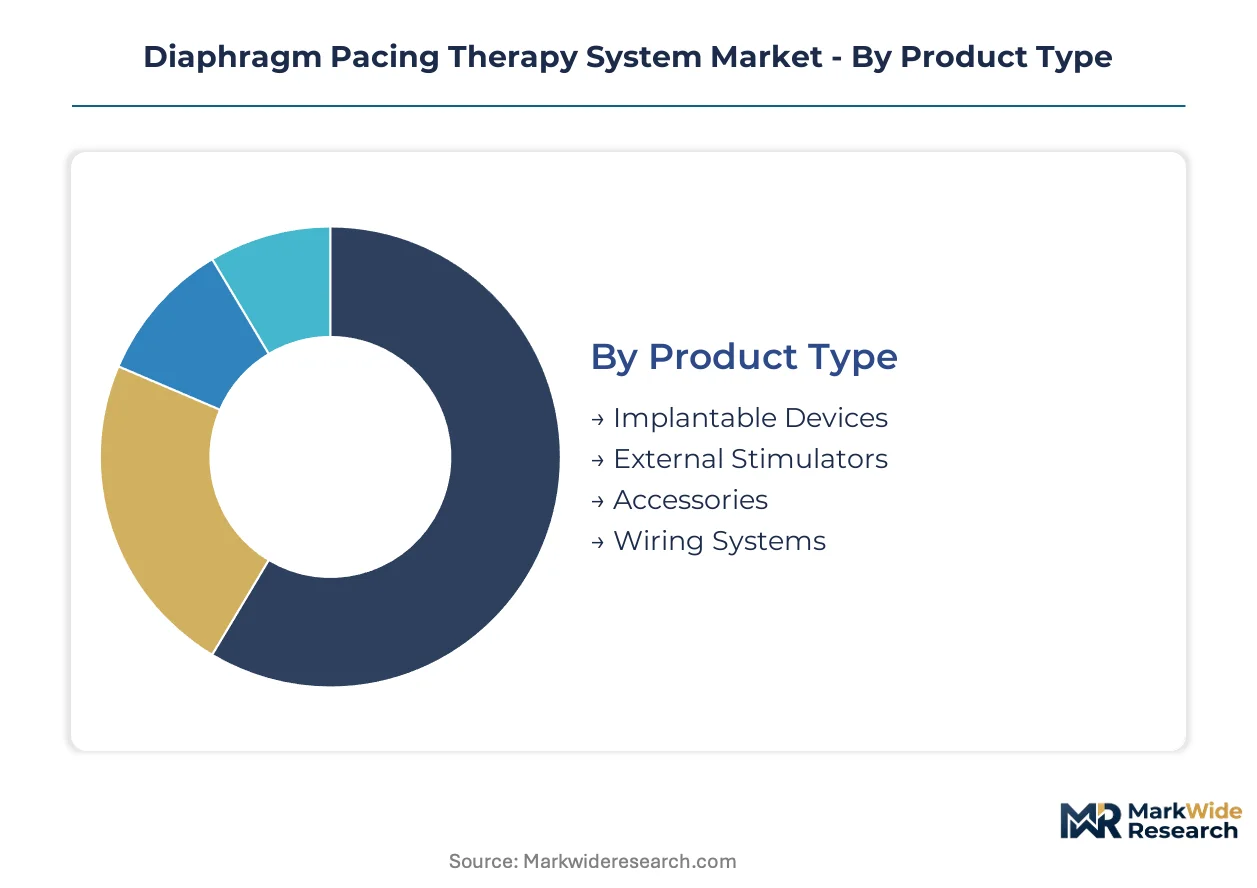
Segmentation in the diaphragm pacing therapy system market reveals distinct procurement patterns across institutional and ambulatory settings. Product architecture, therapy indication, and care delivery location each reshape reimbursement pathways and device specification requirements.
Product Type:
Implantable platforms dominate domestic procurement in the United States and Germany, while external stimulators capture export-led demand in cost-sensitive Asian and Latin American markets.
- Implantable Devices:Fully implanted pulse generators with platinum-iridium electrodes deliver phrenic nerve stimulation at programmable frequencies. Demand concentrates in tertiary academic medical centers across the United States and Germany where fellowship-trained thoracic surgeons manage complex ventilator weaning protocols.
- External Stimulators:Transcutaneous systems with surface electrodes or percutaneous lead interfaces provide temporary or bridge-to-implant therapy. Export markets in India and Brazil favor these platforms due to lower upfront capital requirements and flexible reimbursement coding.
- Accessories:Patient programmers, charging stations, and telemetry modules extend system functionality.
- Wiring Systems:Lead extensions, adaptors, and replacement cables maintain connectivity across device generations.
Implantable devices command the established base. The steepest expansion runs through external stimulators.
End User:
Cost tier stratification separates capital-intensive hospital installations from leaner home care deployments.
- Hospitals:Integrated delivery networks in the United States and university hospitals in Japan anchor procurement volume for invasive implantable systems. These institutions bear the full burden of surgical infrastructure, neurophysiology specialist staffing, and FDA or PMDA compliance documentation.
- Home Care Settings:Long-term ventilator-dependent patients receive external diaphragm pacing systems through durable medical equipment suppliers. Remote monitoring capabilities and telehealth reimbursement codes in Germany and the United States accelerate deployment outside institutional walls.
- Rehabilitation Centers:Post-acute facilities bridge hospital discharge and home transition with temporary pacing protocols.
- Clinics:Outpatient pulmonology practices manage device programming and impedance troubleshooting.
Hospitals retain the revenue concentration. Home care settings are gaining share fastest.
Therapy Area:
Application maturity varies sharply between well-established neuromuscular indications and emerging pediatric congenital segments.
- Neuromuscular Conditions:Amyotrophic lateral sclerosis, spinal cord injury, and multiple sclerosis drive the most intensive clinical utilization. United States academic centers generate concentrated procedure volume for ALS-related respiratory failure where diaphragm pacing extends survival beyond mechanical ventilation dependence.
- Congenital Diaphragmatic Hernia:Neonatal phrenic nerve stimulation represents an underserved pediatric niche with specialized FDA breakthrough and EMA orphan pathway designations. European and Japanese pediatric surgical centers pioneer clinical validation for this high-mortality congenital indication.
- Respiratory Disorders:Chronic obstructive pulmonary disease and central hypoventilation syndromes comprise the broadest addressable population.
- Sleep Apnea:Central and complex sleep-disordered breathing applications remain investigational with limited commercial penetration.
Neuromuscular conditions command the established base. Congenital diaphragmatic hernia shows the steepest expansion trajectory.
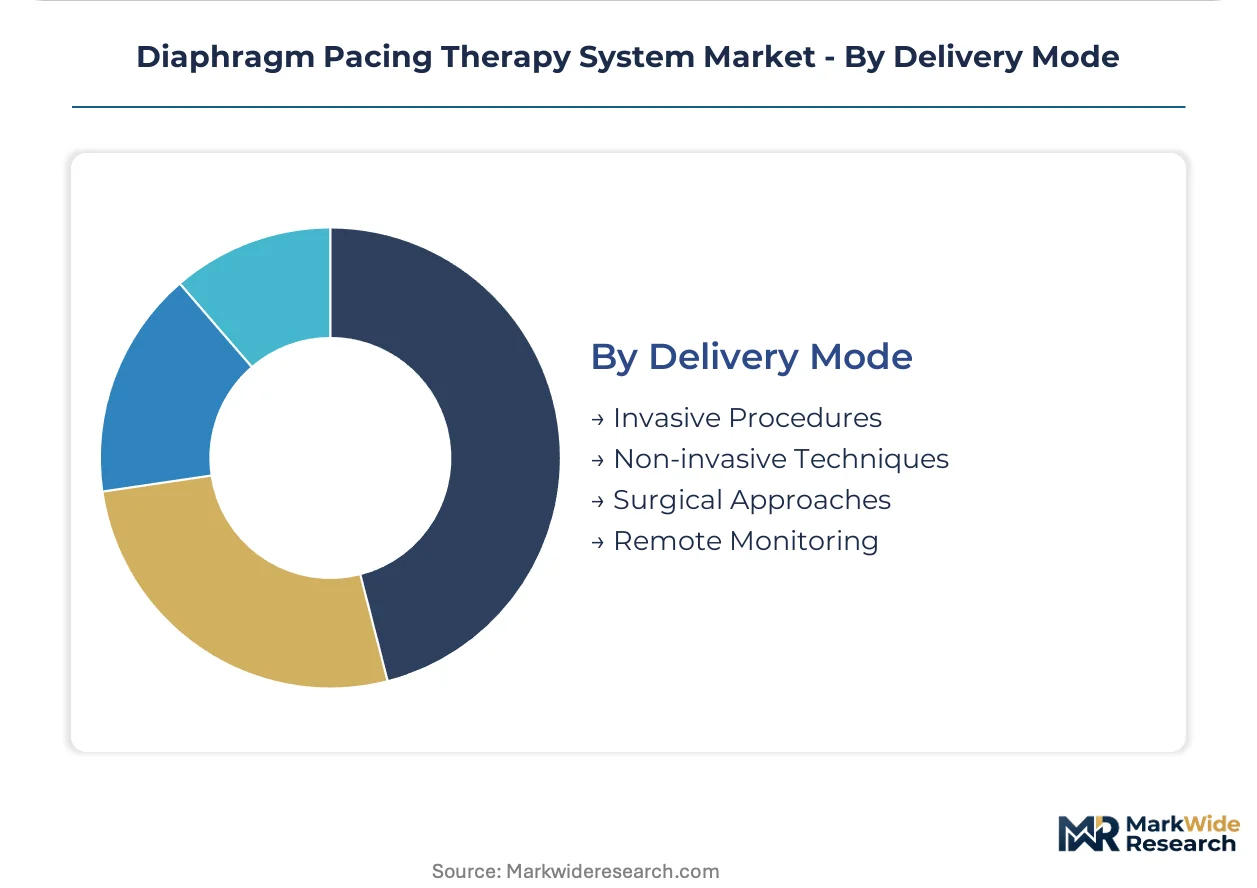
Delivery Mode:
Volume concentration favors invasive surgical implantation, though minimally invasive catheter techniques reshape candidacy expansion.
- Invasive Procedures:Open thoracotomy or laparoscopic approaches for electrode placement on the phrenic nerve or diaphragm motor point. Japanese and German surgical volumes reflect deep expertise in nerve mapping and impedance-optimized electrode positioning.
- Non-invasive Techniques:Surface electrical stimulation and magnetic pacing systems eliminate surgical risk entirely. These platforms serve bridge-to-recovery scenarios in United States rehabilitation settings and resource-limited international markets lacking surgical infrastructure.
- Surgical Approaches:Robotic-assisted and video-assisted thoracoscopic techniques reduce operative morbidity.
- Remote Monitoring:Cloud-connected device telemetry enables home-based parameter adjustment and predictive maintenance alerts.
Invasive procedures command the established base. Non-invasive techniques are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export phrenic nerve stimulator components to Japanese university hospitals, establishing the primary trade corridor for advanced respiratory neuromodulation hardware.
United States
FDA breakthrough device designations compress review timelines for ventilator-weaning indications, accelerating commercialization for novel implantable systems. Academic medical centers in Boston and Baltimore anchor surgical volume for ALS-related respiratory failure interventions. Integrated delivery networks consolidate procurement authority under centralized value analysis committees.
Germany
EU MDR technical documentation requirements intensify post-market surveillance for active implantable devices, extending certification timelines. The country's national pharmaceutical regulator mandates expanded clinical evidence for novel electrode geometries. Heidelberg and Munich surgical clusters specialize in nerve mapping and impedance-optimized positioning techniques.
Japan
PMDA local trial requirements for phrenic nerve stimulators create staggered market entry patterns behind Western approvals. Tokyo and Osaka university hospitals pioneer clinical validation for congenital diaphragmatic hernia applications. Domestic manufacturers partner with foreign developers seeking licensed distribution pathways.
United Kingdom
NHS England specialized commissioning frameworks restrict reimbursement for invasive neuromodulation to designated tertiary centers. The Medicines and Healthcare products Regulatory Agency aligns post-Brexit device regulations with EU MDR standards. London and Manchester academic hospitals concentrate neurophysiology specialist staffing.
India
CDSCO medical device rules classify phrenic nerve stimulators as high-risk imports requiring local adverse event reporting. Cost-sensitive reimbursement environments favor external stimulator platforms over implantable systems. Delhi and Mumbai tertiary centers manage bridge-to-recovery protocols for spinal cord injury patients.
Diaphragm Pacing Therapy System Market Key Industry Players
Listed leaders compete with private specialists across regulatory capital intensity, creating a tiered structure where scale advantages separate from clinical relationship depth. The vendor base concentrates around three strategic archetypes: implantable platform developers, catheter-based minimally invasive innovators, and legacy academic center suppliers. M&A activity targets neurophysiology programming capabilities, while strategic partnerships address Japan PMDA local trial requirements.
Within the implantable platform tier, Synapse Biomedical and Avery Biomedical Devices exemplify divergent positioning strategies. Synapse Biomedical anchors the fully implanted pulse generator segment where wireless power transfer architectures eliminate percutaneous infection risk. Avery Biomedical Devices occupies a position sustained through long-standing clinical relationships with academic medical centers. Lungpacer Medical represents the catheter-based minimally invasive archetype, reducing surgical burden through transvenous electrode placement techniques that expand patient candidacy.
| Leading Market Players |
|---|
| Synapse Biomedical |
| Avery Biomedical Devices |
| Lungpacer Medical |
| Atrotech |
| ZOLL Medical Corporation |
| Astrotech Corp. |
| Arahelio |
| Respironics |
| Pulmonx |
| Others |
Cost & Logistics Intelligence
FDA premarket approval pathways and EU MDR technical documentation standards gate both supplier qualification and price differentiation simultaneously, compressing margins for non-compliant manufacturers while elevating premium capture for certified implantable platforms. Battery replacement cycles and electrode longevity specifications create recurring revenue structures that separate established players from cost-sensitive external stimulator suppliers.
Pricing Analysis
Next-generation wireless power transfer systems command substantial premiums over transcutaneous charging platforms, while prior-generation external stimulators face cost compression in export markets. Three-tier pricing structure across premium implantable, standard external, and economy accessory levels reflects FDA breakthrough designation status and platinum-iridium electrode certification grades. Pricing pressure stems from hospital purchasing consortia consolidating procurement authority under total cost-of-ownership models. Home care settings exhibit highest price sensitivity due to limited reimbursement codes, while academic medical centers absorb premium implantable costs through research funding channels.
Supply Chain Analysis
Inventory lead times for platinum-iridium electrode alloys extend procurement cycles for implantable device manufacturers, compressing working capital efficiency. Supply concentrates in United States, Germany, and Japan for pulse generator assembly, with platinum-iridium electrodes, lithium primary batteries, and biocompatible silicone housings anchoring raw material dependencies. Single-source vulnerability runs through specialized neurophysiology programming talent concentrated at academic medical centers. Distribution runs through hospital value analysis committees in integrated delivery networks and durable medical equipment suppliers serving home care transitions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized surgical expertise in phrenic nerve mapping and electrode impedance optimization represents the critical capability gap constraining market expansion, with fellowship-trained thoracic surgeons concentrated at fewer than fifty academic centers worldwide.
For Market Incumbents: Consolidate neurophysiology programming capabilities through targeted hiring at Heidelberg and Munich surgical clusters, while securing backward integration into platinum-iridium electrode supply to defend against catheter-based minimally invasive substitutes eroding invasive implantable margins. For New Entrants and Emerging Players: FDA breakthrough device designation fast-tracks compress regulatory timelines for ventilator-weaning indications, opening white-space in congenital diaphragmatic hernia applications where European and Japanese pediatric centers pioneer validation. Target India and Brazil external stimulator markets through distributor partnerships leveraging flexible reimbursement coding. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across implantable pulse generator manufacturing as wireless power transfer architectures displace transcutaneous systems, favoring acquisition targets with inductive coupling IP and existing FDA PMA holdings. Watch Japan PMDA local trial completion rates as inflection signal for licensed distribution partnership viability.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Secures formulary placement at integrated delivery networks consolidating procurement authority under value analysis committees. |
| Reimbursement Strategy | Expands home care deployment through telehealth coding alignment and durable medical equipment supplier network development. |
| FDA Breakthrough Pathway | Compresses review timelines for ventilator-dependent respiratory failure indications addressing unmet clinical needs. |
| CE Marking Pathway | Enables EU MDR compliance for active implantable devices through expanded clinical evidence and post-market surveillance systems. |
| Software Companion Development | Enables remote patient monitoring and predictive maintenance alerts for home-based diaphragm pacing deployment. |
Research Approach
The analysis maps implantable platforms, external stimulators, and catheter-based delivery systems, each validated through thoracic surgeons, biomedical engineers, hospital purchasing committee members, and durable medical equipment procurement leads. Primary interviews with GPO contracts managers and neurophysiology specialists combined with FDA 510(k) and PMA filings, EU MDR notified body documentation, and CMS Medicare reimbursement databases. Bottom-up procedure volume estimates triangulate against top-down market sizing across neuromuscular and congenital indication segments.
Consistency checks validated volume and value outputs against hospital procurement database benchmarks and academic medical center surgical volume disclosures. The forecast framework models product architecture, therapy indication, care delivery location, and regulatory approval status dimensions across the projection horizon. CAGRs derive from logistic diffusion curves fitted to ventilator-weaning protocol adoption rates and home care infrastructure expansion trajectories, with inputs from platinum-iridium electrode longevity studies and battery replacement cycle data.
Decision-makers should treat outputs as directional under assumptions of stable FDA breakthrough designation velocity and EU MDR certification timeline continuity; material deviation in regulatory throughput or reimbursement code consolidation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Pediatric Respiratory Syncytial Virus Infection Market
Respiratory Therapy
Alpha-1 Antitrypsin Deficiency (AATD) Treatment Market
Respiratory Therapy
Endobronchial Valve Market
Respiratory Therapy
Breathing Disorders Treatment Market
Respiratory Therapy
Virus-Induced Asthma Treatment Market
Respiratory Therapy
Pediatric Respiratory Disease Therapeutics Market
Respiratory Therapy
Pneumoconiosis Treatment Market
Respiratory Therapy
Pneumonia Treatment Market
Respiratory Therapy
Artificial Lung Market
Respiratory Therapy
Respiratory Antiviral Treatment Market
Respiratory Therapy
Global Hypoxia Treatment Market
Respiratory Therapy
Emphysema Treatment Market
Respiratory Therapy
Global Bronchitis Treatment Market
Respiratory Therapy
Asthma and COPD Biomarkers Market
Respiratory Therapy
Respiratory Disorders Treatment Market
Respiratory Therapy
China Topical Oxygen Therapy Market