
 Artificial Lung Market | 2026-2036
Artificial Lung Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Lung Market Outlook
North American medical device manufacturers is pivoting toward hybrid artificial lung platforms that combine membrane oxygenation with ambulatory support. Getinge AB leverages its intensive care portfolio to sustain leadership in extracorporeal systems. Medtronic plc anchors its position through deep vascular access expertise. Abbott Laboratories differentiates via integrated monitoring ecosystems that pair oxygenation hardware with real-time hemodynamic analytics.
An artificial lung is a mechanical or bioengineered device that replaces or supplements pulmonary gas exchange by routing blood across semipermeable membranes with surface areas typically exceeding 1.5 square meters, achieving oxygen transfer rates of 100-300 mL per minute depending on configuration. These systems serve patients with irreversible respiratory failure, bridging them toward recovery or transplantation. Extracorporeal membrane oxygenation systems command the dominant revenue share due to established reimbursement codes and mature perfusionist training infrastructure, while portable systems represent the fastest-expanding segment as microfluidic pump miniaturization enables ambulatory deployment. Biomaterials technology occupies the highest-margin tier, with silicone and polymethylpentene hollow-fiber membranes commanding premium pricing over earlier polypropylene generations.
FDA enforces premarket approval pathways for Class III life-support devices, while the EU MDR requires notified-body conformity assessment and post-market clinical follow-up for active implantable respiratory supports. ISO 10993 biocompatibility standards and IEC 60601 electrical safety protocols govern material selection and system validation across both jurisdictions. Stakeholders must monitor evolving CMS national coverage determinations for ambulatory ECMO, as reimbursement expansion would fundamentally shift the addressable patient population beyond ICU confines.
Market Dynamics
Membrane oxygenation technology is pivoting from stationary ICU systems toward ambulatory platforms, compressing device form factors while expanding addressable patient populations beyond hospital confines. This structural shift reconfigures supply chains, regulatory pathways, and reimbursement frameworks simultaneously.
Growth Catalysts
- FDA Breakthrough Device Designation:Accelerated clinical trial timelines for ECMO systems compress development cycles, enabling faster market entry for membrane oxygenation innovations targeting acute respiratory distress.
- Hospital ICU Expansion:Intensive care units in the United States, Germany, and Japan are scaling membrane oxygenation capacity, driven by established perfusionist training infrastructure and mature reimbursement codes.
- Microfluidic Pump Miniaturization:Advances in compact pump engineering enable portable artificial lung deployment, creating ambulatory care pathways previously confined to bedside systems.
Market Restraints
- Silicone Membrane Supply Concentration:Hollow-fiber silicone and polymethylpentene production clusters in select manufacturing regions, exposing device makers to input bottlenecks and price volatility.
- EU MDR Conformity Assessment:Notified-body bottlenecks and expanded post-market clinical follow-up requirements extend certification timelines for active implantable respiratory supports.
- Perfusionist Workforce Scarcity:Specialized training pipelines for extracorporeal membrane oxygenation operation lag system deployment rates, constraining effective utilization even where hardware exists.
Strategic Opportunities
- CMS Ambulatory ECMO Reimbursement Expansion:Pending national coverage determinations would shift patient populations beyond ICU confines, fundamentally enlarging the addressable market for portable systems.
- Integrated Hemodynamic Monitoring Convergence:Pairing oxygenation hardware with real-time analytics platforms creates differentiated value propositions for critical care providers seeking unified data ecosystems.
- Japan ECMO Center Network Density:Underpenetrated regional clusters within Japan's existing network infrastructure present deployment opportunities for next-generation membrane systems.
Industry Challenges
- IEC 60601 Electrical Safety Validation:Compliance with international electrical safety protocols for active implantable devices demands specialized testing infrastructure and extended engineering cycles.
- ISO 10993 Biocompatibility Certification:Material selection and validation against biocompatibility standards requires iterative testing, compressing development schedules for novel membrane chemistries.
- Legacy System Integration Complexity:Hybrid artificial lung platforms must interface with existing hospital IT and monitoring architectures, creating deployment friction in established ECMO centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Lung Market |
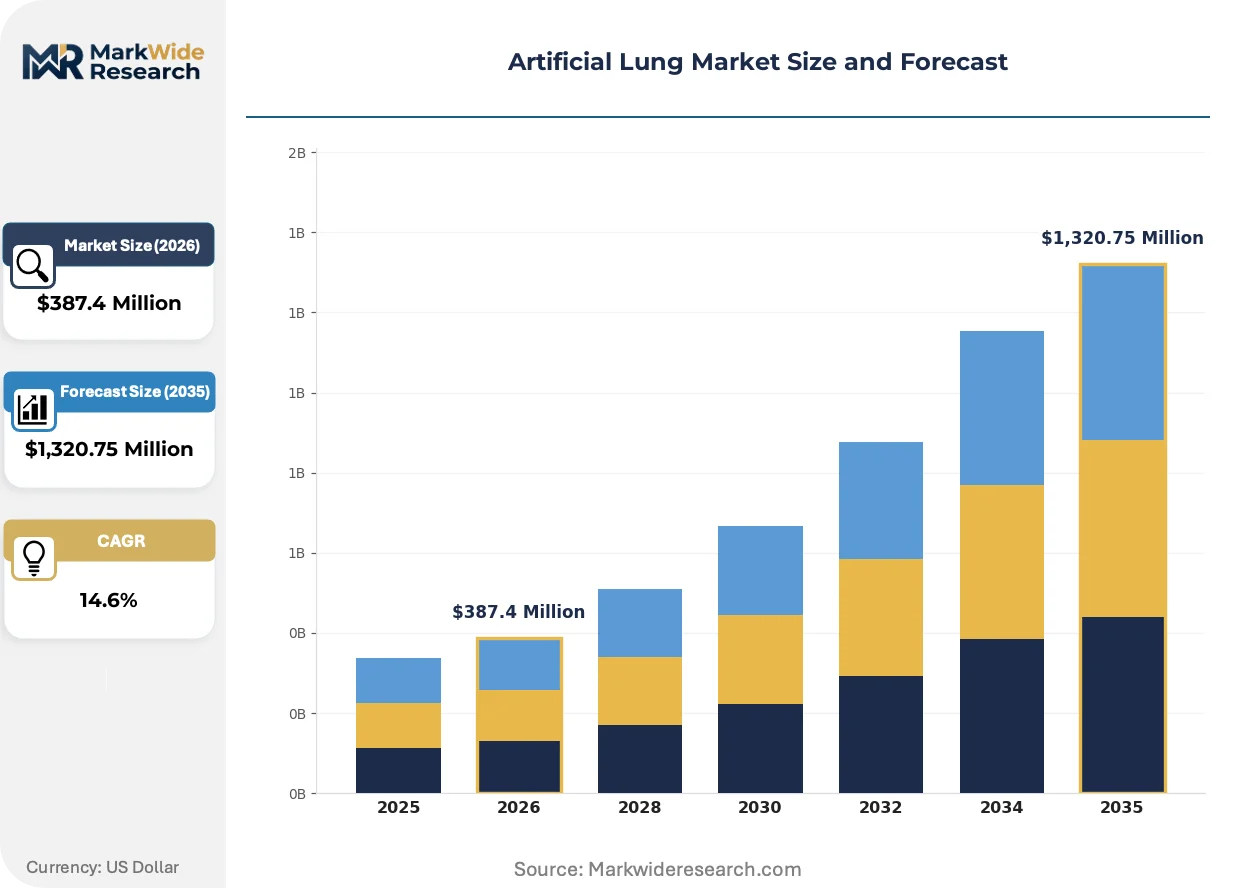
| Market Size in 2026 | $387.4 Million |
| Market Size in 2035 | $1,320.75 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extracorporeal Membrane Oxygenation, Ventilator Support, Invasive Devices, Non-Invasive Devices Application: Respiratory Failure, Cardiac Failure, Pulmonary Rehabilitation, Acute Respiratory Distress Syndrome End User: Hospitals, Specialty Clinics, Home Care Settings, Rehabilitation Centers Technology: Biomaterials, Portable Systems, Microfluidics, Hybrid Technologies |
| Companies Covered | Getinge AB, Xenios AG, Medtronic plc, Abbott Laboratories, Abiomed, Terumo Corporation, LivaNova PLC, Fresenius Medical Care, ALung Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Lung Market Strategic Shifts
Active miniaturization of blood-gas exchange surfaces is compressing device footprints while preserving oxygen transfer performance. This engineering trajectory is enabling new care settings and patient mobility paradigms.
Polymethylpentene hollow-fiber membranes are expanding into ambulatory artificial lung configurations, replacing earlier polypropylene generations in portable systems. Critical care units in Germany and Japan are adopting these compact platforms for inter-hospital patient transport. The technology is expanding into home-based respiratory support applications previously deemed technically unfeasible.
EU MDR post-market clinical follow-up requirements are tightening evidence-generation obligations for active implantable respiratory devices. Manufacturers must now sustain longitudinal safety databases across product lifecycles, elevating regulatory affairs staffing and infrastructure investment. Portable system developers face particular pressure, as ambulatory deployment generates novel real-world evidence demands.
Hospital procurement committees are consolidating vendor relationships around integrated platform providers capable of delivering oxygenation hardware with embedded monitoring analytics. Standalone device manufacturers face displacement unless they forge data-integration partnerships or develop captive analytics capabilities. This concentration is most visible in United States academic medical centers, where capital committees prioritize interoperability with existing electronic health record systems.
Artificial Lung Market Segmentation
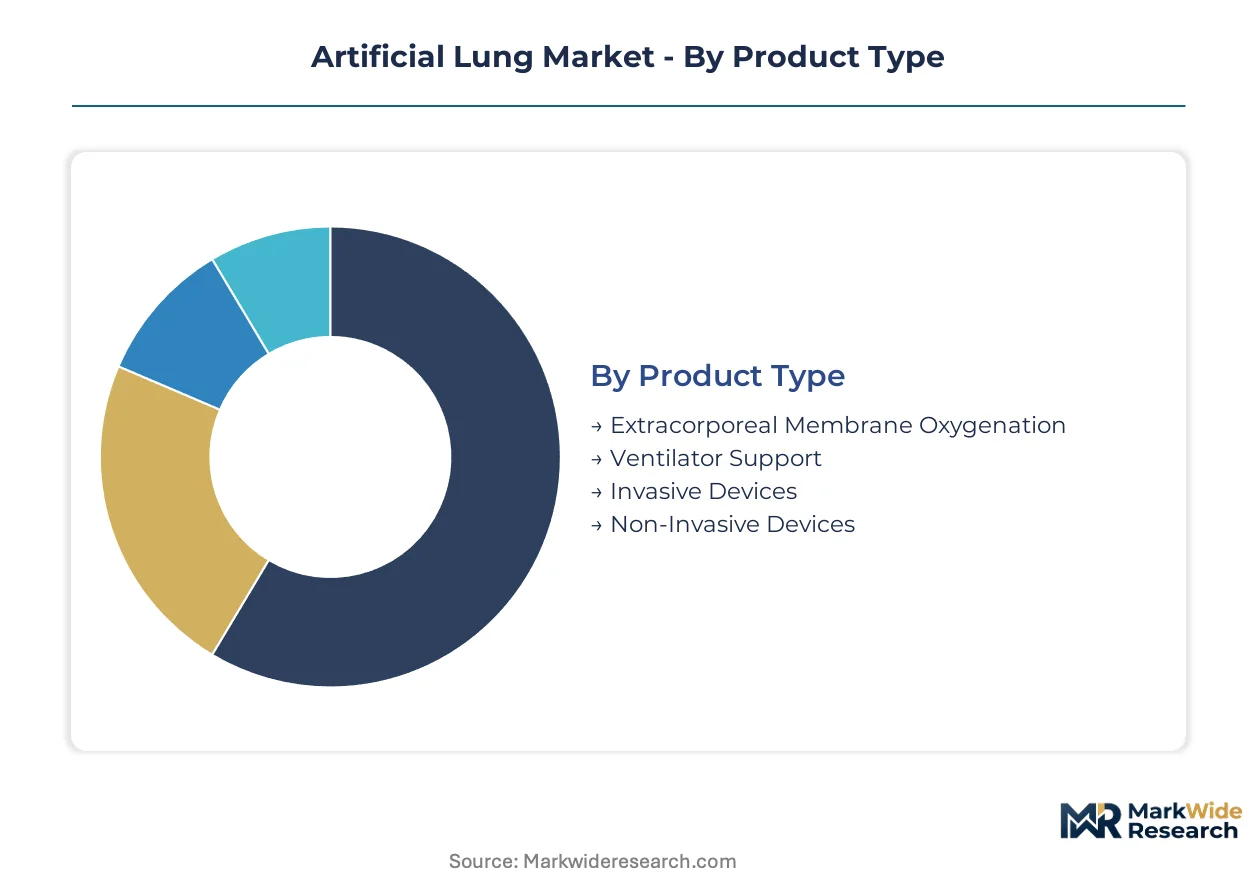
Artificial lung segmentation reflects divergent clinical workflows, from stationary ICU life support to ambulatory home deployment. Each category carries distinct regulatory pathways, reimbursement codes, and supply chain configurations that shape vendor positioning.
Product Type:
Hospital procurement committees weight capital intensity against patient throughput when selecting across these device categories.
- Extracorporeal Membrane Oxygenation:Stationary systems with hollow-fiber membrane bundles exceeding 1.5 square meters surface area dominate revenue. United States academic medical centers anchor demand through established perfusionist training pipelines and mature CMS reimbursement codes.
- Ventilator Support:Mechanical ventilation platforms with integrated gas exchange modules serve bridge-to-recovery scenarios. German ICU networks concentrate procurement of these hybrid configurations for inter-hospital transport applications.
- Invasive Devices:Vascular cannulation systems requiring surgical placement address acute cardiopulmonary collapse in tertiary referral centers.
- Non-Invasive Devices:Mask-based respiratory support platforms reduce intubation rates in early-stage respiratory failure.
Extracorporeal membrane oxygenation leads volumes today; portable configurations within this category are gaining share fastest.
Application:
Clinical indication severity determines device selection, with mortality risk and treatment duration driving hardware specifications.
- Respiratory Failure:Irreversible pulmonary dysfunction requiring complete gas exchange replacement. Japanese ECMO center networks deploy these systems for bridge-to-transplant protocols.
- Cardiac Failure:Cardiopulmonary bypass support during cardiogenic shock or post-cardiotomy failure. United States heart transplant programs concentrate demand for veno-arterial configurations.
- Pulmonary Rehabilitation:Graduated respiratory support during recovery from acute lung injury.
- Acute Respiratory Distress Syndrome:Severe inflammatory lung injury with rapid oxygenation deterioration.
Respiratory failure applications dominate current installations; acute respiratory distress syndrome is climbing the fastest as ICU admission thresholds expand.
End User:
Care setting capabilities constrain device complexity, with staffing models and infrastructure investment creating tiered adoption patterns.
- Hospitals:Tertiary centers with 24/7 perfusionist coverage and cardiac surgery backup anchor system deployment. United States, Germany, and Japan host the densest concentration of ECMO-capable facilities.
- Specialty Clinics:Pulmonary and cardiac-focused outpatient centers manage stable patients on chronic respiratory support.
- Home Care Settings:Ambulatory platforms with miniaturized pumps and portable oxygen supplies enable discharge of stable patients. CMS reimbursement expansion would unlock this segment's steepest expansion trajectory.
- Rehabilitation Centers:Post-acute facilities wean patients from mechanical ventilation toward unassisted breathing.
Hospitals retain the dominant installed base; home care settings show the most rapid enrollment growth where reimbursement permits.
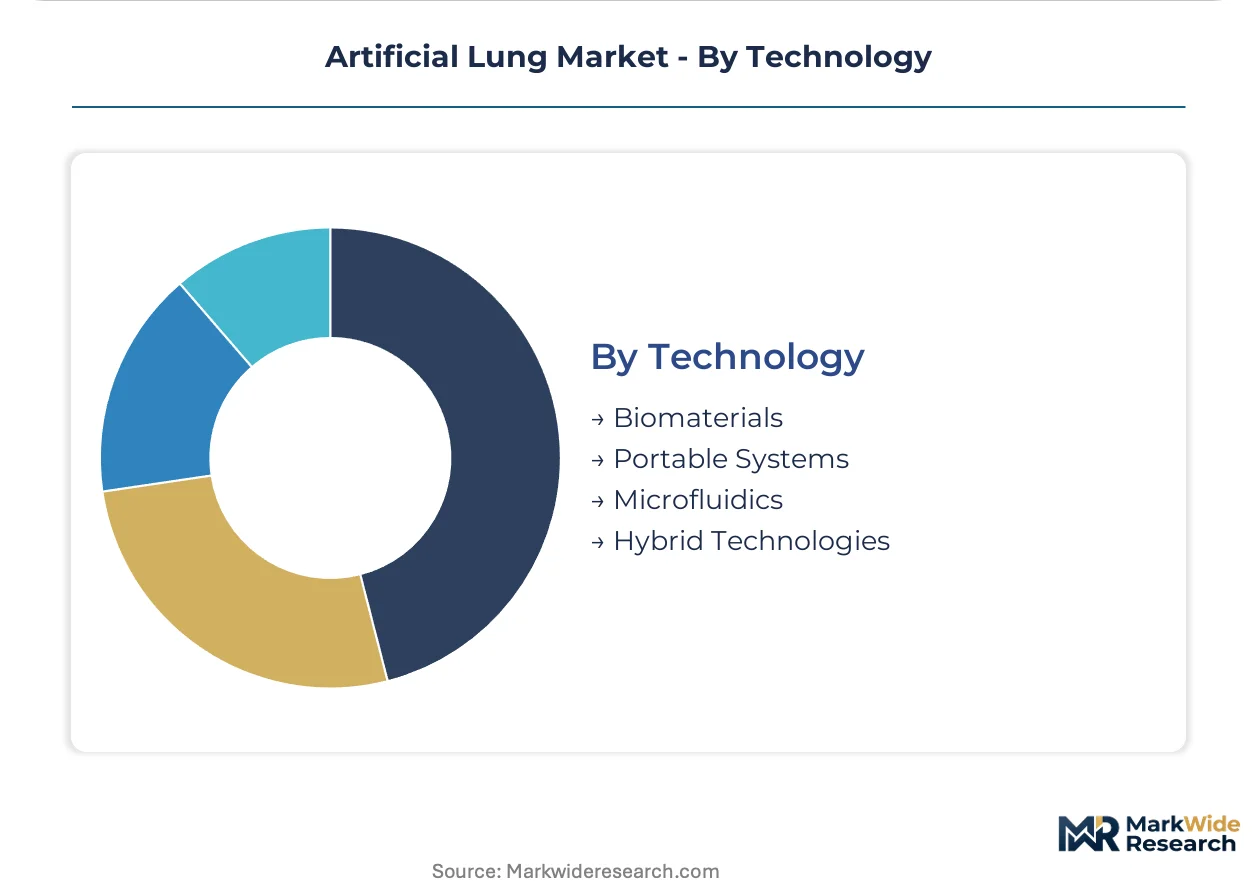
Technology:
Material science and microengineering advances are compressing device footprints while preserving gas exchange performance.
- Biomaterials:Silicone and polymethylpentene hollow-fiber membranes command premium pricing over polypropylene predecessors. Surface coating technologies reduce thrombogenicity and extend circuit lifespan in United States ECMO programs.
- Portable Systems:Battery-powered pumps with compact oxygenators enable patient mobility. German inter-hospital transport networks and Japanese home care pilots drive validation of these configurations.
- Microfluidics:Chip-based blood-gas exchange surfaces promise radical miniaturization for implantable applications.
- Hybrid Technologies:Integrated platforms combining membrane oxygenation with hemodynamic monitoring and automated anticoagulation management.
Biomaterials platforms generate the highest margin contribution; portable systems are expanding most quickly as microfluidic engineering matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States ECMO center density outstrips German deployment rates, while Japanese home care pilots accelerate faster than either market anticipated. Regulatory frameworks and reimbursement structures diverge sharply across these three anchor markets.
United States
FDA breakthrough device designations compress clinical trial timelines for membrane oxygenation systems. CMS reimbursement codes for extracorporeal support anchor demand at academic medical centers in Boston, Houston, and Pittsburgh. The Southeast corridor scales perfusionist training pipelines to match ICU expansion.
Germany
EU MDR conformity assessment requirements extend certification timelines for active implantable respiratory devices. Notified-body bottlenecks concentrate validation work in Baden-Württemberg and Bavaria. Inter-hospital transport networks in North Rhine-Westphalia validate polymethylpentene membrane configurations for mobile deployment.
Japan
PMDA accelerated approval pathways enable faster market entry for miniaturized pump systems. METI funding programs support microfluidic engineering clusters in Kansai and Chubu regions. Tokyo academic centers pilot ambulatory ECMO discharge protocols previously confined to inpatient settings.
United Kingdom
NHS specialized commissioning frameworks concentrate artificial lung deployment at designated tertiary centers in London, Manchester, and Birmingham. MHRA post-Brexit regulatory autonomy creates divergence from EU MDR timelines. Scottish health boards expand transport ECMO capacity for remote patient retrieval.
China
NMPA innovation approval channels for Class III life-support devices accelerate domestic manufacturer market entry. National health insurance reimbursement expansion for extracorporeal support concentrates procurement in Shanghai, Beijing, and Guangzhou hospital networks. Yangtze River Delta medical device clusters scale hollow-fiber membrane production capacity.
Artificial Lung Market Competitive Environment
United States producers anchor one tier; European specialists hold differentiated positions in membrane materials and transport systems. The vendor base concentrates around integrated platform providers capable of delivering oxygenation hardware with embedded monitoring capabilities. Three archetypes dominate: diversified medical technology conglomerates with intensive care portfolios, dedicated extracorporeal device specialists, and emerging microfluidic engineering firms. Competitive moves center on strategic partnerships for data-integration capabilities and geographic expansion into underpenetrated ECMO center networks.
Within the diversified conglomerate tier, Getinge AB, Medtronic plc, and Abbott Laboratories exemplify positioning around integrated critical care ecosystems. Getinge leverages its intensive care portfolio breadth across European and North American hospital networks. Medtronic anchors its presence through vascular access expertise accumulated across cardiac surgery markets. Abbott differentiates via monitoring platform integration that pairs oxygenation hardware with hemodynamic analytics. These three entities represent distinct strategic postures within a market segment favoring comprehensive platform providers over standalone device manufacturers.
| Leading Market Players |
|---|
| Getinge AB |
| Xenios AG |
| Medtronic plc |
| Abbott Laboratories |
| Abiomed |
| Terumo Corporation |
| LivaNova PLC |
| Fresenius Medical Care |
| ALung Technologies |
| Others |
Value Chain & Pricing Dynamics
Polymethylpentene membrane manufacturing migration from batch to continuous extrusion methods is compressing unit production costs while concentrating supply among three specialized polymer houses in Germany, Japan, and the United States. This dual shift simultaneously lowers price floors for ambulatory system OEMs and elevates procurement risk for device makers lacking long-term offtake agreements with these specialized material suppliers.
Pricing Analysis
Capacity additions in China's Yangtze River Delta medical device clusters are reshaping price floors for polypropylene-based oxygenation modules. Three-tier pricing structure across premium polymethylpentene, standard silicone, and economy polypropylene membrane tiers reflects ISO 10993 biocompatibility certification levels and FDA breakthrough device designation status. Pricing pressure stems from CMS reimbursement code uncertainty for ambulatory ECMO, compressing margins for portable system developers. Academic medical centers demonstrate lowest price sensitivity due to bundled procurement budgets, while home care distributors face acute margin constraints.
Supply Chain Analysis
Direct-to-hospital channels handle high-volume ECMO system demand from United States academic medical centers, while specialty distributors serve German inter-hospital transport networks. Hollow-fiber membrane production concentrates in Germany, Japan, and the United States, with silicone polymer feedstocks drawing from petrochemical complexes in the US Gulf Coast and Rotterdam-Antwerp corridor. Polymethylpentene resin supply rests on single-source licensing agreements from Mitsui Chemicals, creating vulnerability for second-tier device manufacturers. Distribution runs through GPO contracts at three major United States hospital purchasing alliances and direct OEM relationships in Japan's Tokyo-Osaka corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The artificial lung market has entered a late-cycle quality phase where polymethylpentene membrane performance specifications and integrated hemodynamic analytics capabilities command sustainable premium positioning against commodity polypropylene alternatives.
For Market Incumbents: Extend perfusionist training infrastructure partnerships into underpenetrated Japanese regional clusters to defend installed base against emerging microfluidic pump specialists. Deepen backward integration into polymethylpentene membrane supply through captive production or exclusive offtake agreements, as silicone feedstock volatility threatens margin stability for non-integrated device makers. For New Entrants and Emerging Players: Ambulatory ECMO reimbursement expansion presents the most penetrable white-space opportunity, with CMS national coverage determinations pending for home-based respiratory support. Microfluidic pump miniaturization expertise enables direct hospital system partnerships bypassing established distributor relationships, particularly in German inter-hospital transport networks where portable system validation is accelerating. For Investors and Strategic Acquirers: Valuations sit cheapest among microfluidic engineering specialists with FDA breakthrough device designations but limited commercial scale. Long-term viability favors platforms combining oxygenation hardware with software-defined monitoring ecosystems over standalone membrane suppliers. The signal to watch is CMS ambulatory ECMO reimbursement code finalization, which would inflect addressable patient population and justify premium acquisition multiples for portable system developers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerated clinical trial timelines compress development cycles for membrane oxygenation innovations targeting acute respiratory distress. |
| CE Marking Pathway under EU MDR | Notified-body conformity assessment requirements extend certification timelines, elevating regulatory affairs investment for active implantable respiratory supports. |
| Hospital System Partnership | Academic medical centers in Boston, Houston, and Pittsburgh consolidate vendor relationships around integrated platform providers with embedded analytics capabilities. |
| Software Companion Development | Real-time hemodynamic analytics integration creates differentiated value propositions for critical care providers seeking unified data ecosystems. |
| Reimbursement Strategy | CMS national coverage determinations for ambulatory ECMO would fundamentally shift addressable patient populations beyond ICU confines. |
Study Parameters
Multiple input streams — structured interviews with ECMO program directors and perfusionist training coordinators, hospital procurement database analysis, and regulatory filing review — were reconciled to construct demand estimates. Primary fieldwork engaged biomedical engineers at tertiary centers in the United States, Germany, and Japan alongside GPO contracts managers and FDA regulatory affairs specialists. Secondary validation drew from FDA 510(k) and PMA filings, EU MDR notified-body documentation, CMS national coverage determination records, and hospital capital expenditure disclosures. Bottom-up device shipment estimates were cross-referenced against top-down healthcare expenditure allocations for extracorporeal support.
Historical utilization patterns at ECMO center networks were cross-referenced against expert panel inputs from intensive care specialists and medical device procurement officers. Segmentation modeling spanned product configuration, clinical application severity, care setting infrastructure, and membrane material technology across the projection horizon. CAGRs were derived from trend extrapolation adjusted for regulatory approval timelines and reimbursement expansion scenarios. Forecast inputs incorporated perfusionist workforce growth projections and polymethylpentene membrane manufacturing capacity expansion schedules.
The model holds under stable FDA and EU MDR regulatory frameworks; deviation in CMS ambulatory coverage determinations or silicone supply disruptions would shift volume trajectories. Forecasts embed assumptions regarding ICU capacity expansion rates and membrane material substitution elasticities. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Respiratory Gating Market
Respiratory Therapy
Virus-Induced Asthma Treatment Market
Respiratory Therapy
Nitric Oxide Management Systems Market
Respiratory Therapy
Diaphragm Pacing Therapy System Market
Respiratory Therapy
Metered Dose Inhalers Market
Respiratory Therapy
Pulmonary Fibrosis Treatment Market
Respiratory Therapy
Opioid-Induced Respiratory Depression Market
Respiratory Therapy
Respiratory Inhaler Market
Respiratory Therapy
United States Idiopathic Pulmonary Fibrosis Treatment Market
Respiratory Therapy
Global Bronchitis Treatment Market
Respiratory Therapy
Cough Systems Market
Respiratory Therapy
Global Pneumonia Therapeutics Market
Respiratory Therapy
Pediatric Respiratory Syncytial Virus Infection Market
Respiratory Therapy
Respiratory Antiviral Treatment Market
Respiratory Therapy
Compression Therapy Market
Respiratory Therapy
Oxygen Therapy Equipment Market