
 Public Safety Market | 2026-2036
Public Safety Market Size, Share, and Industry Trends Forecast 2026-2036
Public Safety Market Outlook
Aftermarket service revenue for legacy radio and surveillance infrastructure is tilting toward cloud-managed platforms and predictive maintenance contracts. Motorola Solutions dominates land-mobile radio upgrade cycles across North American public safety agencies. L3Harris Technologies anchors defense-adjacent communications portfolios that extend into federal emergency response channels. Honeywell leverages building automation expertise to compete in integrated command-and-control center deployments.
Public safety encompasses the systems, services, and protocols that protect populations from criminal activity, natural disasters, and civil emergencies through detection, response coordination, and consequence mitigation. Core technologies include encrypted narrowband voice communications operating in 700-800 MHz bands, IP-based video management platforms with edge analytics processing, and multi-agency computer-aided dispatch software integrating GIS, caller location, and resource availability data. Communication Systems and Surveillance Equipment represent mature margin pools where vendor consolidation has reduced price competition, while AI Analytics within the Technology dimension captures the fastest capability expansion as agencies deploy real-time object recognition and behavioral anomaly detection. Emergency Response Solutions show structural growth from climate-driven disaster frequency, with mobile command units and drone-based situational assessment gaining procurement priority.
FCC Part 90 rules govern spectrum allocation and interoperability standards for US public safety communications, while the EU AI Act imposes risk-classification requirements on automated surveillance systems deployed in public spaces. NHTSA guidelines shape emergency vehicle safety standards that filter into fleet procurement specifications. Stakeholders must monitor evolving encryption mandates and cross-border data transfer restrictions that will determine which platform architectures achieve regulatory clearance for multinational deployment.
Market Dynamics
Interoperability mandates from the FCC and EU AI Act are compressing upgrade cycles for encrypted narrowband systems while forcing algorithmic transparency investments across video analytics platforms.
Growth Catalysts
- FCC Part 90 spectrum reallocation:US public safety agencies are replacing legacy T-band equipment with 700-800 MHz P25-compliant infrastructure, triggering wholesale radio refresh cycles across municipal departments.
- Climate-driven disaster frequency:Emergency response units in Germany and China are procuring mobile command vehicles and drone-based situational assessment systems for wildfire and flood response.
- Edge AI processing:Real-time behavioral anomaly detection at the camera level is reducing bandwidth costs and latency for urban surveillance networks in smart city deployments.
Market Restraints
- Semiconductor supply concentration:Specialized encryption chipsets for public safety radios depend on concentrated foundry capacity in East Asia, creating procurement bottlenecks for North American OEMs.
- GDPR cross-border data friction:Automated surveillance systems deployed by multinational agencies face operational restrictions on biometric data transfers between EU and non-EU jurisdictions.
- Legacy system technical debt:Analog narrowband infrastructure in rural US counties lacks backward compatibility with IP-based dispatch platforms, forcing parallel maintenance costs.
Strategic Opportunities
- India smart city expansion:Municipal corporations in Mumbai, Delhi, and Bangalore are tendering for integrated command-and-control centers under the Ministry of Housing and Urban Affairs programs.
- Predictive maintenance contracts:Cloud-managed radio networks enable recurring revenue models that displace break-fix service arrangements for legacy LMR infrastructure.
- EU Green Deal procurement criteria:Emergency vehicle fleets in France and the Netherlands face electrification mandates that favor integrated energy management and telematics platforms.
Industry Challenges
- Encryption certification timelines:NIST FIPS 140-3 validation for public safety communications hardware extends product launch windows by 18-24 months.
- Interoperability standard fragmentation:P25, TETRA, and DMR protocol coexistence forces agencies to maintain multimode gateway equipment, complicating fleet management.
- AI bias audit capability gaps:Police departments lack in-house data science capacity to conduct required algorithmic impact assessments under the EU AI Act high-risk system classification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Public Safety Market |
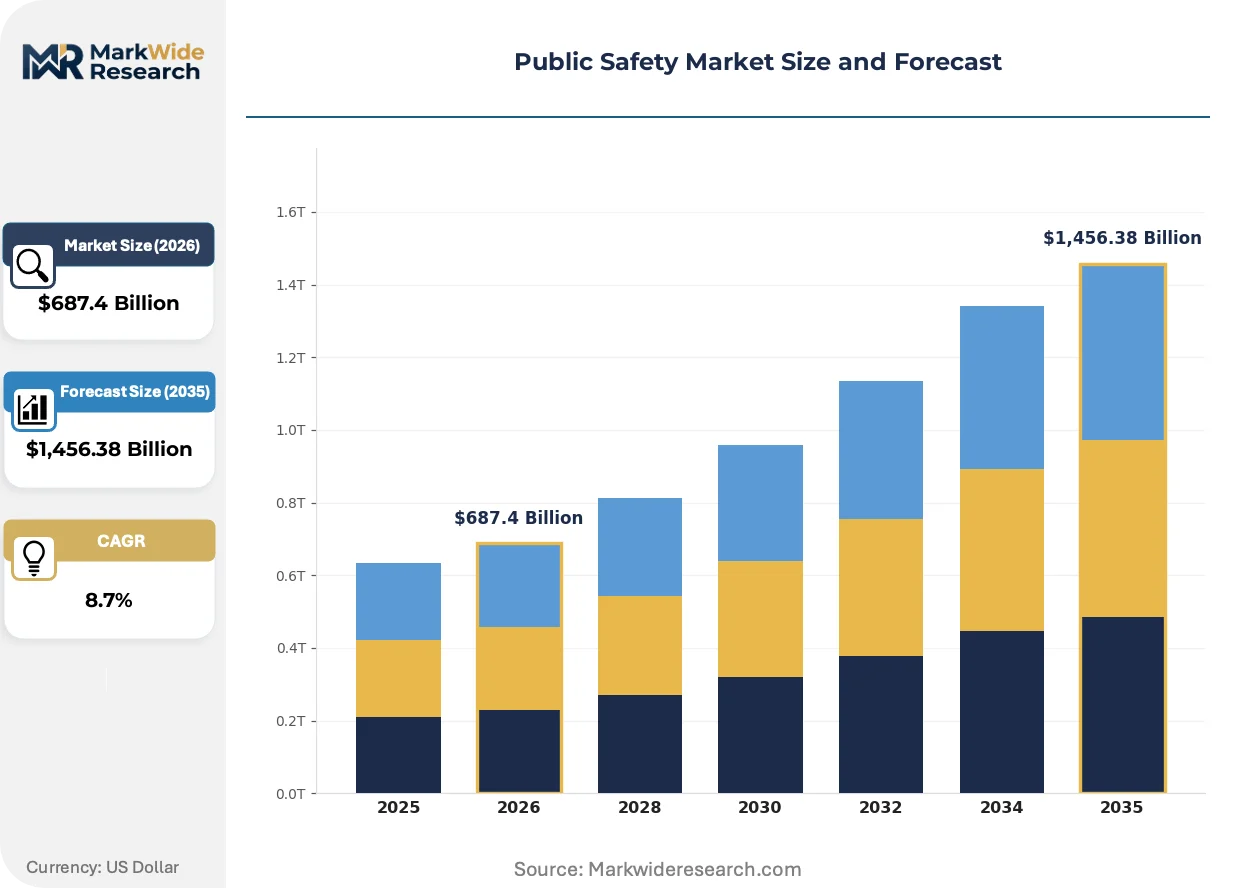
| Market Size in 2026 | $687.4 Billion |
| Market Size in 2035 | $1,456.38 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surveillance Equipment, Communication Systems, Emergency Response Solutions, Access Control End User: Law Enforcement, Fire Departments, Emergency Medical Services, Government Agencies Technology: Cloud Solutions, AI Analytics, Mobile Applications, IoT Integration Application: Crime Prevention, Disaster Management, Public Gathering Security, Traffic Monitoring |
| Companies Covered | Honeywell, L3Harris Technologies, Motorola Solutions, Thales, IBM, Cisco Systems, General Dynamics, Atos, Siemens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Public Safety Market Strategic Shifts
Real-time sensor fusion and automated threat correlation are displacing siloed detection systems, while procurement patterns favor integrated platform vendors over point-solution specialists.
Computer-aided dispatch software is migrating from on-premise server installations to cloud-native architectures with API-first integration layers. State-level emergency management agencies in Texas and Florida are piloting these deployments for multi-jurisdictional resource coordination. The shift is compressing vendor margins on perpetual license sales while expanding subscription attach rates for GIS and mobile data modules.
The EU AI Act risk-classification framework imposes conformity assessment requirements on biometric identification systems deployed in publicly accessible spaces. Vendors must maintain technical documentation and human oversight protocols for real-time facial recognition in transport hubs. German federal police procurement specifications now mandate algorithmic transparency disclosures that exceed baseline CE marking obligations.
Municipal buyers are consolidating vendor relationships through master service agreements that bundle hardware, software, and decade-long maintenance commitments. This pattern concentrates purchasing power with integrated platform providers and marginalizes point-solution vendors lacking nationwide service networks. The trend is most pronounced in US counties with populations exceeding 500,000, where procurement offices face staffing constraints for multi-vendor contract administration.
Public Safety Market Segmentation
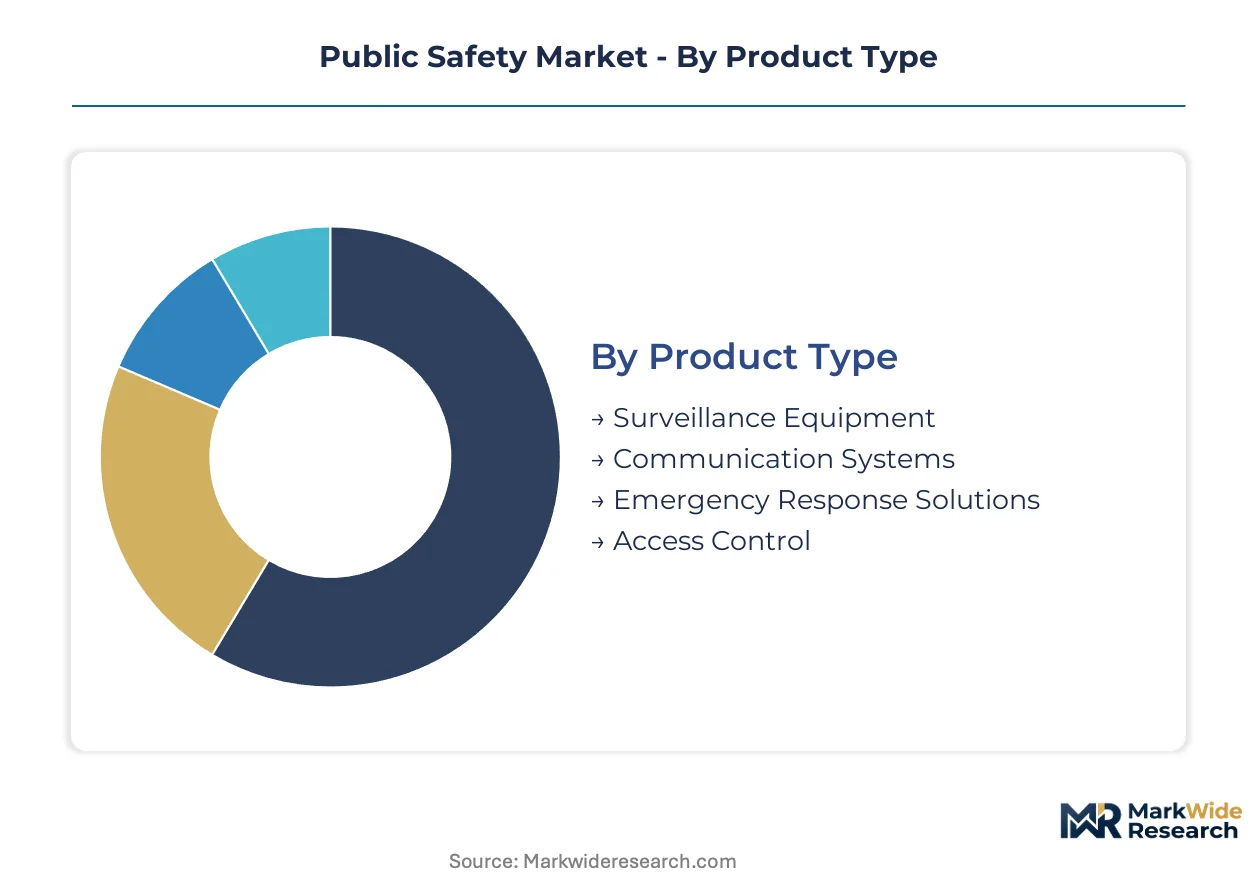
Public safety procurement operates through distinct technical and operational lenses. Vendors must align product architecture with end-user mission profiles and regulatory compliance tiers to secure multi-year agency contracts.
Product Type:
Cost tier differentiation separates capital-intensive hardware installations from software-subscription models across municipal budgets.
- Surveillance Equipment:IP-based video management platforms with edge analytics processing dominate urban deployments. US smart city infrastructure programs and Chinese municipal security networks drive concentrated demand for multi-sensor fusion arrays.
- Communication Systems:Encrypted narrowband voice systems operating in 700-800 MHz bands constitute the technical backbone of first-responder coordination. FCC Part 90 reallocation mandates in the United States and TETRA modernization in Germany are compressing replacement cycles for legacy land-mobile radio infrastructure.
- Emergency Response Solutions:Mobile command units and drone-based situational assessment systems address climate-driven disaster frequency.
- Access Control:Biometric and credential-based entry systems secure critical infrastructure facilities.
Communication Systems holds installed capacity. AI Analytics is rotating up the share rankings.
End User:
Customer type determines procurement authority levels and interoperability requirements across agency hierarchies.
- Law Enforcement:Police departments deploy integrated computer-aided dispatch software combining GIS, caller location, and resource availability data. EU AI Act compliance costs for automated surveillance systems are reshaping vendor selection criteria in France and Germany.
- Fire Departments:Thermal imaging and hazardous materials detection equipment anchor equipment portfolios. Wildfire response units in California and Australia prioritize drone-based situational assessment for remote terrain access.
- Emergency Medical Services:Patient data transmission and fleet telematics integration dominate technology refresh priorities.
- Government Agencies:Federal emergency management channels require defense-adjacent communications security certifications.
Law Enforcement commands the largest procurement volume. Emergency Medical Services is gaining share fastest through telemedicine integration mandates.
Technology:
Maturity curves separate proven deployment models from emerging capability layers requiring regulatory validation.
- Cloud Solutions:Computer-aided dispatch software is migrating from on-premise server installations to cloud-native architectures with API-first integration layers. Texas and Florida state emergency management agencies pilot multi-jurisdictional resource coordination through these platforms.
- AI Analytics:Real-time object recognition and behavioral anomaly detection at the camera level reduce bandwidth costs for urban surveillance networks. GDPR cross-border data friction constrains biometric data transfers between EU and non-EU jurisdictions.
- Mobile Applications:Field officer access to dispatch and records systems extends operational reach beyond vehicle-based terminals.
- IoT Integration:Sensor fusion across emergency vehicle fleets and wearable devices creates unified situational awareness.
Cloud Solutions holds current deployment scale. AI Analytics shows the steepest expansion trajectory as agencies navigate EU conformity assessment requirements.
Application:
Geography and incident type shape specification requirements and interoperability standards.
- Crime Prevention:Real-time facial recognition in transport hubs triggers EU AI Act high-risk system classification and mandated human oversight protocols. German federal police specifications now require algorithmic transparency disclosures exceeding baseline CE marking obligations.
- Disaster Management:Climate-driven wildfire and flood response is accelerating procurement of mobile command vehicles in Germany and China. Integrated energy management platforms face EU Green Deal electrification mandates for emergency vehicle fleets.
- Public Gathering Security:Crowd density monitoring and threat detection systems secure stadiums and transit terminals.
- Traffic Monitoring:Automated incident detection and emergency vehicle preemption optimize roadway response times.
Crime Prevention maintains the deepest installed base. Disaster Management is climbing the fastest on climate adaptation spending.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across procurement contexts. Municipal buyers in the United States and Germany accept premium pricing for encrypted narrowband systems with NIST certification. Budget-constrained agencies in India and Brazil prioritize cost-optimized surveillance hardware with cloud-managed service tiers.
United States
FCC Part 90 spectrum reallocation mandates are compressing radio refresh cycles across municipal police and fire departments. NHTSA guidelines shape emergency vehicle safety standards that filter into fleet procurement specifications. Texas and Florida state emergency management agencies pilot cloud-native dispatch architectures for multi-jurisdictional coordination.
Germany
TETRA modernization programs and EU AI Act compliance costs are reshaping vendor selection for federal police automated surveillance systems. German federal police specifications now mandate algorithmic transparency disclosures exceeding baseline CE marking obligations. Bavaria and North Rhine-Westphalia concentrate procurement authority for integrated command-and-control center deployments.
China
Municipal security networks in smart city programs drive concentrated demand for multi-sensor fusion arrays and edge analytics processing. MIIT governs encryption standards for public safety communications infrastructure. Yangtze River Delta and Pearl River Delta metropolitan clusters anchor deployment scale for urban surveillance network expansion.
India
Municipal corporations in Mumbai, Delhi, and Bangalore tender for integrated command-and-control centers under Ministry of Housing and Urban Affairs programs. BIS certification requirements shape equipment import and domestic manufacturing compliance. Maharashtra and Karnataka state governments concentrate smart city security infrastructure spending in their capital metropolitan regions.
France
EU Green Deal electrification mandates favor integrated energy management platforms for emergency vehicle fleet procurement. ANSM and CNIL oversight extends to biometric data governance in automated surveillance deployments. Île-de-France regional procurement offices bundle hardware, software, and decade-long maintenance commitments through master service agreements.
Public Safety Market Competitive Environment
Capability concentration sits with integrated platform providers possessing nationwide service networks; scale advantage sits with defense-adjacent communications specialists holding federal security certifications. The vendor base separates into three strategic archetypes: legacy radio infrastructure incumbents, building automation integrators, and cloud-native dispatch software entrants. Dominant competitive moves include portfolio diversification into predictive maintenance contracts and strategic partnerships for AI analytics capability acquisition.
Within the integrated platform tier, Motorola Solutions and Honeywell exemplify archetype positioning through their respective land-mobile radio and building automation heritage. L3Harris Technologies occupies a position bridging defense communications security certification with federal emergency response channel access. These three anchors demonstrate how vendor consolidation has reduced price competition in mature margin pools while compressing upgrade cycles through interoperability mandates.
| Leading Market Players |
|---|
| Honeywell |
| L3Harris Technologies |
| Motorola Solutions |
| Thales |
| IBM |
| Cisco Systems |
| General Dynamics |
| Atos |
| Siemens |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta foundry capacity for specialized encryption chipsets constrains downstream pricing power for North American land-mobile radio OEMs, compressing margins on 700-800 MHz P25-compliant infrastructure while elevating premiums for NIST FIPS 140-3 validated hardware.
Pricing Analysis
Aftermarket service revenue through predictive maintenance contracts and cloud-managed platform subscriptions now drives lifetime value for integrated command-and-control center deployments. Three-tier pricing structure across premium, standard, and economy levels separates NIST-certified encrypted narrowband systems from CE-marked TETRA equipment and cost-optimized DMR alternatives. Price differentiation hinges on certification grade and geographic delivery cost, with FCC Part 90 compliance adding substantial validation overhead. Cost compression in economy-tier surveillance hardware is intensifying because municipal buyers in India and Brazil prioritize upfront capital efficiency over decade-long maintenance bundling. Government agencies with defense-adjacent security requirements show least price sensitivity; rural US counties with legacy analog infrastructure exhibit highest.
Supply Chain Analysis
Export-control regimes limiting semiconductor lithography equipment flows to Chinese foundries are reshaping procurement geography for public safety communications hardware. Taiwan, South Korea, and Japan anchor supply for encryption chipsets and edge analytics processors. Raw material dependencies span gallium nitride substrates for RF components, rare earth elements for magnet assemblies, and high-purity silicon wafers. Single-source vulnerability concentrates in East Asian foundry capacity for FIPS-validated secure elements. Distribution runs through defense-authorized distributors and municipal procurement offices with master service agreement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from cloud-native dispatch software entrants displacing on-premise CAD installations, requiring defensive portfolio moves to protect recurring revenue streams.
For Market Incumbents: Insulate installed base relationships by embedding predictive maintenance contracts that displace break-fix arrangements for legacy LMR infrastructure. Acquire edge AI analytics capability through strategic partnerships rather than organic development to compress EU AI Act compliance timelines. Vertical integration into secure element sourcing mitigates foundry concentration risk for encryption chipset supply.
For New Entrants and Emerging Players: Establish a beachhead in India smart city command-and-control center tenders where Motorola Solutions and Honeywell lack localized service density. Target state-level emergency management agencies in Texas and Florida piloting cloud-native dispatch architectures as the most penetrable buyer segment. Lead with API-first integration layers that interoperate with existing GIS and mobile data modules rather than rip-and-replace positioning.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated platform providers with nationwide service networks and federal security certifications over point-solution specialists. Long-term viability rests on recurring revenue attach rates displacing perpetual license models. Acquisition target archetype: cloud-native CAD software firms with state-level agency deployments. Signal to watch: EU AI Act high-risk system classification enforcement accelerating algorithmic transparency investment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first CAD architectures enable multi-jurisdictional resource coordination across Texas and Florida state agencies. |
| Strategic Partnership | Edge AI capability alliances compress EU AI Act compliance timelines for biometric identification system deployments. |
| Acquisition of Specialist Firm | Cloud-native dispatch software targets address displacement risk from on-premise server installations. |
| Geographic Expansion | India smart city tenders in Mumbai and Bangalore exploit service network gaps among integrated platform incumbents. |
| Regulatory Certification Investment | NIST FIPS 140-3 validation secures premium pricing tiers for 700-800 MHz P25-compliant infrastructure. |
Study Parameters
Initial hypotheses were tested against primary input from police and fire department procurement officers, state emergency management directors, federal security certification specialists, and integrated platform vendor sales executives and refined through secondary validation against FCC Part 90 rulemakings, EU AI Act implementing guidance, NHTSA emergency vehicle safety standards, SEC 10-K disclosures from Motorola Solutions and L3Harris Technologies, and municipal tender documents from Mumbai, Delhi, and Bangalore. Bottom-up segment sizing triangulated with top-down macroeconomic anchoring.
Demand-supply-balance framing structured the analytical framework across the projection horizon, modeling segmentation dimensions spanning product type, end user agency, technology deployment model, and application geography. CAGRs derived from historical replacement cycle analysis, regulatory mandate timelines, and climate-driven disaster frequency projections. Forecast inputs incorporated FCC spectrum reallocation schedules and EU Green Deal electrification mandates for emergency vehicle fleets.
Stress conditions across semiconductor foundry capacity utilization, cross-border data transfer restriction enforcement, and municipal budget contraction scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding interoperability standard adoption curves and AI bias audit capability development. Material shifts in NIST encryption certification timelines or EU AI Act high-risk system classification scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Safety
Outdoor Public Safety Market
Public Safety
Global IoT for Public Safety Market
Public Safety
AI for Public Security and Safety Market
Public Safety
Middle East Crime and Combat Market
Public Safety
Voice Evacuation Systems Market
Public Safety
North America Road Safety Market
Public Safety
US Mass Notification Systems Market
Public Safety
Global Public Safety and Security Market
Public Safety
Europe Wireless Broadband in Public Safety Market
Public Safety
Latin America Public Safety Market
Public Safety
Public Safety in-Building Wireless Distributed Antenna System (DAS) Market
Public Safety
Europe Road Safety Market
Public Safety
Counter Terror and Public Safety Technology Market
Public Safety
Safe City Market
Public Safety
Crowd Management System Market
Public Safety
Europe Public Safety Market