
 AI for Public Security and Safety Market | 2026-2036
AI for Public Security and Safety Market Size, Share, and Industry Trends Forecast 2026-2036
AI for Public Security and Safety Market Analysis
The capability gap between full-stack platform providers and point-solution vendors is redrawing competitive boundaries across the AI for Public Security and Safety landscape. Motorola Solutions leverages its deep integration of radio communications with AI-driven video analytics to dominate public safety command centers. Hexagon AB anchors its position through advanced geospatial intelligence fused with real-time incident prediction algorithms. IBM competes by extending its Watson AI suite into threat detection workflows for homeland security clients.
AI for Public Security and Safety encompasses machine learning algorithms, computer vision systems, and natural language processing engines deployed to predict, detect, and respond to threats against populations and critical infrastructure. These systems process multi-source data streams—video feeds, sensor networks, social media, and emergency calls—to generate actionable intelligence for first responders within seconds. Video Analytics technology leads solution deployments due to its maturity in crowd monitoring and anomaly detection, while Facial Recognition faces structural headwinds from evolving privacy mandates that constrain margin pools. Threat Detection solutions within the Solution segment command premium positioning as agencies prioritize preemptive intervention over post-incident analysis.
The EU AI Act, GDPR, and the US Department of Homeland Security's AI governance framework collectively shape product roadmaps by mandating algorithmic transparency, bias auditing, and human-in-the-loop decision protocols. The US Food and Drug Administration's emerging oversight of AI-enabled medical emergency triage systems further complicates vendor compliance obligations across dual-use applications. Stakeholders must monitor regulatory divergence between jurisdictions to avoid architecture lock-in that limits cross-border contract eligibility.
Market Dynamics
The EU AI Act's prohibition of biometric surveillance in public spaces is forcing vendors to reengineer facial recognition architectures, compressing development timelines and redrawing competitive boundaries between compliant full-stack providers and legacy point-solution vendors.
Growth Catalysts
- Federal Homeland Security Grants:US municipal agencies deploy AI-powered video analytics networks through dedicated funding streams for smart city infrastructure and real-time crime center platforms.
- Predictive Policing Algorithms:Law enforcement agencies accelerate procurement of machine learning systems that forecast incident hotspots from historical crime data and environmental sensors.
- Critical Infrastructure Protection Mandates:Energy and transportation operators in Germany and France adopt threat detection AI to satisfy national security directives for perimeter monitoring and anomaly identification.
Market Restraints
- GPU Supply Concentration:Training workloads for computer vision models depend on NVIDIA and AMD chipsets, creating procurement bottlenecks when foundry capacity tightens.
- GDPR Algorithmic Accountability:European data protection authorities require explainable AI documentation that extends sales cycles and inflates compliance costs for biometric system vendors.
- On-Premise Deployment Costs:Agencies with classified data requirements must build dedicated inference infrastructure rather than accessing cloud APIs, doubling capital requirements versus SaaS alternatives.
Strategic Opportunities
- Edge AI Convergence:Federated learning architectures combined with 5G network slicing enable real-time inference without data egress, opening sovereign cloud contracts for defense and intelligence clients.
- India Smart City Mission:Municipal corporations in Mumbai, Delhi, and Bangalore issue tenders for integrated command centers that fuse video analytics with emergency response dispatch systems.
- Human-in-the-Loop Certification:The US Department of Homeland Security's AI governance framework creates premium positioning for vendors offering auditable decision protocols with mandatory operator override functions.
Industry Challenges
- Adversarial Machine Learning Expertise:Security agencies lack personnel capable of red-teaming computer vision systems against spoofing attacks and data poisoning attempts.
- Legacy CAD Integration:Computer-aided dispatch systems from the 1990s resist API connectivity, forcing expensive middleware development for AI-generated alerts to reach field officers.
- Bias Audit Documentation:Third-party fairness certification for facial recognition algorithms requires 18-24 month validation cycles that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI for Public Security and Safety Market |
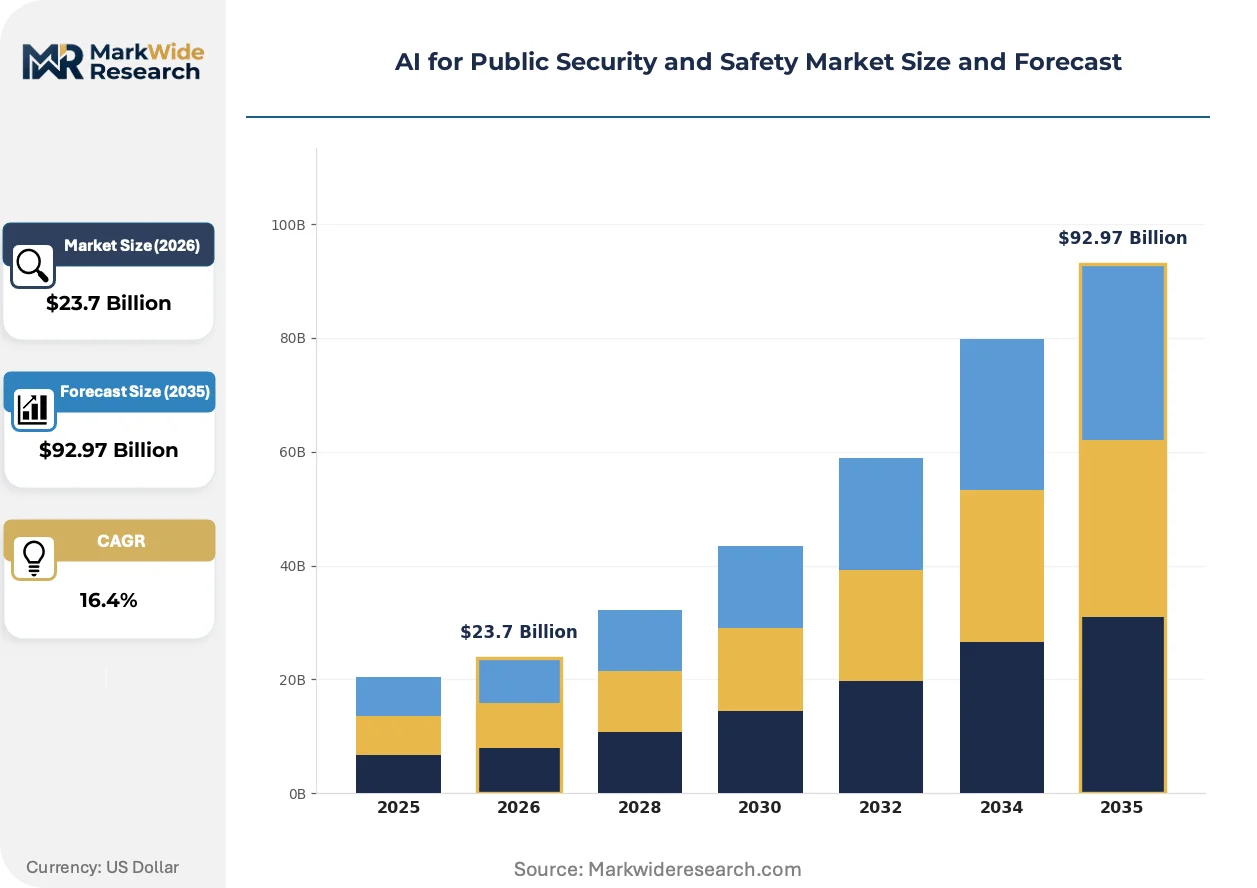
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $92.97 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Facial Recognition, Video Analytics, Natural Language Processing End User: Law Enforcement, Fire Departments, Emergency Services, Homeland Security Solution: Surveillance Systems, Threat Detection, Incident Response, Risk Assessment Service Type: Consulting, System Integration, Maintenance, Training |
| Companies Covered | Motorola Solutions, Hexagon AB, Atos SE, Honeywell International, IBM, Cisco Systems, Siemens, Ericsson, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI for Public Security and Safety Market Emerging Trajectories
Multimodal AI architectures are consolidating previously separate detection workflows into unified platforms, compressing vendor margins while expanding addressable use cases for integrated public safety command centers.
Transformer-based video understanding is supplanting convolutional neural networks for crowd behavior analysis and abandoned object detection. Transit authorities in Singapore and Dubai deploy these models for real-time anomaly flagging in metro systems. The technology is compressing hardware requirements by enabling single-model inference across multiple detection tasks previously handled by specialized pipelines.
The EU AI Act's risk classification system mandates conformity assessments for high-risk biometric applications before market placement. Vendors must submit technical documentation proving accuracy thresholds and bias mitigation measures to notified bodies. Law enforcement procurement in France and Italy now excludes systems lacking CE marking under the AI Act's conformity framework.
Subscription-based AI analytics are displacing perpetual license sales as municipal budgets favor operational expenditure models. State and local agencies in Texas, California, and Florida negotiate usage-based contracts for video processing capacity rather than purchasing on-premise software. This shift concentrates purchasing power with procurement officers who bundle AI services into broader smart city infrastructure agreements.
AI for Public Security and Safety Market Segmentation
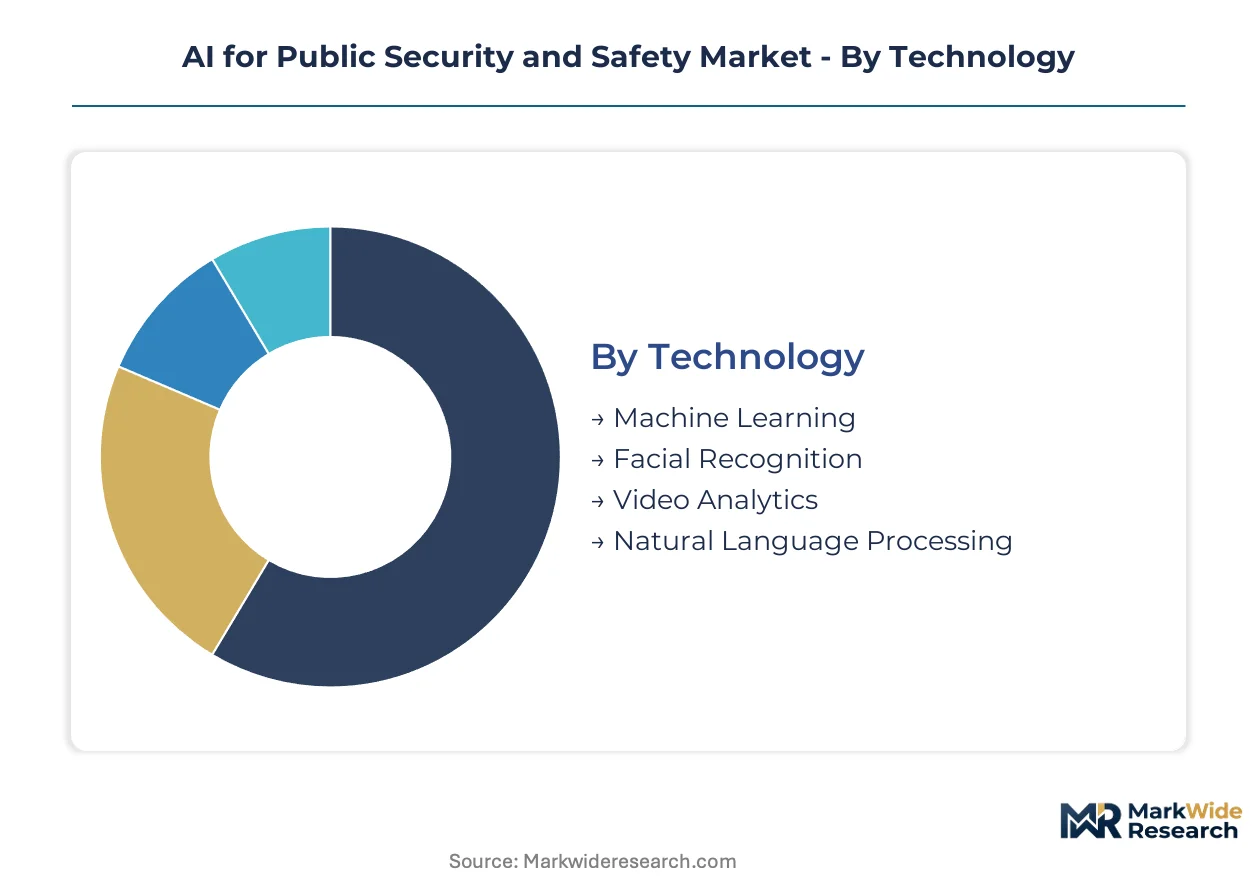
Segmentation in the AI for Public Security and Safety market reveals distinct procurement patterns across technology maturity tiers and agency budget cycles. Channel strategies diverge sharply between turnkey platform vendors serving federal clients and modular component suppliers addressing municipal IT departments.
Technology:
Channel distribution varies by computational intensity—cloud APIs dominate NLP deployments while edge hardware prevails for video analytics in bandwidth-constrained environments.
- Video Analytics:Computer vision pipelines process multi-camera feeds for crowd density estimation and abandoned object detection. Transit authorities in Singapore and Dubai deploy these systems for real-time anomaly flagging in metro environments. Maturity in convolutional and transformer architectures compresses hardware requirements through unified inference models.
- Machine Learning:Predictive algorithms forecast incident hotspots from historical crime data fused with environmental sensor streams. Law enforcement agencies in the United States accelerate procurement of these platforms through federal homeland security grant funding.
- Facial Recognition:Biometric matching systems face structural channel constraints as EU AI Act prohibitions force vendor reengineering for compliance documentation.
- Natural Language Processing:Emergency call triage engines extract location and severity signals from distressed caller speech patterns.
Video Analytics dominates installed base. Machine Learning is where expansion concentrates.
End User:
Budget authority and data classification requirements shape procurement channel selection across agency types.
- Law Enforcement:Municipal police departments and sheriff offices deploy predictive policing platforms and real-time crime center dashboards. Federal grants in the United States fund large-scale AI-powered video analytics networks through dedicated smart city infrastructure streams.
- Homeland Security:National agencies mandate human-in-the-loop decision protocols with auditable operator override functions for threat detection workflows. Premium positioning accrues to vendors satisfying these governance frameworks.
- Emergency Services:Dispatch centers integrate AI-generated alerts with legacy computer-aided dispatch systems through expensive middleware development.
- Fire Departments:Incident command systems leverage geospatial intelligence for resource deployment optimization during multi-alarm events.
Law Enforcement commands the deepest installed base. Homeland Security offers the steepest expansion trajectory.
Solution:
Margin structure inverts between preemptive intervention systems and post-incident analysis tools.
- Threat Detection:Perimeter monitoring and anomaly identification systems command premium positioning as energy and transportation operators in Germany and France adopt these solutions to satisfy national security directives. Real-time inference requirements drive edge deployment architectures.
- Surveillance Systems:Integrated camera networks with AI-enabled video processing form the backbone of municipal smart city infrastructure. Subscription-based analytics displace perpetual licenses as operational expenditure models gain favor.
- Incident Response:Automated alert generation and dispatch coordination platforms require extensive middleware development for legacy system integration.
- Risk Assessment:Pre-operational planning tools evaluate vulnerability profiles for critical infrastructure protection.
Surveillance Systems anchor current revenue. Threat Detection captures the fastest margin expansion.
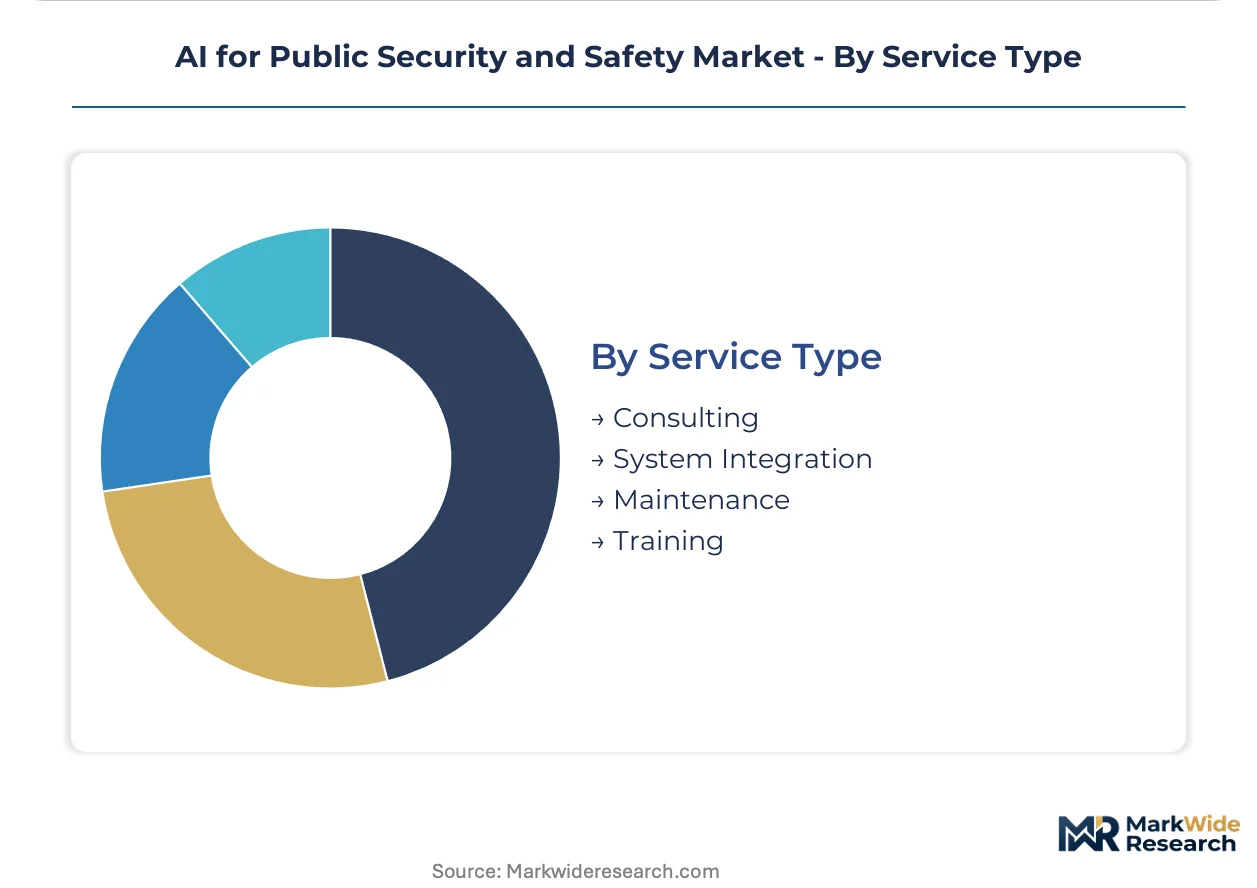
Service Type:
Revenue recurrence and customer lock-in intensity differentiate professional services from recurring support offerings.
- System Integration:Complex deployment of AI platforms with existing radio communications and dispatch infrastructure commands project-based fees. Motorola Solutions leverages deep integration capabilities to dominate public safety command center implementations.
- Maintenance:Ongoing model retraining and algorithmic bias auditing generate recurring revenue streams as GDPR and EU AI Act mandates extend validation cycles.
- Consulting:Workflow redesign and change management services accompany initial platform adoption.
- Training:Operator certification programs address capability gaps in adversarial machine learning red-teaming and human-in-the-loop protocol execution.
System Integration represents the largest project value. Maintenance delivers the most predictable recurring streams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where federal homeland security grants fund premium AI deployments, while European vendors absorb compliance cost premiums from the EU AI Act's biometric surveillance prohibitions.
United States
Municipal police departments in Texas, California, and Florida accelerate procurement of predictive policing platforms through dedicated smart city infrastructure funding streams. The Department of Homeland Security's AI governance framework mandates human-in-the-loop decision protocols with auditable operator override functions. Chicago and New York City operate real-time crime centers that fuse AI-powered video analytics with legacy computer-aided dispatch systems.
Germany
Energy and transportation operators adopt threat detection AI to satisfy national security directives for perimeter monitoring and anomaly identification. The EU AI Act's conformity assessment requirements extend validation cycles for biometric system vendors seeking CE marking. Berlin and Munich anchor development of edge AI architectures for sovereign cloud contracts serving defense and intelligence clients.
France
Law enforcement procurement now excludes facial recognition systems lacking CE marking under the AI Act's high-risk application framework. CNIL enforcement of GDPR algorithmic accountability rules inflates compliance documentation requirements. The Paris metropolitan region hosts integrated command centers combining video analytics with emergency response dispatch systems.
India
Municipal corporations in Mumbai, Delhi, and Bangalore issue tenders for integrated command centers that fuse video analytics with emergency response infrastructure. The Smart City Mission funds AI-powered surveillance networks through centralized government allocation mechanisms. Hyderabad and Chennai develop local vendor ecosystems for computer vision model training and edge hardware deployment.
Singapore
Transit authorities deploy transformer-based video understanding models for real-time anomaly flagging in metro systems. The national AI governance framework emphasizes explainable decision protocols for public sector procurement. The city-state functions as a regional demonstration hub for multimodal AI architectures consolidating detection workflows into unified platforms.
AI for Public Security and Safety Market Vendor Landscape
Concentration sits with full-stack platform providers that integrate radio communications, video analytics, and command center software into unified offerings. The vendor base stratifies between turnkey system integrators serving federal clients and modular component suppliers addressing municipal IT departments. Two strategic archetypes dominate: communications-heritage conglomerates with deep public safety relationships, and geospatial intelligence specialists with advanced incident prediction capabilities. Competitive moves center on middleware development for legacy CAD integration and subscription-based pricing models displacing perpetual licenses.
Within the communications-heritage tier, Motorola Solutions leverages deep radio infrastructure relationships to anchor public safety command center implementations. Hexagon AB occupies a position exemplifying geospatial intelligence fusion with real-time prediction algorithms. IBM represents the enterprise AI platform archetype extending cloud-based threat detection workflows into homeland security client environments.
| Leading Market Players |
|---|
| Motorola Solutions |
| Hexagon AB |
| Atos SE |
| Honeywell International |
| IBM |
| Cisco Systems |
| Siemens |
| Ericsson |
| Thales Group |
| Others |
Supply Flow & Price Mechanics
Ninety-day lead times for NVIDIA H100 GPU clusters concentrate pricing power with foundry-direct buyers while compressing margins for second-tier vendors dependent on spot-market procurement. This inventory scarcity dynamic shapes procurement hierarchies across the AI for Public Security and Safety landscape, where sovereign cloud contracts and federal grant-funded deployments command allocation priority over municipal IT budgets.
Pricing Analysis
The customization-premium spread between configured-to-order threat detection platforms and standard video analytics subscriptions runs three-to-one in project value. SaaS-tiered pricing dominates municipal procurement in Texas, California, and Florida, where agencies negotiate usage-based contracts for processing capacity rather than perpetual licenses. Price differentiation hinges on EU AI Act compliance documentation and human-in-the-loop certification tiers. Cost compression in facial recognition systems is intensifying because vendors must absorb reengineering expenses for biometric architecture modifications. Federal homeland security clients exhibit lowest price sensitivity; small municipal police departments in India and Southeast Asia face acute budget constraints.
Supply Chain Analysis
Taiwan and South Korea anchor GPU and advanced semiconductor fabrication for training workloads, while China dominates edge inference chip assembly and camera sensor manufacturing. The supply chain draws from NVIDIA and AMD datacenter processors, Sony and ON Semiconductor image sensors, and 5G network equipment from Ericsson and Nokia. Single-source vulnerability concentrates in NVIDIA's foundry relationships, where capacity allocation favors hyperscale cloud providers over public safety specialists. Distribution runs through systems integrators like Motorola Solutions and Hexagon AB for federal command center deployments, with direct OEM relationships serving municipal smart city tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where multimodal AI consolidation and 5G network slicing interoperability are collapsing previously separate detection workflows into unified command center architectures.
For Market Incumbents: Compound defensive positioning by deepening integration of radio communications infrastructure with transformer-based video analytics, while accelerating middleware development for legacy CAD system connectivity. The threat of modular AI component suppliers disaggregating full-stack platforms demands certification investment in EU AI Act conformity assessment capabilities. Vertical integration into edge hardware production secures supply allocation priority during foundry capacity constraints.
For New Entrants and Emerging Players: Anchor in India's Smart City Mission tenders for integrated command centers in Mumbai, Delhi, and Bangalore, where local vendor ecosystems remain underdeveloped for computer vision model training. The most penetrable white space sits in federated learning architectures for defense and intelligence sovereign cloud contracts. A go-to-market angle through human-in-the-loop certification consulting bypasses capital-intensive hardware competition.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because jurisdictional divergence between EU AI Act prohibitions and US federal grant permissiveness creates persistent margin premiums for dual-compliance-capable vendors. Acquisition targets should display geospatial intelligence fusion capabilities and established homeland security relationships. The signal to watch is CE marking approval velocity for high-risk biometric applications as a proxy for European market access competitiveness.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies video analytics, radio communications, and CAD systems into single command center architecture. |
| EU AI Act Compliance Investment | Secures CE marking eligibility for biometric systems in French and Italian law enforcement procurement. |
| Edge AI Hardware Development | Reduces dependency on NVIDIA foundry allocation through sovereign inference chip production. |
| Subscription Model Transition | Aligns revenue recurrence with municipal budget preference for operational expenditure over capital. |
| Middleware Development | Enables AI-generated alert integration with 1990s-era computer-aided dispatch infrastructure. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC filings, EU AI Act technical documentation, and homeland security grant allocation databases. Primary interviews engaged public safety command center directors, municipal IT procurement officers, and AI platform engineering leads across the United States, Germany, France, India, and Singapore. Secondary validation drew from notified body conformity assessment records, smart city tender documentation, and hyperscaler capex disclosures. Bottom-up deployment sizing triangulates against top-down federal budget appropriation analysis.
Segmentation dimensions modeled span technology tier, end-user agency classification, solution type, and service delivery model across the projection horizon. The analytical framework incorporates deployment architecture preferences, data classification requirements, and regulatory compliance cost structures as forecast sensitivity inputs. CAGRs derive from installation base expansion rates and average contract value trajectories by buyer segment.
Material uncertainties — GPU supply allocation shocks, EU AI Act enforcement variance, and municipal budget cycle disruptions — sit outside the modeled envelope. Forecasts reflect assumptions regarding federal grant continuity and biometric prohibition scope stability. Recalibration cycles align with material shifts in foundry capacity expansion and transatlantic regulatory harmonization progress.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Safety
Public Safety Market
Public Safety
US Mass Notification Systems Market
Public Safety
Global IoT for Public Safety Market
Public Safety
Global Public Safety and Security Market
Public Safety
Voice Evacuation Systems Market
Public Safety
Europe Public Safety Market
Public Safety
Outdoor Public Safety Market
Public Safety
Global Public Safety Analytics Market
Public Safety
Public Safety in-Building Wireless Distributed Antenna System (DAS) Market
Public Safety
Crowd Management System Market
Public Safety
Global Public Safety Solution Market
Public Safety
Europe Wireless Broadband in Public Safety Market
Public Safety
Crime Risk Report Market
Public Safety
North America Road Safety Market
Public Safety
Latin America Public Safety Market
Public Safety
Global Wireless Broadband in Public Safety Market