
 Asia-Pacific Public Safety Market | 2026-2036
Asia-Pacific Public Safety Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Public Safety Market Insights
Mission-critical reliability standards are redrawing competitive requirements across the Asia-Pacific Public Safety Market. Motorola Solutions dominates professional radio networks through backward integration into encrypted waveform development. NEC Corporation anchors large-scale biometric and video analytics deployments across Japan's municipal police forces. Cisco Systems leverages converged IP backbone architectures to sustain presence in multi-agency communication hubs.
Asia-Pacific public safety encompasses integrated systems for threat detection, emergency coordination, and critical infrastructure protection, typically operating on dedicated spectrum bands with sub-50-millisecond latency requirements and AES-256 encryption protocols. Surveillance systems lead product type revenue as cities replace analog CCTV with edge-computing cameras capable of on-device facial recognition. AI analytics represents the fastest-expanding technology segment, though cloud computing still captures the largest share of recurring service revenue. Government agencies remain the dominant end user, while healthcare facilities represent the fastest-growing buyer category as hospital emergency preparedness mandates tighten.
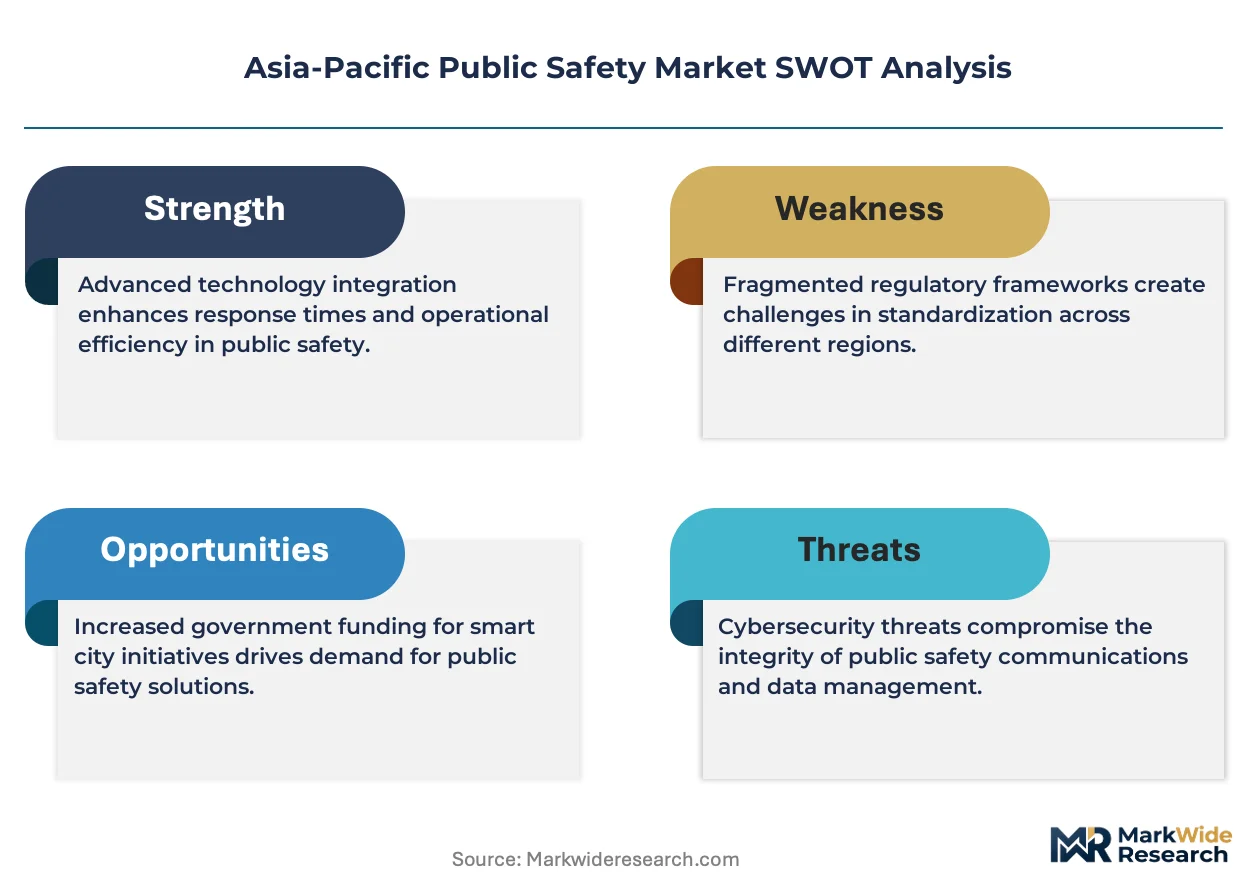
Japan's METI issues technical conformity standards for disaster-resilient communication equipment, while Australia's Critical Infrastructure Centre enforces mandatory reporting obligations across transport and energy assets. India's BIS certification requirements for electronic safety products create compliance barriers that favor established suppliers with testing laboratory partnerships. Stakeholders must weigh sovereign data localization rules against the operational efficiency of cross-border cloud architectures when structuring regional service delivery models.
Market Dynamics
AI-driven video analytics is compressing procurement cycles across Asia-Pacific public safety agencies, forcing legacy analog surveillance vendors to retool or exit as municipal buyers consolidate around integrated platforms with sub-50-millisecond latency requirements.
Growth Catalysts
- India's Smart Cities Mission:Municipal corporations in 100 designated cities are mandating unified command-and-control centers, creating bundled demand for surveillance, emergency response, and traffic management systems.
- Biometric identification systems:Facial recognition deployments at transport hubs and border crossings are accelerating hardware refresh cycles as agencies replace first-generation cameras with edge-computing devices.
- Australia's Critical Infrastructure Centre mandates:Mandatory reporting obligations across energy and transport assets are compelling private operators to upgrade monitoring systems and integrate with government emergency networks.
Market Restraints
- Semiconductor supply concentration:Dependence on Taiwanese and South Korean foundries for image sensors and AI accelerators creates vulnerability to geopolitical disruption and allocation rationing.
- BIS certification timelines:India's Bureau of Indian Standards testing requirements for electronic safety products extend vendor qualification periods by 8-14 months, freezing out suppliers without established laboratory partnerships.
- Optical fiber deployment costs:Last-mile connectivity to remote provincial command centers requires capital-intensive trenching, particularly across Indonesia's archipelago and Australia's interior.
Strategic Opportunities
- Vietnam's provincial security modernization:Public security bureaus in secondary cities remain underpenetrated by integrated platforms, presenting first-mover advantages for vendors with localized technical support.
- Healthcare emergency preparedness:Hospital accreditation standards are tightening across Japan, South Korea, and Australia, opening demand for mass-casualty communication systems and patient tracking technologies.
- Convergence of 5G private networks and drone surveillance:First-responder agencies are piloting beyond-visual-line-of-sight operations using dedicated spectrum slices, creating bundled hardware-software-service contracts.
Industry Challenges
- Legacy radio network integration:Provincial agencies operate heterogeneous equipment from multiple decades, complicating migration to encrypted LTE-based systems without service interruption.
- Cybersecurity workforce scarcity:Shortages of cleared personnel with both operational technology and information security expertise delay deployment of zero-trust architectures across multi-agency hubs.
- Sovereign data localization compliance:Cross-border cloud service delivery requires jurisdictional data segmentation that fragments operational efficiency and multiplies infrastructure costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Public Safety Market |
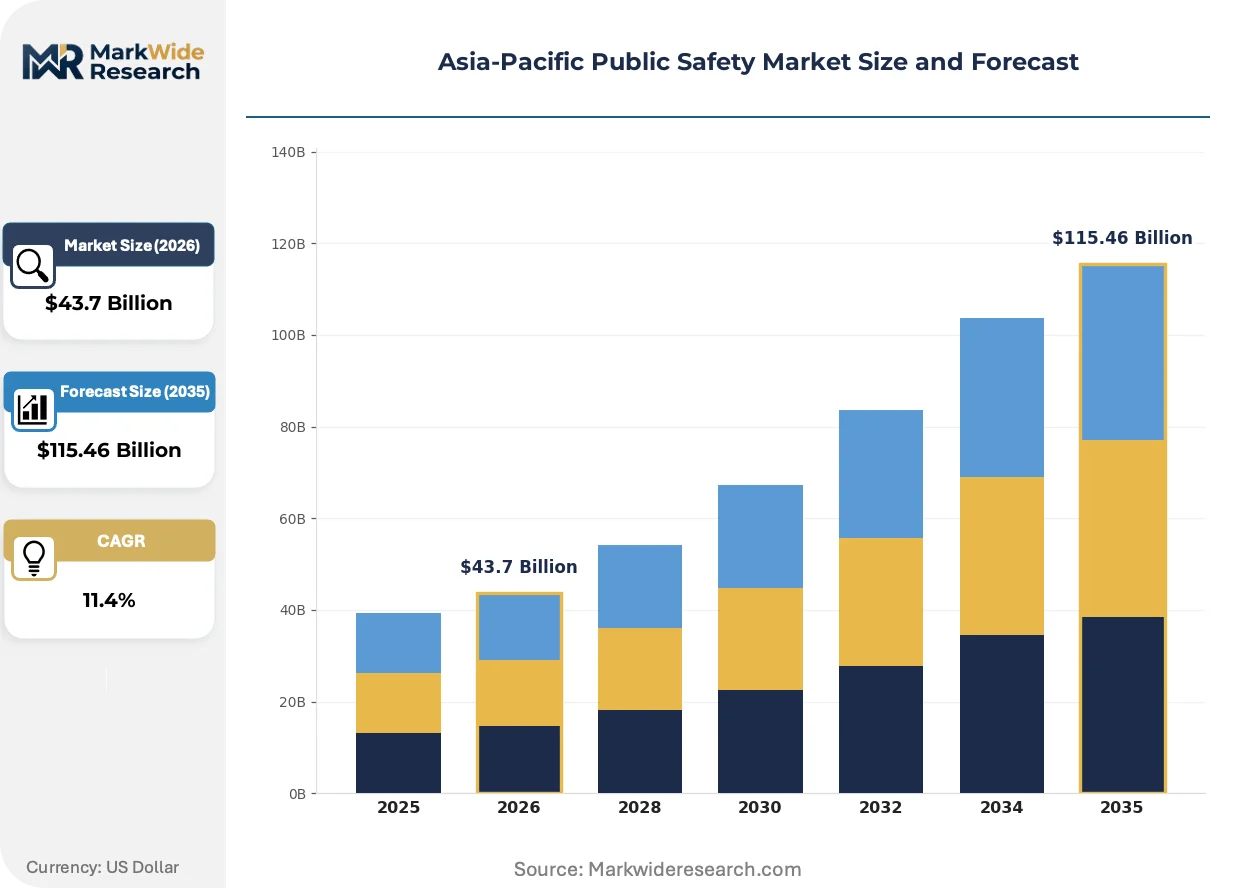
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $115.46 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surveillance Systems, Emergency Response Solutions, Communication Equipment, Access Control Systems Technology: AI Analytics, Cloud Computing, IoT Devices, Video Analytics End User: Government Agencies, Healthcare Facilities, Educational Institutions, Transportation Services Solution: Incident Management, Crowd Control, Fire Safety, Disaster Recovery |
| Companies Covered | Motorola Solutions, Cisco Systems, Hexagon AB, NEC Corporation, Honeywell International, Siemens, IBM, Ericsson, Atos SE, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Public Safety Market Trends and Innovations
Edge-computing surveillance cameras with on-device facial recognition are redrawing procurement specifications across Asia-Pacific municipal police forces. Three interconnected developments are compressing technology refresh cycles and reshaping vendor competitive requirements.
Edge AI processors embedded directly within surveillance cameras are displacing centralized server-based analytics architectures that dominated the previous decade. Provincial public security bureaus in China and municipal police forces in Japan are specifying on-device inference capabilities as mandatory in new tenders. This hardware shift is compressing margins for pure-software analytics vendors unable to secure silicon partnerships.
Australia's Critical Infrastructure Centre has expanded mandatory reporting obligations to encompass data storage and communication systems across transport and energy assets. Industrial consequence includes accelerated procurement of redundant communication backbones and hardened network equipment. Transport operators in Queensland and Western Australia are responding by consolidating vendor relationships to reduce compliance documentation burden.
Hospital emergency preparedness mandates are unbundling traditional equipment procurement into integrated service contracts spanning training, maintenance, and scenario-based certification. Healthcare facilities in Japan and South Korea are displacing capital-purchase models with multi-year operational agreements. This pattern is most visible in tertiary hospital networks where accreditation audits now evaluate response-time performance rather than equipment inventory alone.
Asia-Pacific Public Safety Market Segmentation
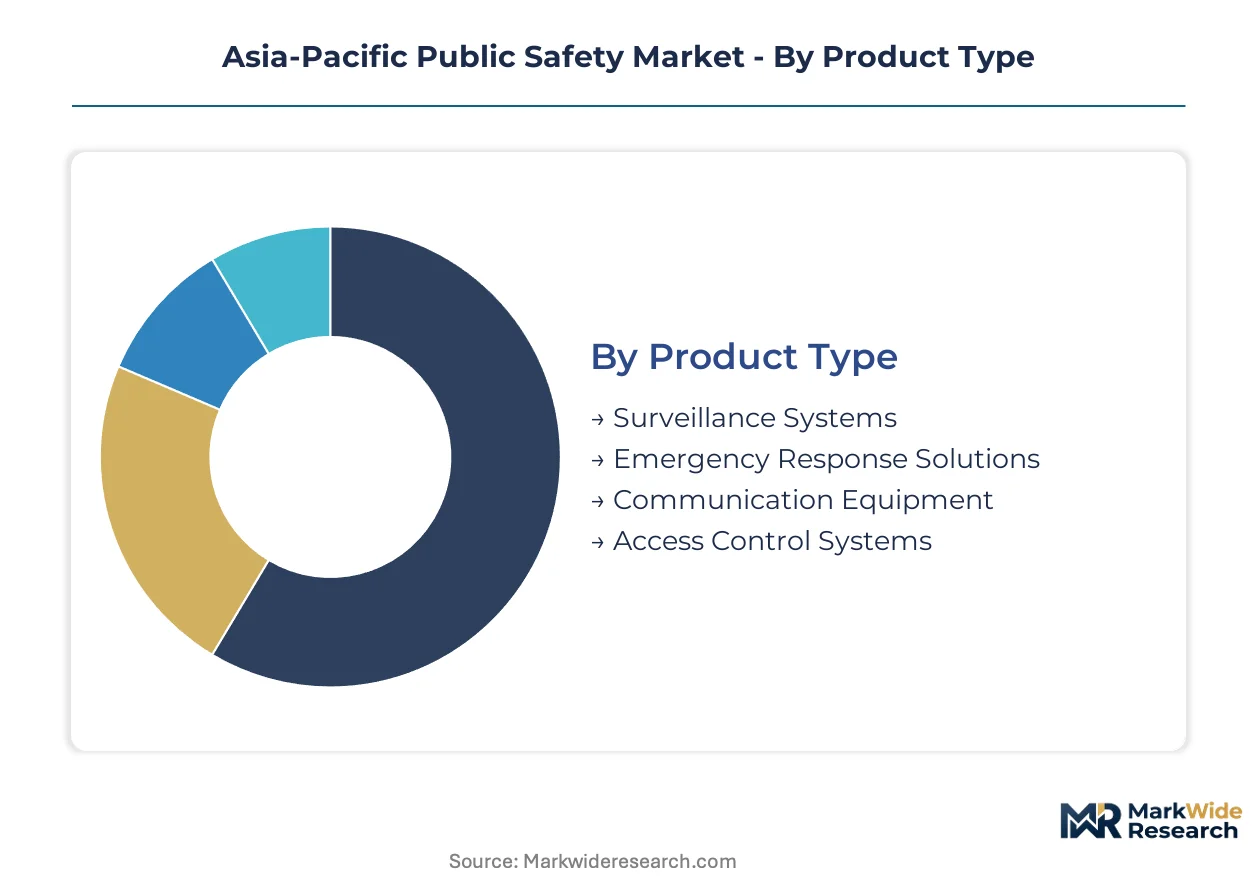
Public safety procurement in Asia-Pacific follows distinct channel patterns across product types, with government tenders dominating capital-intensive systems while healthcare and education sectors increasingly favor subscription-based service models. Segmentation reveals how technology maturity and regulatory pressure reshape buying behaviors across municipal, institutional, and private operator categories.
Product Type:
Surveillance systems flow primarily through systems integrators holding national security clearances, while emergency response equipment channels through specialized distributors with field service capabilities. Communication hardware increasingly routes via telecom operators bundling spectrum access with device procurement.
- Surveillance Systems:Edge-computing cameras with on-device AI inference are displacing centralized server architectures across provincial public security bureaus in China and municipal police forces in Japan. Procurement concentrates in smart city command centers in Seoul and Singapore as integrated platform mandates consolidate vendor relationships.
- Emergency Response Solutions:Unified command-and-control platforms bundle dispatch software, mobile data terminals, and geospatial mapping into single-vendor contracts. India's Smart Cities Mission is accelerating demand across 100 designated cities as municipal corporations mandate interoperable systems.
- Communication Equipment:Encrypted LTE-based systems and professional radio networks serve first-responder agencies requiring sub-50-millisecond latency.
- Access Control Systems:Biometric readers and credential management platforms secure critical infrastructure across transport and energy assets.
By volume, Surveillance Systems leads procurement activity. By growth pace, Emergency Response Solutions is expanding most quickly as platform consolidation accelerates.
Technology:
Technology adoption curves diverge sharply by customer sophistication, with AI analytics commanding premium pricing from government agencies while cloud computing penetrates healthcare and education through operational expenditure models. IoT sensors and video analytics occupy intermediate positions with mixed deployment patterns.
- AI Analytics:Facial recognition algorithms and predictive threat modeling run on edge processors or centralized GPU clusters depending on latency requirements. China's provincial security bureaus are modernizing video analytics capabilities as AI-driven crowd management becomes mandatory in tender specifications.
- Cloud Computing:Multi-tenant platforms for evidence management and cross-agency data sharing generate recurring service revenue. Sovereign data localization rules in India and Australia are fragmenting operational efficiency and multiplying infrastructure costs for regional service delivery.
- IoT Devices:Environmental sensors, wearable panic buttons, and connected vehicle modules extend situational awareness networks.
- Video Analytics:Behavioral recognition and anomaly detection software layers onto existing camera infrastructure.
By volume, Cloud Computing captures the largest share of recurring service revenue. By growth pace, AI Analytics is gaining share fastest as edge-computing hardware refresh cycles compress.
End User:
End-user segmentation reflects divergent procurement authority structures, with central government agencies controlling capital budgets for national systems while healthcare facilities and educational institutions exercise localized purchasing for facility-specific solutions. Transportation operators occupy a hybrid position with both federal oversight and operational autonomy.
- Government Agencies:National police forces, border control authorities, and municipal public safety departments specify mission-critical reliability standards with AES-256 encryption protocols. Australia's Critical Infrastructure Centre mandates are compelling private operators to upgrade monitoring systems and integrate with government emergency networks.
- Healthcare Facilities:Hospital accreditation standards across Japan, South Korea, and Australia are tightening emergency preparedness requirements. Mass-casualty communication systems and patient tracking technologies are displacing capital-purchase models with multi-year operational agreements.
- Educational Institutions:Campus security departments procure access control and emergency notification systems.
- Transportation Services:Airport authorities, rail operators, and port managers deploy integrated threat detection and passenger screening systems.
By volume, Government Agencies dominate absolute spending. By growth pace, Healthcare Facilities is climbing the fastest as accreditation audits evaluate response-time performance.
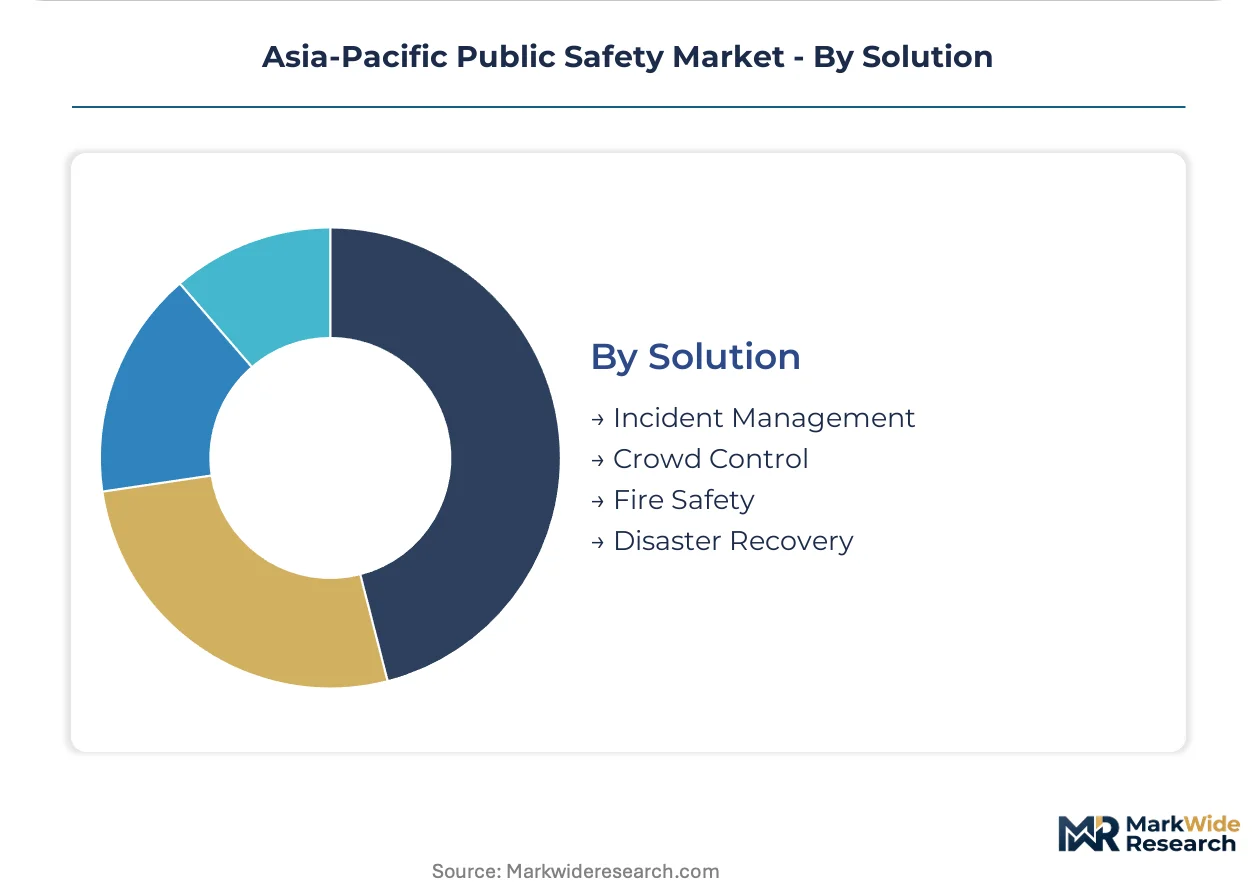
Solution:
Solution-oriented procurement is unbundling traditional equipment sales into integrated service contracts spanning training, maintenance, and scenario-based certification. Incident management platforms anchor the largest contract values while fire safety and disaster recovery solutions follow regulatory compliance timelines.
- Incident Management:Real-time coordination platforms integrate dispatch, resource tracking, and inter-agency communication into unified workflows. Smart city command centers in Seoul and Singapore are expanding procurement of integrated surveillance and emergency response platforms.
- Crowd Control:AI-driven density monitoring and automated flow optimization systems deploy at transport hubs and public gatherings. Edge-computing cameras with on-device facial recognition are redrawing procurement specifications across Asia-Pacific municipal police forces.
- Fire Safety:Detection, suppression, and evacuation systems comply with national building codes.
- Disaster Recovery:Communication restoration and continuity planning services address seismic and climate risks.
By volume, Incident Management leads contract values. By growth pace, Crowd Control is expanding most quickly as biometric identification deployments accelerate hardware refresh cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwanese and South Korean foundries concentrate supply of image sensors and AI accelerators for public safety systems, creating geographic vulnerability that shapes procurement contingency planning across the region.
China
Provincial public security bureaus drive demand for edge-computing cameras with on-device facial recognition capabilities. MIIT issues technical standards for encrypted communication equipment used in smart city deployments. Command centers in Beijing and Shanghai are consolidating vendor relationships around integrated surveillance and emergency response platforms.
Japan
Municipal police forces specify mission-critical reliability standards with sub-50-millisecond latency requirements for emergency coordination systems. METI issues technical conformity standards for disaster-resilient communication equipment. Tokyo and Osaka metropolitan police departments anchor large-scale biometric and video analytics deployments.
India
Municipal corporations in 100 designated smart cities mandate unified command-and-control centers creating bundled demand for surveillance and traffic management systems. BIS certification requirements for electronic safety products extend vendor qualification periods significantly. Delhi-NCR and Mumbai lead procurement of integrated emergency response platforms.
Australia
Private operators across energy and transport assets face mandatory reporting obligations compelling upgrades to monitoring systems and government network integration. The Critical Infrastructure Centre enforces compliance timelines for data storage and communication systems. Queensland and Western Australia transport operators are consolidating vendor relationships to reduce documentation burden.
South Korea
Hospital accreditation standards tighten emergency preparedness requirements opening demand for mass-casualty communication systems. The national regulator enforces certification protocols for medical safety equipment. Seoul metropolitan command centers expand procurement of AI-driven crowd management capabilities.
Asia-Pacific Public Safety Market Competitive Landscape
Concentration sits with diversified technology conglomerates and specialized professional communications providers. The vendor base separates into three strategic archetypes: encrypted radio network specialists, converged IP backbone architects, and integrated platform consolidators. Dominant competitive moves include backward integration into waveform development and geographic expansion through localized technical support partnerships.
Among diversified technology providers, Cisco Systems exemplifies the converged IP backbone architect archetype while NEC Corporation occupies a position within the biometric and video analytics specialist tier. Motorola Solutions represents the encrypted professional radio network archetype. These three anchors illustrate how competitive positioning depends on spectrum access, security clearance relationships, and silicon partnerships rather than scale alone.
| Leading Market Players |
|---|
| Motorola Solutions |
| Cisco Systems |
| Hexagon AB |
| NEC Corporation |
| Honeywell International |
| Siemens |
| IBM |
| Ericsson |
| Atos SE |
| Others |
Pricing and Supply Chain Analysis
Edge AI processor substitution for centralized server architectures is simultaneously shifting procurement geography toward Taiwanese and South Korean foundries and compressing margins for pure-software vendors unable to secure silicon partnerships. This hardware-software bundling dynamic concentrates pricing power with integrated platform providers while fragmenting cost structures across legacy analog surveillance vendors facing exit pressures.
Pricing Analysis
BIS certification requirements dictate the pricing tier structure across India's public safety procurement, separating established suppliers with laboratory partnerships from frozen-out competitors facing 8-14 month qualification delays. Three-tier pricing stratifies across mission-critical encrypted systems, standard municipal surveillance packages, and economy-grade analog replacement hardware. Cost compression in the economy tier is intensifying as provincial buyers in Vietnam and Indonesia consolidate vendor relationships around bundled service contracts. Healthcare facilities exhibit the lowest price sensitivity due to accreditation-driven performance mandates, while secondary city municipalities in Southeast Asia remain highly cost-conscious.
Supply Chain Analysis
Port congestion along the Shanghai-Singapore corridor and container availability constraints on intra-Asia trade lanes are elevating inbound logistics costs for edge-computing camera assemblies. Supply concentrates in Taiwan for image sensors, South Korea for AI accelerators, and China for finished hardware integration. Component dependencies rest on CMOS sensors, neural processing units, and hardened encryption chipsets. Single-source vulnerability in Taiwanese foundry capacity creates exposure to geopolitical disruption. Distribution runs through national systems integrators holding security clearances rather than open-channel distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific public safety market functions as a service-attach opportunity where multi-year operational agreements for training, maintenance, and scenario-based certification are expanding faster than underlying hardware procurement. This recurring-revenue layer now anchors vendor profitability as hospital accreditation standards and smart city mandates displace capital-purchase models.
For Market Incumbents: Fortify encrypted waveform development capabilities through backward integration into silicon partnerships, defending against pure-software analytics vendors retooling around edge-computing hardware. Secure BIS laboratory partnerships in India and METI conformity certification pathways in Japan to extend qualification moats. Channel control through national systems integrator relationships represents the critical defensive lever against emerging platform consolidators. For New Entrants and Emerging Players: Differentiate on localized technical support capabilities targeting Vietnam's provincial security bureaus and Indonesia's underpenetrated secondary cities where first-mover advantages remain available. Healthcare emergency preparedness mandates across Japan, South Korea, and Australia present the most penetrable segment for mass-casualty communication systems. A direct service-contract go-to-market model bypasses capital-budget procurement cycles that favor established vendors. For Investors and Strategic Acquirers: The market sits at a platform-consolidation phase that favors integrated hardware-software-service providers with sovereign data localization compliance capabilities. Long-term viability hinges on 5G private network and drone surveillance convergence plays requiring dedicated spectrum access. Acquisition targets should display biometric-video analytics integration depth and existing security clearance relationships. The signal to watch is tightening hospital accreditation standards accelerating operational expenditure model adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Waveform Development | Motorola Solutions secures encrypted radio differentiation through captive AES-256 protocol control. |
| Platform Integration of AI Analytics | NEC Corporation anchors municipal police deployments through edge-computing camera partnerships. |
| Geographic Expansion via Localized Support | Cisco Systems sustains multi-agency hub presence through converged IP backbone architectures. |
| Service Contract Unbundling | Healthcare facilities displace capital purchases with multi-year operational agreements spanning training. |
| 5G Private Network Deployment | First-responder agencies pilot beyond-visual-line-of-sight drone operations using dedicated spectrum slices. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with smart city procurement officers, public security bureau technology directors, hospital biomedical engineers, and systems integrator executives; and secondary validation against MIIT technical standards filings, BIS certification registries, METI conformity documentation, and Critical Infrastructure Centre compliance disclosures. Bottom-up triangulation across municipal tender databases and top-down reconciliation against national budget appropriations anchored volume estimates.
Across the projection horizon, the analytical framework modeled segmentation dimensions including product type, technology layer, end-user category, and solution orientation with particular attention to sovereign data localization compliance requirements. CAGRs were derived through trend extrapolation of procurement cycle compression and hardware refresh acceleration. Edge-computing adoption curves and 5G private network pilot expansions served as primary forecast inputs.
Material uncertainties — semiconductor allocation rationing, geopolitical disruption to Taiwanese foundry operations, and BIS certification timeline extensions — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding smart city mandate continuity and hospital accreditation standard tightening. Practitioners should keep alternative scenarios live as sovereign data localization rules and cross-border cloud service restrictions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Safety
AI for Public Security and Safety Market
Public Safety
Outdoor Public Safety Market
Public Safety
Voice Evacuation Systems Market
Public Safety
Global Public Safety and Security Market
Public Safety
US Mass Notification Systems Market
Public Safety
Europe Public Safety Market
Public Safety
Europe Public Infrastructure Safety Market
Public Safety
Europe Wireless Broadband in Public Safety Market
Public Safety
Counter Terror and Public Safety Technology Market
Public Safety
Crowd Management System Market
Public Safety
Safe City Market
Public Safety
Latin America Public Safety Market
Public Safety
Global Wireless Broadband in Public Safety Market
Public Safety
Public Safety Market
Public Safety
Global Public Safety Solution for Smart City Market
Public Safety
North America Road Safety Market