
 Public Cloud Storage Services Market | 2026-2036
Public Cloud Storage Services Market Size, Share, and Industry Trends Forecast 2026-2036
Public Cloud Storage Services Market Analytics
Consumption-based leasing and asset-light infrastructure financing is reshaping competitive entry in public cloud storage, allowing specialized operators to scale capacity without balance-sheet heavy data center builds. CoreWeave leverages GPU-dense colocation partnerships to anchor its position in AI-training storage tiers. Microsoft Azure sustains enterprise trust through backward integration into productivity software channels. Amazon Web Services dominates hyperscale object storage with granular lifecycle policies that automate cost-tier migration.
Public cloud storage services deliver networked, multi-tenant data persistence with 99.999999999% durability SLAs, erasure-coded replication across availability zones, and API-driven access for unstructured workloads, file systems, and backup streams. The architecture eliminates capital-intensive on-premises array procurement while enabling elastic capacity expansion. Disaster recovery and backup services lead current revenue pools as enterprises retire tape-based schemes. Hybrid cloud deployments are expanding fastest where regulated workloads require on-premises encryption key custody alongside burst elasticity. File storage segments occupy premium margin tiers for media rendering and high-performance computing workflows.
GDPR data residency mandates, the EU AI Act training-data provenance rules, and SEC cybersecurity disclosure requirements for US-listed firms collectively tighten compliance architectures and elevate sovereign cloud demand. Providers must certify regional data boundaries and audit trails to maintain market access across jurisdictions. Stakeholders should monitor evolving cross-border transfer mechanism rulings and assess whether multi-cloud orchestration investments outpace single-vendor lock-in risks.
Market Dynamics
Sovereign data residency mandates are fragmenting hyperscaler architectures, forcing providers to deploy region-locked infrastructure that duplicates fixed costs across jurisdictions while compressing cross-border data fluidity.
Growth Catalysts
- EU AI Act training-data provenance requirements:Compliance obligations are compelling enterprises to migrate AI workloads to certified cloud environments with auditable lineage chains, expanding demand for compliant storage tiers.
- Healthcare imaging archive offloading:Hospital systems are retiring on-premises PACS infrastructure in favor of cloud-native object storage with automated lifecycle policies for DICOM datasets.
- German industrial IoT telemetry lakes:Automotive and manufacturing conglomerates require sub-20ms latency object storage for real-time equipment monitoring, driving edge-deployed capacity expansion.
Market Restraints
- Cross-border data transfer uncertainty:Schrems II rulings and evolving adequacy decisions are freezing multi-region architecture investments as legal teams assess Standard Contractual Clause viability.
- Energy input cost volatility:Data center power purchase agreements face repricing pressure from grid instability, directly inflating per-gigabyte operational costs for providers.
- Hyperscaler supply concentration:Three providers control the majority of object storage API standards, creating interoperability friction for multi-cloud orchestration tooling.
Strategic Opportunities
- India's data localization mandates:The country's central bank and telecom regulator are requiring domestic data residency for financial and subscriber records, opening greenfield capacity deployment.
- Confidential computing integration:Hardware-based trusted execution environments are converging with encrypted object storage to enable multi-tenant processing of regulated datasets without decryption exposure.
- FinOps-driven consumption models:Automated cost optimization platforms are emerging as a distribution channel, embedding storage procurement into cloud financial management workflows.
Industry Challenges
- Encryption key custody specialization:Enterprises demand hardware security module expertise that outpaces current certified talent pools, delaying hybrid deployment timelines.
- Legacy tape archive migration complexity:Petabyte-scale retrieval from magnetic media requires bespoke orchestration tooling that most IT organizations lack in-house.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Public Cloud Storage Services Market |
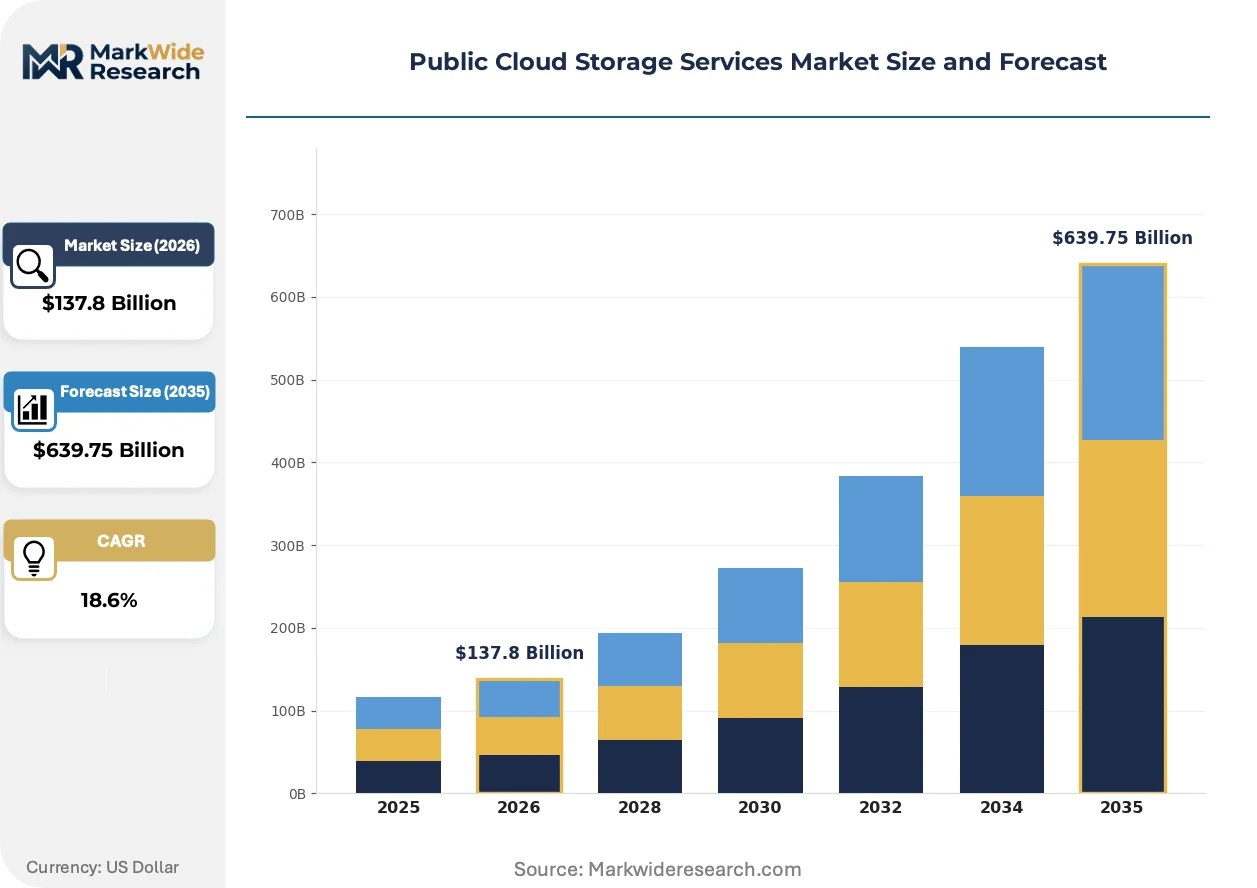
| Market Size in 2026 | $137.8 Billion |
| Market Size in 2035 | $639.75 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Backup Services, Archiving Services, Disaster Recovery, File Storage Deployment Model: Public Cloud, Hybrid Cloud, Managed Cloud, Multi-Cloud End User: SMEs, Large Enterprises, Government Agencies, Educational Institutions Storage Capacity: Small Scale, Medium Scale, Large Scale, Enterprise Level |
| Companies Covered | Amazon Web Services, Microsoft Azure, Google Cloud, Oracle Cloud Infrastructure, Alibaba Cloud, IBM Cloud, Salesforce, SAP, CoreWeave, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Public Cloud Storage Services Market Evolving Landscape
Computational storage architectures are dissolving the boundary between persistence and processing, enabling data-intensive workloads to execute directly on storage nodes rather than shuttling information across network fabrics.
Software-defined storage controllers are virtualizing the hardware abstraction layer between NVMe media and cloud orchestration APIs. Hyperscalers are deploying these controllers at rack scale to decouple capacity procurement from server refresh cycles. This architecture is virtualizing the traditional storage array vendor relationship, allowing cloud providers to source commodity flash directly from foundries.
GDPR Article 44 cross-border transfer mechanisms are tightening audit requirements for data exporters, with EU data protection authorities demanding enhanced technical safeguards beyond contractual clauses. Financial services and healthcare verticals are most affected, responding by contracting with regional cloud operators that maintain EU-only infrastructure footprints.
FinOps practices are embedding unit economics accountability into engineering teams, replacing centralized IT procurement with decentralized workload cost ownership. Channel relationships are shifting toward cloud cost management platforms that aggregate storage consumption across providers. This behavioral pivot is most visible in US technology and media enterprises with mature cloud-native operations.
Public Cloud Storage Services Market Segmentation
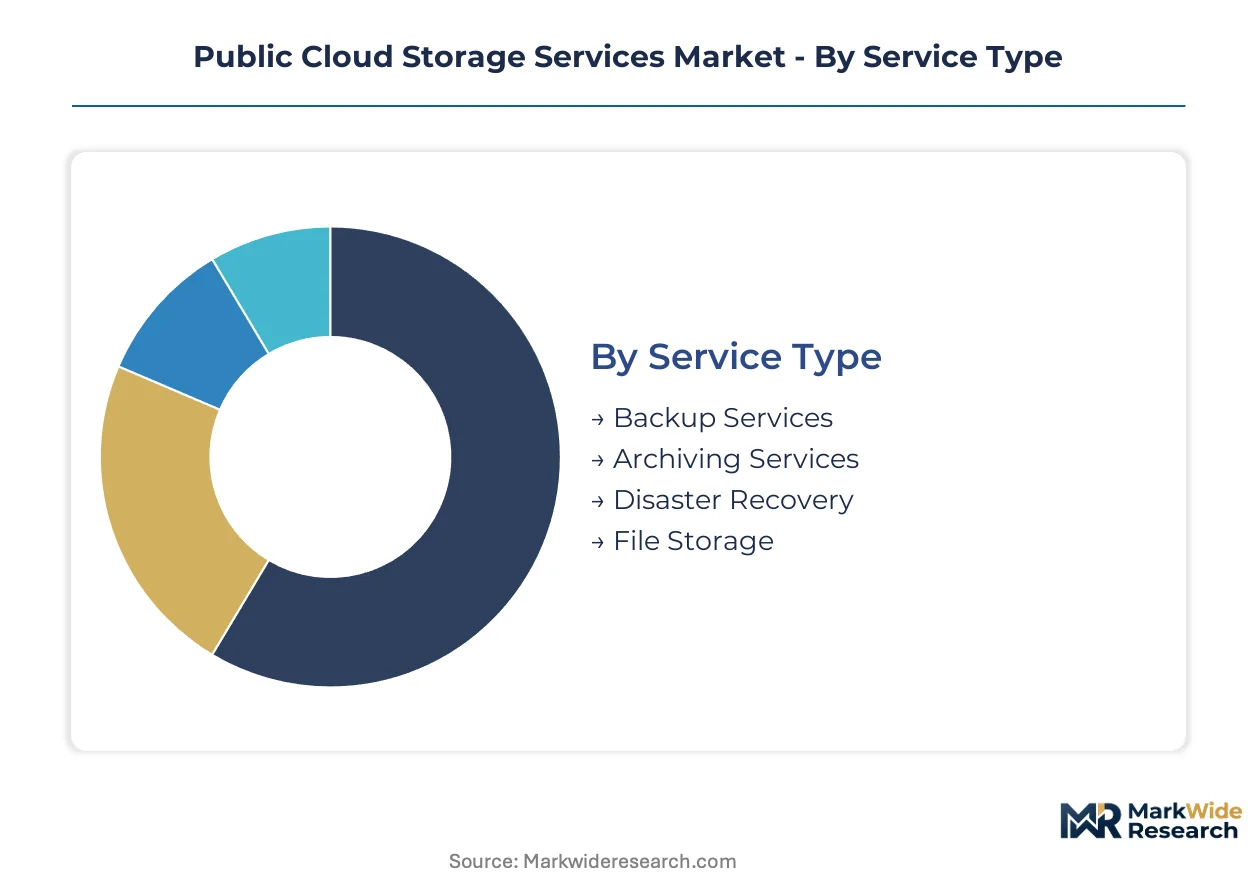
Public cloud storage services fragment across service architecture, deployment topology, customer scale, and capacity tiers. Each dimension carries distinct margin profiles, compliance obligations, and integration complexity that shape vendor positioning and procurement patterns.
Service Type:
After-sales service intensity varies sharply across service types, with archival and disaster recovery offerings demanding continuous data integrity verification and restoration testing protocols that backup-only providers rarely match.
- Backup Services:Automated snapshot orchestration with point-in-time recovery capabilities dominates enterprise adoption. Financial services firms in Frankfurt and Singapore drive demand for immutable backup vaults that satisfy SEC and Monetary Authority of Singapore retention mandates.
- Archiving Services:Cold-tier object storage with retrieval latency SLAs measured in hours. Healthcare networks in the US and Germany are migrating decades of DICOM imaging to glacier-equivalent tiers to retire on-premises tape libraries.
- Disaster Recovery:Cross-region replication with sub-15-minute RTO guarantees. Manufacturing conglomerates require this for production line continuity.
- File Storage:POSIX-compliant shared filesystems for media rendering and HPC workloads. Studios in Los Angeles and London concentrate demand here.
Backup services hold the largest share; momentum sits with archiving services.
Deployment Model:
Cost tier differentiation separates deployment models, with pure public cloud commanding the lowest per-gigabyte rates while hybrid and managed variants extract premiums for compliance certification and dedicated infrastructure.
- Public Cloud:Multi-tenant infrastructure with shared security boundaries and API-standardized access. Startups and digital-native enterprises dominate consumption, prioritizing elasticity over isolation.
- Hybrid Cloud:Split architecture keeping encrypted data on-premises while bursting compute to cloud tiers. German automotive suppliers and US defense contractors require this for ITAR and EU AI Act compliance.
- Managed Cloud:Dedicated single-tenant environments operated by third-party providers. Swiss banks and UAE sovereign wealth funds contract for these to satisfy national data residency laws.
- Multi-Cloud:Orchestration layers abstracting storage APIs across competing hyperscalers. Enterprises with vendor diversification mandates are expanding this fastest.
Public cloud retains volume leadership; hybrid deployments are climbing the fastest as regulated industries partition sensitive workloads.
End User:
Customer type determines contract structure, with government and educational sectors demanding fixed-price multi-year agreements that contrast with the consumption-based flexibility preferred by commercial enterprises.
- SMEs:Self-service portal procurement with pay-as-you-grow scaling. Regional software vendors and professional services firms in secondary cities concentrate here.
- Large Enterprises:Negotiated enterprise agreements with committed use discounts and dedicated support tiers. Fortune 500 manufacturers and telecom operators anchor this segment.
- Government Agencies:FedRAMP, IL5, and equivalent national certification requirements. US federal civilian agencies and UK Crown Commercial Service frameworks exemplify procurement patterns.
- Educational Institutions:Research data lakes and learning management system archives. University consortia in California and Bavaria drive collaborative storage contracting.
Large enterprises command the greatest revenue concentration; government agencies are gaining share fastest through sovereign cloud mandates.
Storage Capacity:
Volume thresholds align with infrastructure sophistication, with enterprise-level deployments requiring dedicated network fabrics and custom erasure coding schemes unavailable at smaller tiers.
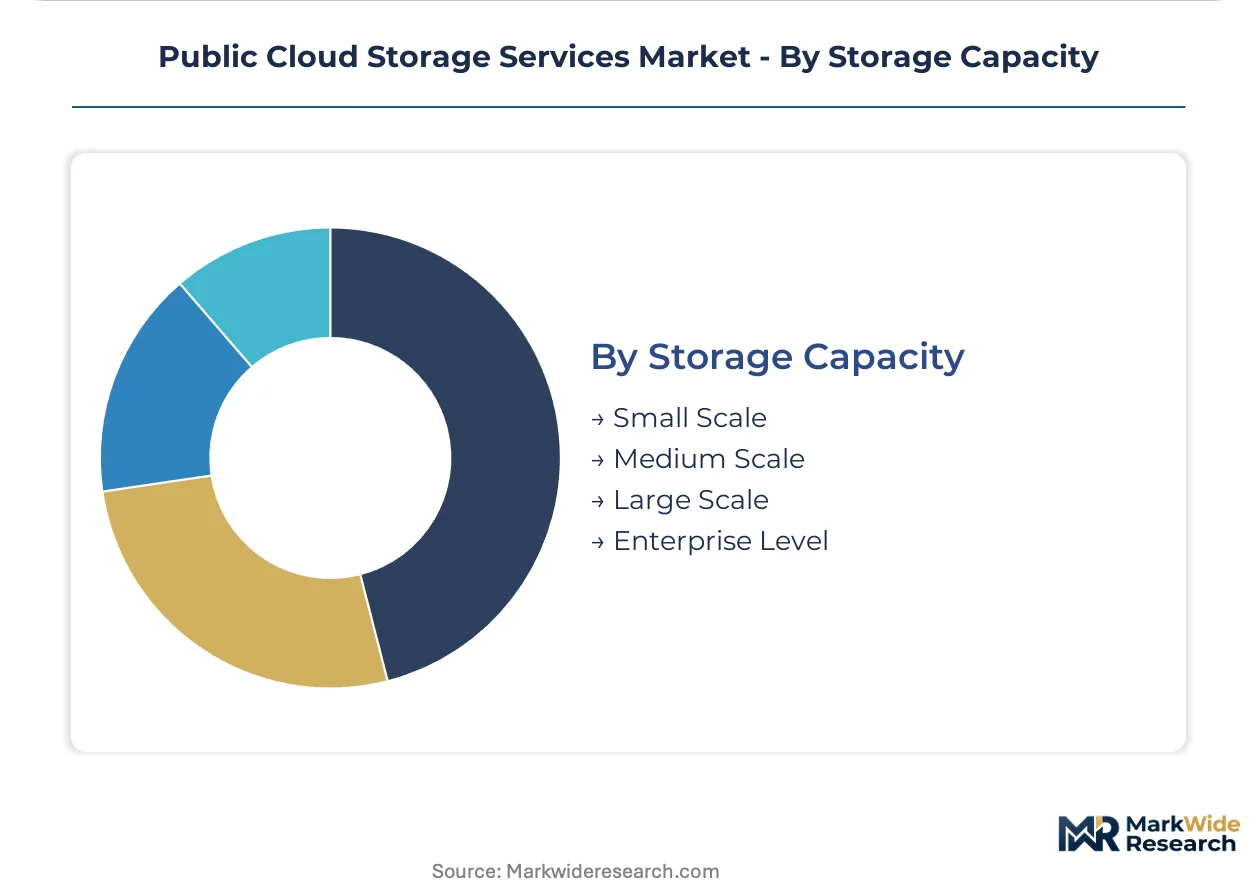
- Small Scale:Sub-100-terabyte deployments for departmental workloads and development environments. Boutique law firms and architectural practices typify users.
- Medium Scale:Petabyte-range repositories for mid-market SaaS providers and regional media distributors. These customers balance cost optimization against performance requirements.
- Large Scale:10-100 petabyte estates serving national retail chains and hospital networks. Latency-sensitive analytics and AI training datasets dominate use cases.
- Enterprise Level:Exabyte-scale infrastructure spanning multiple availability zones. Streaming platforms, genomics consortia, and national meteorological services operate at this tier.
Enterprise-level deployments generate the highest absolute revenue; medium-scale adoption is expanding most quickly as mid-market firms exit self-managed infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data sovereignty requirements are reshaping cross-border storage flows, with jurisdictions imposing residency mandates that fragment hyperscaler architectures. Export-restricted data categories now dominate procurement criteria in regulated economies, forcing providers to duplicate infrastructure across national boundaries.
United States
Financial services firms in New York and Chicago are driving demand for immutable backup vaults that satisfy SEC cybersecurity disclosure mandates. The federal FedRAMP certification framework governs procurement for civilian agencies, creating a two-tier compliance architecture. Silicon Valley hyperscalers anchor enterprise object storage consumption, while defense contractors in Virginia and Texas require ITAR-compliant air-gapped environments.
Germany
Automotive suppliers in Stuttgart and Munich require sub-20ms latency object storage for real-time equipment monitoring across factory floors. The EU AI Act training-data provenance rules compel enterprises to maintain auditable lineage chains for machine learning datasets. Industrial conglomerates in North Rhine-Westphalia are consolidating IoT telemetry lakes into sovereign-certified cloud tiers.
India
Domestic fintech platforms in Mumbai and Bangalore are scaling petabyte-range data lakes for credit risk modeling and payment fraud detection. The Reserve Bank of India's data localization directives mandate domestic residency for financial transaction records. Regional software vendors in Hyderabad and Pune are migrating from self-managed infrastructure to consumption-based storage leasing.
United Kingdom
Media production studios in London and Manchester concentrate demand for POSIX-compliant shared filesystems supporting 4K rendering pipelines. The UK Crown Commercial Service frameworks standardize procurement for government research data archives. University consortia in Cambridge and Edinburgh are contracting collaborative storage pools for genomics and climate modeling datasets.
Japan
Electronics manufacturers in Tokyo and Osaka are deploying edge-deployed capacity for semiconductor fabrication telemetry. METI's data governance guidelines encourage domestic cloud adoption for critical infrastructure operators. Automotive R&D centers in Nagoya require hybrid architectures that partition intellectual property on-premises while bursting compute to cloud tiers.
Public Cloud Storage Services Market Competitive Landscape
On the supply side, the industry is consolidating around three hyperscale operators that control API standards and pricing benchmarks, while specialized challengers carve out vertical niches through sovereign certification and workload-specific optimization. Strategic archetypes divide between full-stack hyperscalers with productivity software integration, GPU-dense specialists targeting AI training tiers, and regional sovereign operators with domestic-only infrastructure footprints. Dominant competitive moves center on multi-cloud orchestration partnerships and confidential computing integrations that enable processing of encrypted datasets.
Within the hyperscaler tier, Amazon Web Services, Microsoft Azure, and Google Cloud exemplify the scale-driven archetype through backward integration into enterprise software channels and granular lifecycle policy automation. Amazon Web Services anchors object storage consumption through eleven-nines durability SLAs and cross-availability zone replication architectures. Microsoft Azure occupies a position emphasizing enterprise trust through productivity suite integration. Google Cloud represents the analytics-optimized vector with native BigQuery connectivity for data lakehouse workloads.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft Azure |
| Google Cloud |
| Oracle Cloud Infrastructure |
| Alibaba Cloud |
| IBM Cloud |
| Salesforce |
| SAP |
| CoreWeave |
| Others |
Value Network & Pricing Analysis
Overcapacity in Northern Virginia data center clusters is compressing spot pricing for hyperscale object storage while forcing providers toward long-term reserved capacity commitments that lock in margin structures. This utilization imbalance simultaneously erodes pricing power for undifferentiated tiers and elevates premiums for sovereign-certified deployments where supply remains physically constrained.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across hot, warm, and cold storage tiers with retrieval latency SLAs as the primary differentiation driver. Price differentiation hinges on data durability certification levels and cross-region replication guarantees, with German automotive conglomerates least sensitive due to latency requirements while Indian fintech platforms exhibit acute price elasticity. Cost compression in cold archival tiers is intensifying because hyperscalers are automating lifecycle policies that migrate data to glacier-equivalent storage without manual intervention.
Supply Chain Analysis
Contract manufacturing concentration rests with Foxconn, Quanta, and Wistron for server assembly anchoring flash storage integration into hyperscale racks. Geographic supply concentration centers on Taiwan for advanced NAND foundry output, South Korea for DRAM-dependent caching tiers, and Malaysia for passive component integration. Raw material dependencies include neon gas for lithography, cobalt for controller chips, and rare earth elements for power supply units. Single-source vulnerability in EUV lithography equipment feeds from ASML's monopoly position. Distribution runs through direct hyperscaler procurement teams bypassing traditional channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection is materializing as API standardization fragments and multi-cloud orchestration layers disintermediate single-vendor lock-in. The interoperability shift toward S3-compatible object storage protocols is eroding proprietary format premiums.
For Market Incumbents: Entrench sovereign certification moats by accelerating EU AI Act compliance investments and deploying region-locked infrastructure in Germany and India before regulatory deadlines solidify. CoreWeave's GPU-dense positioning threatens specialized AI training tiers; counter through backward integration into confidential computing hardware partnerships that enable encrypted processing without decryption exposure.
For New Entrants and Emerging Players: Mid-market healthcare providers in secondary US metro areas represent the most penetrable entry point for DICOM-compliant archival services with automated lifecycle management. India's domestic fintech platforms scaling petabyte-range data lakes offer secondary white-space as RBI localization mandates exclude uncommitted foreign capacity. Go-to-market through FinOps platform partnerships embeds procurement into cloud financial management workflows rather than competing for direct enterprise relationships.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among regional sovereign operators with domestic-only infrastructure footprints that command multi-year fixed-price contracts from government agencies. Long-term viability over the next decade hinges on exclusive national data residency certifications that resist hyperscaler replication. Watch confidential computing integration timelines as the inflection indicator for premium tier pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | EU AI Act compliance investments in Germany and India secure regulatory moats against hyperscaler replication. |
| Confidential Computing Integration | Hardware-based trusted execution environments enable multi-tenant processing of encrypted healthcare datasets without decryption exposure. |
| FinOps Platform Partnership | Embedding storage procurement into cloud cost management workflows captures mid-market buyers exiting self-managed infrastructure. |
| Edge-Deployed Capacity Expansion | Sub-20ms latency object storage in Stuttgart and Munich factory floors anchors automotive telemetry lake contracts. |
| Legacy Tape Migration Services | Petabyte-scale retrieval orchestration tooling addresses hospital systems retiring on-premises PACS infrastructure. |
Research Methodology
Cross-validation between hyperscaler capex disclosures and channel partner interviews anchors the qualitative findings on capacity deployment timelines. Primary interviews with cloud infrastructure architects, FinOps platform engineers, healthcare IT directors, and sovereign compliance officers combined with secondary validation from SEC filings, EU regulatory databases, and national data protection authority rulings. Bottom-up demand modeling across deployment topologies and top-down supply verification through foundry output tracking ensures triangulation integrity.
Calibration against historical capacity absorption rates and regulatory implementation schedules shaped the analytical framework across the analysis window. Segmentation dimensions modeled include service architecture, deployment topology, customer scale, capacity tiers, and regional regulatory cluster. CAGRs were derived through regression analysis of correlated technology adoption curves and compliance-driven procurement accelerations. Forecast inputs incorporated power purchase agreement repricing trajectories and cross-border transfer mechanism legal uncertainty.
Macroeconomic conditions sit as an overlay; deviation in energy input costs, central bank rate trajectories, or adequacy decision timelines would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and hyperscaler capacity expansion cadence. Quarterly review of EU data protection authority rulings and hyperscaler regional infrastructure announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Nigeria Data Center Storage Market
Storage Solutions
Netherlands Data Center Storage Market
Storage Solutions
Storage Software Market
Storage Solutions
Switzerland Data Center Storage Market
Storage Solutions
Mexico Data Center Storage Market
Storage Solutions
United States Data Center Storage Market
Storage Solutions
Europe in-Memory Database Market
Storage Solutions
Belgium Data Center Storage Market
Storage Solutions
Disk Based Data Fabric Market
Storage Solutions
Cloud Object Storage Solutions Market
Storage Solutions
Global Storage As a Service Market
Storage Solutions
Philippines Data Center Storage Market
Storage Solutions
Asia Pacific Automated Storage and Retrieval System Market
Storage Solutions
New Zealand Data Center Storage Market
Storage Solutions
Indonesia Data Center Storage Market
Storage Solutions
Storage and Backup Software Market