
 Netherlands Data Center Storage Market | 2026-2036
Netherlands Data Center Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Data Center Storage Market Insights
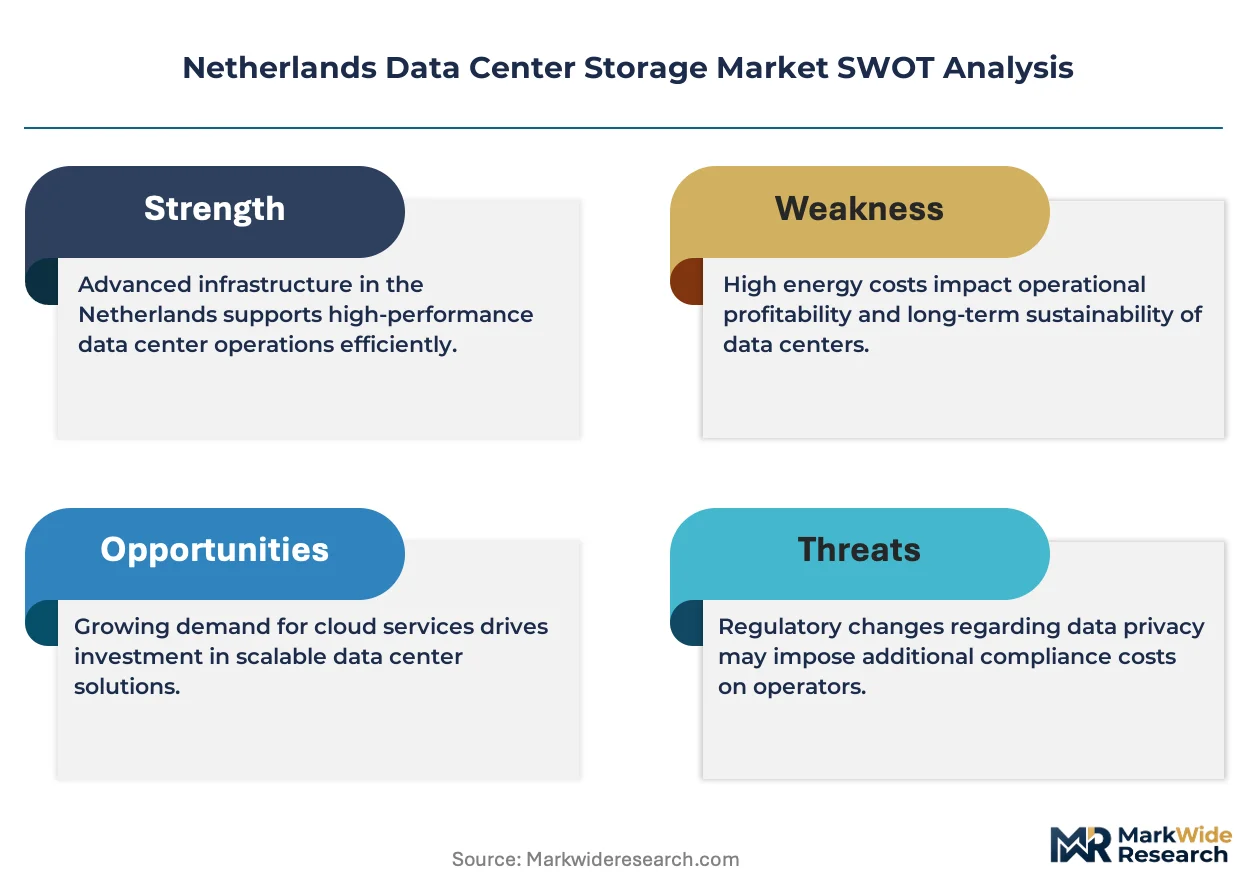
Modular all-flash arrays bundled with software-defined management layers is restructuring procurement patterns across Dutch data center operators. Dell Technologies leverages its integrated supply chain to dominate rack-scale deployments in Randstad corridors. Hewlett Packard Enterprise anchors its position through in-house silicon development for NVMe-optimized controllers. NetApp differentiates with cloud-adjacent file services that bridge on-premises and hosted environments.
Netherlands data center storage encompasses electromechanical and solid-state systems engineered for persistent data retention at petabyte scale, typically operating across latency tiers from sub-millisecond flash to archival tape with throughput measured in gigabytes per second. These systems serve commercial and industrial functions spanning real-time transaction processing, machine learning training pipelines, and regulatory-compliant long-term record preservation. Flash storage leads value generation as AI inference and high-frequency trading workloads demand consistent microsecond response times. Hybrid storage architectures occupy the broadest deployment base among mid-tier enterprises balancing capital constraints against performance requirements. Disk storage retains relevance for sequential backup streams where cost-per-terabyte economics outweigh access speed.
The Dutch Authority for Digital Infrastructure enforces energy performance standards that filter storage procurement toward Tier IV-certified facilities with power usage effectiveness below industry baselines. BIS-equivalent conformity assessment for electromagnetic compatibility shapes hardware import and integration protocols for non-EU vendors. NEN norms for fire safety and structural load govern physical array installation in Amsterdam, Rotterdam, and Eindhoven facilities. Stakeholders must monitor how forthcoming EU AI Act data governance requirements will reshape retention policies and encryption standards for training dataset repositories.
Market Dynamics
The Dutch Climate Agreement carbon reduction targets are compressing procurement timelines toward liquid-cooled flash arrays and energy-optimized storage architectures across Randstad facilities.
Growth Catalysts
- AI Training Workload Density:Hyperscale operators in Amsterdam metropolitan clusters are expanding NVMe-optimized petabyte-scale repositories to serve generative model development pipelines.
- EU AI Act Data Governance:Forthcoming retention and encryption mandates for training datasets are accelerating compliance-oriented storage infrastructure refresh cycles.
- Liquid Cooling Infrastructure:Immersion and direct-to-chip thermal management systems are enabling higher rack densities for flash storage deployments in space-constrained urban facilities.
Market Restraints
- Flash Memory Supply Concentration:NAND fabrication capacity concentration in East Asian foundries creates exposure to geopolitical friction and input cost volatility.
- Tier IV Certification Cost Structure:Dutch Authority for Digital Infrastructure energy performance standards impose capital-intensive facility upgrades that filter mid-tier enterprise procurement.
- Tape Archive Substitution Economics:Sequential cold storage retention for regulatory-compliant long-term records retains cost-per-terabyte advantages over flash for infrequently accessed datasets.
Strategic Opportunities
- Eindhoven Industrial Corridor:Semiconductor and advanced manufacturing clusters present underpenetrated demand for edge-integrated storage nodes with microsecond latency requirements.
- Cloud-Adjacent File Convergence:Hybrid architectures bridging on-premises NVMe arrays with hosted object storage are capturing enterprise workload migration projects.
- CSRD Sustainability Reporting:Corporate Sustainability Reporting Directive scope expansion is creating procurement pull for storage systems with embedded carbon accounting and power monitoring telemetry.
Industry Challenges
- Liquid Cooling Technician Scarcity:Specialized thermal engineering and immersion system maintenance skills are concentrated among hyperscale operators, constraining mid-market facility upgrades.
- NEN Fire Safety Integration:Physical array installation compliance with Dutch structural load and suppression system norms extends deployment timelines for imported hardware platforms.
- Legacy Disk Migration Complexity:Hybrid environment management during flash transition cycles demands software-defined orchestration capabilities that strain existing IT operations teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Data Center Storage Market |
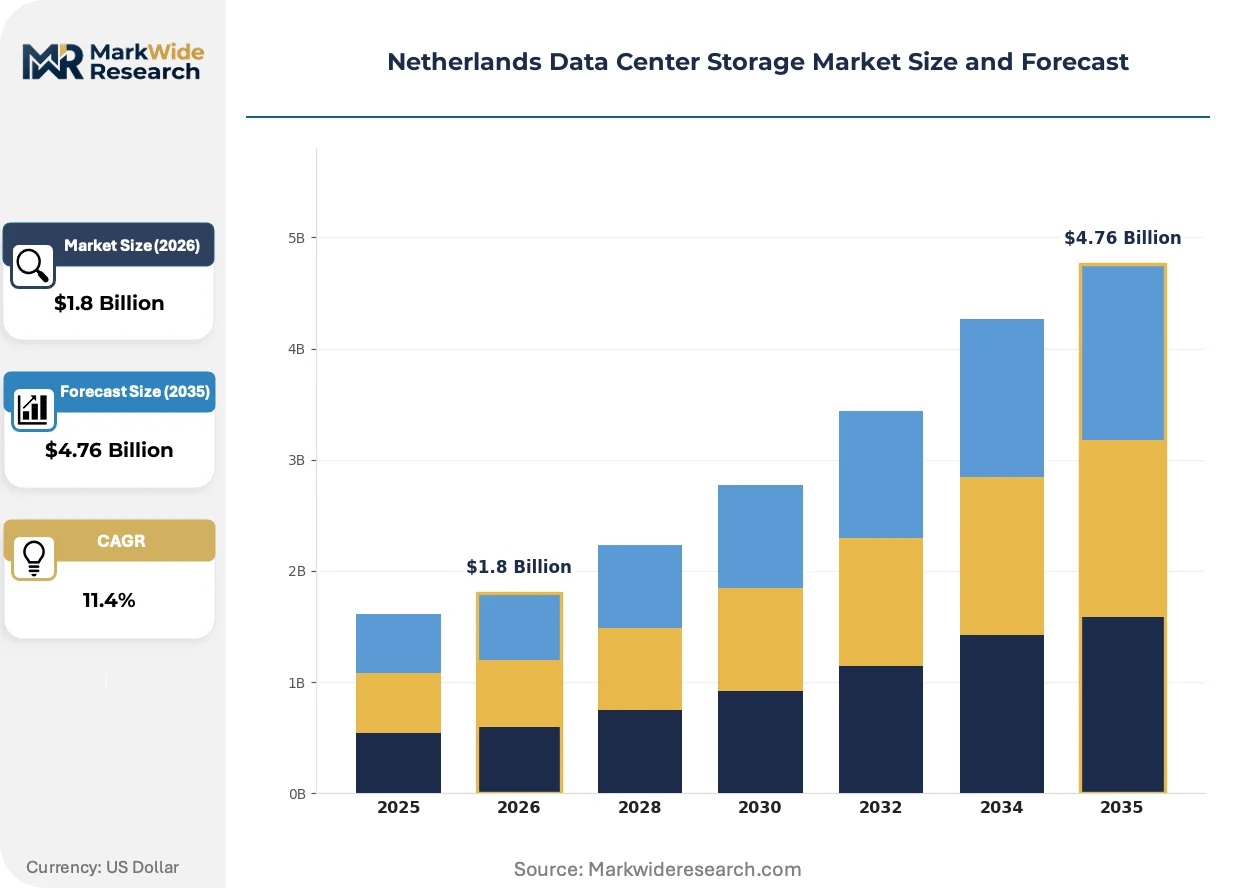
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Storage Type: Disk Storage, Flash Storage, Tape Storage, Hybrid Storage End User: Cloud Providers, Enterprises, Managed Service Providers, Telecom Companies Deployment Model: On-premises, Colocation, Hosted, Hybrid Cloud Connectivity: Ethernet, Fibre Channel, InfiniBand, iSCSI |
| Companies Covered | Dell Technologies, Hewlett Packard Enterprise, NetApp, IBM Corporation, Cisco Systems, Huawei Technologies, Hitachi Vantara, Seagate Technology, Veeam Software, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Data Center Storage Market Trends and Innovations
Storage architectures across Dutch facilities are compressing toward software-defined disaggregation, with compute and persistence layers decoupling to optimize thermal and power profiles.
Computational storage drives integrating processing capabilities directly at the NAND controller level are absorbing inference workload segments previously routed through server CPUs. High-frequency trading firms and real-time analytics operators in Amsterdam are deploying these devices to reduce data movement latency. This absorption of compute into storage hardware is compressing traditional server-storage network topologies and reshaping rack-scale design specifications.
CSRD disclosure requirements are mandating granular power consumption telemetry across IT infrastructure asset classes. Dutch data center operators must now instrument storage arrays with continuous carbon intensity tracking and report embodied emissions through supply chains. Facilities in Rotterdam and Eindhoven are responding by prioritizing hardware vendors with validated lifecycle assessment documentation and modular upgrade paths.
Consumption-based financing models are displacing capital-intensive ownership structures among mid-tier enterprises with cyclical capacity requirements. Leasing arrangements bundling hardware, software management layers, and refresh cycles are capturing procurement decisions previously executed through direct purchase. This pattern concentrates in Amsterdam metropolitan financial services and logistics verticals where balance sheet flexibility outweighs long-term asset control preferences.
Netherlands Data Center Storage Market Segmentation
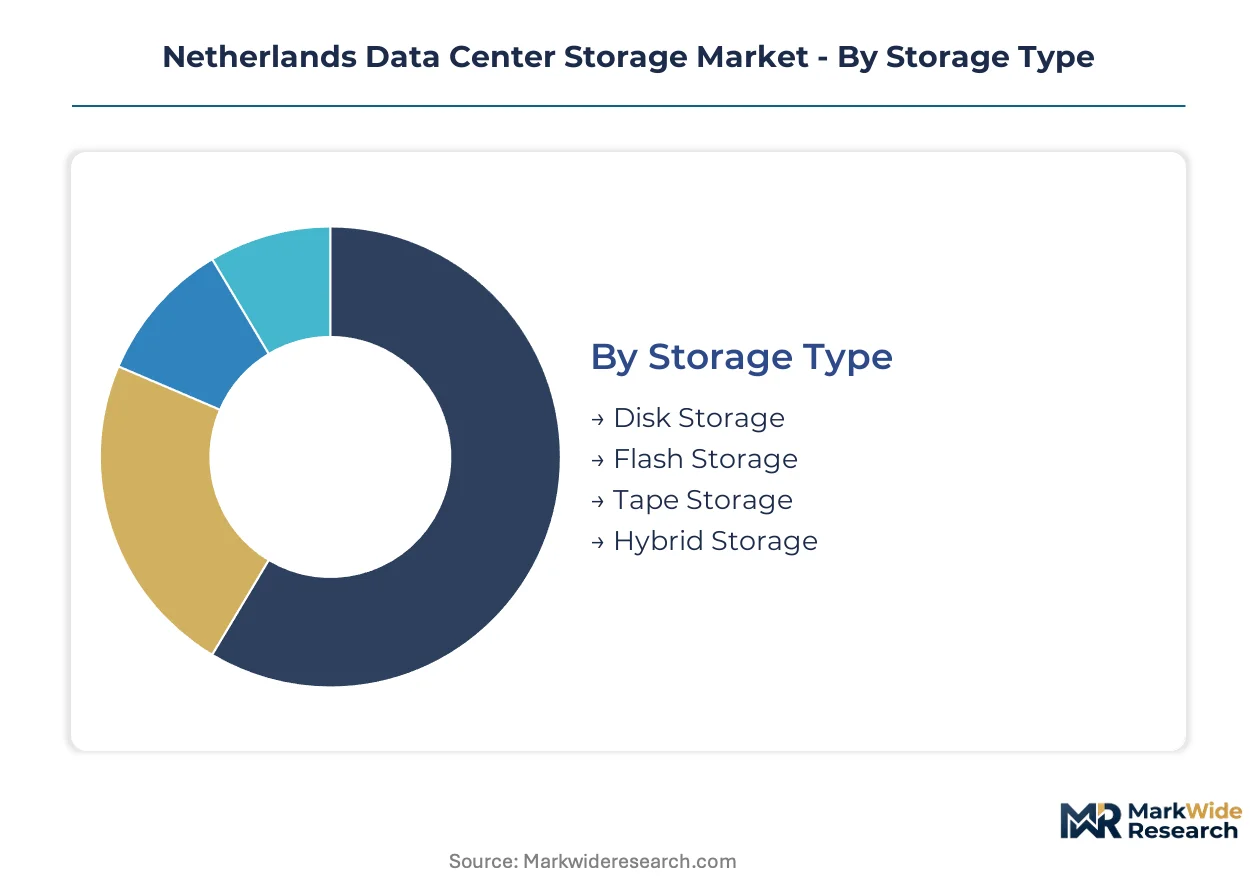
Storage procurement patterns across Dutch facilities diverge sharply by workload latency requirements, thermal constraints, and data sovereignty obligations. Understanding these segment boundaries enables infrastructure planners to align capital deployment with specific operational mandates rather than generic capacity expansion.
Storage Type:
Capital intensity escalates dramatically from sequential-access tape systems to sub-millisecond flash arrays, with liquid-cooled NVMe deployments commanding premium infrastructure investment.
- Flash Storage:Solid-state arrays built on NAND and emerging SCM technologies deliver consistent microsecond response times for AI inference and high-frequency trading workloads. Amsterdam metropolitan hyperscale clusters are prioritizing these systems for generative model training pipelines, though Dutch Climate Agreement carbon targets are compressing procurement toward energy-optimized controller architectures.
- Hybrid Storage:Tiered architectures combining flash front-ends with disk or tape back-ends balance performance against capital constraints for mid-tier enterprises. Randstad financial services firms are deploying these systems to satisfy regulatory retention mandates without overprovisioning expensive solid-state capacity for archival workloads.
- Disk Storage:Electromechanical hard drive arrays retain cost-per-terabyte advantages for sequential backup streams and bulk data lakes.
- Tape Storage:Linear magnetic media systems serve regulatory-compliant long-term retention with minimal idle power draw.
Hybrid Storage absorbs the bulk of installed capacity; Flash Storage is expanding most quickly.
End User:
Procurement scale and technical sophistication vary substantially across customer archetypes, from hyperscale operators with captive engineering teams to regulated enterprises outsourcing infrastructure management.
- Cloud Providers:Hyperscale operators with autonomous procurement functions deploy rack-scale NVMe clusters across Amsterdam metropolitan facilities to serve multi-tenant AI and analytics workloads. These buyers negotiate directly with NAND foundries and specify custom firmware for power efficiency telemetry mandated by Dutch Authority for Digital Infrastructure standards.
- Enterprises:Corporate IT organizations spanning financial services, logistics, and manufacturing verticals purchase through channel partners with managed refresh cycles. Eindhoven semiconductor clusters are driving edge-integrated storage demand for microsecond-latency process control applications.
- Managed Service Providers:Third-party infrastructure operators bundle storage capacity with professional services for mid-market clients lacking internal platform expertise.
- Telecom Companies:Network operators with distributed real estate portfolios deploy storage nodes at mobile edge computing sites to reduce backhaul congestion.
Cloud Providers command the largest share of petabyte-scale deployments; Enterprises are climbing the fastest as CSRD disclosure requirements force infrastructure refresh cycles.
Deployment Model:
Facility ownership structures determine capital allocation patterns, with balance-sheet constraints pushing mid-tier buyers toward operational expenditure models.
- Colocation:Wholesale and retail data center operators in Amsterdam, Rotterdam, and Eindhoven provide powered shell space with cross-connect density for tenant-owned storage arrays. Dutch Authority for Digital Infrastructure Tier IV certification requirements are filtering procurement toward facilities with validated power usage effectiveness below industry baselines.
- Hybrid Cloud:Architectures spanning on-premises NVMe arrays with hosted object storage are capturing enterprise workload migration projects seeking data sovereignty compliance without full capital commitment.
- On-premises:Captive facility ownership persists among defense contractors and critical infrastructure operators with classified or nationally sensitive data retention obligations.
- Hosted:Fully managed storage-as-a-service offerings appeal to cyclical capacity requirements in seasonal logistics and media production verticals.
Colocation absorbs the bulk of new capacity installation; Hybrid Cloud is gaining share fastest as financial services firms navigate EU AI Act data governance uncertainty.
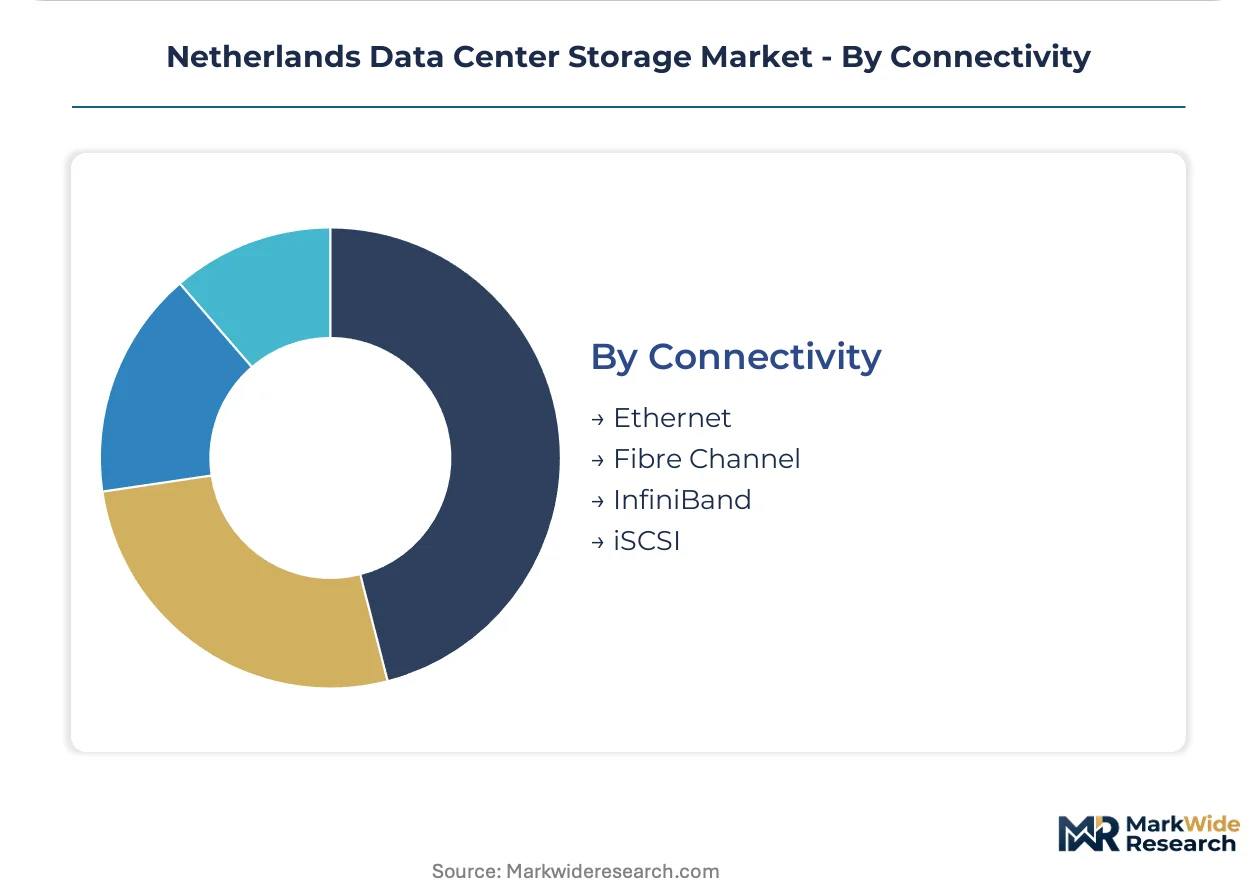
Connectivity:
Protocol selection constrains achievable latency and determines switch infrastructure compatibility across storage network topologies.
- InfiniBand:High-bandwidth, low-latency interconnects dominate AI training clusters where RDMA-enabled data movement between GPU servers and NVMe arrays eliminates TCP/IP overhead. Amsterdam hyperscale facilities are standardizing on these fabrics for generative model development pipelines.
- Ethernet:Converged network adapters running RoCE or standard TCP/IP serve general-purpose enterprise workloads with sufficient latency tolerance for transactional databases and virtualized infrastructure.
- Fibre Channel:Dedicated storage area networks persist in legacy financial services environments with established zoning and multipathing operational procedures.
- iSCSI:IP-based block protocols enable storage extension across routed networks for disaster recovery and remote office consolidation scenarios.
Ethernet retains the broadest installed base; InfiniBand is expanding most quickly as AI workload density concentrates in Amsterdam metropolitan clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Storage production concentrates in East Asian NAND foundries while Dutch facilities consume petabyte-scale capacity for AI and financial services workloads. The Netherlands imports flash controllers and solid-state arrays through Rotterdam port logistics. Domestic demand pulls advanced storage architectures toward Amsterdam metropolitan interconnection hubs.
Randstad
Amsterdam's hyperscale clusters drive NVMe-optimized procurement for generative AI training pipelines. The Dutch Authority for Digital Infrastructure enforces Tier IV energy standards that filter procurement toward liquid-cooled flash arrays. Schiphol-Rijk and Amsterdam Science Park facilities host cloud provider storage nodes with microsecond latency specifications for high-frequency trading.
Brabant
Eindhoven's semiconductor equipment manufacturers demand edge-integrated storage for process control telemetry. The Dutch Climate Agreement carbon targets compress procurement timelines toward energy-efficient architectures. ASML-adjacent facilities in Veldhoven deploy petabyte-scale repositories for lithography pattern data retention.
Rotterdam Port Region
Logistics operators and commodity trading firms require hybrid storage for real-time risk analytics and regulatory document archives. NEN fire safety norms govern physical array installation in port-adjacent data centers. Waalhaven industrial zones host colocation facilities serving maritime insurance and freight forwarding verticals.
Northern Netherlands
Groningen's energy transition data centers leverage underground geological stability for archival tape repositories. National carbon reduction targets incentivize low-power storage for seismic survey and wind farm telemetry datasets. Eemshaven's cable landing stations create interconnection pull for distributed storage nodes serving Nordic and German markets.
Netherlands Data Center Storage Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Dutch procurement channels. Rack-scale system integrators dominate hyperscale deployments through direct sales relationships. Software-defined storage vendors capture enterprise refresh cycles with consumption-based financing models. Strategic moves center on silicon controller development and cloud-adjacent file service integration.
Within the integrated infrastructure tier, Dell Technologies and Hewlett Packard Enterprise occupy positions as full-stack system architects. NetApp exemplifies the cloud-hybrid specialist archetype bridging on-premises NVMe with hosted object storage. These three companies anchor competitive positioning across Randstad financial services and Eindhoven manufacturing verticals.
| Leading Market Players |
|---|
| Dell Technologies |
| Hewlett Packard Enterprise |
| NetApp |
| IBM Corporation |
| Cisco Systems |
| Huawei Technologies |
| Hitachi Vantara |
| Seagate Technology |
| Veeam Software |
| Others |
Pricing and Supply Chain Analysis
Tier IV certification mandates from the Dutch Authority for Digital Infrastructure are compressing procurement timelines toward liquid-cooled flash arrays, forcing NAND foundries and system integrators to absorb higher thermal engineering costs that transmit into premium pricing for certified deployments.
Pricing Analysis
Margin tightening in mid-tier enterprise segments reflects Dutch Climate Agreement carbon targets that disqualify air-cooled disk arrays from public sector tenders. Three-tier pricing structure across liquid-cooled NVMe, air-cooled flash, and hybrid disk-tape configurations segments buyers by latency requirements and compliance obligations. Cloud providers with rack-scale direct procurement exhibit lowest price sensitivity, while cyclical logistics operators in Rotterdam port zones prioritize consumption-based financing to preserve balance sheet flexibility.
Supply Chain Analysis
EU AI Act data governance requirements are reshaping sourcing protocols toward vendors with validated encryption firmware and EU-based data residency guarantees. NAND fabrication concentrates in South Korea, Taiwan, and Japan, with flash controllers and solid-state arrays assembling through Chinese contract manufacturers before Rotterdam port clearance. Dutch facilities draw from East Asian memory foundries while depending on German precision cooling component suppliers for liquid-immersion infrastructure. Single-source vulnerability in advanced NVMe controller silicon creates exposure to export control friction. Distribution runs through Amsterdam metropolitan hyperscale clusters with direct foundry relationships, channeling secondary volumes through Randstad system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Netherlands data center storage market functions as a cost-of-compliance arena where Dutch Authority for Digital Infrastructure Tier IV standards and forthcoming EU AI Act encryption mandates construct regulatory moats favoring incumbent vendors with validated certification documentation.
For Market Incumbents: Hedge against flash memory supply concentration by cultivating captive relationships with South Korean NAND foundries for allocation priority during allocation cycles. Accelerate in-house silicon controller development to reduce dependency on Taiwanese fabless designers exposed to geopolitical friction. Deepen software-defined management layer investments to capture enterprise refresh cycles displacing legacy disk architectures. For New Entrants and Emerging Players: Computational storage drives integrating inference processing at the NAND controller level offer white-space penetration into Amsterdam high-frequency trading clusters demanding microsecond latency reduction. Edge-integrated storage nodes for Eindhoven semiconductor process control telemetry represent underpenetrated demand outside hyperscale procurement channels. Lead with consumption-based financing models to displace capital-intensive ownership structures among mid-tier Randstad enterprises. For Investors and Strategic Acquirers: The window for entry favors cloud-hybrid software specialists bridging on-premises NVMe with hosted object storage architectures. Long-term viability rests on vendors with validated lifecycle assessment documentation satisfying CSRD sustainability reporting mandates. Monitor Dutch Authority for Digital Infrastructure enforcement patterns around Tier IV certification as inflection indicator for compliance-premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Infrastructure Deployment | Enables Amsterdam hyperscale facilities to satisfy Dutch Climate Agreement carbon density targets while supporting AI training workloads. |
| NVMe Controller Silicon Development | Reduces latency overhead for generative model pipelines while insulating from East Asian foundry allocation volatility. |
| Cloud-Adjacent File Service Integration | Captures enterprise workload migration projects seeking data sovereignty compliance without full capital commitment. |
| CSRD-Compliant Telemetry Instrumentation | Positions storage arrays for mandatory carbon accounting disclosures across Rotterdam and Eindhoven facilities. |
| Edge Storage Node Distribution | Addresses microsecond-latency requirements in Eindhoven semiconductor manufacturing corridors outside metropolitan hubs. |
Research Methodology
Document review covered Dutch Authority for Digital Infrastructure certification databases, EU AI Act draft provisions, and hyperscaler capex disclosures, complemented by interviews with data center facility operators, storage procurement leads at Randstad financial services firms, thermal engineering specialists, and channel distribution partners. Secondary validation drew from customs import records through Rotterdam port, NEN fire safety compliance filings, and SEC 10-K filings of listed storage vendors. Bottom-up capacity installation tracking across Amsterdam, Rotterdam, and Eindhoven facilities triangulated against top-down market sizing from NAND foundry shipment data.
Historical deployment patterns across flash, hybrid, disk, and tape storage types were cross-referenced against panel input from infrastructure planners regarding procurement timeline compression. The analytical framework modeled segmentation across storage type, end user archetype, deployment model, and connectivity protocol throughout the forecast period. CAGRs were derived from elasticity-adjusted capacity expansion curves incorporating Dutch Climate Agreement carbon target compliance deadlines. Industry-specific inputs included liquid cooling adoption rates and EU AI Act data governance implementation timelines.
Several conditions sit outside the modeled scope, including unannounced NAND foundry capacity expansions, geopolitical export control escalations affecting controller silicon, and disruptive storage-class memory technology commercialization. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and hyperscale demand continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Public Cloud Storage Services Market
Storage Solutions
Data Backup and Recovery Market
Storage Solutions
Virtual Machine Backup and Recovery Market
Storage Solutions
United States Data Center Storage Market
Storage Solutions
Thailand Data Center Storage Market
Storage Solutions
Global All-Flash Array Market
Storage Solutions
Disk Based Data Fabric Market
Storage Solutions
Nigeria Data Center Storage Market
Storage Solutions
Poland Data Center Storage Market
Storage Solutions
UK Data Center Storage Market
Storage Solutions
Spain Data Center Storage Market
Storage Solutions
Cloud Storage Gateways Market
Storage Solutions
New Zealand Data Center Storage Market
Storage Solutions
5D Data Storage Market
Storage Solutions
Cloud Storage Market
Storage Solutions
Global Server Storage Area Network Market