
 Global Storage As a Service Market | 2026-2036
Global Storage As a Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global Storage As a Service Market Foresight
Hyperscaler data center buildouts in Northern Virginia are shifting procurement patterns across the entire storage services value chain. Amazon Web Services, Inc. leverages its region-dense footprint to anchor enterprise contracts requiring low-latency access. Microsoft Corporation competes through deep integration with productivity suites that sustain switching costs for large organizations. Dell Technologies specializes in hybrid cloud orchestration, positioning its Apex portfolio between on-premises hardware and public cloud consumption.
Storage as a Service denotes a cloud computing delivery model where third-party providers manage storage infrastructure via network access, typically offering redundancy through multi-availability-zone replication and encryption at rest and in transit. The architecture eliminates capital expenditure on physical arrays while enabling elastic capacity scaling for unstructured data lakes, transactional databases, and disaster recovery repositories. Public cloud deployment leads absolute revenue contribution due to hyperscaler economies of scale, though hybrid cloud configurations are capturing margin-rich enterprise workloads governed by data sovereignty constraints. Object storage within the service type dimension is extending fastest as video analytics, genomic sequencing, and IoT telemetry generate petabyte-scale unstructured volumes that resist traditional file system hierarchies.
The EU AI Act, GDPR, and SEC cybersecurity disclosure rules are collectively reshaping vendor qualification criteria, forcing providers to certify data lineage, audit logging, and cross-border transfer mechanisms before contract execution. HIPAA in the United States imposes comparable technical safeguards on healthcare-oriented storage architectures, narrowing the field to providers with dedicated compliance teams. Stakeholders must monitor evolving encryption standards and residency mandates as regulatory fragmentation becomes the primary constraint on service architecture decisions.
Market Dynamics
Hyperscaler infrastructure buildouts are compressing unit economics for enterprise storage procurement, forcing independent software vendors to reposition around data sovereignty and workload-specific performance tiers rather than competing on raw capacity pricing.
Growth Catalysts
- EU AI Act compliance mandates:Data residency requirements under the EU AI Act and GDPR are compelling enterprises to adopt sovereign cloud architectures with certified in-region replication.
- Healthcare imaging data explosion:PACS and DICOM archive migrations to managed object storage are accelerating as radiology departments confront petabyte-scale unstructured data accumulation.
- Genomic sequencing pipelines:Research institutions processing CRISPR and next-generation sequencing outputs require elastic capacity scaling that on-premises arrays cannot provision economically.
Market Restraints
- Hyperscaler supply concentration:Northern Virginia, Frankfurt, and Singapore data center clusters concentrate critical infrastructure, creating regional failure exposure and procurement bottlenecks.
- Egress fee opacity:Cross-availability-zone transfer pricing and retrieval cost unpredictability complicate total cost of ownership calculations for finance departments.
- Encryption standard fragmentation:Divergent national cryptographic certification regimes (FIPS 140-3 in the United States, BSI technical guidelines in Germany) force redundant compliance investments.
Strategic Opportunities
- Industrial Mittelstand migration:German mid-market manufacturers with legacy SAN infrastructure represent underpenetrated demand for hybrid cloud orchestration services.
- Edge-to-core data pipelines:Convergence of 5G MEC nodes with centralized object storage tiers enables real-time analytics for autonomous systems and predictive maintenance.
- SEC cybersecurity disclosure rules:Mandatory incident reporting requirements are elevating managed detection and response bundles as preferred procurement vehicles.
Industry Challenges
- Multi-cloud orchestration expertise scarcity:Kubernetes-native storage architecture and FinOps tooling require specialized engineering talent that reskilling programs have not yet produced at scale.
- HIPAA technical safeguard validation:Healthcare providers face extended audit timelines when certifying business associate agreements with emerging storage providers lacking established compliance track records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Storage As a Service Market |
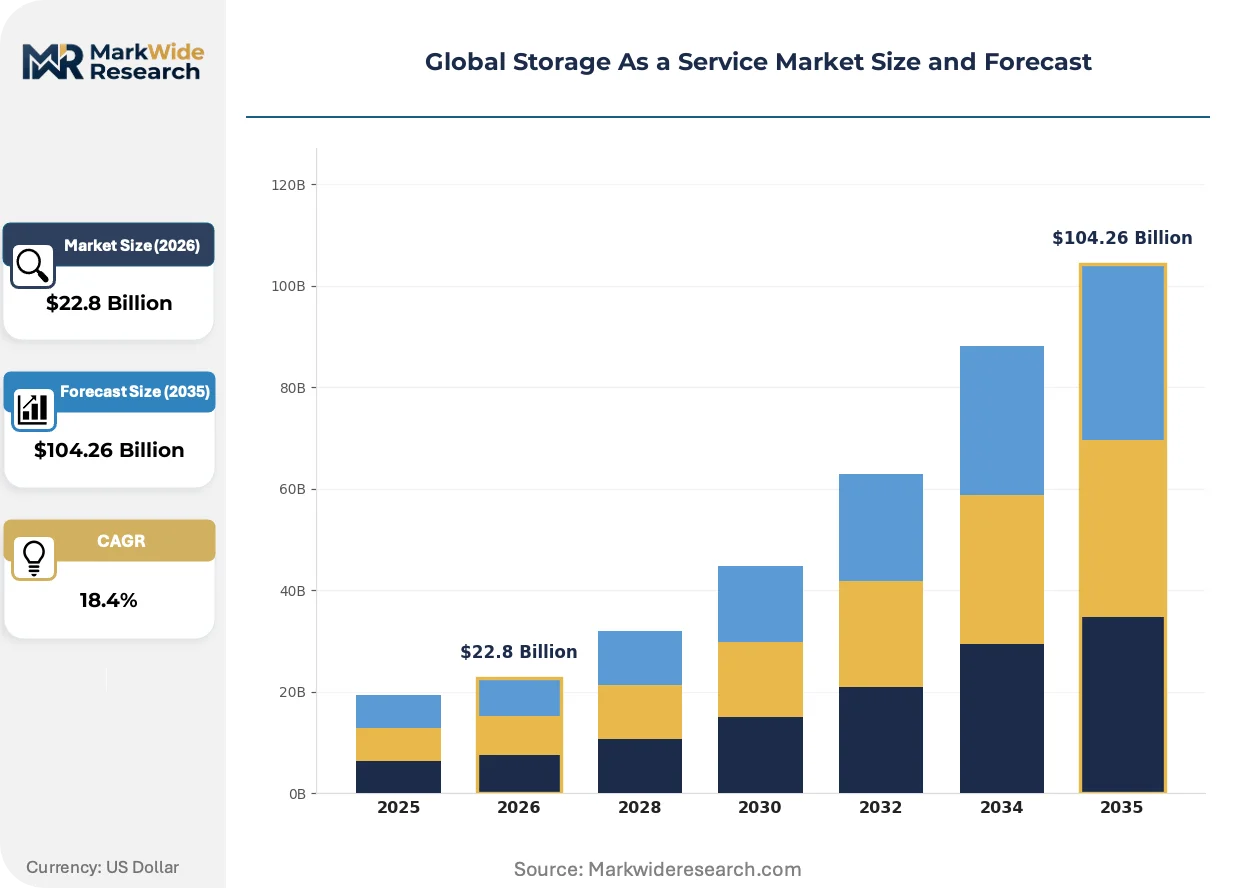
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $104.26 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Service Type: Block Storage, File Storage, Object Storage, Backup Storage End User Industry: Information Technology, Telecommunications, Media & Entertainment, Manufacturing Pricing Model: Pay-As-You-Go, Subscription-Based, Usage-Based, Tiered Pricing |
| Companies Covered | Amazon Web Services, Inc., Microsoft Corporation, Google LLC, IBM Corporation, Dell Technologies, Hewlett Packard Enterprise, Rackspace Technology, NetApp, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Storage As a Service Market Shifts & Advancements
Storage architecture is bifurcating between hyperscale commodity tiers and precision-engineered sovereign instances, with automation layers determining competitive positioning more than underlying hardware specifications.
Immutable object storage with native ransomware detection is converging with automated air-gapping workflows to create self-healing data protection architectures. Financial services institutions and healthcare systems are adopting these configurations fastest, compressing recovery point objectives from hours to minutes while eliminating tape-based archival dependencies.
The EU AI Act's data lineage documentation requirements are forcing providers to implement automated metadata capture and audit trail generation at the infrastructure layer. This regulatory pressure is most acute in Germany and France, where national supervisory authorities are conducting pre-contractual compliance verification before procurement authorization.
Consumption-based billing models are displacing committed-use discounts as the dominant enterprise procurement structure. Manufacturing and life sciences verticals in the United States are piloting usage-only arrangements with cost caps, transferring capacity planning risk to providers while retaining operational flexibility for seasonal workload spikes.
Global Storage As a Service Market Segmentation
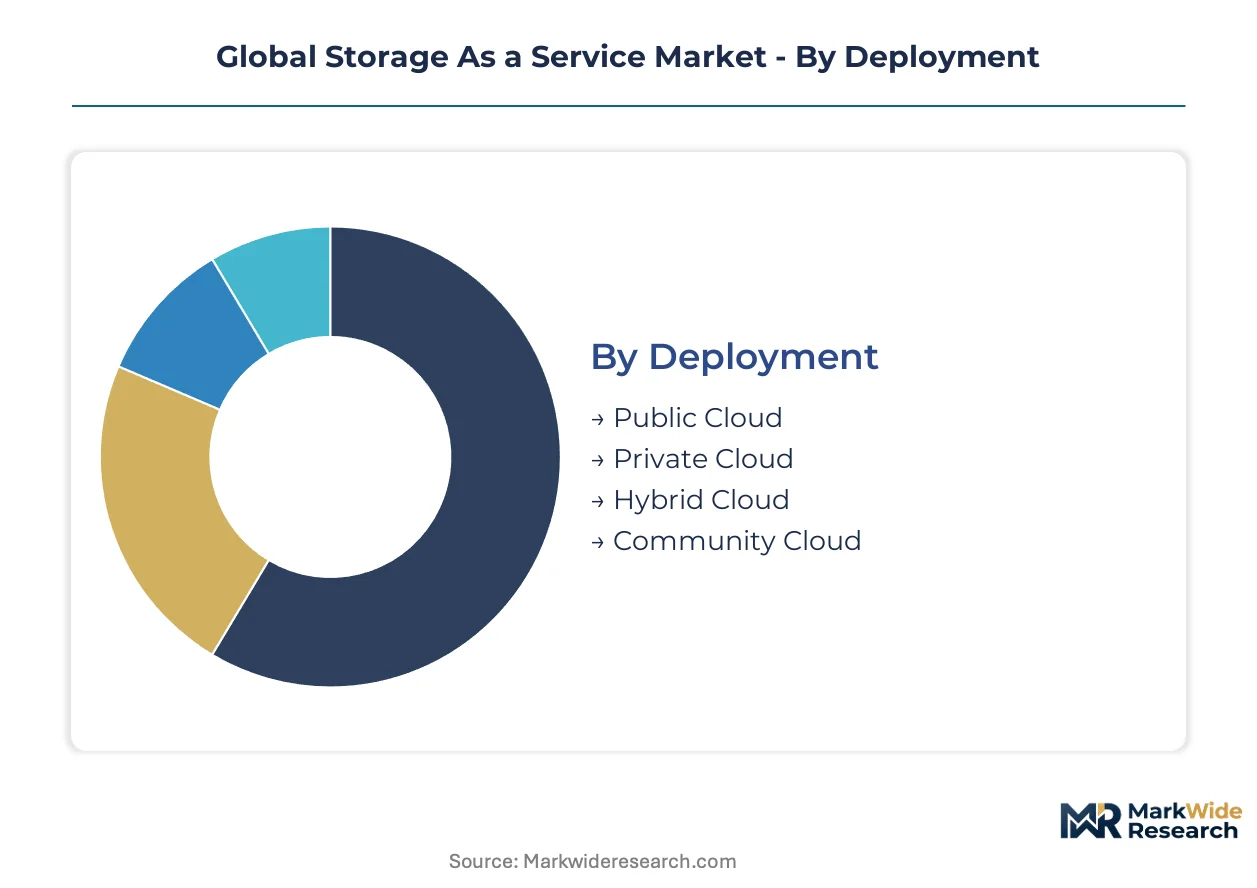
Storage as a Service procurement patterns diverge sharply across deployment architectures, workload characteristics, and consumption economics. Each segmentation axis reveals distinct vendor qualification criteria and margin structures that reshape competitive positioning.
Deployment:
Customization intensity varies from fully standardized hyperscale tiers to engineered sovereign instances with certified residency controls.
- Public Cloud:Multi-tenant infrastructure delivers elastic capacity through hyperscaler economies of scale. Healthcare providers in the United States and media streaming platforms in Germany concentrate demand here, driven by burst workload requirements and HIPAA technical safeguard certifications.
- Hybrid Cloud:Orchestration layers unify on-premises arrays with public cloud tiers through policy-driven data placement. Industrial Mittelstand manufacturers in Germany and financial services institutions in Singapore anchor procurement, compelled by GDPR data sovereignty mandates and SEC cybersecurity disclosure rules.
- Private Cloud:Single-tenant dedicated infrastructure with customer-controlled encryption key management. Defense contractors and classified research institutions require FIPS 140-3 validated configurations.
- Community Cloud:Shared infrastructure serving specific vertical or regulatory communities with common compliance requirements. Academic research consortia and healthcare information exchanges adopt these for cost-pooled HIPAA business associate agreements.
Leading the category by volume: Public Cloud. Expanding most quickly: Hybrid Cloud.
Service Type:
Performance requirements and data structure characteristics determine which abstraction layer dominates procurement.
- Object Storage:Flat namespace architecture optimized for petabyte-scale unstructured data with custom metadata tagging. Genomic sequencing facilities in the United States and video analytics platforms in Germany drive fastest adoption, confronting CRISPR output volumes and 8K streaming archive accumulation that resist hierarchical file systems.
- Block Storage:Raw volume presentation to operating systems with consistent low-latency performance. Transactional database workloads and virtual machine hosting in Singapore and Northern Virginia data center clusters sustain core demand.
- File Storage:POSIX-compliant hierarchical access for legacy application compatibility. Enterprise content management and engineering design workstations retain dependency on NFS and SMB protocols.
- Backup Storage:Immutable repository configurations with air-gapped recovery workflows. Financial services institutions in the United States and healthcare systems in Germany adopt fastest for ransomware resilience and HIPAA audit requirements.
Dominant by revenue: Object Storage. Steepest expansion trajectory: Backup Storage with native immutability.
End User Industry:
Vertical-specific compliance regimes and data velocity patterns create divergent service requirements.
- Information Technology:Software vendors and cloud-native enterprises consuming infrastructure for DevOps pipelines and SaaS delivery. Primary demand centers in Northern Virginia and Frankfurt for low-latency development environments.
- Telecommunications:5G MEC node integration with centralized object tiers enabling real-time network analytics. Singapore and German operators lead edge-to-core pipeline deployments.
- Media & Entertainment:Streaming platforms and post-production houses managing petabyte-scale content libraries. Los Angeles and London production clusters drive tiered archival demand.
- Manufacturing:Industrial IoT telemetry ingestion and predictive maintenance data lakes. German automotive suppliers and United States aerospace contractors anchor hybrid cloud migration.
Highest absolute spend: Information Technology. Gaining share fastest: Manufacturing with legacy SAN displacement.
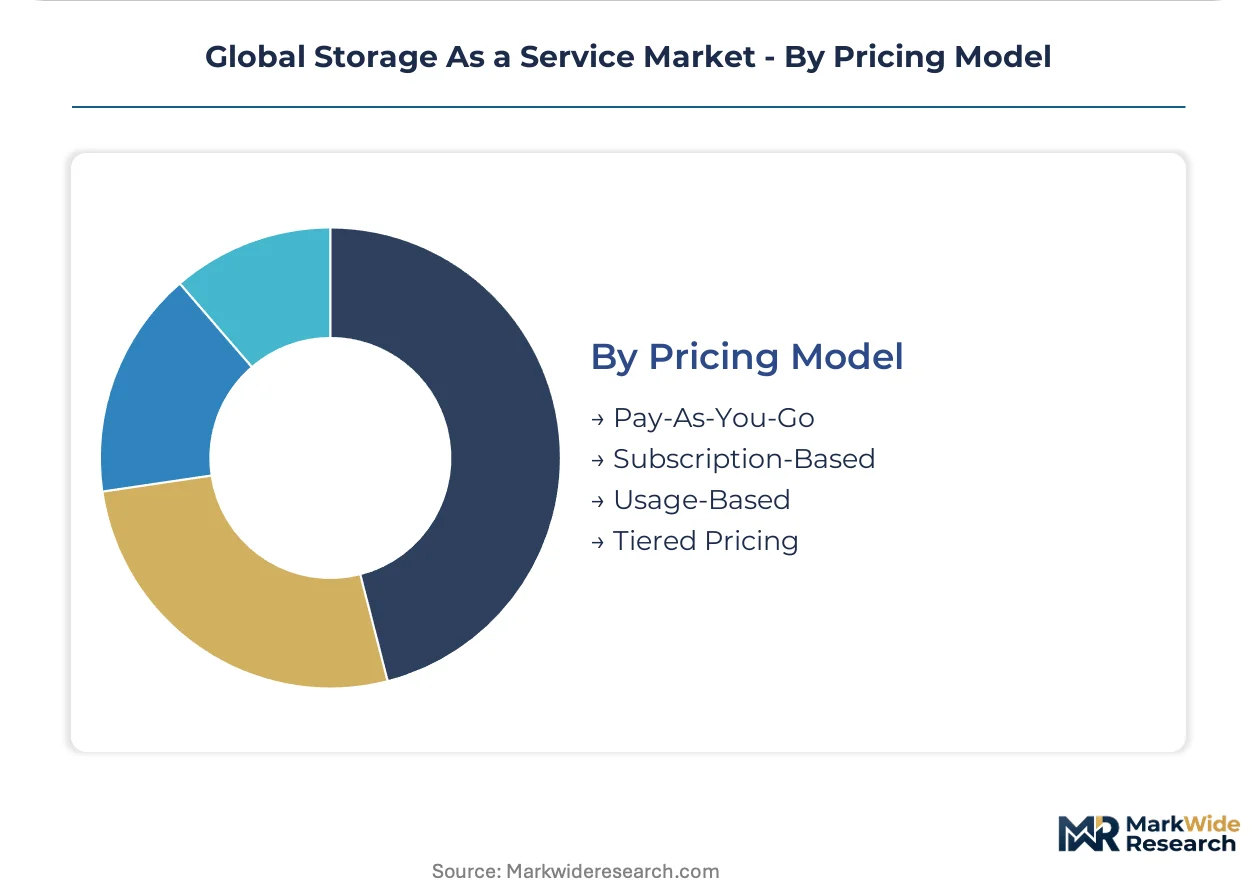
Pricing Model:
Risk allocation between provider and customer shifts dramatically across contract structures.
- Pay-As-You-Go:Uncommitted consumption with per-gigabyte egress and retrieval charges. Startups and seasonal workload operators tolerate cost unpredictability for operational flexibility.
- Subscription-Based:Fixed monthly fees for predictable capacity tiers with overage penalties. Mid-market enterprises in Germany prefer cost certainty for budget planning cycles.
- Usage-Based:Metered consumption with negotiated rate floors and ceilings. United States life sciences verticals pilot these arrangements for clinical trial data spikes.
- Tiered Pricing:Performance-stratified rates across hot, warm, and cold access frequencies. Archive-heavy media and genomic workloads optimize total cost through automated lifecycle policies.
Prevailing structure: Subscription-Based. Displacing fastest: Usage-Based with cost cap guarantees.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Northern Virginia's hyperscaler corridor anchors the densest concentration of storage infrastructure globally, with Frankfurt and Singapore clusters forming complementary poles that reshape procurement geography across three continents.
United States
Healthcare imaging archives and genomic sequencing pipelines drive petabyte-scale demand from Boston research hospitals and San Diego biotech clusters. HIPAA technical safeguard enforcement by the Office for Civil Rights narrows vendor qualification to providers with dedicated compliance teams. Northern Virginia's Ashburn-Loudoun data center corridor hosts the world's largest concentration of cloud storage capacity, with AWS, Microsoft, and Google operating adjacent campuses that compress latency for federal and enterprise contracts.
Germany
Industrial Mittelstand manufacturers in Baden-Württemberg and Bavaria are displacing legacy SAN infrastructure with hybrid cloud orchestration platforms. The EU AI Act and GDPR data residency mandates enforced by BSI and state data protection authorities require certified in-region replication before procurement authorization. Frankfurt's Rhine-Main cluster anchors continental European capacity, with Deutsche Telekom and regional providers competing against hyperscalers on sovereign cloud credentials.
Singapore
Telecommunications operators and financial institutions demand edge-to-core pipelines converging 5G MEC nodes with centralized object tiers. The Monetary Authority of Singapore's technology risk management guidelines impose audit logging and encryption standards that favor providers with established regional compliance track records. The Jurong and Tanjong Kling data center districts concentrate Southeast Asian capacity, serving as failover hubs for Australian and Indonesian enterprise workloads.
United Kingdom
Media streaming platforms and post-production houses in London's Soho district generate tiered archival demand for petabyte-scale content libraries. The Information Commissioner's Office enforces UK GDPR with post-Brexit divergence from EU standards, complicating cross-border data transfer mechanisms for multinational contracts. Slough's Trading Estate and East London's Docklands corridor host the densest storage infrastructure outside the United States, with Microsoft and Google anchoring enterprise-facing facilities.
Japan
Automotive suppliers and precision manufacturers in Aichi Prefecture and the Kanto region migrate engineering design workstations to managed file storage services. METI's data free flow with trust initiatives and APPI amendments impose localization requirements that favor domestic providers and joint ventures with global hyperscalers. Tokyo's Inzai and Osaka's Sakai data center districts concentrate national capacity, with NTT and Fujitsu competing against AWS Tokyo and Microsoft Japan on latency and regulatory familiarity.
Global Storage As a Service Market Competitive Landscape
Global majors compete with regional champions across compliance certification and latency optimization, producing a tiered structure where hyperscaler economies of scale face sovereign cloud specialization. The vendor base organizes around three archetypes: hyperscale platform operators with region-dense footprints, hybrid cloud orchestrators bridging on-premises hardware with public consumption, and sovereign specialists emphasizing data residency controls. Dominant competitive moves include strategic partnerships with systems integrators for Mittelstand migration and portfolio diversification into immutable backup with native ransomware detection.
Within the hyperscale tier, Amazon Web Services, Inc., Microsoft Corporation, and Dell Technologies occupy positions that exemplify divergent anchoring strategies. AWS leverages its Northern Virginia region density to secure enterprise contracts requiring sub-10-millisecond access. Microsoft competes through productivity suite integration that sustains organizational switching costs. Dell Technologies represents the hybrid orchestration archetype, positioning its Apex portfolio between legacy hardware estates and elastic cloud consumption to capture margin-rich workloads governed by GDPR and SEC disclosure constraints.
| Leading Market Players |
|---|
| Amazon Web Services, Inc. |
| Microsoft Corporation |
| Google LLC |
| IBM Corporation |
| Dell Technologies |
| Hewlett Packard Enterprise |
| Rackspace Technology |
| NetApp |
| Oracle Corporation |
| Others |
Supply & Pricing Matrix
EU AI Act data lineage mandates gate qualified supply and premium-tier pricing access, forcing providers to certify automated metadata capture before contract execution. German industrial buyers pay sovereignty premiums for BSI-validated configurations that hyperscale commodity tiers cannot match.
Pricing Analysis
Warranty bundling separates premium sovereign tiers from unbundled hyperscale consumption, with GDPR-compliant audit logging and encryption key escrow included only at upper pricing levels. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification depth and residency control granularity. Cost compression in standard tiers intensifies because hyperscaler capacity buildouts in Northern Virginia compress unit economics. Healthcare providers in the United States exhibit lowest price sensitivity due to HIPAA technical safeguard non-negotiability, while German Mittelstand manufacturers negotiate hardest on total cost of ownership.
Supply Chain Analysis
Reverse-logistics flows for decommissioned storage arrays and key-escrow hardware refurbishment create secondary supply channels for cost-sensitive sovereign cloud deployments. Component manufacturing concentrates in Taiwan, South Korea, and China for NAND flash and controller silicon. Supply chain risk hinges on single-source vulnerability for advanced encryption processors validated under FIPS 140-3 and BSI regimes. Distribution runs through hyperscaler-operated data center campuses in Northern Virginia, Frankfurt, and Singapore, with regional systems integrators handling Mittelstand migration services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a vertical-integration race where control over encryption processor supply and sovereign data center real estate determines margin capture. Players are pursuing backward integration into certified hardware manufacturing to escape hyperscaler commodity pricing.
For Market Incumbents: To counter hyperscaler price compression in standard storage tiers, incumbents must deepen control over sovereign cloud hardware supply chains and acquire regional compliance certification capabilities. Capacity addition in Frankfurt and Singapore data center districts secures GDPR and MAS-regulated contract access. Investment in automated metadata capture infrastructure addresses EU AI Act pre-contractual verification requirements.
For New Entrants and Emerging Players: German automotive suppliers with legacy SAN infrastructure represent the most penetrable buyer archetype for hybrid cloud orchestration services. Edge-to-core pipeline integration for 5G MEC nodes offers second white-space entry. Go-to-market execution should route through Mittelstand-focused systems integrators with established BSI audit relationships.
For Investors and Strategic Acquirers: Pre-contractual compliance verification delays by German state data protection authorities are the leading indicator that sovereign cloud specialization will command sustained pricing power. Acquisition targets should display hybrid orchestration software stacks paired with certified regional data center presence. Monitor BSI technical guideline updates for encryption standard fragmentation signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification Investment | BSI-validated configurations unlock GDPR-governed Mittelstand procurement budgets in Germany. |
| Hybrid Orchestration Platform Launch | Policy-driven data placement captures margin-rich workloads escaping hyperscale commoditization. |
| Immutable Backup Service Introduction | Native ransomware detection addresses SEC cybersecurity disclosure requirements for financial services. |
| Edge-to-Core Pipeline Partnership | 5G MEC integration with centralized object tiers enables Singapore telecommunications operator contracts. |
| Key Escrow Hardware Manufacturing Scale-Up | FIPS 140-3 validated component production reduces dependency on single-source encryption processor suppliers. |
Research Methodology
SEC cybersecurity disclosure filings, EU AI Act implementation guidance, and hyperscaler capital expenditure disclosures formed the secondary backbone of this analysis. Primary interviews with cloud procurement officers at German automotive suppliers, HIPAA compliance leads at United States health systems, and sovereign cloud architects at European telecommunications operators combined with secondary validation across deployment model, service type, end-user industry, and regional regulatory cluster dimensions. Bottom-up capacity installation tracking and top-down enterprise IT spending analysis provided triangulation.
Historical trendline analysis examined storage infrastructure investment patterns across the analysis window. Segmentation modeling incorporated deployment architecture, service abstraction layer, vertical compliance requirements, and consumption economics. CAGRs derived from elasticity-adjusted capacity demand curves and sovereign premium pricing differentials. Forecast inputs included genomic sequencing pipeline data volume projections and EU AI Act enforcement timeline assumptions.
Revisions become necessary when BSI encryption guideline updates, SEC disclosure rule amendments, or hyperscaler regional capacity expansion announcements materialize differently than modeled. Practitioners should monitor German state data protection authority procurement authorization timelines and Northern Virginia data center permitting activity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Consumer Cloud Storage Services Market
Storage Solutions
Network Attached Storage (NAS) Market
Storage Solutions
Network File System Market
Storage Solutions
UK Data Center Storage Market
Storage Solutions
United Arab Emirates Data Center Storage Market
Storage Solutions
Indonesia Data Center Storage Market
Storage Solutions
Enterprise File Sync and Share Platform Market
Storage Solutions
Multi Cloud Storage Market
Storage Solutions
Vietnam Data Center Storage Market
Storage Solutions
Asia Pacific Automated Storage and Retrieval System Market
Storage Solutions
Philippines Data Center Storage Market
Storage Solutions
Stand Alone Cloud Storage Market
Storage Solutions
New Zealand Data Center Storage Market
Storage Solutions
Automated Storage and Retrieval Systems in Laboratories Market
Storage Solutions
Europe in-Memory Database Market
Storage Solutions
Cloud Object Storage Solutions Market