
 Indonesia Data Center Storage Market | 2026-2036
Indonesia Data Center Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Data Center Storage Market Insights
Domestic colocation providers in Greater Jakarta is pivoting toward flash-intensive architectures to serve financial services tenants. Dell Technologies leverages its direct sales presence across Southeast Asian hubs to sustain enterprise relationships. Huawei Technologies anchors government and telecom contracts through localized assembly and support infrastructure. NetApp competes on software-defined storage orchestration for hybrid cloud deployments.
Indonesia data center storage encompasses electromechanical and solid-state systems engineered for persistent data retention in climate-controlled facilities, typically operating within temperature bands of 18°C to 27°C per ASHRAE guidelines, with redundancy tiers spanning N+1 to 2N configurations. SSD deployments command premium positioning among banking end users seeking sub-millisecond latency for real-time payment processing, while HDD arrays retain dominance in archival and backup workloads where cost-per-terabyte governs procurement. Cloud storage technology is expanding fastest as domestic enterprises migrate from captive server rooms to managed service environments.
BIS certification requirements and TRAI data localization directives compel foreign suppliers to establish in-country assembly or partnership structures before qualifying for public sector tenders. The country's national pharmaceutical regulator and central bank frameworks indirectly amplify storage demand through mandated record retention periods for transaction logs and patient data. Stakeholders must weigh sovereign compliance obligations against total cost of ownership when selecting between imported all-flash systems and locally integrated hybrid platforms.
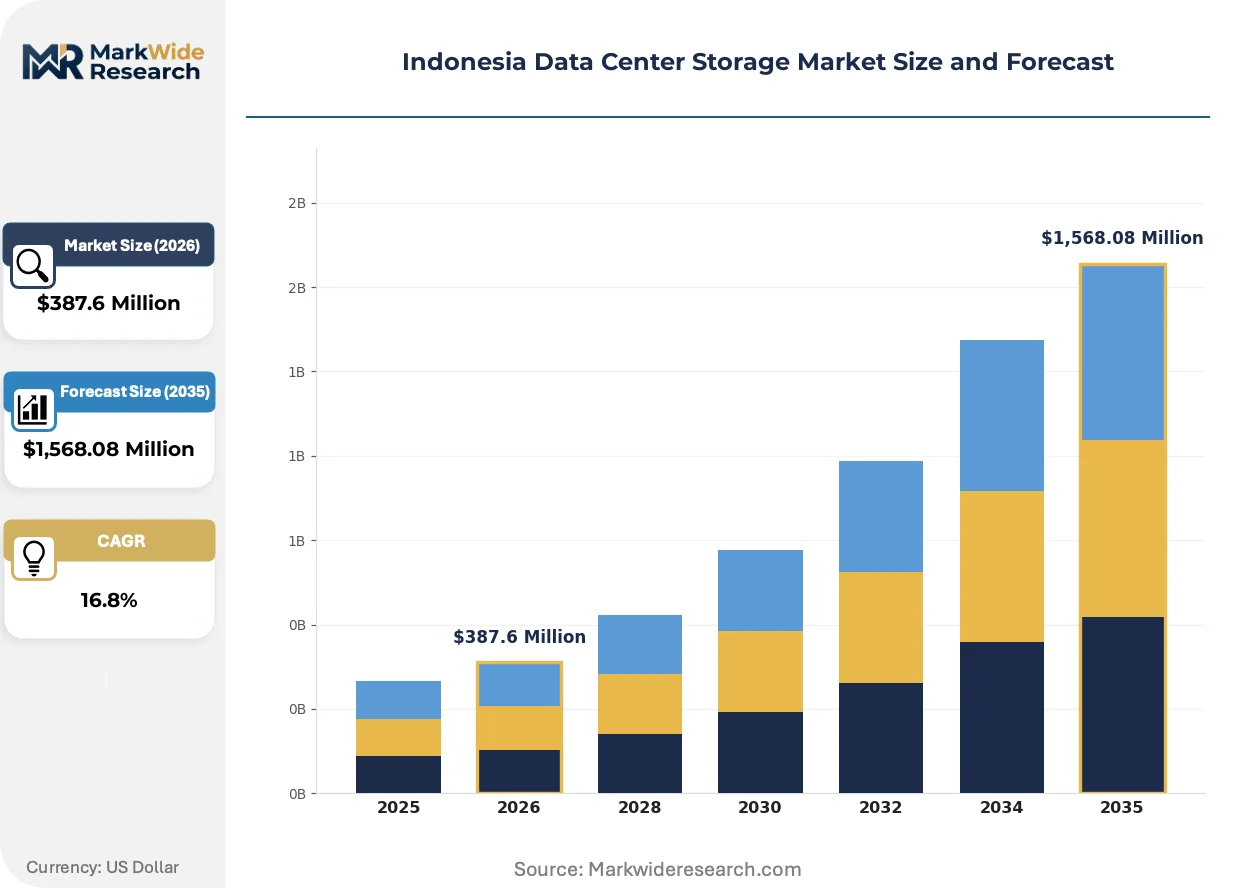
Market Dynamics
Flash storage arrays are compressing latency benchmarks across Indonesian financial services, forcing incumbent HDD suppliers to reposition toward archival tiers while BIS certification timelines reshape vendor qualification cycles.
Growth Catalysts
- Data Localization Mandates:TRAI directives on data sovereignty require foreign cloud operators to store transaction records within national borders, directly expanding domestic storage infrastructure requirements.
- E-commerce Transaction Volumes:Indonesian marketplace platforms are scaling petabyte-class storage clusters to process real-time payment settlements and inventory synchronization across archipelago logistics networks.
- Submarine Cable Landing Zones:Hyperscale facility construction concentrates in Batam and Greater Jakarta proximity to SEA-ME-WE and IGG cable systems, reducing latency to Singapore and Hong Kong financial hubs.
Market Restraints
- NAND Flash Price Volatility:Memory chip spot markets exhibit cyclical swings that compress gross margins for all-flash array deployments in cost-sensitive enterprise segments.
- Imported Equipment Duty Structures:Indonesian customs classifications impose non-tariff barriers on fully assembled storage systems, elevating landed costs versus locally integrated alternatives.
- Power Infrastructure Gaps:Outside Greater Jakarta, grid reliability fluctuations necessitate oversized UPS and generator investments that inflate total facility cost structures.
Strategic Opportunities
- Eastern Indonesia Expansion:Makassar and Manado present underdeveloped colocation markets where first-mover hyperscale construction could capture latency-sensitive content distribution workloads.
- AI Training Cluster Demand:GPU-intensive machine learning pipelines require high-throughput NVMe storage fabrics that command premium pricing versus general-purpose enterprise arrays.
- Green Building Certifications:Indonesia's national energy efficiency standards create procurement preference for liquid-cooled storage systems that reduce PUE ratios in tropical operating conditions.
Industry Challenges
- Certification Timeline Compression:BIS type-approval processes for imported storage hardware extend 4-6 months, delaying revenue recognition for vendors competing against locally assembled alternatives.
- Legacy Tape Migration Complexity:Government archives and banking institutions maintain decades of magnetic tape records requiring specialized retrieval infrastructure during hybrid cloud transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Data Center Storage Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,568.08 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HDD, SSD, Hybrid, Tape Technology: Cloud Storage, On-Premises, Virtualization, Blockchain Form Factor: Rack-Mount, Tower, Blade, Modular End User: Banking, Healthcare, E-Commerce, Government |
| Companies Covered | Dell Technologies, Hewlett Packard Enterprise (HPE), Huawei Technologies, NetApp, IBM Corporation, Hitachi Vantara, Cisco Systems, Lenovo, DCI Indonesia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Data Center Storage Market Trends and Innovations
Computational storage architectures and sovereign compliance frameworks are restructuring how Indonesian enterprises evaluate total cost of ownership across on-premise and managed service environments.
NVMe-over-Fabrics is rewriting storage access patterns by enabling remote solid-state arrays to match local direct-attached latency profiles. Banking payment switch operators in Jakarta are deploying these fabrics for real-time clearing systems. The technology is compressing the traditional boundary between server and storage hardware procurement decisions.
BIS certification amendments now mandate electromagnetic compatibility testing for all data center equipment classes entering public sector tenders. This regulatory friction favors domestic integrators with established testing relationships over direct-import vendors. Foreign suppliers are responding by establishing local assembly partnerships to compress qualification cycles.
Consumption-based storage contracts are displacing traditional capital purchase models among mid-market Indonesian enterprises. Managed service providers in Greater Jakarta are unbundling hardware ownership from operational support, transferring refresh risk to vendor balance sheets. This pattern is most visible in retail and logistics verticals with seasonal demand volatility.
Indonesia Data Center Storage Market Segmentation
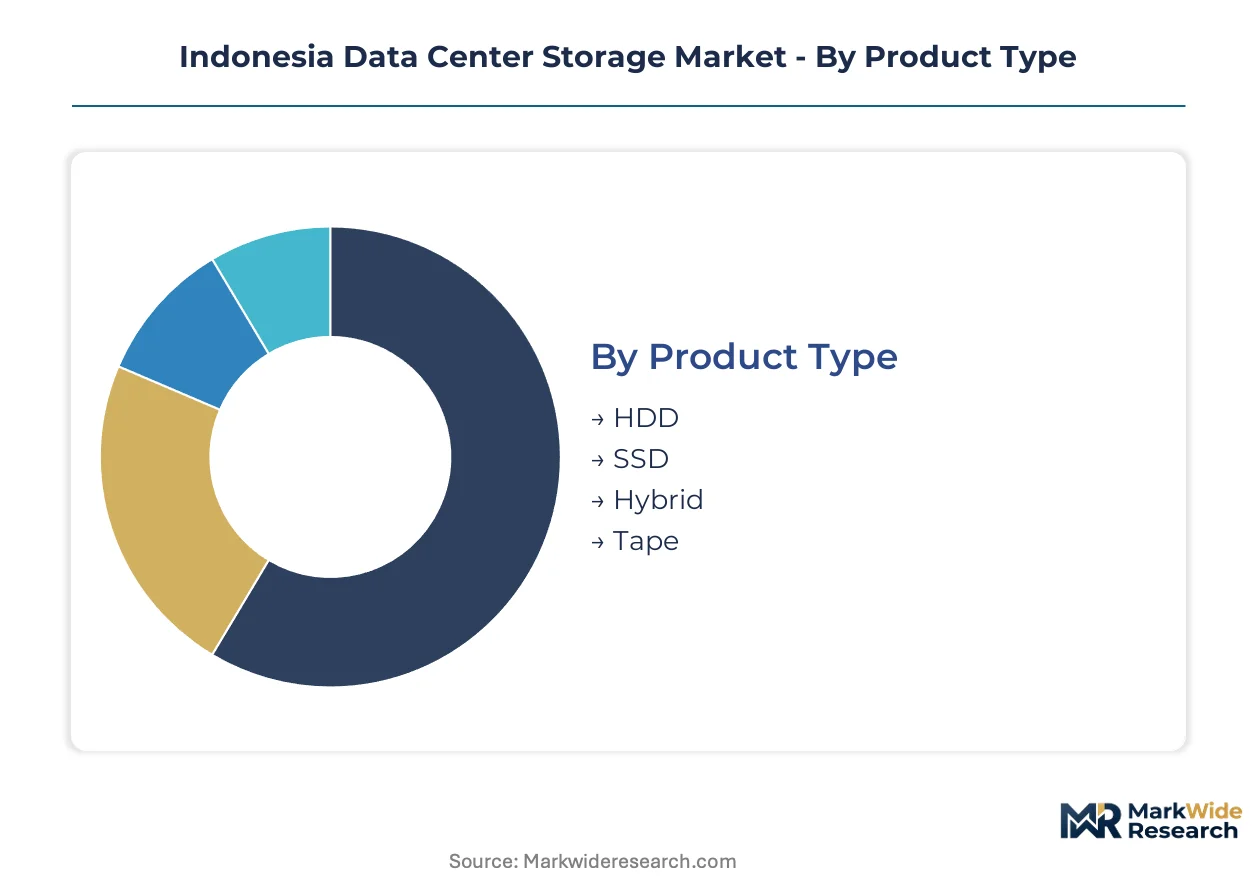
Storage procurement patterns across Indonesian enterprises diverge sharply by workload latency requirements, compliance exposure, and infrastructure ownership models. Understanding these segment boundaries clarifies why HDD arrays dominate archival budgets while flash systems command premium positioning in financial services.
Product Type:
Cost-per-terabyte sensitivity separates buyers optimizing for capacity density from those prioritizing access speed.
- HDD:Electromechanical platters deliver multi-terabyte capacity at the lowest acquisition cost per gigabyte. State-owned enterprises and media archives in Greater Jakarta specify these arrays for regulatory-mandated retention periods exceeding seven years.
- SSD:NAND-based solid-state architectures eliminate mechanical latency, achieving sub-millisecond response times critical for real-time payment processing. Banking payment switches in Jakarta's central business district deploy these exclusively for transactional databases.
- Hybrid:Tiered architectures combine flash caching layers with HDD backplanes, balancing performance and economics for mid-market enterprises migrating from captive server rooms.
- Tape:Linear magnetic storage retains dominance in offline vault scenarios where air-gapped compliance and decades-long retention override retrieval speed requirements.
Volume sits with HDD; growth tilts toward SSD.
Technology:
Infrastructure control preferences—capex retention versus opex transfer—determine deployment architecture selection.
- Cloud Storage:Third-party managed environments abstract hardware ownership, appealing to e-commerce platforms with volatile seasonal demand. Consumption-based billing aligns costs with transaction volume fluctuations across archipelago logistics networks.
- On-Premises:Captive facilities within enterprise-owned buildings satisfy BIS certification requirements for sensitive government and financial workloads. Direct hardware control supports customized encryption and audit trail implementations.
- Virtualization:Software-defined abstraction pools heterogeneous storage assets into unified resource layers, enabling multi-tenant colocation providers to optimize utilization across disparate client workloads.
- Blockchain:Distributed ledger implementations impose immutable write-once requirements, driving specialized storage configurations for notarization and supply chain provenance applications.
On-Premises retains the largest installed base; Cloud Storage is climbing the fastest.
Form Factor:
Facility power density and floor loading constraints shape physical chassis selection.
- Rack-Mount:Standardized 19-inch enclosures dominate hyperscale facilities in Batam and Greater Jakarta, maximizing vertical space utilization within raised-floor environments.
- Tower:Freestanding configurations serve edge deployments and smaller enterprise server rooms where dedicated rack infrastructure remains uneconomical.
- Blade:High-density modular designs integrate compute and storage within shared chassis, reducing cabling complexity for GPU-intensive AI training clusters.
- Modular:Containerized and micro-data-center formats address rapid deployment scenarios in Eastern Indonesia where permanent facility construction timelines exceed business requirements.
Rack-Mount captures current volume; Modular formats are gaining share fastest in frontier geographies.
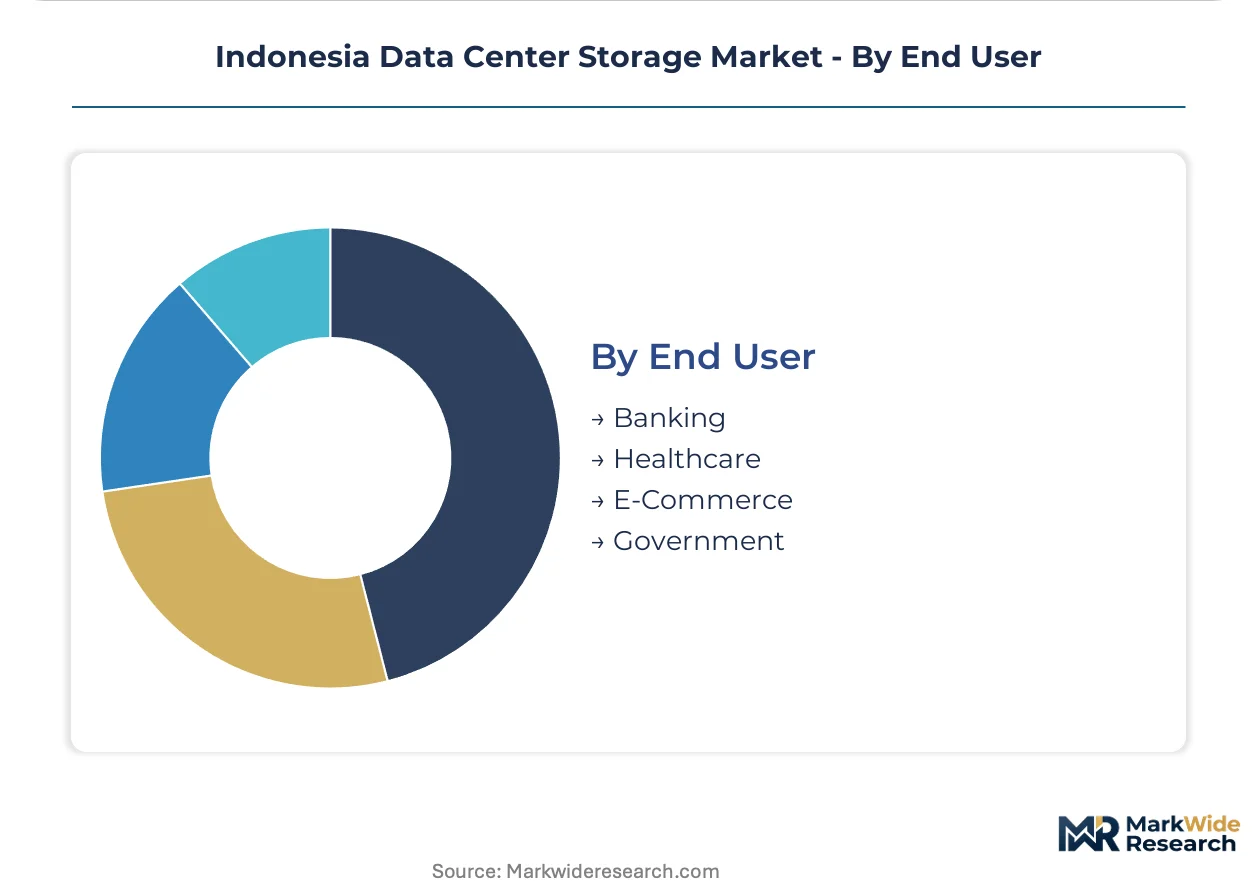
End User:
Regulatory intensity and transaction velocity create divergent storage performance requirements.
- Banking:Real-time gross settlement systems and anti-money-laundering databases mandate all-flash latency profiles. The central bank's transaction log retention rules amplify capacity requirements beyond raw transaction volume.
- Healthcare:Patient imaging archives and electronic medical record systems balance fast retrieval for active cases against cost-optimized cold storage for historical records. The national pharmaceutical regulator's data integrity standards govern procurement specifications.
- E-Commerce:Marketplace platforms synchronize inventory across fragmented logistics networks, requiring elastic capacity scaling during promotional events.
- Government:Citizen identity systems and tax administration databases operate under sovereign data mandates that restrict cross-border replication and favor domestically assembled hardware.
Banking commands premium pricing per terabyte; E-Commerce is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Nickel mining corridors in Sulawesi and Maluku underpin Indonesia's data center buildout through captive power generation and industrial zone development. The archipelago's storage demand clusters along submarine cable landing points where latency to Singapore financial hubs determines facility economics. Regulatory fragmentation across provincial jurisdictions complicates nationwide infrastructure deployment.
Greater Jakarta
Financial services and hyperscale cloud operators dominate storage procurement in the capital region. BIS certification requirements for public sector tenders favor locally integrated hardware over direct imports. Cibitung and Cikarang industrial zones host the densest concentration of Tier III facilities serving banking payment switches.
Batam
Free Trade Zone status and proximity to SEA-ME-WE cable landings attract submarine cable operators and content delivery networks. TRAI data localization directives compel foreign platforms to maintain in-country replication nodes here. Nagoya and Batam Center districts concentrate modular data center deployments for rapid scaling.
Surabaya
East Java's logistics and manufacturing base generates transactional data volumes requiring edge storage architectures. The central bank's regional clearing operations mandate sub-millisecond latency for interbank settlement systems. Rungkut and Gresik industrial corridors see rising colocation demand from e-commerce fulfillment networks.
Bandung
West Java's technology education ecosystem feeds system integration talent into enterprise storage deployments. Local government smart city initiatives drive mid-scale hybrid cloud procurement from domestic service providers. Dago and Buah Batu districts cluster software-defined storage development labs.
Makassar
Eastern Indonesia's underserved status creates first-mover opportunities for latency-sensitive content distribution infrastructure. The national broadband program's submarine cable extensions reduce reliance on satellite backhaul for Sulawesi and Maluku connectivity. Tanjung Bunga and industrial zones near Sultan Hasanuddin Airport attract exploratory hyperscale site assessments.
Indonesia Data Center Storage Market Competitive Landscape
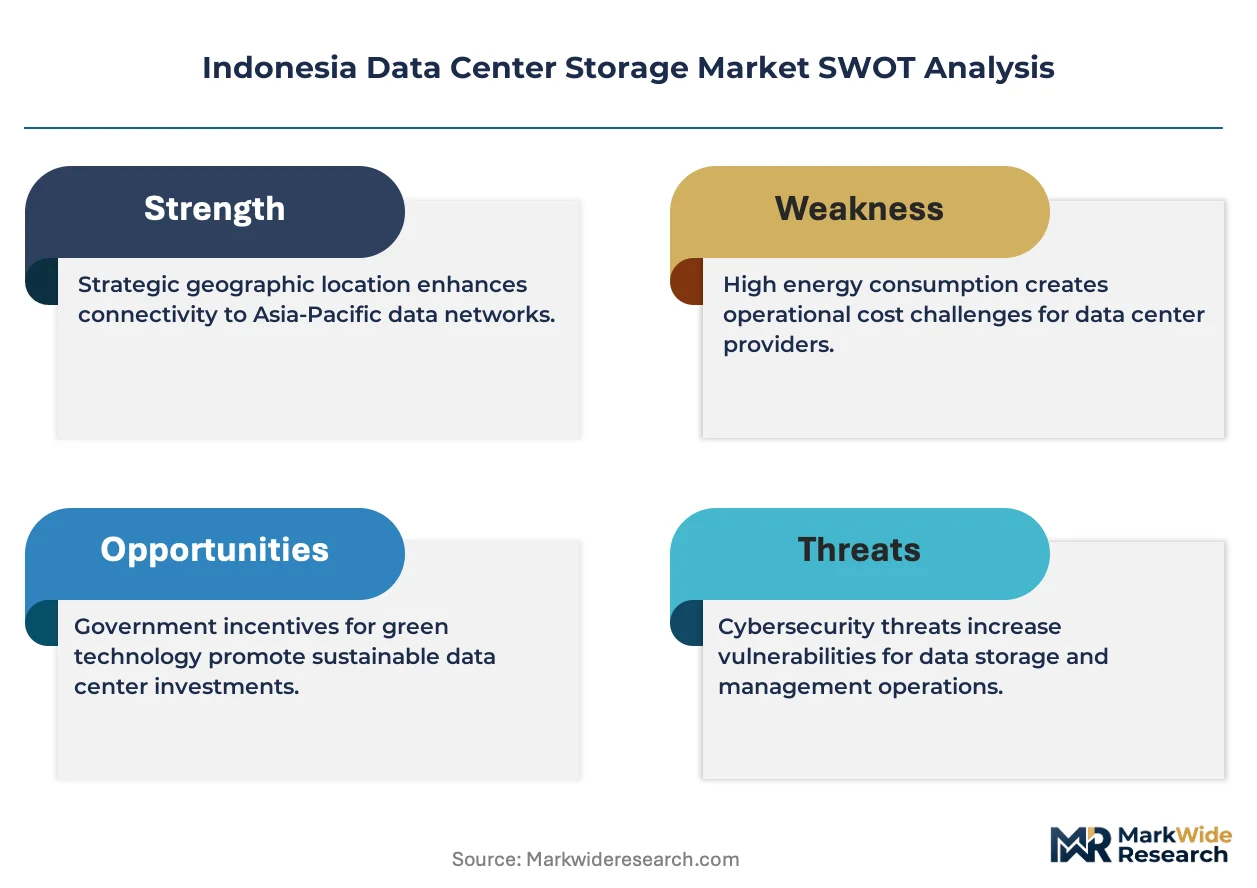
Global majors compete with regional champions across certification compliance and localized support infrastructure. The vendor landscape splits between direct-import premium brands and domestic assembly partnerships that compress BIS approval timelines. Three archetypes dominate: integrated technology conglomerates with government relationships, pure-play storage specialists competing on software differentiation, and local system integrators bridging foreign hardware with in-country service capabilities. Competitive moves center on local assembly joint ventures to circumvent import duty structures and consumption-based contract models that transfer refresh risk to vendor balance sheets.
Within the integrated technology tier, Dell Technologies and Huawei Technologies anchor contrasting market positions. Dell leverages its direct sales presence across Southeast Asian hubs to sustain enterprise banking relationships. Huawei secures government and telecom contracts through localized assembly and support infrastructure. NetApp occupies a specialist position competing on software-defined storage orchestration for hybrid cloud deployments. DCI Indonesia represents the domestic integrator archetype, bridging foreign hardware procurement with provincial compliance navigation.
| Leading Market Players |
|---|
| Dell Technologies |
| Hewlett Packard Enterprise (HPE) |
| Huawei Technologies |
| NetApp |
| IBM Corporation |
| Hitachi Vantara |
| Cisco Systems |
| Lenovo |
| DCI Indonesia |
| Others |
Pricing and Supply Chain Analysis
Indonesia's national energy efficiency standards gate qualified supply for data center storage deployments, restricting premium-tier pricing access to vendors with liquid-cooled architectures and green building certifications that satisfy tropical operating requirements. BIS certification timelines and TRAI data localization mandates further segment pricing power between locally integrated hardware and direct-import alternatives.
Pricing Analysis
Warranty and service bundling separate premium from economy tiers, with full lifecycle support contracts commanding substantial markups over bare-metal procurement. Three-tier pricing structure across premium, standard, and economy levels reflects BIS certification status, flash density ratios, and localized assembly depth. Pricing pressure stems from NAND flash spot market cyclicality, compressing margins for all-flash array vendors serving cost-sensitive mid-market enterprises. Banking payment switches demonstrate lowest price sensitivity, prioritizing sub-millisecond latency guarantees over acquisition cost.
Supply Chain Analysis
NAND flash supply rests on fabrication capacity concentrated in South Korea, Taiwan, and Japan, with controller silicon and enterprise SSD assembly anchored in China and Malaysia. Precision cooling components, power distribution units, and chassis materials feed from Thailand, Vietnam, and domestic Indonesian metalworking. Single-source vulnerability runs through advanced node memory wafer supply, where geopolitical friction or natural disruption in Northeast Asia propagates rapidly to Indonesian landed costs. Distribution runs through Singapore logistics hubs into Batam Free Trade Zone, then onward via domestic integrators to Greater Jakarta and Surabaya facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's data center storage sector sits in a technology-transition phase, with NVMe-over-Fabrics and software-defined architectures displacing legacy Fibre Channel and captive HDD deployments across financial services and hyperscale environments.
For Market Incumbents: To counter consumption-based contract models that transfer refresh risk to vendor balance sheets, Dell Technologies and Huawei Technologies should deepen backward integration into local assembly partnerships that compress BIS certification cycles. Incumbents must also anchor government relationships through sovereign-compliant hardware configurations that satisfy TRAI data localization directives for public sector tenders. For New Entrants and Emerging Players: Capture first-mover positioning in Makassar and Manado colocation markets where submarine cable extensions reduce satellite backhaul dependency and latency-sensitive content distribution workloads remain underserved. Eastern Indonesia's infrastructure gap presents the most penetrable geography, with modular data center formats offering rapid deployment without permanent facility construction timelines. For Investors and Strategic Acquirers: DCI Indonesia's expansion into provincial compliance navigation and domestic system integration is the leading indicator that localized service capabilities will command acquisition premiums over pure hardware distribution plays. Long-term viability favors vertically integrated platforms spanning assembly, certification, and managed services, with BIS approval timeline compression serving as the critical inflection signal for vendor competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Local Assembly Partnership | BIS certification timelines compress from 4-6 months to 8-12 weeks for qualifying vendors. |
| NVMe-over-Fabrics Deployment | Jakarta banking payment switches achieve sub-millisecond latency matching direct-attached storage profiles. |
| Consumption-Based Contract Model | Mid-market enterprises transfer hardware refresh risk to vendor balance sheets during cloud migration. |
| Liquid-Cooled Architecture Investment | Premium positioning opens through Indonesia's national energy efficiency standards for tropical data centers. |
| Eastern Indonesia Site Assessment | Makassar and Manado present first-mover capture opportunities for latency-sensitive content distribution. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with data center operators, storage procurement officers at Indonesian banks, colocation facility managers, BIS certification consultants, and subsystem integrators. SEC filings from Dell Technologies and NetApp, hyperscaler capex disclosures, and ASEAN customs databases provided volume triangulation against bottom-up facility buildout tracking across Greater Jakarta and Batam.
Reconciliation of shipment data, import manifests, and enterprise procurement surveys informed the analytical framework across the projection horizon. Segmentation dimensions modeled include storage technology type, deployment architecture, form factor density, and end-user regulatory intensity. CAGRs derived from facility pipeline analysis, enterprise storage refresh cycles, and cloud migration velocity indicators specific to Indonesian e-commerce and financial services verticals.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NAND flash supply disruption, BIS regulatory amendments, and submarine cable capacity expansion timelines. Assumptions underlying projections reflect documented facility commitments, sovereign compliance trajectories, and technology substitution patterns. A small set of named triggers warrants ongoing watch: BIS electromagnetic compatibility testing mandate expansion, TRAI cross-border data flow restrictions, and GPU-intensive AI training cluster procurement acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Poland Data Center Storage Market
Storage Solutions
Europe Data Center Storage Market
Storage Solutions
Storage in Big Data Market
Storage Solutions
Global Enterprise File Sharing and Synchronization (EFSS) Market
Storage Solutions
Copy Data Management Software Market
Storage Solutions
Stand Alone Cloud Storage Market
Storage Solutions
Thailand Data Center Storage Market
Storage Solutions
Data Backup and Recovery Market
Storage Solutions
Disk Based Data Fabric Market
Storage Solutions
Europe in-Memory Database Market
Storage Solutions
Global Cloud Object Storage Market
Storage Solutions
Singapore Data Center Storage Market
Storage Solutions
Enterprise File Sync and Share Platform Market
Storage Solutions
Consumer Cloud Storage Services Market
Storage Solutions
Nigeria Data Center Storage Market
Storage Solutions
Network Attached Storage (NAS) Market