
 New Zealand Data Center Storage Market | 2026-2036
New Zealand Data Center Storage Market Size, Share, and Industry Trends Forecast 2026-2036
New Zealand Data Center Storage Market Insights
Market Context
A chronic shortage of certified data center engineers is unwinding capacity expansion timelines across New Zealand. Dell Technologies leverages its established channel network to dominate enterprise installations in Auckland and Christchurch. Pure Storage differentiates through all-flash arrays targeting financial services workloads. NetApp anchors its position with cloud-connected storage fabrics that bridge on-premises and hyperscaler environments.
Technical Definition and Segment Structure
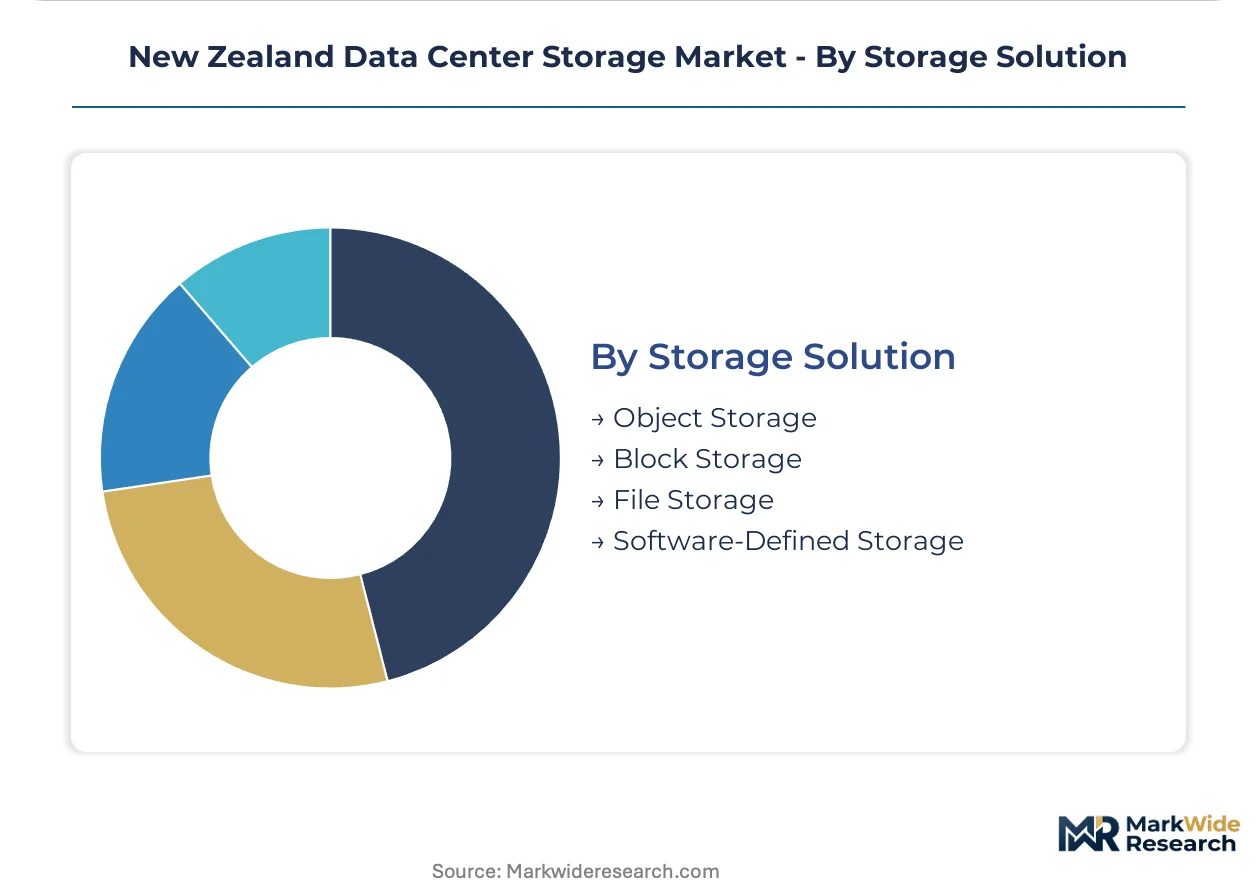
New Zealand Data Center Storage encompasses electromechanical and solid-state systems engineered for capacities from terabyte to petabyte scale, operating at latency thresholds below five milliseconds for primary workloads and serving the core function of persistent data retention for enterprise and cloud computing operations. SSD deployments are capturing margin pools as performance-tier demand accelerates, while HDD retains volume leadership in archival and cold storage tiers. Object storage solutions are expanding fastest among the storage solution categories, driven by unstructured data growth from telecommunications and healthcare end users.
Regulatory Framework and Outlook
The Privacy Act 2020 and Office of the Privacy Commissioner enforcement protocols shape data residency requirements, compelling domestic storage infrastructure investment. BIS and ISO 27001 certification standards govern facility design and operational compliance, raising barriers for uncertified operators. Stakeholders must weigh sovereign cloud mandates against hybrid deployment economics as regulatory scrutiny intensifies.
Market Dynamics
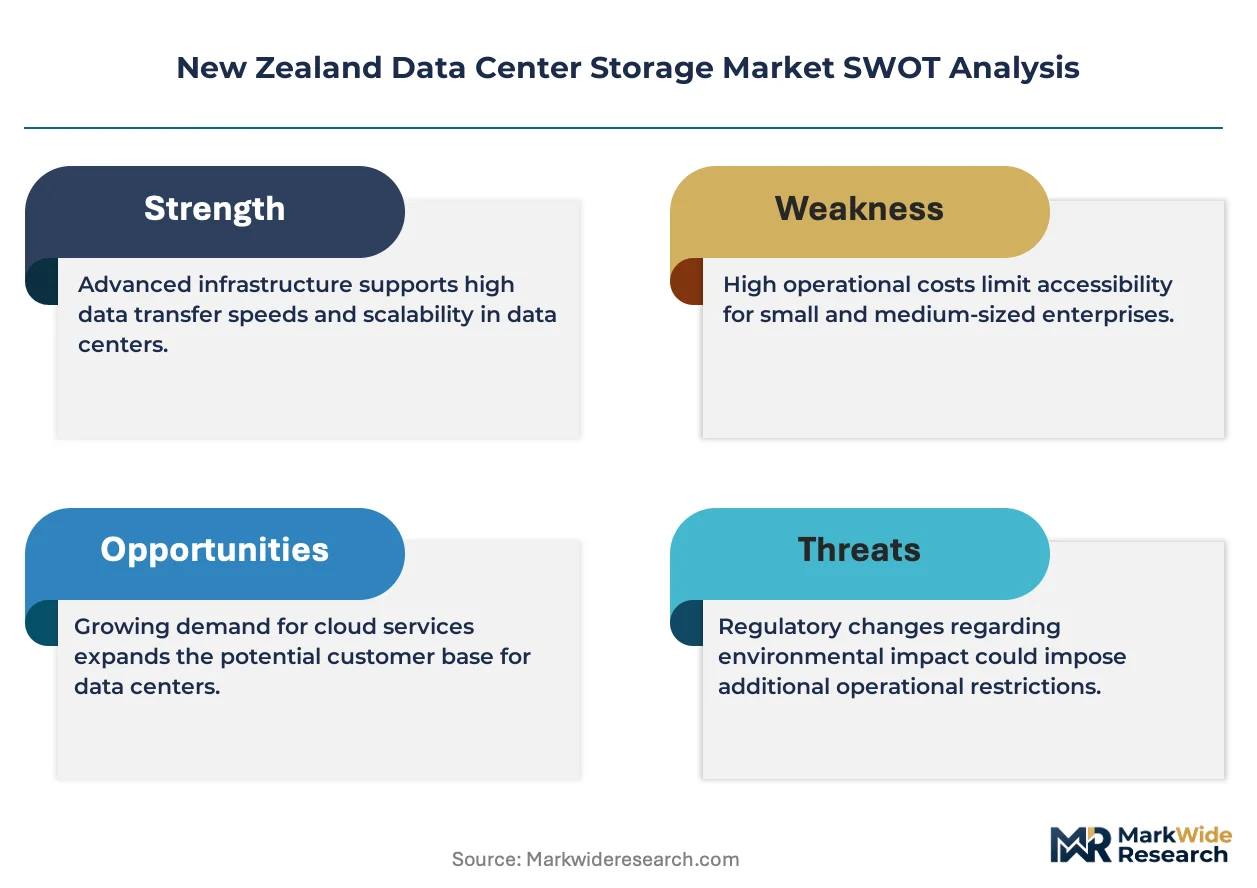
Data sovereignty mandates under the Privacy Act 2020 are forcing domestic infrastructure buildouts faster than local engineering talent pipelines can supply, compressing deployment timelines and inflating labor premiums across Auckland and Wellington facilities.
Growth Catalysts
- Privacy Act 2020 enforcement:The Office of the Privacy Commissioner's strict data residency protocols compel financial institutions and healthcare providers to maintain primary storage within New Zealand borders.
- Telecommunications data proliferation:5G network rollouts and IoT sensor density are generating petabyte-scale unstructured datasets that demand scalable object storage architectures.
- Hyperscaler edge expansion:Cloud service providers are establishing Auckland and Wellington points-of-presence to reduce latency for latency-sensitive enterprise workloads.
Market Restraints
- Specialized engineering scarcity:Certified data center infrastructure engineers command 40-60% wage premiums over general IT roles, inflating operational expenditure baselines.
- Import dependency for solid-state components:NAND flash and controller chips flow through concentrated Asian supply corridors, exposing capacity planning to shipping volatility.
- Power grid constraints:Transpower's transmission bottlenecks in the upper North Island limit hyperscale facility expansion beyond current substation capacities.
Strategic Opportunities
- Canterbury recovery infrastructure:Christchurch's post-earthquake fiber backbone and seismic isolation standards position the region as a secondary disaster recovery cluster.
- Maori data sovereignty frameworks:Iwi-led data governance initiatives are creating demand for culturally auditable storage infrastructure with localized operational control.
- AI/ML training workload migration:GPU-accelerated storage fabrics converging with high-bandwidth networking enable domestic inference and fine-tuning services.
Industry Challenges
- BIS and ISO 27001 certification timelines:Facility accreditation processes stretch 12-18 months, delaying revenue recognition for greenfield developments.
- Legacy storage migration complexity:Financial services institutions operating decades-old tape archives face petabyte-scale data validation and format conversion costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | New Zealand Data Center Storage Market |
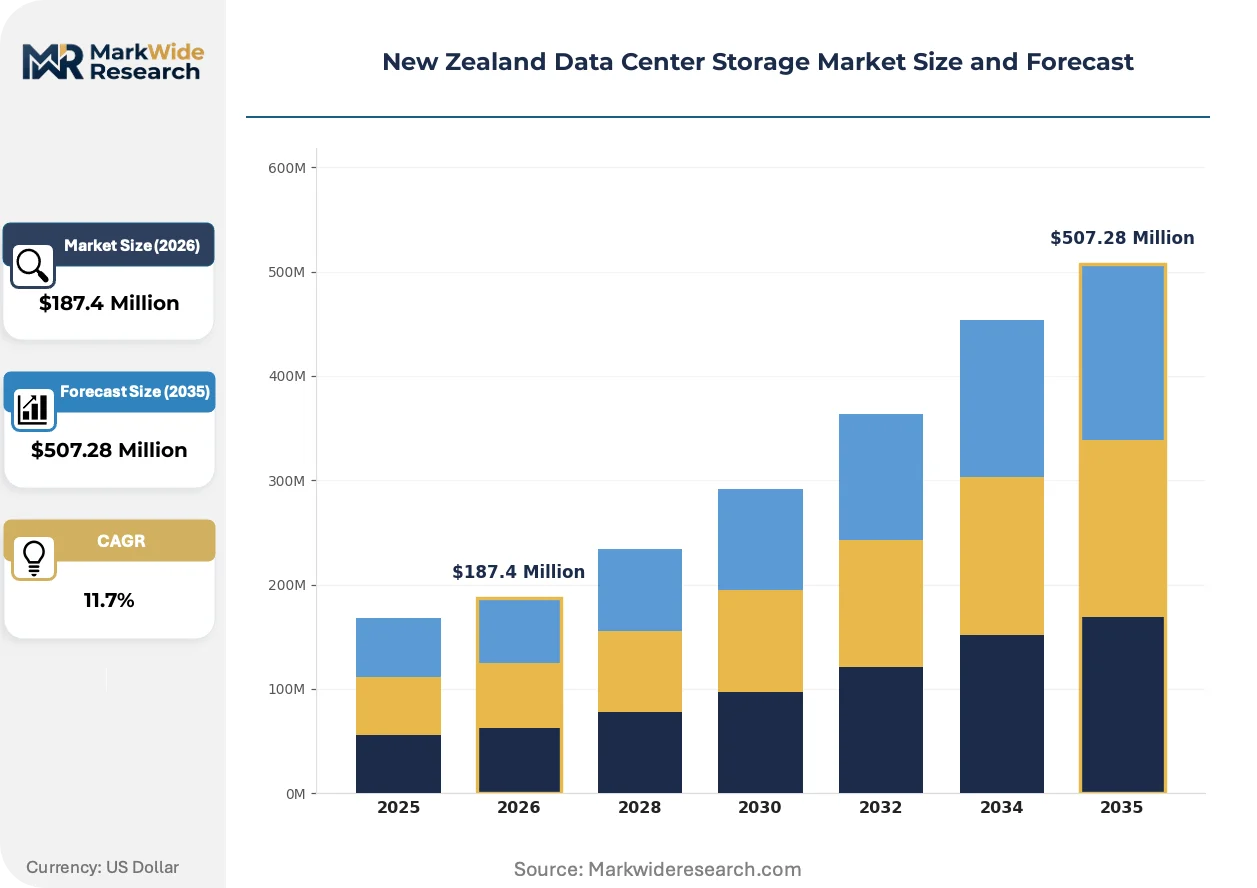
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HDD, SSD, Hybrid Drives, Tape Storage Deployment Model: On-Premises, Cloud, Hybrid, Edge End User: Telecommunications, Financial Services, Healthcare, Education Storage Solution: Object Storage, Block Storage, File Storage, Software-Defined Storage |
| Companies Covered | Dell Technologies, Hewlett Packard Enterprise, NetApp, Pure Storage, Hitachi Vantara, IBM Corporation, Lenovo Group, Fujitsu, Seagate Technology, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
New Zealand Data Center Storage Market Trends and Innovations
Storage architecture decisions in New Zealand are increasingly bifurcated between performance-optimized flash tiers for operational workloads and dense capacity tiers for compliance-mandated retention, with software-defined management layers bridging the divide.
Software-defined storage is fragmenting traditional hardware-centric procurement patterns. Enterprise buyers in Auckland's financial district are deploying disaggregated storage pools across commodity servers. This approach compresses vendor lock-in and enables independent scaling of compute and capacity resources.
The Privacy Act 2020's extraterritorial reach provisions are reshaping cross-border data flow architectures. Multinational enterprises must now maintain physically segregated New Zealand storage estates. Healthcare providers and government agencies are driving demand for sovereign cloud certifications that attest to exclusive domestic data processing.
Consumption-based financing models are displacing capital-intensive storage ownership. Telecommunications operators and mid-market enterprises are adopting managed capacity contracts with local service providers. Wellington-based hosting firms are bundling storage, compute, and network resources into single monthly subscriptions with committed utilization tiers.
New Zealand Data Center Storage Market Segmentation
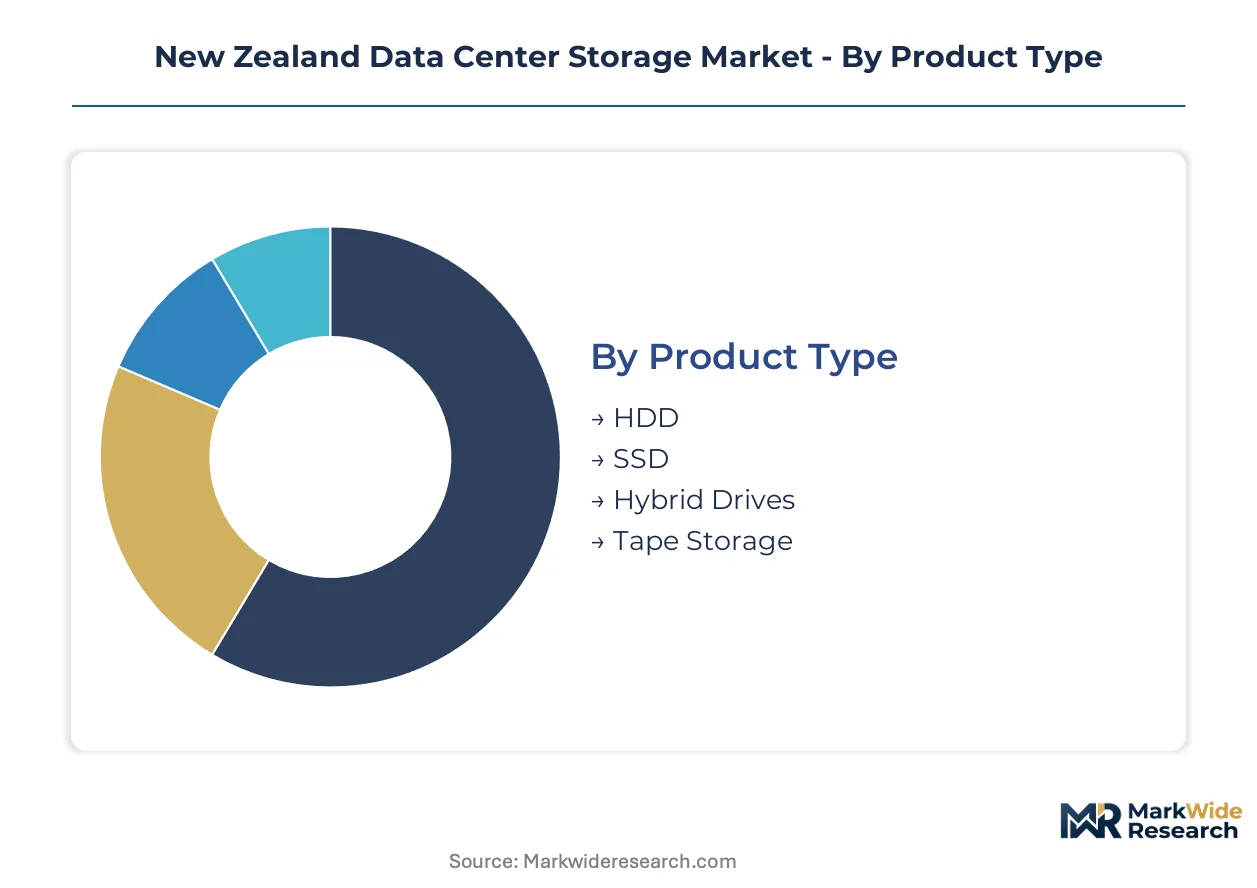
Storage procurement in New Zealand diverges sharply across workload characteristics, with latency requirements and sovereignty mandates creating distinct tier preferences. Segment boundaries are blurring as software-defined layers abstract underlying hardware, yet procurement committees still anchor budgets to physical media classifications and deployment location decisions.
Product Type:
SSD arrays face substitution pressure from emerging storage-class memory and high-density QLC flash, while tape archives confront cloud cold storage economics that challenge retention cost structures.
- HDD:Rotating magnetic media in 3.5-inch and 2.5-inch form factors delivers cost-per-terabyte economics below solid-state alternatives. Auckland hyperscale operators and Wellington government data lakes deploy high-capacity helium-filled drives for archival tiers, constrained by Transpower grid limitations that favor denser rack configurations over power-hungry flash alternatives.
- SSD:NAND flash arrays with NVMe interfaces achieve sub-millisecond latency for transactional databases and virtualized infrastructure. Canterbury financial services clusters specify enterprise-grade SSDs for trading platforms, driven by Reserve Bank operational resilience guidelines mandating recovery point objectives under five minutes.
- Hybrid Drives:Conventional hard disk drives with integrated NAND cache tiers accelerate boot sequences and frequently accessed files without full solid-state cost structures. Education sector procurement in Otago and Southland favors these configurations for budget-constrained server refreshes.
- Tape Storage:Linear Tape-Open and enterprise tape formats provide air-gapped backup for ransomware protection and long-term compliance retention. Healthcare providers in Waikato maintain tape libraries for patient record archives exceeding seven-year statutory requirements.
HDD retains volume leadership across petabyte-scale deployments; SSD holds the steepest expansion curve as financial services accelerate all-flash consolidation.
Deployment Model:
Cost tier stratification separates capital-intensive on-premises builds from operational expenditure cloud contracts, with hybrid architectures capturing margin from enterprises seeking workload portability without full migration.
- On-Premises:Dedicated storage infrastructure within enterprise-owned or colocation facilities. North Island telecommunications carriers maintain on-premises arrays for core network functions, constrained by Privacy Act 2020 data residency verification requirements that complicate audit trails for off-site processing.
- Cloud:Storage resources provisioned from hyperscale providers with Auckland and Wellington points-of-presence. Mid-market enterprises in Tauranga and Hamilton adopt cloud object storage for backup and development environments, eliminating capital commitment and facility management overhead.
- Hybrid:Orchestrated storage pools spanning on-premises and cloud tiers with policy-driven data placement. Auckland financial institutions deploy hybrid configurations to retain sensitive customer data locally while bursting analytics workloads to cloud compute.
- Edge:Distributed storage nodes positioned close to data generation sources for latency reduction and bandwidth conservation. 5G network operators deploy edge storage clusters in Christchurch and Dunedin for real-time video analytics and IoT stream processing.
On-premises deployments anchor revenue concentration among established enterprises; hybrid configurations are gaining share fastest as sovereignty-conscious buyers seek architectural flexibility.
End User:
Application-specific performance requirements segment demand, with telecommunications and financial services driving divergent specifications around throughput versus durability.
- Telecommunications:Network operators generating petabyte-scale call detail records, subscriber data, and content delivery logs. Spark and Vodafone NZ specify scalable object storage for 5G infrastructure, with Auckland and Wellington metro fiber enabling low-latency replication between primary and disaster recovery sites.
- Financial Services:Banks, insurers, and payment processors subject to Reserve Bank prudential standards and Financial Markets Authority conduct regulations. ASB, BNZ, and ANZ NZ maintain tiered storage with synchronous mirroring for trading systems, driven by mandatory recovery time objectives and audit trail preservation.
- Healthcare:District health boards and private providers managing electronic medical records and diagnostic imaging. Canterbury DHB and Auckland DHB deploy PACS storage with lifecycle policies that migrate studies to lower-cost tiers after clinical review periods.
- Education:Universities and polytechnics supporting research computing and administrative systems. University of Auckland and Victoria University of Wellington operate research data repositories with tape integration for grant-mandated retention periods.
Telecommunications retains volume leadership; financial services holds the steepest expansion curve as regulatory data retention periods extend.
Storage Solution:
Customer type segmentation separates enterprises seeking turnkey appliances from cloud-native organizations demanding API-driven provisioning and consumption billing.
- Object Storage:Flat namespace architectures addressing unstructured data at exabyte scale with erasure-coded durability. Telecommunications operators and media companies in Auckland deploy object stores for video archives and analytics datasets, replacing legacy file hierarchies that fragment at scale.
- Block Storage:Raw volume presentation to operating systems with Fibre Channel or iSCSI connectivity. Financial services database clusters in Wellington specify all-flash block arrays for OLTP workloads, constrained by BIS certification requirements that delay new vendor qualification.
- File Storage:Hierarchical namespace access via NFS or SMB protocols for user directories and application shares. Education and healthcare IT departments maintain NAS appliances for home directories and departmental collaboration, with capacity scaling through clustered configurations.
- Software-Defined Storage:Decoupled control and data planes enabling commodity hardware deployment with enterprise feature sets. Canterbury technology firms and Wellington SaaS providers adopt Ceph and VMware vSAN to avoid proprietary lock-in and align storage costs with compute refresh cycles.
Block storage retains volume leadership among legacy enterprise workloads; object storage holds the steepest expansion curve as unstructured data generation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center storage deployment patterns across New Zealand diverge sharply between the latency-sensitive financial corridors of the upper North Island and the disaster recovery-oriented infrastructure emerging in the South Island's rebuilt urban centers.
Auckland Region
Auckland concentrates hyperscale cloud points-of-presence and enterprise primary storage for financial services. The Privacy Act 2020's data residency mandates compel ASB, BNZ, and ANZ NZ to maintain sovereign storage estates within Auckland metro fiber rings. Spark and Vodafone NZ operate petabyte-scale object storage clusters in Silverdale and Albany for 5G network analytics.
Wellington Region
Wellington anchors government and telecommunications storage demand with sovereign cloud certifications driving procurement. The Office of the Privacy Commissioner maintains enforcement protocols that require physically segregated infrastructure for agencies handling citizen data. Datacom and Catalyst Cloud operate tier-III facilities in the Hutt Valley with seismic isolation standards exceeding national building codes.
Canterbury Region
Christchurch's post-earthquake fiber backbone positions Canterbury as New Zealand's secondary disaster recovery cluster. The 2010-2011 seismic events catalyzed investment in redundant substations and diverse fiber paths that now attract financial services failover infrastructure. Canterbury District Health Board deploys PACS storage with synchronous replication to Auckland for patient record resilience.
Waikato Region
Waikato supports healthcare and agricultural research storage demand with lower-cost land and power relative to Auckland. District health boards in Hamilton maintain tape libraries for seven-year statutory retention of patient records. AgResearch and Waikato University operate research data repositories with grant-mandated retention periods exceeding a decade.
Otago and Southland
The southernmost regions concentrate education sector storage with budget-constrained procurement patterns favoring hybrid drive configurations. University of Otago operates research data infrastructure with tape integration for long-term dataset preservation. Polytechnics in Invercargill and Dunedin refresh server infrastructure on extended cycles, prioritizing capital efficiency over performance tiering.
New Zealand Data Center Storage Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with Dell Technologies leveraging channel density to dominate enterprise installations while Pure Storage and NetApp occupy distinct performance and cloud-connectivity niches. The market structure rewards established vendor relationships given BIS and ISO 27001 certification timelines that stretch 12-18 months for new equipment qualification. Three archetypes predominate: full-stack infrastructure vendors with services arms, all-flash performance specialists, and cloud-connected fabric providers. Competitive dynamics center on strategic partnerships with local systems integrators and portfolio diversification into consumption-based financing models.
Among the integrated infrastructure tier, Dell Technologies and Hewlett Packard Enterprise exemplify full-stack providers with established channel networks spanning Auckland and Christchurch. NetApp occupies a position within the cloud-connected fabric archetype, bridging on-premises and hyperscaler environments. Pure Storage represents the performance-specialist vector with all-flash arrays targeting financial services workloads. These three anchors demonstrate how vendor selection in New Zealand tracks certification heritage and local engineering support density rather than pure technology differentiation.
| Leading Market Players |
|---|
| Dell Technologies |
| Hewlett Packard Enterprise |
| NetApp |
| Pure Storage |
| Hitachi Vantara |
| IBM Corporation |
| Lenovo Group |
| Fujitsu |
| Seagate Technology |
| Others |
Pricing and Supply Chain Analysis
BIS and ISO 27001 certification standards gate both vendor qualification timelines and price differentiation across New Zealand data center storage procurement, compressing margins for uncertified challengers while enabling incumbent premium capture through audit-ready heritage.
Pricing Analysis
Long-term managed capacity contracts dominate enterprise procurement, displacing capital-intensive ownership models across Auckland financial services and Wellington government estates. Price differentiation rests on certification tier and local engineering support density, with certified integrators commanding 25-40% premiums over hardware-only suppliers. Cost compression in mid-market hybrid configurations is intensifying because telecommunications operators aggregate demand through consolidated procurement vehicles. Education and regional healthcare buyers exhibit highest price sensitivity, while Reserve Bank-regulated financial institutions prioritize operational resilience over unit economics.
Supply Chain Analysis
Inventory lead times for NAND flash and enterprise HDDs stretch 16-24 weeks through concentrated Asian supply corridors, exposing New Zealand capacity planning to shipping volatility and customs processing variability. Component flows draw from Taiwan, South Korea, and China for solid-state controllers and memory modules, with Malaysia and Thailand contributing assembly and testing operations. Single-source vulnerability concentrates in advanced NAND fabrication, where geopolitical friction threatens supply continuity. Distribution runs through Auckland-based systems integrators and direct hyperscale channels, with Christchurch emerging as a secondary logistics node for South Island deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
New Zealand data center storage represents a service-attach opportunity where managed capacity and lifecycle support contracts expand faster than underlying hardware shipments, rewarding vendors who bundle operational expertise with infrastructure.
For Market Incumbents: Shield certification heritage through accelerated BIS requalification cycles that outpace emerging software-defined challengers. Deepen vertical integration into Wellington and Auckland field engineering pools to offset 40-60% wage premiums eroding margin structures. Anchor enterprise relationships with consumption-based financing models that lock in multi-year recurring revenue against hyperscaler encroachment. For New Entrants and Emerging Players: Lead with sovereign cloud certifications targeting Maori data sovereignty frameworks and iwi-led governance initiatives where cultural auditability requirements exceed incumbent capabilities. Canterbury disaster recovery clusters present the most penetrable geography, with post-earthquake fiber infrastructure attracting financial services failover demand underserved by Auckland-centric vendors. Position through managed service wrappers rather than hardware-centric procurement to bypass 12-18 month certification barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from telecommunications carrier infrastructure divisions spinning out colocation and storage assets as core network virtualization accelerates. Long-term viability hinges on recurring revenue attachment rates exceeding 60% of total contract value. Monitor Reserve Bank operational resilience guideline revisions as the critical inflection signal, with extended recovery time objective mandates expanding addressable market for certified domestic operators.| Strategic Initiative | Industry Significance |
|---|---|
| Managed Capacity Contract Expansion | Bundles storage, compute, and network resources into single monthly subscriptions with committed utilization tiers. |
| Sovereign Cloud Certification Investment | Attests to exclusive domestic data processing for Privacy Act 2020 compliance and government agency procurement. |
| Canterbury Disaster Recovery Cluster Development | Leverages Christchurch's post-earthquake fiber backbone and seismic isolation standards for financial services failover. |
| Maori Data Sovereignty Partnership | Creates culturally auditable storage infrastructure with localized operational control under iwi-led governance. |
| Software-Defined Storage Platform Integration | Enables commodity hardware deployment with enterprise feature sets, avoiding proprietary vendor lock-in. |
Research Methodology
The analysis maps HDD, SSD, hybrid, and tape storage sub-sectors alongside deployment model and end-user segments, each validated through facility engineering directors, procurement officers at District Health Boards, and telecommunications infrastructure planners. Primary interviews with Dell Technologies and Pure Storage channel partners, Datacom and Catalyst Cloud operations leads, and Reserve Bank technology risk supervisors combined with secondary validation from BIS certification registries, Transpower grid capacity disclosures, and Office of the Privacy Commissioner enforcement protocols. Bottom-up installation tracking across Auckland, Wellington, and Christchurch facilities triangulates against top-down vendor shipment estimates.
Consistency checks against hyperscaler capex disclosures and enterprise storage refresh cycles validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include storage media type, deployment architecture, end-user industry vertical, and facility tier certification status. CAGRs derive from fitted growth curves incorporating Privacy Act 2020 compliance deadlines, 5G network rollout timelines, and Reserve Bank operational resilience mandate implementation schedules.
The analysis sits within stated boundaries; outcomes outside sustained data sovereignty enforcement or grid capacity expansion in the upper North Island would require recalibration. Forecasts reflect documented assumptions regarding certification timeline stability and NAND supply corridor continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Global Cloud Object Storage Market
Storage Solutions
Austria Data Center Storage Market
Storage Solutions
Thailand Data Center Storage Market
Storage Solutions
Hard Disk Market
Storage Solutions
Singapore Data Center Storage Market
Storage Solutions
Indonesia Data Center Storage Market
Storage Solutions
Europe in-Memory Database Market
Storage Solutions
Automated Storage and Retrieval Systems in Laboratories Market
Storage Solutions
Network Attached Storage (NAS) Market
Storage Solutions
Netherlands Data Center Storage Market
Storage Solutions
5D Data Storage Market
Storage Solutions
Global in-Memory Database Market
Storage Solutions
Mexico Data Center Storage Market
Storage Solutions
South Africa Data Center Storage Market
Storage Solutions
Vietnam Data Center Storage Market
Storage Solutions
Saudi Arabia Data Center Storage Market